
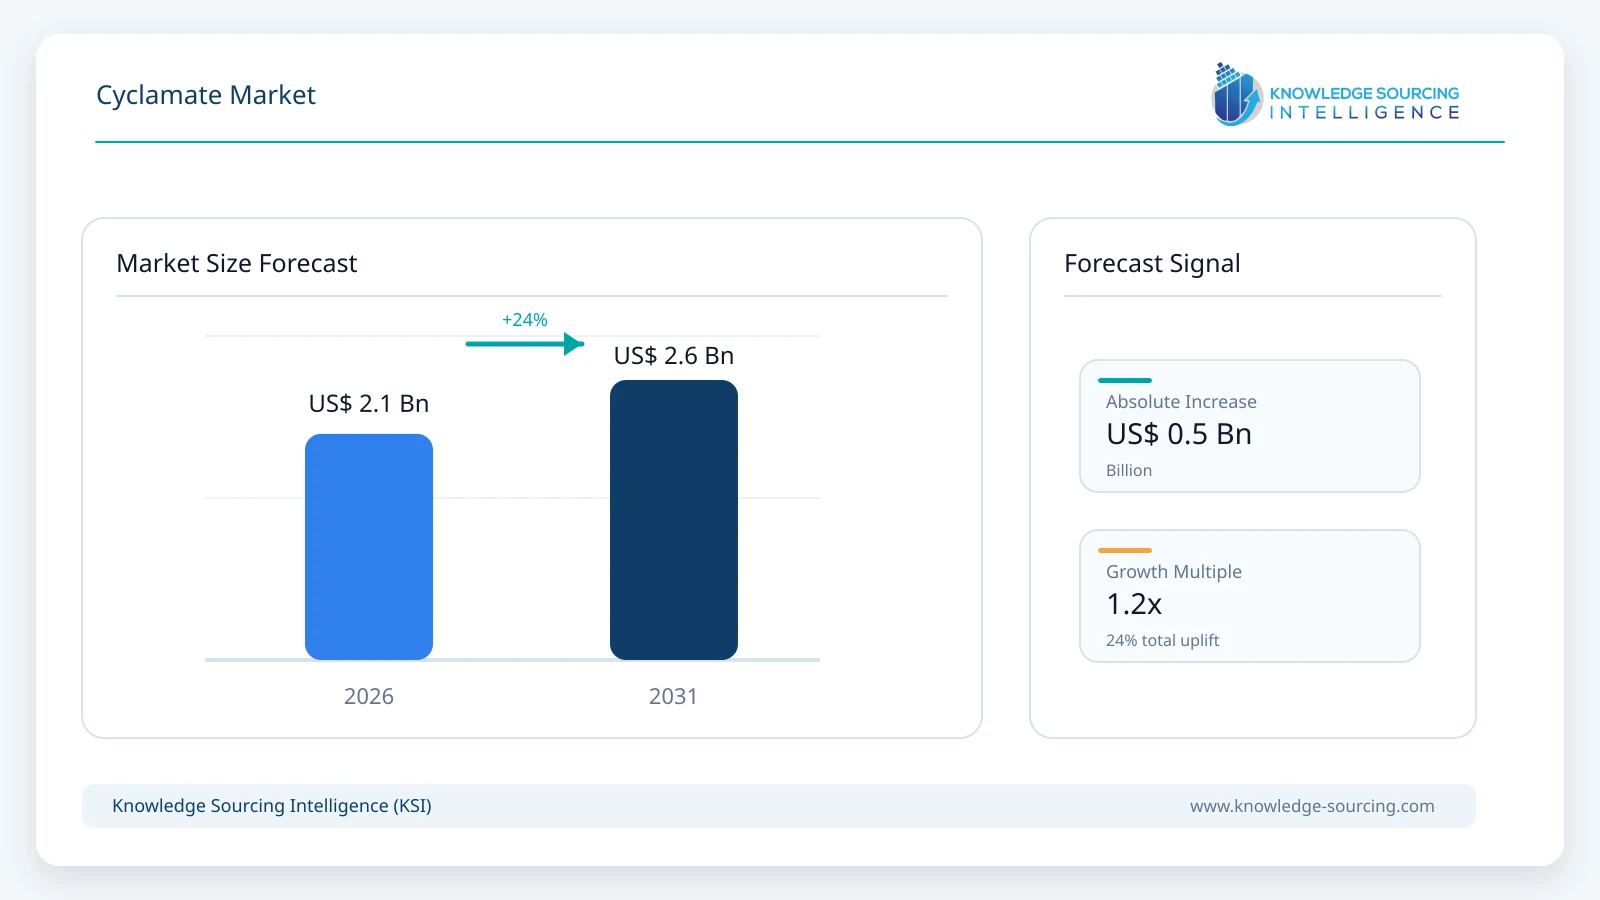
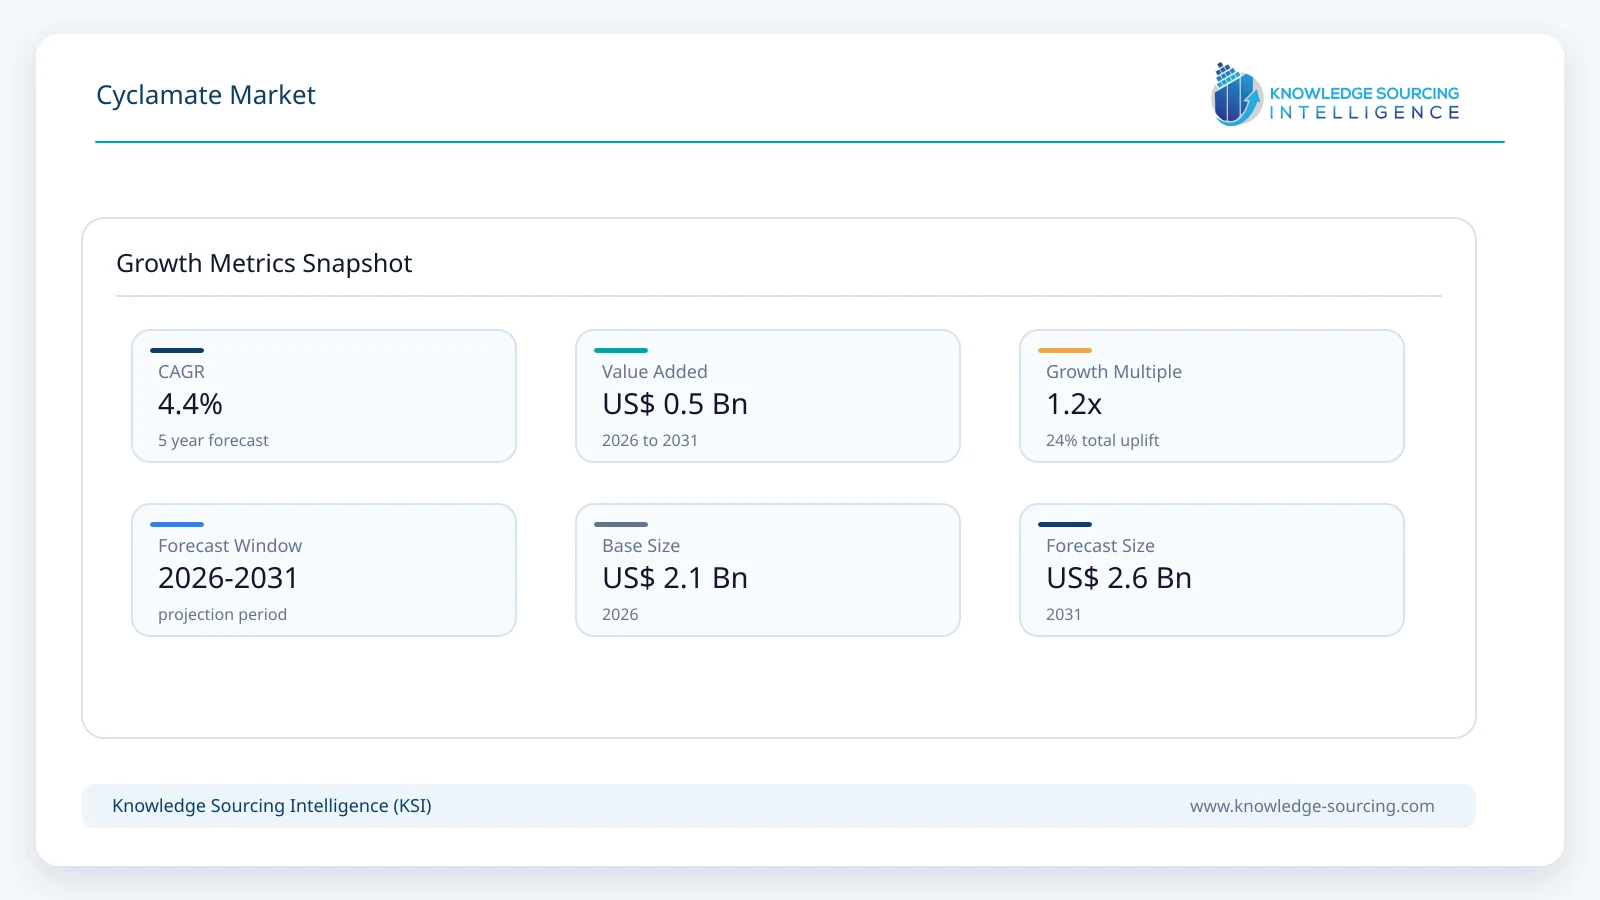
The Cyclamate market is forecast to grow at a CAGR of 4.4%, reaching USD 2.6 billion in 2031 from USD 2.1 billion in 2026.
Highlights:
- 1Food and beverage manufacturers are evaluating cyclamate blends for sweetness, formulation flexibility, and cost control.
- 2Demand for reduced-sugar beverages and processed foods is supporting interest in alternative sweetening ingredients.
- 3Emerging food-processing markets are creating opportunities for approved cyclamate applications in selected product categories.
- 4National food-additive regulations, permitted-use limits, and labelling requirements are shaping cyclamate sourcing and product development.
Cyclamate is a synthetic, high-intensity sweetener used to provide sweetness at concentrations substantially lower than those required for conventional sugar. Depending on the formulation and cyclamate salt used, it is commonly described as approximately 30 to 40 times sweeter than sucrose. Discovered by Michael Sveda in 1937, cyclamate subsequently became an ingredient of interest to food manufacturers seeking economical alternatives to sugar. Its relatively low cost, suitability for selected heat-processed applications, and compatibility with other sweeteners have contributed to its continued use in countries where food regulations permit it.
Sodium cyclamate and calcium cyclamate are relevant commercial forms. The ingredient is used in certain beverages, tabletop sweeteners, confectionery, and other food applications, subject to the applicable country's regulations. Cyclamate is frequently combined with saccharin because the blend can produce a more balanced sweetness profile than either ingredient alone. The appropriate blend depends on the product's flavour, acidity, processing conditions, intended shelf life, and target consumer. This formulation flexibility can make cyclamate attractive to manufacturers working within tight ingredient-cost budgets.
However, cyclamate is not a universally authorised food ingredient. The United States Food and Drug Administration (FDA) prohibits cyclamates and their salts in food, while cyclamates are authorised for specified uses in Great Britain and the European regulatory framework provides for permitted uses and maximum levels in eligible food categories. China's GB 2760-2024 national food safety standard, which took effect on 8 February 2025, sets out food-additive usage requirements, including specified applications for sodium and calcium cyclamate. Manufacturers must therefore assess the regulations of each destination market before selecting cyclamate for a product. FDA guidance on high-intensity sweeteners, the Great Britain food authorisation register, and the USDA's review of China's food-additive standard provide useful regulatory reference points.
These differences influence the commercial structure of the cyclamate market. Producers and distributors must manage product specifications, purity, documentation, import requirements, and customer-specific compliance. In authorised markets, the ingredient can compete on price and formulation performance. In restricted markets, manufacturers must consider alternative sweeteners rather than assume cyclamate can be used in mainstream food and beverage products.
The market's growth prospects are connected to the broader development of sugar-reduction strategies. Manufacturers are exploring high-intensity sweeteners, polyols, rare sugars, and plant-derived ingredients to reduce added sugar or adjust sweetness while preserving taste. Cyclamate represents one option within this wider formulation landscape, rather than a universal replacement for sugar. Its commercial prospects depend on regulatory access, the economics of competing ingredients, consumer acceptance, and the technical requirements of individual products.
Health considerations also influence ingredient selection. Cyclamate has a long history of regulatory debate, particularly following animal studies that contributed to its prohibition in the United States. Its authorisation in other jurisdictions reflects different regulatory assessments and conditions of use, not an unrestricted global safety clearance. Food manufacturers need to follow applicable exposure limits and food-category permissions, while avoiding unsupported claims that cyclamate prevents diabetes, treats obesity, or independently improves health outcomes.
Overall, the cyclamate market is shaped by a combination of formulation economics, food-processing demand, sugar-reduction initiatives, and jurisdiction-specific food safety rules. The most relevant opportunities are likely to arise in markets and applications where the ingredient is permitted and where manufacturers can demonstrate acceptable taste, product stability, and compliance. The forecast presented above is the report's market estimate; government statistics on obesity, diabetes, or food regulation provide context for demand drivers but do not independently validate the market's revenue forecast.
Market Drivers
The growing food and beverage industry is expected to support cyclamate market growth.
Expansion in packaged foods, beverages, and industrial food processing is creating opportunities for ingredients that meet manufacturers' cost, performance, and product-development requirements. In countries where cyclamate is authorised, its relatively low ingredient cost and compatibility with selected sweetener blends can support its consideration in suitable formulations.
Food and beverage manufacturers routinely balance sweetness, flavour, texture, stability, shelf life, and ingredient cost. These requirements can make high-intensity sweeteners useful in selected applications, particularly where producers want to reduce sugar content without substantially changing the product's established sensory profile. Cyclamate can be considered for beverages, tabletop sweeteners, and certain processed foods where local rules allow its use. Its ability to work alongside other sweeteners may also help formulators adjust sweetness perception and reduce unwanted flavour notes.
Nevertheless, expansion in the food and beverage industry does not translate automatically into higher cyclamate consumption. Manufacturers may choose sucralose, acesulfame potassium, steviol glycosides, aspartame, or other ingredients depending on local regulations, consumer expectations, product claims, and total formulation cost. Cyclamate's commercial position is therefore determined by its relative advantages within individual product categories, not simply by growth in packaged food production.
Asia-Pacific is relevant to this driver because the region includes large food-processing industries and substantial consumer markets. China's food-additive framework illustrates how defined usage permissions can support commercial applications while setting limits on where and how an ingredient can be used. The Chinese authorities published GB 2760-2024 in 2024, and it became effective in February 2025. The standard updated the country's previous food-additive framework and includes permitted-use conditions for various additives. Food manufacturers and exporters must consult the relevant entries and restrictions rather than infer approval for every cyclamate application. China's National Health Commission announcement documents the publication of the revised standard.
Product development and manufacturing efficiency are additional considerations. A sweetener that performs consistently during processing can reduce formulation uncertainty, although suitability depends on the complete recipe and processing conditions. Manufacturers may assess cyclamate alongside other ingredients through pilot batches, stability testing, sensory panels, and regulatory review. Suppliers that provide consistent quality, appropriate technical documentation, and reliable deliveries can be better positioned to serve approved applications.
Consequently, food-sector expansion is best understood as an enabling factor. It enlarges the pool of potential applications, while regulatory eligibility, ingredient economics, and technical performance determine the portion of that opportunity accessible to cyclamate.
Growing interest in low-calorie sweeteners is expected to encourage formulation opportunities for cyclamate.
Interest in reduced-sugar foods and beverages has encouraged manufacturers to investigate multiple sweetening systems. High-intensity sweeteners can deliver sweetness at low use levels, while other ingredients may contribute bulk, mouthfeel, browning, or texture. Cyclamate's role is particularly relevant where its sweetness profile, cost, and compatibility with other permitted sweeteners align with the product's technical requirements.
For a manufacturer, choosing a sweetener involves more than comparing sweetness intensity. Taste quality, aftertaste, solubility, heat exposure, acidity, shelf life, labelling, and ingredient cost all affect the final decision. Cyclamate-sacharin blends, for example, can be considered where the combined profile is suitable and the relevant regulations permit the formulation. However, other sweetener combinations may be preferable for products marketed on particular ingredient, flavour, or nutritional attributes.
The World Health Organization's 2023 guideline on non-sugar sweeteners is an important consideration in this area. WHO recommended against using non-sugar sweeteners as a long-term strategy for weight control or reducing the risk of noncommunicable diseases, while noting that the recommendation was conditional and does not replace toxicological safety evaluations of individual sweeteners. The guideline also distinguishes its recommendation from assessments of the safety of individual substances and does not apply to polyols. Manufacturers should therefore avoid presenting the wider shift towards sugar reduction as proof that every non-sugar sweetener produces a health benefit. WHO's non-sugar sweetener guideline provides the relevant policy context.
Despite these qualifications, manufacturers still need to address formulation challenges associated with reducing sugar. Sugar contributes not only sweetness but also bulk, moisture retention, texture, and other functional properties. Replacing it can require a combination of ingredients and process adjustments. Cyclamate may be one component of a suitable formulation in permitted applications, but it cannot replace every functional role of sugar by itself.
Price sensitivity may strengthen the case for economical sweeteners in selected product categories. Where a manufacturer can use cyclamate legally and achieve the required sensory and technical performance, the ingredient may help manage formulation costs. The opportunity remains application-specific because supply costs, dosage, blend requirements, compliance testing, and the price of alternative sweeteners affect total cost.
Increasing awareness of obesity and diabetes is influencing sugar-reduction strategies, although it does not establish cyclamate-specific demand.
Obesity and diabetes are significant public health challenges, encouraging governments, healthcare professionals, and food manufacturers to examine dietary patterns and the consumption of foods high in free or added sugars. This attention can influence demand for reformulated products, but the relationship between these health conditions and individual sweeteners must be interpreted carefully. Neither obesity prevalence nor diabetes incidence demonstrates that cyclamate consumption is increasing, and cyclamate should not be represented as a treatment or preventive measure for either condition.
The World Health Organization's October 2026 fact sheet reports that approximately 1.1 billion people worldwide were living with obesity in 2024. It also estimates that 2.6 billion adults aged 18 years and older were overweight in 2024, including 940 million adults living with obesity. These figures illustrate the scale of the global health challenge and the need for coordinated responses involving nutrition, healthcare, physical activity, and food environments. They do not establish that low-calorie sweeteners, or cyclamate in particular, reduce obesity risk. WHO's updated obesity and overweight fact sheet provides the latest figures cited here.
Diabetes data offer further context. A pooled analysis published in The Lancet in 2024, covering population-representative studies from 1990 to 2022, estimated that 828 million adults aged 18 years and older were living with diabetes in 2022. India and China accounted for particularly large numbers of affected adults. This evidence highlights the importance of diabetes prevention, diagnosis, and management, but it should not be interpreted as a direct measure of sweetener demand. The Lancet study provides the underlying estimate.
For food manufacturers, the commercial implication is the need to respond to diverse dietary preferences and product requirements. Some consumers seek products with less added sugar, while others prioritise taste, affordability, ingredient familiarity, or specific dietary guidance. Manufacturers may therefore develop conventional, reduced-sugar, and sugar-free variants within the same category. Cyclamate can participate in this product-development process where authorised, but its selection depends on the intended use and applicable safety requirements.
Regulatory and public-health messaging can also affect consumer acceptance. Product labels need to comply with local rules, and nutrition or health claims must be supported by appropriate evidence. The resulting environment favours ingredient suppliers that can offer reliable technical data, clear documentation, and support for regulatory compliance. These requirements are relevant to cyclamate suppliers as well as providers of alternative sweetening ingredients.
Geographical Analysis
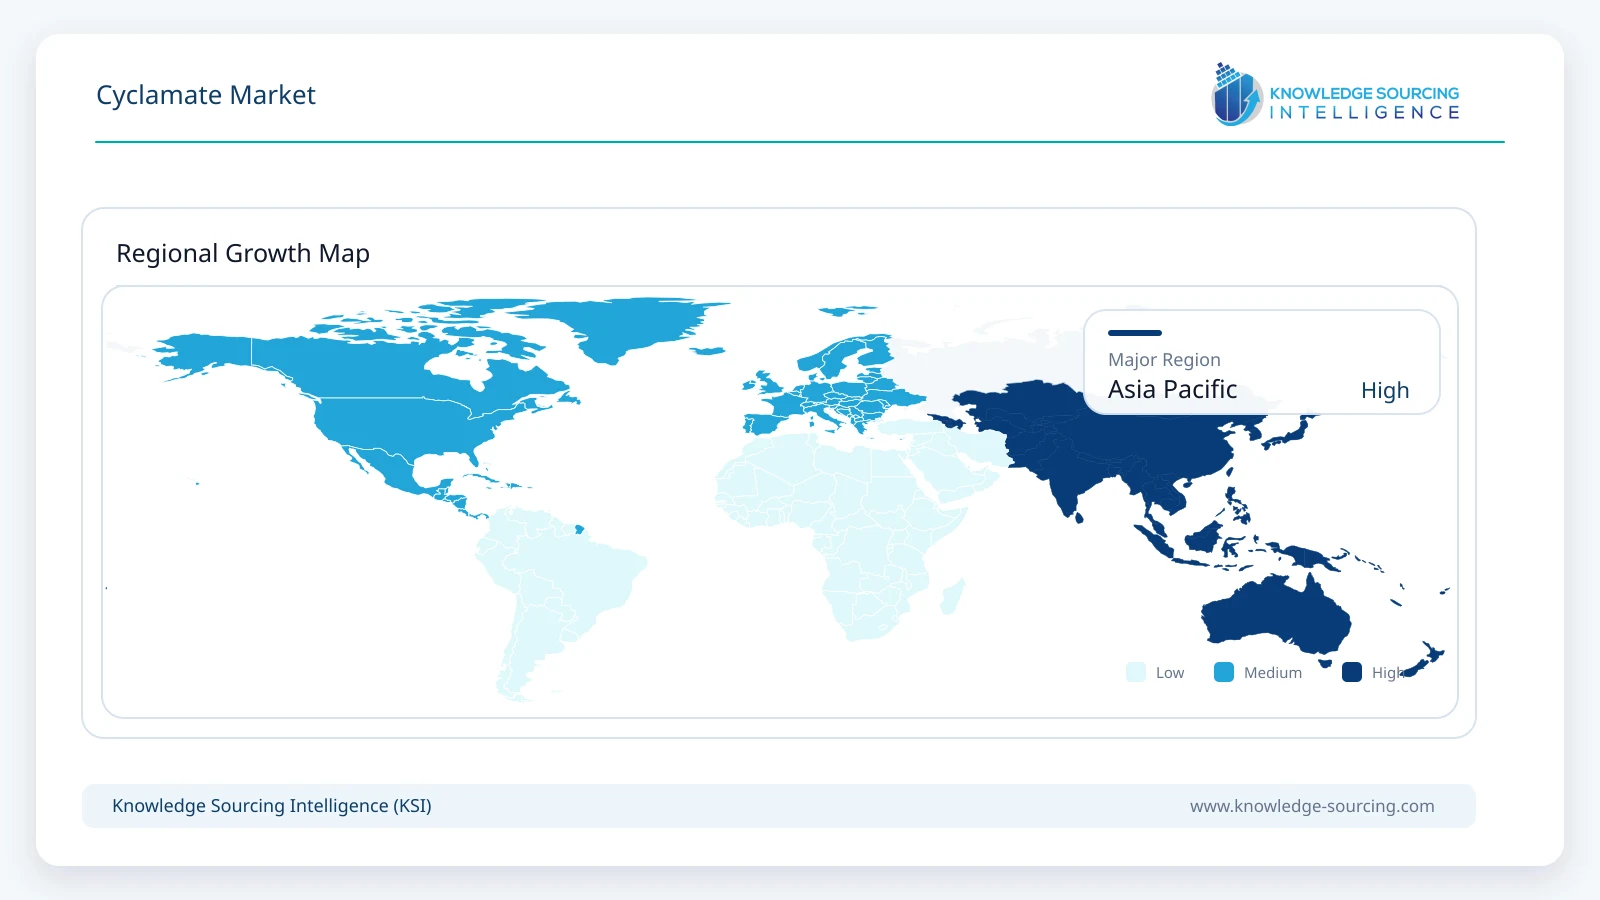
Asia-Pacific is expected to remain an important regional opportunity for the cyclamate market.
Asia-Pacific presents a potential growth opportunity because of its large population, diverse food-processing industries, and demand for packaged food and beverage products. China and other regional markets have established food manufacturing and ingredient supply chains, while changes in retail distribution and product development create opportunities for a wide range of sweetening ingredients. The extent of cyclamate adoption, however, depends on each country's food-additive permissions and the applications permitted under those rules.
China provides a useful example of the importance of regulatory detail. GB 2760-2024 became effective on 8 February 2025 and establishes food-additive usage requirements, including specified conditions for sodium and calcium cyclamate. The standard identifies permitted food categories and maximum levels for relevant applications. These limits are not interchangeable across products, and compliance may require manufacturers to account for the cyclamate content calculated on the basis specified by the standard. Companies exporting into China should review the official standard and obtain qualified regulatory advice where necessary. USDA Foreign Agricultural Service's regulatory summary explains the standard's introduction and implementation.
China's regulatory framework should not be treated as evidence that every Asian market permits the same uses. Manufacturers selling across borders must check national rules, permitted food categories, maximum use levels, labelling obligations, and import requirements. Differences between countries can influence production planning, product specifications, and supplier selection. For companies operating across several markets, maintaining separate formulations or ingredient specifications may be necessary.
India and Indonesia also represent sizeable food and beverage markets, but their commercial prospects for cyclamate need to be assessed against their own food safety regulations. Population growth and increasing consumption of packaged products may create a broader opportunity for sweeteners; neither factor alone establishes cyclamate's permitted use or market share. A reliable regional assessment should combine official regulatory information with country-specific evidence on manufacturing, product applications, and consumer demand.
Competition from other sweeteners is another consideration. Stevia-derived ingredients, sucralose, acesulfame potassium, and other authorised alternatives may appeal to manufacturers seeking particular taste profiles, product positioning, or labelling characteristics. The balance between synthetic and plant-derived sweeteners may differ by application and consumer segment. Cyclamate suppliers therefore need to demonstrate the ingredient's technical and economic suitability rather than rely on the general growth of sugar-reduction products.
North America has a different regulatory profile. The US FDA states that cyclamates and their salts are prohibited for use as sweeteners in food. Consequently, the United States should not be presented as a conventional food-market growth opportunity for cyclamate without a clear distinction between permitted non-food uses and prohibited food uses. The FDA's high-intensity sweetener guidance confirms this restriction.
In Europe, the regulatory position also requires precision. Cyclamates are listed as E 952, and authorised uses are subject to food-category conditions and maximum levels. Great Britain's regulated-products register identifies cyclamates as authorised under the applicable framework. These permissions do not mean that cyclamate can be added to any food or used without limits. Manufacturers must confirm the current requirements for the destination market and product category. The Great Britain authorisation entry is a relevant starting point.
Overall, Asia-Pacific offers a potentially important base for cyclamate applications, but a definitive ranking of regional market share or growth requires comparable regional sales and forecast data. The report's regional conclusions should therefore distinguish between documented regulatory access, broader food-industry opportunities, and independently measured cyclamate revenue. This distinction helps readers assess the market without confusing the growth of sugar-reduction products with the performance of a single ingredient.
Latest Industry Developments
October 2026: Tate & Lyle and BioHarvest Sciences reported a milestone in their next-generation sweetener programme, demonstrating progress in BioHarvest's Botanical Synthesis platform.
July 2026: Ingredion highlighted sugar-reduction, clean-label, and nutrition-focused ingredient concepts at IFT FIRST 2026, including solutions designed for beverage and food applications.
May 2026: Tate & Lyle announced an expanded collaboration with BioHarvest to develop multiple plant-based sweetener molecules for different food and beverage formulation requirements.
February 2026: Tate & Lyle and Manus launched the Yume sweetener brand, introducing Yume M Stevia, a stevia-derived ingredient intended to support sugar-reduction formulations.
These announcements indicate that sweetener suppliers are competing through taste improvement, ingredient innovation, manufacturing scalability, and formulation support. They should be treated as wider industry developments, not as evidence that the companies manufacture or have launched cyclamate products. No cyclamate-specific 2026 product launch or capacity expansion is asserted here without direct company-source verification.
Cyclamate Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.1 billion |
| Total Market Size in 2031 | USD 2.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Cyclamic Acid
Sodium Cyclamate
Calcium Cyclamate
By End-User
Food and Beverages
Pharmaceuticals
Cosmetics and Personal Care
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key benefits for the stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. CYCLAMATE MARKET BY TYPE
5.1. Introduction
5.2. Cyclamic Acid
5.3. Sodium Cyclamate
5.4. Calcium Cyclamate
6. CYCLAMATE MARKET BY END-USER
6.1. Introduction
6.2. Food and Beverages
6.3. Pharmaceuticals
6.4. Cosmetics and Personal Care
6.5. Others
7. CYCLAMATE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By End-User
7.2.3. By Country
7.2.3.1. USA
7.2.3.2. Canada
7.2.3.3. Mexico
7.3. South America
7.3.1. By Type
7.3.2. By End-User
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.2. Argentina
7.3.3.3. Others
7.4. Europe
7.4.1. By Type
7.4.2. By End-User
7.4.3. By Country
7.4.3.1. United Kingdom
7.4.3.2. Germany
7.4.3.3. France
7.4.3.4. Italy
7.4.3.5. Others
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By End-User
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.2. UAE
7.5.3.3. Others
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By End-User
7.6.3. By Country
7.6.3.1. China
7.6.3.2. Japan
7.6.3.3. India
7.6.3.4. South Korea
7.6.3.5. Indonesia
7.6.3.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Foodchem International Corporation
9.2. PT. Batang Alum Industrie
9.3. Productos Aditivos, S.A.
9.4. Golden Time Enterprises Limited
9.5. Prakash Chemicals International Private Limited (PCIPL)
9.6. Tongaat Hulett
9.7. Jebsen & Jessen Life Science GmbH
9.8. Ataman Chemicals





Frequently asked questions
What is the projected market size of the Cyclamate Market by 2031?
The Cyclamate Market is forecast to reach USD 2.6 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for the Cyclamate Market?
The Cyclamate Market is forecast to grow at a CAGR of 4.4%.
What are the primary growth drivers for the Cyclamate Market?
Consumer acceptance of low-calorie sweeteners and growing food & beverage industry.
What is the regulatory status of cyclamate across key regions?
EU and over 55 countries approve its use; US bans food products.
What are the main characteristics and advantages of cyclamate?
The Cyclamate Market is an affordable, heat-stable, artificial sweetener, 30-50 times sweeter than sugar.
What are the key end-use applications of cyclamate?
Primarily used in beverages, foods (outside US), toothpaste, and mouthwash.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Cyclamate Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/cyclamate-market