
The France AI in Finance market is forecast to grow at a CAGR of 14.9%, reaching USD 9.8 billion in 2031 from USD 4.9 billion in 2026.
Highlights:
- 1Artificial intelligence adoption is becoming mainstream among French financial-market participants, with 90% of respondents in an AMF study reporting current use or planned adoption within 12 months, while 54% already had production use cases in 2026.
- 2Generative AI is emerging as an important technology layer in French financial services, supporting document analysis, knowledge retrieval, customer interaction, software development, compliance activities, and other operational processes.
- 3French financial-sector AI adoption is increasingly shaped by governance requirements, as the ACPR is preparing for its supervisory role for high-risk financial AI systems and is developing assessment approaches covering AI risks, performance, explainability, and fairness.
- 4AI adoption is extending from internal institutional use toward business-facing financial services, with Qonto deploying AI agents that can analyse financial data and prepare actions involving payments, invoices, cards, and other business-finance workflows.
- 5Investment-related consumer adoption remains comparatively limited, indicating that the near-term market opportunity is stronger in institutional, operational, risk-management, and business-finance applications than in fully autonomous AI-led investment decisions.
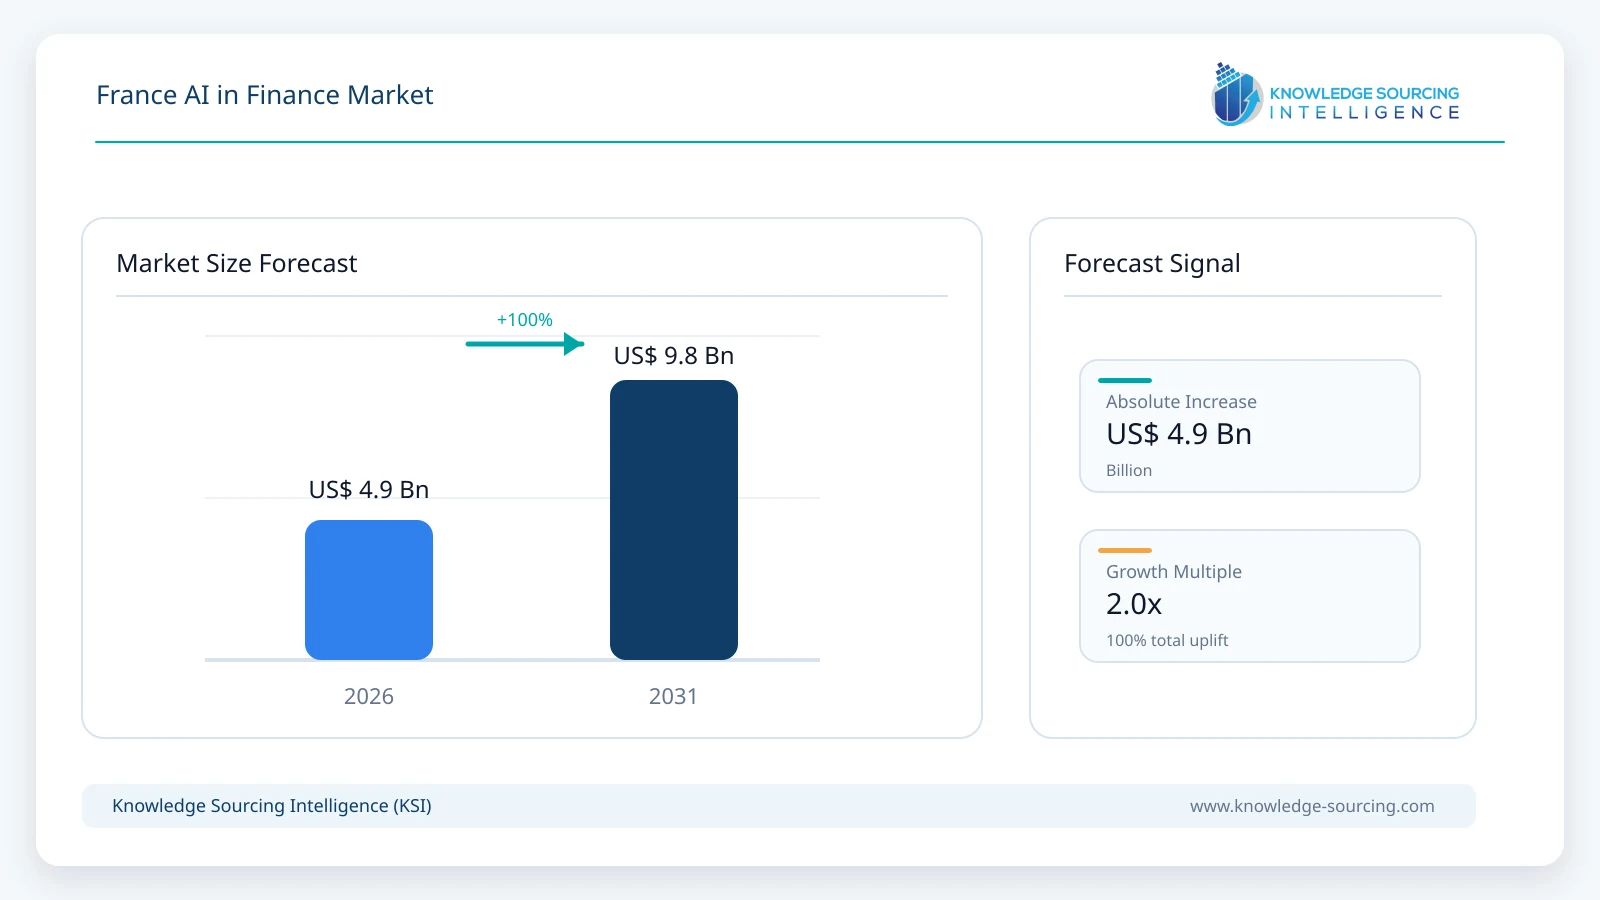
The French AI in Finance market is entering a more structured adoption phase in which financial institutions are moving from experimentation toward controlled deployment. The market is supported by demand for automation, data analysis, fraud detection, risk management, regulatory compliance, customer engagement, and financial decision support. At the same time, the use of AI in finance is subject to a higher level of scrutiny than many general enterprise applications because financial decisions can directly affect consumers, investors, businesses, and financial stability.
Evidence from the Autorité des Marchés Financiers (AMF) provides a strong indication of this transition. In February 2026, the AMF published a study based on responses from 100 French financial-market participants. It found that 90% of respondents were already using AI or planned to use it within the following 12 months, while 54% reported that AI use cases were already in production. The AMF also reported that generative AI was the most widely used AI technology among the participants and that most respondents expected AI investment to increase over the following two years. This evidence supports a market structure in which AI spending is moving beyond isolated pilots toward production-oriented applications.
The market is nevertheless developing unevenly across financial functions. Large financial institutions have greater access to proprietary data, technology budgets, compliance teams, and model-risk expertise, while smaller institutions and fintechs can compete through narrower, application-specific AI products. The resulting competitive environment favours solutions that combine financial-sector domain knowledge with secure data processing, explainability, human oversight, and measurable operational outcomes.
France AI in Finance Market Analysis:
Growth Drivers
Increasing production-level adoption across French financial institutions is a central growth driver. The February 2026 AMF study demonstrates that AI is no longer limited to experimental projects. The finding that 54% of surveyed participants already had production use cases indicates that financial organizations are increasingly integrating AI into operating processes rather than treating it solely as an innovation initiative. The same study found that generative AI was the most widely used technology, creating demand for natural language processing, large language models, retrieval systems, model governance, and secure enterprise AI environments.
Operational efficiency is another important driver. Financial institutions process large volumes of transactions, documents, communications, customer requests, compliance records, and market information. AI can support classification, summarisation, anomaly detection, information extraction, forecasting, and decision support across these workflows. The commercial value is particularly visible in back-office and middle-office functions where repetitive processes can be automated without removing the need for human review. Financial institutions can therefore use AI to increase processing capacity while maintaining control over sensitive decisions.
Fraud detection and financial-crime prevention also create sustained demand. Financial institutions must identify suspicious transactions, unusual customer behaviour, fraudulent claims, and other patterns that may not be efficiently captured by static rules alone. Machine-learning models can analyse larger datasets and identify relationships or anomalies that can be escalated for investigation. The ACPR's 2026 work programme specifically identifies continued work involving artificial intelligence and existing initiatives related to anti-money-laundering and counter-terrorist-financing controls, reinforcing the importance of AI-enabled supervision and risk-management capabilities.
Competition between traditional financial institutions and technology-led financial providers is another demand driver. Digital-first providers can introduce automated customer journeys, data-driven financial management, and conversational interfaces without carrying the same level of legacy-system complexity as many incumbent institutions. Traditional players therefore have an incentive to modernise internal operations and customer-facing services while maintaining regulatory controls.
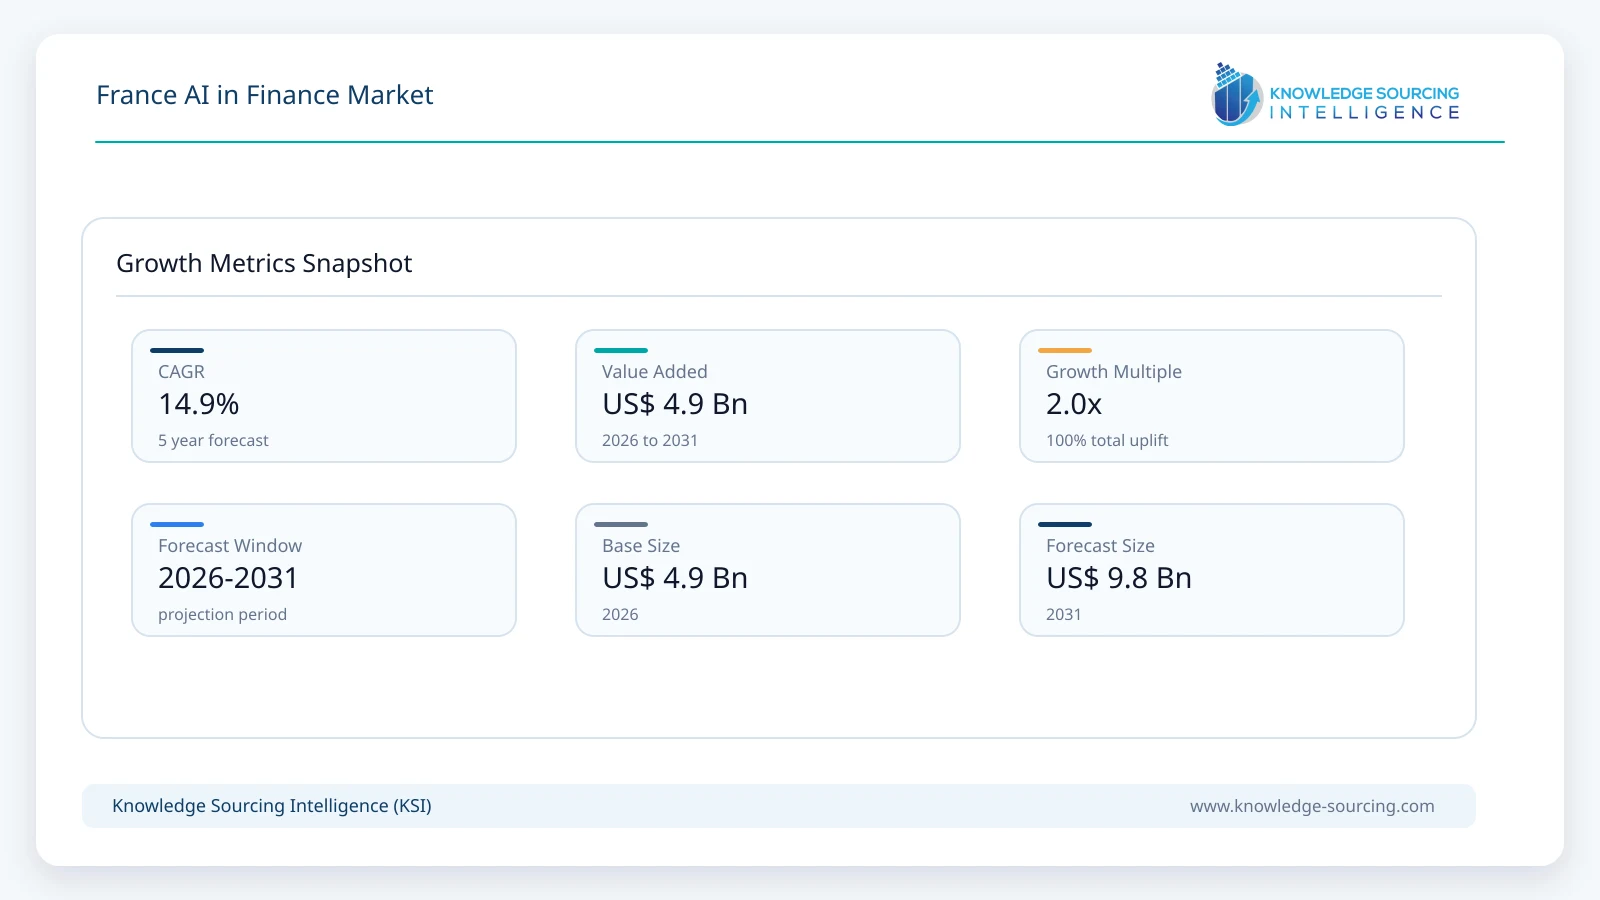
Challenges and Opportunities
Data governance remains a major challenge because financial AI systems depend on high-quality, appropriately governed data. Transaction histories, customer information, financial records, claims information, and other datasets can contain sensitive personal or commercially confidential information. Poor-quality or incomplete data can reduce model performance, while inappropriate data use can create privacy, discrimination, or compliance risks. As a result, market demand is increasingly shifting toward AI platforms that include data controls, monitoring, access management, auditability, and human oversight.
Model explainability and algorithmic fairness are additional challenges. Financial decisions involving creditworthiness, insurance risk, customer treatment, and other sensitive outcomes can create significant consequences for individuals. In July 2026, the ACPR published work on algorithmic fairness in the financial sector, highlighting the complexity of applying non-discrimination principles to statistical and AI-based decision systems. The development of this supervisory focus creates opportunities for model-validation, fairness-testing, explainability, monitoring, and AI-governance solutions.
Regulatory complexity creates both a constraint and an opportunity. Financial institutions must interpret requirements originating from financial-sector regulation, data-protection rules, digital-resilience requirements, and the EU AI Act. This increases the cost of deploying AI but also creates demand for governance technology. Vendors that can combine model monitoring, documentation, risk classification, audit trails, access controls, and compliance workflows can therefore address a growing institutional requirement.
A further opportunity is the expansion of AI agents. AI agents can move beyond generating information toward executing controlled multi-step tasks. Qonto's 2026 deployment demonstrates this direction in business finance, with its AI agents able to analyse financial information and prepare actions such as payments and invoice-related tasks while retaining user approval. This creates a new application category between conventional automation and fully autonomous decision-making.
Consumer-facing investment applications represent a longer-term opportunity but currently require a more cautious assessment. The AMF's June 2026 investment study found that AI use for obtaining information before investing remained a minority behaviour among French people, although younger investors were substantially more likely to use AI for this purpose. This suggests that consumer adoption may expand as familiarity increases, but financial providers must address reliability, disclosure, suitability, and investor-protection concerns before AI becomes a primary investment-information channel.
Supply Chain Analysis
The France AI in Finance supply chain consists of data, infrastructure, AI models, application platforms, integration services, and financial-sector users. At the foundation are financial datasets generated through banking transactions, payments, investments, insurance activity, accounting systems, customer interactions, regulatory reporting, and external economic information. These datasets require secure collection, storage, processing, and governance before they can support production AI applications.
The infrastructure layer includes cloud computing, enterprise data platforms, application programming interfaces, cybersecurity systems, model-development environments, and computing resources. Financial institutions increasingly need infrastructure that can satisfy their security, privacy, resilience, and regulatory requirements. This does not mean that every financial AI workload must be hosted on a SecNumCloud-certified environment; rather, the applicable security and sovereignty requirements depend on the data, institution, workload, contractual arrangements, and regulatory context. Consequently, infrastructure selection is becoming a risk-management decision rather than simply a technology-cost decision.
The AI technology layer includes machine-learning models, natural language processing, generative AI, large language models, computer vision, predictive analytics, and AI-agent frameworks. These technologies are increasingly combined rather than deployed independently. For example, an insurance workflow can combine machine learning for fraud scoring, generative AI for document summarisation, and an AI agent for orchestrating a controlled sequence of tasks.
The application layer converts these technologies into financial-sector solutions. Applications include fraud detection, credit analysis, customer service, regulatory compliance, financial forecasting, investment support, claims management, payment monitoring, treasury management, and document processing. Vendors with specialised financial datasets and domain-specific models can establish stronger competitive positions because general-purpose AI models do not automatically provide the regulatory, operational, or contextual reliability required for financial workflows.
The final layer consists of banks, insurance companies, asset managers, fintechs, payment providers, financial infrastructure companies, SMEs, large enterprises, and individual users. Adoption decisions increasingly depend on measurable business outcomes, integration requirements, data governance, and regulatory assurance rather than AI capability alone.
Government Regulations
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
|---|---|---|
European Union / France | EU AI Act / ACPR | The AI Act establishes a risk-based framework for artificial intelligence. In financial services, certain AI systems used for assessing the creditworthiness of natural persons and certain insurance risk and pricing applications are classified as high-risk, increasing the need for governance, documentation, risk management, data controls, human oversight, and technical compliance capabilities. |
France | ACPR AI Supervision and Algorithmic Fairness | The ACPR is preparing for its supervisory responsibilities concerning high-risk financial AI systems and is developing approaches for assessing AI-related risks. Its 2026 work on algorithmic fairness increases attention to discrimination, model outcomes, customer protection, and explainability. |
European Union / France | GDPR / CNIL | Data-protection requirements affect the collection, processing, retention, and use of personal data in AI systems. Financial AI providers therefore require strong data-governance, purpose-limitation, security, and privacy controls when developing and deploying customer-facing models. |
European Union / France | Digital Operational Resilience Act (DORA) | DORA strengthens ICT-risk and operational-resilience requirements for financial entities and relevant technology relationships. Its requirements increase the importance of resilience, third-party risk management, incident management, testing, and technology governance for AI-enabled financial infrastructure. |
France | ANSSI and SecNumCloud | SecNumCloud provides a high-security qualification framework for cloud service providers. Its relevance to financial AI depends on the sensitivity and regulatory requirements of the workload, but it strengthens demand for secure and trusted cloud environments where applicable. |
France AI in Finance Market Segment Analysis:
By Technology: Generative Artificial Intelligence
Generative artificial intelligence represents one of the most important technology segments in the France AI in Finance market because it enables financial institutions to interact with large volumes of unstructured information through natural language. The AMF's February 2026 study identified generative AI as the most widely used AI technology among the French financial-market participants surveyed, supporting its position as a leading adoption category.
Financial institutions can apply generative AI to internal knowledge management, document summarisation, regulatory research, customer communications, software development, meeting transcription, financial analysis, and other information-intensive activities. However, deployment in financial services differs from consumer use because outputs must be subject to security controls, data-access restrictions, accuracy checks, and human review where decisions have material consequences.
The segment is therefore moving toward enterprise-grade generative AI rather than unrestricted public chatbot usage. Financial institutions require retrieval-augmented generation, controlled access to proprietary information, model monitoring, prompt controls, logging, and mechanisms for preventing inappropriate disclosure of sensitive information. The growth opportunity extends to specialist vendors that can provide secure AI environments tailored to banking, insurance, investment, and payment workflows.
Generative AI is also becoming a foundation for AI agents. Instead of simply responding to questions, agents can interpret requests, retrieve information, prepare actions, and coordinate workflows. Qonto's 2026 AI agents provide an example of this direction in business finance. The company's Operator can prepare actions involving transfers, invoices, and cards, while its Analyst can examine transaction information. Qonto also launched an MCP server in June 2026 that enables business-finance data and actions to be accessed through compatible AI assistants. These developments illustrate how generative AI can become an interface layer for financial applications rather than remain a standalone content-generation tool.
The key limitation remains reliability. Financial users cannot treat generated responses as automatically correct. Providers therefore need human approval, controlled permissions, traceability, model evaluation, and secure data architecture. This requirement creates parallel demand for AI governance and validation tools alongside generative AI platforms.
By Application: Back Office
The Back Office segment represents a strong application opportunity because many back-office processes involve high transaction volumes, repetitive procedures, structured rules, and large quantities of documents. Financial institutions can apply AI to reconciliation, document classification, regulatory reporting support, accounting workflows, data extraction, exception identification, claims processing, and internal administrative tasks.
Natural language processing and computer vision can extract information from documents, while machine-learning models can identify anomalies and prioritise cases for review. Generative AI can summarise long documents or generate first drafts of internal communications, while AI agents can coordinate multiple steps under controlled permissions. These applications can reduce manual workloads and improve processing consistency without requiring financial institutions to automate the final decision in every case.
Back-office AI is particularly attractive because the business case can often be measured through processing time, error rates, case volumes, employee productivity, and turnaround times. This allows financial institutions to evaluate AI investments against operational metrics rather than relying on less measurable innovation objectives.
Nevertheless, the segment requires strong controls. Automated extraction errors can propagate into downstream financial records, while inaccurate summaries can affect compliance or operational decisions. Consequently, production deployments increasingly require validation rules, audit logs, exception management, human review, and monitoring. The combination of efficiency and governance is likely to remain central to the expansion of AI in French financial back-office operations.
Competitive Environment and Analysis
The French AI in Finance competitive environment combines established financial institutions, fintech companies, specialist AI providers, insurance technology companies, payment infrastructure providers, and software companies. Competition is increasingly based on the ability to integrate AI into existing financial workflows while maintaining security, regulatory compliance, and user control.
Qonto provides an example of a fintech pursuing an AI-native operating model. In April 2026, the company announced its transition toward an AI-native fintech model and the deployment of intelligent agents across a customer base of more than 600,000 businesses. In June 2026, it launched Qonto MCP, enabling its business account to be accessed through compatible AI assistants. By August 2026, Qonto's documentation described two AI agents, the Operator and Analyst, as integrated into customer accounts.
Shift Technology represents another competitive model, although its primary focus is insurance rather than banking. Its AI decisioning platform applies artificial intelligence to claims, fraud detection, subrogation, and other insurance workflows. In 2026, the company expanded its focus on agentic AI and proposed the ARISE framework to classify levels of AI-agent autonomy in insurance. This illustrates how specialist financial-services AI providers are moving from predictive models toward controlled agent-based workflows.
Competition is also affected by regulatory expectations. Providers that can demonstrate explainability, security, fairness, human oversight, and operational resilience may be better positioned to win financial-sector deployments than generic AI vendors that lack sector-specific controls. The competitive landscape is therefore likely to remain fragmented across use cases, with specialised providers competing alongside larger technology platforms and financial institutions' internal AI teams.
France AI in Finance Market Company Profiles:
Qonto
Qonto is a French business-finance platform serving SMEs, freelancers, and other businesses. Its 2026 product strategy demonstrates a direct move toward AI-enabled financial operations. Qonto introduced AI agents designed to assist with financial tasks, including transaction analysis, invoice workflows, payments, and card-related actions. The Operator prepares actions for user approval, while the Analyst enables customers to query and analyse their financial data. This approach positions AI as an embedded interface within business finance rather than as a separate application.
In June 2026, Qonto announced Qonto MCP, allowing its business-finance environment to connect with compatible AI assistants. By August 2026, the company's support documentation confirmed that its AI agents were available through web and mobile interfaces. The company's strategy therefore demonstrates a shift toward agentic financial management, with explicit user approval remaining an important control for sensitive financial actions.
Shift Technology
Shift Technology is a Paris-based AI company focused primarily on insurance decisioning. Its platform applies artificial intelligence to fraud detection, claims, underwriting, subrogation, and other insurance processes. The company's positioning is particularly relevant to the AI in Finance market when insurance is included within the market definition because insurance is a major financial-services activity with significant data and decisioning requirements.
In April 2026, Shift described an Agent First approach and stated that it had integrated generative AI into products in 2024 and agentic capabilities in 2025. In June 2026, it introduced the ARISE framework for describing AI-agent autonomy in insurance. In August 2026, Shift appointed Zach Haehn as Chief Technology Officer as it accelerated agentic AI development, with the company highlighting AI governance, security, fraud detection, claims, subrogation, underwriting, and risk workflows. These developments demonstrate the company's current strategic focus on moving AI agents into production insurance workflows while maintaining accuracy, transparency, security, and human control.
Yomoni
Yomoni is a French digital wealth-management company whose business model places technology at the centre of investment and financial-advisory services. In March 2026, Yomoni reported the use of advanced AI technologies to enhance its tax and wealth-support services. The company described automated reading of tax documents, automated tax summaries, AI-based eligibility scoring, and an updated knowledge base intended to support advisers during client interactions.
This development illustrates a practical application of AI in wealth management where technology augments human advisers rather than fully replacing financial decision-making. The approach can reduce administrative effort, accelerate document analysis, and help advisers provide more structured information to customers while retaining human responsibility for the final advice.
Lydia Solutions
Lydia Solutions operates the Sumeria digital banking proposition and remains relevant to the French consumer-finance and digital-banking ecosystem. Its positioning reflects the broader shift from payment applications toward broader digital financial services. For the purposes of an AI in Finance market assessment, its relevance should be evaluated based on documented AI deployment rather than simply its status as a fintech. The company should therefore be assessed through publicly verifiable evidence of AI use in customer service, risk management, fraud detection, personalisation, or other financial workflows.
Treezor
Treezor is a banking-as-a-service and payment infrastructure provider supporting embedded-finance applications. Its relevance to the France AI in Finance market is primarily through the financial infrastructure layer. In April 2026, Treezor announced a strategic partnership with I.B.E. GmbH involving non-cash compensation in Germany, while its August 2026 documentation continued to expand payment and open-banking capabilities. Treezor's contribution to the market is therefore more closely associated with programmable financial infrastructure and APIs than with a standalone AI product category.
Kantox
Kantox focuses on foreign-exchange management and corporate treasury solutions. Its relevance to AI in Finance is linked to automated and data-driven management of currency exposure, cash flows, and treasury processes. The company operates within a segment where financial organisations increasingly require technology that can support forecasting, exposure analysis, workflow automation, and controlled execution.
Banque Palatine
Banque Palatine represents the established banking side of the French financial ecosystem. Its inclusion provides a useful counterpoint to fintech companies because incumbent institutions typically operate larger legacy technology environments and must integrate AI while maintaining established risk, compliance, security, and governance frameworks. Any assessment of Banque Palatine within the AI in Finance competitive landscape should be based on documented AI deployments and strategic initiatives rather than treating the institution's general digital activity as evidence of AI-market participation.
France AI in Finance Market Recent Developments:
August 2026: Qonto's AI agents were documented as integrated into its business-finance accounts, with the Operator preparing actions such as transfers and invoice creation and the Analyst analysing transaction history. The company also continued expanding AI-assisted financial workflows across its platform.
August 2026: Shift Technology appointed Zach Haehn as Chief Technology Officer as the company accelerated its development of agentic AI for insurers, with a focus on AI governance, security, fraud detection, claims, subrogation, underwriting, and risk workflows.
June 2026: Qonto launched its MCP server, enabling its business-finance account to connect with compatible AI assistants and allowing users to manage financial information and selected banking workflows through natural-language interactions.
June 2026: Shift Technology introduced its ARISE framework for describing levels of AI-agent autonomy in insurance, reflecting the industry's movement from AI assistants and recommendations toward increasingly autonomous but governed financial-services workflows.
France AI in Finance Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.9 billion |
| Total Market Size in 2031 | USD 9.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 14.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Deployment Model, End User, Application, Financial Function |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Technology
By Deployment Model
By End User
By Application
By Financial Function
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Artificial Intelligence in Finance
4.2. Machine Learning
4.3. Natural Language Processing
4.4. Generative Artificial Intelligence
4.5. Large Language Models
4.6. Computer Vision
4.7. Predictive Analytics
4.8. Other Technologies
5. FRANCE AI IN FINANCE MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Machine Learning
5.3. Natural Language Processing
5.4. Generative Artificial Intelligence
5.5. Large Language Models
5.6. Computer Vision
5.7. Predictive Analytics
5.8. Other Technologies
6. FRANCE AI IN FINANCE MARKET BY DEPLOYMENT MODEL
6.1. Introduction
6.2. On-Premises
6.3. Cloud
6.4. Hybrid
7. FRANCE AI IN FINANCE MARKET BY END USER
7.1. Introduction
7.2. Individuals
7.3. Small and Medium-Sized Enterprises
7.4. Large Enterprises
7.5. Financial Institutions
7.6. Fintech Companies
7.7. Insurance Companies
7.8. Others
8. FRANCE AI IN FINANCE MARKET BY APPLICATION
8.1. Introduction
8.2. Back Office
8.3. Middle Office
8.4. Front Office
9. FRANCE AI IN FINANCE MARKET BY FINANCIAL FUNCTION
9.1. Introduction
9.2. Banking
9.3. Payments
9.4. Lending and Credit
9.5. Wealth Management
9.6. Insurance
9.7. Risk Management
9.8. Fraud Detection
9.9. Regulatory Compliance
9.10. Other Financial Functions
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Competitive Positioning Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Qonto
11.2. Lydia Solutions
11.3. Shift Technology
11.4. Yomoni
11.5. Treezor
11.6. Kantox
11.7. Banque Palatine
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected growth and market value of the France AI in Finance market between 2026 and 2031?
The France AI in Finance market is forecast to grow at a Compound Annual Growth Rate (CAGR) of 14.9%, reaching USD 9.8 billion in 2031. This growth represents a significant increase from an estimated USD 4.9 billion in 2026, highlighting the market's robust expansion. The market is moving from an experimental phase toward more structured and controlled deployment within financial institutions.
Which AI technologies and application areas are primarily driving the growth of the French AI in Finance market?
Generative AI is emerging as an important technology layer, supporting diverse applications such as document analysis, knowledge retrieval, customer interaction, software development, and compliance activities. Beyond Generative AI, the market is driven by demand for automation, data analysis, fraud detection, risk management, regulatory compliance, customer engagement, and financial decision support. The primary opportunities are concentrated in institutional, operational, risk-management, and business-finance applications rather than fully autonomous AI-led consumer investment.
How is the regulatory landscape, specifically the ACPR and AMF, influencing AI adoption and development within the French financial sector?
AI adoption in the French financial sector is increasingly shaped by governance requirements, with the ACPR preparing its supervisory role for high-risk financial AI systems and developing assessment approaches for risks, performance, explainability, and fairness. The AMF's February 2026 study indicates high adoption rates, with 90% of participants using or planning AI, underscoring the market's transition to production-oriented applications under regulatory scrutiny. This heightened oversight reflects the direct impact financial decisions can have on consumers, investors, and financial stability.
What is the current state of AI adoption among French financial institutions, and what are the main areas of focus for deployment?
According to a February 2026 AMF study, 90% of French financial-market participants reported current use or planned adoption of AI within 12 months, with 54% already having production use cases. AI adoption is extending from internal institutional processes toward business-facing financial services, exemplified by Qonto deploying AI agents for tasks involving payments, invoices, and other business-finance workflows. This indicates a shift from isolated pilot projects to production-level applications in areas like automation, data analysis, and operational efficiency.
What are the key market opportunities and emerging challenges in the French AI in Finance sector?
Key opportunities lie in institutional, operational, risk-management, and business-finance applications, with Generative AI offering significant potential for enhancing document analysis and operational processes. An emerging challenge is the higher level of scrutiny on AI in finance compared to general enterprise applications, given its direct impact on consumers, investors, and financial stability. Additionally, investment-related consumer adoption remains comparatively limited, indicating a stronger near-term focus on institutional-grade solutions.
How do different types of financial institutions, particularly large versus smaller ones, approach AI adoption in France?
AI adoption is developing unevenly across financial functions and institutions in France. Large financial institutions generally possess distinct advantages, including greater access to proprietary data, larger technology budgets, dedicated compliance teams, and more extensive model-risk expertise. These resources enable them to move more swiftly from experimentation toward controlled deployment, potentially creating a disparity in the pace and scale of AI implementation compared to smaller institutions.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). France AI in Finance Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/france-ai-in-finance-market