
The global fruit juice market is growing at a CAGR of approximately 4.8%, from USD 172.0 billion in 2026 to USD 217.7 billion by 2031.
Highlights:
- 1Orange-based products account for approximately 34% of global fruit-juice market value in 2026.
- 2Europe contributes roughly 29% of 2026 revenue, supported by established per-capita juice consumption and branded retail.
- 3Shelf-stable juice remains the largest format, while chilled and premium not-from-concentrate products grow faster.
- 4USDA forecasts global orange-juice consumption to rise 4% in 2025/26 to approximately 1.2 million tonnes.
- 5New EU rules applying from June 2026 created a formal reduced-sugar fruit-juice category requiring at least 30% sugar reduction.
- 6Supply volatility in oranges and other processing fruit continues to influence concentrate prices, margins and retail pricing.

Fruit juice remains one of the largest established categories within non-alcoholic beverages, but growth is increasingly driven by value mix rather than by rapid increases in litres consumed. Mature markets have experienced pressure from consumer concerns around naturally occurring sugars, while premium not-from-concentrate juice, functional blends, organic products and convenient single-serve formats support higher average selling values. At the same time, demand in many emerging markets continues to benefit from urbanization, modern retail development, refrigeration availability and the expansion of branded packaged beverages. The result is a market in which conventional shelf-stable juice remains the volume foundation while higher-value formats generate a growing proportion of incremental revenue.
Orange juice continues to anchor global supply economics. USDA's January 2026 citrus outlook forecasts global orange-juice production at about 1.4 million tonnes in 2025/26, with Brazil producing approximately 1.0 million tonnes. Global consumption is forecast to increase by around 4% to 1.2 million tonnes as supply availability improves. This rebound follows a period of tight orange supply and elevated prices that weakened demand in several markets. USDA's European Union outlook notes that high prices and weather-related quality issues caused consumers to switch to alternative beverages during the previous season, with a modest consumption recovery expected in 2025/26. These supply-demand conditions are important because orange juice remains a reference product for retail pricing and procurement across the wider fruit-juice category.
Regulation is also reshaping product development. Directive (EU) 2024/1438, applied by Member States from 14 June 2026, introduced categories for reduced-sugar fruit juice, reduced-sugar fruit juice from concentrate and concentrated reduced-sugar fruit juice. Products using these designations must reduce naturally occurring sugars by at least 30% while maintaining the other essential characteristics of the original juice. In the United States, the FDA finalized a modernization of the pasteurized-orange-juice standard in July 2026, reducing minimum soluble solids from 10.5 to 10.0 degrees Brix and allowing up to 15% mandarin/tangerine or related hybrid juice by volume. Both developments provide manufacturers with additional formulation flexibility while preserving regulated product identities.
Market Trends
Reduced-Sugar Juice Is Moving from Niche Innovation into a Formal Product Category
Sugar reduction is becoming more technically and commercially important because conventional 100% fruit juice contains naturally occurring sugars that cannot simply be removed through standard reformulation without changing the product identity. The European Union's new reduced-sugar categories are therefore significant: they establish a regulatory pathway for products with at least 30% lower naturally occurring sugar while maintaining essential physical, chemical, organoleptic and nutritional characteristics. Permitted approaches include membrane filtration and yeast fermentation under defined conditions. This creates a new innovation space between traditional 100% juice and diluted juice drinks and is likely to encourage investment in processing, sensory optimization and claims-based differentiation.
Functional Positioning Is Extending Juice Beyond the Breakfast Occasion
Fruit juice is increasingly being combined with fibre, vitamins, minerals, botanicals and digestive-health propositions as brands seek relevance outside traditional breakfast consumption. Keurig Dr Pepper's 2026 Mott's Zero Sugar Juice Drinks broaden lower-sugar choice in the juice aisle, while The Coca-Cola Company's Simply brand has extended into juice-based functional beverages using fruit juice alongside prebiotic fibre. Tropicana Brands Group also combines core orange juice with Naked smoothies, KeVita functional beverages and fruit-led sparkling products. The important commercial shift is not that all functional beverages become fruit juice, but that juice brands increasingly use functionality to defend shelf space against hydration, energy and wellness beverages.
Packaging and Manufacturing Scale Are Becoming More Strategic
Juice economics depend heavily on aseptic processing, cold-chain infrastructure, packaging efficiency and access to fruit-processing capacity. Refresco operates 82 facilities across 14 countries and manufactures from-concentrate, not-from-concentrate and freshly squeezed juices alongside other beverage categories. Its May 2026 completion of the SunOpta acquisition expanded North American manufacturing capabilities and illustrates continuing consolidation among large beverage manufacturing platforms. Flexible co-packing and private-label capacity is important because retailers and brand owners increasingly want multiple pack sizes, shorter innovation cycles and the ability to shift between chilled, ambient and functional formats without building dedicated plants.
Premium Not-From-Concentrate Products Continue to Gain Value Share
Not-from-concentrate juice carries higher production, logistics and cold-chain requirements than concentrate-based juice, but it also supports stronger premium positioning around freshness, taste and minimal processing. The category is particularly important in North America and Europe and is expanding through chilled retail, foodservice and premium urban channels in Asia. Premiumization does not eliminate concentrate demand: concentrate remains essential for global supply balancing, cost-efficient transportation and shelf-stable production. Instead, the market is developing a two-tier structure in which concentrate provides scale while not-from-concentrate, organic and functional products support higher value per litre.
Market Drivers
Premiumization and Product Mix Support Value Growth Despite Moderate Volume Expansion
The principal growth mechanism in mature juice markets is increasingly a shift in product mix rather than a large increase in per-capita consumption. Consumers willing to pay more for chilled, not-from-concentrate, organic, functional or traceable products raise average selling values even when overall volumes remain stable. This dynamic also benefits brands that can segment portfolios by occasion, package size and nutritional proposition. Premium single-serve packs, cold-chain products and fortified blends create additional revenue without requiring the entire category to return to historical consumption levels.
Emerging-Market Retail Expansion Broadens Access to Packaged Juice
Modern grocery, convenience retail, foodservice and e-commerce continue to expand packaged beverage access across Asia Pacific, Latin America, the Middle East and Africa. The strongest opportunities are not limited to premium 100% juice; locally relevant flavours such as mango, mixed fruit, guava and tropical blends allow brands to compete at multiple price points. Large domestic companies including Dabur, Parle Agro, Nongfu Spring and regional dairy-and-beverage groups combine distribution reach with local taste familiarity, while global brands use bottling and manufacturing partnerships to extend availability.
Supply Normalization Supports Recovery from Recent Orange-Juice Price Pressure
A better global orange-juice supply balance supports demand recovery after several years of weather, disease and crop-related constraints. USDA forecasts 2025/26 global production at about 1.4 million tonnes and consumption at 1.2 million tonnes, with Brazil remaining the dominant producer. Improved availability can ease extreme concentrate pricing and help manufacturers rebuild promotional activity, although structural risks from citrus greening, climate variability and orchard productivity remain. The forecast therefore assumes gradual normalization rather than a return to consistently low raw-material costs.

Market Restraints
Sugar Perception, Fruit-Cost Volatility and Competing Beverage Categories Limit Volume Growth
The market faces a structural tension between fruit juice's natural nutrient content and consumer concern over free sugars. 100% juice cannot be reformulated in the same way as many soft drinks without changing its regulated identity, which limits conventional sugar-reduction options. At the same time, fruit and concentrate prices can move sharply because of weather, crop disease, harvest quality and processing availability. Retailers and consumers can respond to higher prices by reducing frequency or switching to water, flavored hydration, carbonated beverages or other functional drinks. These factors constrain volume growth and increase the importance of pack-size management, portfolio segmentation and procurement discipline.
Segment Analysis
By Concentration - Concentrate
Concentrate-based juice is estimated at approximately USD 104.9 billion in 2026 and remains the largest concentration segment. Concentration reduces transportation and storage costs, supports global trade in orange, apple and other juice bases, and enables manufacturers to produce shelf-stable products close to final markets. The segment is especially important for mainstream retail and private-label juice. Not-from-concentrate products are expected to grow faster from a smaller base because they benefit from premium positioning and consumer preference for less processed chilled formats.
By Type - Shelf-Stable
Shelf-stable juice is estimated at approximately USD 99.8 billion in 2026, making it the largest type segment. Ambient storage, long distribution reach and lower refrigeration requirements make the format particularly important in emerging markets, institutional channels and high-volume grocery. Aseptic PET and carton technology continue to improve quality retention while reducing logistics complexity. Chilled ready-to-serve juice is smaller but records stronger value growth in markets where cold-chain infrastructure and premium retail support higher price points.
By Flavour - Orange
Orange remains the largest flavour globally and is projected to approach USD 72.5 billion by 2031. Its scale reflects established breakfast consumption, global processing infrastructure and widespread availability of concentrate and not-from-concentrate formats. The segment's growth is slower than several tropical and mixed-fruit flavours because mature markets face high penetration and orange supply remains exposed to citrus greening and weather variability. Mango and mixed-fruit products gain share in Asia, the Middle East and other markets where tropical flavours align closely with local consumption preferences.
By Category - Naturally Sweetened / No Artificial Sweeteners
Naturally sweetened and no-artificial-sweetener products are estimated at approximately USD 72.2 billion in 2026 under KSI's primary-positioning classification. The segment benefits from clean-label preferences and from the fact that regulated 100% fruit juice cannot contain added sugars in major markets such as the European Union. Functional and reduced-sugar propositions grow faster, but they are assigned separately in the model only when functionality or sugar reduction is the product's principal marketed proposition, preventing double counting across overlapping claims.
By Geography - Europe
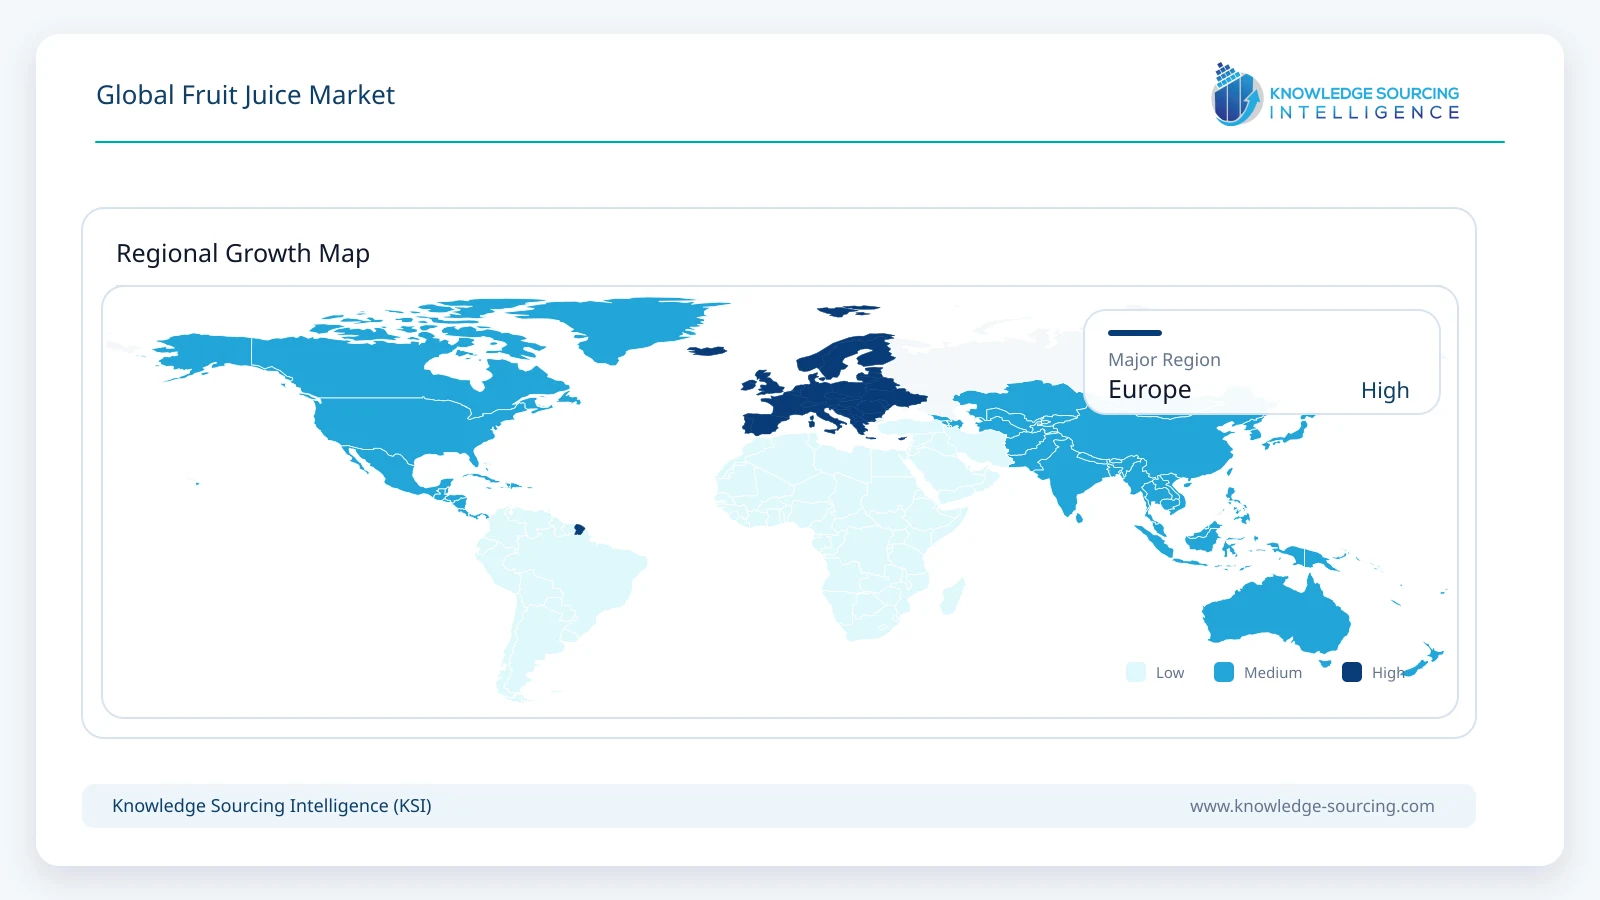
Europe remains the largest regional market and is projected to reach approximately USD 61.8 billion by 2031. The region has an established juice processing and branded-retail base, high penetration of ambient and chilled products and a well-developed regulatory framework for juice identity. Growth remains moderate because volumes are mature, but the region is an important innovation market for reduced-sugar juice, premium not-from-concentrate formats, organic products and packaging sustainability. Asia Pacific is expected to grow faster through 2031 as modern retail, urban incomes and locally relevant fruit flavours expand packaged-juice demand.
Competitive Environment
The competitive landscape combines global beverage companies, specialist juice groups, cooperatives, vertically integrated citrus processors and large contract manufacturers. The Coca-Cola Company participates through Minute Maid, Simply, innocent and Del Valle, while Tropicana Brands Group operates Tropicana, Naked, Copella and other chilled and fruit-based beverage brands. Keurig Dr Pepper competes through Mott's, and Ocean Spray and Welch's bring cooperative-backed fruit sourcing into branded beverages. Eckes-Granini, Rauch and Lassonde are important regional branded and manufacturing participants, while Refresco is a major private-label and contract-manufacturing platform.
Upstream fruit and concentrate supply is also strategically important. Citrosuco, Cutrale and Louis Dreyfus Company are major participants in global citrus processing and juice supply, particularly for orange products. Their role becomes more visible during periods of crop tightness because concentrate availability and pricing affect manufacturers across multiple regions. Competitive advantage therefore depends on a combination of brand strength, sourcing security, cold-chain and aseptic manufacturing, retailer relationships, formulation capability and the ability to manage both premium and value-oriented portfolios.
Recent Developments
July 2026: The U.S. FDA finalized a revised pasteurized-orange-juice standard, lowering minimum soluble solids to 10.0 degrees Brix and permitting up to 15% mandarin/tangerine or related hybrid juice.
June 2026: EU Member States began applying Directive (EU) 2024/1438, introducing formal reduced-sugar fruit-juice categories with at least 30% lower naturally occurring sugars.
May 2026: Refresco completed its acquisition of SunOpta, expanding its North American beverage manufacturing and supply-chain capabilities.
February 2026: Keurig Dr Pepper announced Mott's Zero Sugar Juice Drinks as part of its 2026 refreshment innovation program.
November 2025: AIJN published sustainability guidance intended to align definitions, recognized standards and practical tools across the European juice sector.
February 2025: The Coca-Cola Company launched Simply Pop, extending the Simply brand into fruit-juice-based functional beverages with prebiotic fibre.
Fruit Juice Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 172.0 billion |
| Total Market Size in 2031 | USD 217.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Concentration, Type, Flavour, Category, Geography |
| Companies |
|
Market Segmentation
By Concentration
Concentrate
Non-Concentrate
By Type
Shelf-Stable
Frozen
Chilled Ready-to-Serve
Others
By Flavour
Apple
Orange
Mango
Lemon
Mixed Fruit
Others
By Category
Organic Juices
Carbonated Juices
Naturally Sweetened (No Artificial Sweeteners)
Functional Juices
Prebiotic and Probiotic Juices
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Premiumization and Product Mix Support Value Growth Despite Moderate Volume Expansion
3.1.2. Emerging-Market Retail Expansion Broadens Access to Packaged Juice
3.1.3. Supply Normalization Supports Recovery from Recent Orange-Juice Price Pressure
3.2. Market Restraints
3.2.1. Sugar Perception, Fruit-Cost Volatility and Competing Beverage Categories Limit Volume Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Juice Concentration and Reconstitution
4.2. Not-From-Concentrate Processing and Cold Chain
4.3. Aseptic Filling and Shelf-Life Extension
4.4. Reduced-Sugar Processing Technologies
4.5. Functional Formulation and Fortification
4.6. Packaging and Traceability
5. GLOBAL FRUIT JUICE MARKET BY CONCENTRATION
5.1. Introduction
5.2. Concentrate
5.3. Non-Concentrate
6. GLOBAL FRUIT JUICE MARKET BY TYPE
6.1. Introduction
6.2. Shelf-Stable
6.3. Frozen
6.4. Chilled Ready-to-Serve
6.5. Others
7. GLOBAL FRUIT JUICE MARKET BY FLAVOUR
7.1. Introduction
7.2. Apple
7.3. Orange
7.4. Mango
7.5. Lemon
7.6. Mixed Fruit
7.7. Others
8. GLOBAL FRUIT JUICE MARKET BY CATEGORY
8.1. Introduction
8.2. Organic Juices
8.3. Carbonated Juices
8.4. Naturally Sweetened (No Artificial Sweeteners)
8.5. Functional Juices
8.6. Prebiotic and Probiotic Juices
8.7. Others
9. GLOBAL FRUIT JUICE MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. USA
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East & Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Product Launches, Mergers, Acquisitions and Partnerships
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. The Coca-Cola Company
11.2. Tropicana Brands Group
11.3. Keurig Dr Pepper Inc.
11.4. Ocean Spray Cranberries, Inc.
11.5. Eckes-Granini Group GmbH
11.6. Refresco Group
11.7. Lassonde Industries Inc.
11.8. Welch Foods Inc. / National Grape Cooperative
11.9. Citrus World, Inc. (Florida's Natural Growers)
11.10. Rauch Fruchtsäfte GmbH & Co OG
11.11. Suntory Beverage & Food Limited
11.12. Nongfu Spring Co., Ltd.
11.13. Dabur India Limited
11.14. Parle Agro Pvt. Ltd.
11.15. Almarai Company
11.16. Citrosuco
11.17. Sucocitrico Cutrale Ltda.
11.18. Louis Dreyfus Company
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











