
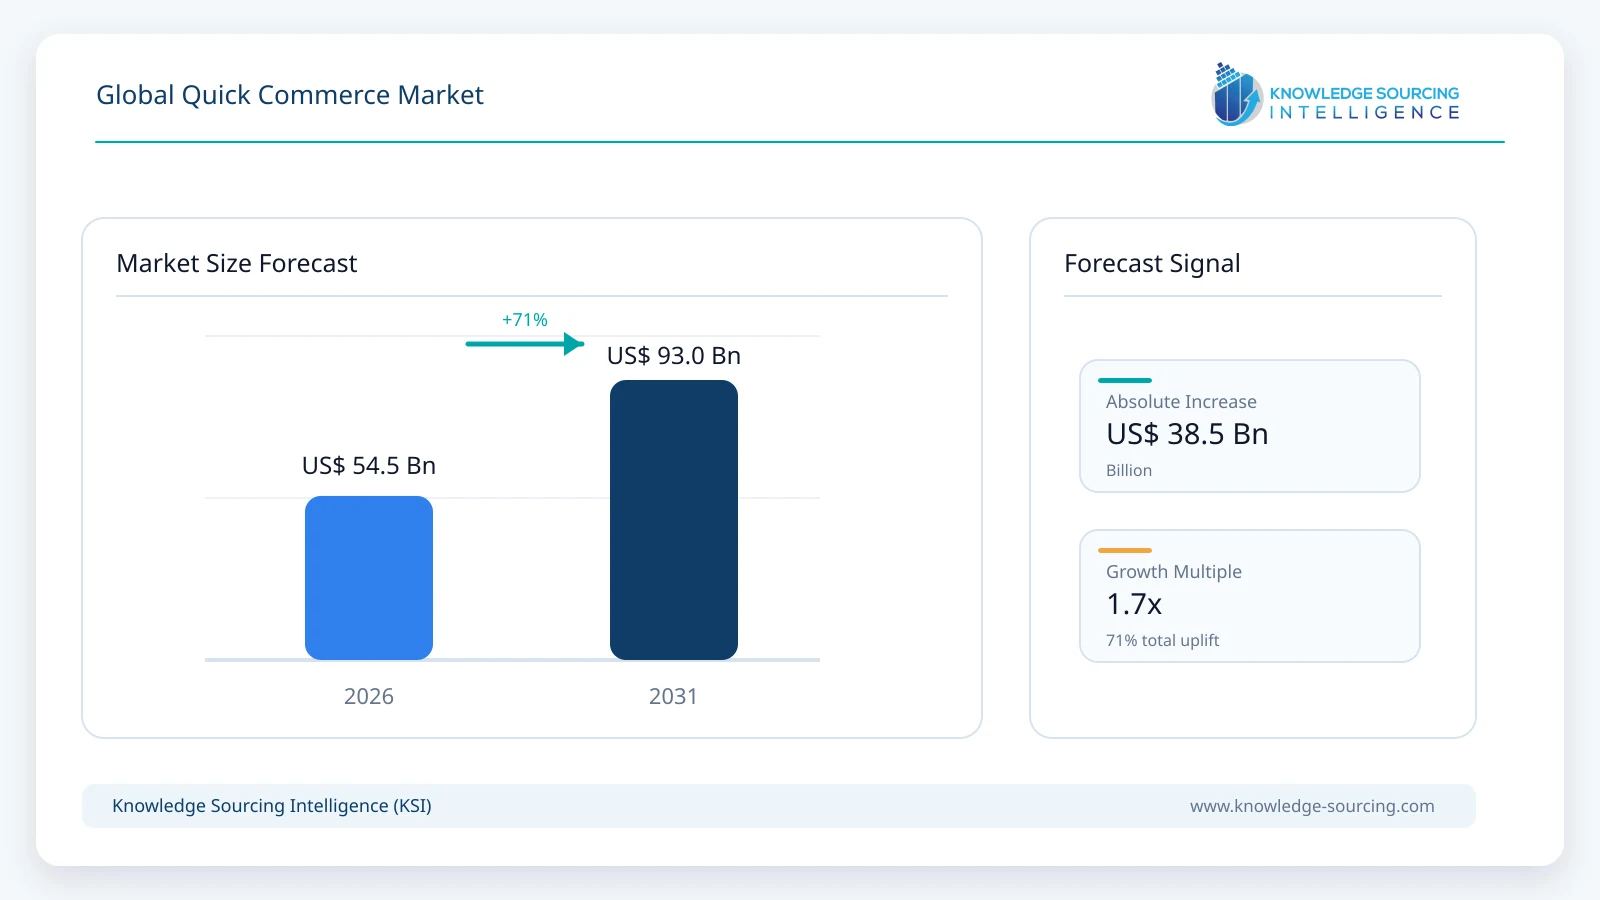
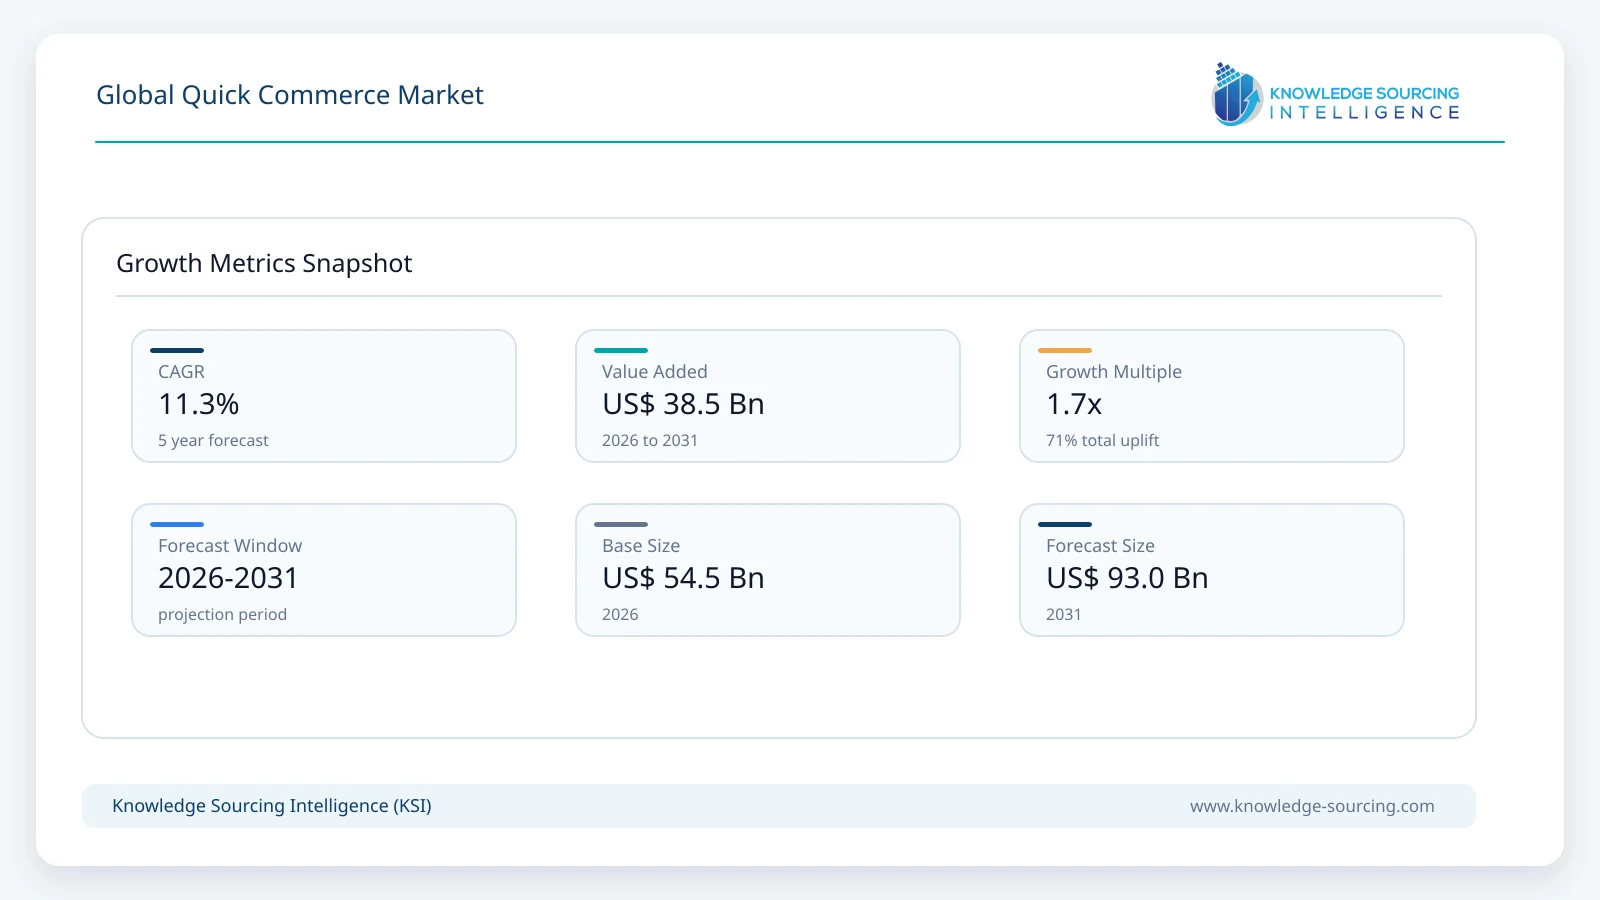
The Global Quick Commerce Market is forecast to grow at a CAGR of 11.3%, reaching USD 93.0 billion in 2031 from USD 54.5 billion in 2026.
Highlights:
- 1Market outlookThe Quick Commerce Market is estimated at USD 54.5 billion in 2026 and projected to reach USD 93.0 billion by 2031, reflecting an 11.3% CAGR.
- 2Core product categoryGrocery and Staples is a commercially important product category because frequent household purchases support repeat orders and customer retention.
- 3Assortment shiftSwiggy's non-grocery mix reached 26.2% of Instamart GOV in Q2 FY2026, indicating a widening revenue base beyond traditional grocery.
- 4Fulfillment scaleBlinkit had 2,400+ stores in June 2026, while Instamart operated more than 1,100 stores, highlighting the importance of dense local inventory networks.
- 5Basket economicsInstamart's FY2026 average order value reached INR 700, showing the growing commercial importance of larger baskets to quick-commerce profitability.
- 6Regional developmentAsia Pacific, particularly India, remains an important quick-commerce operating market, while North America is increasingly combining digital delivery platforms with established retail networks.
Market Overview
The global Quick Commerce Market covers digitally ordered products fulfilled through localized inventory points and delivered within short time windows, typically using dark stores, micro-fulfillment facilities, retail partners, or a combination of these models. The market is moving beyond emergency grocery purchases as platforms widen assortments into household essentials, personal care, electronics, medicines, toys, pet supplies, and other frequently or occasionally purchased products. The commercial model depends on a dense relationship between inventory availability, local demand, basket value, picking efficiency, delivery density, rider utilization, and delivery cost.
Consumer buying behavior is also changing the economics of the category. Larger baskets and broader assortments reduce the dependence on very small convenience orders, while dense store networks can improve delivery productivity when order volumes reach adequate levels. Swiggy reported that Instamart's average order value reached INR 700 in FY2026, up 32.8% year on year, while the network reached 1,143 stores across 129 cities.
The value proposition therefore depends on more than delivery speed. Availability, assortment, price, substitution quality, product freshness, delivery reliability, payment convenience, and customer trust increasingly influence repeat purchasing. Platforms are also using larger fulfillment locations to carry more stock and expand beyond conventional grocery categories. Swiggy's FY2025 annual report described larger dark stores of 3,500 to 4,500 square feet and Megapods of 10,000 to 12,000 square feet, with some Megapods capable of holding more than 50,000 SKUs.
What is driving the Quick Commerce Market?
The immediate demand mechanism is the reduction in the time and effort required to purchase everyday goods. Consumers can replace a short physical shopping trip with an app order, while retailers gain another channel for incremental transactions. The model becomes more commercially attractive when platforms can combine frequent grocery purchases with higher-value non-grocery products.
Why are quick commerce platforms expanding beyond groceries?
Grocery provides transaction frequency, but many grocery products have relatively low unit values. Platforms therefore have an incentive to increase basket size through personal care, household products, electronics, toys, beauty products, medicines where permitted, and other categories. Swiggy reported that non-grocery categories represented 26.2% of Instamart GOV in Q2 FY2026, compared with 8.7% a year earlier. This shift indicates how assortment expansion can change the economics of the model.
How are operators improving quick commerce economics?
Operators are shifting from indiscriminate geographic expansion toward better utilization of existing infrastructure, larger stores, broader assortments, and higher order values. Swiggy stated in January 2026 that its Instamart network had reached 1,136 active dark stores at the end of Q3 FY2026 and 4.8 million square feet of active dark-store area, while average store size had increased to 4,217 square feet.
Key Market Indicators
Indicator | Key Indicators | Business Impact |
|---|---|---|
U.S. retail e-commerce | 17.1% of total retail sales in Q2 2026 | A large digital retail base provides an established channel for rapid delivery models. |
Swiggy Instamart GOV | INR 7,881 crore in FY2026 | Higher transaction value is becoming central to quick-commerce economics in India. |
Instamart active stores | 1,143 stores in FY2026 | Dense local inventory remains central to short delivery windows. |
Instamart average order value | INR 700 in FY2026 | Larger baskets can improve revenue per delivery and reduce the burden of low-value orders. |
Blinkit stores | 2,400+ in June 2026 | Scale is shifting toward extensive local fulfillment networks in India. |
India gig and platform workers | 23.5 million projected for 2029–30 | Delivery labor availability and social-security obligations will remain material operating considerations. |
Market Drivers
Larger baskets and broader product selection. Quick commerce initially relied heavily on small, frequent grocery purchases. That model creates pressure on delivery economics because fulfillment and rider costs are incurred even when order values remain low. Platforms are responding by expanding into categories with higher average selling prices and by encouraging consumers to consolidate purchases. Swiggy's reported increase in AOV and its rising non-grocery mix show the commercial value of this strategy.
Dense local fulfillment networks. Delivery speed depends on the distance between inventory and the customer, making local inventory density a structural requirement. Dark stores allow operators to control assortment, inventory placement, picking, and dispatch without depending entirely on conventional store layouts. Eternal reported more than 2,400 Blinkit stores in June 2026, illustrating the scale of local fulfillment infrastructure being built in India.
Expansion of digital retail purchasing. Quick commerce benefits from a consumer base already comfortable with mobile ordering, digital payments, real-time tracking, and app-based product discovery. U.S. Census Bureau data showed that e-commerce accounted for 17.1% of total U.S. retail sales in the second quarter of 2026, with adjusted e-commerce sales of USD 340.2 billion. Quick commerce represents a narrower category within this broader digital retail channel, but the underlying purchasing infrastructure supports continued adoption.
Retailer demand for incremental digital reach. Traditional retailers increasingly use delivery platforms to add convenience without building a complete proprietary rapid-delivery infrastructure. Uber Eats expanded its grocery network through partnerships with regional grocers in 2025 and announced an expanded relationship with Kroger that was designed to bring nearly 2,700 stores across Kroger banners onto Uber Eats from early 2026.
Improved network utilization. Once a dense store network has been established, additional growth can come from increasing order frequency, assortment, basket size, and utilization rather than adding locations at the same rate. Swiggy's 2026 disclosures show this shift clearly. The company reported selective store additions while emphasizing network utilization and larger store formats.
Market Restraints and Challenges
Low order economics at small basket sizes. A rapid-delivery order carries picking, packing, payment-processing, customer-service, and last-mile costs. When order values are low, these costs consume a larger share of revenue. Platforms therefore face pressure to raise AOV without damaging customer frequency through excessive fees or reduced discounts.
Dark-store utilization and fixed operating costs. Local fulfillment requires rent, labor, inventory, utilities, technology, shrinkage controls, and delivery infrastructure. Underutilized stores can weaken contribution margins even when the network provides strong geographic coverage. Swiggy reported that network underutilization remained a factor in its quick-commerce contribution margin during FY2026, although larger baskets and cost improvements were helping offset the pressure.
Competitive pricing and customer acquisition costs. Platforms compete for habitual purchasing behavior through discounts, membership programs, delivery incentives, product pricing, and promotional campaigns. The resulting pressure can delay profitability even when order volumes rise. Operators must balance customer acquisition with contribution margin improvement rather than treating order growth as the sole performance measure.
Labor and delivery economics. The model depends on a large pool of delivery workers who can respond to concentrated demand during peak periods. India's Code on Social Security, 2020 was enforced on November 21, 2025, extending the framework to gig and platform workers and creating implications for social-security coverage and aggregator responsibilities. These changes can affect the cost structure of delivery-intensive platforms.
Inventory accuracy and product compliance. Short delivery windows increase the importance of real-time inventory accuracy. Stockouts, substitutions, expired food, damaged goods, and incorrect picking can weaken customer trust and raise refund costs. Food operators must also meet food-safety requirements. FSSAI states that food business operators must obtain the relevant license or registration, while its current compliance system specifically includes e-commerce food businesses.
Major Segment Analysis
Grocery & Staples
Grocery and staples remain a commercially important product category because they combine high purchase frequency with predictable household demand. Milk, packaged foods, fresh produce, beverages, household consumables, and pantry items create repeat ordering occasions that support customer retention. The category also gives platforms a base from which they can introduce higher-value products.
The economics of grocery quick commerce depend heavily on availability and inventory turns. Customers generally expect familiar brands, competitive prices, acceptable freshness, and low substitution rates. Operators therefore need accurate demand forecasting and sufficient local stock while limiting spoilage and excess inventory. These requirements make assortment planning a core operating capability rather than a simple catalog decision.
The category is also changing as platforms widen the range of products held in local fulfillment centers. Swiggy reported that larger stores and Megapods were being used to increase assortment while its non-grocery contribution expanded sharply. Grocery remains important because it generates recurring demand, while non-grocery categories can raise basket value and improve the revenue economics of each delivery.
Regional Analysis
North America
North American quick commerce is developing through a combination of dedicated rapid-delivery networks and partnerships between digital platforms and established retailers. Grocery and household essentials are particularly suited to this model because retailers already hold local inventory across dense store networks. Uber's expansion with regional grocery chains and its broader retail strategy demonstrate the importance of using existing retail infrastructure rather than relying exclusively on company-owned dark stores.
The region also benefits from a large established e-commerce market. U.S. retail e-commerce reached USD 340.2 billion in the second quarter of 2026 and represented 17.1% of total retail sales. The competitive challenge is converting this broad digital demand into economically viable short-window delivery while maintaining assortment and service quality.
Europe
European quick commerce faces a stronger regulatory overlay around online platforms, consumer protection, product traceability, and marketplace transparency. The European Commission states that the Digital Services Act applies to online marketplaces and requires obligations including trader traceability and reasonable efforts to check products offered through marketplaces.
These requirements increase the importance of seller verification, product information, complaint handling, and platform controls. European operators therefore need to balance fast fulfillment with compliance processes that may become more demanding as assortment expands across categories.
Asia Pacific
Asia Pacific has a broad base for quick commerce because mobile commerce, digital payments, dense cities, and large consumer populations support frequent app-based purchasing. India is particularly important to the regional market, with Blinkit and Instamart operating large dark-store networks and expanding product categories. Eternal reported more than 2,400 Blinkit stores in June 2026, while Swiggy reported 1,143 Instamart stores in FY2026.
China and other developed Asian markets operate under different platform, retail, and delivery structures. The commercial model therefore varies by local retail density, labor costs, payment behavior, regulation, and consumer expectations. Regional competition is likely to favor operators that can match delivery speed with sustainable basket economics rather than relying only on promotional intensity.
Middle East and Africa
Quick commerce adoption in the Middle East is supported by high smartphone penetration, concentrated urban demand, and consumer preference for convenience. The economics can differ materially from South Asian markets because of labor costs, import dependence, retail structures, and population density. Africa presents a more varied opportunity, with delivery economics influenced by infrastructure quality, payment access, addressability, and local retail fragmentation.
Competitive Landscape
The companies covered in the report include Gopuff, Getir, Flink, Zepto, Blinkit, Swiggy Instamart, Zapp, DoorDash, Meituan, and Uber Technologies. The competitive structure is platform-led but operationally dependent on local inventory and delivery capacity.
Competition is increasingly shifting from simple delivery-time claims toward assortment, availability, basket size, network density, fulfillment productivity, retailer relationships, and customer retention. Indian operators provide a clear example of this shift. Swiggy has expanded larger dark stores and Megapods, while Eternal's Blinkit network has exceeded 2,400 stores.
North American platforms are using a different route in several markets. DoorDash introduced DashMart Fulfillment Services in September 2025, allowing retailers to use DashMart infrastructure for inventory management, picking, packing, and delivery. CVS and Party City were among the initial users, with Kroger announced as an upcoming participant.
Uber is also emphasizing retailer integration. Its relationship with Kroger was expanded to bring nearly 2,700 stores across Kroger banners onto Uber Eats, while the company continued adding grocery and retail partners. This approach reduces the need for a purely dark-store-led model and gives retailers access to existing delivery infrastructure.
The resulting market structure contains several operating models: company-owned dark stores, retailer-fulfilled delivery, third-party marketplace delivery, hybrid fulfillment, and technology-enabled fulfillment services. Switching costs for consumers remain relatively low, which increases the importance of delivery reliability, assortment, price, memberships, loyalty programs, and user experience.
Recent Developments
August 2026: Swiggy announced that Instamart had reached more than 14 million monthly transacting users across 130+ cities and more than 1,200 dark stores, while its contribution margin approached breakeven. The company also outlined a FY31 target of more than INR 1.5 lakh crore in Instamart GOV.
April 2026: Eternal reported that more than 109 million Indians completed transactions worth over USD 10 billion through Blinkit, District, and Zomato during FY2026. The disclosure illustrates the increasing scale of Eternal's consumer platforms and the expanding role of Blinkit within its portfolio.
April 2026: DoorDash continued expanding its new-verticals business through grocery and retail partnerships, while its DashMart Fulfillment Services model moved beyond conventional marketplace delivery into retailer fulfillment. The model gives retailers access to inventory, picking, packing, and delivery infrastructure.
Regulatory and Policy Environment
India's Consumer Protection (E-Commerce) Rules, 2020 provide a core consumer-protection framework for online commerce, with subsequent amendments also listed by the Department of Consumer Affairs. Quick-commerce operators must therefore manage disclosures, consumer grievance mechanisms, seller information, and other applicable e-commerce obligations.
Food safety is particularly relevant because grocery represents a central category. FSSAI requires food businesses to obtain the appropriate license or registration, and its FoSCoS system identifies e-commerce as a specific food-business category requiring a central license where applicable. Current FSSAI announcements also include compliance obligations for e-commerce food businesses and updated food-safety requirements.
Labor policy is becoming more relevant as delivery networks expand. India's Ministry of Labour and Employment stated in January 2026 that the Code on Social Security, 2020 had been enforced from November 21, 2025 and covered gig and platform workers within the social-security framework. Operators and delivery aggregators therefore need to account for evolving workforce obligations when assessing long-term delivery costs.
Data governance is another operating consideration because quick-commerce platforms process location, payment, purchase, behavioral, and account information. India's Digital Personal Data Protection Rules, 2025 were published by MeitY in November 2025, together with an enforcement timeline and information concerning the Data Protection Board of India.
For operators selling OTC medicines, compliance becomes more specialized. India's Drugs and Cosmetics Act regulates the import, manufacture, distribution, and sale of drugs, while CDSCO maintains public notices concerning online drug sales and drug-sale requirements. Quick-commerce platforms therefore cannot treat medicines as ordinary grocery products when licensing, pharmacist supervision, prescription controls, labeling, and storage requirements apply.
Outlook and Strategic Implications
The 2026–2031 outlook favors operators that improve the economics of each local fulfillment node rather than simply increasing geographic coverage. The supplied market estimate indicates expansion from USD 54.5 billion in 2026 to USD 93.0 billion in 2031 at an 11.3% CAGR. The commercial quality of this growth will depend on whether higher order values, better assortment, greater network utilization, and improved delivery productivity can offset labor, real estate, inventory, and promotional costs.
Larger fulfillment formats are likely to become more important as platforms add products that do not require immediate replenishment. A broader assortment can increase wallet share, but it also raises inventory complexity and working-capital exposure. Operators will need stronger local demand forecasting, category-level replenishment, inventory controls, and pricing systems as product ranges expand.
Retail partnerships provide another route to scale. Uber and DoorDash demonstrate how delivery networks can be combined with established retail inventory, while Indian operators continue to invest in dedicated dark-store infrastructure. The competitive advantage will increasingly depend on selecting the right fulfillment model for each geography, product category, and order profile rather than applying one operating structure across all markets.
Key Questions for Business Analysts and Executives
What will determine Quick Commerce Market profitability?
Profitability will depend on basket value, order frequency, store utilization, picking productivity, delivery density, inventory accuracy, and promotional spending. Faster delivery alone does not guarantee attractive economics. Operators need sufficient orders per fulfillment location and enough revenue per delivery to absorb fixed infrastructure and last-mile costs.
Why are quick commerce companies expanding their assortment?
Broader assortments create additional purchase occasions and raise basket value. Grocery generates frequent demand, while electronics, household products, personal care, toys, beauty, and other categories can increase revenue per order. Swiggy's rise in non-grocery contribution demonstrates how assortment expansion is being used to improve the commercial mix.
How will dark stores evolve through 2031?
Dark stores are likely to become larger and more category-focused where demand supports deeper assortments. Smaller locations can remain useful in dense, high-frequency zones, while larger facilities can carry more SKUs and support higher-value categories. The balance will depend on local rent, order density, assortment requirements, and delivery distance.
What is the main competitive risk?
Low switching costs allow customers to move between platforms based on price, availability, delivery reliability, promotions, and assortment. Operators therefore need strong local execution rather than relying only on national brand recognition. Retail partnerships may also intensify competition by giving established retailers access to third-party delivery networks.
How will regulation affect the market?
Regulation will increasingly influence food safety, consumer protection, workforce obligations, personal-data handling, and medicine sales. Compliance costs may rise as platforms expand into regulated categories. Operators with stronger seller controls, traceability, inventory systems, data governance, and category-specific compliance processes will be better positioned to scale across jurisdictions.
What should investors monitor?
Investors should focus on contribution margin, AOV, order frequency, orders per dark store, store utilization, customer acquisition cost, promotional intensity, inventory losses, delivery cost per order, and the pace at which new stores reach acceptable utilization. Store count alone provides an incomplete view of operating quality.
Quick Commerce Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 54.5 billion |
| Total Market Size in 2031 | USD 93.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Payment Mode, Platform, Delivery Time |
| Companies |
|
Market Segmentation
By Product Type
Grocery & Staples
Snacks & Beverages
Dairy & Bakery
Personal Care Products
Household Essentials
Baby Products
Pet Supplies
Over-the-Counter (OTC) Medicines
By Payment Mode
Digital Wallets
Credit/Debit Cards
Cash on Delivery
By Platform
Mobile Application
Web-Based
By Delivery Time
10 Minutes
10–30 Minutes
30–60 Minutes
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL QUICK COMMERCE MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Grocery & Staples
5.3. Snacks & Beverages
5.4. Dairy & Bakery
5.5. Personal Care Products
5.6. Household Essentials
5.7. Baby Products
5.8. Pet Supplies
5.9. Over-the-Counter (OTC) Medicines
6. GLOBAL QUICK COMMERCE MARKET BY PAYMENT MODE
6.1. Introduction
6.2. Digital Wallets
6.3. Credit/Debit Cards
6.4. Cash on Delivery
7. GLOBAL QUICK COMMERCE MARKET BY PLATFORM
7.1. Introduction
7.2. Mobile Application
7.3. Web-Based
8. GLOBAL QUICK COMMERCE MARKET BY DELIVERY TIME
8.1. Introduction
8.2. 10 Minutes
8.3. 10–30 Minutes
8.4. 30–60 Minutes
9. GLOBAL QUICK COMMERCE MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Product Type
9.2.2. By Payment Mode
9.2.3. By Platform
9.2.4. By Delivery Time
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Product Type
9.3.2. By Payment Mode
9.3.3. By Platform
9.3.4. By Delivery Time
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Product Type
9.4.2. By Payment Mode
9.4.3. By Platform
9.4.4. By Delivery Time
9.4.5. By Country
9.4.5.1. United Kingdom
9.4.5.2. Germany
9.4.5.3. France
9.4.5.4. Italy
9.4.5.5. Spain
9.4.5.6. Others
9.5. Middle East and Africa
9.5.1. By Product Type
9.5.2. By Payment Mode
9.5.3. By Platform
9.5.4. By Delivery Time
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. United Arab Emirates
9.5.5.3. South Africa
9.5.5.4. Others
9.6. Asia Pacific
9.6.1. By Product Type
9.6.2. By Payment Mode
9.6.3. By Platform
9.6.4. By Delivery Time
9.6.5. By Country
9.6.5.1. China
9.6.5.2. India
9.6.5.3. Japan
9.6.5.4. South Korea
9.6.5.5. Indonesia
9.6.5.6. Taiwan
9.6.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Gopuff
11.2. Getir
11.3. Flink
11.4. Zepto
11.5. Blinkit
11.6. Swiggy Instamart
11.7. Zapp
11.8. DoorDash
11.9. Meituan
11.10. Uber Technologies
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
List of Tables
List of Figures
Navigate
Trusted by the world's leading organizations











