
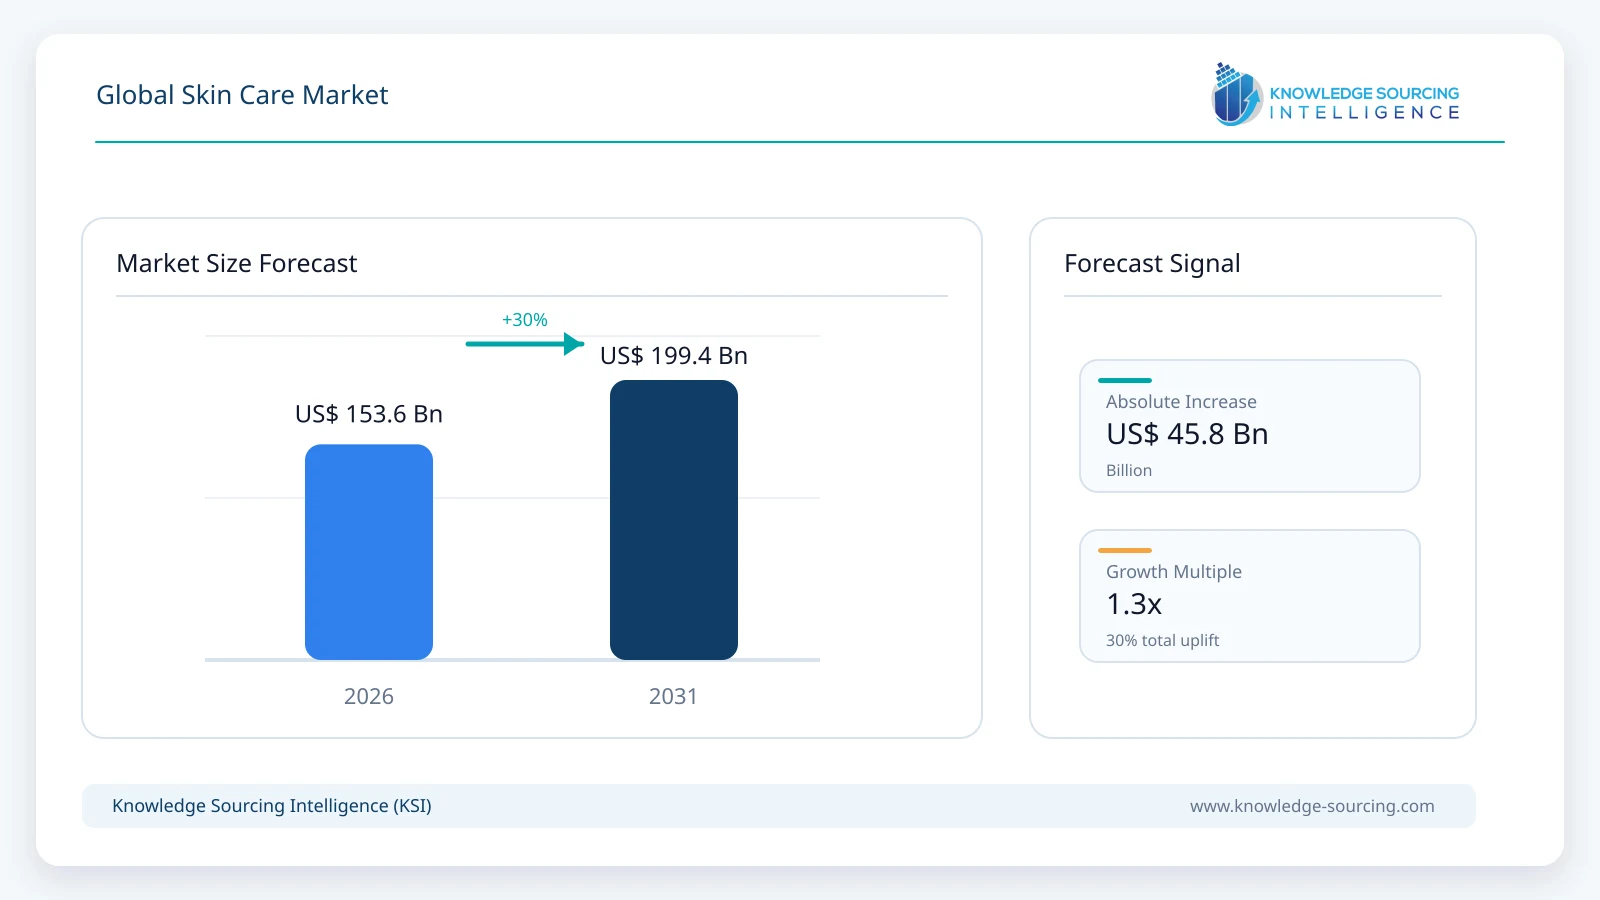
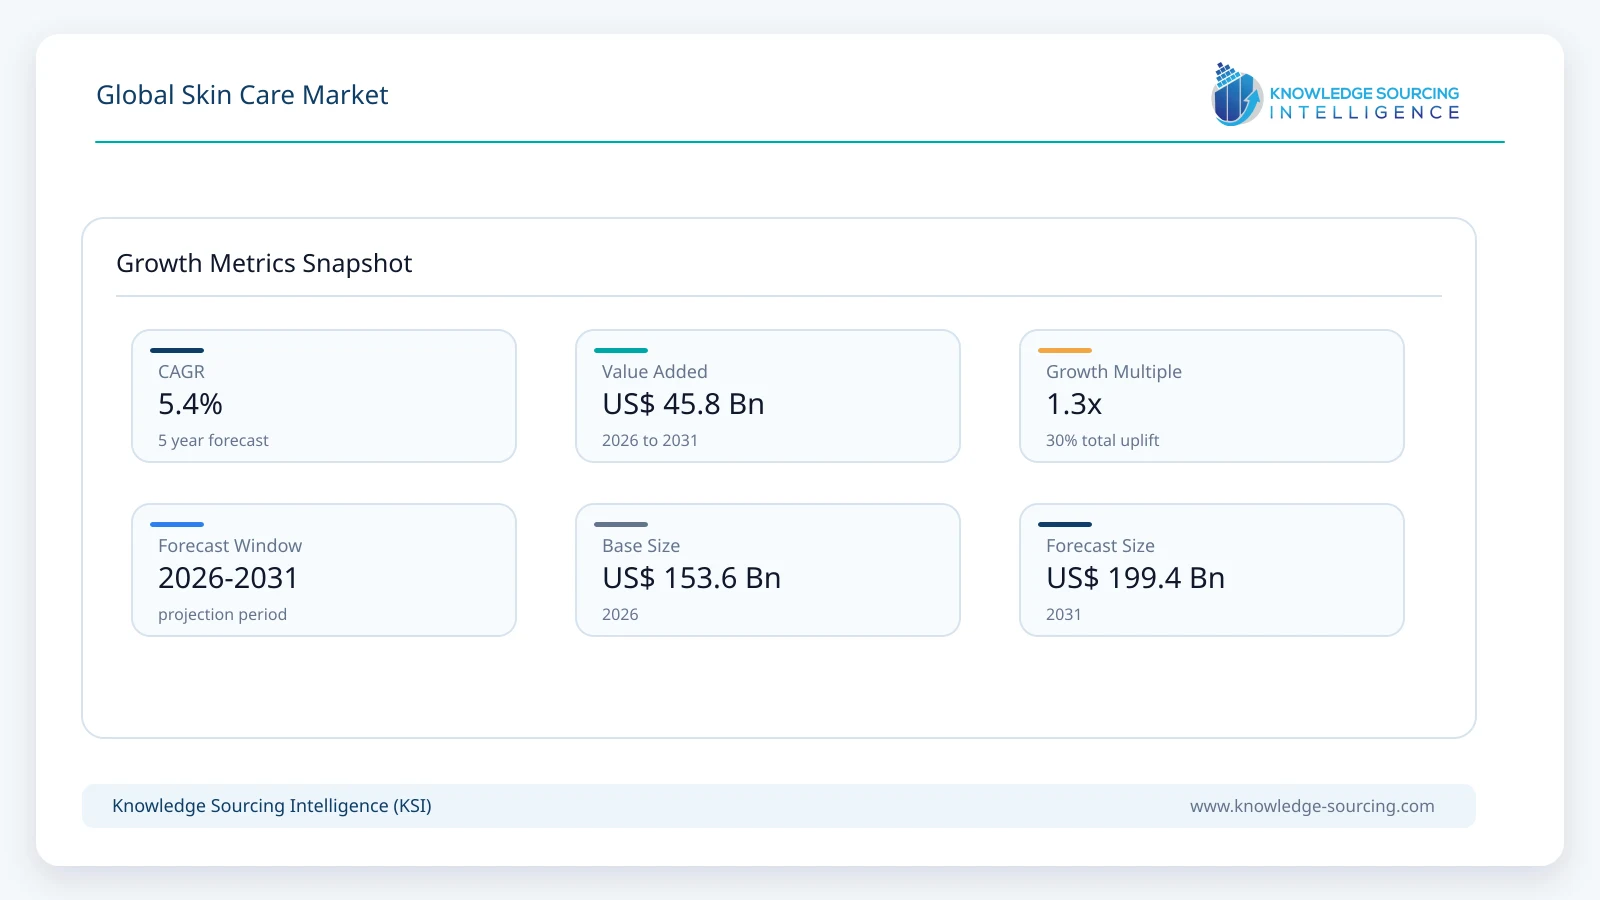
The Global Skincare Market is forecast to grow at a CAGR of 5.4%, reaching USD 199.4 billion in 2031 from USD 153.6 billion in 2026.
Highlights:
- 1Face care products account for approximately 71% of global skin care market value in 2026, supported by moisturizers, cleansers, serums, anti-aging products and targeted treatment formulations.
- 2Offline distribution accounts for approximately 72% of global market value in 2026, reflecting the continuing importance of pharmacies, beauty stores, supermarkets and department stores.
- 3Asia Pacific accounts for approximately 43% of global market value in 2026, supported by sophisticated skin-care routines, high category penetration and expanding consumer spending across China, Japan, South Korea and emerging Asian markets.
- 4L'Oréal estimates skin care represented approximately 39% of the global beauty market in 2025, maintaining its position as the industry's largest product category.
- 5Beiersdorf's Derma business recorded 7.8% organic sales growth in the first half of 2026, supported by Eucerin and Aquaphor, illustrating continued consumer demand for science-led dermatological skin care.
The market covers products designed primarily to cleanse, moisturize, protect and improve the condition or appearance of the skin. It includes face care, body care, sun care and lip care products sold through mass retail, pharmacies, specialty beauty stores, department stores, brand-owned channels and e-commerce platforms. Prescription dermatology products, professional aesthetic procedures, injectable treatments and general personal-care categories without a primary skin-care function are excluded.
Skin care remains the largest category within the global beauty market. L'Oréal estimates that skin care represented approximately 39% of the global beauty market in 2025, reflecting its position as a recurring-use category rather than a predominantly discretionary purchase. Demand is supported by daily use of cleansers, moisturizers and sun-care products alongside expanding interest in serums, barrier-repair formulations, pigmentation treatments, retinoids, peptides, ceramides, niacinamide and other active ingredients.
The market is increasingly divided between mass, premium and dermatological propositions. Large consumer brands continue to address high-volume moisturizing and cleansing demand, while dermocosmetic and prestige suppliers compete through clinical substantiation, differentiated active ingredients and dermatologist credibility. Beiersdorf reported continued outperformance from Eucerin and Aquaphor during 2026, while L'Oreal's Dermatological Beauty division continues to expand through La Roche-Posay, CeraVe, Vichy and SkinCeuticals. Estee Lauder similarly reported renewed growth in skin care during fiscal 2026, supported by La Mer, The Ordinary and Estee Lauder.
Digital commerce is also altering product discovery and brand competition. Consumers increasingly compare ingredients, clinical claims, user reviews, and dermatologist recommendations before purchase, reducing the informational advantage historically held by large established brands. E-commerce allows newer brands to scale rapidly without securing extensive physical shelf space, while multinational companies are increasing direct-to-consumer engagement, AI-assisted recommendations and personalized product discovery.
Market Trends
Dermatological Skin Care Is Expanding Beyond Traditional Pharmacy Channels
Dermatological and clinically positioned skin care is becoming a larger part of mainstream beauty consumption. Consumers increasingly seek products associated with dermatologists, clinically tested active ingredients and clearly defined outcomes for acne, pigmentation, sensitive skin, barrier repair and visible aging. This has strengthened brands including La Roche-Posay, CeraVe, Eucerin, Aquaphor, Avène and Cetaphil while encouraging mass and prestige brands to adopt more science-oriented positioning. L'Oréal reported a 25.8% share of the dermocosmetics market through its Dermatological Beauty division in 2025, while Beiersdorf's Derma business continued to outperform its wider consumer portfolio during 2026. The distinction between conventional cosmetics and dermatological skin care is therefore becoming less rigid as pharmacy brands expand into specialty beauty, online marketplaces and mainstream retail.
Active Ingredients Are Becoming Central to Consumer Purchasing
Skin care purchasing is increasingly organized around ingredients and functions rather than only around brand or product format. Consumers actively search for retinol, niacinamide, vitamin C, ceramides, hyaluronic acid, peptides, salicylic acid and other ingredients associated with specific outcomes. This encourages manufacturers to build product ranges around active concentrations and clinical claims while increasing pressure to provide understandable ingredient information. The Ordinary helped accelerate transparent ingredient-led positioning, while larger companies have increasingly adopted similar language across mass and premium portfolios. Beiersdorf continues expanding the use of proprietary actives such as Thiamidol, while Shiseido and Estée Lauder maintain substantial research programs around aging, pigmentation, skin structure and biological mechanisms. Ingredient differentiation therefore supports premiumization while also shortening innovation cycles as competing brands introduce products around similar consumer trends.
Skin Longevity Is Extending the Anti-Aging Category
Conventional anti-aging skin care is increasingly being repositioned around skin longevity, cellular resilience and healthy aging rather than solely wrinkle reduction. Estée Lauder published new clinical research around visible aging and its Re-Nutriv portfolio in April 2026, while Shiseido continued research into collagen structure, senescent cells and age-related biological changes during the year. L'Oréal has similarly positioned longevity as an expanding area across beauty and wellness. The commercial shift allows manufacturers to address consumers before visible aging becomes pronounced and creates opportunities for premium serums, moisturizers and treatment products positioned around preventive care. The trend is particularly relevant in developed Asian markets, Europe and North America, where aging populations coexist with high per-capita beauty spending.
E-Commerce Continues to Outgrow Physical Beauty Retail
Online channels are increasing their role in product discovery and replenishment. L'Oréal reported double-digit e-commerce growth in the first half of 2026, at nearly twice the pace of the wider beauty market. Digital channels are particularly effective for ingredient-led skin care because brands can provide detailed education, before-and-after content, clinical information and consumer reviews that are difficult to communicate on a conventional retail shelf. Direct-to-consumer platforms also allow brands to launch narrower products aimed at specific skin concerns without immediately requiring large physical distribution networks. Offline retail nevertheless remains commercially dominant because skin care continues to rely on pharmacies, specialty beauty stores, mass retailers and department stores for trial, consultation and immediate availability.
Market Drivers
Preventive Skin Health Is Becoming Part of Daily Consumer Routines
Consumers increasingly treat skin care as an ongoing health and wellness routine rather than an occasional cosmetic purchase. Daily cleansing, moisturizing, and sun protection create recurring product demand, while concerns around pollution, UV exposure, sensitivity, and impaired skin barriers encourage additional treatment products. This supports resilient purchase frequency even when discretionary beauty spending weakens.
The development is particularly visible in dermocosmetics. Consumers seek formulations that provide both cosmetic and functional benefits, while dermatologists and other healthcare professionals increasingly influence brand credibility. L'Oréal's Dermatological Beauty division reached more than 320,000 healthcare professionals in 2025, illustrating the scale of professional engagement surrounding modern skin-care brands.
Science-Backed Innovation Supports Premiumization
Clinical substantiation allows companies to differentiate products in a highly crowded market. Manufacturers continue investing in proprietary ingredients, biological research, delivery systems and clinical testing to support claims around pigmentation, acne, sensitivity and aging.
Beiersdorf introduced new microbiome technology for acne-prone skin under Eucerin in September 2026, while Estée Lauder presented new research during 2026 covering skin longevity, glycation, exosomes and UV protection. Shiseido continued publishing research into skin structure and cellular aging. These investments support premium pricing when consumers perceive a product as producing measurable outcomes rather than offering only sensory or branding benefits.
Emerging Markets Are Adding New Beauty Consumers
Rising incomes, urbanization and increased digital access continue expanding the addressable skin-care population across India, Southeast Asia, Latin America, the Middle East and parts of Africa. L'Oréal expects hundreds of millions of additional potential beauty consumers by 2030, with particularly strong demographic expansion across South Asia, the Middle East and Africa.
Multinational manufacturers are increasingly adapting formulation, pricing and digital communication to local consumer needs. In June 2026, L'Oréal announced the acquisition of a majority stake in India's digital-first personal-care company Innovist, reflecting the importance of locally developed brands in high-growth markets.
Social Media Accelerates Product Education and Adoption
Skin care lends itself strongly to digital education because consumers actively research ingredients, routines and visible results. Dermatologists, cosmetic chemists, creators and beauty communities can rapidly increase awareness of new ingredients or product formats, creating demand beyond traditional advertising.
The effect is particularly strong among younger consumers, who often discover products through TikTok, Instagram, YouTube and online beauty communities before purchasing through marketplaces or specialty retailers. Trends can therefore emerge rapidly, although the same environment also increases scrutiny when efficacy claims or product experiences fail to meet expectations.
Market Restraints
Category Saturation Increases Customer Acquisition Costs
Developed skin-care markets contain extensive product choice across nearly every price point and skin concern. Moisturizers, cleansers, vitamin C serums, retinoids, niacinamide products and barrier creams are available from mass, premium, dermatological and digital-first brands.
This abundance makes differentiation increasingly difficult. Brands need sustained investment in clinical evidence, creator marketing, retail visibility and consumer education, increasing the cost of acquiring and retaining customers. Smaller digital-first companies can scale rapidly when a product becomes popular but may face difficulty sustaining growth once larger competitors introduce comparable formulations.
Regulatory Scrutiny of Ingredients and Claims Is Increasing
Skin care companies operate across regulatory systems that differ in permitted ingredients, labeling, sun-protection claims, testing requirements and environmental standards. The European Union, United States, China, Japan and other major markets maintain different cosmetic frameworks, requiring international brands to adapt formulations and documentation.
Claims around anti-aging, acne, pigmentation and clinically proven efficacy receive particularly close scrutiny because wording can influence whether products remain classified as cosmetics or move toward pharmaceutical treatment claims. Regulatory complexity increases development timelines and creates additional compliance requirements for companies operating across multiple markets.
Consumers Are More Skeptical of Unsupported Claims
Ingredient awareness and easy access to product information have made consumers more critical of vague marketing language. Products positioned around clinical performance increasingly need visible evidence, credible testing or dermatologist support.
Social media amplifies both successful product experiences and negative reactions, which can quickly influence purchasing behavior. Companies consequently face greater reputational risk from exaggerated claims, undisclosed formulation changes or products that do not provide the expected consumer experience.
Economic Pressure Can Affect Prestige Skin Care
Daily skin care remains relatively resilient, but premium serums, luxury creams and complex multi-step routines remain partly discretionary. Inflation and weaker consumer confidence can encourage customers to reduce the number of products used, trade down to lower-priced formulations or extend replacement cycles.
This effect is not uniform across the market. High-performance dermocosmetics and established prestige franchises can remain resilient when consumers believe efficacy justifies the price, while undifferentiated premium products face greater pressure.
Segment Analysis
By Product: Face Care Products
Face care products are projected to generate approximately USD 145.5 billion by 2031, remaining the largest product segment throughout the forecast period. The category includes moisturizers, cleansers and toners, brightening products, serums, anti-aging formulations, acne-oriented products, masks and other treatments designed primarily for facial use.
The segment benefits from both frequency and complexity of use. Consumers often use several facial products within one routine, allowing suppliers to generate revenue across cleansing, hydration, treatment and protection rather than relying on one product. Facial skin is also the principal focus of anti-aging, pigmentation and acne concerns, giving the segment stronger exposure to premium actives and clinical innovation than most body-care categories.
Growth through 2031 is supported by dermocosmetics, ingredient-led purchasing and targeted treatments. Face care gradually increases its share of the wider skin-care market as consumers adopt higher-value serums and treatment products, although mass moisturizers and cleansers continue to generate substantial volume.
By Distribution Channel: Offline
Offline distribution is projected to generate approximately USD 138.5 billion by 2031, remaining the largest channel despite faster growth in e-commerce. Physical retail includes pharmacies, drugstores, specialty beauty stores, supermarkets, hypermarkets, department stores and brand-operated locations.
The channel remains important because consumers often want to test texture, fragrance and product feel before purchasing, while pharmacies and beauty stores provide consultation that is particularly valuable for dermatological and premium products. Large retailers also support immediate availability and brand visibility across consumers who do not begin product discovery online.
Online channels continue gaining relative share as consumers become more comfortable replenishing familiar products digitally and as marketplaces broaden access to specialist brands. The market therefore develops around omnichannel purchasing rather than a complete migration away from stores.
By Geography: Asia Pacific
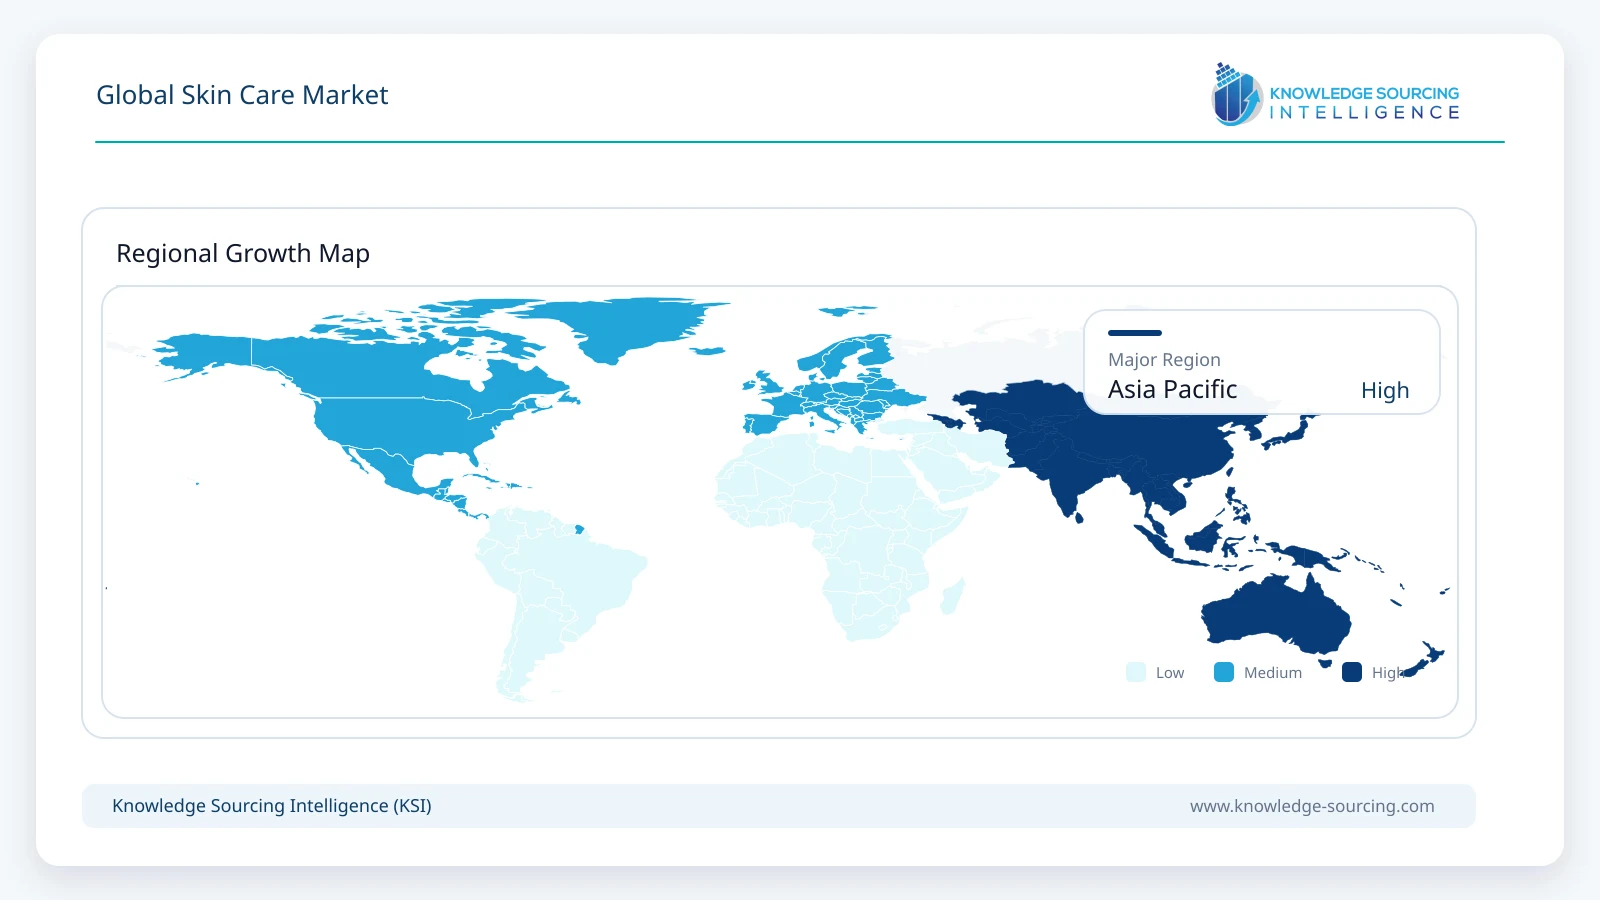
Asia Pacific is projected to generate approximately USD 91.7 billion by 2031, remaining the largest regional skin-care market. China, Japan and South Korea combine high category penetration with sophisticated consumer routines, while India and Southeast Asia provide additional growth through expanding middle-income populations and digital commerce.
Consumers across major Asian markets demonstrate strong interest in sun protection, brightening, hydration, anti-aging and multi-step facial routines. Japan and South Korea also maintain substantial domestic beauty industries with strong research and product-development capabilities, while Chinese brands continue gaining competitiveness through digital distribution and rapid product innovation.
The region's growth increasingly comes from a mixture of premiumization in established markets and penetration in emerging markets. Multinational suppliers therefore compete alongside increasingly capable Asian companies rather than relying solely on imported prestige positioning.
Competitive Environment and Analysis
The global skin care market combines multinational beauty companies, consumer-goods groups, prestige brands, dermatological specialists and rapidly expanding digital-first companies. L'Oréal maintains the broadest global portfolio across mass, luxury and dermatological skin care through brands including L'Oréal Paris, Lancôme, La Roche-Posay, CeraVe, Vichy and SkinCeuticals. The company reported continued growth across all divisions in the first half of 2026, with Dermatological Beauty maintaining particularly strong momentum.
Estée Lauder competes more heavily in prestige and high-performance skin care through Estée Lauder, La Mer, Clinique and The Ordinary. Fiscal 2026 skin-care sales increased approximately 4%, supported by La Mer, The Ordinary and Estée Lauder. Beiersdorf maintains major positions through NIVEA, Eucerin and Aquaphor, with its Derma business continuing to outperform the wider consumer portfolio.
Unilever participates through Vaseline, Dermalogica and Tatcha, while Shiseido combines prestige and Asian mass-premium brands including SHISEIDO, Clé de Peau Beauté, ELIXIR and Dr. Dennis Gross Skincare. Kao, Amorepacific, Kenvue, Galderma, Pierre Fabre, Rohto Pharmaceutical, Kosé, Clarins and L'Occitane add further competition across geographic and consumer segments.
Competitive advantage increasingly depends on formulation science, proven efficacy, brand trust, digital engagement and distribution breadth. Ingredient trends can be copied relatively quickly, making proprietary technology, clinical validation and established consumer communities more difficult to replicate than product formulations alone.
Recent Developments
September 2026: Beiersdorf introduced Eucerin DERMOPURE CLINICAL PROBIOM8, using viable skin-native probiotics for acne-prone skin and expanding the company's microbiome-based dermatological skin-care portfolio.
September 2026: Beiersdorf launched NIVEA FACE+ across Europe, extending a targeted facial-moisturizer concept using ingredients including vitamin C, hyaluronic acid, niacinamide and panthenol.
August 2026: Estée Lauder reported fiscal 2026 skin-care sales growth of approximately 4%, supported by La Mer, The Ordinary and Estée Lauder.
July 2026: Shiseido announced new research into "Ring Collagen," identifying a collagen structure associated with maintaining facial shape.
June 2026: L'Oréal agreed to acquire a majority stake in Indian digital-first personal-care company Innovist, expanding its exposure to science-led local brands in India.
April 2026: Estée Lauder published new peer-reviewed research supporting its Re-Nutriv skin-longevity positioning and a new methodology for evaluating visible age across diverse skin tones.
Market Outlook
The global skin care market encompasses daily skin-health routines, dermocosmetics, active ingredients and premium treatment products, with consumer interest in personal wellness and advanced skin-health solutions supporting continued market development.
Face care remains the largest product category and strengthens its position as consumers adopt more complex routines involving serums, active treatments and targeted products alongside basic moisturizers and cleansers. Body care, sun care and lip care continue to expand, particularly as skin-barrier and UV-protection awareness increases.
Offline retail continues to generate the majority of sales, but e-commerce gains share through ingredient-led product discovery, subscriptions, replenishment and direct-to-consumer brands. Leading manufacturers increasingly operate integrated omnichannel strategies rather than treating online and physical retail as separate businesses.
Asia Pacific remains the largest regional market through 2031, supported by established beauty cultures in North Asia and expanding purchasing power across India and Southeast Asia. Emerging markets contribute an increasing share of incremental consumers, while North America and Europe remain important for premium, clinical and dermatological skin care.
Growth is therefore expected to remain steady rather than explosive, with the strongest commercial opportunities concentrated in facial care, dermocosmetics, science-led actives, skin longevity and digitally enabled personalization.
Skin Care Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 153.6 billion |
| Total Market Size in 2031 | USD 199.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Product
Face Care Products
Face Moisturizers
Brightening Products
Cleansers And Toners
Serums And Treatments
Others
Body Care Products
Sun Care Products
Lip Care Products
By Distribution Channel
Online
Offline
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East And Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Skin Care Market Size, 2026-2031
3.3. Product Outlook
3.4. Distribution Channel Outlook
3.5. Regional Outlook
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Preventive Skin Health and Daily Skin-Care Routines
4.1.2. Science-Backed Innovation and Premiumization
4.1.3. Expansion of Emerging Beauty Markets
4.1.4. Digital Product Discovery and Social Commerce
4.2. Market Restraints
4.2.1. Category Saturation and Customer Acquisition Costs
4.2.2. Regulatory Scrutiny of Ingredients and Claims
4.2.3. Consumer Skepticism Toward Unsupported Claims
4.2.4. Economic Pressure on Prestige Skin Care
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Regulatory and Product Safety Environment
5. GLOBAL SKIN CARE MARKET BY PRODUCT
5.1. Face Care Products
5.1.1. Face Moisturizers
5.1.2. Brightening Products
5.1.3. Cleansers and Toners
5.1.4. Serums and Treatments
5.1.5. Others
5.2. Body Care Products
5.3. Sun Care Products
5.4. Lip Care Products
6. GLOBAL SKIN CARE MARKET BY DISTRIBUTION CHANNEL
6.1. Online
6.2. Offline
7. GLOBAL SKIN CARE MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. United Kingdom
7.3.2. Germany
7.3.3. France
7.3.4. Italy
7.3.5. Spain
7.3.6. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. UAE
7.4.3. South Africa
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. Japan
7.5.3. India
7.5.4. South Korea
7.5.5. Australia
7.5.6. Thailand
7.5.7. Indonesia
7.5.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. L'Oréal S.A.
9.2. The Estée Lauder Companies Inc.
9.3. Unilever PLC
9.4. The Procter & Gamble Company
9.5. Beiersdorf AG
9.6. Shiseido Company, Limited
9.7. Kao Corporation
9.8. Amorepacific Corporation
9.9. Kenvue Inc.
9.10. Galderma Group AG
9.11. Pierre Fabre S.A.
9.12. Natura &Co Holding S.A.
9.13. Kosé Corporation
9.14. Rohto Pharmaceutical Co., Ltd.
9.15. Clarins Group
9.16. L'Occitane International S.A.
10. APPENDIX
Navigate
Trusted by the world's leading organizations











