
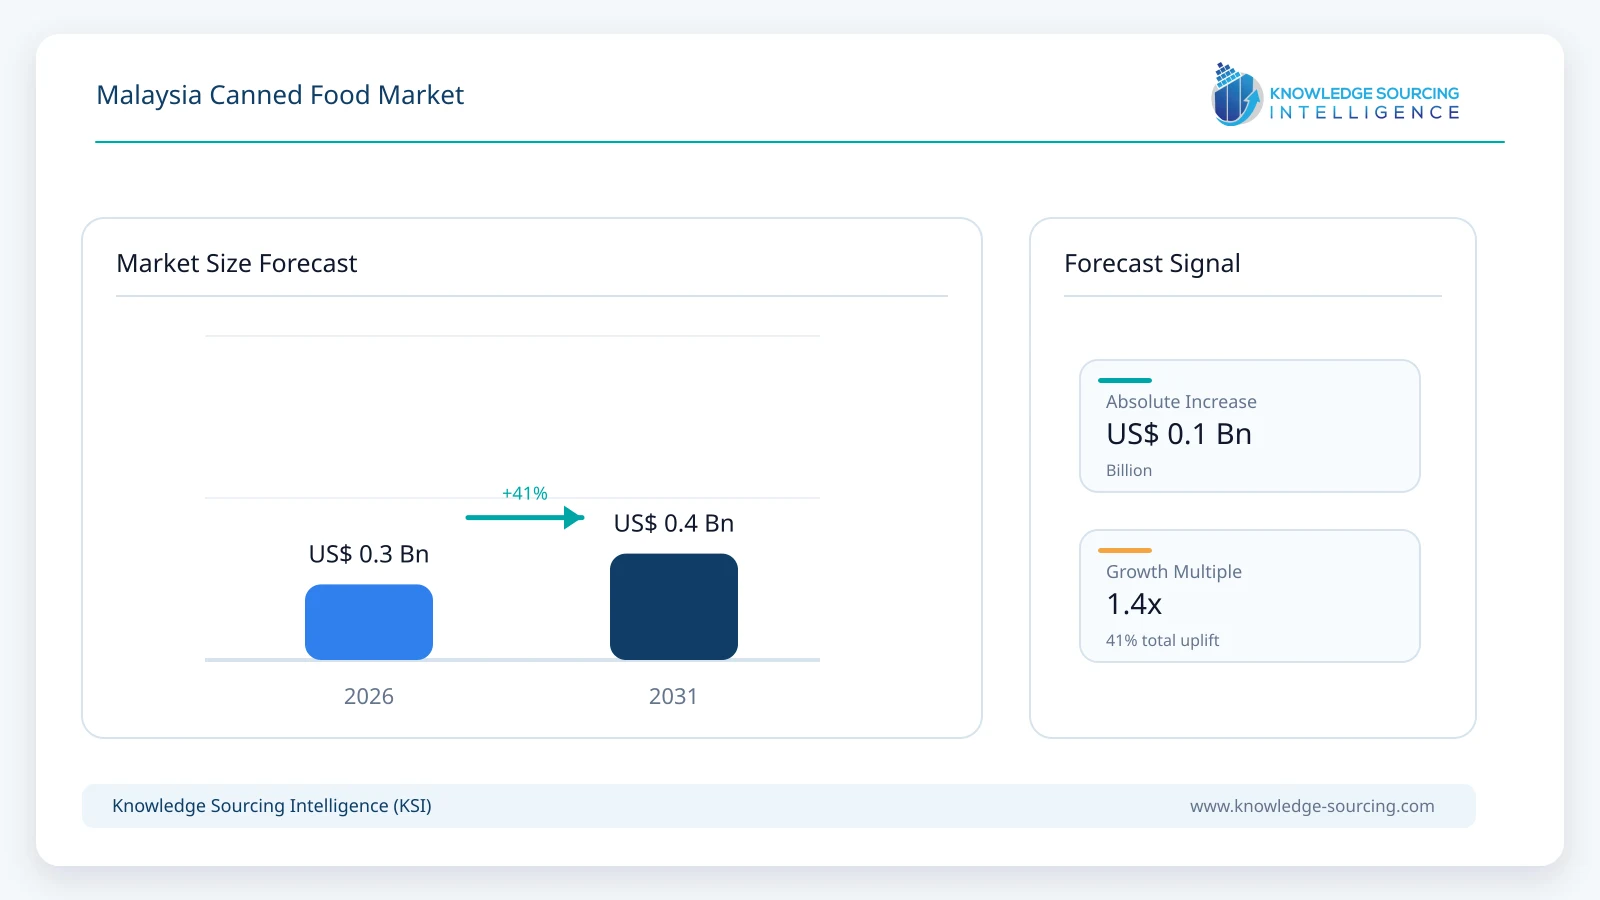
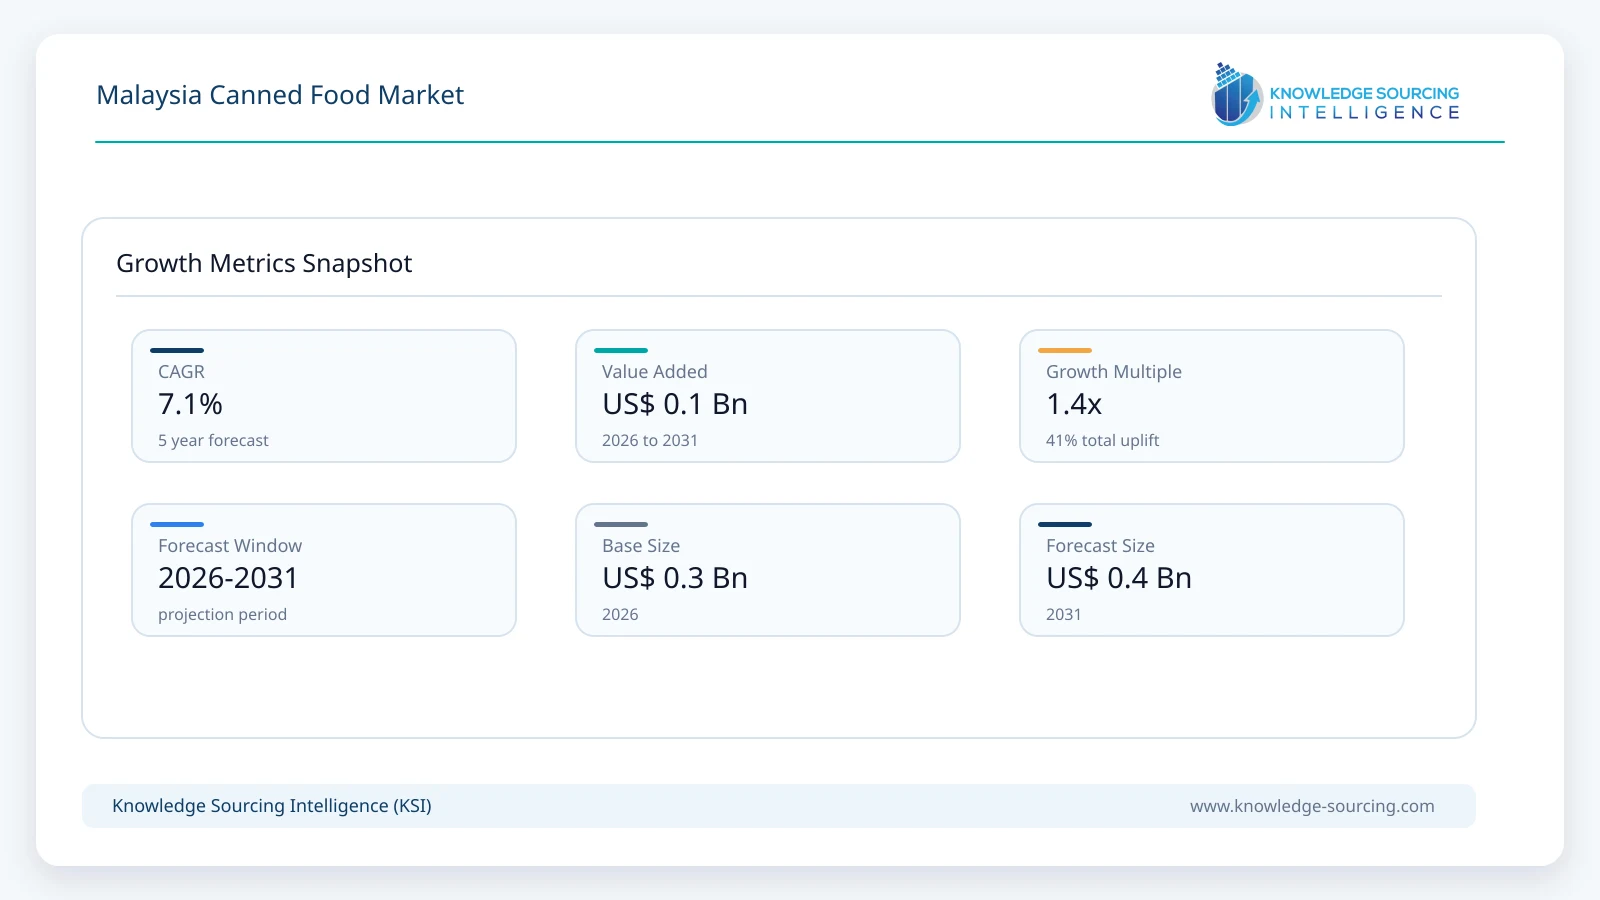
The Malaysian Canned Food market is forecast to grow at a CAGR of 7.1%, reaching USD 377.0 million in 2031 from USD 267.6 million in 2026.
Highlights:
- 146% of market value in 2026Canned Fish and Seafood accounts for approximately .
- 2USD 53.5 million in 2026Canned Meat Products represent approximately .
- 37.2% annually through 2031Canned Vegetables are projected to grow at approximately .
- 49% annuallyOther Canned Foods, including prepared meals and specialty products, are projected to grow at approximately , faster than the total market.
- 5Offline retail remains the principal channel, while Online sales are projected to record a low-double-digit CAGR.
- 6Selangor remains the largest geographic market, while Johor records one of the stronger forecast growth rates.
- 7Malaysia’s food-manufacturing investment and processed-food exports provide additional scale for local canned-food manufacturers.
Demand is supported by the continued role of canned products as affordable, shelf-stable and convenient foods across Malaysian households, foodservice establishments and institutional buyers. The market includes canned fish and seafood, meat products, vegetables, fruits and a growing range of prepared meals and other shelf-stable foods. Canned products remain commercially relevant because they reduce refrigeration dependence, provide long storage life and allow manufacturers to distribute products efficiently across both Peninsular and East Malaysia.
Canned Fish and seafood remain the largest product category and account for approximately 46% of market value in 2026. Sardines, mackerel and tuna are well established in Malaysian household consumption, supported by brands including Ayam Brand, King Cup, TC Boy, Botan, Rex and other domestic and regional participants. Marushin Canneries states that King Cup accounts for around 30% of Malaysia’s canned sardine and mackerel market, illustrating the depth of domestic demand for shelf-stable seafood.
The domestic market is also benefiting from broader investment in food manufacturing and Malaysia’s increasing role as a processed-food exporter. Approved investment in Food Manufacturing reached approximately RM6.3 billion in 2025 and RM4.9 billion during the first half of 2026. The H1 2026 figure was around 40.9% higher than the corresponding period a year earlier, indicating continued investment in food-processing capacity, automation and export-oriented manufacturing.
Malaysia’s processed-food export position is particularly relevant because canned-food manufacturers can use the same processing, sterilisation, packaging and quality-control infrastructure to serve both domestic and international customers. Processed-food exports to the Middle East and North Africa reached approximately RM2.42 billion in 2025, while Malaysian companies continue to promote Halal-certified convenience and shelf-stable foods internationally.
Growth Drivers and Trends
Convenience and Shelf Stability Support Core Household Demand
Canned food retains a strong position because it provides one of the simplest ways to store protein, vegetables, fruits and prepared meals for extended periods without refrigeration before opening. This is particularly relevant for urban households seeking rapid meal preparation, families maintaining pantry stocks, and consumers in areas where fresh-food availability can vary. Unlike frozen foods, canned products do not depend on continuous cold-chain infrastructure, improving distribution economics across smaller retail outlets and geographically dispersed markets.
Malaysia’s income profile supports broader consumption of branded packaged food. Median monthly household income reached RM7,017 in 2024, while the urban median was RM8,139. Kuala Lumpur and Selangor recorded median household incomes above RM10,700, supporting both mass-market canned staples and higher-value convenience products.
Manufacturers are consequently expanding canned products beyond basic preservation. Current portfolios include ready-to-eat chicken, soups, curries, sauces, prepared seafood and other meal components in addition to sardines, tuna, vegetables and beans. This broadens consumption occasions and helps the market participate in Malaysia’s larger convenience-food trend.
Processed-Food Exports Support Manufacturing Scale
Malaysia’s export infrastructure provides a significant advantage to the canned-food industry. Food manufacturers can serve ASEAN markets, the Middle East and other international destinations using established ports, Halal certification and regional trade agreements. International demand helps producers operate larger manufacturing runs and spread the fixed cost of filling, sterilisation, canning, laboratory testing and packaging across a wider output base.
Food Manufacturing attracted approximately RM4.9 billion of approved investment in the first half of 2026, while nearly one-third of all approved Malaysian manufacturing projects during the period planned to export at least 80% of their output.
This export orientation is particularly relevant for seafood processors. Malaysian companies manufacture canned sardines, mackerel and tuna for domestic consumers while also serving markets across Asia, Oceania, Africa and other regions. The result is a manufacturing base whose economics extend beyond domestic canned-food consumption alone.
Halal Positioning Strengthens Domestic and Export Competitiveness
Halal compliance remains strategically important to Malaysia’s processed-food industry because it provides access to the country’s large Muslim consumer base while also supporting export positioning in Muslim-majority markets. For canned seafood, meat and prepared meals, certification influences formulation, ingredient sourcing, manufacturing controls and supply-chain documentation.
The commercial importance extends beyond religious compliance. International distributors increasingly use recognized certification as a quality and traceability signal when sourcing Malaysian packaged foods. Malaysia’s processed-food exports to MENA reached RM2.42 billion in 2025, while MATRADE’s Gulfood 2026 promotion placed significant emphasis on Halal-certified convenience products.
Manufacturers capable of combining Halal assurance with long shelf life, regional flavours and export-scale manufacturing are consequently positioned to serve a larger addressable market than domestic Malaysia alone.
Product Portfolios Are Expanding Beyond Traditional Sardines
Sardines, mackerel and tuna remain central to the market, but product development is gradually shifting towards complete or near-complete meals. Malaysian manufacturers increasingly offer curries, ready-to-eat proteins, soups, sauces, beans and other foods that require minimal additional preparation.
This shift increases the commercial importance of the Other Canned Foods category. The segment is projected to grow at approximately 9% annually through 2031, above the total-market rate. Prepared formulations also provide greater scope for flavour differentiation and brand positioning than standardized canned vegetables or basic fish products.
The market therefore evolves from preservation-led consumption towards broader meal convenience while retaining the long shelf life and distribution advantages of traditional canned products.
Modern Retail and E-Commerce Expand Product Availability
Offline retail remains the dominant purchasing channel because canned food is a routine grocery product and supermarkets can stock wide assortments without requiring refrigerated space. Hypermarkets, supermarkets, convenience stores, and traditional grocery outlets therefore continue to account for most sales.
Online Distribution represents approximately USD 37.5 million in 2026 and is projected to grow at around 13% annually through 2031. Canned food is well suited to e-commerce because products are standardized, shelf-stable, and frequently purchased in multipacks. Digital channels also allow smaller brands and specialty products to reach customers without securing national shelf space.
Online sales nevertheless remain supplementary rather than replacing physical grocery retail during the forecast period.
Market Restraints
Imported Fish Inputs Create Raw-Material Exposure
Malaysia’s canned seafood industry remains partly dependent on imported raw fish. Marushin Canneries states that it imports approximately 4,500 metric tons of sardines and mackerel annually from Mexico and South Africa for King Cup production.
This exposes manufacturers to international fish prices, shipping costs, exchange rates and availability. Because seafood represents the largest product segment, volatility in sardine, mackerel and tuna inputs can materially affect industry margins.
Metal Packaging and Energy Costs Affect Production Economics
Canning requires tinplate or aluminium packaging, coatings, cartons and significant thermal-processing energy. These inputs create additional cost exposure even when food commodity prices remain stable.
The impact is particularly important in value-oriented categories because packaging represents a meaningful part of total unit cost. Manufacturers need to balance lighter packaging and production efficiency against food-safety, shelf-life and package-integrity requirements.
Fresh, Frozen and Retort Foods Compete for Convenience Demand
Canned products no longer compete only with other canned brands. Frozen foods, chilled meals, retort pouches, instant foods and food-delivery services increasingly compete for the same convenience-oriented eating occasions.
Retort pouches are particularly relevant because they provide long shelf life with lower package weight and can support prepared meals in formats that consumers may perceive as more contemporary. Canned-food manufacturers therefore need to compete on taste, price, nutrition and convenience rather than relying solely on shelf stability.
Health Considerations Increase Reformulation Requirements
Sodium, sugar and fat levels vary considerably across canned-food categories, and health-conscious consumers increasingly compare nutritional panels. Manufacturers are responding with lower-sodium sauces, foods packed in water and products with simplified ingredient positioning.
Malaysia has also introduced limits on industrially produced trans fats, increasing formulation and compliance requirements for certain prepared food products. The direct impact on simple canned fish and vegetables is limited, but formulated meals and sauces face greater scrutiny.
Price Sensitivity Limits Premiumisation
Although Malaysian household income is increasing, canned food remains an important value category. Consumers can compare similarly sized tins directly, creating high price transparency and limiting manufacturers’ ability to pass through raw-material inflation.
Premium products perform best in higher-income urban markets, but value-oriented sardines, fish, beans and vegetables continue to account for substantial physical demand. Market growth therefore depends on balancing affordability with incremental value from convenience, flavour and quality.
Segment Analysis
By Type
Canned Fish and Seafood accounts for approximately 46% of market value in 2026, equivalent to around USD 123.1 million. Sardines and mackerel remain the core products, while tuna supports both mainstream and premium demand. Malaysia has a particularly deep competitive base in this category, with Ayam Brand, King Cup, TC Boy, Botan, Rex, Pertima and other brands operating across domestic retail.
Canned Meat Products represent approximately USD 53.5 million in 2026. The category includes chicken, beef, prepared meat dishes and other shelf-stable protein products. Its expansion is supported by demand for rapid meal preparation, but it remains smaller than seafood because canned sardines and mackerel are more deeply established in Malaysian food consumption.
Canned Vegetables are projected to grow at approximately 7.2% annually through 2031. Sweet corn, beans, peas, mushrooms and related products provide convenient ingredients for households and foodservice operators. Their long shelf life and relatively low preparation requirements support steady demand.
Canned Fruits remain a smaller category and compete directly with Malaysia’s abundant fresh tropical fruit supply. Demand is concentrated in desserts, foodservice, bakery applications and selected household uses.
Other Canned Foods are projected to record approximately 9% annual growth, making them the fastest-growing major category. Prepared meals, soups, curries, sauces, and other shelf-stable products increase the role of canned food from preserved ingredient to convenient meal solution.
By Distribution Channel
Offline Distribution represents approximately USD 230.1 million in 2026 and remains the dominant channel. Supermarkets and hypermarkets provide broad assortment and promotional visibility, while convenience stores and traditional outlets extend availability into smaller towns and residential areas.
Online Distribution accounts for approximately 14% of 2026 market value and grows substantially faster than the offline channel. Multipack purchasing, online grocery services and marketplace availability improve access to both established brands and specialty products.
By 2031, physical stores remain dominant, but digital retail accounts for a materially larger share of incremental market growth.
Geographical Outlook
Selangor accounts for approximately 30% of market value in 2026, equivalent to around USD 80.3 million. The state combines Malaysia’s largest economic base with high household income, dense retail networks, food-manufacturing activity and proximity to Port Klang.
Kuala Lumpur remains disproportionately important relative to population because of high household spending power and demand for premium and imported foods. The territory recorded Malaysia’s highest median monthly household income in 2024.
Johor represents approximately 15% of the 2026 market and is projected to grow at around 8% annually through 2031. Its large population, food-manufacturing base, proximity to Singapore and strong logistics position support both domestic consumption and processing activity.
Sarawak accounts for a smaller share but retains structural demand for shelf-stable foods because of longer distribution distances across parts of East Malaysia.
Other states collectively represent a substantial share of total consumption and include important urban and manufacturing centres such as Penang, Sabah and Perak.
Recent Developments
In the first half of 2026, Malaysia approved approximately RM4.9 billion of investment in Food Manufacturing, an increase of around 40.9% from the corresponding period of 2025.
During 2026, Malaysian processed-food producers continued to expand their international visibility through MATRADE-led trade programmes, with Halal-certified convenience and retort foods positioned as priority export categories.
Malaysia entered 2026 after processed-food exports to the MENA region reached RM2.42 billion in 2025, highlighting the international opportunity for shelf-stable Malaysian foods.
Manufacturers also continued to broaden their product ranges beyond traditional seafood into prepared meals, sauces, proteins, and convenience formats, strengthening competition with retort and frozen foods.
Competitive Environment
The Malaysia Canned Food Market combines established domestic manufacturers, Southeast Asian regional brands and imported international companies. Ayam Brand maintains one of the broadest canned-food portfolios, while Marushin Canneries has a particularly strong position in sardines and mackerel through King Cup.
Domestic competition is deeper than the previous company list suggested. ETA Group/Rex, Protigam, TC Boy, Pertima, Adabi, Sunstar and Makmur participate across seafood, prepared foods and other canned categories. Local manufacturing allows these companies to adapt formulations and pricing to Malaysian consumer preferences while benefiting from domestic distribution and Halal expertise.
International competitors add canned fruit, vegetables, meat, seafood and soups. Del Monte Pacific, Kraft Heinz, Hormel, Campbell’s, Century Pacific, Thai Union, Hosen and Dole expand the range available through modern retail and imported-food channels.
Competition through 2031 is expected to centre on affordability, sourcing reliability, Halal assurance, flavour localization and expansion into higher-value meal solutions. Strong local and regional manufacturers should retain an advantage where supply-chain responsiveness and product adaptation are more important than global scale alone.
Analyst View
The Malaysia Canned Food Market remains fundamentally defensive because shelf stability, affordability, and pantry convenience continue to support household demand, while Malaysia’s established food-processing and export ecosystem strengthens manufacturing capabilities and market accessibility.
Canned Fish and seafood remain the market’s foundation, but it is unlikely to be the only meaningful source of value growth. Prepared meals, canned proteins and other convenient products are becoming more important as consumers compare canned foods with pouches, frozen meals and food delivery rather than only with alternative canned brands.
Malaysia’s role as a Halal food exporter provides an additional structural advantage. Manufacturers capable of serving both domestic consumers and international distributors can achieve greater manufacturing scale and justify investment in automation, quality assurance and new formats.
The strongest competitive position through 2031 therefore belongs to companies that preserve the category’s affordability while adding convenience, local flavour profiles, transparent certification and wider channel access.
Malaysia Canned Food Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 267.6 million |
| Total Market Size in 2031 | USD 377.0 million |
| Forecast Unit | Million |
| Growth Rate | 7.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Distribution Channel , Geography |
| Companies |
|
Market Segmentation
By Type
· Canned Fish/Seafood
· Canned Meat Products
· Canned Vegetables
· Canned Fruits
· Other Canned Foods
By Distribution Channel
· Online
· Offline
o Supermarkets/Hypermarkets
o Convenience Stores
o Others
By Geography
· Selangor
· Kuala Lumpur
· Johor
· Sarawak
· Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. MALAYSIA CANNED FOOD MARKET BY TYPE
5.1. Introduction
5.2. Canned Fish/Seafood
5.3. Canned Meat Products
5.4. Canned Vegetables
5.5. Canned Fruits
5.6. Other Canned Foods
6. MALAYSIA CANNED FOOD MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Online
6.3. Offline
6.3.1. Supermarkets/Hypermarkets
6.3.2. Convenience Stores
6.3.3. Others
7. MALAYSIA CANNED FOOD MARKET BY GEOGRAPHY
7.1. Introduction
7.2. Selangor
7.3. Kuala Lumpur
7.4. Johor
7.5. Sarawak
7.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Denis Asia Pacific Pte. Ltd. / Ayam Brand
9.2. Yeo Hiap Seng (Malaysia) Sdn. Bhd.
9.3. ETA Group Berhad / Rex
9.4. Adabi Consumer Industries Sdn. Bhd.
9.5. Marushin Canneries (Malaysia) Sdn. Bhd. / King Cup
9.6. Protigam Food Industries Sdn. Bhd.
9.7. TC Boy Marketing Sdn. Bhd.
9.8. Pertima Terengganu Sdn. Bhd.
9.9. Sunstar Food Industries Sdn. Bhd.
9.10. Makmur Food Industries Sdn. Bhd.
9.11. Del Monte Pacific Limited
9.12. The Kraft Heinz Company
9.13. Hormel Foods Corporation
9.14. The Campbell’s Company
9.15. Century Pacific Food, Inc.
9.16. Thai Union Group PCL
9.17. Hosen Group Ltd.
9.18. Dole plc
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











