
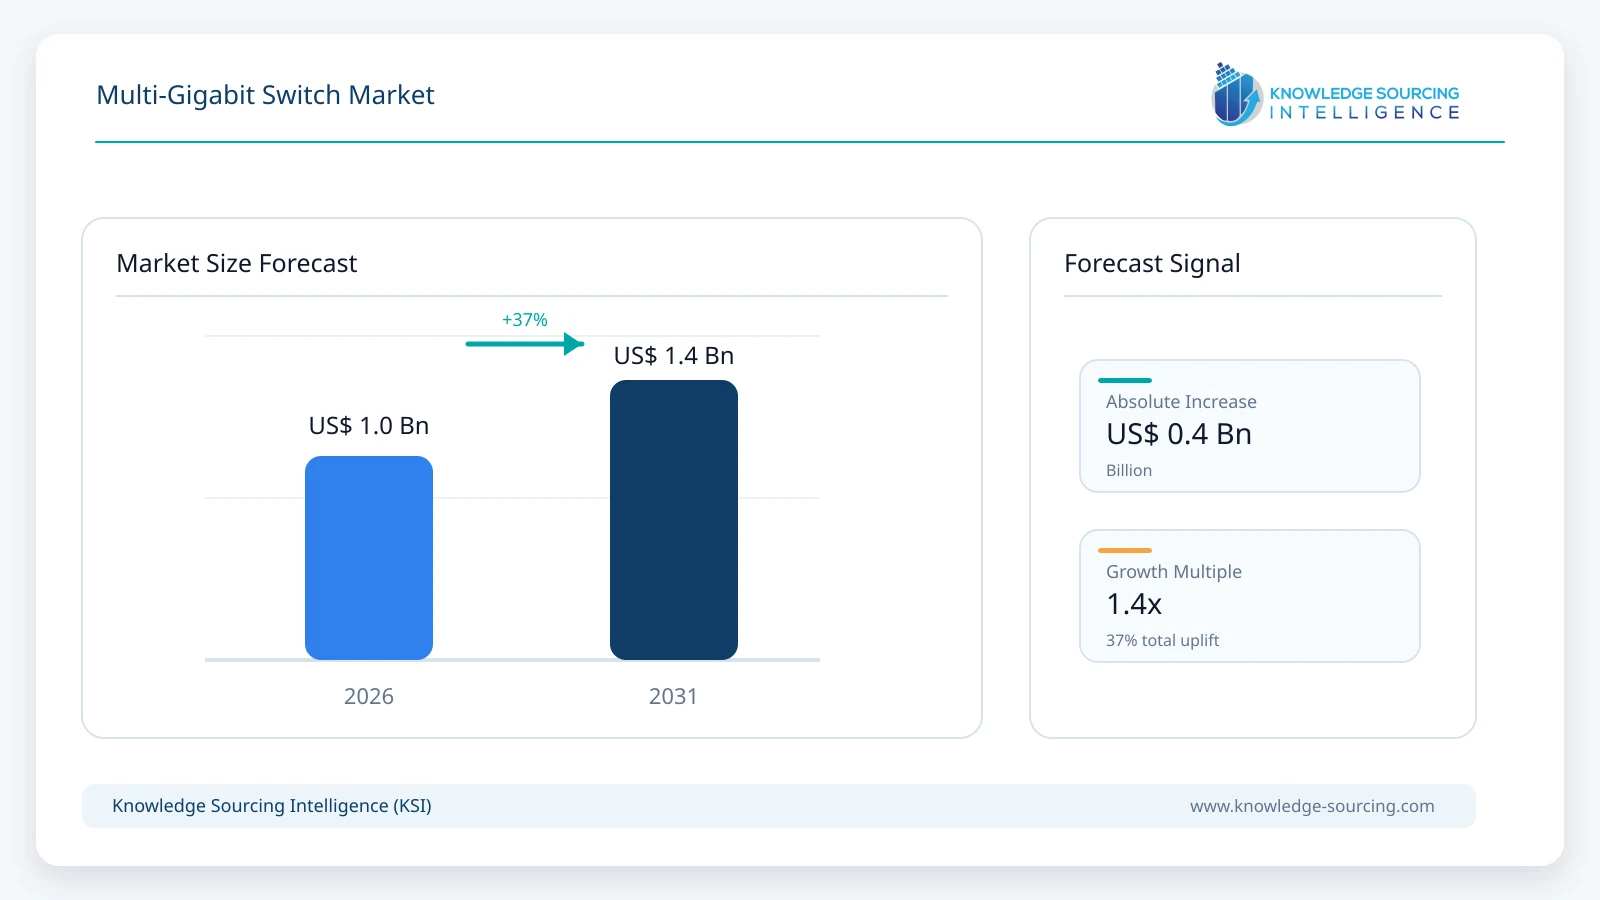
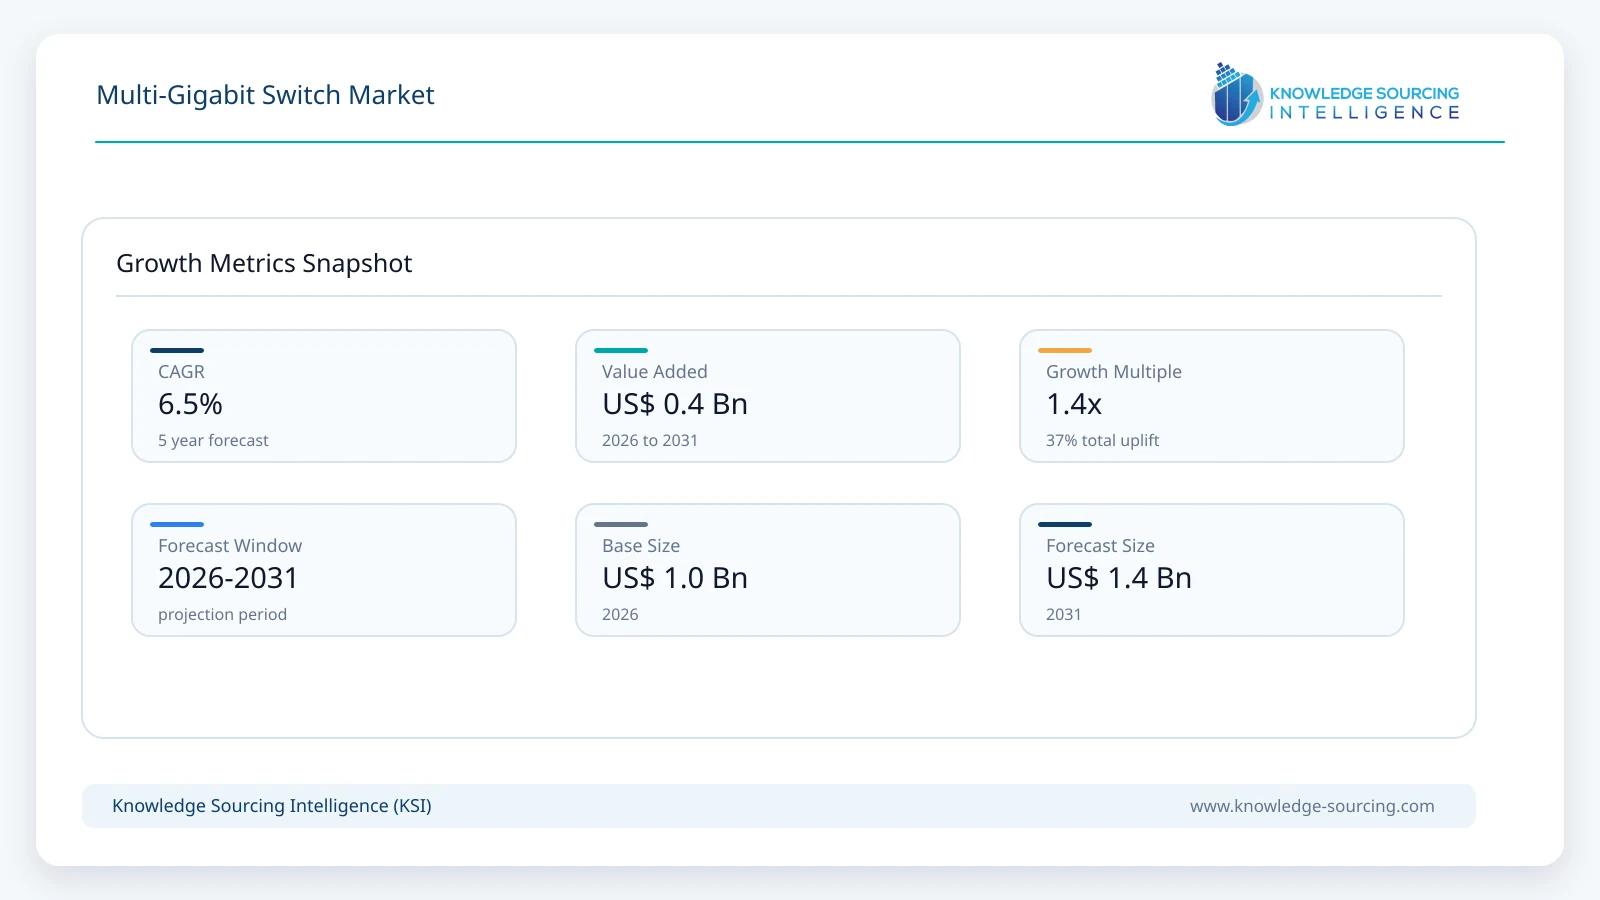
The multi-gigabit switch market is forecast to grow at a CAGR of 6.55%, reaching USD 1.40 billion in 2031 from USD 1.02 billion in 2026.
Highlights:
- 1Fully managed switches account for approximately 58% of global market value in 2026, reflecting their importance in enterprise and campus environments requiring segmentation, security, telemetry and centralized control.
- 225-48 port configurations account for approximately 42% of market value in 2026, supported by enterprise access-layer and campus wiring-closet deployments.
- 32.5GbE accounts for approximately 47% of global multi-gigabit switch revenue in 2026, benefiting from its ability to operate across large portions of the existing Cat 5e and Cat 6 cabling base.
- 4Large enterprises account for approximately 52% of market value in 2026, reflecting wider adoption of managed multi-gigabit access networks and higher-density Wi-Fi infrastructure.
- 5Campus networks are projected to grow at approximately 8.1% annually through 2031, supported by Wi-Fi 7, higher-power PoE and AI-enabled network management.
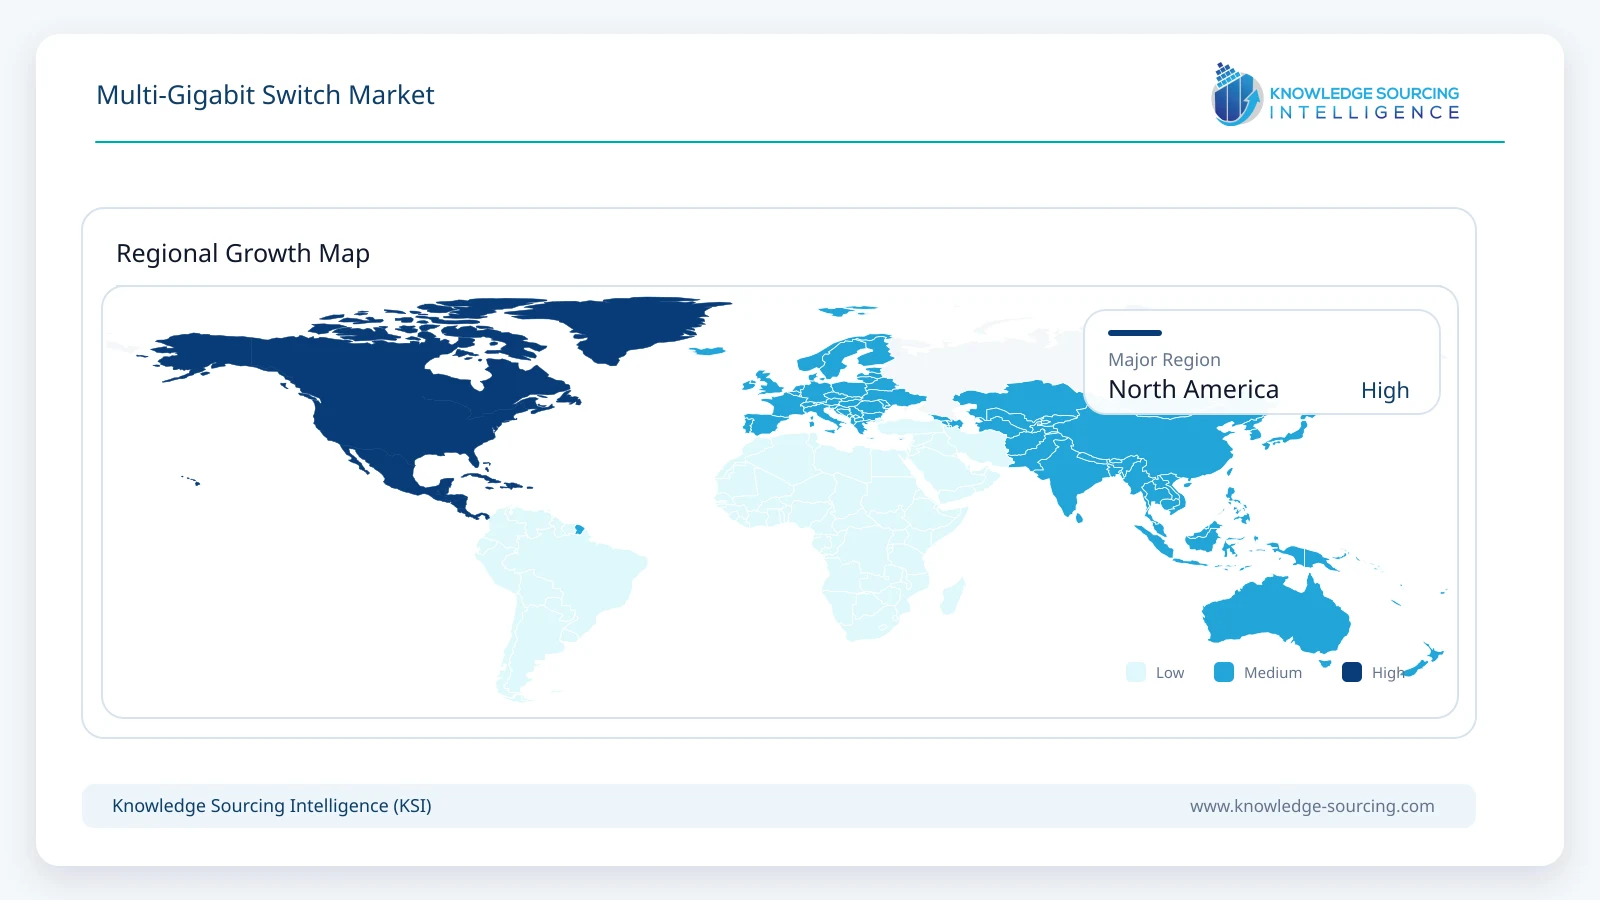
- 6North America accounts for approximately 36% of global market value in 2026, supported by enterprise network modernization and early Wi-Fi 7 adoption.
Multi-gigabit switches are Ethernet switching platforms that support access speeds above conventional 1GbE, principally 2.5GbE, 5GbE and 10GbE over copper or fiber-connected uplinks. The market includes unmanaged, smart, or web-managed and fully managed switches used across enterprise, campus, branch, industrial and selected data-center edge environments. Products designed solely around conventional 1GbE switching are excluded unless they form part of a multi-rate platform containing multi-gigabit ports.
The principal value proposition is the ability to increase throughput without replacing the complete installed cabling infrastructure. IEEE 802.3bz established 2.5GBASE-T and 5GBASE-T specifically to provide higher Ethernet speeds across much of the existing Category 5e and Category 6 installed base. The Ethernet Alliance continues to identify these intermediate speeds as a practical upgrade route for enterprise networks where 1GbE has become a bottleneck but immediate migration to 10GbE across every access port is unnecessary.
Wi-Fi is increasingly the strongest catalyst for access-layer upgrades. Modern Wi-Fi 7 access points can generate aggregate wireless throughput beyond the capacity of a conventional 1GbE uplink, particularly in dense enterprise and campus deployments. HPE Aruba Networking's 750 Series, for example, supports wired connections configurable at 1, 2.5, 5, or 10Gbps and wireless aggregate throughput well above 10Gbps, while Cisco's current C9350 switch family includes access models with 1/2.5/5/10GbE downlinks specifically positioned for Wi-Fi 7 environments.
Market Trends
Wi-Fi 7 Is Moving Multi-Gigabit Ethernet Into the Mainstream Access Layer
Wi-Fi 7 is increasing the practical need for faster wired access because the access point can no longer be assumed to fit comfortably within a 1GbE uplink. Modern platforms use wider channels, multi-link operation and greater spectral efficiency, creating aggregate wireless capacity that can exceed several gigabits per second. Cisco's C9350 Series includes 24- and 48-port configurations with 1/2.5/5/10GbE access ports and up to 90W of power delivery per port, while HPE Aruba Networking offers 1/2.5/5/10GbE Smart Rate options across its campus switching portfolio. The resulting upgrade cycle is different from earlier switch replacement programs because organizations are often modernizing the wired and wireless access layers together. Multi-gigabit switching therefore becomes part of a broader campus infrastructure decision involving Wi-Fi 7 access points, PoE budgets, uplink capacity, network automation and security rather than a standalone bandwidth upgrade.
Multi-Gigabit Access Is Increasing Without Full Building Recabling
A major advantage of 2.5GBASE-T and 5GBASE-T is that many organizations can increase access-layer capacity while retaining existing twisted-pair cabling. The Ethernet Alliance notes that these technologies were designed specifically to provide a practical upgrade path over installed Cat 5e and Cat 6 infrastructure, addressing the gap between 1GbE and 10GbE. This reduces one of the largest barriers to campus network modernization because structured cabling replacement can involve extensive construction work, downtime and labor cost. As a result, enterprises can replace access switches and endpoints progressively rather than complete a building-wide cabling project before realizing higher throughput. The economic advantage is particularly relevant in offices, educational campuses, hospitals, hospitality properties and other facilities with large existing copper footprints, supporting sustained demand for switches capable of automatically negotiating several Ethernet speeds on the same physical port.
PoE and Multi-Gigabit Connectivity Are Becoming Tightly Linked
Access switches increasingly need to provide both bandwidth and power to Wi-Fi access points, cameras, sensors, digital signage and other connected infrastructure. Higher-performance Wi-Fi 7 access points and smart-building devices can require more power than earlier generations, encouraging adoption of PoE++ and vendor-specific high-power implementations. Cisco's C9350 multi-gigabit models support up to 90W per port, while HPE Aruba Networking CX 6300 configurations combine 1/2.5/5/10GbE Smart Rate ports with high-power IEEE 802.3bt PoE support. The switch purchasing decision is therefore increasingly influenced by total power budget, per-port power availability, thermal design and power redundancy alongside switching capacity. This favors managed enterprise platforms capable of delivering high-density PoE while maintaining telemetry and power-management visibility, especially where organizations use the network as infrastructure for wireless access, building automation and edge devices simultaneously.
Market Drivers
Enterprise Campus Networks Are Replacing 1GbE Access Bottlenecks
The enterprise access layer has historically been dominated by 1GbE because it offered sufficient capacity for conventional desktop and wireless traffic. That assumption is changing as organizations deploy faster Wi-Fi, higher-resolution collaboration systems, network-attached storage, cloud applications, AI-enabled endpoints and increasingly dense IoT environments. Multi-gigabit switching provides an intermediate upgrade path that allows the access layer to increase capacity without requiring 10GbE on every port. The value proposition is particularly strong where network administrators can reuse existing copper cabling and upgrade selectively according to endpoint requirements. Cisco, HPE and HPE Juniper Networking now position multi-gigabit access as a standard element of enterprise campus portfolios rather than a specialist high-performance option. Juniper's EX4000, for example, offers multi-gigabit access variants positioned as Wi-Fi 7-ready with PoE++ and cloud-based management. This broadening product availability supports a gradual replacement cycle across installed enterprise access networks.
AI-Enabled Network Operations Are Increasing the Value of Managed Switching
Multi-gigabit switches are increasingly purchased as part of software-managed network architectures rather than as standalone forwarding devices. Enterprise networking platforms now combine switching, wireless management, telemetry, security policy, automation and AI-assisted troubleshooting within common management environments. HPE Aruba Networking integrates its CX switches with Aruba Central, while HPE Juniper Networking positions its EX portfolio within an AI-native campus architecture and Cisco combines access switching with centralized network management and security services. This favors fully managed switches because organizations need visibility into application traffic, PoE consumption, wireless uplinks, device behavior, and network health. The commercial opportunity therefore extends beyond raw port speed. Vendors able to integrate multi-gigabit switching with cloud management, zero-touch provisioning, analytics and automated troubleshooting can command higher value and create stronger customer retention than suppliers competing primarily through low-cost unmanaged hardware.
Existing Copper Infrastructure Supports Economical Migration
The ability to increase Ethernet capacity without replacing the entire cable plant remains one of the most market-specific drivers of multi-gigabit switching. IEEE 802.3bz introduced 2.5GBASE-T and 5GBASE-T as intermediate rates compatible with large portions of existing structured cabling, allowing organizations to upgrade switches and endpoints independently from the building cabling cycle. This provides a particularly strong economic case for campuses where replacing horizontal cabling would require opening ceilings, interrupting operations or modifying hundreds of individual runs. Organizations can instead deploy 2.5GbE or 5GbE access ports selectively to Wi-Fi access points, workstations or edge devices while maintaining 1GbE compatibility on the same switch. The resulting migration path encourages incremental adoption and reduces the risk associated with multi-gigabit upgrades, supporting continued penetration even in organizations without an immediate requirement for 10GbE access across every endpoint.
Market Restraints and Challenges
Existing 1GbE Networks Remain Sufficient for Many Endpoints
Multi-gigabit switching does not provide equal value across every access port. Standard office desktops, printers, basic IoT devices and many business applications remain adequately served by 1GbE, limiting the economic justification for replacing functioning switches solely to increase nominal port speed. Organizations therefore tend to deploy multi-gigabit connectivity selectively around wireless access points, high-performance workstations, storage devices, cameras or specialized applications rather than upgrade every endpoint simultaneously. This selective adoption moderates unit growth and explains why vendors increasingly offer mixed-port platforms combining 1GbE and multi-gigabit access. Cisco's current C9350 lineup includes both conventional 1GbE and 1/2.5/5/10GbE variants, allowing customers to match investment with actual bandwidth requirements. The market therefore grows through a staged replacement cycle rather than a rapid universal migration away from 1GbE.
Higher PoE and Multi-Gigabit Density Increase Infrastructure Requirements
Higher-speed access ports can create additional demands on switch power supplies, thermal management and upstream bandwidth. A switch supporting dozens of Wi-Fi 7 access points may need substantial PoE capacity while simultaneously forwarding several times the traffic handled by the previous access layer. This can require upgrades to distribution and core uplinks, redundant power systems and cooling, increasing the effective cost of migration beyond the switch itself. High-density multi-gigabit environments also need appropriate cabling quality because not every legacy installation will reliably support the maximum available speed. These considerations can encourage organizations to phase upgrades or prioritize only high-value locations. The restraint is therefore not simply the purchase price of the switch; it is the broader cost of ensuring that power, cabling and upstream network architecture can support the higher-capacity access layer without creating new bottlenecks.
Segment Analysis
By Type: Fully Managed Switches
Fully managed switches are projected to generate approximately USD 0.85 billion by 2031, remaining the largest product type as enterprise networks require increasingly sophisticated security, visibility and automation. Multi-gigabit access is being deployed primarily in environments where network administrators need VLAN segmentation, policy enforcement, PoE management, telemetry, quality of service and integration with centralized network-management platforms. These requirements favor fully managed platforms over unmanaged alternatives, particularly as Wi-Fi 7 increases both throughput and the number of connected high-value endpoints. Cisco's C9350 platform combines multi-rate access with routing, security and high-power PoE, while HPE Aruba Networking and HPE Juniper Networking integrate multi-gigabit switching with cloud-based management and network analytics. Smart and unmanaged switches retain an important role in small-business and prosumer environments, but the higher average selling price and richer software functionality of fully managed platforms keep them dominant in market value through 2031.
By Port Configuration: 25-48 Ports
The 25-48 port segment is projected to reach approximately USD 0.63 billion by 2031, supported by conventional enterprise wiring-closet design and high-density campus access deployments. Organizations typically require sufficient port density to aggregate users, wireless access points, IP cameras and other devices within each floor or network zone while retaining manageable switch count and rack space. Multi-gigabit vendors therefore concentrate substantial enterprise portfolios around 24- and 48-port models. Cisco's current C9350 range includes 24- and 48-port multi-gigabit variants, while HPE Aruba Networking offers 24- and 48-port Smart Rate configurations across its CX 6300 portfolio. Lower-port-count switches remain important for branches, small businesses and specialized edge applications, but the 25-48 port class captures the largest value pool because it aligns directly with mainstream enterprise access-layer architecture and supports higher aggregate PoE budgets and uplink capacity.
By Network Speed: 2.5GbE
2.5GbE switches are projected to generate approximately USD 0.62 billion by 2031, remaining the largest multi-gigabit speed category because they provide a relatively low-cost upgrade from 1GbE while supporting existing Cat 5e and Cat 6 installations. The speed is particularly well suited to wireless access points, small-business servers, NAS systems and high-performance desktops where 1GbE has become restrictive but 10GbE would provide more bandwidth and cost than required. The Ethernet Alliance continues to position 2.5GBASE-T and 5GBASE-T as practical intermediate technologies that preserve installed cabling investment. TP-Link, Cisco, HPE and other vendors maintain broad 2.5GbE portfolios covering unmanaged, smart-managed and enterprise-class platforms, illustrating how the technology has spread beyond specialist networking products. 5GbE and 10GbE increase their presence in higher-performance environments, but 2.5GbE retains the broadest access-layer addressable base through 2031.
By Enterprise Size: Large Enterprises
Large enterprises are projected to account for approximately USD 0.73 billion of market value by 2031, remaining the largest customer segment because they operate extensive campus networks, larger Wi-Fi estates and more complex security and management environments. Multi-gigabit adoption becomes particularly attractive when organizations need to upgrade hundreds or thousands of wireless access points while preserving installed horizontal cabling. Larger enterprises are also more likely to require centralized policy, zero-touch provisioning, telemetry, high-availability stacking and large PoE budgets, increasing average switch value compared with smaller organizations. Their migration commonly occurs in stages, beginning with buildings or floors where Wi-Fi 7, high-density collaboration or specialized workstations create immediate demand for additional bandwidth. Smaller businesses increasingly adopt 2.5GbE through lower-cost unmanaged and smart-managed switches, but large enterprises retain the largest revenue contribution because deployment scale and software requirements support higher overall contract values.
By Application: Campus Networks
Campus networks are projected to reach approximately USD 0.38 billion by 2031, supported by the interaction between Wi-Fi 7, high-density wireless access, PoE-powered devices and centralized network management. Universities, hospitals, corporate campuses, hotels and other large facilities increasingly depend on wireless connectivity as the primary user-access medium, shifting the wired network toward a role as high-capacity backhaul and power infrastructure for access points. Wi-Fi 7 access points can support aggregate throughput well above 1Gbps, making multi-gigabit Ethernet increasingly relevant when organizations want to avoid the wired uplink becoming the limiting factor. HPE Aruba Networking's 750 Series supports Ethernet connectivity up to 10Gbps, while Cisco positions several C9350 multi-gigabit models specifically around dense Wi-Fi 7 access. Campus deployments therefore provide one of the clearest commercial cases for coordinated wireless, multi-gigabit switching and high-power PoE upgrades.
Geographical Outlook
Major Region: North America
North America is projected to generate approximately USD 0.50 billion by 2031, remaining the largest regional market as enterprises, educational institutions and large public-sector networks continue upgrading campus infrastructure. The region benefits from early adoption of Wi-Fi 7, a large installed enterprise Ethernet base, and a strong presence of major networking vendors including Cisco, HPE, NETGEAR, Extreme Networks, Arista Networks and Ubiquiti. Multi-gigabit adoption is particularly attractive across facilities with substantial existing Cat 5e and Cat 6 cabling because organizations can increase access speeds without undertaking immediate building-wide recabling. North American enterprises also show strong adoption of cloud-managed networking, zero-trust security and AI-assisted operations, supporting demand for fully managed switches rather than basic unmanaged products. Growth is therefore driven less by greenfield network creation and more by recurring campus refresh cycles in which organizations replace aging 1GbE access layers while simultaneously deploying newer generations of wireless infrastructure.
Major Country: United States
The United States remains the largest individual country market and is projected to account for approximately USD 0.39 billion by 2031. Enterprise network refresh, university and healthcare campus upgrades, cloud-managed networking and early Wi-Fi 7 deployment support demand across fully managed and smart multi-gigabit switching. The country is also home to several influential networking vendors, which accelerates introduction of new enterprise platforms and makes advanced switching features available early in product cycles. Cisco expanded its C9350 Series during 2026 with new 24- and 48-port models supporting combinations of 2.5GbE, 5GbE and 10GbE alongside high-power PoE and higher-speed uplinks. The U.S. market also contains a large SMB and prosumer segment purchasing lower-port-count 2.5GbE switches for NAS, workstations and Wi-Fi upgrades, giving the market a broader demand base than enterprise campuses alone.
Competitive Environment and Analysis
The multi-gigabit switch market includes large enterprise networking companies and specialist SMB networking suppliers. Cisco maintains a strong position in managed enterprise switching through the C9000 family, with current C9350 platforms providing 1/2.5/5/10GbE multi-rate access, high-power PoE and high-speed uplinks. HPE participates through both Aruba Networking and HPE Juniper Networking, providing multi-gigabit campus switches integrated with centralized cloud and AI-driven management. NETGEAR, TP-Link, D-Link, TRENDnet and EnGenius compete strongly across SMB, prosumer and lower-density enterprise deployments, while Extreme Networks, Ubiquiti, Arista Networks, Zyxel, Allied Telesis, Huawei and Ruijie Networks broaden competition across campus and business networks. Competition increasingly revolves around more than port speed. Customers compare PoE budgets, management architecture, AI-assisted operations, security, uplink capacity, stacking, interoperability and lifecycle support. The result is a market with substantial hardware commoditization at the lower end but continued software and platform differentiation in managed enterprise deployments.
Recent Developments
August 2026: TP-Link announced six new unmanaged switches for Japan, including 2.5GbE models aimed at higher-speed home and small-business networks.
June 2026: Cisco updated the C9350 Series with enterprise access models providing up to 10Gbps multi-gigabit Ethernet and up to 90W PoE per port.
2026: Cisco introduced additional C9350 configurations including 24-port and mixed 48-port multi-gigabit variants supporting combinations of 2.5GbE, 5GbE and 10GbE access.
2026: HPE Aruba Networking continued expanding Smart Rate access configurations across the CX 6300 family with multi-gigabit ports and high-power PoE positioned for AI, Wi-Fi 7 and IoT requirements.
2026: HPE Juniper Networking positioned the EX4000 as a Wi-Fi 7-ready multi-gigabit access platform with cloud-native management and PoE++ support.
Market Outlook
The global multi-gigabit switch market is expected to increase from USD 1.02 billion in 2026 to USD 1.40 billion by 2031 as organizations gradually replace 1GbE access infrastructure with higher-speed platforms capable of supporting Wi-Fi 7, cloud applications and increasingly demanding edge devices. Growth remains evolutionary rather than disruptive because conventional 1GbE continues to meet the needs of many endpoint categories, while multi-gigabit connectivity is concentrated initially around wireless access points, high-performance workstations, storage and selected campus applications.
The most durable market advantage comes from the ability of 2.5GbE and 5GbE to use much of the installed copper cabling base, reducing the cost and disruption associated with network upgrades. Fully managed switches remain the largest value segment, while campus networks provide one of the strongest growth opportunities as high-performance wireless becomes the primary access medium in many organizations. North America remains the largest regional market, led by the United States, although adoption broadens globally as Wi-Fi 7 and multi-gigabit endpoint availability increase.
Multi-Gigabit Switch Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.02 billion |
| Total Market Size in 2031 | USD 1.40 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.55% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Port Configuration, Network Speed, Enterprise Size |
| Companies |
|
Market Segmentation
By Type
Unmanaged Switches
Smart / Web-Managed Switches
Fully Managed Switches
By Port Configuration
5-12 Ports
13-24 Ports
25-48 Ports
Above 48 Ports
By Network Speed
2.5GbE
5GbE
10GbE
Above 10GbE
By Enterprise Size
Small Enterprises
Medium Enterprises
Large Enterprises
By Application
Data Centers
Enterprise Networks
Campus Networks
Industrial Networks
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East And Africa
Saudi Arabia
United Arab Emirates
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Wi-Fi 7 and Wired Access Upgrade Outlook
3.7. Multi-Gigabit Ethernet Standards and Cabling Compatibility
3.8. PoE and Smart-Building Infrastructure Outlook
4. TECHNOLOGY OUTLOOK
4.1. 2.5GBASE-T
4.2. 5GBASE-T
4.3. 10GBASE-T
4.4. Multi-Gigabit PoE and PoE++
4.5. Cloud-Managed Switching
4.6. AI-Enabled Network Operations
4.7. High-Speed Access and Aggregation Uplinks
5. MULTI-GIGABIT SWITCH MARKET BY TYPE
5.1. Introduction
5.2. Unmanaged Switches
5.3. Smart / Web-Managed Switches
5.4. Fully Managed Switches
6. MULTI-GIGABIT SWITCH MARKET BY PORT CONFIGURATION
6.1. Introduction
6.2. 5-12 Ports
6.3. 13-24 Ports
6.4. 25-48 Ports
6.5. Above 48 Ports
7. MULTI-GIGABIT SWITCH MARKET BY NETWORK SPEED
7.1. Introduction
7.2. 2.5GbE
7.3. 5GbE
7.4. 10GbE
7.5. Above 10GbE
8. MULTI-GIGABIT SWITCH MARKET BY ENTERPRISE SIZE
8.1. Introduction
8.2. Small Enterprises
8.3. Medium Enterprises
8.4. Large Enterprises
9. MULTI-GIGABIT SWITCH MARKET BY APPLICATION
9.1. Introduction
9.2. Data Centers
9.3. Enterprise Networks
9.4. Campus Networks
9.5. Industrial Networks
9.6. Others
10. MULTI-GIGABIT SWITCH MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. Germany
10.4.2. United Kingdom
10.4.3. France
10.4.4. Italy
10.4.5. Spain
10.4.6. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. United Arab Emirates
10.5.3. Israel
10.5.4. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. Japan
10.6.3. India
10.6.4. South Korea
10.6.5. Taiwan
10.6.6. Indonesia
10.6.7. Thailand
10.6.8. Others
11. COMPETITIVE LANDSCAPE
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Benchmarking
12. COMPANY PROFILES
12.1. Cisco Systems, Inc.
12.2. Hewlett Packard Enterprise
12.3. HPE Juniper Networking
12.4. NETGEAR, Inc.
12.5. TP-Link Corporation Limited
12.6. D-Link Corporation
12.7. Extreme Networks, Inc.
12.8. Ubiquiti Inc.
12.9. Arista Networks, Inc.
12.10. TRENDnet Inc.
12.11. EnGenius Technologies
12.12. Zyxel Networks Corporation
12.13. Allied Telesis, Inc.
12.14. Huawei Technologies Co., Ltd.
12.15. Ruijie Networks Co., Ltd.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years
13.4. Research Methodology
13.5. Abbreviations
Navigate
Trusted by the world's leading organizations











