
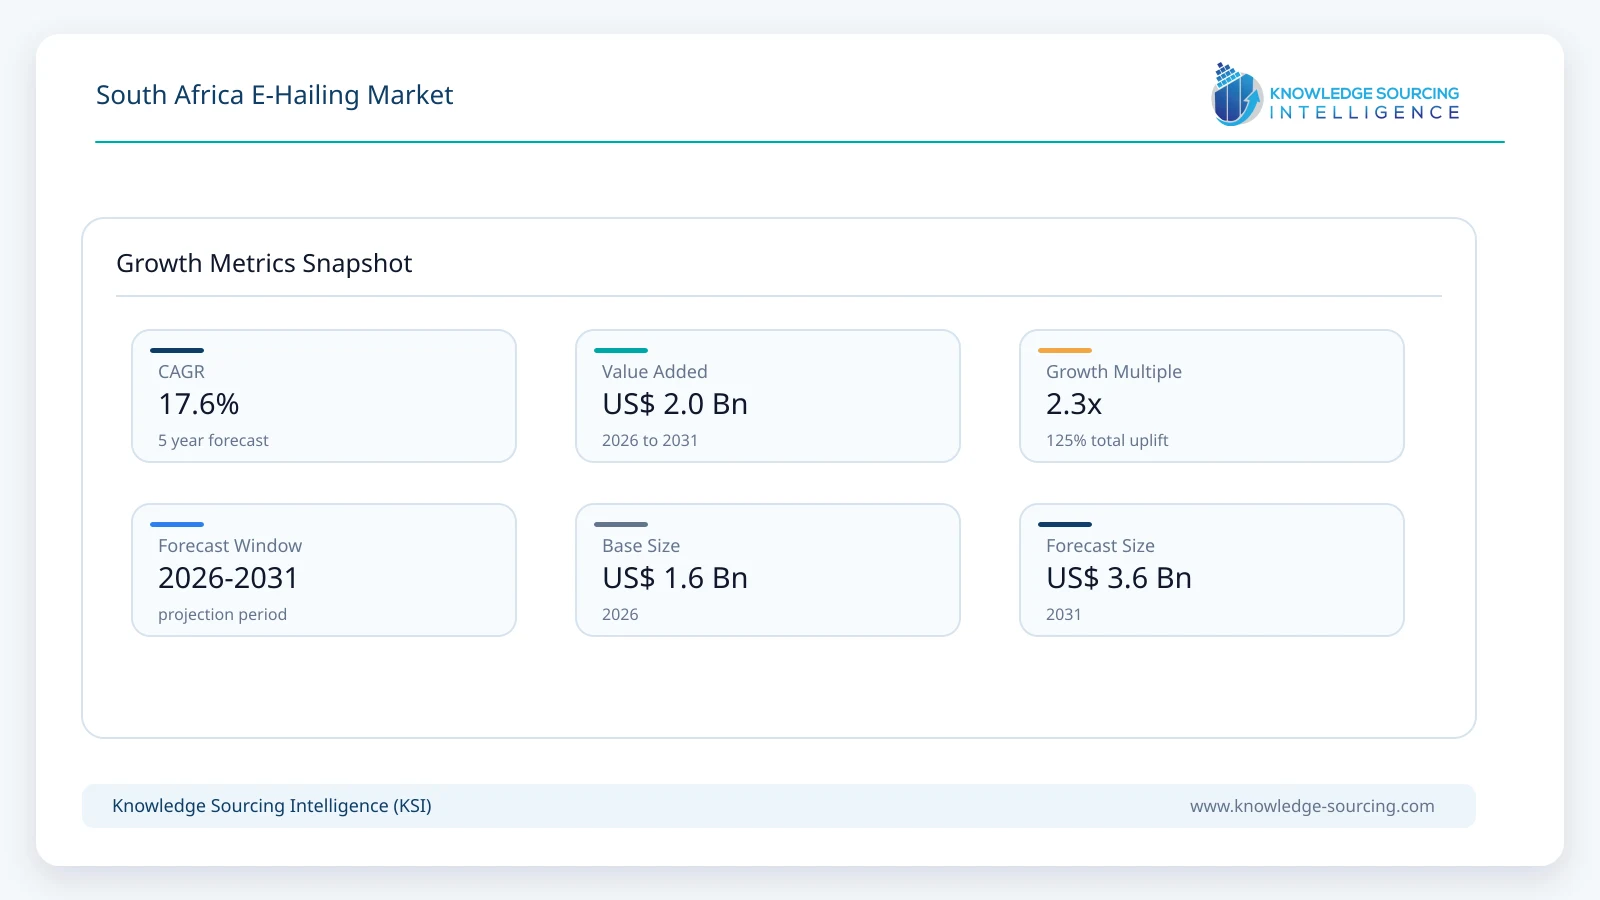
The South Africa E-Hailing market is forecast to grow at a CAGR of 17.6%, reaching USD 3.6 billion in 2031 from USD 1.6 billion in 2026.
Highlights:
- 1Smartphone-based bookings account for the largest share of platform transactions due to widespread mobile internet access and app-centric service delivery.
- 2Personal (B2C) users represent the largest revenue pool, supported by daily commuting, airport transfers, leisure travel, and urban mobility needs.
- 3Johannesburg and Cape Town collectively account for a substantial portion of trip demand owing to population density, tourism activity, and business travel volumes.
- 4Ride-hailing services remain a commercially important category as consumers prioritize point-to-point transportation with real-time tracking and digital payment options.
- 5Competition increasingly centers on pricing, driver availability, safety features, platform reliability, and geographic coverage rather than simple user acquisition.
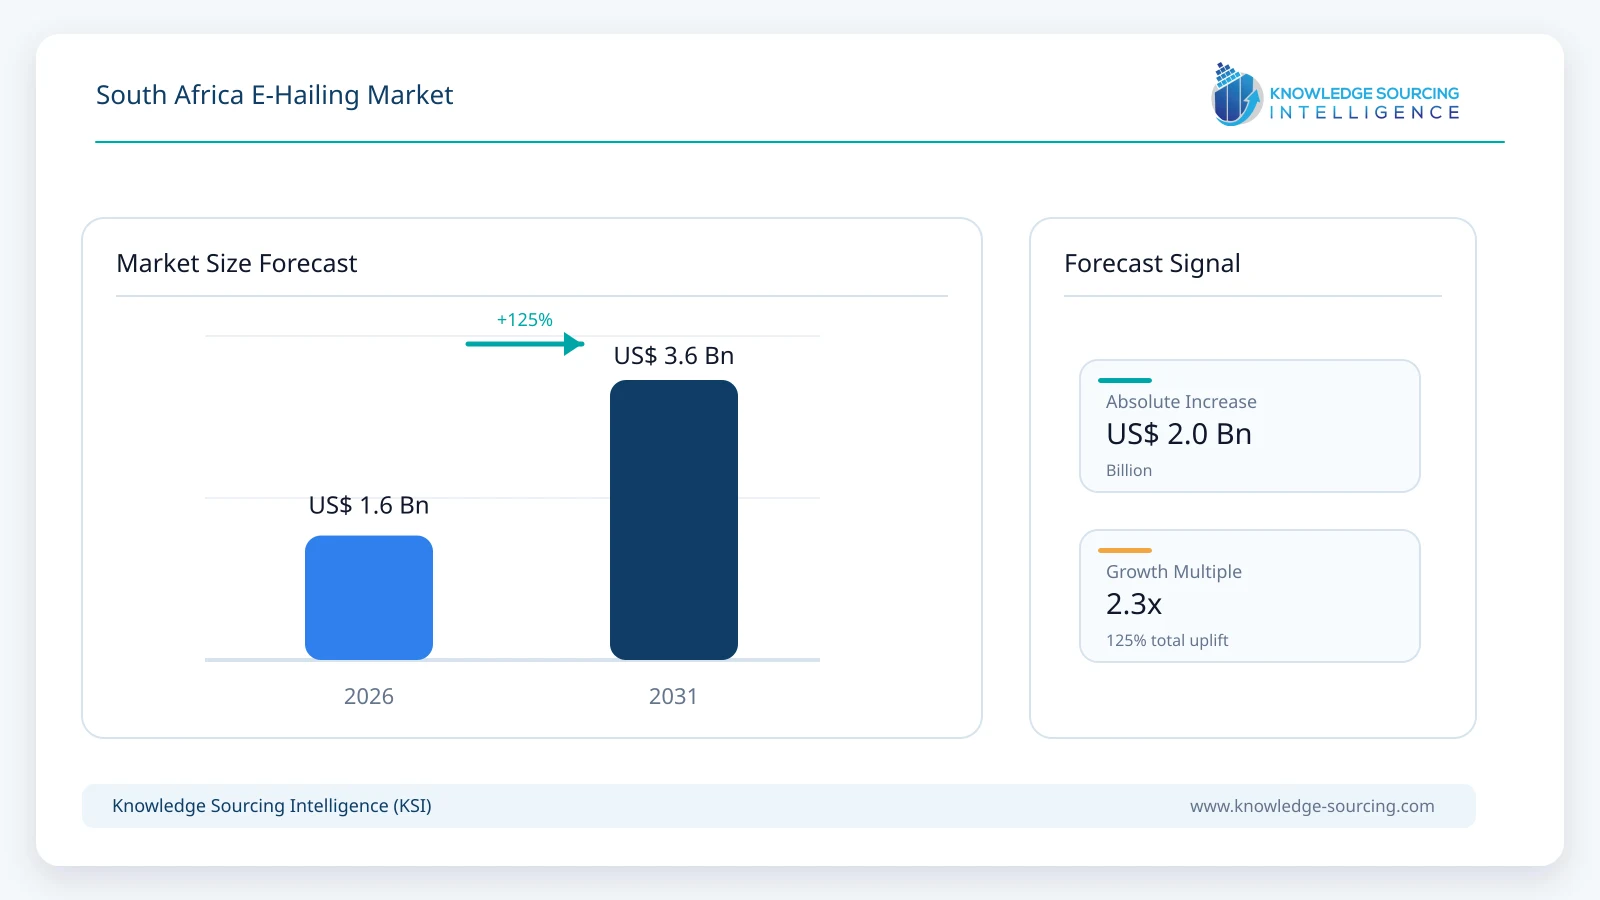
South Africa's e-hailing market is becoming an increasingly important part of urban mobility because consumers and businesses are shifting toward app-based transport services that offer convenience, transparent pricing, digital payments, and on-demand availability. Rising smartphone penetration, expanding platform ecosystems, growing demand for flexible transportation, and continued investment by operators such as Uber, Bolt, inDrive, and local providers are widening the user base. Corporate travel management, tourism activity, and demand for affordable mobility alternatives are also supporting market expansion across major metropolitan areas.
Market Overview
The South Africa e-hailing market encompasses app-based transportation services that connect passengers with drivers through digital platforms. The market includes ride-hailing, ride-sharing, and related mobility services accessed primarily through smartphones and connected devices. Revenue is generated through trip commissions, booking fees, premium service offerings, corporate mobility programs, and value-added transportation services.
Demand is concentrated in urban centers where traffic congestion, commuting requirements, tourism activity, and uneven public transport availability encourage consumers to use on-demand mobility services. Buyers increasingly evaluate transportation options based on convenience, waiting time, trip transparency, digital payment support, safety features, and total journey cost. These considerations have shifted transportation spending toward platform-enabled services that offer predictable user experiences.
The market is benefiting from broader digital adoption across South Africa. Smartphone ownership, mobile banking adoption, and increased familiarity with app-based services have lowered barriers to platform use. Consumers who previously relied on traditional taxi services increasingly compare transportation options through mobile applications, creating a more transparent and competitive mobility environment.
Corporate demand is also becoming more relevant. Businesses are using e-hailing platforms to manage employee transportation, client travel, airport transfers, and short-distance business mobility. This trend is supporting higher-value trips and recurring platform usage, particularly in Johannesburg, Cape Town, and Durban.
The market growth reflects rising trip volumes, wider service availability, expanding user penetration, and continued platform investment across key metropolitan areas.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
|---|---|---|
Urban-focused demand structure | Major demand concentrated in Johannesburg, Cape Town, Durban and other metropolitan areas | Revenue generation remains closely linked to city mobility patterns |
Device preference | Smartphones represent the primary booking interface | Mobile-first platform design remains essential for service providers |
End-user mix | Personal transportation accounts for the majority of trip activity | Consumer mobility spending drives platform utilization |
Service model adoption | Ride-hailing remains a core commercial service category | Point-to-point transportation continues to underpin platform revenues |
Competitive structure | Global and local operators compete in the market | Pricing, safety, and driver supply influence market share outcomes |
Key indicator: Smartphone-based booking remains the primary gateway to e-hailing services in South Africa.
Commercial meaning: Platform performance, payment integration, user experience, and mobile connectivity directly influence customer acquisition and retention.
Market Drivers
Expansion of smartphone-enabled mobility behavior
Consumers increasingly organize transportation through mobile applications rather than traditional dispatch systems. Smartphones combine trip booking, route tracking, driver information, payment processing, and customer support within a single interface. This reduces transaction friction and supports repeat usage. Service providers continue investing in application functionality, digital payments, and localized user experiences to strengthen customer retention.
Growing demand for flexible urban transportation
Large metropolitan areas face congestion, variable commuting patterns, and transportation accessibility gaps. Many users prefer transportation services that can be ordered immediately without vehicle ownership costs. E-hailing platforms provide flexible mobility that adapts to changing travel schedules, making them attractive for commuters, students, tourists, and occasional travelers.
Increasing use of digital payment ecosystems
Mobile banking and digital payment adoption support platform expansion because users can complete bookings and payments through integrated applications. Cashless transactions improve convenience for riders and operational efficiency for service providers. Platform operators continue to enhance payment options to accommodate varying consumer preferences across different income groups.
Tourism and airport mobility demand
South Africa's tourism sector contributes meaningful transportation demand in cities that receive domestic and international visitors. Travelers frequently rely on app-based transportation due to route visibility, fare transparency, and convenience. Airport transfers, hotel transportation, and urban sightseeing trips create recurring demand that supports utilization rates for platform operators and drivers.
Corporate mobility management requirements
Organizations increasingly seek structured transportation solutions for employees and business travelers. Digital trip records, centralized billing, travel visibility, and spending controls make e-hailing platforms attractive alternatives to conventional transportation arrangements. Corporate mobility contracts can generate recurring revenue streams and improve trip consistency throughout the year.
Market Restraints and Challenges
Driver safety and security concerns
Safety remains one of the most important operational challenges in South Africa's mobility sector. Driver incidents, passenger security concerns, and vehicle-related risks can affect platform adoption and service availability. Operators continue investing in identity verification, emergency assistance tools, ride tracking systems, and safety partnerships to address these issues.
Regulatory uncertainty across transport frameworks
Digital mobility platforms often operate within transport environments that continue to evolve through regulatory updates and licensing requirements. Changes affecting driver permits, operating conditions, taxation, or platform obligations can influence operating costs and market participation. Regulatory clarity remains important for long-term investment decisions.
Intense pricing competition
Competition among global and local operators places pressure on commissions and fare structures. Consumers frequently compare service options based on price, while drivers evaluate platforms based on earning potential. Sustained discounting can improve user acquisition but may compress profitability and increase customer switching behavior.
Driver supply and retention challenges
Service quality depends heavily on maintaining an adequate driver base. Fuel expenses, vehicle maintenance costs, insurance requirements, and earnings expectations influence driver participation. Platforms must balance rider affordability with driver economics to sustain network growth and service reliability.
Infrastructure and connectivity limitations
Although smartphone adoption is widespread, service quality can still be affected by network coverage variability, device limitations, and location-mapping challenges. Connectivity issues may increase booking friction in certain areas, limiting platform penetration outside established urban centers.
Major Segment Analysis
Ride-Hailing Services
Ride-hailing represents a commercially important segment within the South Africa e-hailing market because it directly addresses everyday transportation requirements across urban environments. Consumers use ride-hailing services for commuting, airport transfers, shopping trips, entertainment activities, and short-notice travel. The segment benefits from clear value propositions that include convenience, route visibility, fare estimates, and digital payment integration.
Purchasing decisions within this segment are influenced by trip cost, waiting time, driver availability, safety features, and platform reliability. Users frequently compare several applications before booking a trip, which intensifies competition among providers. As a result, operators continue investing in route optimization, driver incentives, customer support, and platform functionality to improve retention.
Corporate travelers, tourists, and regular commuters create distinct demand profiles within the ride-hailing segment. Corporate users often prioritize reliability and reporting capabilities, while leisure travelers emphasize convenience and transparent pricing. Performance in ride-hailing remains important because it influences driver engagement, platform utilization, and broader customer perceptions of service quality.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
|---|---|---|
North America | Mature app-based mobility adoption and advanced digital payment systems | Regulatory variation across jurisdictions |
Europe | Urban mobility policies and multimodal transportation integration | Complex transport compliance requirements |
Asia Pacific | High population density and large-scale app ecosystem adoption | Intense platform competition |
Middle East & Africa | Expanding smartphone usage and urban transportation demand | Infrastructure and regulatory differences |
South Africa
Within South Africa, demand is concentrated in metropolitan areas where population density and economic activity support higher trip volumes. Johannesburg serves as a major commercial hub with strong demand from commuters and business travelers. Cape Town benefits from tourism activity, airport transportation demand, and a large urban user base.
Durban continues to attract demand through commercial activity, residential mobility needs, and tourism-related transportation. Emerging demand in cities such as Gqeberha and East London reflects broader awareness of app-based mobility services and increasing smartphone usage.
Urban consumers generally prioritize affordability, service availability, and safety features. Business users place greater emphasis on reliability, trip tracking, and centralized payment systems. These differences influence platform strategies and service offerings across cities.
Competitive Landscape
The South Africa e-hailing market exhibits characteristics of a platform-led competitive structure where network scale, driver availability, pricing strategy, and user experience strongly influence market performance. Competition extends beyond passenger acquisition because operators must simultaneously attract drivers, maintain service quality, and optimize platform economics.
Uber Technologies Inc. remains one of the most established international participants in the market. The company competes through brand recognition, platform functionality, safety tools, corporate mobility programs, and broad geographic coverage.
Bolt Technology OÜ competes aggressively on affordability, service accessibility, and driver participation. Pricing flexibility and broad user reach remain central elements of its market strategy.
inDrive differentiates itself through its fare-negotiation model, which gives riders and drivers greater flexibility in trip pricing. This approach appeals to users seeking more direct control over transportation costs.
Local providers including Yookoo Ride, Shesha, and Wanatu contribute to market diversity by targeting specific user groups, local operating conditions, and regional transportation needs. Their presence increases competitive pressure and encourages service differentiation.
Competition increasingly focuses on several factors:
Driver acquisition and retention
Passenger safety features
Fare competitiveness
Geographic coverage
Corporate mobility solutions
Mobile application performance
Customer support quality
Payment flexibility
Barriers to entry remain moderate because new platforms require substantial investments in technology, user acquisition, driver recruitment, compliance, and brand development. Network effects favor established operators that maintain large user and driver communities.
Recent Developments
September 2026: Uber Technologies Inc. announced corporate restructuring via its global newsroom, titled Building a simpler, faster Uber, reflecting organizational efficiency changes rather than local South African platform enhancements.
April 2026: Uber presented GO–GET 2026, its latest product showcase, introducing an expanded vision for an integrated mobility platform and new features designed to simplify everyday transportation through one Uber application.
March 2026: Bolt introduced pick-up codes for rides, adding an additional verification layer that enables passengers and drivers to confirm the correct vehicle before a trip begins.
March 2025: Shesha updated its South African e-hailing application, with the company’s official app listing confirming a March 24, 2025 update containing bug fixes and performance improvements for its local ride-hailing service.
February 2026: inDrive reported continued global ride-hailing expansion and its transition toward a super app, adding intercity transportation, courier, grocery delivery, and financial services around its core peer-to-peer ride platform.
Regulatory and Policy Environment
Transport regulation remains an important factor influencing market development in South Africa. Platform operators must operate within licensing, vehicle compliance, driver qualification, and safety frameworks established by relevant authorities. Regulatory requirements affect market entry, operational costs, and service expansion strategies.
Authorities continue evaluating how digital mobility platforms fit within broader transportation systems. Policy discussions often focus on passenger safety, driver protections, operating permits, taxation, and competition between app-based services and traditional transportation providers.
Compliance capabilities are becoming more important competitive assets. Larger operators often possess greater resources to manage regulatory obligations, technology upgrades, reporting requirements, and safety-related investments. Smaller providers may face higher compliance burdens relative to their scale.
The regulatory environment is expected to remain commercially important because policy decisions can influence driver participation, service availability, and long-term investment planning.
Key Answers to Questions Frequently Asked by CEOs, CXOs, CTOs, and Business Analysts
What is the primary source of demand in the South Africa e-hailing market?
Urban transportation needs remain the principal source of demand. Daily commuting, airport transfers, business travel, tourism activity, and on-demand mobility requirements generate recurring platform usage across major cities.
Why are smartphone-based services commercially important?
Smartphones serve as the main customer interface for booking, payment, ride tracking, and communication. Platform growth depends heavily on mobile application adoption and digital payment integration.
How are companies competing for market share?
Competition increasingly revolves around fare levels, driver availability, service quality, safety features, customer support, and platform reliability. Network scale and user retention have become important competitive differentiators.
What is the biggest operational challenge for providers?
Maintaining a balance between affordable pricing, driver earnings, and platform profitability remains one of the most complex challenges. Safety concerns and regulatory compliance also require ongoing investment.
How does corporate demand affect the market?
Corporate mobility programs generate recurring transportation spending and create demand for centralized billing, travel reporting, and reliable service delivery, supporting higher-value platform transactions.
Outlook and Strategic Implications
The South Africa e-hailing market is entering a period where operational execution will matter as much as customer acquisition. Platform operators that improve safety systems, driver retention, payment flexibility, and service reliability are likely to strengthen their competitive position. Market expansion will continue to be supported by smartphone penetration, digital payment adoption, and urban mobility requirements.
Several strategic implications emerge for industry participants:
Operators must invest continuously in safety and trust mechanisms.
Driver economics will remain critical to platform scalability.
Corporate mobility services offer opportunities for recurring revenue.
Regional expansion beyond the largest metropolitan areas can unlock additional demand.
Regulatory engagement will remain essential for sustainable growth.
Technology investment focused on routing, customer experience, and fraud prevention can improve operational efficiency.
Market performance through 2031 will be shaped by the ability of providers to balance affordability, service quality, and regulatory compliance while expanding access to reliable urban transportation across South Africa.
South Africa E-Hailing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.6 billion |
| Total Market Size in 2031 | USD 3.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 17.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Service Type, Device Type, Vehicle Type, End-User |
| Companies |
|
Market Segmentation
By Service Type
Ride Sharing
Ride Hailing
Others
By Device Type
Smartphones
Tablets
Others
By Vehicle Type
Two-Wheeler
Three-Wheeler
Four-Wheeler
Sedans
SUVs
Others
By End-User
Personal (B2C)
Corporations (B2B)
By City
Cape Town
Johannesburg
Gqeberha
East London
Durban
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. SOUTH AFRICA E-HAILING MARKET BY SERVICE TYPE
5.1. Introduction
5.2. Ride Sharing
5.3. Ride Hailing
5.4. Others
6. SOUTH AFRICA E-HAILING MARKET BY DEVICE TYPE
6.1. Introduction
6.2. Smartphones
6.3. Tablets
6.4. Others
7. SOUTH AFRICA E-HAILING MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Two-Wheeler
7.3. Three-Wheeler
7.4. Four-Wheeler
7.5. Sedans
7.6. SUVs
7.7. Others
8. SOUTH AFRICA E-HAILING MARKET BY END-USER
8.1. Introduction
8.2. Personal (B2C)
8.3. Corporations (B2B)
9. SOUTH AFRICA E-HAILING MARKET BY CITY
9.1. Introduction
9.2. Cape Town
9.3. Johannesburg
9.4. Gqeberha
9.5. East London
9.6. Durban
9.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Uber Technologies Inc.
11.2. Bolt Technology OÜ
11.3. Yookoo Ride
11.4. inDrive
11.5. Shesha
11.6. Wanatu
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for the Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF TABLES
LIST OF FIGURES
Navigate
Trusted by the world's leading organizations











