
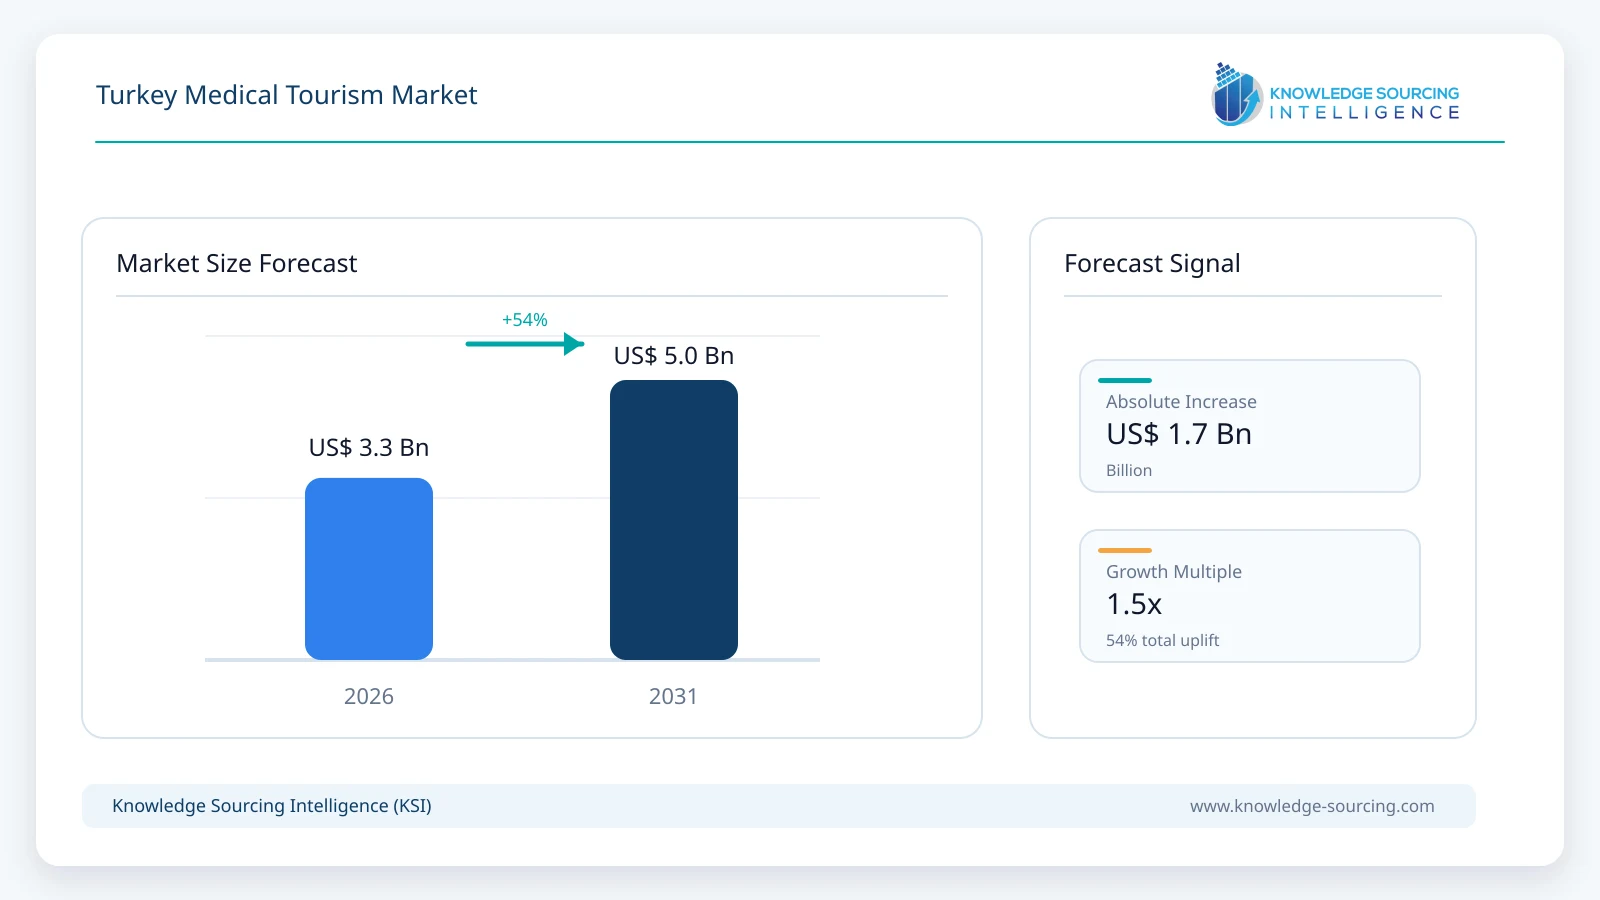
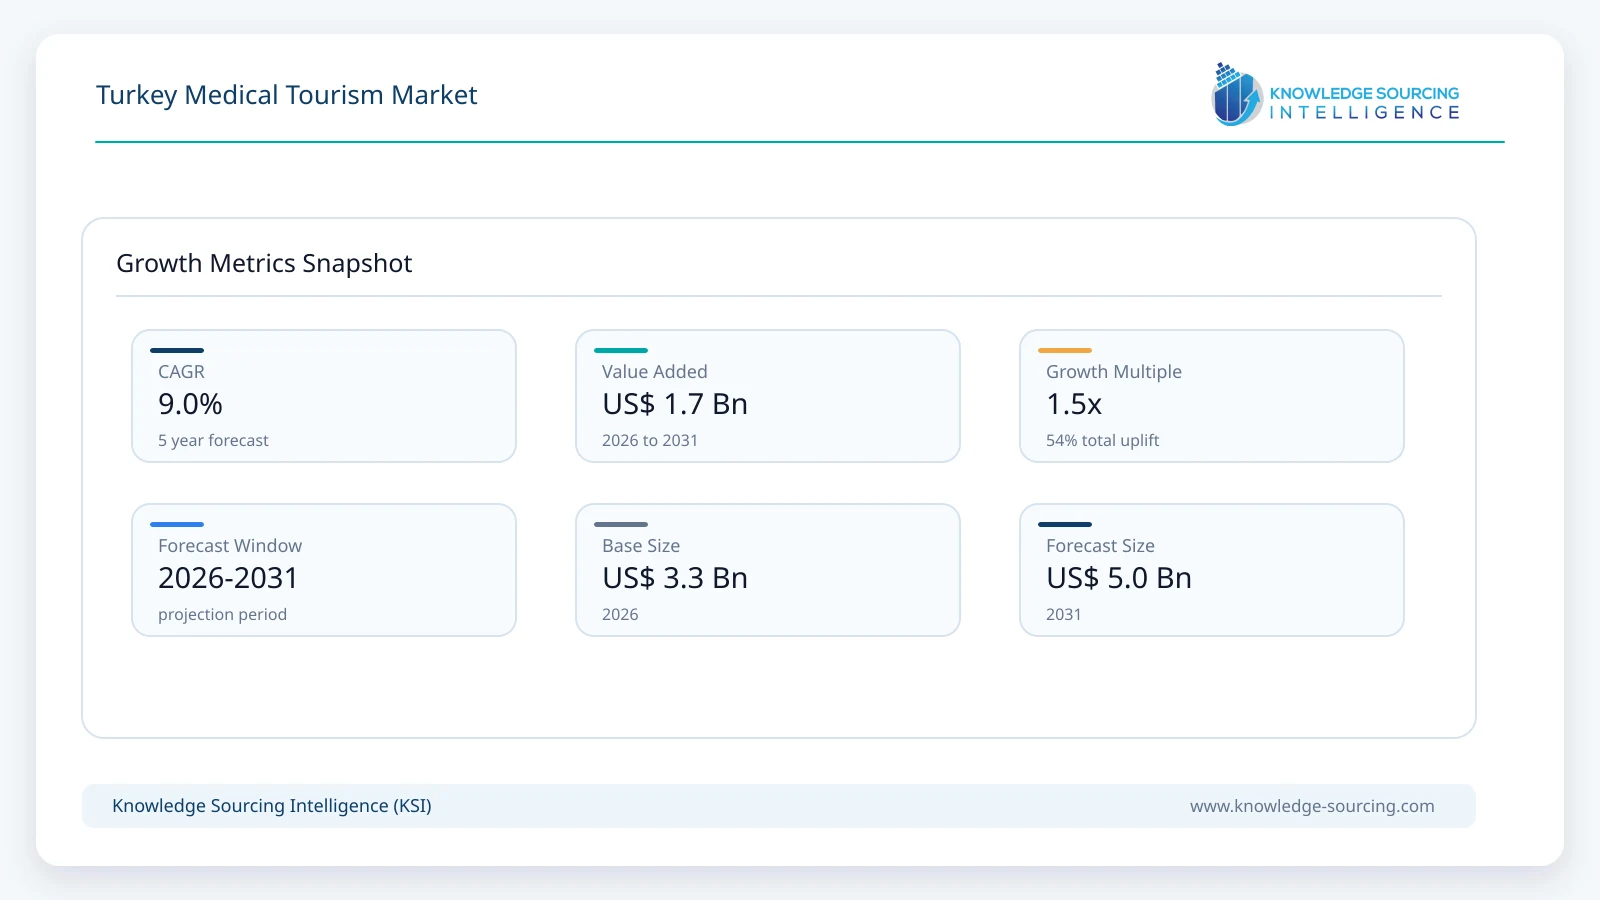
The Turkey medical tourism market is estimated at USD 3.25 billion in 2026 and is projected to reach approximately USD 5.00 billion in 2031, representing a CAGR of about 9.0% during the forecast period.
Highlights:
- 1Aesthetic, plastic-surgery and hair-restoration services account for approximately 29% of 2026 market revenue.
- 2Private hospitals and specialty clinics collectively generate about 82% of international-patient clinical revenue in 2026.
- 3Europe contributes approximately 42% of 2026 source-market revenue, supported by short-haul access and diaspora links.
- 4Istanbul and the Marmara region account for roughly 68% of national medical-tourism revenue in 2026.
- 5Q1 2026 health-tourism revenue reached USD 761.5 million despite lower patient volumes than Q1 2025.
- 6The 2025-2026 regulatory framework raises accreditation, platform-registration and service-quality requirements for providers.
Turkey's medical-tourism industry sits at the intersection of private healthcare, specialty clinics, aviation connectivity and destination marketing. Its scale is unusual because it serves both high-volume elective demand and complex tertiary-care demand. Hair transplantation, dental restoration, cosmetic surgery, refractive eye procedures and bariatric treatment attract price-sensitive self-pay patients, while oncology, cardiovascular surgery, orthopedics, fertility treatment and transplant-related services depend more heavily on physician reputation, hospital technology and clinical coordination. This mix gives Turkey a broad addressable patient base but also creates substantial differences in average treatment value and care complexity.
Recent official and industry data provide a stronger anchor than the older nominal-lira forecast. The Ministry of Trade reported about 1.5 million health tourists and approximately USD 3.0 billion of health-service exports in 2024. Industry data cited in July 2026 indicate that 2025 patient volume eased to 1.40 million while revenue remained near USD 3.02 billion. The first quarter of 2026 then produced USD 761.5 million from 302,487 patients. Compared with Q1 2025, patient volume was lower but revenue was higher, implying a material increase in revenue per patient. That shift is consistent with a market moving toward more complex treatment, better formalization and improved price realization rather than relying only on patient-count expansion.
The supply base is led by large private networks and specialist providers. Acibadem, MLP Care's Medical Park and Liv Hospital brands, Memorial, Medicana, Florence Nightingale and other national groups operate international-patient departments capable of coordinating clinical review, translators, airport transfer, accommodation support and follow-up. Turkey also has a large fragmented base of dental, hair-transplant and aesthetic clinics, particularly in Istanbul and Antalya. The 2025 international health-tourism regulation and the certification requirements being implemented through 2026 are intended to reduce uneven service quality, strengthen oversight of facilitators and ensure that international-patient activity is concentrated in authorized facilities.
Market Trends
Revenue per Patient Is Becoming More Important than Patient Volume
The clearest 2026 signal is the divergence between patient volume and revenue. Turkey treated 302,487 international patients in Q1 2026 compared with 354,457 in Q1 2025, yet health-tourism revenue increased from USD 643.4 million to USD 761.5 million. The resulting improvement in revenue per patient is commercially important because high-volume categories such as dentistry and hair transplantation face intense price competition. Hospitals and clinics are therefore placing greater emphasis on complex surgery, oncology, cardiovascular care, robotics, fertility treatment and bundled diagnostic pathways where clinical expertise and technology matter more than headline price. This mix shift can support value growth even if total inbound patient counts fluctuate.
Provider Formalization Is Raising the Competitive Threshold
Turkey is tightening the operating framework for international healthcare. The April 2025 regulation replaced the earlier 2017 framework and strengthened authorization, service and intermediary requirements. During 2026, the Ministry of Health clarified that hospitals, medical centers, laboratories and dialysis centers holding health-tourism authorization must complete the applicable accreditation process by the end of 2026, while other facilities must obtain the required certification. Providers that fail to comply cannot continue international-patient activity under the health-tourism framework. This creates near-term compliance cost but should favor scaled hospitals and professionally managed specialty clinics with stronger clinical governance, documentation and patient-support systems.
Hair, Dental and Aesthetic Services Remain High-Volume Entry Categories
Turkey's international reputation remains closely associated with hair transplantation, dentistry and aesthetic surgery. These categories benefit from visible before-and-after outcomes, comparatively short treatment cycles, self-pay demand and the ability to combine treatment with travel. Istanbul has built dense clusters of clinics serving European and Middle Eastern patients, while Antalya and Izmir benefit from tourism connectivity. However, commoditization is increasing. Clinics must differentiate through surgeon credentials, complication management, transparent packages, infection-control standards and post-treatment follow-up. The regulatory shift toward authorized and certified providers is particularly relevant in these fragmented categories because lower-quality informal competition can damage destination reputation.
Large Hospital Groups Are Expanding International-Patient Capabilities
Scaled hospital networks are increasingly important as the market moves toward higher-acuity treatment. MLP Care operates the Medical Park and Liv Hospital brands across a broad hospital network and reported that foreign medical-tourism revenue returned to growth in Q1 2026 as patient numbers improved. Acibadem, part of IHH Healthcare, combines a large Turkish hospital footprint with a wider international network and continued investment in complex care. These groups can invest in multilingual call centers, digital pre-arrival assessment, oncology systems, robotic surgery, transplant programs and cross-border referral partnerships. Their ability to coordinate multiple specialties inside one network also supports international patients with complex or multi-stage treatment pathways.
Market Drivers
Cost and Access Advantages Remain the Core Cross-Border Proposition
Turkey competes strongly where patients face high out-of-pocket prices, long wait times or limited access in their home markets. Its private hospitals and clinics can offer specialist consultations and scheduled procedures relatively quickly, while treatment prices for dental reconstruction, hair transplantation, cosmetic surgery, bariatric treatment and ophthalmology are often materially below those in Western Europe, the United Kingdom and North America. The value proposition is strengthened by direct air connectivity to Istanbul and major tourism centers. Cost alone is not sufficient for complex procedures, but it remains a powerful acquisition factor when combined with international accreditation, specialist reputation and transparent care coordination.
Geographic Position Supports a Diversified Source-Market Base
Turkey is accessible to a wide corridor stretching across Europe, the Balkans, the Caucasus, Central Asia, the Middle East and North Africa. Industry reporting identifies Germany, the United Kingdom, Iraq, Azerbaijan, Russia, Libya and Gulf countries among important source markets. This geographic breadth reduces dependence on any single long-haul corridor and allows providers to build specialty-specific referral relationships. European demand is particularly important for self-pay dental, hair and aesthetic procedures, while Middle Eastern, North African and Eurasian patients contribute more high-acuity hospital cases. The national HealthTürkiye platform and health-visa support further reduce search and administrative friction for international patients.
Quality Regulation and Digital Discovery Are Professionalizing the Market
Destination reputation is a critical market asset because individual adverse events can affect patient trust well beyond one clinic. Turkey's revised international health-tourism rules, provider authorization lists, certification criteria and official digital portals are therefore commercially significant. The Ministry of Health publishes authorized provider and facilitator lists, while the Heal in Türkiye platform helps patients identify treatments and participating institutions. Formalization should improve transparency and make it more difficult for unauthorized intermediaries to compete only on price. Over time, this can shift marketing from unverified claims toward documented credentials, patient outcomes, treatment pathways and structured complication support.
Market Restraints
Price Competition and Fragmented Specialty Clinics Can Pressure Quality and Margins
Hair transplantation, cosmetic procedures and dental tourism have relatively low barriers to marketing compared with hospital-based tertiary care. A large number of clinics and facilitators compete for similar international patients, which can lead to aggressive discounting, opaque packages and inconsistent follow-up. This creates margin pressure for reputable providers and increases the risk that complications at lower-quality facilities damage Turkey's broader destination brand. Regulation can reduce the problem, but enforcement, online marketing and cross-border lead-generation channels remain difficult to standardize. Providers that invest in accreditation, specialist staffing and complication management therefore carry higher costs than informal competitors.
Macroeconomic Volatility and Source-Market Disruptions Affect Patient Conversion
The sector is exposed to exchange-rate movements, inflation, geopolitical events, aviation disruptions and changes in consumer confidence across source markets. Currency depreciation can improve international price competitiveness but also raises imported equipment, drug and technology costs for providers. MLP Care's 2025 foreign medical-tourism revenue declined in reported Turkish-lira terms and also fell in original-currency terms, illustrating that provider performance can diverge from national tourism trends. Political or travel disruptions in Russia, the Middle East or Europe can quickly affect specific patient corridors, while complex-care patients may defer travel when uncertainty rises.
Turkey Medical Tourism Market Segment Analysis
By Treatment Type
Aesthetic, Plastic Surgery and Hair Restoration
Aesthetic surgery and hair restoration remain the largest identifiable treatment cluster by revenue and are projected to reach approximately USD 1.72 billion by 2031. The segment combines high international awareness, short treatment cycles and strong patient acquisition through digital channels. Hair transplantation delivers high procedure volumes, while rhinoplasty, facial surgery, breast procedures and body contouring contribute higher average treatment values. Growth through 2031 is expected to come from stronger provider certification, premium surgeon brands and more bundled post-operative support rather than unlimited volume expansion. Dental treatment remains another large self-pay category, while oncology, cardiac care and orthopedic surgery are smaller by patient count but materially higher in revenue per case.
By Service Provider
Private Multispecialty Hospitals
Private multispecialty hospitals are expected to expand at approximately 8.5% annually through 2031 as Turkey shifts toward complex international cases. Their competitive advantage is the ability to combine diagnostics, surgery, intensive care, pathology, oncology, imaging and post-operative management under one clinical governance structure. International patients seeking cardiac surgery, cancer care, orthopedics or multi-disciplinary treatment place greater weight on accreditation, physician depth and complication-management capacity than patients purchasing a single elective outpatient procedure. Specialty clinics grow faster in selected aesthetic, hair and dental niches, but hospitals retain the highest share of high-acuity revenue.
By Patient Source Region
Europe
Europe remains Turkey's largest source region and is projected to generate close to USD 1.95 billion of treatment revenue by 2031. Germany and the United Kingdom are especially important because of large Turkish and regional diaspora populations, direct air links and substantial self-pay demand for dental and aesthetic treatment. Other European markets contribute through both elective procedures and hospital care. Growth is likely to remain steady rather than explosive because competition from Central and Eastern Europe is increasing, but Turkey's provider depth and airline connectivity preserve a strong structural advantage.
By Destination
Istanbul and Marmara
Istanbul and the wider Marmara region remain the commercial center of the market and are projected to approach USD 3.25 billion of international-patient clinical revenue by 2031. Istanbul combines the country's largest concentration of private hospitals, cosmetic and dental clinics, international airports, specialist physicians and multilingual facilitators. Antalya and the Mediterranean coast form the next major cluster because tourism infrastructure can support elective treatment and recovery, while Ankara is more relevant for complex hospital care and public-university expertise. Izmir and other western cities provide additional capacity but remain smaller international-healthcare hubs.
Recent Developments
July 2026: Industry data reported 302,487 international patients and USD 761.5 million of health-tourism revenue in Q1 2026; revenue per patient rose by about 39% year over year.
June 2026: The Ministry of Health published health-tourism certification criteria supporting the end-2026 accreditation and certification deadline for authorized facilities.
February 2026: Turkey introduced a regulation governing cooperation between Ministry of Health facilities and state universities for international health services.
April 2025: A new International Health Tourism and Tourist Health Regulation took effect, replacing the 2017 framework and strengthening provider and intermediary authorization requirements.
June 2025: The Ministry of Trade reported that Turkey served about 1.5 million health tourists and generated approximately USD 3.0 billion of health-service exports in 2024.
Market Outlook
Turkey's medical-tourism market is expected to grow more slowly than the aggressive targets sometimes cited in promotional material, but the underlying value trajectory remains positive. The 2024 and 2025 revenue data show that a large patient base already exists, while the first quarter of 2026 demonstrates that revenue can rise even when patient numbers decline. This supports a forecast centered on treatment-value expansion rather than headline visitor targets. The largest upside sits in oncology, cardiovascular care, orthopedics, robotics and other complex services where revenue per case is materially above that of routine elective procedures.
The competitive landscape should become more polarized through 2031. Large hospital networks and premium specialty clinics can absorb certification costs, invest in digital patient acquisition and maintain multilingual follow-up programs. Smaller clinics that compete mainly through price will face greater compliance and reputation pressure. Istanbul remains the dominant hub, but Antalya, Ankara and Izmir can gain share in selected specialties. The strongest providers will combine clinical credibility with transparent pricing, rapid pre-arrival review, health-visa support, complication insurance or structured aftercare and referral partnerships in source countries.
Turkey Medical Tourism Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.25 billion in 2026 |
| Total Market Size in 2031 | 5.00 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Treatment Type , Service Provider, Patient Source Region, Destination |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
BY TREATMENT TYPE
Aesthetic and Plastic Surgery
Hair Restoration
Dental Treatment
Ophthalmology
Bariatric and Metabolic Surgery
Oncology
Cardiovascular Treatment
Orthopedic and Spine Treatment
Fertility and Reproductive Treatment
Transplant and Other Specialized Treatments
BY SERVICE PROVIDER
Private Multispecialty Hospitals
Specialty Hospitals and Medical Centers
Dental, Hair and Aesthetic Clinics
Public and University Hospitals
BY PATIENT SOURCE REGION
Europe
Middle East and Gulf
Russia, Caucasus and Central Asia
North Africa
Other Regions
BY DESTINATION
Istanbul and Marmara
Antalya and Mediterranean Turkey
Ankara and Central Anatolia
Izmir and Aegean Turkey
Other Turkey
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Cost and Access Advantages Remain the Core Cross-Border Proposition
3.1.2. Geographic Position Supports a Diversified Source-Market Base
3.1.3. Quality Regulation and Digital Discovery Are Professionalizing the Market
3.2. Market Restraints
3.2.1. Price Competition and Fragmented Specialty Clinics Can Pressure Quality and Margins
3.2.2. Macroeconomic Volatility and Source-Market Disruptions Affect Patient Conversion
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Digital Pre-Arrival Assessment and Patient Navigation
4.2. Robotics, Precision Oncology and Advanced Diagnostics
4.3. Telemedicine and Cross-Border Follow-Up
5. TURKEY MEDICAL TOURISM MARKET BY TREATMENT TYPE
5.1. Introduction
5.2. Aesthetic and Plastic Surgery
5.3. Hair Restoration
5.4. Dental Treatment
5.5. Ophthalmology
5.6. Bariatric and Metabolic Surgery
5.7. Oncology
5.8. Cardiovascular Treatment
5.9. Orthopedic and Spine Treatment
5.10. Fertility and Reproductive Treatment
5.11. Transplant and Other Specialized Treatments
6. TURKEY MEDICAL TOURISM MARKET BY SERVICE PROVIDER
6.1. Introduction
6.2. Private Multispecialty Hospitals
6.3. Specialty Hospitals and Medical Centers
6.4. Dental, Hair and Aesthetic Clinics
6.5. Public and University Hospitals
7. TURKEY MEDICAL TOURISM MARKET BY PATIENT SOURCE REGION
7.1. Introduction
7.2. Europe
7.3. Middle East and Gulf
7.4. Russia, Caucasus and Central Asia
7.5. North Africa
7.6. Other Regions
8. TURKEY MEDICAL TOURISM MARKET BY DESTINATION
8.1. Introduction
8.2. Istanbul and Marmara
8.3. Antalya and Mediterranean Turkey
8.4. Ankara and Central Anatolia
8.5. Izmir and Aegean Turkey
8.6. Other Turkey
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Acibadem Healthcare Group (IHH Healthcare)
10.2. MLP Care - Medical Park Hospitals
10.3. MLP Care - Liv Hospital
10.4. Memorial Healthcare Group
10.5. Medicana Health Group
10.6. Group Florence Nightingale Hospitals
10.7. Anadolu Medical Center
10.8. Koc University Hospital
10.9. American Hospital Istanbul
10.10. Hisar Intercontinental Hospital
10.11. Dunyagoz Hospitals Group
10.12. Medipol Mega University Hospital
10.13. Yeditepe University Hospitals
10.14. Bayindir Healthcare Group
10.15. Lokman Hekim Health Group
10.16. Kent Health Group
10.17. DentGroup
10.18. Vera Clinic
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market size for Turkey medical tourism by 2031?
The Turkey Medical Tourism Market is projected to reach approximately USD 5.00 billion by 2031.
What is the CAGR for Turkey medical tourism from 2026-2031?
The Turkey Medical Tourism Market is projected to grow at about 9.0% CAGR.
Which services dominate Turkey's medical tourism revenue in 2026?
Aesthetic, plastic-surgery, and hair restoration services lead with 29%.
Which regions within Turkey generate most medical tourism revenue?
Istanbul and the Marmara region account for roughly 68% of revenue.
What patient types does Turkey's medical tourism cater to?
The Turkey Medical Tourism Market serves both high-volume elective and complex tertiary-care demands.
What proportion of revenue do private hospitals generate in 2026?
Private hospitals and clinics generate 82% of international patient revenue.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Turkey Medical Tourism Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/turkey-medical-tourism-market