
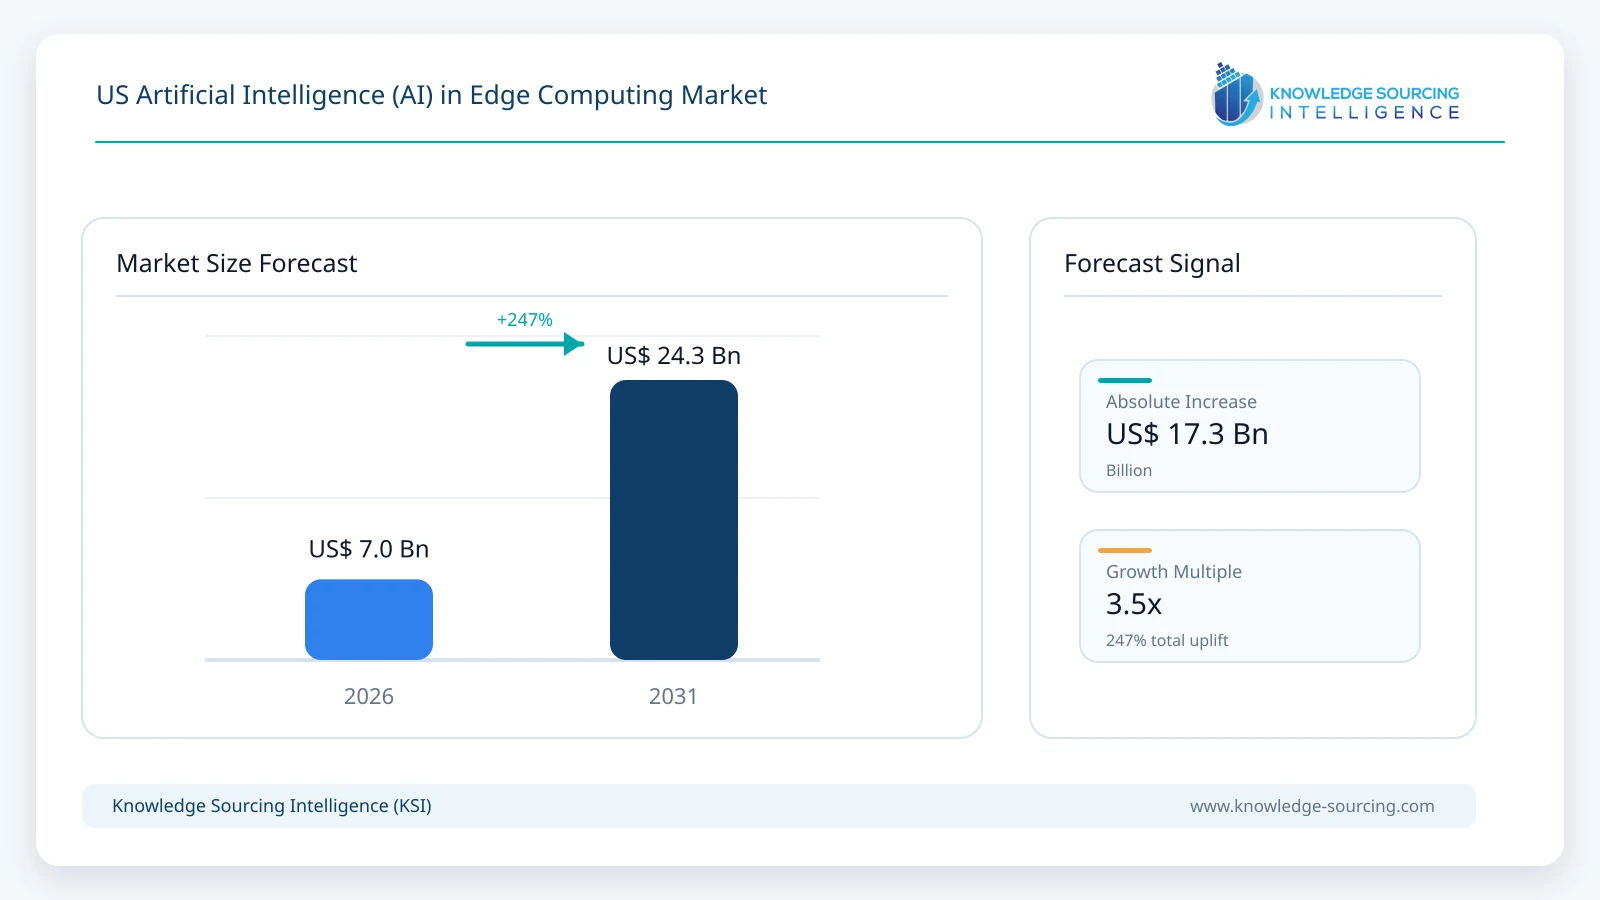
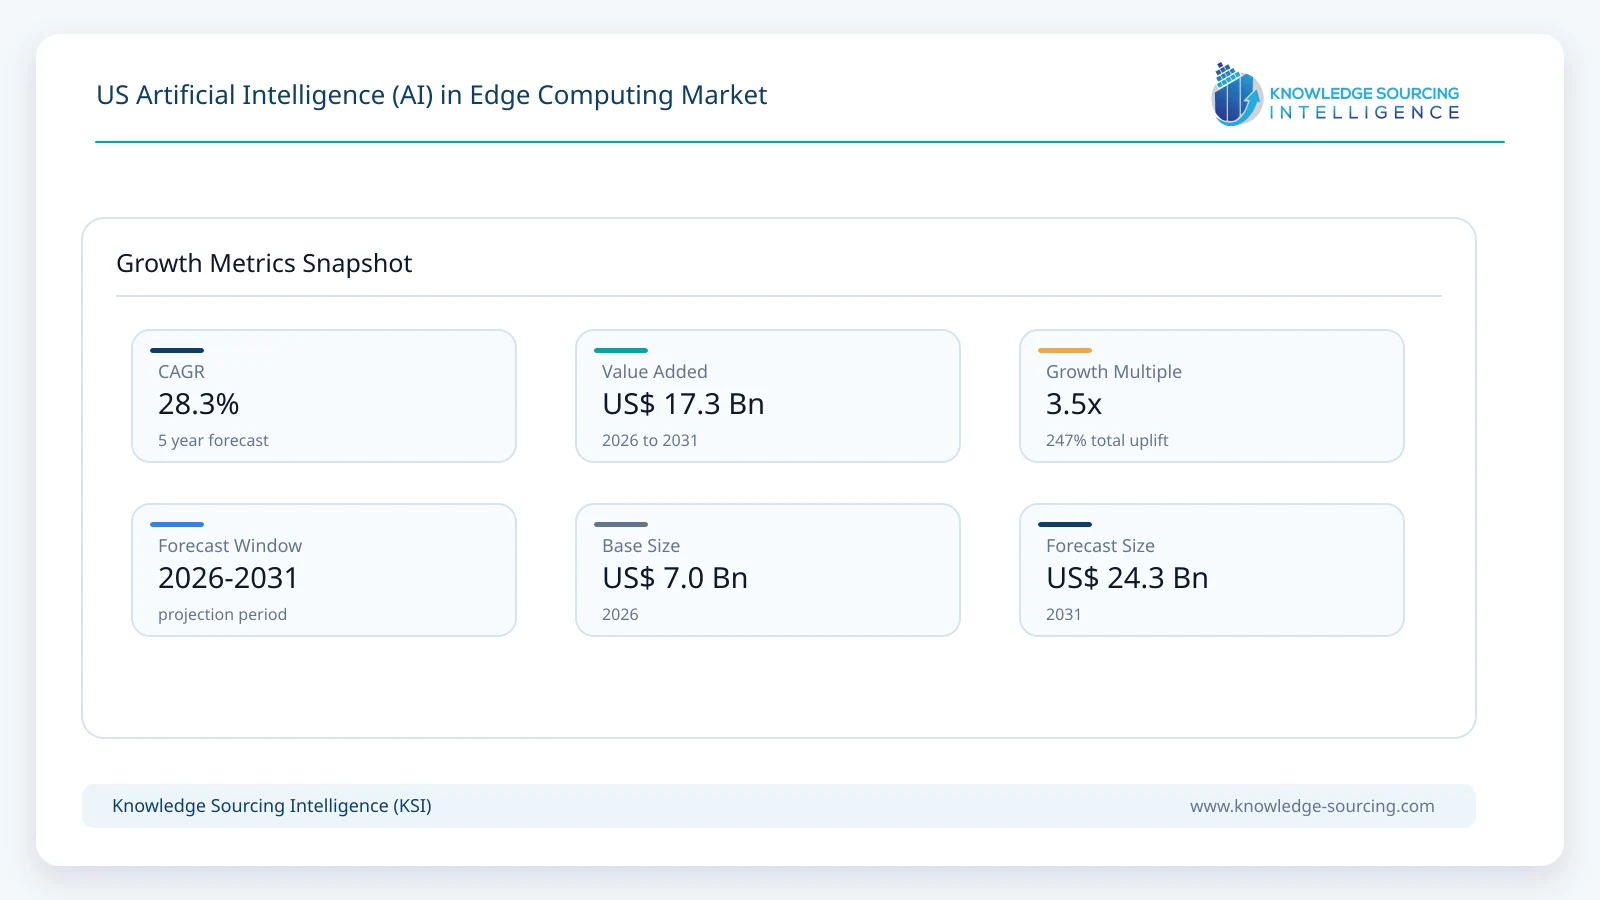
The US AI in Edge Computing Market is forecast to grow at a CAGR of 28.3%, reaching USD 24.3 billion in 2031 from USD 7.0 billion in 2026.
Highlights:
- 1Growing deployment of connected industrial assets is driving enterprise investment in low-latency AI processing at the network edge.
- 2Hardware remains the most commercially significant offering because specialised processors determine inference performance and energy efficiency.
- 3Manufacturing represents one of the strongest end-user opportunities due to predictive maintenance, quality inspection, and production automation.
- 4AI-enabled edge infrastructure increasingly combines dedicated accelerators with cloud-based model management and orchestration.
- 5Federal cybersecurity initiatives and AI governance frameworks are encouraging greater attention to secure edge deployments.
- 6Competition increasingly centres on integrated hardware, software, developer ecosystems, and strategic enterprise partnerships rather than standalone products.
The US Artificial Intelligence (AI) in Edge Computing Market comprises hardware, software, and services that enable artificial intelligence algorithms to process and analyse data directly on edge devices or local infrastructure rather than relying exclusively on centralised cloud environments. Edge AI combines embedded processors, accelerators, networking equipment, software frameworks, and lifecycle management services to support applications requiring low latency, data privacy, operational resilience, and reduced bandwidth consumption. The technology has moved beyond pilot deployments and is becoming part of mainstream enterprise infrastructure across manufacturing, healthcare, telecommunications, retail, transportation, and critical utilities.
Enterprise demand is being shaped by the growing volume of connected sensors, industrial equipment, autonomous systems, and intelligent devices generating continuous streams of operational data. Processing this information at the source enables organisations to make immediate operational decisions while reducing dependence on cloud connectivity. Manufacturers seek shorter production response times, hospitals require local processing of diagnostic imaging, retailers deploy computer vision for store operations, while telecommunications operators integrate AI capabilities into distributed network infrastructure to improve service quality.
Purchasing decisions increasingly extend beyond raw computing performance. Enterprise buyers evaluate scalability, cybersecurity capabilities, compatibility with existing operational technology (OT) environments, software ecosystem maturity, power efficiency, lifecycle support, and regulatory compliance. Procurement teams also favour vendors capable of delivering integrated platforms combining AI hardware, orchestration software, security, and long-term enterprise support, reducing implementation complexity and ownership costs.
Commercial competition reflects this shift. Semiconductor companies continue introducing specialised AI accelerators, cloud providers extend managed edge services, while enterprise infrastructure vendors integrate AI capabilities into networking, servers, storage platforms, and industrial systems. The result is an ecosystem where technology partnerships often determine purchasing outcomes as much as product specifications.
Market Drivers
Expansion of Industrial Automation and Smart Manufacturing
Manufacturing facilities across the United States continue expanding investments in machine vision, robotics, and connected production equipment. These environments generate continuous operational data requiring immediate analysis to prevent equipment failures and maintain product quality. Processing AI workloads locally reduces network delays while supporting uninterrupted production.
Industrial buyers prioritise reliability, deterministic performance, and compatibility with legacy production assets. Suppliers therefore compete by providing ruggedised hardware, industrial software integration, and long-term product support. Vendors able to combine AI acceleration with industrial networking capabilities improve their competitive position among large manufacturing customers.
Growth in Connected Healthcare Infrastructure
Healthcare providers increasingly deploy AI-enabled imaging systems, patient monitoring devices, and connected diagnostic equipment. Many clinical applications require local inference because patient information must remain protected while supporting rapid clinical decision-making.
Hospitals evaluate cybersecurity, regulatory compliance, interoperability, and lifecycle management before procurement. Vendors offering secure AI software alongside validated hardware platforms gain advantages in healthcare purchasing decisions, particularly as providers modernise digital clinical infrastructure.
Telecommunications Network Modernisation
US telecommunications operators continue expanding distributed computing infrastructure to support 5G applications. AI at the network edge enables traffic optimisation, predictive maintenance, automated resource allocation, and improved service quality.
Telecommunications companies favour scalable platforms capable of supporting multiple workloads across geographically distributed locations. Infrastructure providers increasingly collaborate with semiconductor companies and cloud service providers to deliver integrated edge AI solutions suitable for carrier environments.
Rising Enterprise Focus on Data Privacy and Operational Continuity
Many organisations prefer processing sensitive operational data locally instead of transferring every workload to central cloud platforms. Edge AI reduces exposure to network interruptions while supporting compliance with internal governance and industry regulations.
This preference encourages procurement of hybrid architectures combining local inference with centralised model training. Vendors therefore differentiate themselves through unified software management platforms capable of coordinating distributed AI deployments securely across enterprise environments.
Market Restraints and Challenges
High Infrastructure Investment Requirements
Enterprise-grade edge AI deployments require specialised processors, networking equipment, storage systems, software licences, cybersecurity tools, and integration services. Initial investment remains substantial, particularly for organisations operating multiple facilities.
Smaller enterprises often delay implementation because expected operational savings may require several years to offset deployment costs. Suppliers increasingly address this challenge through subscription-based software, managed services, and modular deployment models.
Integration with Legacy Operational Systems
Many industrial organisations continue operating equipment installed over several decades. Integrating AI platforms with proprietary industrial protocols and legacy control systems frequently requires customised engineering.
System integration increases project timelines and implementation costs while creating interoperability challenges. Vendors investing in open standards, middleware, and industrial partnerships reduce these adoption barriers.
Cybersecurity Risks Across Distributed Infrastructure
Distributed AI infrastructure expands the number of connected endpoints requiring continuous protection. Compromised edge devices may disrupt operations or expose sensitive enterprise information.
Buyers therefore demand secure hardware architectures, encrypted communications, identity management, remote software updates, and continuous monitoring. Security capabilities increasingly influence supplier selection alongside computing performance.
Shortage of AI Infrastructure Expertise
Successful deployment requires expertise spanning AI software, networking, cybersecurity, cloud orchestration, industrial engineering, and systems integration. Many organisations lack multidisciplinary implementation teams.
This skills gap increases dependence on external service providers while extending deployment schedules. Technology suppliers continue expanding consulting, deployment, and managed service offerings to address customer capability shortages.
Major Segment Analysis
Hardware
Hardware represents the most commercially important offering because AI inference performance depends heavily on specialised processing capability. Enterprise customers increasingly procure graphics processing units (GPUs), neural processing units (NPUs), AI accelerators, edge servers, embedded processors, and intelligent networking equipment capable of executing machine learning models with minimal latency.
Demand originates primarily from manufacturing, telecommunications, healthcare, and transportation sectors where operational decisions must occur within milliseconds. Buyers assess computational performance, energy consumption, thermal efficiency, reliability, software compatibility, and expected operating lifespan before procurement.
Competition within the hardware segment extends beyond processing speed. Vendors invest heavily in software development kits, developer ecosystems, hardware optimisation libraries, and strategic partnerships with enterprise software providers. Organisations increasingly prefer hardware platforms supporting multiple AI frameworks while simplifying deployment across thousands of distributed endpoints.
The commercial significance of hardware also reflects long replacement cycles. Enterprise customers making infrastructure investments typically expect several years of operational support, creating recurring revenue opportunities through maintenance services, software upgrades, and complementary infrastructure expansion.
Competitive Landscape
Competition within the US Artificial Intelligence in Edge Computing Market combines semiconductor innovation, cloud infrastructure, enterprise software, networking expertise, and systems integration capabilities. Suppliers increasingly compete through complete technology ecosystems rather than isolated hardware or software products.
Strategic partnerships remain central to commercial positioning. Semiconductor manufacturers collaborate with cloud providers to optimise AI frameworks, while enterprise infrastructure companies integrate networking, storage, cybersecurity, and lifecycle management into unified edge platforms. Software compatibility, developer tools, and enterprise support increasingly influence purchasing decisions alongside processing performance.
The competitive environment includes Intel Corporation, NVIDIA Corporation, Qualcomm Technologies, Inc., Amazon Web Services, Inc., Microsoft Corporation, Alphabet Inc. (Google Cloud), International Business Machines Corporation (IBM), Cisco Systems, Inc., Dell Technologies Inc., and Oracle Corporation. These companies compete through platform integration, ecosystem development, enterprise partnerships, geographic expansion, and continued investment in AI infrastructure capabilities.
Recent Developments
June 2026: NVIDIA unveiled the RTX Spark AI chip at Computex 2026, designed to execute advanced AI models and autonomous AI agents directly on PCs, accelerating the industry's shift toward local, edge-based AI inference rather than cloud-only processing.
June 2026: HPE announced significant enhancements to its self-driving networking portfolio, integrating AI-native networking, Agentic AIOps, routing, and security technologies to simplify AI operations and optimise performance across enterprise edge, AI factories, and distributed data centre environments.
March 2026: Hewlett Packard Enterprise (HPE), in collaboration with NVIDIA, introduced the HPE AI Grid, enabling secure orchestration of distributed AI inference across regional and far-edge locations for real-time enterprise, healthcare, manufacturing, retail, and telecommunications applications.
Regulatory and Policy Environment
The regulatory environment increasingly influences enterprise AI deployment decisions. The US government continues promoting trustworthy AI development through guidance issued by federal agencies while strengthening cybersecurity expectations for critical infrastructure operators.
The National Institute of Standards and Technology (NIST) AI Risk Management Framework provides voluntary guidance supporting governance, transparency, security, and responsible AI implementation. Organisations deploying edge AI increasingly align procurement and operational policies with these recommendations.
Cybersecurity regulations affecting critical infrastructure encourage stronger protection of distributed computing assets. Zero-trust security principles, software supply chain verification, encryption requirements, and continuous monitoring have become common procurement expectations for enterprise buyers.
Federal initiatives supporting semiconductor manufacturing, advanced computing research, and domestic technology resilience also contribute to investment across AI hardware ecosystems, benefiting suppliers participating in US infrastructure expansion.
Outlook and Strategic Implications
The US Artificial Intelligence in Edge Computing Market is expected to experience sustained enterprise investment over the next several years as organisations seek faster operational decision-making, improved resilience, and greater control over sensitive data. Future procurement will increasingly favour integrated platforms combining AI accelerators, secure software management, cloud interoperability, and lifecycle services.
Investment priorities are expected to focus on energy-efficient processors, scalable orchestration platforms, cybersecurity, industrial interoperability, and AI model management. Hybrid cloud-edge architectures will remain the preferred deployment model because they balance centralised training with distributed inference.
Competitive positioning will depend less on individual hardware specifications and more on ecosystem maturity, enterprise software compatibility, developer support, and strategic alliances. Suppliers capable of delivering secure, scalable, and operationally efficient platforms will be better positioned to capture enterprise spending across manufacturing, healthcare, telecommunications, transportation, retail, and critical infrastructure.
Despite continued opportunities, organisations must manage cybersecurity exposure, integration complexity, evolving AI governance expectations, and workforce capability constraints. Enterprises that align infrastructure investments with long-term operational objectives while selecting interoperable technology platforms are expected to achieve stronger returns from edge AI deployment over the forecast period.
US AI in Edge Computing Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 7.0 billion |
| Total Market Size in 2031 | USD 24.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 28.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Offering, Enterprise Size, Application, End User |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Offering
Hardware
Software
Services
By Enterprise Size
Small and Medium-sized Enterprises (SMEs)
Large Enterprises
By Application
Real-Time Data Analytics
Computer Vision
Predictive Maintenance
Anomaly Detection
Natural Language Processing (NLP)
Others
By End-user
Manufacturing
Healthcare
Retail
Telecommunications
Transportation & Logistics
Energy & Utilities
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. US ARTIFICIAL INTELLIGENCE (AI) IN EDGE COMPUTING MARKET BY OFFERING
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
6. US ARTIFICIAL INTELLIGENCE (AI) IN EDGE COMPUTING MARKET BY ENTERPRISE SIZE
6.1. Introduction
6.2. Small and Medium-sized Enterprises (SMEs)
6.3. Large Enterprises
7. US ARTIFICIAL INTELLIGENCE (AI) IN EDGE COMPUTING MARKET BY APPLICATION
7.1. Introduction
7.2. Real-Time Data Analytics
7.3. Computer Vision
7.4. Predictive Maintenance
7.5. Anomaly Detection
7.6. Natural Language Processing (NLP)
7.7. Others
8. US ARTIFICIAL INTELLIGENCE (AI) IN EDGE COMPUTING MARKET BY END-USER
8.1. Introduction
8.2. Manufacturing
8.3. Healthcare
8.4. Retail
8.5. Telecommunications
8.6. Transportation & Logistics
8.7. Energy & Utilities
8.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Intel Corporation
10.2. NVIDIA Corporation
10.3. Qualcomm Technologies, Inc.
10.4. Amazon Web Services, Inc.
10.5. Microsoft Corporation
10.6. Alphabet Inc. (Google Cloud)
10.7. International Business Machines Corporation (IBM)
10.8. Cisco Systems, Inc.
10.9. Dell Technologies Inc.
10.10. Oracle Corporation
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected growth rate and market size for the US AI in Edge Computing market?
The US Artificial Intelligence (AI) in Edge Computing Market is forecast to grow at a robust Compound Annual Growth Rate (CAGR) of 28.3% between 2026 and 2031. This significant expansion is projected to increase the market value from USD 7.00 billion in 2026 to an impressive USD 24.30 billion by 2031, reflecting strong adoption across various sectors.
Which components and end-user industries are driving the US AI in Edge Computing market growth?
The US Artificial Intelligence (AI) in Edge Computing Market comprises hardware, software, and services, with hardware identified as the most commercially significant offering due to its critical role in determining inference performance and energy efficiency. Manufacturing represents one of the strongest end-user opportunities, driven by applications such as predictive maintenance, quality inspection, and production automation. Other key industries include healthcare, telecommunications, retail, transportation, and critical utilities.
What are the primary factors fueling enterprise demand for AI in Edge Computing within the US market?
Enterprise demand in the US is primarily shaped by the growing volume of connected sensors, industrial equipment, autonomous systems, and intelligent devices generating continuous streams of operational data. Organizations seek to process this information at the source to enable immediate operational decisions, enhance data privacy, ensure operational resilience, and reduce dependence on cloud connectivity.
Who are the key players and what defines the competitive landscape in the US AI in Edge Computing market?
The competitive landscape features semiconductor companies introducing specialized AI accelerators, cloud providers extending managed edge services, and enterprise infrastructure vendors integrating AI capabilities into their networking, servers, storage platforms, and industrial systems. In this ecosystem, technology partnerships are frequently a decisive factor in purchasing outcomes, influencing product specifications and market penetration.
What critical considerations are shaping enterprise purchasing decisions for AI in Edge Computing solutions in the US?
Enterprise buyers are increasingly evaluating solutions based on scalability, robust cybersecurity capabilities, and compatibility with existing operational technology (OT) environments. Other key factors include software ecosystem maturity, power efficiency, lifecycle support, and regulatory compliance. Procurement teams also favor vendors capable of delivering integrated platforms combining AI hardware, orchestration software, and long-term enterprise support to reduce implementation complexity and ownership costs.
What specific benefits and applications does AI in Edge Computing offer to US enterprises?
US enterprises deploy AI in Edge Computing to achieve critical benefits such as low latency processing, enhanced data privacy, increased operational resilience, and reduced bandwidth consumption by processing data locally. This enables applications like shorter production response times and predictive maintenance in manufacturing, local processing of diagnostic imaging in healthcare, and computer vision for store operations in retail, directly addressing immediate operational needs.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). US Artificial Intelligence (AI) in Edge Computing Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/us-artificial-intelligence-ai-in-edge-computing-market