
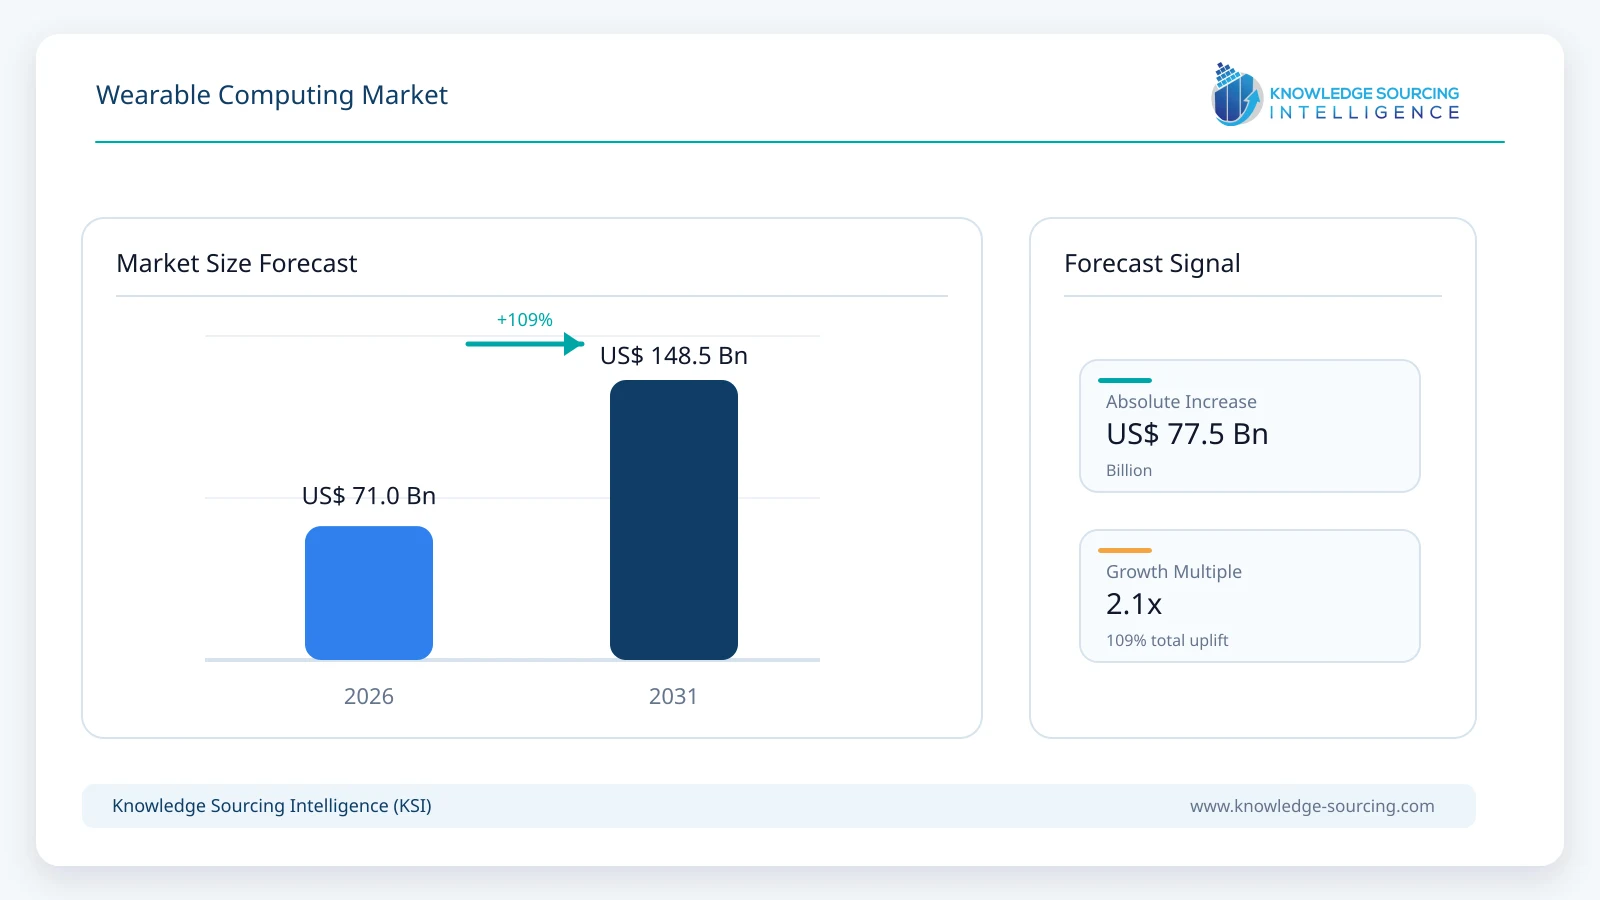
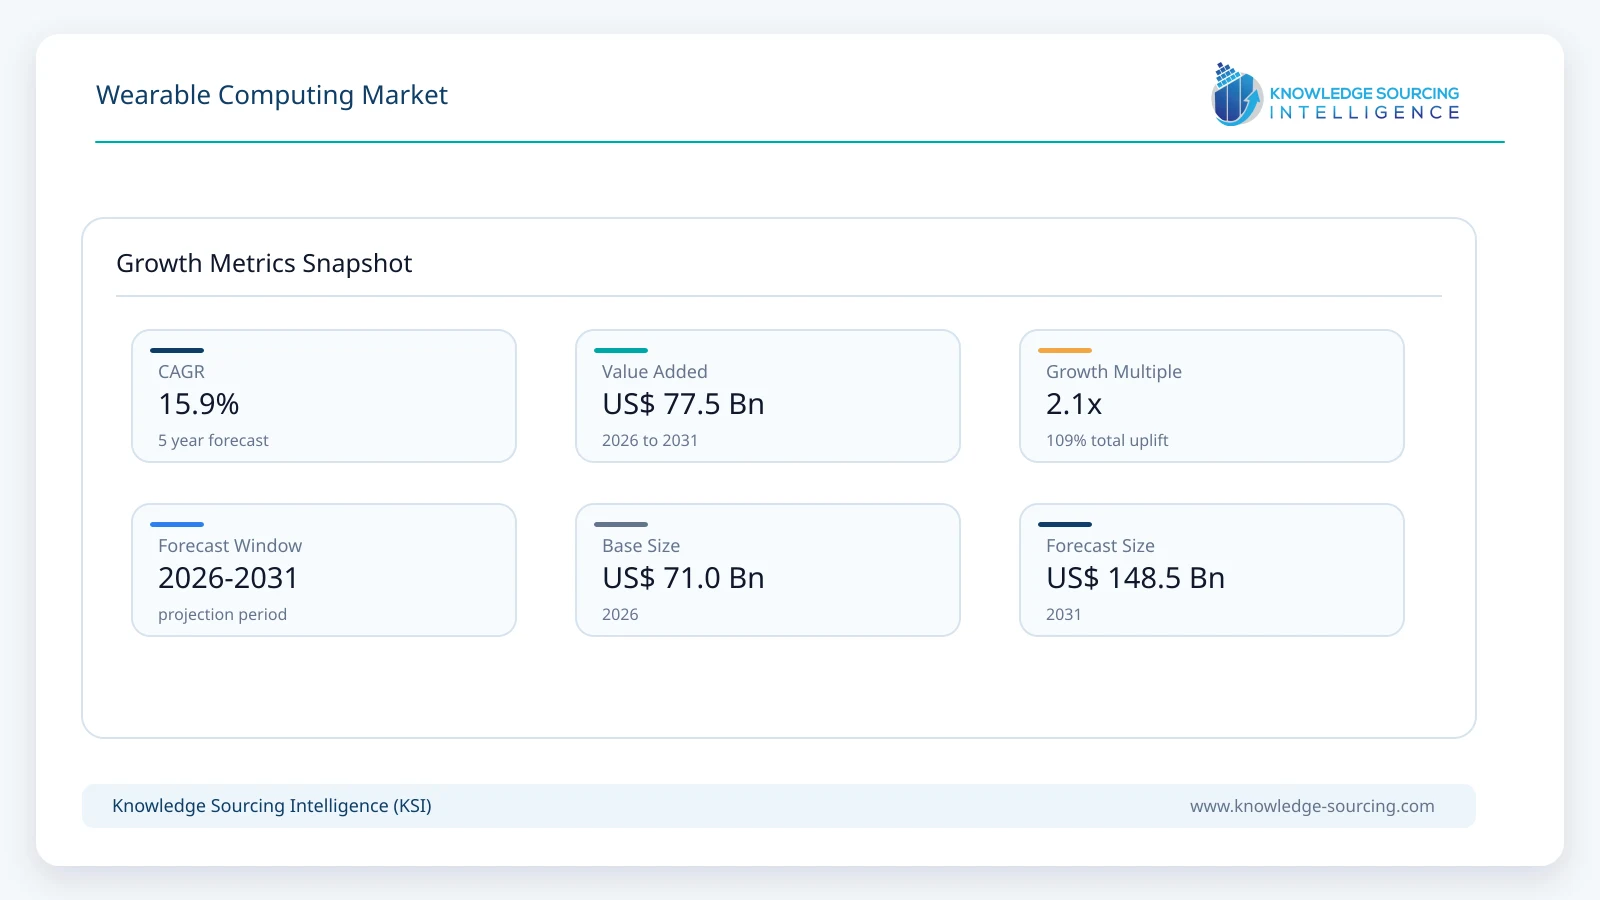
The wearable computing market is forecast to grow at a CAGR of 15.9%, reaching USD 148.5 billion in 2031 from USD 71.0 billion in 2026.
Highlights:
- 1Health-Centered ComputingSmartwatches, fitness trackers, smart rings, and other connected wearables are increasingly supporting continuous health, fitness, sleep, and activity monitoring.
- 2AI-Enabled PersonalizationWearable platforms are increasingly combining biometric signals with artificial intelligence to convert continuous measurements into personalized health, fitness, and wellness insights.
- 3Connected Wearable EcosystemsWearables are becoming more closely integrated with smartphones, cloud platforms, health applications, and enterprise systems, increasing the value of real-time data.
- 4Miniaturization and New Form FactorsSmart rings, screen-free trackers, smart glasses, e-textiles, and other compact devices are expanding wearable computing beyond conventional wrist-worn products.
- 5Increasing Institutional AdoptionGovernment health agencies and public-health organizations are examining wearable technologies for physical-activity measurement, population monitoring, digital health, and remote care applications.
The wearable computing market comprises body-worn or body-attached electronic systems that combine computing, sensing, connectivity, processing, display, or interactive capabilities. The market includes smartwatches, fitness trackers, smart glasses and augmented reality devices, virtual reality headsets, smart clothing and e-textiles, hearables, and related wearable computing products. These devices use sensors, processors, wireless connectivity, software, and increasingly artificial intelligence to collect and interpret information and provide users with digital functionality in real time.
The distinction between wearable computing and general wearable technology is important. A wearable computing product does more than simply provide a body-worn electronic function; it incorporates computing or connected processing capabilities that allow information to be captured, processed, communicated, displayed, or acted upon. This definition places smartwatches, connected fitness trackers, smart glasses, VR headsets, smart clothing, and intelligent hearables within the addressable market while avoiding the inclusion of conventional non-computing accessories.
Healthcare and wellness represent important areas of application because wearable devices can continuously or periodically collect physiological and behavioral information. The U.S. Food and Drug Administration identifies wearable devices as part of the broader digital-health ecosystem and notes that digital health technologies can combine computing platforms, connectivity, software, and sensors for healthcare and related applications. The FDA also maintains a specific list of authorized sensor-based digital-health technologies that includes wearable products such as smartwatches, rings, patches, and bands.
Public-health institutions are also moving beyond consumer adoption toward systematic evaluation of wearable data. In May 2026, the World Health Organization published a technical report examining how wearable technologies can be integrated into population health monitoring systems for physical-activity measurement. The work addresses device selection, wear location, wear-time protocols, data processing, representativeness, cost, data management, standardization, and national capacity building. This provides institutional evidence that wearable computing is increasingly relevant to population-level health measurement rather than being limited to consumer fitness applications.
The market is also benefiting from wider digital connectivity. India's Ministry of Statistics and Programme Implementation reported in its 2025 Comprehensive Modular Survey on Telecom that approximately 85.5% of Indian households possessed at least one smartphone and around 86.3% had internet access within the household premises. Among people aged 15–29 years, smartphone ownership among mobile-phone owners was approximately 95.5% in rural areas and 97.6% in urban areas. These indicators demonstrate the increasingly connected consumer environment in which companion wearable devices can operate.
Government digital infrastructure is also relevant to enterprise and connected-device adoption. The Telecom Regulatory Authority of India continues to publish monthly telecom subscription data, including data through June 2026, providing evidence of ongoing development of the country's mobile and connectivity infrastructure. Such infrastructure supports the broader ecosystem required for connected wearable devices, although telecom subscription growth should not be interpreted directly as wearable-device adoption.
How Wearable Computing Impacts Different Sectors
Wearable computing is increasingly affecting healthcare, sports and fitness, enterprise operations, consumer services, manufacturing, logistics, and entertainment by allowing users to access computing capabilities while moving through physical environments.
Healthcare Sector
Healthcare is one of the most important application areas because wearable computing can support continuous or intermittent collection of physiological and behavioral information. Smartwatches, rings, patches, and other connected devices can capture signals such as heart rate, activity, sleep, temperature, oxygen saturation, and other measurements depending on the device and its intended use. However, consumer wellness measurements should not automatically be treated as medical diagnoses. Regulatory status depends on the intended use and the applicable jurisdiction.
The FDA's digital-health framework explicitly includes wearable devices, while its sensor-based digital-health database identifies authorized wearable technologies for continuous or spot monitoring in non-clinical environments. The database includes examples such as wearable cardiac and neurological monitoring technologies and authorized continuous glucose-monitoring systems. This regulatory recognition strengthens the role of wearables within digital healthcare while also highlighting the importance of clinical validation and intended-use claims.
The World Health Organization's 2026 work on wearable technology and population monitoring further demonstrates the healthcare relevance of these systems. WHO identified opportunities to use wearables alongside conventional self-report instruments while also emphasizing challenges involving data quality, standardization, participation, representativeness, and data management. These considerations are important for the market because broader healthcare adoption depends not only on sensor accuracy but also on interoperability, validation, privacy, and the ability to interpret data consistently.
Business, Manufacturing, and Logistics
Enterprise wearable computing enables employees to access information without repeatedly interacting with conventional computing equipment. Smart glasses can display instructions or technical information, while wearable scanners and connected devices can support inventory management, inspection, maintenance, training, and logistics activities. In manufacturing, wearable computing can combine sensors, communication systems, and software to provide workers with contextual information while keeping their hands available for physical tasks.
The business opportunity is therefore broader than consumer electronics. Enterprise deployments can be linked to productivity, workforce safety, equipment maintenance, training, remote assistance, and operational data. However, adoption depends on device durability, battery life, integration with enterprise software, cybersecurity, worker acceptance, and measurable returns on investment.
India also provides an important manufacturing and digital-infrastructure context for wearable computing. According to the Ministry of Electronics and Information Technology's 2025–26 annual report, India had more than 300 manufacturing units producing cellular mobile phones and related parts and components. Mobile-phone production reached approximately INR 5.45 lakh crore in FY2024–25, while mobile-phone exports were approximately INR 2.05 lakh crore. Although these figures relate to mobile electronics rather than wearable devices specifically, they indicate the increasing depth of India's electronics manufacturing ecosystem that can support adjacent connected-device supply chains.
Wearable computing therefore has a dual-sector role: it serves consumers seeking personal health and connectivity capabilities while also providing enterprises with hands-free computing, sensing, communication, and workforce-management tools.
Several factors are supporting the wearable computing market:
Increasing Health and Wellness Awareness: Consumers are increasingly using connected devices to understand physical activity, sleep, recovery, exercise, and selected health indicators. Government and public-health institutions are also examining wearable data as a potential source for more consistent physical-activity measurement.
Artificial Intelligence Integration: AI is increasingly being incorporated into wearable platforms to interpret biometric and behavioral data, generate summaries, identify patterns, and provide personalized recommendations. The shift from simple tracking toward contextual guidance is becoming an important competitive factor.
Expansion of Connected Ecosystems: Integration with smartphones, cloud platforms, health applications, and enterprise software increases the utility of wearable devices. Users can increasingly view wearable data across multiple devices and services rather than treating the wearable as an isolated product.
New Wearable Form Factors: Smart rings, smart glasses, screen-free fitness trackers, smart clothing, and AI-enabled hearables are broadening the market beyond conventional smartwatches and fitness bands.
Despite these opportunities, the wearable computing market faces several challenges:
Data Privacy and Security: Wearables can collect highly personal information, including health, location, activity, sleep, and behavioral data. The European Commission's Joint Research Centre has highlighted questions surrounding the sharing and reuse of wearable-generated data and the implications of European data legislation. Privacy and data-governance requirements therefore remain important considerations for manufacturers and platform operators.
Battery and Energy Constraints: Small wearable form factors restrict available battery capacity. Continuous sensing, displays, wireless connectivity, satellite communication, and local AI processing can increase power consumption. Manufacturers must therefore balance device size, sensing capability, processing performance, battery life, and user comfort.
Accuracy and Validation: Wearable measurements can vary according to device design, sensor placement, user behavior, algorithms, and intended use. Healthcare applications require stronger validation than general wellness functions, increasing development, testing, and regulatory requirements.
The wearable computing market is therefore developing from a collection of connected personal devices into a broader computing ecosystem that combines sensors, AI, connectivity, software, and increasingly specialized form factors. Continued growth will depend on the ability of manufacturers to deliver useful computing experiences while addressing privacy, energy efficiency, interoperability, cybersecurity, accuracy, and regulatory requirements.
Wearable Computing Market Overview:
The wearable computing market is supported by the convergence of miniaturized electronics, sensors, wireless connectivity, cloud computing, artificial intelligence, and mobile applications. Smartwatches and fitness trackers remain important because they combine multiple functions in compact form factors, while smart rings and smart glasses are expanding the range of ways users can interact with computing systems.
The market's health orientation is becoming particularly significant. WHO's 2026 technical work on integrating wearable technologies into population health monitoring demonstrates growing institutional interest in using wearable-generated measurements for physical-activity and sedentary-behavior surveillance. At the same time, the FDA's sensor-based digital-health database shows that wearable devices can form part of regulated digital-health solutions when they meet applicable requirements.
Connectivity is another important market foundation. India's 2025 telecom survey found that 86.3% of households had internet access within the household premises, while 85.5% possessed at least one smartphone. These levels of digital access support the ecosystem surrounding companion wearables because many wearable products depend on smartphone applications, internet connectivity, cloud synchronization, or connected services.
India is also strengthening its broader electronics manufacturing capacity. MeitY reported more than 300 cellular mobile-phone and component manufacturing units and approximately INR 5.45 lakh crore of mobile-phone production in FY2024–25. While wearable manufacturing has its own supply-chain requirements, the expansion of electronics manufacturing, component production, and assembly capabilities creates a favorable foundation for connected-device production.
Competition is increasingly shifting from hardware specifications alone toward ecosystem strength, software intelligence, health-data interpretation, battery performance, comfort, connectivity, and recurring digital services. Companies with established mobile ecosystems have an advantage because they can integrate wearable products with smartphones, operating systems, health applications, cloud services, and AI platforms.
Wearable Computing Market Trends
The wearable computing market is moving toward continuous, contextual, and increasingly AI-assisted computing. Rather than functioning solely as step counters or notification screens, newer wearables are designed to interpret multiple data streams and convert them into more actionable information.
AI-enabled health interpretation is becoming a major trend. Samsung announced in June 2026 that its Samsung Health platform was being updated to translate biometric data from Galaxy Watch into more actionable daily guidance, including information related to sleep, activity, and other health signals. In July 2026, Samsung introduced Galaxy Watch9 and Galaxy Watch Ultra2 with an expanded focus on AI-driven health intelligence, continuous monitoring, and personalized guidance.
Another trend is the expansion of discreet wearable form factors. Oura introduced Oura Ring 5 in May 2026 and described it as a smaller smart ring with next-generation sensing, week-long battery life, and expanded software functionality. Oura also introduced Health Radar, Live Activity Tracking, and other software capabilities intended to turn continuous biometric data into more personalized insights.
Smart glasses are also moving toward AI-enabled computing. In June 2026, Meta announced a partnership with EssilorLuxottica to introduce Meta Glasses, featuring Meta AI from launch and compatibility with prescription lenses. The development demonstrates the industry's movement toward glasses that combine conventional eyewear with AI-assisted computing and hands-free interaction.
Connectivity is also expanding beyond smartphone notifications. Garmin introduced new smartwatch functionality in March 2026 that allows users of selected smartwatches to read, reply to, and react to WhatsApp messages directly from the wrist. Garmin subsequently introduced the f?nix 9 and f?nix 9 Pro in August 2026, with the Pro models incorporating satellite and LTE connectivity for voice, text, and SOS communication directly from the wrist.
These developments indicate a shift toward wearable devices acting as independent computing interfaces. The long-term opportunity is not limited to collecting data; it involves enabling communication, contextual assistance, health interpretation, navigation, safety, and other digital functions without requiring constant interaction with a smartphone.
Wearable Computing Market Dynamics
Market Drivers
Rising Health, Wellness, and Fitness Adoption
Wearables are increasingly used for activity, sleep, exercise, recovery, and selected health measurements. WHO's 2026 technical work confirms that wearable technology is being evaluated for population-level physical-activity measurement, creating an institutional dimension to demand beyond consumer fitness. Apple's January 2026 update also reported analysis from approximately 100,000 participants in the Apple Heart and Movement Study, illustrating the scale at which wearable-generated activity data can support research.AI and Sensor Innovation
AI is increasing the value of wearable sensor data by enabling devices and companion applications to identify patterns and provide personalized guidance. Samsung's 2026 Galaxy Watch strategy emphasizes AI-driven health insights, while Oura has introduced AI-oriented software capabilities alongside its latest ring platform. These developments encourage manufacturers to compete on data interpretation and software intelligence rather than only on sensor counts or hardware specifications.Expansion of Digital Connectivity
Wearables benefit from increasingly connected consumer environments. India's 2025 government survey found that 86.3% of households had internet access and 85.5% had at least one smartphone. Smartphone and internet access enable wearable synchronization, cloud services, software updates, notifications, and health-data management.Growth of Independent Wearable Functions
Wearables are increasingly capable of performing functions that previously required smartphones. Garmin's 2026 WhatsApp integration and f?nix 9 Pro satellite and LTE communication demonstrate the progression toward independent wrist-based communication and emergency functions.
Wearable Computing Market Restraints
Data Privacy and Cybersecurity Risks
Wearable devices can collect continuous information about health, movement, sleep, location, and daily routines. The European Commission's Joint Research Centre has specifically examined the policy implications of sharing wearable data for public-interest purposes, while emphasizing that privacy and data-access questions remain important. Manufacturers must therefore develop strong privacy controls and secure data-management systems while complying with applicable laws.Battery Life and Device Comfort
Continuous sensing and connected functions increase power requirements, while wearable products must remain small and comfortable enough for extended use. Manufacturers are responding through improved power management, larger-capacity batteries, more efficient sensors, and optimized software. Samsung's 2026 Galaxy Watch9, for example, incorporates a 390mAh battery that the company says provides 20% more capacity than the previous generation. Oura's Ring 5 emphasizes compact construction alongside week-long battery life.Regulatory and Validation Requirements
Wearables making health-related claims can face additional regulatory and evidence requirements depending on their intended use. The FDA's digital-health framework distinguishes general digital-health technologies from products that meet medical-device requirements. Manufacturers therefore need to align claims, algorithms, clinical evidence, cybersecurity practices, and product design with the relevant regulatory framework.
Wearable Computing Market Segmentation Analysis
By Type: Smartwatches
Smartwatches remain one of the most comprehensive wearable-computing form factors because they combine sensing, processing, communication, applications, displays, health monitoring, fitness functions, and notification capabilities in a single device. The category is evolving from basic activity tracking toward continuous health and AI-assisted computing. Samsung introduced Galaxy Watch9 and Galaxy Watch Ultra2 in July 2026 with an emphasis on continuous health monitoring, AI-driven insights, improved battery performance, and expanded health-management functions.
Apple's current Apple Watch portfolio also illustrates the breadth of smartwatch computing. Apple's 2026 materials identify Series 11, SE 3, and Ultra 3 as current products, with features spanning fitness tracking, sleep monitoring, ECG, safety, hypertension notifications, cellular connectivity, and satellite-based emergency communication on applicable models. Apple also expanded availability of sleep-apnoea notifications in India in May 2026.
Garmin is expanding the category in performance and outdoor applications. In August 2026, Garmin introduced f?nix 9 and f?nix 9 Pro, with the Pro models offering built-in satellite and LTE connectivity for voice, text, and SOS communication. Garmin also continued to expand smartwatch software and communication functions during 2026.
These developments support smartwatches as a major wearable-computing segment because manufacturers are increasingly combining health sensing, AI, communications, safety, fitness, and third-party applications in one wrist-based computing platform.
By Application: Health, Wellness, and Fitness
Health, wellness, and fitness represent a major application area because wearable devices can provide frequent measurements without requiring users to interact continuously with conventional medical or computing equipment. The application includes exercise tracking, activity monitoring, sleep analysis, recovery assessment, heart-rate measurement, selected physiological monitoring, and wellness insights.
Government and institutional activity provides evidence of the increasing importance of this application. WHO's 2026 report on wearable technology and population health monitoring evaluates how wearable devices can complement traditional methods for measuring physical activity and sedentary behavior. The report also emphasizes the need for standardized protocols, data processing, device evaluation, and representative participation.
The FDA likewise identifies wearable devices as part of digital health and maintains a database of authorized sensor-based digital-health technologies. Its list includes wearable products designed for continuous or spot monitoring in non-clinical settings. This creates opportunities for health-oriented wearables while reinforcing the need for appropriate validation and regulatory compliance when products are positioned for medical applications.
Commercial developments are reinforcing the trend. Samsung's 2026 Galaxy Watch strategy centers on converting biometric data into personalized health guidance, while Oura's Ring 5 and associated Health Radar features emphasize continuous health and recovery insights. Apple's 2026 Apple Watch updates also expanded health functionality in India, including sleep-apnoea notifications and a clinically validated Hearing Test through AirPods Pro.
Consequently, the health, wellness, and fitness application is likely to remain central to wearable-computing adoption, particularly as manufacturers improve sensor accuracy, battery efficiency, AI interpretation, data privacy, and integration with healthcare ecosystems.
Wearable Computing Market Geographical Outlook
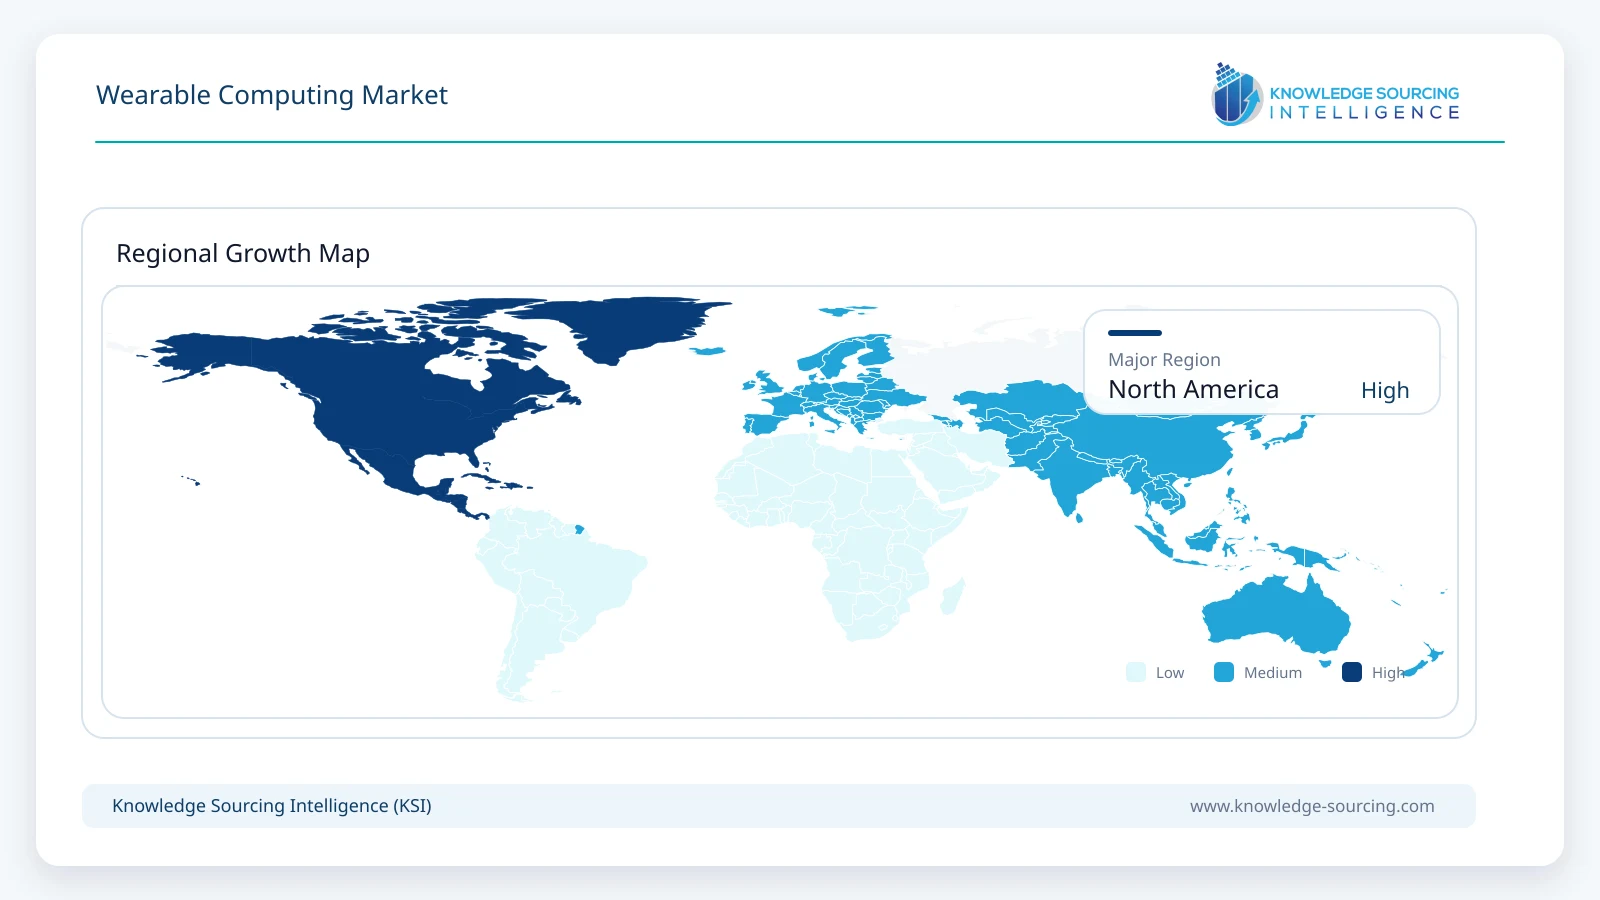
By Region: North America
North America remains an important wearable-computing region because of its established technology ecosystem, strong presence of global device manufacturers, mature digital-health infrastructure, and high level of consumer and enterprise technology adoption. The region is also significant for regulatory development because the U.S. FDA maintains dedicated digital-health and sensor-based digital-health resources covering wearable devices.
The U.S. regulatory environment is increasingly relevant to health-oriented wearables. The FDA's AI-enabled medical-device resources show that artificial intelligence is becoming an established component of regulated medical technologies, while the agency's digital-health framework recognizes wearable devices as one category within digital health. In December 2025, the FDA also launched its TEMPO pilot for selected digital-health devices intended to support outcomes in chronic-disease areas, reflecting continued regulatory attention to technology-enabled healthcare.
North America's commercial environment is also characterized by strong competition among Apple, Google, Garmin, Meta, Oura, and other technology companies. Product innovation is increasingly focused on health intelligence, AI, independent connectivity, smart glasses, and new form factors.
Oura's 2026 expansion further demonstrates the region's role as a center for advanced health-wearable development. The company introduced Oura Ring 5 with smaller dimensions, expanded sensing, and new software capabilities, while also expanding its global presence into markets including India, Australia, New Zealand, Mexico, and the UAE.
North America's position is therefore supported not simply by consumer purchasing power but by the combination of technology companies, software ecosystems, digital-health infrastructure, regulatory development, research activity, and investment in next-generation wearable interfaces.
List of Top Wearable Computing Companies:
Apple Inc.
Samsung Electronics Co., Ltd.
Google LLC (Fitbit)
Garmin Ltd.
Huawei Technologies Co., Ltd.
Xiaomi Corporation
Oura Health Oy
Meta Platforms, Inc.
Wearable Computing Market Key Developments:
August 2026: Garmin introduced fenix 9 and fenix 9 Pro, with the Pro models adding built-in satellite and LTE connectivity for voice, text, and SOS communication directly from the wrist.
July 2026: Samsung introduced Galaxy Watch9 and Galaxy Watch Ultra2, combining continuous health monitoring, AI-driven health intelligence, enhanced battery capacity, and personalized guidance through the Samsung Health ecosystem.
June 2026: Meta announced a partnership with EssilorLuxottica to introduce Meta Glasses, expanding AI-enabled smart eyewear with Meta AI available from launch and compatibility with prescription lenses.
May 2026: Google launched the Google Health app, transitioning the Fitbit app into a broader health platform that combines wearable-device data, Health Connect, Apple Health, and other health information, with Google Health Coach built using Gemini.
May 2026: Apple expanded wearable health functionality in India by making sleep-apnoea notifications available on Apple Watch and introducing a clinically validated Hearing Test through AirPods Pro, strengthening its health-focused wearable ecosystem.
May 2026: Oura introduced Oura Ring 5 with a smaller form factor, next-generation sensing, week-long battery life, and new software including Health Radar and Live Activity Tracking.
Wearable Computing Market Regulatory and Policy Environment:
Regulation is becoming increasingly important as wearable computing moves into healthcare, workplace monitoring, AI-assisted decision support, and connected personal services. General wellness products may face different requirements from products intended to diagnose, treat, monitor, or prevent disease. The regulatory classification therefore depends heavily on intended use, claims, risk, and jurisdiction.
In the United States, the FDA recognizes wearable devices within the broader digital-health category and maintains dedicated resources for sensor-based digital-health technologies. Its public database identifies authorized wearable devices including smartwatches, rings, patches, and bands that monitor health parameters. The agency also maintains a list of AI-enabled medical devices, demonstrating the increasing intersection of AI and regulated healthcare technology.
Data governance is another major consideration. Wearables can generate continuous streams of health and behavioral information, creating questions around ownership, consent, portability, security, interoperability, and secondary use. The European Commission's Joint Research Centre has examined how European data initiatives could influence the ability to share wearable-generated data for public-health research and innovation.
In the United Kingdom, the government's digital-health strategy is also creating opportunities for connected health technologies. The Department of Health and Social Care stated in 2025 that the NHS App would enable patients to connect wearable technology and access health applications as part of its broader digital-health strategy.
Manufacturers therefore need to consider privacy, cybersecurity, medical-device requirements, wireless connectivity requirements, AI governance, consumer protection, data interoperability, and product-specific safety requirements when expanding wearable computing applications.
Wearable Computing Market Outlook and Strategic Implications
The wearable computing market is moving toward a model in which computing is increasingly distributed across the body rather than concentrated in smartphones and personal computers. Smartwatches are expanding into health, safety, communications, AI, and independent connectivity, while smart rings provide discreet continuous sensing. Smart glasses are emerging as an interface for AI-assisted, hands-free computing, and smart clothing and e-textiles offer opportunities for embedding sensing capabilities directly into garments.
Health and wellness are expected to remain central to market development because wearable devices can generate frequent longitudinal data that can support personal monitoring and, where appropriately validated and regulated, healthcare applications. WHO's work on wearable technology demonstrates growing interest in standardized use of wearable-generated information for population health measurement.
AI is likely to become a major differentiator. As sensors generate increasingly large volumes of data, consumers are unlikely to benefit from raw measurements alone. Manufacturers are therefore developing systems that summarize data, identify patterns, provide contextual recommendations, and connect wearable information with broader digital ecosystems. Samsung's AI health strategy, Google's Google Health platform, Apple's health features, and Oura's Health Radar illustrate different approaches to this transition.
Connectivity will also remain important. Garmin's 2026 smartwatch developments demonstrate how wearables are becoming communication endpoints rather than merely smartphone accessories. Satellite, LTE, messaging, emergency communication, and independent application capabilities can increase the value of wearables in sports, outdoor activities, enterprise applications, and safety-critical environments.
For manufacturers, the strategic priority will be to balance functionality with comfort, battery life, privacy, cybersecurity, accuracy, and affordability. For healthcare organizations, validation, interoperability, data governance, and clinical usefulness will be more important than feature volume alone. For enterprises, integration with existing software, measurable productivity benefits, worker acceptance, and security will determine deployment success.
Regional strategies will also differ. North America benefits from established technology and digital-health ecosystems, Europe places strong emphasis on data governance and health-data interoperability, while Asia Pacific offers significant consumer, manufacturing, and electronics-production opportunities. India's government data illustrates the growing digital foundation supporting connected-device ecosystems, while MeitY's electronics-manufacturing figures highlight the country's expanding production capabilities.
Overall, the wearable computing market is expected to progress from device-centric innovation toward ecosystem-centric computing. Companies that combine reliable sensing, efficient hardware, AI-enabled interpretation, secure connectivity, strong software platforms, and compelling user experiences will be better positioned to capture emerging opportunities. The market's long-term development will depend on whether manufacturers can turn continuous data collection into useful, trusted, and actionable computing experiences while maintaining regulatory and privacy compliance.
Wearable Computing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 71.0 billion |
| Total Market Size in 2031 | USD 148.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 15.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Component, Application, End User, Geography |
| Companies |
|
Market Segmentation
By Type
By Component
By Application
By End User
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. WEARABLE COMPUTING MARKET BY TYPE
5.1. Introduction
5.2. Smartwatches
5.3. Fitness Trackers
5.4. Smart Glasses and Augmented Reality (AR) Devices
5.5. Virtual Reality (VR) Headsets
5.6. Smart Clothing and E-Textiles
5.7. Hearables
5.8. Others
6. WEARABLE COMPUTING MARKET BY COMPONENT
6.1. Introduction
6.2. Hardware
6.3. Sensors
6.4. Processors and Memory
6.5. Displays and User Interfaces
6.6. Connectivity Modules
6.7. Batteries and Power Systems
6.8. Software
6.9. Services
7. WEARABLE COMPUTING MARKET BY APPLICATION
7.1. Introduction
7.2. Health, Wellness, and Fitness
7.3. Entertainment and Gaming
7.4. Communication and Navigation
7.5. Industrial and Enterprise
7.6. Safety and Workforce Monitoring
7.7. Lifestyle and Personal Productivity
7.8. Others
8. WEARABLE COMPUTING MARKET BY END USER
8.1. Introduction
8.2. Consumers
8.3. Healthcare
8.4. Sports and Fitness
8.5. Military and Defense
8.6. Manufacturing and Logistics
8.7. Retail and Fashion
8.8. Enterprise
8.9. Others
9. WEARABLE COMPUTING MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. United Arab Emirates
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Product Launches, Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Apple Inc.
11.2. Samsung Electronics Co., Ltd.
11.3. Google LLC (Fitbit)
11.4. Garmin Ltd.
11.5. Huawei Technologies Co., Ltd.
11.6. Xiaomi Corporation
11.7. Oura Health Oy
11.8. Sony Group Corporation
11.9. Polar Electro Oy
11.10. Withings SA
11.11. Whoop, Inc.
11.12. Carré Technologies Inc. (Hexoskin)
11.13. Bose Corporation
11.14. Meta Platforms, Inc.
11.15. Snap Inc.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











