
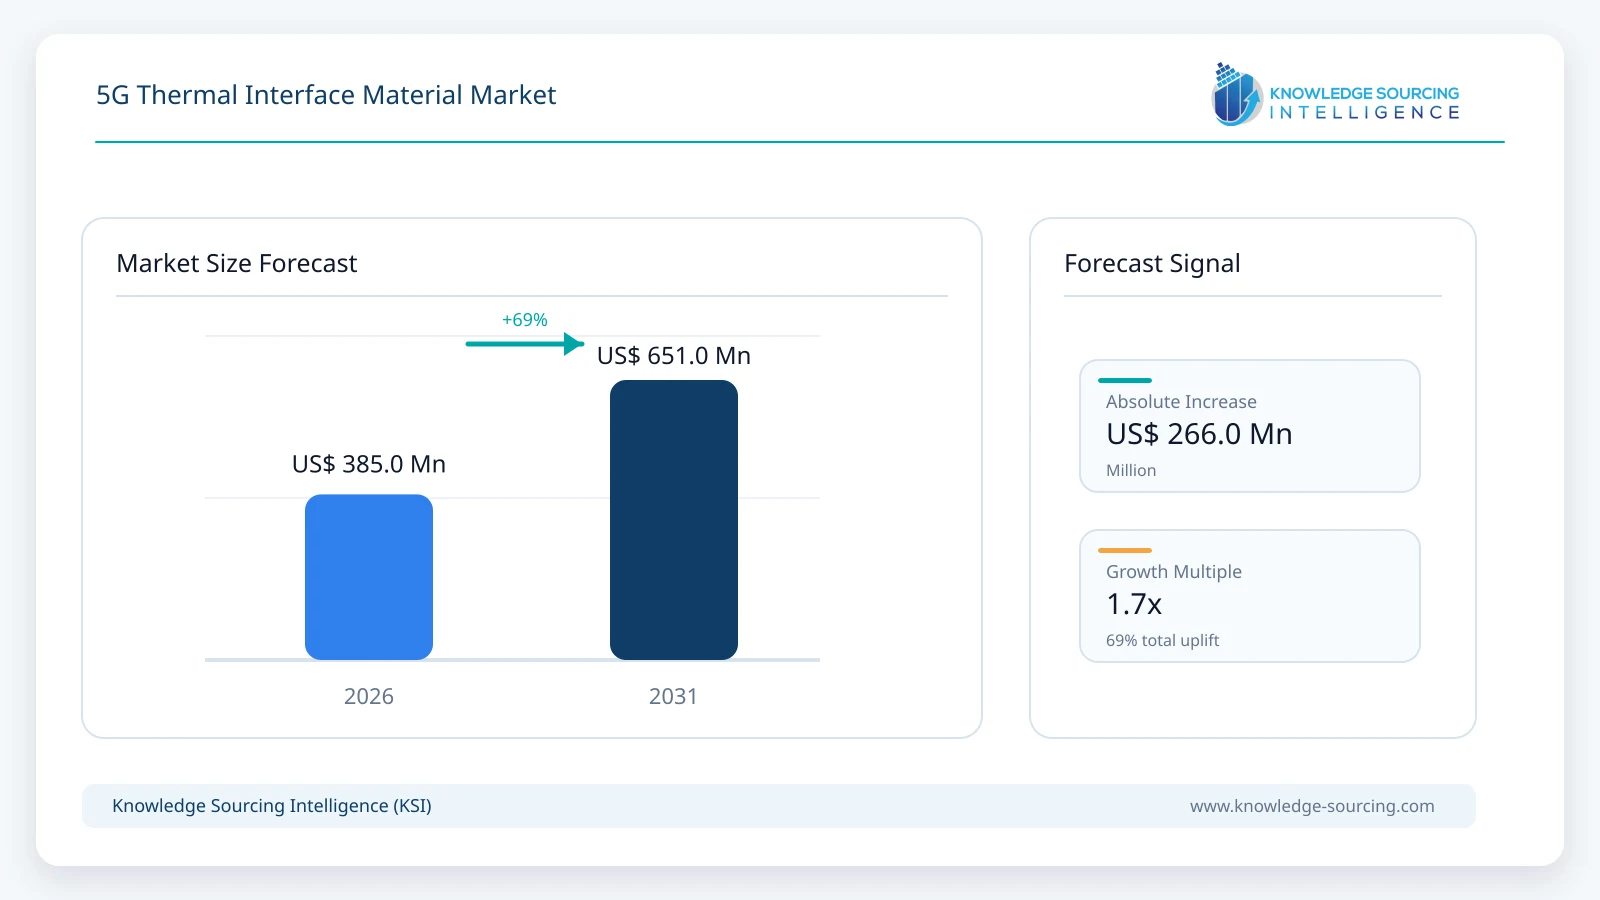
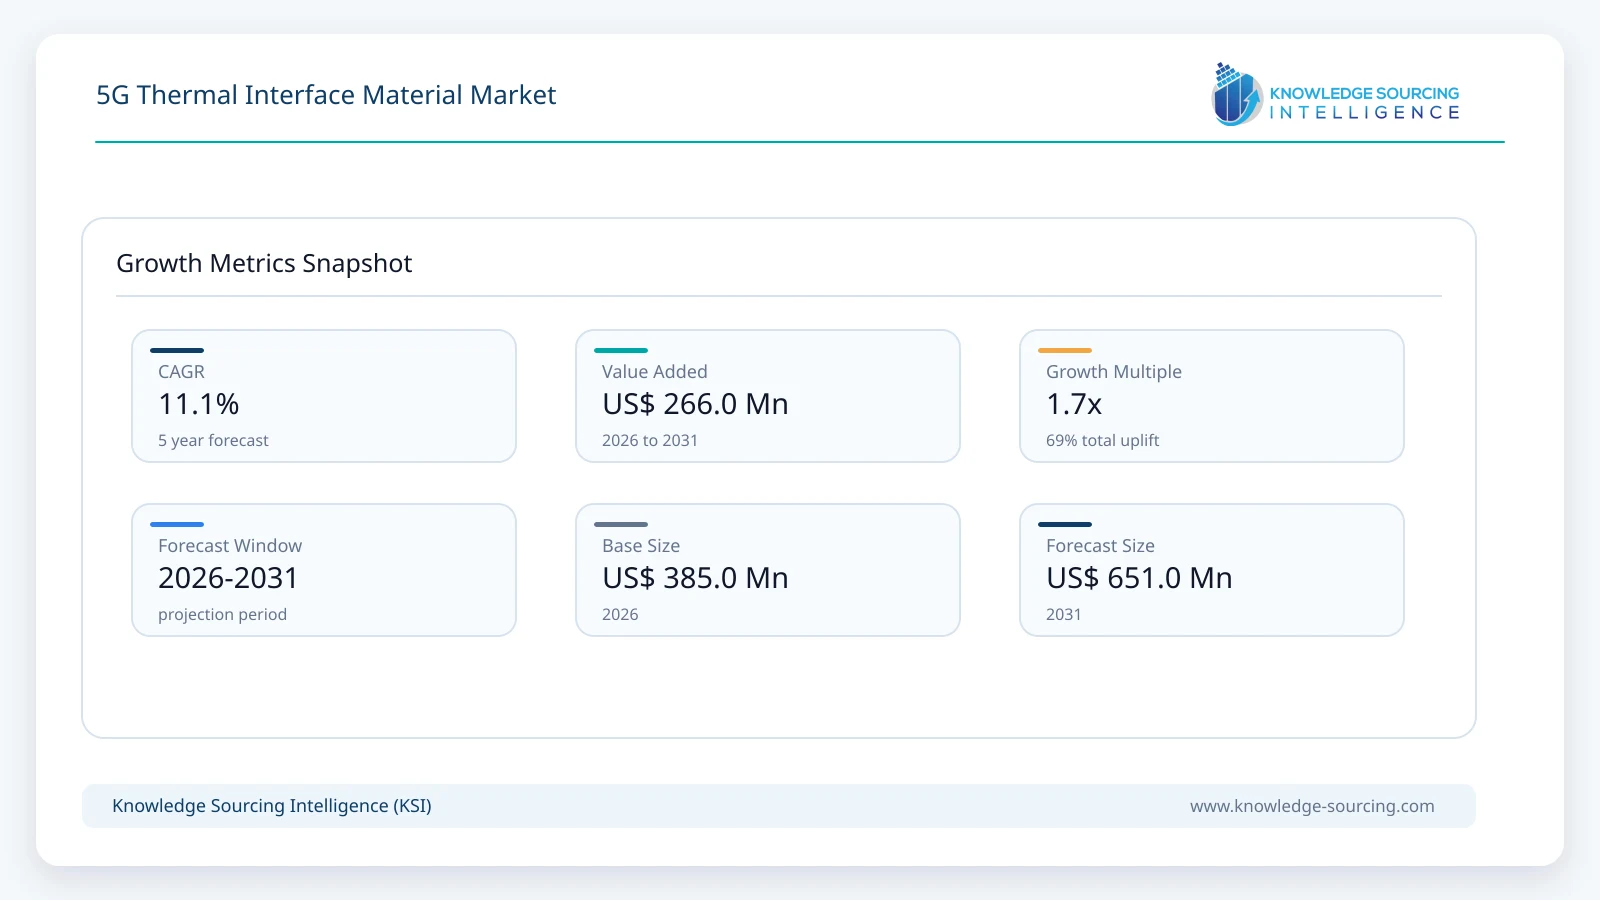
The 5G Thermal Interface Material Market is predicted to grow at a CAGR of 11.1% to increase from USD 385.0 million in 2026 to USD 651.0 million by 2031.
Highlights:
- 1Thermal gap pads account for approximately 34.0% of market revenue in 2026, supported by their established use in telecom electronics, consistent thickness and straightforward assembly.
- 2Thermal gels and dispensable gap fillers represent approximately 31.0% of the market in 2026 and are projected to become the largest material format by 2031 as automated dispensing expands.
- 35G RAN and base-station equipment accounts for approximately 42.0% of market revenue in 2026, reflecting the thermal requirements of AAUs, Massive MIMO radios, RRUs, small cells and associated processing equipment.
- 4Sub-6 GHz applications account for approximately 79.0% of market revenue in 2026, while mmWave applications grow considerably faster through 2031.
- 5Asia Pacific represents approximately 47.0% of global revenue in 2026, supported by its concentration of telecom-equipment, semiconductor, smartphone and electronics manufacturing.
- 6Parker Chomerics’ THERM-A-GAP GEL 120 provides 12 W/m-K thermal conductivity and is designed for telecommunications equipment and automated manufacturing environments.
- 7Henkel’s current 5G materials portfolio includes gap pads, thermal gels, phase-change materials and thermally conductive adhesives designed for base stations, RRUs and fixed-wireless equipment.
Growth is supported by increasing power density in 5G radio equipment, greater processing requirements in baseband and edge systems, continued adoption of Massive MIMO, higher-capacity optical connectivity, increasing use of mmWave equipment and integration of 5G connectivity into automotive and industrial electronics.
Thermal interface materials, or TIMs, are positioned between heat-generating electronic components and heat sinks, chassis surfaces or other cooling structures to reduce thermal resistance created by microscopic air gaps. The market includes thermal gap pads, dispensable gels and liquid gap fillers, thermal greases, phase-change materials, thermally conductive adhesives, films and other specialized interface materials used in 5G-enabled electronic equipment.
The market covers TIMs used in 5G RAN and base-station equipment, smartphones and FWA devices, network and optical-transport equipment, edge infrastructure, and 5G-enabled automotive and industrial electronics. General-purpose thermal materials used exclusively in data centers, EV batteries, conventional consumer electronics, and unrelated industrial applications are excluded from the market.
The technical requirement is becoming more demanding as 5G equipment combines greater processing capability with smaller and lighter equipment designs. Parker Chomerics identifies increasing electronics density as a central thermal challenge in 5G mmWave hardware and has documented base-station applications requiring robotically dispensable TIMs with thermal conductivity of at least 7 W/m-K. Momentive similarly identifies higher-powered processors and increased chipset density as drivers for specialized thermal solutions in RRUs, MIMO/AAU systems, BBUs, small cells and optical transceivers.
Thermal management is becoming a more important design constraint in 5G equipment because radio and processing performance are increasing faster than the physical volume available for cooling. Massive MIMO radios integrate numerous RF paths, power amplifiers, digital processors and antenna elements within outdoor enclosures, while baseband and edge systems process substantially larger data volumes than earlier network generations. High-speed optical interfaces add additional localized heat loads across the transport network.
TIMs do not actively cool an electronic system. Their function is to improve conduction between a heat-generating device and the component responsible for dissipating that heat. Even highly conductive heat sinks can perform poorly when microscopic air pockets exist at the interface because air has very low thermal conductivity. The material therefore fills surface irregularities and establishes a more effective thermal path.
Material selection depends on substantially more than headline thermal conductivity. Mechanical softness, bond-line thickness, compression force, vertical stability, pump-out resistance, oil bleed, environmental reliability and production method can all influence actual system performance. A softer, highly conformable material can deliver lower system-level thermal resistance than a nominally more conductive material that does not wet the interface effectively.
Henkel’s telecom portfolio illustrates this diversity. Its 5G solutions include thermal gels, gap pads, phase-change materials and conductive adhesives for base stations, remote-radio equipment, fixed wireless arrays and optical systems. The BERGQUIST LIQUI FORM TLF 6000HG thermal gel, for example, provides 6 W/m-K conductivity, accommodates gaps of up to 3 mm and is designed specifically for remote antennas and 5G base stations.
Parker Chomerics follows a similar approach through dispensable gels and conformable pads. Its 5G base-station work demonstrates the importance of combining thermal performance with low mechanical stress and high-volume robotic dispensing rather than optimizing one material property in isolation.
Market Drivers
Increasing heat density in 5G radios and Massive MIMO equipment
The largest demand driver is the continuing increase in thermal density within radio equipment. Modern 5G systems deploy wider spectrum channels, higher transmit capacity and significantly more antenna elements than earlier generations. Massive MIMO architectures place large numbers of RF chains and power-amplifier components inside equipment that must remain sufficiently light and compact for tower and rooftop installation.
Outdoor telecom equipment also operates without the same cooling environment available to conventional computing systems. Radio units can face wide temperature ranges, solar heating, humidity and continuous high-load operation. Maintaining component temperatures within acceptable limits becomes important to output power, reliability and equipment life.
Momentive specifically provides thermal gap fillers and greases for MIMO/AAU, RRU, BBU and small-cell applications and links the increasing requirement for thermal management to greater processor power and chipset density in modern wireless systems.
The RAN remains the largest TIM application through 2031, but expenditure increasingly shifts toward materials offering greater conductivity and improved manufacturability rather than simply increasing the physical quantity of material used.
Automated equipment manufacturing favors gels and liquid gap fillers
Manufacturing economics are changing the material mix. Traditional pads are cut into specific shapes and thicknesses and then placed between the component and cooling surface. They provide repeatable mechanical properties but can require multiple individual parts within a complex telecom assembly.
Dispensable gels and liquid gap fillers can be applied robotically to irregular surfaces and different gap dimensions. Henkel notes that liquid gap fillers conform to complex topographies and support high-volume automated production while producing low mechanical stress on electronic components.
Parker’s GEL 120 provides another example. The one-component material is fully cured, requires no secondary curing operation and can fill gaps ranging from below 0.5 mm to approximately 4 mm. The product is formulated for controlled robotic dispensing and high production repeatability.
Thermal gels and dispensable gap fillers are projected to increase from approximately USD 119 million in 2026 to USD 247 million in 2031, representing a CAGR of about 15.7%. Their share consequently rises enough for the category to overtake gap pads by the end of the forecast period.
mmWave equipment creates disproportionately demanding thermal conditions
Millimeter-wave equipment combines RF, antenna and processing components within particularly compact systems. Antenna elements need to remain physically close to RF front-end electronics, reducing the freedom available to designers to separate heat-generating components.
Parker identifies the combination of more electronic components and confined space as one of the central thermal issues affecting 5G mmWave systems. Thermal management also needs to be coordinated with EMI shielding because both functions occupy the same limited space within the equipment.
Sub-6 GHz equipment remains substantially larger in absolute demand because it dominates commercial macro-network deployment. However, TIM revenue associated with mmWave applications is projected to expand from approximately USD 81 million in 2026 to USD 202 million in 2031, representing growth of about 20.1% annually.
The higher growth rate reflects greater thermal intensity per unit as well as expansion of mmWave in fixed wireless, high-capacity venues, private networks and selected industrial applications.
Higher-speed optical equipment creates additional thermal requirements
5G traffic does not stop at the radio. Increasing RAN capacity raises throughput requirements across optical fronthaul, backhaul and aggregation systems. Higher-speed optical modules contain increasingly power-dense electronics within standardized physical packages, creating another thermal-management challenge.
Parker identifies optical transceivers as a major telecommunications TIM application, while Momentive includes optical-transceiver gap fillers within its wireless-network portfolio.
Dow’s DOWSIL TC-3120 illustrates the technical direction of this part of the market. The product provides approximately 12 W/m-K thermal conductivity and is designed for optical modules, dense electronics and high-speed data applications while reducing oil bleed and outgassing that can interfere with sensitive optical assemblies.
The network, edge and optical-transport application segment consequently grows faster than the overall TIM market through 2031.
Higher-performance materials increase value per application
Thermal-interface suppliers continue increasing conductivity while attempting to preserve softness, dispensing performance and long-term stability. Parker’s current portfolio includes 12 W/m-K dispensable gel, while Henkel supplies liquid, gel and pad formats optimized for different bond-line and manufacturing requirements.
High conductivity normally requires greater loading of thermally conductive fillers, which can increase material cost and make dispensing or conformability more difficult. Successful products therefore command value by balancing multiple requirements rather than maximizing conductivity alone.
This creates a market-value driver that is partly independent of equipment volumes. A newer radio platform can use a more valuable TIM formulation than the system it replaces even if the overall number of interfaces remains similar.
5G is broadening into automotive and industrial electronics
5G connectivity is increasingly used in vehicles, industrial gateways, robotics, private-network devices and edge systems. Thermal materials used in these environments need to remain reliable through vibration, temperature cycling, mechanical stress and extended operating lifetimes.
The automotive and industrial 5G application segment is projected to expand at approximately 15.2% annually through 2031, reaching around USD 117 million by the end of the forecast period. Its growth gradually reduces the dominance of conventional telecom infrastructure within the overall market.
Market Restraints and Challenges
Premium TIM formulations increase material cost
Higher thermal conductivity generally requires larger quantities of ceramic or other conductive fillers and more complex formulation control. Premium gels and gap fillers can therefore cost materially more than conventional thermal pads and greases.
Telecom OEMs do not need maximum conductivity at every interface. Equipment designers typically use different thermal materials depending on heat generation, mechanical tolerance and available cooling. This limits the addressable volume of premium TIMs even as their value share increases.
Suppliers need to demonstrate that higher-performance materials reduce junction temperature, improve equipment reliability or simplify manufacturing sufficiently to justify their cost.
Thermal conductivity alone can give an incomplete view of performance
TIM performance depends on thermal resistance across the complete interface rather than only bulk conductivity. Contact resistance, wet-out, pressure and bond-line thickness can materially affect heat transfer.
Liquid gap fillers can provide an advantage on irregular surfaces because they conform closely to component geometry. Henkel states that their conformability can improve surface wet-out and reduce thermal resistance while limiting mechanical stress.
Qualification therefore requires application-level thermal testing rather than selecting a material solely from its W/m-K specification.
Oil bleed, outgassing and contamination matter in sensitive systems
Silicone-based materials provide strong thermal stability and mechanical flexibility, but sensitive optical and electronic systems can impose tighter requirements for volatile compounds and fluid migration.
This is increasing demand for low-bleed, low-outgassing and non-silicone TIM formulations. Dow’s TC-3120 specifically targets optical-grade cleanliness alongside high thermal conductivity, illustrating how contamination performance is becoming a competitive specification in advanced optical assemblies.
More efficient electronics can moderate TIM volume growth
Semiconductor suppliers and telecom equipment manufacturers are simultaneously improving radio efficiency, processor efficiency, enclosure design and cooling structures. Better equipment architecture can reduce the amount of heat generated for a given unit of network capacity.
More integrated devices can also reduce the number of separate material interfaces. Market revenue therefore cannot be projected directly from 5G traffic or installed-site growth.
TIM growth increasingly reflects a combination of greater equipment complexity, higher value per material interface and expansion into new 5G-enabled device classes.
Major Segment Analysis
By Material Format
Thermal gap pads account for approximately 34.0% of market revenue in 2026, making them the largest material format at the beginning of the forecast period. Their strengths include predictable thickness, electrical insulation, mechanical conformability and straightforward installation.
Pad revenue is projected to reach approximately USD 189 million by 2031, equivalent to growth of about 7.6% annually. The category continues growing but loses relative share as equipment manufacturers increase automated dispensing.
Thermal gels and liquid gap fillers expand considerably faster and reach approximately USD 247 million by 2031. These products are particularly well suited to automated manufacturing, complex component topographies and interfaces with varying gap thicknesses.
Thermal greases and phase-change materials reach approximately USD 117 million by 2031, with applications concentrated around thin bond lines and high-performance processors.
Thermally conductive adhesives and films expand at approximately 13.2% annually as equipment designers combine thermal transfer with mechanical attachment and specialized assembly requirements.
By Application
5G RAN and base-station equipment accounts for approximately 42.0% of market revenue in 2026. AAUs, RRUs, baseband equipment, small cells and associated power electronics contain several heat-generating assemblies requiring reliable transfer into chassis and cooling structures.
The segment is projected to reach approximately USD 254 million by 2031 and remains the largest application despite growing more slowly than several downstream device categories.
Smartphones, FWA devices and other 5G terminals reach approximately USD 150 million by 2031, supported by increasing device processing requirements and compact mechanical designs.
Network, edge and optical-transport equipment expands at approximately 12.2% annually, reaching roughly USD 130 million in 2031. Higher-speed optical modules and denser networking equipment support the segment.
Automotive and industrial 5G electronics record the fastest growth among the major application groups as cellular connectivity becomes embedded in vehicles, industrial equipment and private-network endpoints.
By Frequency Band
Sub-6 GHz accounts for approximately 79.0% of market revenue in 2026 because most commercial 5G infrastructure and devices continue to operate primarily across low- and mid-band spectrum.
Sub-6 GHz TIM revenue reaches approximately USD 449 million by 2031, but its market share declines as mmWave equipment expands.
mmWave grows from approximately USD 81 million to USD 202 million, increasing its contribution from around 21% to 31%. More compact antenna architectures and higher localized thermal density support the higher TIM intensity of these systems.
Regional Analysis
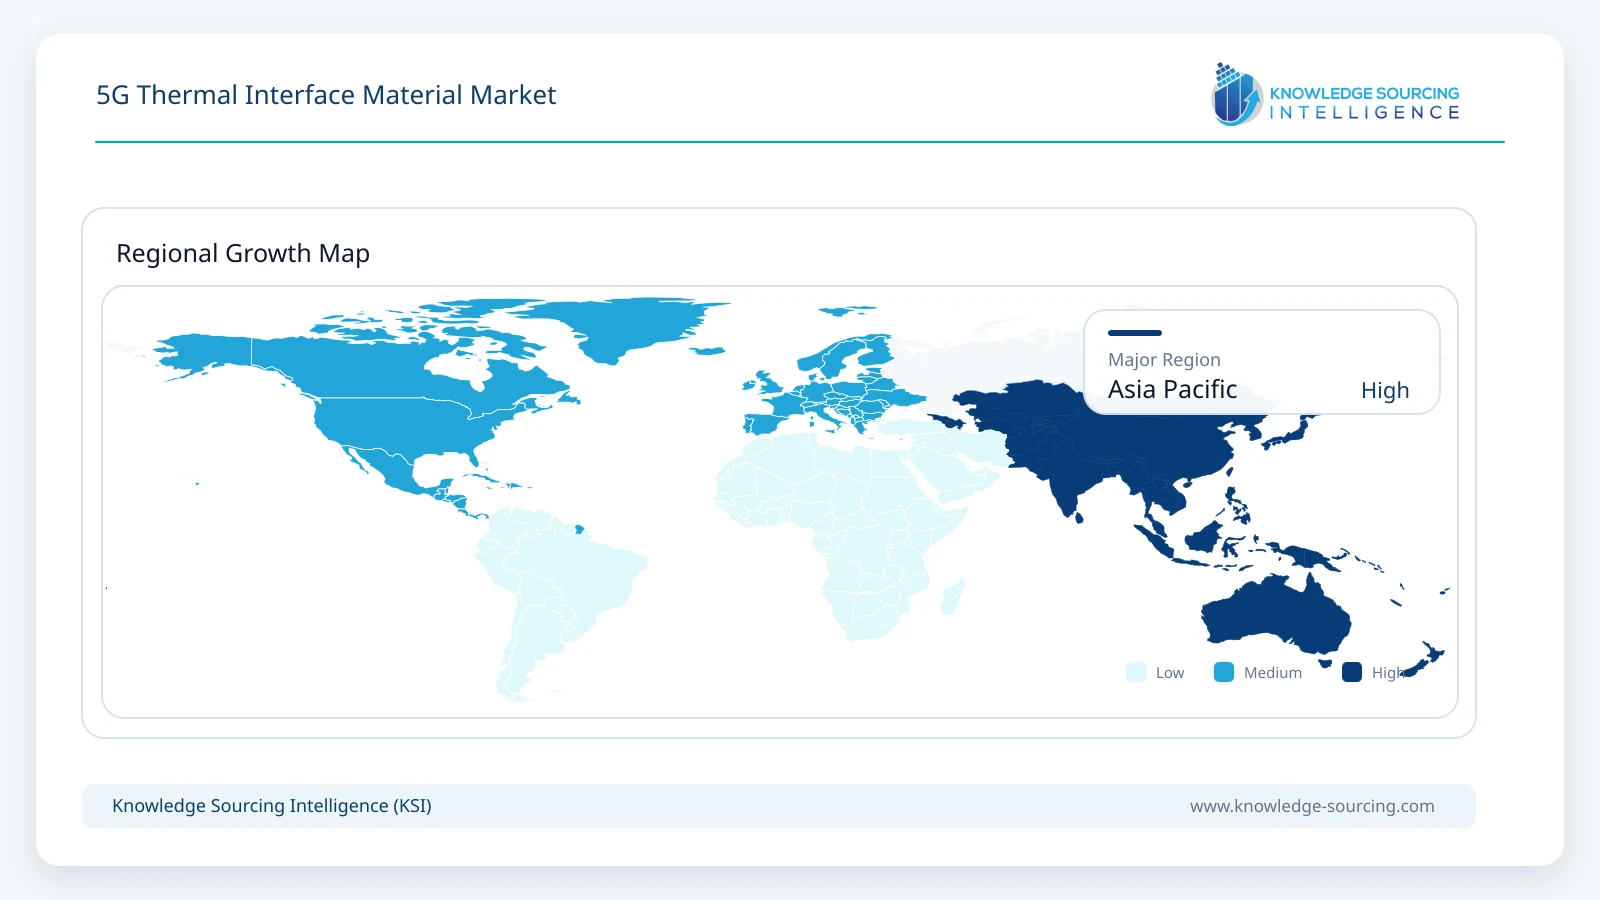
Asia Pacific accounts for approximately 47.0% of global market revenue in 2026. China, Japan, South Korea, Taiwan and other regional economies contain major telecom-equipment, semiconductor, smartphone, automotive-electronics and materials manufacturing ecosystems.
Asia Pacific revenue is projected to reach approximately USD 312 million by 2031, representing growth of about 11.5% annually.
India is becoming increasingly relevant as electronics and telecom-equipment manufacturing expands. Henkel opened an advanced Customer Application Center in Bengaluru in March 2026 with laboratory capabilities for thermal-management testing and precision dispensing. Telecom and 5G infrastructure is one of the facility’s five explicitly identified target sectors.
North America represents approximately one-quarter of the market in 2026 and remains important through advanced telecom infrastructure, semiconductor development, optical networking and a substantial domestic thermal-material supplier base.
Europe maintains a significant share through telecom, automotive and industrial electronics, while Middle East and Africa record the fastest regional percentage growth as operators continue deploying high-capacity 5G infrastructure in challenging outdoor thermal environments.
Technology Outlook
High-Conductivity Dispensable TIMs
Dispensable gels increasingly combine high conductivity with low compression force and automated processing. Parker’s GEL 120 provides 12 W/m-K conductivity while requiring no secondary cure and supporting robotic dispensing.
The format allows manufacturers to handle complex surface tolerances without stocking numerous pad shapes and thicknesses, making dispensing economics increasingly important in high-volume telecom manufacturing.
Low-Volatility and Contamination-Controlled Materials
Advanced optical and electronic systems increasingly require TIMs with lower oil migration and outgassing. Suppliers are therefore developing formulations that combine thermal conductivity with greater chemical cleanliness and long-term stability.
The requirement is particularly important around optical transceivers and densely packaged electronic assemblies where contamination can affect optical or electrical performance.
Application-Level Thermal Co-Development
TIM suppliers are increasingly working with customers during equipment development rather than selling materials only after the thermal architecture has been finalized.
Henkel’s Bengaluru application center includes advanced thermal-management testing and precision dispensing equipment that allows electronics manufacturers to qualify materials and production processes before scaling them commercially.
This favors suppliers with application-engineering and testing capability because system-level thermal resistance, manufacturing yield and long-term reliability can matter as much as the standalone material specification.
Recent Developments
August 2026: Henkel launched LOCTITE ABLESTIK CDF900 conductive die attach films, exceeding 8 W/m-K thermal conductivity, for AI, 5G, emerging 6G, and HPC applications at SEMICON Taiwan 2026.
May 2026: Dow launched DOWSIL TC-3120 Thermal Gel, delivering approximately 12 W/m-K conductivity for optical modules, dense electronics and high-speed data applications, including telecommunications and automotive electronic controllers.
March 2026: Qnity launched Laird Tflex SF16, a non-silicone thermal gap filler delivering 16 W/m-K conductivity with low hardness, targeting high-performance electronics, data centers, automotive and networking applications.
March 2026: Henkel opened an advanced Customer Application Center in Bengaluru, India, providing approximately 2,400 square feet of dedicated laboratory and testing space within a 5,000-square-foot facility. The center supports thermal-management testing, precision dispensing, electrical characterization and materials validation, with telecom and 5G infrastructure identified as one of its five principal target sectors.
Competitive Landscape
Henkel participates through its BERGQUIST thermal-management portfolio, including gap pads, liquid gap fillers, thermal gels, phase-change materials and thermally conductive adhesives. Its broadband-connectivity portfolio directly addresses 5G base stations, remote-radio equipment and fixed wireless systems, with material selection spanning interfaces ranging from low-stress pads to automated liquid dispensing.
Parker Hannifin’s Chomerics division provides thermal gap pads, dispensable gels and complementary EMI-management materials for telecommunications equipment. Its current portfolio includes the 12 W/m-K THERM-A-GAP GEL 120, while its 5G application work covers base stations, mmWave equipment and optical transceivers.
Qnity Electronics’ Laird thermal and EMI materials portfolio serves 5G telecommunications alongside high-performance computing, automotive and IoT electronics. Its major TIM product families include Tputty liquid gap fillers, Tflex gap pads and CoolZorb multifunctional thermal and EMI materials.
Shin-Etsu Chemical supplies high-thermal-conductivity silicone materials and other electronics materials used across information and communications applications. Its wider electronics-materials portfolio includes high-thermal-conductivity silicone resins and related materials for increasingly thermally demanding semiconductor and communication systems.
Momentive competes through SILCOOL and related thermal-management materials. Its wireless-communications portfolio specifically addresses RRUs, MIMO/AAUs, BBUs, small cells and optical transceivers through gap fillers, thermal greases and related materials.
Fujipoly participates through the SARCON thermal-management portfolio, including thermally conductive gap-filler materials designed for telecommunications and high-performance electronic equipment. Boyd combines thermal interface materials with broader thermal-engineering and component-conversion capabilities, allowing it to participate in applications requiring custom thermal assemblies rather than only standardized TIM products.
Dow supplies silicone-based thermal materials for dense electronics and optical systems. Its 2026 TC-3120 thermal gel reaches approximately 12 W/m-K while emphasizing low oil bleed and low outgassing for optical modules and high-speed electronic assemblies.
GLPOLY, Wacker Chemie, Denka and other specialized thermal-material manufacturers provide additional competition across gap fillers, pads, silicone formulations and thermally conductive compounds.
Competition increasingly centers on system-level thermal resistance, conductivity, softness, reliability, contamination control, automated dispensing and application-engineering support rather than headline conductivity alone.
Analyst View
5G TIM demand increasingly depends on thermal density rather than simply the number of 5G devices or base stations deployed. Modern radios and processors place greater compute and RF capability into smaller physical packages, allowing the thermal-management value per unit of equipment to increase even as the first nationwide 5G deployment wave matures.
RAN equipment remains the largest application because Massive MIMO radios, AAUs and outdoor base-station electronics present a demanding combination of high heat generation and constrained active cooling. Incremental growth, however, is becoming more diversified as optical networking, FWA equipment, automotive electronics and private-network devices contribute a larger proportion of demand.
The material mix is also changing. Gap pads remain important because of their simplicity and predictable mechanical properties, but the strongest incremental opportunity lies in dispensable gels and liquid gap fillers. Their ability to accommodate multiple gap geometries and integrate into automated assembly provides a manufacturing benefit alongside thermal performance.
mmWave applications create another high-value opportunity. Their overall equipment base remains smaller than Sub-6 GHz, but dense antenna and RF architectures increase the difficulty of transferring heat within limited mechanical space. The resulting TIM intensity supports substantially faster growth than the broader Sub-6 GHz category.
The competitive advantage is therefore shifting toward suppliers that can solve the entire interface problem rather than offer the highest conductivity figure. Material reliability, low mechanical stress, contamination control, robotic dispensing and application-level thermal engineering increasingly determine whether a product can move from laboratory qualification into large-scale 5G equipment manufacturing.
5G Thermal Interface Material Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 385.0 million |
| Total Market Size in 2031 | USD 651.0 million |
| Forecast Unit | Million |
| Growth Rate | 11.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Material Format, Application, Frequency Band, Geography |
| Companies |
|
Market Segmentation
By Material Format
Thermal Gap Pads
Thermal Gels & Dispensable Gap Fillers
Thermal Greases & Phase-Change Materials
Thermally Conductive Adhesives & Films
Others
By Application
5G RAN & Base Station Equipment
Smartphones, FWA & CPE
Network, Edge & Optical Transport Equipment
Automotive & Industrial 5G Electronics
By Frequency Band
Sub-6 GHz
mmWave
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. 5G Equipment Thermal Density
3.5. TIM Performance and Thermal Resistance
3.6. Manufacturing Automation and Dispensing Economics
3.7. Materials Reliability and Thermal Cycling
3.8. Supply Chain and Raw-Material Considerations
3.9. Porter’s Five Forces Analysis
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. High-Conductivity Dispensable TIMs
4.2. Low-Volatility and Contamination-Controlled Materials
4.3. Application-Level Thermal Co-Development
5. 5G THERMAL INTERFACE MATERIAL MARKET BY MATERIAL FORMAT
5.1. Introduction
5.2. Thermal Gap Pads
5.3. Thermal Gels & Dispensable Gap Fillers
5.4. Thermal Greases & Phase-Change Materials
5.5. Thermally Conductive Adhesives & Films
5.6. Others
6. 5G THERMAL INTERFACE MATERIAL MARKET BY APPLICATION
6.1. Introduction
6.2. 5G RAN & Base Station Equipment
6.3. Smartphones, FWA & CPE
6.4. Network, Edge & Optical Transport Equipment
6.5. Automotive & Industrial 5G Electronics
7. 5G THERMAL INTERFACE MATERIAL MARKET BY FREQUENCY BAND
7.1. Introduction
7.2. Sub-6 GHz
7.3. mmWave
8. 5G THERMAL INTERFACE MATERIAL MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. United Kingdom
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. Japan
8.5.3. South Korea
8.5.4. India
8.5.5. Taiwan
8.5.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Competitive Positioning
9.2. Thermal Conductivity and Resistance Benchmarking
9.3. Gap Pad & Dispensable Material Portfolios
9.4. Low-Volatility and Contamination-Control Capability
9.5. Automated Dispensing Compatibility
9.6. Telecom & 5G Application Capability
9.7. Strategic Developments
9.8. Competitive Dashboard
10. COMPANY PROFILES
10.1. Henkel AG & Co. KGaA
10.2. Parker Hannifin Corporation
10.3. Qnity Electronics
10.4. Shin-Etsu Chemical Co., Ltd.
10.5. Momentive Performance Materials Inc.
10.6. Fujipoly (Fuji Polymer Industries Co., Ltd.)
10.7. Boyd Corporation
10.8. Dow Inc.
10.9. GLPOLY
10.10. Wacker Chemie AG
10.11. Denka Company Limited
11. ANALYST VIEW
12. APPENDIX
12.1. Research Methodology
12.2. Market Estimation and Assumptions
12.3. Scope and Double-Counting Controls
12.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











