
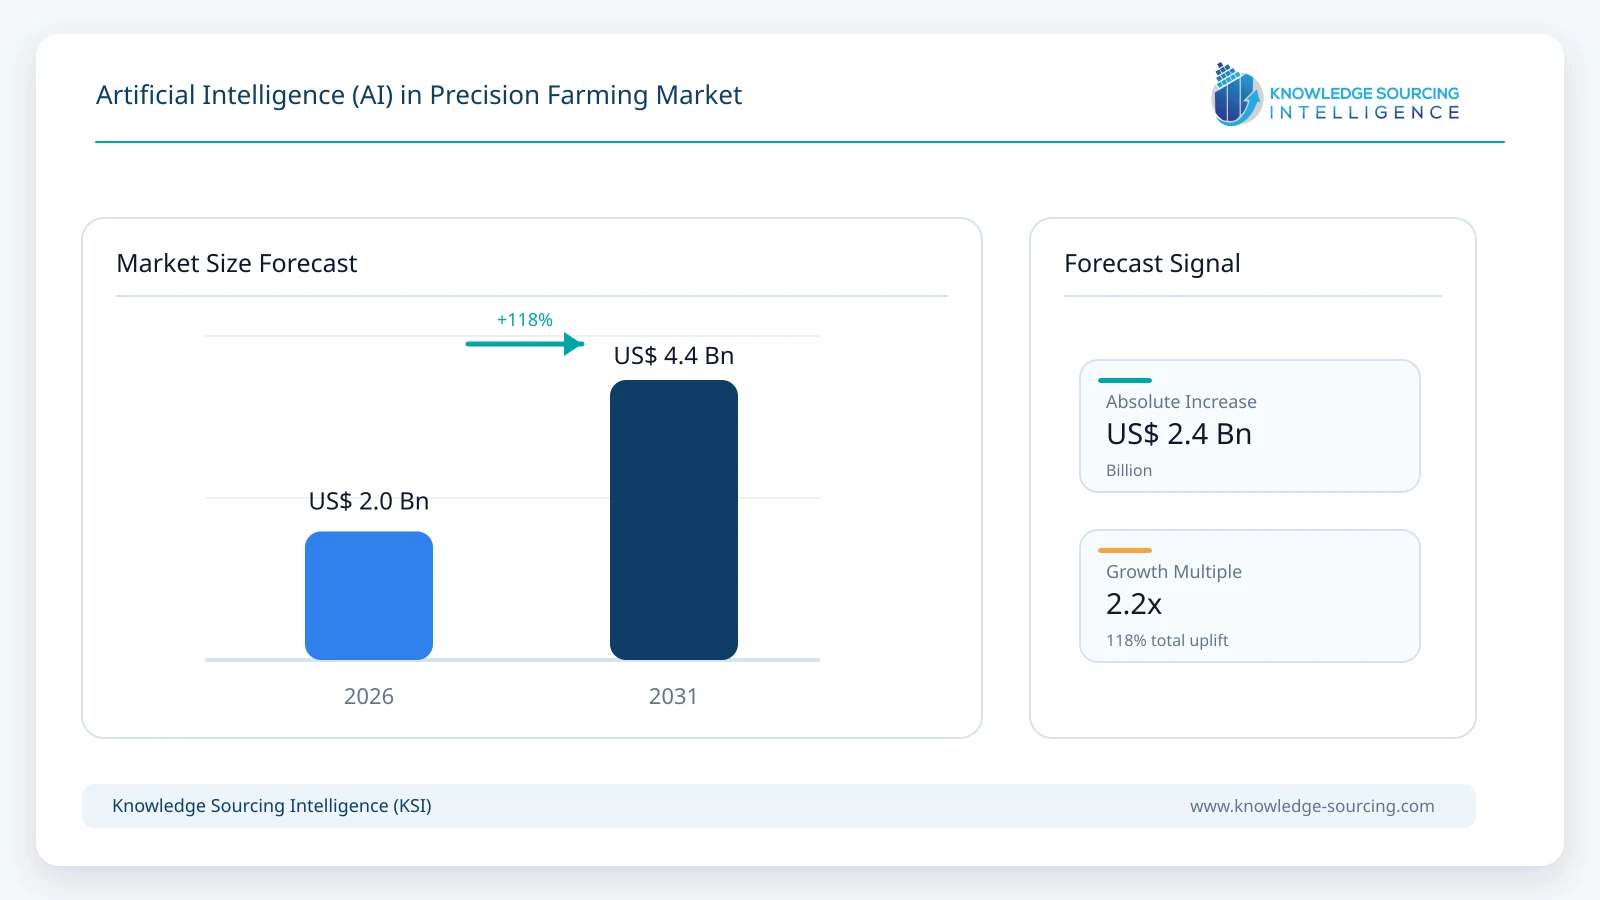
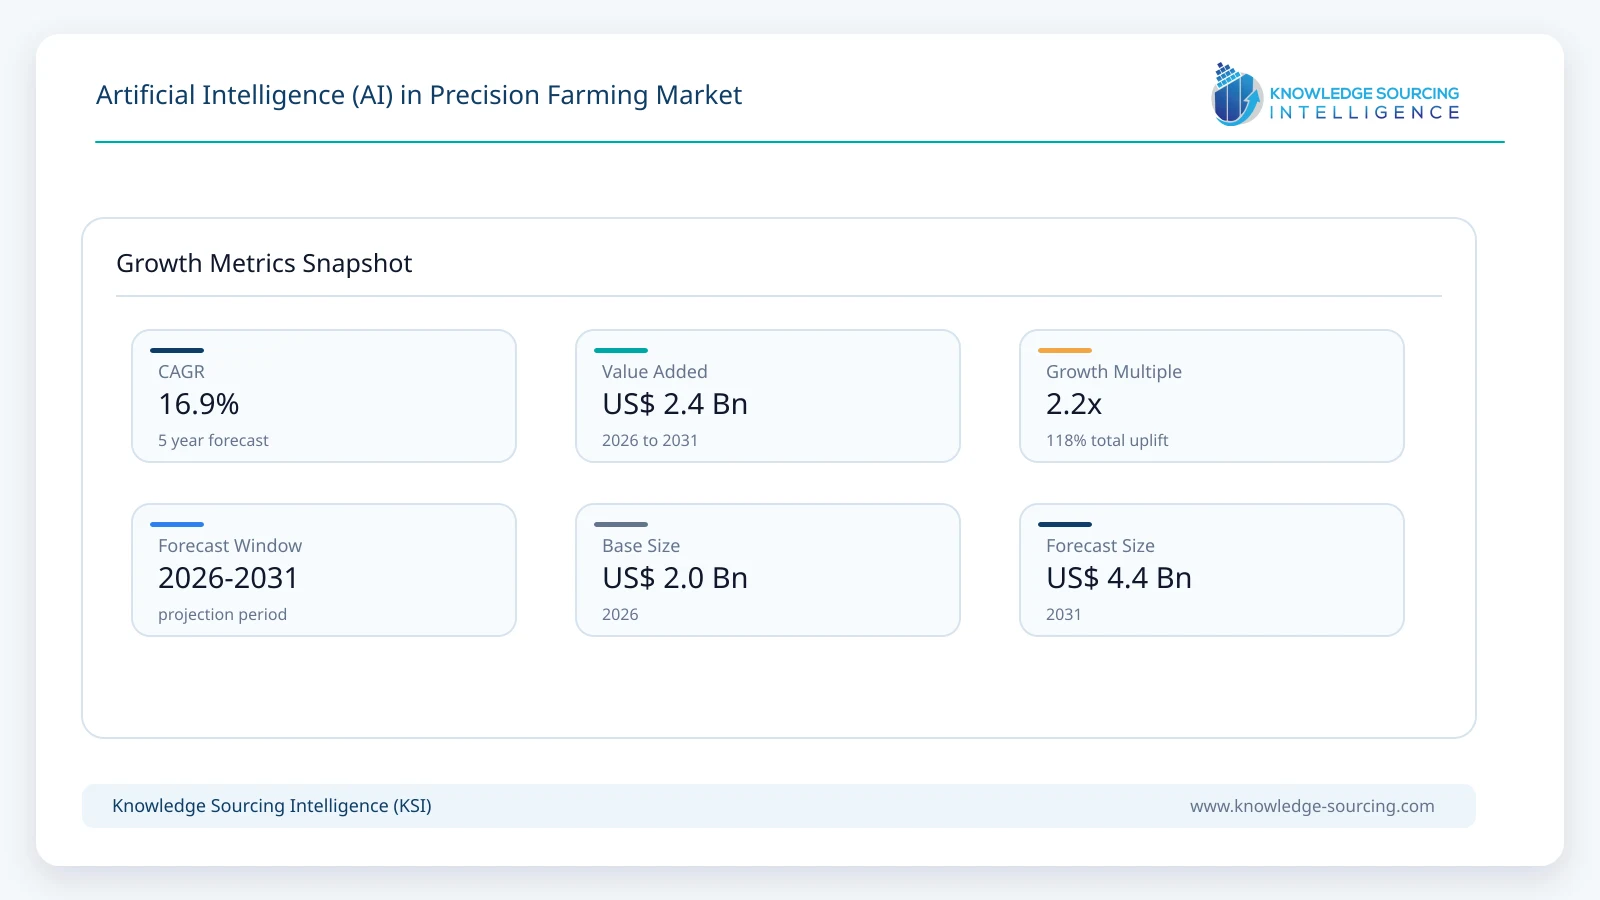
The Artificial Intelligence (AI) in Precision Farming Market is forecast to grow at a CAGR of 16.85%, reaching USD 4.40 billion in 2031 from USD 2.02 billion in 2026.
Highlights:
- 1Machine learning accounts for approximately 37% of the market in 2026reflecting its broad use across yield modeling, agronomic recommendations, crop classification and farm-management platforms.
- 2Computer vision is projected to grow at approximately 19.3% CAGR through 2031supported by targeted spraying, crop scouting and plant-level monitoring.
- 3Software represents approximately 43% of market value in 2026and gains share as AI shifts from isolated equipment features toward recurring analytics and decision-support platforms.
- 4AI-powered robotics is projected to expand at approximately 21.2% CAGRsupported by autonomous tractors, robotic weeding and automated field operations.
- 5Disease and pest detection is projected to grow at approximately 18.9% CAGRas higher-resolution imagery and machine-learning models move scouting toward plant-level detection.
- 6North America represents approximately 39% of the market in 2026while Asia Pacific grows faster as public digital-agriculture infrastructure and farm technology adoption expand.
Artificial intelligence is moving from a decision-support layer around precision agriculture toward direct participation in field operations, with computer vision, machine learning and autonomous systems increasingly determining where machinery moves, which plants receive inputs and how field-level data is converted into agronomic action.
Commercial deployment is becoming more visible across major agricultural equipment and digital-farming platforms. John Deere’s See & Spray systems use cameras and machine learning to distinguish crops from weeds and trigger targeted application, while its second-generation autonomy architecture combines computer vision, AI and 360-degree camera coverage for autonomous agricultural machinery. AGCO is similarly developing AI-based crop recognition, autonomous retrofits and mixed-fleet data platforms through its PTx business.
The market is therefore broadening beyond standalone analytics. AI is increasingly embedded into sprayers, tractors, drones, soil and crop-monitoring systems, irrigation tools and farm-management platforms. At the same time, generative AI is beginning to change how farmers and agronomists interact with agricultural data. John Deere introduced its JD AI assistant in September 2026 to allow growers to interrogate years of field, machine, and operational data using natural-language questions, while Taranis’ Ag Assistant converts leaf-level crop intelligence and agronomic datasets into field-specific recommendations.
The commercial opportunity is consequently shifting from collecting more agricultural data toward turning field data into automated decisions and physical actions. This favors technologies that can combine machine perception, agronomic models, historical records and real-time environmental information while operating reliably under variable field conditions.
Market Growth Drivers and Trends
Computer Vision Is Moving from Observation to Direct Field Action
Computer vision is becoming one of the most commercially important forms of agricultural AI because it enables machines to make decisions at plant or sub-field level. John Deere’s See & Spray platform uses camera vision and machine learning to distinguish crops from weeds and actuate individual nozzles, while the newer Gen 2 system can detect biomass variation and vary application rates without requiring a conventional prescription map. Starting with 2027 machines, Deere also plans to generate weed-pressure maps and stand counts from images collected during normal passes.
The commercial implication goes beyond better crop imagery. Vision systems are increasingly converting observation directly into treatment, reducing the gap between detecting a problem and acting on it. This supports faster growth for computer vision than the broader AI precision-farming market through 2031.
Autonomous Field Operations Are Moving Toward Commercial Deployment
Autonomy is progressing from controlled demonstrations toward agricultural systems that can be integrated into actual machinery fleets. Deere’s second-generation autonomy kit uses multiple cameras, high-speed processing and AI to navigate field environments, while retrofit pathways allow existing equipment to adopt autonomous capabilities without complete machine replacement.
AGCO’s PTx business is pursuing a similar retrofit approach. Its OutRun platform converts conventional tractors into autonomous machines, and AGCO reported successful autonomous tillage and fertilizer testing in 2025 with broader commercial deployment planned. This retrofit model is important because it expands the potential market beyond purchases of new autonomous machinery and allows AI capability to enter mixed-brand fleets over the forecast period.
Farm Data Platforms Are Becoming the Operating Layer for Agricultural AI
AI performance depends on reliable field, machinery and agronomic data. This is increasing the importance of integrated platforms capable of combining multiple data sources rather than running isolated algorithms. Bayer’s FieldView platform manages more than 220 million acres in over 20 countries and uses machine learning for field zoning and variable-rate seed prescriptions, providing an installed digital base through which new AI capabilities can be deployed.
AGCO launched PTx FarmENGAGE in 2025 as a mixed-fleet cloud platform integrating machine connectivity, agronomic information and task management, while Deere’s Operations Center provides the foundation for its JD AI assistant. These developments support KSI’s expectation that software gains market share as AI becomes a persistent farm-management layer rather than an occasional analytical service.
Plant-Level Intelligence Is Strengthening Pest and Disease Detection
AI-enabled crop monitoring is moving from field averages toward individual plant and leaf-level intelligence. Taranis combines high-resolution aerial imagery with AI models to identify weeds, diseases, insects and nutrient issues and has extended its platform toward economic yield-impact estimation. Its partnership with Syngenta is expanding these tools through agricultural retailers in the U.S. Midwest, linking detected crop threats to agronomic action and crop-protection decisions.
The value proposition is particularly strong where agronomists must monitor large acreages during narrow intervention windows. Automated image analysis allows human experts to focus attention on high-risk fields rather than performing uniform manual scouting, supporting the continued expansion of disease and pest detection through 2031.
Government Digital-Agriculture Infrastructure Is Expanding the Addressable Market
Public-sector digital infrastructure is creating conditions for AI adoption beyond large farms in North America and Western Europe. India’s Digital Agriculture Mission is developing AgriStack, crop registries, georeferenced maps and the Krishi Decision Support System, while government AI initiatives already cover pest surveillance, crop identification, farmer advisories and weather-related decisions. As of late 2025, India’s digital crop survey had covered more than 23.5 crore plots, giving future AI systems a much larger structured data foundation.
The National Pest Surveillance System is already using AI and machine learning across multiple crops and pest types, and India’s 2026 Bharat-VISTAAR initiative is intended to combine agricultural datasets with multilingual AI-based farmer advisories. These developments support faster Asia-Pacific growth because AI adoption is increasingly being supported by public digital infrastructure rather than depending solely on farm-level technology investment.
Market Restraints
Fragmented Farm Data Reduces Model Portability
AI systems depend on consistent data, yet farm information remains fragmented across machinery brands, agronomic platforms, sensors, satellite providers and farm-management systems. The European Commission identifies fragmented data access and interoperability as major obstacles to wider agricultural AI adoption and is supporting shared agricultural data initiatives to reduce formatting and integration costs.
This creates a structural challenge for AI providers because a model trained on one combination of crops, sensors and field conditions may not transfer cleanly to another. Companies therefore need substantial integration, calibration and local training capabilities before a solution can scale across regions and equipment ecosystems.
AI Performance Is Highly Dependent on Local Agronomic Conditions
Agriculture is unusually difficult for generalized AI because biological and environmental conditions change continuously. Soil type, plant variety, weed species, weather, crop stage, lighting and farming practices can materially affect model performance. Deere’s continual expansion of See & Spray into additional crops illustrates the need to develop and validate crop-specific machine-vision models rather than assuming one algorithm can identify all weeds in all conditions.
The same limitation applies to yield prediction and disease detection. AI providers need large, continuously refreshed training datasets from different regions and seasons, making agricultural model development more expensive than software markets where operating conditions are comparatively standardized.
Smallholder Economics Limit Hardware-Intensive Adoption
The economics of autonomous machinery, advanced camera systems and connected sensors remain challenging for smaller farms. While software can reduce the entry barrier, many AI applications still require precision equipment, connectivity, compatible machinery or data-collection infrastructure. India’s technology roadmap explicitly identifies affordability and the gap between digital innovation and physical farm infrastructure as constraints on scaling frontier technologies among smaller producers.
This creates a two-speed market. Large farms can justify AI through labor, chemical and machinery savings, while smallholders often require shared services, government infrastructure or lower-cost mobile solutions to achieve similar economics.
Rural Connectivity and Edge-Processing Requirements Increase System Complexity
Precision-farming AI frequently operates in environments where continuous cloud connectivity cannot be assumed. Deere explicitly uses edge computing in its Sense & Act architecture so machines can process images and make field decisions locally rather than relying entirely on remote computing.
This improves reliability but raises hardware requirements. Agricultural AI systems may need rugged processors, storage and machine-level inference capabilities in addition to cloud analytics, increasing development costs and creating more complex hardware-software integration requirements.
Farmer Data Control and Trust Affect Platform Adoption
Farm data contains commercially sensitive information about yields, production practices, machinery utilization and field performance. As AI systems become more capable of drawing conclusions from this information, farmers increasingly expect clarity on ownership and permitted use. Deere’s 2026 Farmer Data Commitment explicitly states that farmers control their farm data and can decide which third parties receive access, showing that data governance has become a competitive issue as well as a regulatory one.
Providers that cannot demonstrate transparent data practices may face adoption resistance even when the underlying AI performs well. Trust, portability and customer control therefore become important conditions for scaling software-led precision agriculture.
Market by Technology
Machine Learning
Machine learning remains the largest technology category, accounting for approximately 37% of the market in 2026. Its breadth explains its leadership: machine-learning models are used for crop classification, yield forecasting, variable-rate prescriptions, anomaly detection and agronomic recommendations across multiple farm-management platforms. Bayer, BASF, Deere, CropX and Taranis all use machine-learning techniques within commercial agricultural systems, giving the technology a broad installed base.
Its share moderates through 2031 as computer vision and robotics expand more rapidly, but machine learning continues to provide the analytical foundation beneath many specialized AI applications.
Computer Vision
Computer vision is projected to grow at approximately 19.3% CAGR through 2031. The technology is becoming increasingly important in targeted spraying, crop scouting, stand counting, weed identification and crop-stress detection because high-resolution cameras can convert physical field conditions into machine-readable data.
Deere’s See & Spray and CropX Vision illustrate two different deployment models. One places machine vision directly on agricultural machinery to control application, while the other uses smartphone imagery and AI to estimate vineyard water stress. Together they indicate that computer vision is becoming useful across both capital-intensive machinery and relatively accessible mobile tools by the end of the forecast period.
Predictive Analytics
Predictive analytics represents approximately 20% of market value in 2026. These systems combine weather, crop, soil and historical information to forecast yield, disease risk, irrigation requirements and other agronomic outcomes. The segment remains important because precision agriculture increasingly focuses on acting before a problem becomes visible rather than responding after damage occurs.
Generative and conversational interfaces are likely to make predictive outputs more accessible, but the underlying commercial value continues to depend on model accuracy and the quality of data available for each field.
AI-Powered Robotics
AI-powered robotics is projected to expand at approximately 21.2% CAGR through 2031, making it the fastest-growing technology group in the KSI model. Autonomous tractors, robotic weed-control systems and intelligent implements combine perception, navigation and physical actuation, converting AI from advisory software into a direct substitute for selected field labor.
Commercial growth is being supported by retrofit architectures as well as new machinery. This reduces the need for farms to replace entire equipment fleets before adopting automation and should expand the accessible market through the end of the forecast period.
Market by Offering
Software
Software accounts for approximately 43% of market value in 2026 and gains share through 2031. AI software increasingly manages agronomic modeling, image interpretation, equipment coordination, prescriptions, decision support and conversational access to farm data. Unlike much of the underlying machinery, software can also generate recurring revenue through subscriptions and licenses.
The shift toward AI assistants and continuously updated field intelligence strengthens this recurring model. Deere, Bayer, BASF, Taranis and CropX are all moving toward platforms in which AI insights are delivered throughout the crop cycle rather than through one-off analytical projects.
Hardware
Hardware is projected to grow at approximately 15.0% CAGR through 2031. Cameras, processors, sensors, autonomous-control systems and connected equipment remain essential because agricultural AI ultimately needs information about physical field conditions. Hardware therefore continues expanding strongly even as its relative market share moderates.
Services
Services remain important for system integration, agronomic support, calibration and implementation. AI tools often require local configuration and ongoing interpretation, particularly where farms operate mixed equipment fleets or where machine-learning models need to be adapted to local crops and conditions.
Market by Application
Crop health monitoring remains the largest application and accounts for approximately 26% of market value in 2026. Satellite imagery, drones, machinery-mounted cameras and sensors allow AI systems to identify stress and variability much earlier than conventional visual inspection across large fields.
Disease and pest detection grows faster, at approximately 18.9% CAGR through 2031, as image quality and plant-level models improve. Taranis and India’s National Pest Surveillance System demonstrate how AI-based detection is moving into commercial agronomy and public agricultural services rather than remaining limited to research environments.
Irrigation optimization benefits from the integration of soil data, weather information and crop models, while CropX’s computer-vision approach demonstrates that water stress can increasingly be assessed from plant imagery in addition to soil sensors. Climate and weather forecasting remains important as changing rainfall and temperature patterns increase the value of localized decision support throughout the forecast period.
Geographical Outlook
North America
North America represents approximately 39% of global market value in 2026. Large farm sizes, advanced machinery fleets and the presence of Deere, AGCO, CNH, Trimble, Taranis and several agricultural technology providers create favorable conditions for early adoption. The region is particularly strong in autonomous machinery, targeted application and crop intelligence, although growth increasingly depends on demonstrating measurable return on investment rather than technology novelty alone.
Asia Pacific
Asia Pacific is projected to grow at approximately 20.9% CAGR through 2031. The opportunity combines advanced agricultural machinery markets such as Japan and Australia with rapidly digitizing agricultural systems in China and India. India’s Digital Agriculture Mission is especially important because it is creating shared agricultural datasets and government AI applications that can reduce the infrastructure barrier faced by technology providers.
This allows the region to gain global share even though adoption models may differ substantially from North America. Mobile, advisory and public-infrastructure approaches are likely to be more important in smallholder-dominated markets than capital-intensive autonomy.
Europe
Europe remains a major precision-agriculture market but is projected to grow more slowly than Asia Pacific. The European Commission identifies agricultural AI as an important efficiency and sustainability tool but also highlights interoperability, data access and regulatory uncertainty as obstacles to adoption. European initiatives around agricultural data spaces and sector-specific AI models are intended to address these limitations over the forecast period.
South America remains important because of large commercial farming operations in Brazil and Argentina, particularly for crop monitoring, application optimization and machinery automation. The Middle East & Africa remains smaller, with adoption concentrated around high-value agriculture, irrigation optimization and projects where water or labor constraints provide a strong economic case.
Key Developments
September 2026: John Deere introduced JD, an AI assistant integrated into Operations Center that allows farmers to ask natural-language questions about their field, machine and operational data. The development supports KSI’s assumption that software gains share as precision-agriculture platforms evolve from dashboards toward conversational decision systems and recurring AI services.
August 2026: CropX acquired SCIO to create what it describes as a self-improving agronomic intelligence platform spanning the production cycle. The transaction strengthens CropX’s move toward integrated agronomic AI rather than isolated monitoring tools and supports the broader forecast for software-led farm intelligence.
May 2026: Taranis introduced Yield Impact, a model designed to convert leaf-level detected threats into estimates of potential yield loss. The development demonstrates the shift from simple crop detection toward economic decision intelligence, supporting faster growth in disease and pest analytics.
March 2026: CropX launched CropX Vision, using computer vision and agronomic modeling to estimate vineyard water stress from canopy images captured by a smartphone. The launch supports KSI’s higher computer-vision growth assumption by showing that image-based agronomy is expanding beyond machinery-mounted cameras into lower-cost mobile applications.
February 2026: John Deere selected five companies for its 2026 Startup Collaborator Program, with technologies covering advanced sensing, analytics, AI-driven robotics and digital crop intelligence. The program demonstrates continued investment by major equipment manufacturers in external AI technologies that can be incorporated into agricultural equipment and workflows.
October 2025: Syngenta and Taranis formalized a strategic AI partnership to expand leaf-level crop intelligence through agricultural retailers in the U.S. Midwest during the 2026 season. The partnership connects AI detection directly with crop-management decisions and provides commercial evidence for the projected expansion of plant-level pest and disease intelligence.
Competitive Environment
The competitive environment combines agricultural machinery manufacturers, precision-agriculture specialists, digital agronomy platforms, crop-input companies and AI-focused startups. Deere, AGCO and CNH possess an important advantage because they can integrate AI directly into machinery, while Trimble, Topcon and Ag Leader provide technology across mixed equipment fleets. Bayer, BASF and Syngenta bring agronomic datasets and crop expertise, while Taranis, CropX, Solinftec and other technology specialists compete through more focused AI capabilities.
Interoperability is becoming a significant basis of competition. Farmers frequently operate mixed fleets and use multiple agronomic platforms, making brand-agnostic deployment commercially important. AGCO’s PTx strategy explicitly emphasizes retrofit technology across different equipment brands, while cloud platforms increasingly compete on their ability to ingest external machine and field data.
The next stage of competition is likely to center on measurable field economics. Technologies that demonstrate lower chemical use, reduced labor, improved yield or better machinery utilization will have an advantage over AI products that merely generate additional information without changing farm decisions.
Artificial Intelligence (AI) in Precision Farming Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.02 billion |
| Total Market Size in 2031 | USD 4.40 billion |
| Forecast Unit | Billion |
| Growth Rate | 16.85% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Offering, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Technology
By Offering
By Application
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Computer Vision Moving from Crop Observation to Real-Time Field Action
3.1.2. Commercial Deployment of Autonomous and Retrofit Agricultural Machinery
3.1.3. Farm Data Platforms Becoming the Operating Layer for Agricultural AI
3.1.4. Plant-Level AI Intelligence Expanding Pest and Disease Management
3.1.5. Government Digital-Agriculture Infrastructure Expanding AI Accessibility
3.2. Market Restraints
3.2.1. Fragmented Agricultural Data and Limited Platform Interoperability
3.2.2. Dependence of AI Accuracy on Crop, Region and Field Conditions
3.2.3. Weak Economics of Hardware-Intensive AI for Smallholder Farms
3.2.4. Rural Connectivity and Edge-Computing Requirements
3.2.5. Farmer Data Ownership, Control and Trust Concerns
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Agricultural Computer Vision
4.2. Edge AI and On-Machine Processing
4.3. Autonomous Agricultural Systems
4.4. Generative AI and Agricultural Assistants
4.5. AI-Enabled Digital Twins and Predictive Agronomy
5. ARTIFICIAL INTELLIGENCE (AI) IN PRECISION FARMING MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Machine Learning
5.3. Computer Vision
5.4. Predictive Analytics
5.5. AI-Powered Robotics
5.6. Others
6. ARTIFICIAL INTELLIGENCE (AI) IN PRECISION FARMING MARKET BY OFFERING
6.1. Introduction
6.2. Hardware
6.3. Software
6.4. Services
7. ARTIFICIAL INTELLIGENCE (AI) IN PRECISION FARMING MARKET BY APPLICATION
7.1. Introduction
7.2. Crop Health Monitoring
7.3. Soil Health Monitoring
7.4. Disease and Pest Detection
7.5. Irrigation Optimization
7.6. Climate and Weather Forecasting
7.7. Others
8. ARTIFICIAL INTELLIGENCE (AI) IN PRECISION FARMING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Rest of South America
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Rest of Europe
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. South Africa
8.5.4. Rest of Middle East and Africa
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Australia
8.6.6. Indonesia
8.6.7. Thailand
8.6.8. Rest of Asia Pacific
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Deere & Company
10.2. AGCO Corporation
10.3. CNH Industrial N.V.
10.4. Trimble Inc.
10.5. Bayer AG
10.6. BASF SE
10.7. Syngenta Group
10.8. CropX Technologies Ltd.
10.9. Taranis
10.10. Topcon Positioning Systems, Inc.
10.11. Hexagon AB
10.12. Kubota Corporation
10.13. CLAAS KGaA mbH
10.14. DJI Agriculture
10.15. Arable Labs, Inc.
10.16. Ag Leader Technology
10.17. Solinftec
10.18. Carbon Robotics
10.19. Valmont Industries, Inc.
10.20. OneSoil
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for the Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth trajectory for the Artificial Intelligence (AI) in Precision Farming Market between 2026 and 2031?
The Artificial Intelligence (AI) in Precision Farming Market is forecast to grow at a robust Compound Annual Growth Rate (CAGR) of 16.85%. This expansion will see the market nearly double, reaching USD 4.40 billion by 2031, up from USD 2.02 billion in 2026, driven by advanced smart farming solutions.
Which key AI technologies and applications are driving the growth within the precision farming market, according to the report?
Key AI technologies driving growth include robotics, autonomous tractors, agricultural drones, predictive analytics, and machine learning. These are applied in critical areas such as real-time crop monitoring, yield optimization, precise resource management, climate adaptation, and forecasting pests, diseases, and weather risks for more resilient farming practices.
How does the report characterize the regional adoption and growth of AI in precision farming?
North America is identified as leading the market adoption of AI in precision farming, indicating strong existing infrastructure and farmer readiness. Meanwhile, the Asia-Pacific region is witnessing significant growth, largely fueled by governmental support and increasing demands for food security across its diverse agricultural landscapes.
What strategic insights does the report offer regarding the impact of AI on sustainable agriculture practices?
The report highlights that software platforms and IoT integrations are pivotal in driving sustainable agriculture. AI-powered solutions optimize irrigation, reduce chemical use, and minimize environmental impact, enabling farmers to make data-driven decisions that enhance productivity while preserving natural resources.
What global challenges are Artificial Intelligence (AI) in Precision Farming solutions designed to address, as per the market analysis?
AI in precision farming is strategically positioned to address pressing global challenges, including food security, climate change, and resource scarcity. Additionally, these solutions tackle labor shortages and boost overall operational efficiency worldwide by automating tasks and providing predictive insights.
Does the 'Artificial Intelligence (AI) in Precision Farming Market - Strategic Insights and Forecasts (2026-2031)' report include an analysis of the competitive landscape?
While the provided report highlights market dynamics, technological advancements, and regional growth drivers, a comprehensive strategic insights and forecasts report typically includes a detailed analysis of the competitive landscape. This usually covers profiles of key market players, their strategic initiatives, and market shares to provide a holistic view for stakeholders.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Artificial Intelligence (AI) in Precision Farming Market – Strategic Insights and Forecasts, 2026–2031. https://www.knowledge-sourcing.com/report/ai-in-precision-farming-market