
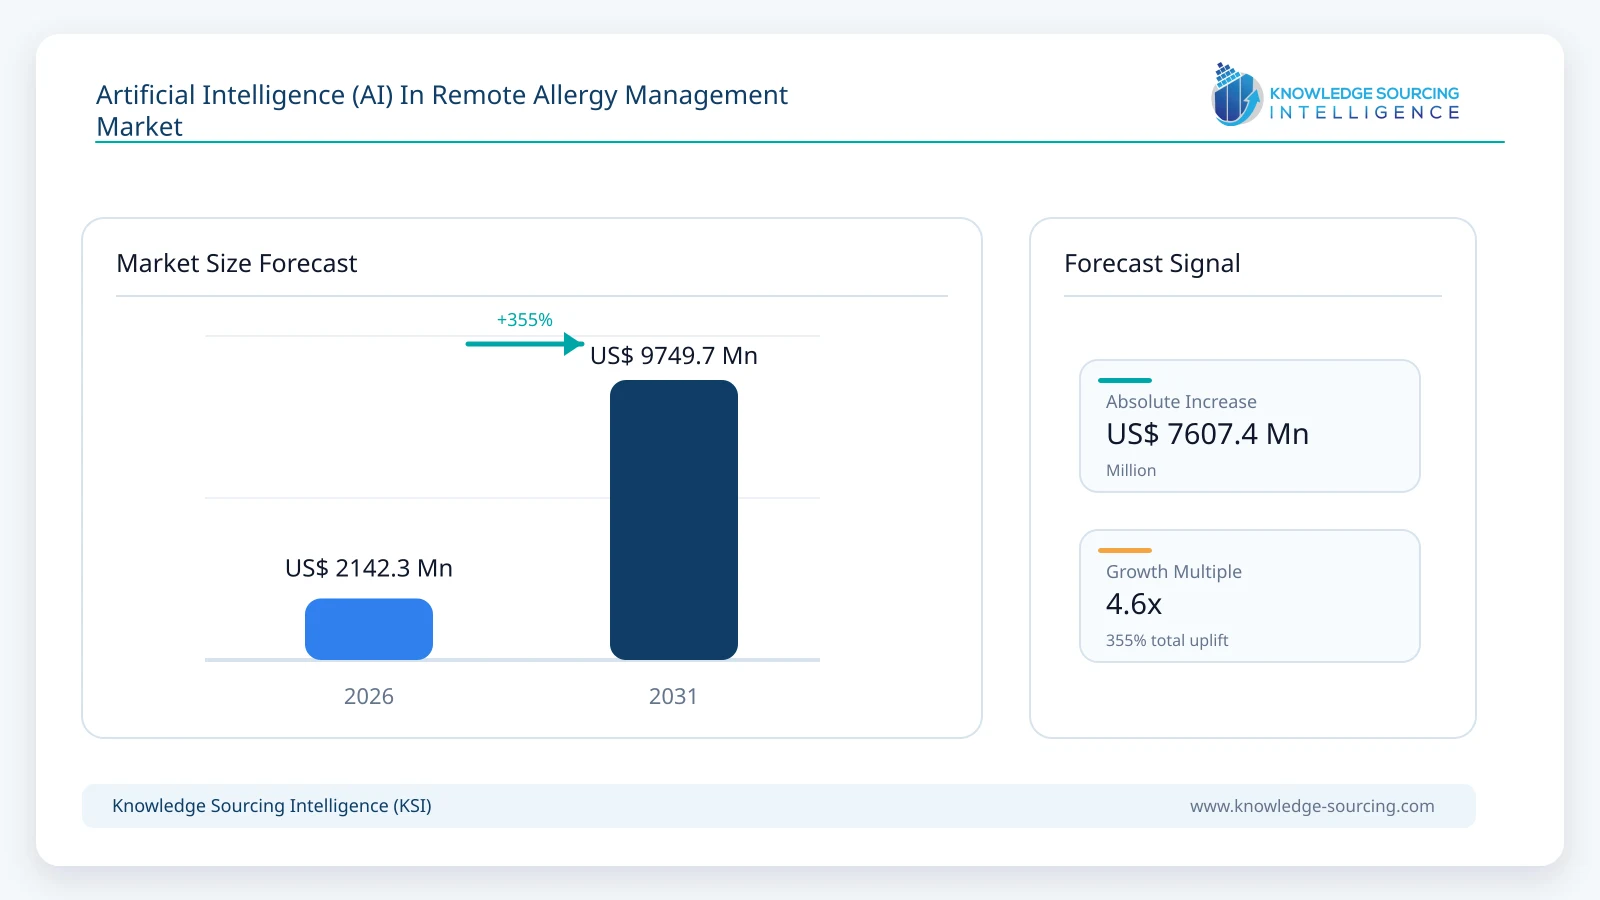
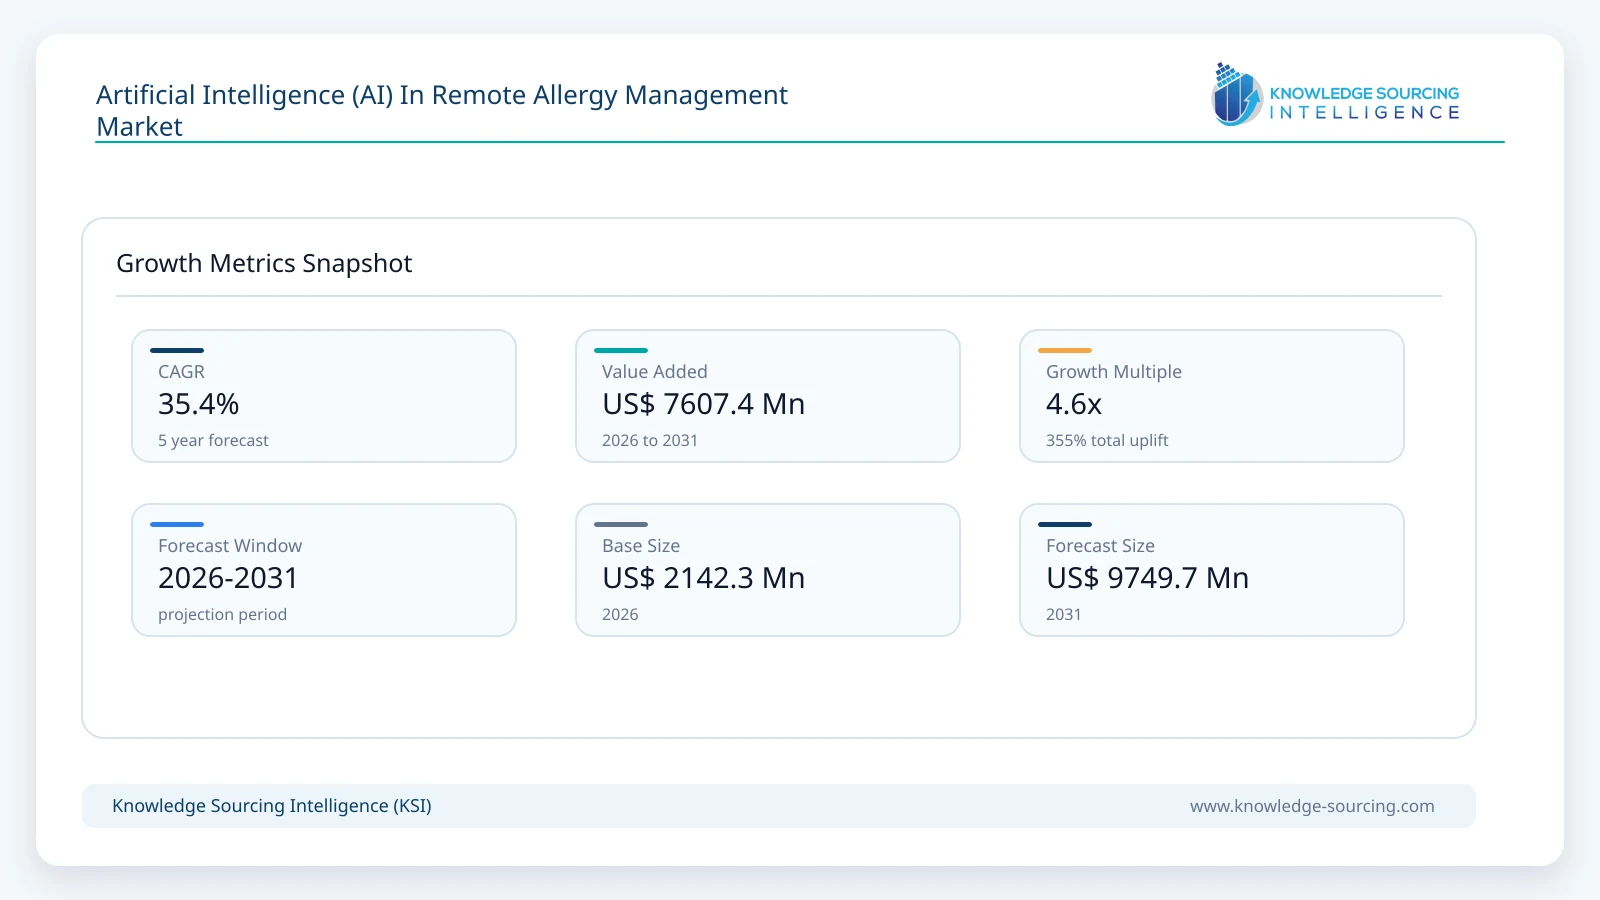
The global AI in remote allergy management market is expected to expand from USD 2,142.3 million to USD 9,749.7 million, driven by a robust compound annual growth rate (CAGR) of 35.4% across the 2026–2031 forecast period.
Highlights:
- 1Remote allergy tools fall into distinct commercial groupscondition-specific devices, specialist monitoring software and broad symptom-navigation platforms.
- 2Mobile Apps are the largest modeled product type, representing an estimated 53% of 2026 revenue, while dedicated wearables face higher device-specific evidence requirements.
- 3Symptom Monitoring and Management contributes an estimated 43% of 2026 application revenue; immunotherapy management requires separate specialist controls.
- 4Allergy Clinics and Centers account for approximately 31% of modeled 2026 end-user spending, alongside a comparable direct-to-consumer allocation.
- 5North America has a developed commercialization ecosystem, while Asia Pacific presents meaningful access-led expansion opportunities.
- 6Mediktor now owns Sensely; Healthily is the successor name to Your.MD, and 98point6's business structure changed in 2023.
AI in remote allergy management encompasses applications, connected medical devices and identifiable technology-enabled care services that help patients and professionals interpret symptoms, document exposures, oversee treatment and maintain contact outside the clinic. Products range from mobile diaries and pollen-sensitive alerts to physician-supervised immunotherapy support, virtual triage and an AI-personalized device for nasal congestion. The market boundary is the attributable allergy-management product or service, rather than every telemedicine visit or general-purpose wearable sold to a person with allergies.
Clinical pathways cannot be reduced to a single algorithm. A patient with seasonal rhinitis may benefit from a symptom diary tied to changing pollen conditions. Suspected food anaphylaxis needs immediate emergency protocols, not an app-generated probability. During oral immunotherapy, the treating specialist retains responsibility for dosing, adverse-event assessment and escalation. Vendors must establish where the software supports clinical judgment and where it has no authorization to diagnose or change treatment independently.
The product category also spans different purchasing cycles. Consumers may buy a wearable or use a self-management app directly. Clinics and health systems assess security, clinical governance, integration with records and suitability for pediatric care before contracting for monitoring services. This division affects customer-acquisition costs, retention and the evidence required to support reimbursement.
The January 2026 CDC release provides a useful demand benchmark: its 2024 survey found diagnosed seasonal allergy in 25.2% of US adults and food allergy in 6.7%. Among children, the corresponding figures were 20.6% and 5.3%. These are population prevalence estimates, not measurements of AI-product penetration or addressable software revenue. They nevertheless explain why scalable follow-up, repeat symptom capture and caregiver communications are recurring operational needs.
Wearables and symptom platforms have to solve different data problems. SoundHealth personalizes acoustic treatment using facial data and its connected band, whereas care-navigation systems such as Ada and Infermedica structure patient-reported complaints and suggest an appropriate care setting. Environmental readings, medication use and symptom intensity are useful only when the device or app collects them consistently and the resulting recommendation is clinically interpretable.
Contracts in the near term are likely to favor products that remove a measurable burden: fewer unproductive specialist contacts, better therapy follow-up, improved adherence documentation or earlier recognition of worsening symptoms. Selling a general AI assistant as an allergy product without a dedicated clinical program invites both pricing pressure and higher scrutiny of the claimed benefit.
Market Trends
Remote rhinitis treatment is becoming a defined device category
The US FDA recorded a 510(k) decision for SoundHealth's Sonu on 24 April 2025, expanding the indicated age population for its acoustic device. The official record describes an external mechanical stimulator for moderate-to-severe nasal congestion related to allergic and non-allergic rhinitis. SoundHealth's July 2025 Android release broadened smartphone access to the AI-assisted personalization used with the band. Commercially, this is a tighter proposition than an app claiming to predict all allergic events: users buy a specified home treatment, while efficacy and indications can be examined against device documentation.
The clinical distinction affects distribution. A rhinitis device can be marketed against a documented indication, whereas a generic allergy-attack predictor needs prospective evidence before customers should rely on it for urgent decisions. Pharmacy, specialist referral and device servicing also make the economics unlike those of an app-only subscription.
Food-allergy software is shifting toward treatment supervision
Alerje has repositioned around FAIT, a food-allergy immunotherapy support platform connecting families with care teams. Its business describes personalized tracking, predictive insights and clinical coordination, following the transfer of its earlier connected auto-injector program to a strategic partner. The opportunity is not automatic treatment of anaphylaxis. It lies in organizing the complex period between supervised visits, when daily exposure, adherence and symptom data can otherwise be fragmented across messages and paper logs.
A treatment log only becomes useful when a clinician can review out-of-range symptoms or adherence concerns without searching through unstructured messages. The FAIT model also illustrates why clinics, rather than app downloads, are a meaningful distribution route: protocol configuration, training and supported communication remain ongoing services.
Clinical AI is moving closer to formal care navigation
Ada's partnership with Fullspan Health, disclosed in October 2025, connects symptom assessment with pathways to provider care. Infermedica's September 2026 partnership with GP Triage in the UK similarly embeds certified triage into primary-care access. Neither announcement is an allergy-only commercial contract. Both demonstrate the route by which specialist allergy questions can be captured within a broader entry point, then escalated or referred rather than handled solely by a consumer chatbot.
Embedding symptom assessment within primary care can reduce the friction of seeking advice, but most patients sent through these systems do not have an allergy-specific diagnosis. A specialist vendor must therefore demonstrate what additional information is transferred to an allergist and how that information changes the next consultation.
Conversational interfaces need auditable reasoning
Mediktor expanded its AI-assisted triage proposition in April 2026 around guidance for both patients and care organizations. In an allergy context, the danger is not a weakly worded answer but an understated red flag, such as respiratory compromise after suspected food exposure. Procurement teams increasingly need decision logs, clinical escalation rules, documentation of supported languages and evidence that performance holds across age groups. Fluency of interaction is commercially useful only after the safety case is established.
Systems should be evaluated using case scenarios that include uncertain exposure, conflicting answers and severe symptoms. Their reliability depends on triage rules, human escalation, language performance and complete logs of the recommendation supplied, especially when an insurer or hospital uses the tool as a first contact point.
Biometric-data governance is entering product design
SoundHealth's July 2026 biometric notice specifically addresses facial geometry and related information processed through its AI-enabled device applications. For a subscription-based remote-care provider, a more detailed notice is not a substitute for a secure architecture, but it signals that privacy obligations go beyond ordinary contact information. Institutions purchasing these tools will examine retention periods, consent, secondary model training and the ability to transfer data to another provider when a patient changes care teams.
Images, geolocation, medications and reports of children's reactions can be sensitive in combination even when individual fields appear innocuous. Commercial deployments will need purpose limits and deletion arrangements that fit the care relationship, along with security testing of how biometric or environmental inputs are handled.
AI in Remote Allergy Management Market Segment Analysis
By Product Type
Mobile Apps
Mobile applications remain the most accessible route to recurring allergy management because they can collect symptom diaries, record treatments, display environmental conditions and connect patients to clinicians without a separate device. They represent an estimated USD 1,135.4 million, or 53% of the 2026 market, and reach approximately USD 4,874.9 million by 2031 in the reconciled outlook. This growth is not a function of downloads alone: a paid product must support an enduring need such as follow-up, monitored therapy or a reliable decision to seek care. Ada and Mediktor illustrate broad navigation, while Alerje is more narrowly associated with food-allergy treatment oversight.
Wearable Devices and Telemedicine Platforms remain substantial alternatives, but they carry different cost and evidence profiles. A Sonu band requires dedicated hardware and a defined indication; a virtual allergy consultation involves clinician time and licensure. Counting the whole consultation fee as AI revenue would overstate the distinct technology market.
By Application
Symptom Monitoring and Management
Symptom Monitoring and Management is the leading application, with an estimated 2026 value of USD 921.2 million and a 43% share. Allergic disease changes with season, place, activity and adherence, giving longitudinal records greater clinical usefulness than an isolated message. Repeated reports may help establish a pattern, but pollen concentrations, respiratory infection and medication changes can confound a seemingly convincing association. An effective platform shows the uncertainty and gives a professional a concise history rather than automatically converting correlation into treatment instructions.
Allergy Testing and Diagnosis requires stronger claims control, while Allergen Immunotherapy Management involves documented dosing and adverse-event follow-up under clinical oversight. Medication Management can support reminders and refill coordination; it should not independently authorize emergency medication changes. The highest-value workflows bring those functions together without blurring their clinical boundaries.
By End-User
Allergy Clinics and Centers
Allergy Clinics and Centers are well positioned to buy specialist remote monitoring because oral immunotherapy, follow-up consultations and testing generate regular work outside scheduled appointments. Their allocated revenue rises from approximately USD 664.1 million in 2026 to USD 3,217.4 million by 2031, equivalent to an estimated five-year CAGR of 37.1%. The strongest proposition is an auditable view of symptoms, missed check-ins and escalation events that fits the specialist's existing clinical system. A clinic cannot justify a platform that shifts the work of collecting histories from patients to nurses without a corresponding operational benefit.
Hospitals and Clinics may purchase broader digital-front-door applications, whereas Patients (Direct-to-Consumer) buy apps or devices with limited integration. Research Institutes are significant for protocol validation but should not be assumed to dominate recurring clinical spending. Vendor sales teams need to distinguish the procurement authority in each setting rather than apply one consumer-marketing approach to all four groups.
Market Drivers
High allergy prevalence and repeated monitoring needs
The CDC's January 2026 release reports that 31.7% of US adults had at least one of three diagnosed allergic conditions in 2024. The large patient base matters because persistent rhinitis, eczema and food-allergy care involve repeated decisions rather than a single diagnostic encounter.
A consistent remote history may reduce avoidable calls and give clinicians a better account of exposure and response to treatment. That does not establish willingness to pay: converting prevalence into revenue requires an identifiable funded service, a reason to return to the application and clinically meaningful use of the information. The demand does not translate automatically into technology sales. In the United States, diagnosed seasonal allergies affected 25.2% of adults in the 2024 survey, but only users with a funded clinical pathway or a recurring product need will generate meaningful vendor receipts. Measuring follow-up completion matters more than multiplying prevalence by an assumed app price.
Limited specialist capacity outside major cities
Remote monitoring gives patients in smaller communities a way to share structured observations before traveling to a specialist. The practical benefit is not replacement of an examination or supervised food challenge.
It is prioritization of who needs assessment, which symptoms can be reviewed asynchronously and whether the next visit should involve testing, medication review or education. Providers can justify investment where this reduces repeat administration and improves clinic capacity. The model weakens if a patient has unreliable connectivity or the system cannot route an urgent escalation to local emergency services. Clinic economics can be improved when monitoring captures the information needed before an appointment, reduces repeat administrative calls and prioritizes patients requiring supervised testing. Digital triage is unsuitable as a substitute for immediate emergency assessment, and the revenue opportunity can be limited where remote staff response is not funded.
Progress in connected therapeutic devices
SoundHealth's Sonu illustrates a device-led commercial pathway based on a specifically documented indication. Its connected app analyzes facial information to configure acoustic stimulation, distinguishing its product from generic symptom diaries.
Such devices can support device revenue and companion-software engagement, though hardware manufacturing, customer support and regulatory maintenance raise the entry threshold. A supplier that demonstrates repeat use and measurable relief has a clearer payer or consumer proposition than one offering a loosely defined allergy-risk score. Indication-specific labeling remains essential. The difference between a cleared device and a wellness recommendation has implications for costs. Hardware entails manufacturing control, compatibility testing, device support and continuing clinical surveillance. Providers that combine a defined home-use indication with straightforward technical support have a more substantial competitive position than those making general claims about AI diagnosis.
More structured follow-up for immunotherapy
Allergen immunotherapy and food-allergy intervention programs place operational demands on both households and specialist teams. Between-visit records, treatment reminders and controlled messaging can make the care plan easier to supervise and reduce missing information during follow-up.
Alerje's FAIT positioning addresses precisely this workflow. Revenue opportunities favor providers that can demonstrate clinician adoption, secure consented records and interoperability with clinic operations. AI-driven pattern detection may eventually improve monitoring efficiency, but it cannot independently set dosing or declare that emergency precautions are no longer required. Clinical oversight remains the decisive constraint. Daily logs may expose a pattern of missed doses or adverse symptoms, but they do not independently justify a dose change. Allergy clinics will prefer systems that allow predefined escalation and communication permissions, while providers will seek billing structures that recognize this recurring supervisory work.
Clinical AI partnerships expanding the route to care
Ada's October 2025 Fullspan agreement and Infermedica's 2026 GP Triage partnership point to procurement beyond standalone health apps. Payers, primary-care networks and hospitals increasingly want one initial contact point that can recognize a broad presentation and route it appropriately.
Allergy management could benefit when symptoms are flagged for specialist follow-up within this infrastructure. The commercial advantage is integration and distribution, not evidence that the platforms have separately monetized large allergy-specific contracts. Deployment partners still need transparent referral criteria and local clinical accountability. These distribution relationships can improve access to providers without proving that the partnership generated allergy-specific receipts. For suppliers, the relevant contract questions concern whether triage output reaches the receiving clinic, whether referral criteria can be customized and who bears responsibility if a high-risk symptom is classified incorrectly.
Market Restraints
Safety risks in autonomous advice
Severe allergic reactions may progress rapidly, leaving little tolerance for an algorithm that labels breathing difficulty as routine rhinitis. Emergency escalation needs clear rules, patient-facing instructions and tested handling of incomplete answers.
A model may also misread a caregiver's description of a child's symptoms. Vendors must delimit what the system does: symptom documentation, triage, or a specific regulated therapeutic function. Clinical review, ongoing surveillance and liability arrangements increase product-development costs, and they constrain the expansion of general-purpose conversational tools into specialist allergy care. Sales to health systems are consequently governed by case-level testing, override policies and safety monitoring. An algorithm may work on straightforward rhinitis presentations yet behave differently for a child with incomplete history or an adult reporting breathing difficulty. The result is a narrower scope for autonomous features than product demonstrations can imply.
Unclear payer coverage and fragmented purchasing
One clinic may view remote monitoring as a staff-efficiency purchase; another may expect insurers to reimburse remote-management services. Consumers, by contrast, can abandon an app after a single season.
This fragmentation makes it hard to build uniform pricing or estimate annual recurring revenue from downloads. Device reimbursement is additionally linked to its authorized indications and local benefit rules. Even where clinical value is plausible, pilot funding may not progress to long-term contracts unless a buyer can identify avoided workload, improved follow-up or another financial return. Monetization is particularly uneven across purchasing groups. A consumer might pay once for a device, a practice may subscribe to a patient panel, and a payer may contract for triage across many conditions. Without agreement on reimbursable activity and evidence of retained use, initial adoption can fail to produce recurring revenue.
Sensitive personal and biometric information
Exposure diaries, medicines, locations and photographs can reveal detailed health circumstances. Some AI-enabled devices also process facial geometry or other biometric information. SoundHealth's 2026 privacy notice illustrates this additional data class.
Cross-border cloud processing, secondary use for model improvement and caregiver access introduce requirements that differ across jurisdictions. Hospitals may require local hosting or contractual controls, while a consumer app needs consent explanations that can be understood without legal assistance. Compliance audits and cybersecurity obligations can materially lengthen sales cycles. Biometric inputs introduce another diligence requirement: healthcare buyers will ask whether local device processing can be substituted for cloud transfer and whether users can revoke permissions. Even a platform with a reassuring privacy notice needs independent security assessment, defensible retention periods and a route to delete or export data.
Inconsistent data capture and limited generalizability
A patient may log symptoms after exposure but omit a missed dose, record the wrong time or stop using the application once symptoms improve. Environmental readings can also be coarse relative to actual indoor exposure.
Predictive algorithms built on such records risk finding correlations that fail for another geography, age cohort or allergen. Vendors need prospective clinical assessment, calibration checks and a mechanism for detecting poor-quality inputs. Without those safeguards, attractive dashboards can generate extra clinician work rather than reliable decisions. Incomplete diary entries also bias the population from which a model learns. Patients with poorly controlled symptoms may report more frequently, while those improving may stop recording. Vendor claims require prospective validation against clinical endpoints, not only a retrospective correlation between symptom logs and environmental sensors.
Complex device, app and clinic interoperability
Remote allergy care frequently crosses consumer phones, provider portals, connected devices and a practice's electronic health record. A supplier that cannot return a concise, verified report to the clinician may leave staff reconciling multiple screens.
In pediatric care, permissions for parents and guardians add another layer. Integrating a vendor into an existing care network can demand localization, clinical workflow changes, cybersecurity reviews and training. Smaller allergy practices are especially exposed to these fixed costs, limiting immediate uptake of feature-rich platforms. Integration costs differ between a direct consumer application and a specialist practice. Pediatric authorization, multiple caregiver roles, EHR interfaces, immunotherapy schedules and audit logs can extend procurement. Standardized export and concise clinician summaries can lower those costs without forcing a clinic to replace existing records and billing systems.
Regional Outlook
North America: established care infrastructure and product commercialization
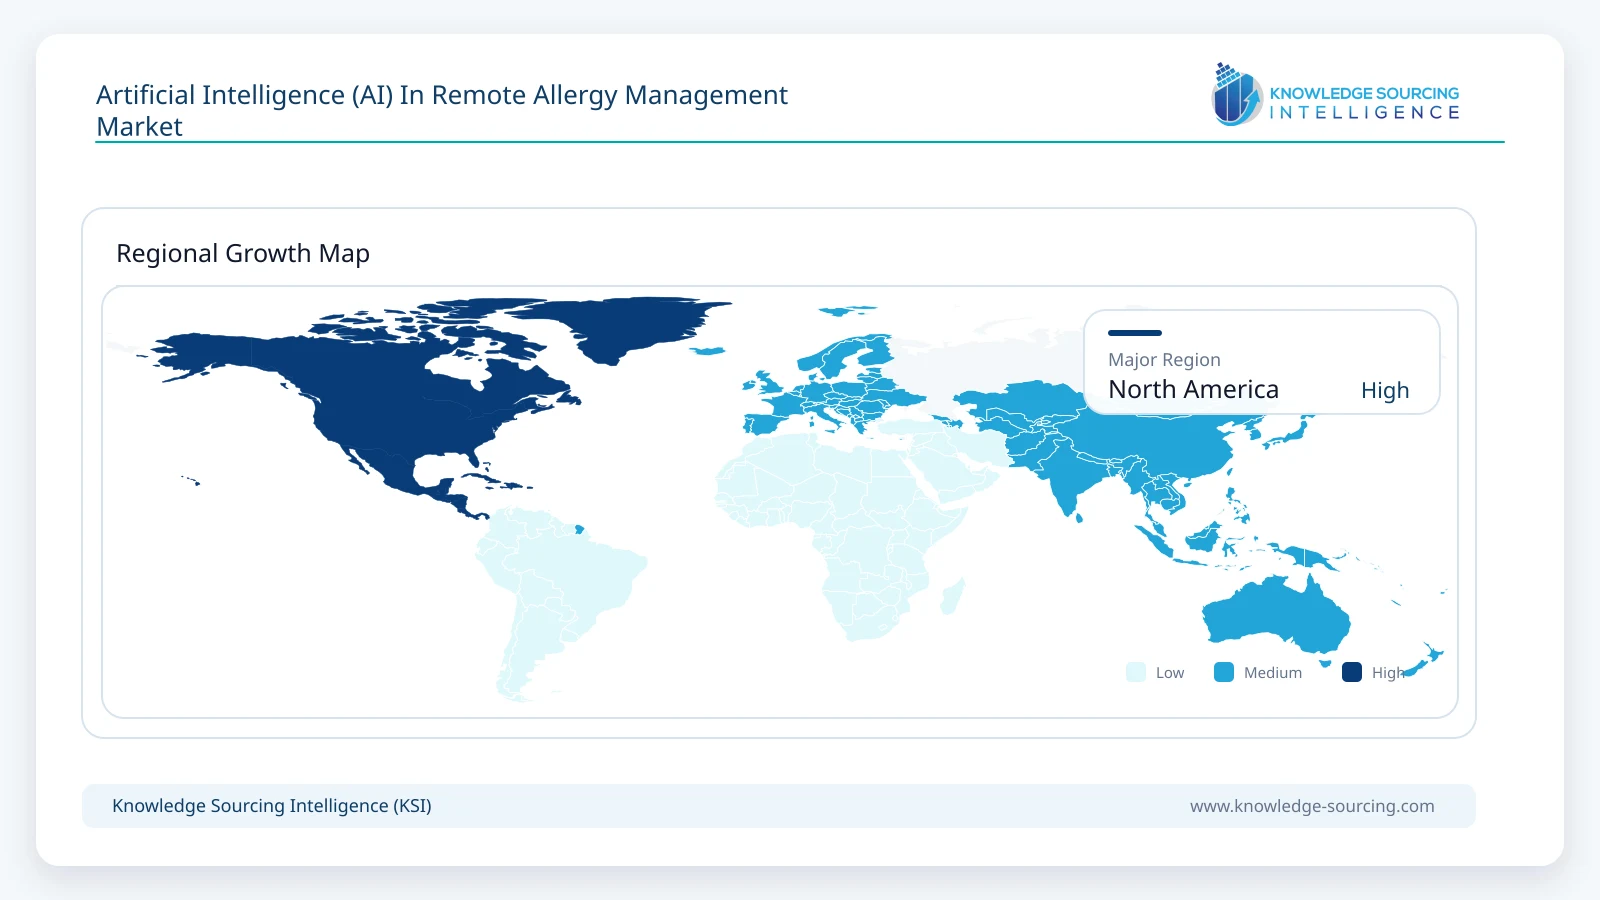
North America is the largest regional market in the reconciled outlook, with estimated revenue of USD 921.2 million in 2026, equivalent to 43% of global spending. The regional value rises to approximately USD 3,509.9 million in 2031, implying a 30.7% CAGR. A large diagnosed-allergy population, mature specialty networks and the presence of clinically oriented digital-health companies support procurement. The United States provides a visible route to market through FDA-cleared devices such as SoundHealth's SONU, while care-navigation contracts connect health plans and clinical practices to broader AI infrastructure.
Growth will still be selective. U.S. specialist programs must address emergency escalation, data protection and payment for work completed outside a visit; the relative contribution of consumer-device sales and recurring clinic software will vary. Canada and Mexico face different reimbursement and access conditions, limiting the transferability of a single U.S. pricing model. Supplier claims of a wide regional installed base require scrutiny because general telehealth users are not equivalent to paid allergy-management clients.
Asia Pacific: expanding digital access and specialist-service need
Asia Pacific is the fastest-growing distinct region in the allocation, rising from an estimated USD 428.4 million in 2026 to USD 2,827.4 million in 2031, at an implied CAGR of 45.9%. Its share of worldwide spending increases from about 20% to 29%. This trajectory reflects a developing mobile-care ecosystem, expanding specialist services and demand for remote support in locations where travel or appointment shortages complicate allergy follow-up. Growth opportunities differ substantially between China, India, Japan, South Korea and Southeast Asia.
Patient reach is not the same as clinical monetization. A local-language interface, documented exposure data and reliable referrals are essential for meaningful allergy management, particularly when symptoms overlap with asthma or respiratory infection. Providers entering these markets need partnerships with local clinics and suitable handling of healthcare information. Environmental forecast applications may attract engagement, but recurring value will depend on whether monitoring feeds a funded consultation or a condition-specific care program.
Competitive Landscape
SoundHealth and Alerje provide the clearest specialist examples. SoundHealth combines AI-enabled personalization with an FDA-cleared acoustic device for specified nasal congestion; Alerje develops FAIT around allergy immunotherapy supervision and home records. ModuleMD offers AllerSpect AI for skin-test image measurement within allergy practices, while TPS Software Production's AllergyMonitor supports structured allergy symptom and medication diaries. These products do not address identical clinical stages, and their evidence requirements and sales channels differ.
Broader AI health-navigation companies occupy an adjacent commercial layer. Ada Health, Infermedica and Mediktor can assess and route presentations involving suspected allergies but do not disclose stand-alone allergy management revenue. Mediktor acquired Sensely in June 2024, and Healthily is the successor brand to Your.MD; Healthily's app is now operated under licence by Webron. 98point6 Technologies primarily licenses virtual-care software after its 2023 care-delivery divestment. Treating these businesses as dedicated allergy-management specialists would overstate their product-market exposure.
Market leadership depends on the buyer's purpose. A specialist clinic looks for documentation, validated symptoms and dependable patient follow-up; a consumer evaluates convenience and price; a payer values safe care routing. In each case, clinical responsibilities must remain explicit. A vendor showing a defined effect on staff workload or follow-up is better positioned to sustain contracts than one offering an unvalidated generalized allergy-prediction score.
Recent Developments
September 2026: Infermedica and GP Triage-Announced integration of Infermedica's certified clinical triage into a UK primary-care digital front door. The partnership supports care routing across symptoms; no allergy-specific revenue was reported.
April 2026: Mediktor-Introduced an integrated patient-and-provider digital care-navigation proposition for hospitals, insurers and clinics. The service extends symptom guidance but is not an autonomous allergy diagnostic product.
22 April 2026: Ada Health-Reported a prospective study of its AI symptom assessment in Portugal's CUF network, covering 1,470 adults and their subsequent care choices. The outcome concerns general clinical navigation rather than validated allergy diagnosis.
December 2025: ModuleMD-Announced AllerSpect AI for standardized wheal-and-flare image measurements within an allergy-specialty workflow; the vendor described a documentation feature, not permission for autonomous diagnostic decisions.
21 October 2025: Ada Health and Fullspan Health-Announced a partnership connecting AI symptom assessment to care-navigation pathways. The arrangement spans multiple therapeutic areas and is not evidence of a dedicated allergy contract.
Market Outlook
The next stage of this market will be shaped less by the number of AI-enabled health apps than by specialist relevance. Patient monitoring for rhinitis or food-allergy treatment can support recurring engagement if it yields consistent histories and appropriately escalates risks. Condition-specific connected devices have clearer product boundaries, but they carry evidence and regulatory costs. Broader care-navigation platforms can distribute allergy-related services at scale, although attribution of their revenue remains difficult.
Over the forecast period, the most credible investment priorities are secure between-visit monitoring, clinician-directed immunotherapy support, validated home-use interventions and better referral integration. Continued growth also depends on privacy safeguards, reimbursement and the ability to demonstrate value in routine practice. The market will reward careful clinical positioning over claims that unsupervised AI can diagnose or treat the full spectrum of allergic disease.
AI in Remote Allergy Management Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2,142.3 million |
| Total Market Size in 2031 | USD 9,749.7 million |
| Forecast Unit | Million |
| Growth Rate | 35.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Product Type
Mobile Apps
Wearable Devices
Telemedicine Platforms
Others
By Application
Allergy Testing and Diagnosis
Allergen Immunotherapy Management
Symptom Monitoring and Management
Medication Management
Others
By End-User
Hospitals and Clinics
Allergy Clinics and Centers
Research Institutes
Patients (Direct-to-Consumer)
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. CXO Perspective
2. MARKET SNAPSHOT
2.1. Market Definition, Scope and Value Pool
2.2. Forecast and Segmentation Overview
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. High allergy prevalence and repeated monitoring needs
3.1.2. Limited specialist capacity outside major cities
3.1.3. Progress in connected therapeutic devices
3.1.4. More structured follow-up for immunotherapy
3.1.5. Clinical AI partnerships expanding the route to care
3.2. Market Restraints
3.2.1. Safety risks in autonomous advice
3.2.2. Unclear payer coverage and fragmented purchasing
3.2.3. Sensitive personal and biometric information
3.2.4. Inconsistent data capture and limited generalizability
3.2.5. Complex device, app and clinic interoperability
3.3. Market Opportunities
3.4. Porter’s Five Forces
3.5. Industry Value Chain
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Clinical AI and Symptom Interpretation
4.2. Connected Wearables and Data Capture
4.3. Privacy, Safety and Integration
5. AI IN REMOTE ALLERGY MANAGEMENT MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Mobile Apps
5.3. Wearable Devices
5.4. Telemedicine Platforms
5.5. Others
6. AI IN REMOTE ALLERGY MANAGEMENT MARKET BY APPLICATION
6.1. Introduction
6.2. Allergy Testing and Diagnosis
6.3. Allergen Immunotherapy Management
6.4. Symptom Monitoring and Management
6.5. Medication Management
6.6. Others
7. AI IN REMOTE ALLERGY MANAGEMENT MARKET BY END-USER
7.1. Introduction
7.2. Hospitals and Clinics
7.3. Allergy Clinics and Centers
7.4. Research Institutes
7.5. Patients (Direct-to-Consumer)
7.6. Others
8. AI IN REMOTE ALLERGY MANAGEMENT MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Product Type
8.2.2. By Application
8.2.3. By End-User
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Product Type
8.3.2. By Application
8.3.3. By End-User
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Product Type
8.4.2. By Application
8.4.3. By End-User
8.4.4. By Country
8.4.4.1. Germany
8.4.4.2. United Kingdom
8.4.4.3. France
8.4.4.4. Italy
8.4.4.5. Spain
8.4.4.6. Others
8.5. Middle East and Africa
8.5.1. By Product Type
8.5.2. By Application
8.5.3. By End-User
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. South Africa
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Product Type
8.6.2. By Application
8.6.3. By End-User
8.6.4. By Country
8.6.4.1. China
8.6.4.2. India
8.6.4.3. Japan
8.6.4.4. South Korea
8.6.4.5. Australia
8.6.4.6. Indonesia
8.6.4.7. Thailand
8.6.4.8. Taiwan
8.6.4.9. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. SoundHealth
10.2. Alerje, Inc.
10.3. ModuleMD
10.4. TPS Software Production (AllergyMonitor)
10.5. Ada Health GmbH
10.6. Infermedica
10.7. Mediktor (including Sensely)
10.8. Healthily (formerly Your.MD)
10.9. 98point6 Technologies
10.10. K Health, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits to Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











