
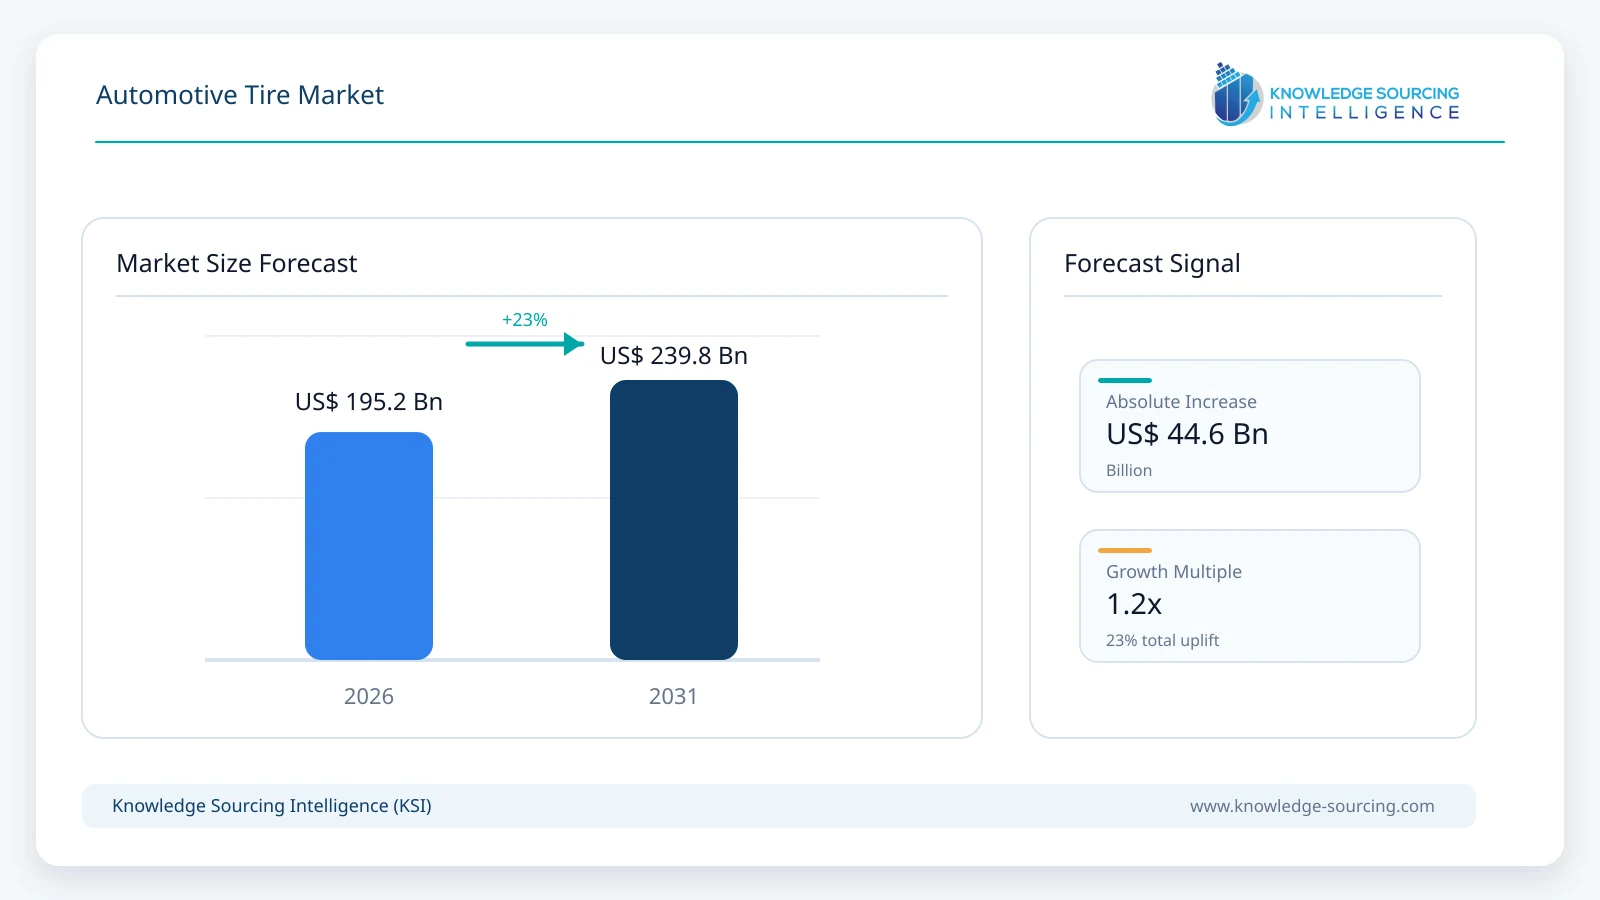
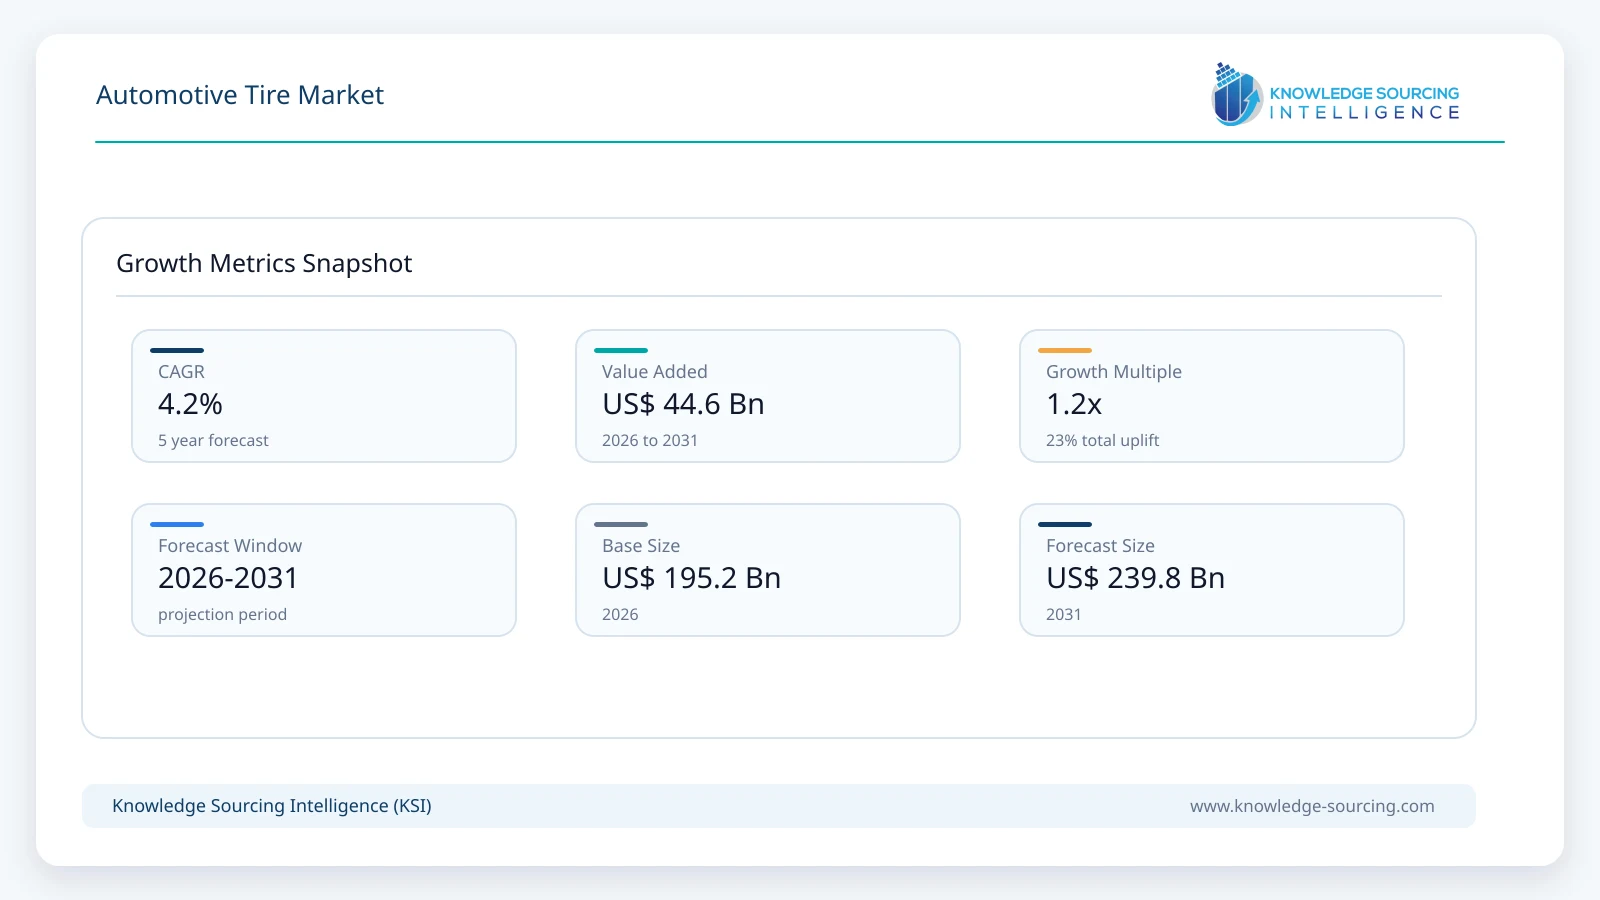
The automotive tire market will grow from USD 195.2 billion in 2026 to USD 239.8 billion by 2031, at a CAGR of 4.2% during this period.
Highlights:
- 1Passenger-car tires account for approximately 54% of global automotive tire revenue in 2026.
- 2Radial tires generate approximately USD 177.6 billion of global market value in 2026.
- 3The aftermarket segment is projected to grow at approximately 4.5% annually through 2031.
- 4Asia Pacific represents approximately 43% of global automotive tire revenue in 2026.
- 5Larger rim sizes are gaining value share as SUVs and premium vehicles expand globally.
- 6Electric vehicles are increasing demand for lower rolling resistance, higher load capacity and quieter tires.
Automotive tires are engineered around the combined requirements of load carrying, braking, cornering, ride comfort, durability and energy efficiency. The product specification varies materially by vehicle type. Passenger tires prioritize comfort, wet grip, noise and rolling resistance. Commercial tires place greater emphasis on casing durability, mileage and retreadability. Two-wheeler tires require different profiles and compounds for lean-angle performance, while off-the-road tires are designed for high loads, rough terrain and cut resistance.
The replacement market provides a stable demand base because it is linked to vehicles already in use rather than only to current production. In the United States, the U.S. Tire Manufacturers Association expects total tire shipments of about 330.3 million units in 2026, with replacement shipments materially larger than original-equipment volumes. Europe also has a large installed fleet. The European Automobile Manufacturers' Association reported 256 million passenger cars, 31.1 million vans and 6.2 million trucks on European Union roads in 2024. An older vehicle parc supports recurring replacement demand even when new-vehicle production slows.
Industry value is also supported by product mix. Michelin reported that 18-inch and larger tires represented 68% of its branded passenger-car tire sales in 2025. Continental reported that ultra-high-performance tires accounted for 62% of Continental-brand passenger-car tire sales in 2025. These trends indicate that revenue growth can exceed unit growth when consumers and vehicle manufacturers move toward larger, higher-performance tires.
Market Trends
Electric vehicles are changing load, wear, rolling-resistance and noise requirements
Electric vehicles combine higher curb weight with instant torque and strong sensitivity to rolling resistance. This creates a more demanding tire design problem than simply increasing tread life. Manufacturers are using stronger structures, optimized compounds and lower-noise tread patterns to protect range and manage wear. Continental supplied all ten of the highest-volume electric vehicle manufacturers in the Europe, Middle East and Africa region during 2025. Hankook continues to expand its iON range for electric vehicles, while Yokohama is increasing original-equipment supply for battery-electric models.
Premium and ultra-high-performance tires are taking a larger share of revenue
Vehicle size and performance continue to rise, particularly in sport utility vehicles, crossovers and premium electric models. This is supporting 18-inch and larger tires with higher speed ratings and more complex performance requirements. Continental plans to add more than 650 ultra-high-performance sizes by the end of 2027. Michelin introduced the Primacy 5 Energy and Pilot Sport 5 Energy ranges in March 2026 with a focus on efficiency, longevity and vehicle performance. The trend raises average selling prices but also increases development and manufacturing complexity.
Circular materials and tire-wear reduction are moving deeper into product development
Tire manufacturers are increasing the use of recycled and renewable materials while studying tire and road wear particles more closely. Continental developed a concept tire containing around 43% recycled materials for the European ZEvRA project in August 2026. Bridgestone had obtained ISCC PLUS certification at 19 tire plants by April 2026 and is expanding traceable renewable and recycled inputs. The shift is likely to affect material sourcing, compound design and supplier qualification over the forecast period.
Market Drivers
A large and aging vehicle parc sustains replacement demand
Replacement demand is less cyclical than original-equipment demand because tires must be replaced as vehicles accumulate mileage. The installed fleet continues to expand in major regions, while average vehicle age remains high in many developed markets. This supports recurring demand across passenger cars, vans and commercial trucks. The effect is particularly important for premium brands that have strong replacement distribution and for commercial suppliers that sell products around mileage, casing durability and total cost of ownership.
Electric and premium vehicles support higher-value tire specifications
Electric vehicles, premium sport utility vehicles and high-performance cars require tires with greater load capacity, tighter noise control and lower rolling resistance. These specifications support more sophisticated compounds, stronger constructions and larger rim diameters. Continental's 2026 collaboration with Renault demonstrated that optimized tire design can materially reduce rolling resistance and improve vehicle range. The growth opportunity therefore comes not only from more tire units, but from higher value per tire.
Road-safety and efficiency regulation encourage continuous product improvement
Tire performance is regulated through safety standards and increasingly through labeling systems that disclose rolling resistance, wet grip and external noise. The European Union tire label makes product efficiency and safety attributes directly comparable at the point of purchase. The United States applies Federal Motor Vehicle Safety Standard requirements to new pneumatic tires, while China uses national compulsory standards. These frameworks support investment in compounds, tread design and construction technology.
Market Restraint
Raw-material volatility and low-priced imports pressure margins in mature replacement markets
Natural rubber, synthetic rubber, carbon black, steel cord and energy costs remain important inputs to tire production. Manufacturers also face tariffs, freight volatility and intense price competition from lower-cost imported products. Michelin and Goodyear both reported challenging market conditions during 2025 as lower-priced imports affected parts of the replacement market. The pressure is strongest in commoditized sizes where brand differentiation is limited. Premiumization and stronger distribution help offset the impact but do not remove raw-material and trade risk.
Segment Analysis
By Vehicle Type - Passenger Cars
Passenger cars form the largest vehicle-type segment because they represent the largest installed vehicle population and generate frequent replacement demand. The segment is projected to reach approximately USD 128.0 billion by 2031. Demand is being supported by larger sport utility vehicles, electrified powertrains and premium fitments. Manufacturers are also broadening all-season and electric-vehicle-ready product ranges to cover more passenger-car platforms with fewer specialized product families.
By Tire Type - Radial
Radial tires dominate passenger-car and commercial applications because their construction provides lower rolling resistance, better heat management and longer tread life than conventional bias designs. The segment is projected to grow at approximately 4.3% annually through 2031. Bias tires remain relevant in selected off-road, agricultural, construction and specialty applications where sidewall flexibility and rugged service conditions can favor a different construction.
By End User - Aftermarket
The aftermarket is the largest end-user segment because the number of tires replaced on the installed vehicle fleet substantially exceeds the number fitted to newly produced vehicles. The segment accounts for approximately 73% of market value in 2026. Replacement demand is influenced by vehicle mileage, tire life, climate, road conditions and consumer willingness to move to premium products. The segment also gives manufacturers greater pricing and brand control than many original-equipment contracts.
By Rim Size - Below 18 Inches
Tires below 18 inches remain the largest rim-size segment because they are widely used on mass-market passenger cars, compact sport utility vehicles and light commercial vehicles. The segment is estimated at approximately USD 91.7 billion in 2026. Its share is gradually declining as vehicle platforms move toward 18-inch and larger wheels. Smaller rim sizes remain important in price-sensitive markets and in high-volume replacement applications.
By Geography - Asia Pacific
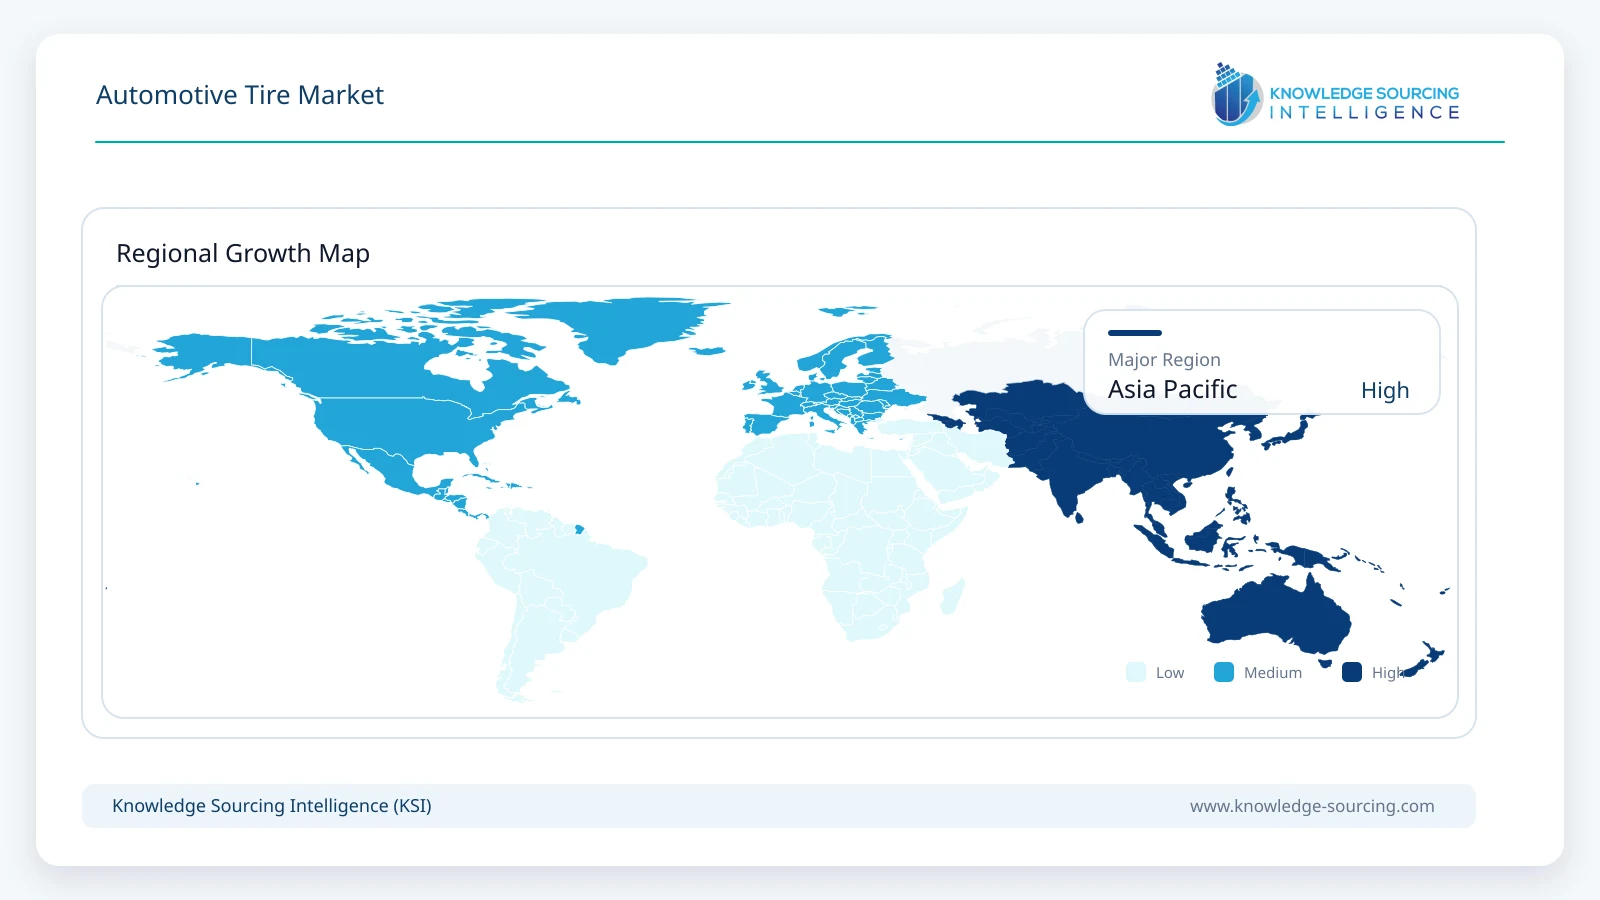
Asia Pacific is the largest regional market because it combines the world's largest vehicle-production base with substantial replacement demand and a large tire-manufacturing ecosystem. Regional market value is projected to reach approximately USD 106.0 billion by 2031. China is the largest manufacturing and consumption center, while Japan, South Korea, India and Southeast Asia contribute major production capacity and replacement demand. Local manufacturers continue to gain scale alongside established global brands.
Competitive Environment
Michelin and Bridgestone remain the largest global tire manufacturers by tire sales. Both operate across passenger, commercial and specialty applications and compete through premium brands, original-equipment relationships and global replacement networks. Michelin is emphasizing larger rim sizes, energy efficiency and product longevity. Bridgestone continues to invest in premium fitments, sustainable materials and manufacturing expansion in growth markets such as India.
Goodyear, Continental and Pirelli form another major competitive group. Goodyear generated USD 15.39 billion of worldwide tire-unit sales in 2025 after completing several portfolio divestitures. Continental's Tires business generated EUR 13.8 billion of sales in 2025 and continues to increase its exposure to ultra-high-performance and electric-vehicle fitments. Pirelli remains concentrated in the premium and high-value segment.
Asian manufacturers are gaining scale across both domestic and export markets. Sumitomo Rubber, Hankook, Yokohama, ZC Rubber, Sailun, Toyo, Kumho and Linglong all rank among the world's largest tire producers. Indian manufacturers such as MRF, Apollo Tyres, CEAT and JK Tyre have also expanded international reach. Competition increasingly depends on product mix, distribution strength, original-equipment approvals, manufacturing cost and the ability to support regional regulatory requirements.
Recent Developments
September 2026: Pirelli and the Arma dei Carabinieri agreed to test Cyber Tyre technology on selected vehicles in Rome.
September 2026: Continental announced plans to add more than 650 new ultra-high-performance tire sizes by the end of 2027.
September 2026: Bridgestone launched the Potenza Race R track tire for the 2026 Lamborghini Revuelto SV.
August 2026: Continental developed a concept tire containing around 43% recycled materials for the European ZEvRA project.
July 2026: Yokohama Rubber expanded original-equipment fitments for ADVAN tires across premium and electric vehicle platforms.
June 2026: Yokohama Rubber announced the BluEarth-AllSeason2 for Europe in 74 sizes covering passenger cars, SUVs and BEVs.
June 2026: Continental and Renault Group announced an energy-efficiency tire collaboration focused on lower rolling resistance.
March 2026: Michelin introduced the Primacy 5 Energy and Pilot Sport 5 Energy summer tire ranges.
Automotive Tire Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 195.2 billion |
| Total Market Size in 2031 | USD 239.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Vehicle Type, Tire Type, End-User, Rim Size, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Vehicle Type
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
Two-Wheelers
Off-the-Road Vehicles
By Tire Type
Radial
Bias
By End User
OEM
Aftermarket
By Rim Size
Below 18 Inches
18-20 Inches
Above 20 Inches
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. A Large and Aging Vehicle Parc Sustains Replacement Demand
3.1.2. Electric and Premium Vehicles Support Higher-Value Tire Specifications
3.1.3. Road-Safety and Efficiency Regulation Encourage Continuous Product Improvement
3.2. Market Restraint
3.2.1. Raw-Material Volatility and Low-Priced Imports Pressure Margins in Mature Replacement Markets
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Electric-Vehicle Tire Design
4.2. Low-Rolling-Resistance Compounds
4.3. Smart and Connected Tires
4.4. Recycled and Renewable Materials
4.5. Wear Reduction and Tire-and-Road Wear Particle Management
5. AUTOMOTIVE TIRE MARKET BY VEHICLE TYPE
5.1. Introduction
5.2. Passenger Cars
5.3. Light Commercial Vehicles
5.4. Heavy Commercial Vehicles
5.5. Two-Wheelers
5.6. Off-the-Road Vehicles
6. AUTOMOTIVE TIRE MARKET BY TIRE TYPE
6.1. Introduction
6.2. Radial
6.3. Bias
7. AUTOMOTIVE TIRE MARKET BY END USER
7.1. Introduction
7.2. OEM
7.3. Aftermarket
8. AUTOMOTIVE TIRE MARKET BY RIM SIZE
8.1. Introduction
8.2. Below 18 Inches
8.3. 18-20 Inches
8.4. Above 20 Inches
9. AUTOMOTIVE TIRE MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Product and Technology Positioning
10.4. Mergers, Acquisitions, Agreements and Collaborations
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Michelin Group
11.2. Bridgestone Corporation
11.3. The Goodyear Tire & Rubber Company
11.4. Continental AG
11.5. Pirelli & C. S.p.A.
11.6. Sumitomo Rubber Industries, Ltd.
11.7. Hankook Tire & Technology Co., Ltd.
11.8. The Yokohama Rubber Co., Ltd.
11.9. Zhongce Rubber Group Co., Ltd.
11.10. Sailun Group Co., Ltd.
11.11. Toyo Tire Corporation
11.12. Kumho Tire Co., Inc.
11.13. MRF Limited
11.14. Apollo Tyres Limited
11.15. Shandong Linglong Tire Co., Ltd.
11.16. Cheng Shin Rubber Ind. Co., Ltd. (Maxxis)
11.17. Giti Tire Pte. Ltd.
11.18. Nexen Tire Corporation
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for automotive tires?
Market projected to reach USD 239.8 billion by 2031, growing at 4.2% CAGR.
Which tire segment accounts for the largest share of revenue in 2026?
Passenger-car tires account for approximately 54% of global revenue in 2026.
Which geographical region dominates the Automotive Tire Market?
Asia Pacific represents approximately 43% of global revenue in 2026.
What key factors are driving growth in the Automotive Tire Market?
Larger rim sizes, electric vehicles, and stable replacement demand drive growth.
How significant is the aftermarket segment's growth?
The aftermarket segment is projected to grow at approximately 4.5% annually.
How are electric vehicles impacting tire design and demand?
EVs demand lower rolling resistance, higher load capacity, and quieter tires.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Automotive Tire Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-tire-market