
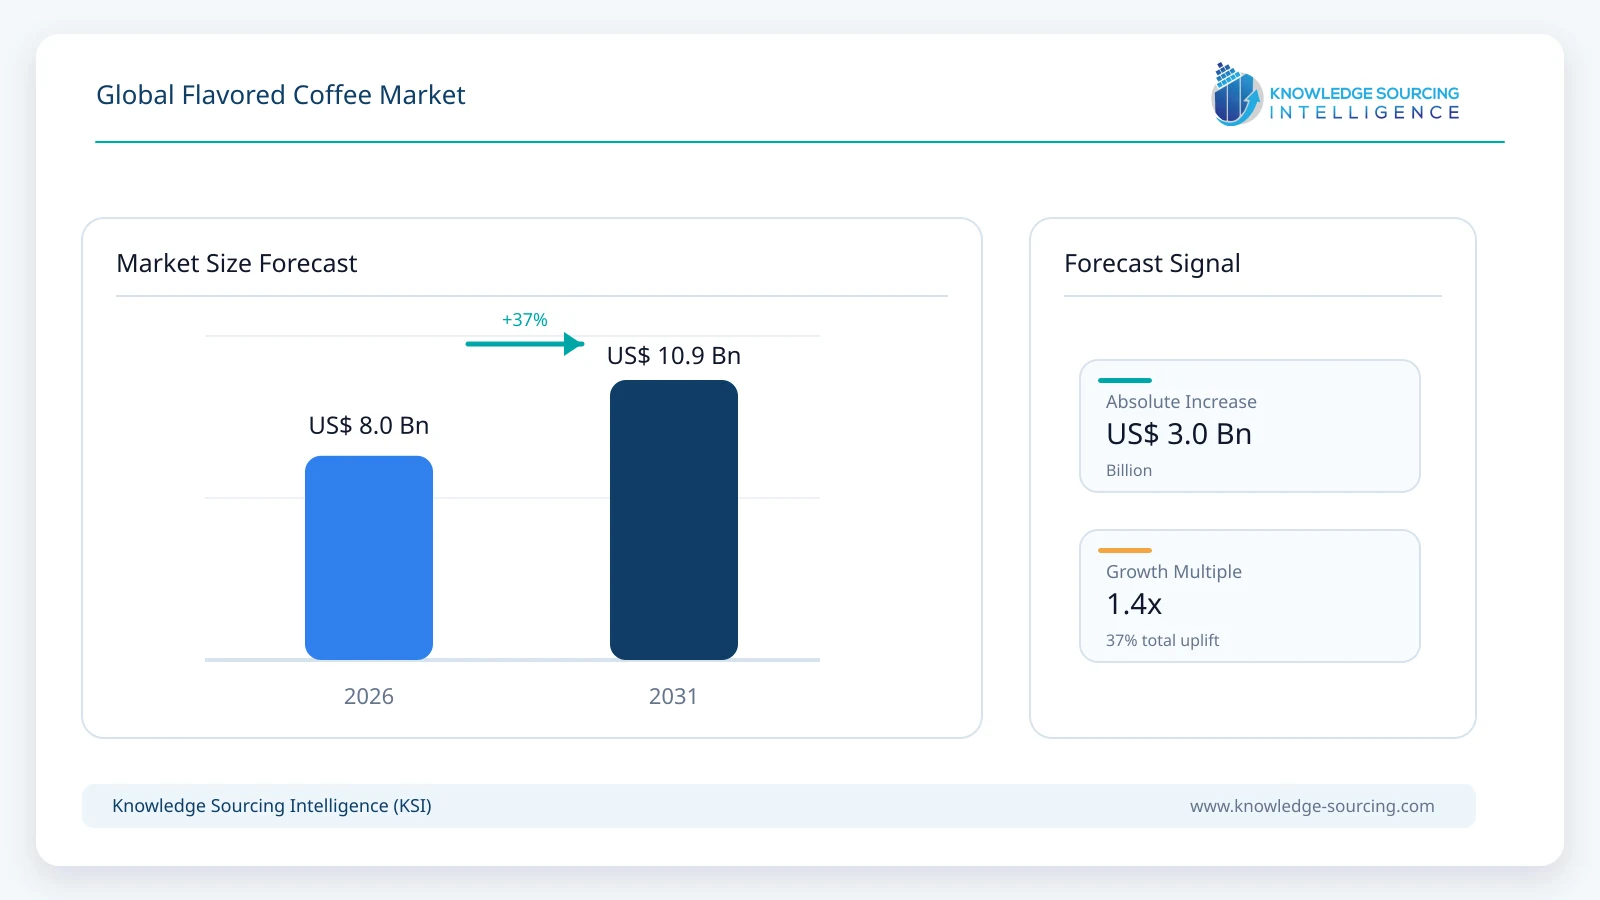
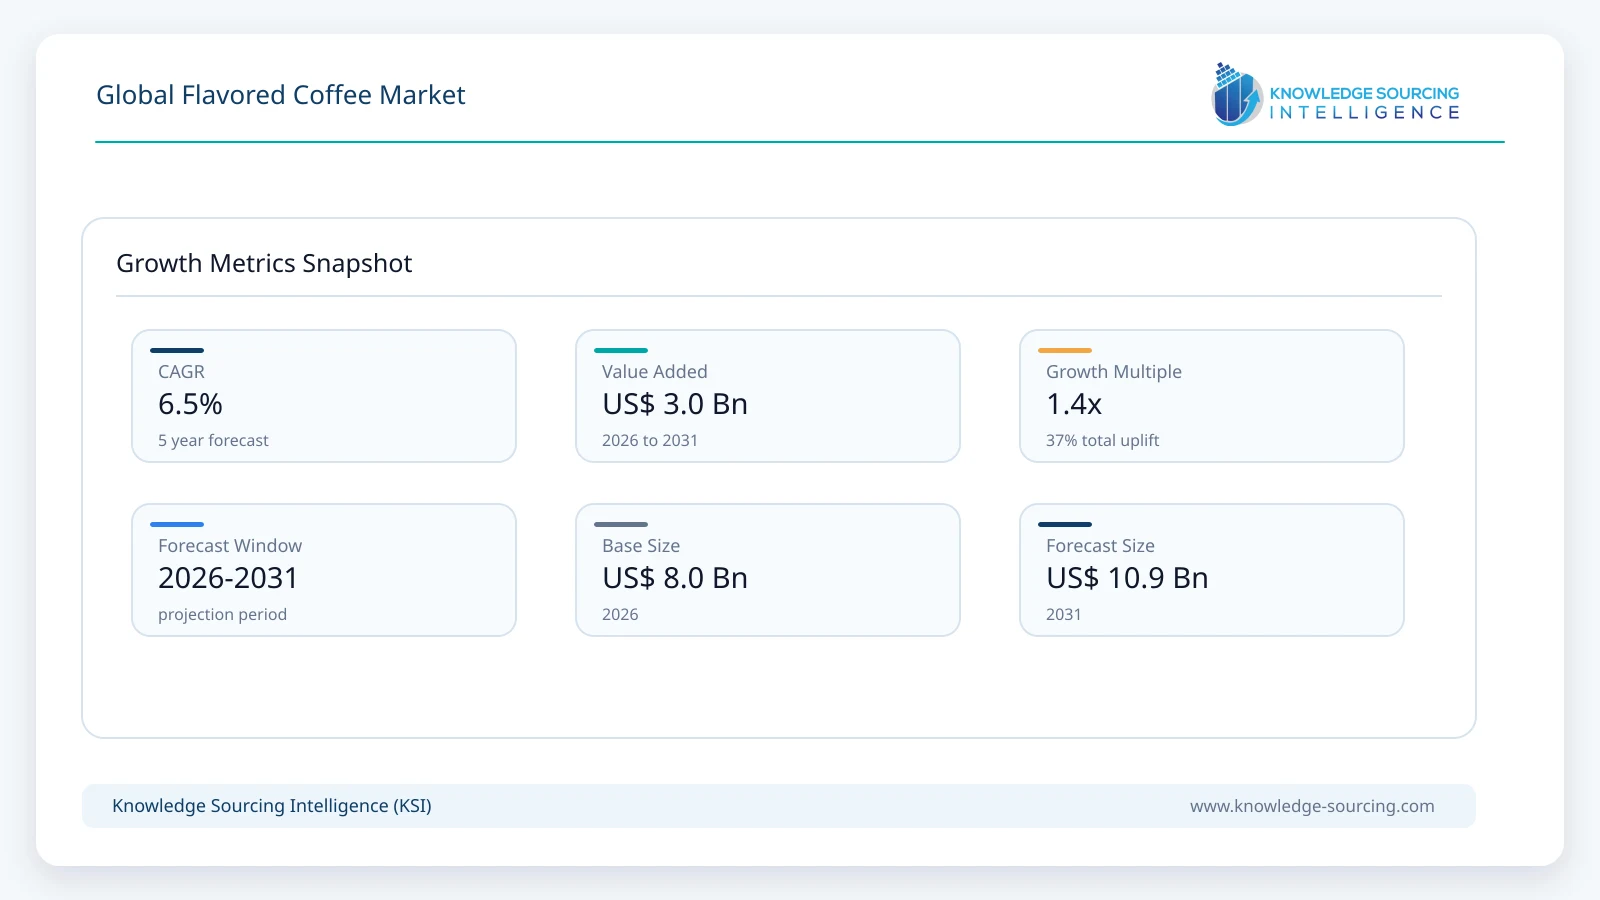
The Global Flavored Coffee market is forecast to grow at a CAGR of 6.5%, reaching USD 10.90 billion in 2031 from USD 7.95 billion in 2026.
Highlights:
- 1Ground coffee accounts for approximately 38% of market value in 2026, retaining the largest format because it combines established household penetration with broad flavor availability.
- 2Coffee pods and capsules are projected to expand at approximately 9.5% CAGR through 2031, supported by single-serve convenience and a high rate of flavor innovation.
- 3Vanilla represents approximately 28% of the market in 2026, retaining the largest individual flavor position because of its broad compatibility with roast profiles and milk-based preparation.
- 4Seasonal and dessert-inspired flavors are projected to grow at approximately 10.9% CAGR, supported by limited-edition launches and cross-brand collaborations.
- 5Off-trade channels account for approximately 73% of market value in 2026, reflecting the primarily packaged nature of the market and expansion of at-home brewing.
- 6Asia Pacific is projected to grow at approximately 9.4% CAGR, as flavored instant coffee, pods and premium at-home formats gain adoption in markets with expanding coffee cultures.
Growth is being driven less by the simple addition of flavor to conventional coffee and increasingly by the intersection of premiumization, single-serve convenience, café-inspired consumption and frequent product rotation. Vanilla and hazelnut remain core flavors, but caramel, dessert-inspired combinations and seasonal launches are increasing the amount of innovation within the category.
The market is also becoming more format-diverse. Flavored coffee now spans roast and ground products, instant coffee, whole bean products and single-serve pods, allowing manufacturers to address consumers across different price points and preparation methods. Starbucks currently markets flavored coffees including vanilla, caramel, mocha and seasonal combinations across ground coffee and K-Cup formats, while Nespresso maintains flavored capsule ranges built around vanilla, caramel, chocolate and hazelnut profiles. Keurig Dr Pepper is using its K-Cup ecosystem to introduce co-branded and dessert-inspired flavors such as Pop-Tarts Brown Sugar Cinnamon, creating additional consumption occasions around indulgence rather than traditional morning coffee alone.
The category is particularly suited to at-home premiumization because flavor provides a relatively accessible route to experimentation. Consumers can obtain café-inspired or dessert-oriented profiles without purchasing syrups, visiting a coffee shop or developing advanced brewing skills. This positioning supports flavored pods and ground coffee in mature markets while creating opportunities for flavored instant products in markets where soluble coffee remains structurally important.
Raw coffee economics nevertheless remain important. The Food and Agriculture Organization reported that world coffee prices increased 38.8% in 2024 as adverse weather and supply constraints affected major producing countries, while the International Coffee Organization continues to record significant price volatility through 2026. Flavored-coffee manufacturers therefore need to balance premium product positioning against volatile underlying Arabica and Robusta costs.
Market Growth Drivers and Trends
Seasonal Flavor Rotation Is Increasing Purchase Frequency
Flavor rotation has become a core merchandising strategy rather than an occasional promotional activity. Starbucks’ 2026 at-home portfolio includes White Chocolate Macadamia and Vanilla Lavender alongside returning seasonal flavors, while its autumn lineup includes Pumpkin Spice and Smoked Butterscotch in ground and K-Cup formats. This approach creates repeat purchase opportunities because consumers can move between permanent products and short-duration seasonal releases without changing the underlying brewing format.
The commercial implication is particularly important for the seasonal and dessert-inspired segment. Limited availability creates urgency, while familiar dessert or café references reduce the risk associated with trying unfamiliar coffee flavors. KSI therefore expects this segment to gain share faster than traditional vanilla and hazelnut even though those established flavors remain substantially larger.
Single-Serve Systems Are Becoming Important Flavor-Innovation Platforms
Single-serve coffee provides manufacturers with a particularly efficient format for flavor experimentation because households can purchase multiple varieties without committing to a full bag of ground coffee. Keurig Dr Pepper continues to use K-Cup pods for partnerships and flavor launches, including collaborations involving SNICKERS, TWIX, Cinnamon Toast Crunch and Pop-Tarts. Its 2026 beverage-trend work also indicates particularly strong flavored-coffee participation among younger consumers.
The platform effect extends beyond KDP’s own brands. In April 2026, Keurig Dr Pepper and Nestlé renewed and expanded their agreement covering Starbucks K-Cup pods in the United States and Canada, specifically identifying continued innovation across Starbucks blends, roasts and flavored coffees. This supports KSI’s expectation that pods and capsules will gain market share through 2031.
Café-Inspired Flavors Are Moving Further Into the Home
Consumers increasingly expect packaged coffee to reproduce flavor experiences previously associated with cafés. Dessert, latte and seasonal profiles are now appearing across ground coffee, instant coffee and pods rather than remaining dependent on syrups added after brewing. Nestlé’s flavored soluble coffee development is a clear example: its Nescafé products in Europe combine caramel or hazelnut with soluble coffee that can be prepared hot or cold, while Nespresso’s Barista Creations range incorporates vanilla, caramel, chocolate and hazelnut directly into capsule products.
This trend strengthens packaged flavored coffee because manufacturers can deliver a more complete sensory proposition within the coffee itself. It also makes flavor an important method of differentiating products in categories such as instant coffee, where technology and roast differences may otherwise be less visible to mainstream consumers.
Branded Food Collaborations Are Expanding Dessert-Inspired Coffee
Cross-category collaborations are introducing recognizable food and confectionery brands into coffee. Keurig Dr Pepper’s Original Donut Shop portfolio includes branded K-Cup collaborations with Pop-Tarts and other established snack brands, allowing consumers to recognize the intended flavor before trying the coffee. The strategy reduces discovery friction and turns flavored coffee into part of a broader treat occasion rather than positioning it only as a beverage staple.
This is particularly supportive of younger consumers who rotate across beverage categories and are more receptive to novelty. KSI expects collaborations to remain concentrated in pods and other convenient formats where limited-edition products can be introduced and removed relatively quickly.
At-Home Premiumization Supports Higher-Value Flavored Formats
Premiumization remains important because flavored coffee increasingly competes with the coffeehouse experience rather than with plain commodity coffee alone. Nestlé identifies coffee as one of its major growth businesses and highlights customization, premiumization and the creation of additional coffee-drinking occasions as important strategic priorities. Its portfolio across Nescafé, Nespresso and Starbucks allows the company to address flavored coffee through instant, capsule and roast-and-ground formats at different price levels.
The effect is particularly important in pods, capsules and premium ground coffee, where consumers are already accustomed to paying a higher price per serving. Flavor therefore contributes to value growth even when overall household coffee consumption is relatively mature.
Market Restraints
Coffee-Bean Price Volatility Compresses Flavored Product Margins
Flavored coffee still depends on the economics of the underlying coffee bean. FAO reported a 38.8% increase in world coffee prices during 2024, with Arabica and Robusta both experiencing substantial price escalation due largely to adverse production conditions. The ICO continued to record significant price volatility in 2026, including sharp month-to-month movements.
Manufacturers therefore face a difficult pricing decision. Passing higher bean costs through to consumers can weaken demand, while absorbing them reduces the margin available to fund flavor development, packaging and promotion. The problem is particularly relevant to premium flavored Arabica products.
Consumer Customization Can Substitute for Pre-Flavored Coffee
Flavored coffee competes not only with plain coffee but also with a large ecosystem of syrups, creamers, milk alternatives and other additions that allow consumers to customize ordinary coffee themselves. This is especially relevant in cafés and households with espresso equipment, where flavor can be added after brewing. Manufacturers of pre-flavored coffee therefore need to offer convenience or a distinctive integrated flavor profile rather than assuming that demand for flavored beverages automatically translates into demand for flavored beans or pods.
Rapid Seasonal Rotation Creates Inventory Risk
Seasonal innovation drives attention but also creates forecasting complexity. Pumpkin, peppermint, lavender and dessert-based products can experience highly concentrated demand windows, and unsold inventory becomes less attractive once the relevant season or promotion ends. Brands with large distribution footprints must therefore balance enough inventory to create visibility with the risk of markdowns or obsolete stock.
The risk becomes greater as companies expand the number of limited-edition SKUs. Product rotation supports category engagement, but excessive fragmentation can reduce manufacturing efficiency and complicate retailer inventory management.
Flavor Authenticity and Ingredient Expectations Are Increasing
Consumers are becoming more attentive to ingredient lists and the distinction between natural and artificial flavors. Starbucks, for example, explicitly identifies natural flavors in several current flavored-coffee products, while Nestlé’s 2024 soluble launches were positioned around natural flavoring and no added sugar.
This increases formulation pressure because flavor needs to remain recognizable after roasting, grinding, brewing and milk addition while also meeting clean-label expectations. Premium brands therefore need more sophisticated flavor systems than low-cost products that rely primarily on strong sweet or artificial notes.
Single-Serve Growth Faces Packaging and Sustainability Pressure
Pods and capsules provide one of the strongest growth opportunities in flavored coffee, but they also create packaging challenges. Manufacturers are investing in recyclable, compostable or reduced-material systems to address regulatory and consumer concerns. Nestlé’s Nescafé Dolce Gusto NEO system, for example, uses home-compostable paper-based pods in selected markets, indicating that packaging innovation is becoming part of the competitive proposition.
For flavored-coffee suppliers, this means that growth in pods may require parallel investment in material redesign and compatibility rather than simply launching additional flavors.
Flavored Coffee Market Segmentation Analysis
By Type
Whole Bean
Whole-bean flavored coffee remains a smaller premium segment and is projected to represent approximately 12% of market value by 2031. The format appeals to consumers who grind coffee immediately before brewing but faces a structural tension: specialty-coffee enthusiasts often prefer natural origin and roast characteristics rather than added flavor. Whole-bean flavored products therefore remain relevant but grow more slowly than convenience-oriented flavored formats.
Ground Coffee
Ground coffee retains the largest position, accounting for approximately 38% of market value in 2026. The format combines widespread brewing compatibility with relatively low switching costs, allowing manufacturers to introduce flavored variants without requiring consumers to purchase proprietary equipment. Starbucks maintains vanilla, caramel, mocha and seasonal ground offerings, while Keurig Dr Pepper expanded The Original Donut Shop into bagged ground coffee in 2025 after building a strong position in flavored single-serve products.
Ground coffee remains important through 2031, although it loses modest share as pods and capsules expand faster.
Instant Coffee
Instant flavored coffee is projected to expand at approximately 5.5% CAGR. The format is particularly relevant in markets where soluble coffee already has high penetration and where consumers value convenience over more complex brewing. Nestlé’s launch of caramel and hazelnut Nescafé Classic products that dissolve in both hot and cold water illustrates how manufacturers are adding flavor innovation to a category traditionally associated with functional convenience.
Coffee Pods and Capsules
Pods and capsules are projected to grow at approximately 9.5% CAGR through 2031, making them the fastest-growing major format in the KSI model. Single-serve architecture is particularly well suited to flavor because households can maintain several varieties simultaneously and switch by occasion without opening multiple bags of coffee.
The current product environment supports this assumption. Starbucks flavored coffees are available in K-Cup and Nespresso-compatible formats, Nespresso maintains dedicated flavored capsule ranges, and KDP continues to use the K-Cup ecosystem for new dessert and co-branded products.
By Flavor Type
Vanilla
Vanilla remains the largest individual flavor with approximately 28% share in 2026. Its broad appeal reflects compatibility with different roast profiles, milk and cold preparation while avoiding the stronger sweetness associated with some dessert flavors. Starbucks, Nespresso and Nescafé all maintain vanilla-flavored coffee offerings, supporting its role as a core rather than seasonal flavor.
Hazelnut
Hazelnut is projected to grow at approximately 5.6% CAGR and remains another established flavor with broad recognition. Nespresso’s Nocciola and Nestlé’s hazelnut soluble products demonstrate its presence across both capsule and instant formats. The flavor is particularly resilient because it can be positioned as either mainstream indulgence or premium nut-derived inspiration.
Caramel
Caramel gains modest share and is projected to expand at approximately 7.7% CAGR. Its growth is being supported by café-inspired beverages and its adaptability across hot, iced and milk-based coffee. Nestlé has extended caramel across multiple coffee formats, while Nespresso maintains dedicated caramel capsule offerings.
Seasonal and Dessert-Inspired Flavors
Seasonal and dessert-inspired products are projected to expand at approximately 10.9% CAGR, the fastest rate within the flavor segmentation. Starbucks’ White Chocolate Macadamia, Vanilla Lavender, Pumpkin Spice and Smoked Butterscotch products demonstrate how seasonal rotation supports repeated launches, while KDP’s Pop-Tarts Brown Sugar Cinnamon product shows how coffee is increasingly borrowing recognizable profiles from adjacent food categories.
Distribution Channel Analysis
Off-trade distribution represents approximately 73% of market value in 2026 because the study focuses on packaged flavored coffee rather than finished café drinks. Supermarkets, mass retailers, club stores, specialty grocery, e-commerce and direct-to-consumer channels therefore account for most commercial sales.
Online retail is becoming increasingly important within this structure because flavor experimentation benefits from broad assortment and easy comparison. Limited-edition products can also be introduced digitally before receiving full national retail distribution, as demonstrated by recent KDP launches.
On-trade demand remains relevant where cafés and hospitality operators use flavored beans or packaged products, but many flavored café beverages are created by adding syrups to regular coffee after brewing. KSI therefore expects on-trade to remain a smaller portion of the specifically pre-flavored coffee market.
Geographical Outlook
North America
North America accounts for approximately 42% of market value in 2026 and remains the largest regional market. The United States has a particularly developed packaged-coffee sector, high penetration of single-serve systems and a strong seasonal-flavor culture. Starbucks and Keurig Dr Pepper continuously introduce flavored products in K-Cup and ground formats, giving the region a higher level of SKU rotation than many other markets.
Europe
Europe is projected to grow at approximately 5.7% CAGR. Traditional coffee cultures in countries such as Italy and Germany can favor unflavored espresso and roast-and-ground coffee, but flavored instant coffee, capsules and milk-oriented products provide growing opportunities, particularly among younger consumers. Nestlé’s recent flavored soluble launches and Nespresso’s dessert-inspired capsules demonstrate continued investment in the region.
Asia Pacific
Asia Pacific is projected to expand at approximately 9.4% CAGR, making it the fastest-growing major region in the KSI model. Coffee culture is expanding alongside cafés, e-commerce and premium at-home consumption in markets such as China, India and South Korea, while Japan and Australia already have mature coffee cultures. Flavored instant and single-serve products provide an accessible route for newer consumers who may enter the coffee category through sweeter or café-inspired profiles.
South America and the Middle East & Africa remain smaller but meaningful markets. South America benefits from proximity to major coffee-producing countries and established domestic consumption, while urban café expansion and younger consumer demographics create flavored-coffee opportunities across parts of the Middle East.
Key Developments
August 2026: Starbucks introduced its 2026 autumn at-home range, including Pumpkin Spice Flavored Coffee and Smoked Butterscotch Flavored Coffee across packaged formats. The rollout supports the KSI assumption that seasonal and dessert-inspired flavors will grow faster than traditional flavor categories because limited-edition rotation creates incremental purchase occasions.
April 2026: Keurig Dr Pepper and Nestlé USA renewed and expanded their Starbucks K-Cup partnership in the United States and Canada, including programs focused on distribution and product innovation. The agreement directly reinforces KSI’s higher growth assumption for flavored pods and capsules because Starbucks flavored coffees continue to be distributed through the Keurig ecosystem.
March 2026: The Original Donut Shop expanded its flavored K-Cup portfolio with Pop-Tarts Brown Sugar Cinnamon coffee following existing collaborations involving SNICKERS, TWIX and Cinnamon Toast Crunch. The launch supports the modeled faster growth of dessert-inspired flavors and shows how branded food collaborations are becoming a repeatable innovation mechanism rather than isolated promotions.
2026 Spring Season: Starbucks expanded its seasonal at-home portfolio with White Chocolate Macadamia and Vanilla Lavender flavored coffee. Both are sold in packaged formats, including ground coffee and K-Cup pods, supporting the continued importance of flavor rotation across multiple preparation systems.
May 2025: Keurig Dr Pepper expanded The Original Donut Shop from K-Cup pods into bagged ground coffee, noting that the brand had been a leading contributor to share growth in flavored single-cup coffee. The development supports KSI’s view that successful single-serve flavor concepts are increasingly being extended into traditional ground-coffee formats.
November 2024: Nestlé launched Nescafé Classic soluble coffee in caramel and hazelnut flavors for hot or cold preparation in Central and Eastern Europe. The product demonstrates that flavor innovation is broadening beyond ground coffee and capsules into mainstream soluble formats, supporting continued growth in flavored instant coffee.
Competitive Environment
Competition is increasingly organized around format breadth, flavor-development capability, seasonal speed and distribution access. Nestlé has unusual breadth because its Nescafé, Nespresso and licensed Starbucks consumer packaged-goods portfolio spans instant, capsules and packaged roast-and-ground coffee. Keurig Dr Pepper has a different advantage through the installed base of Keurig brewing systems and its ability to combine owned brands, licensed brands and partnership-driven K-Cup innovation.
Starbucks remains one of the strongest flavor trend setters in packaged coffee because café flavors can migrate into at-home products, while JDE Peet’s, Lavazza, Tchibo, Strauss and other established coffee businesses compete through brand heritage, roasting capabilities and regional distribution. Smaller flavored-coffee specialists compete by offering wider or more unconventional flavor assortments than multinational companies can economically maintain.
The market therefore remains fragmented below the leading global platforms. Competitive advantage increasingly depends on the ability to identify emerging flavors, scale winning products quickly, manage limited-edition inventory and support products across multiple brewing formats.
Flavored Coffee Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 7.95 billion |
| Total Market Size in 2031 | USD 10.90 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Flavor Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Type
Whole Bean
Ground Coffee
Instant Coffee
Coffee Pods & Capsules
By Flavor Type
Vanilla
Hazelnut
Caramel
Chocolate/Mocha
Seasonal & Dessert-Inspired
Others
By Distribution Channel
On-Trade
Off-Trade
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Rest of Europe
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Rest of Middle East and Africa
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Rest of Asia Pacific
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Seasonal Flavor Rotation Increasing Repeat Purchase Occasions
3.1.2. Single-Serve Systems Becoming Platforms for Flavor Innovation
3.1.3. Café-Inspired Flavors Moving into At-Home Coffee
3.1.4. Branded Food Collaborations Expanding Dessert-Inspired Coffee
3.1.5. At-Home Premiumization Supporting Higher-Value Flavored Formats
3.2. Market Restraints
3.2.1. Coffee-Bean Price Volatility Compressing Flavored Product Margins
3.2.2. Consumer Customization with Syrups and Creamers Substituting for Pre-Flavored Coffee
3.2.3. Seasonal SKU Rotation Creating Inventory and Forecasting Risk
3.2.4. Increasing Flavor-Authenticity and Ingredient Expectations
3.2.5. Packaging and Sustainability Pressure on Single-Serve Coffee Formats
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Flavor Encapsulation and Aroma Retention
4.2. Hot-and-Cold Soluble Coffee Technology
4.3. Single-Serve Pod and Capsule Technology
4.4. Natural Flavor Systems
4.5. Sustainable Single-Serve Packaging
5. GLOBAL FLAVORED COFFEE MARKET BY TYPE
5.1. Introduction
5.2. Whole Bean
5.3. Ground Coffee
5.4. Instant Coffee
5.5. Coffee Pods & Capsules
6. GLOBAL FLAVORED COFFEE MARKET BY FLAVOR TYPE
6.1. Introduction
6.2. Vanilla
6.3. Hazelnut
6.4. Caramel
6.5. Chocolate/Mocha
6.6. Seasonal & Dessert-Inspired
6.7. Others
7. GLOBAL FLAVORED COFFEE MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. On-Trade
7.3. Off-Trade
8. GLOBAL FLAVORED COFFEE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Rest of South America
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Rest of Europe
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. South Africa
8.5.4. Rest of Middle East and Africa
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Australia
8.6.6. Indonesia
8.6.7. Rest of Asia Pacific
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Nestlé S.A.
10.2. Starbucks Corporation
10.3. Keurig Dr Pepper Inc.
10.4. JDE Peet’s N.V.
10.5. Luigi Lavazza S.p.A.
10.6. Tchibo GmbH
10.7. Strauss Coffee B.V.
10.8. The J.M. Smucker Company
10.9. The Kraft Heinz Company
10.10. Tata Consumer Products Limited
10.11. Tim Hortons Inc.
10.12. Massimo Zanetti Beverage Group
10.13. Community Coffee Company, L.L.C.
10.14. New England Coffee
10.15. Cameron’s Coffee
10.16. Trilliant Food & Nutrition, LLC
10.17. Lifeboost Coffee
10.18. Bones Coffee Company
10.19. Coffee Beanery
10.20. Door County Coffee & Tea Co.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for the Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











