
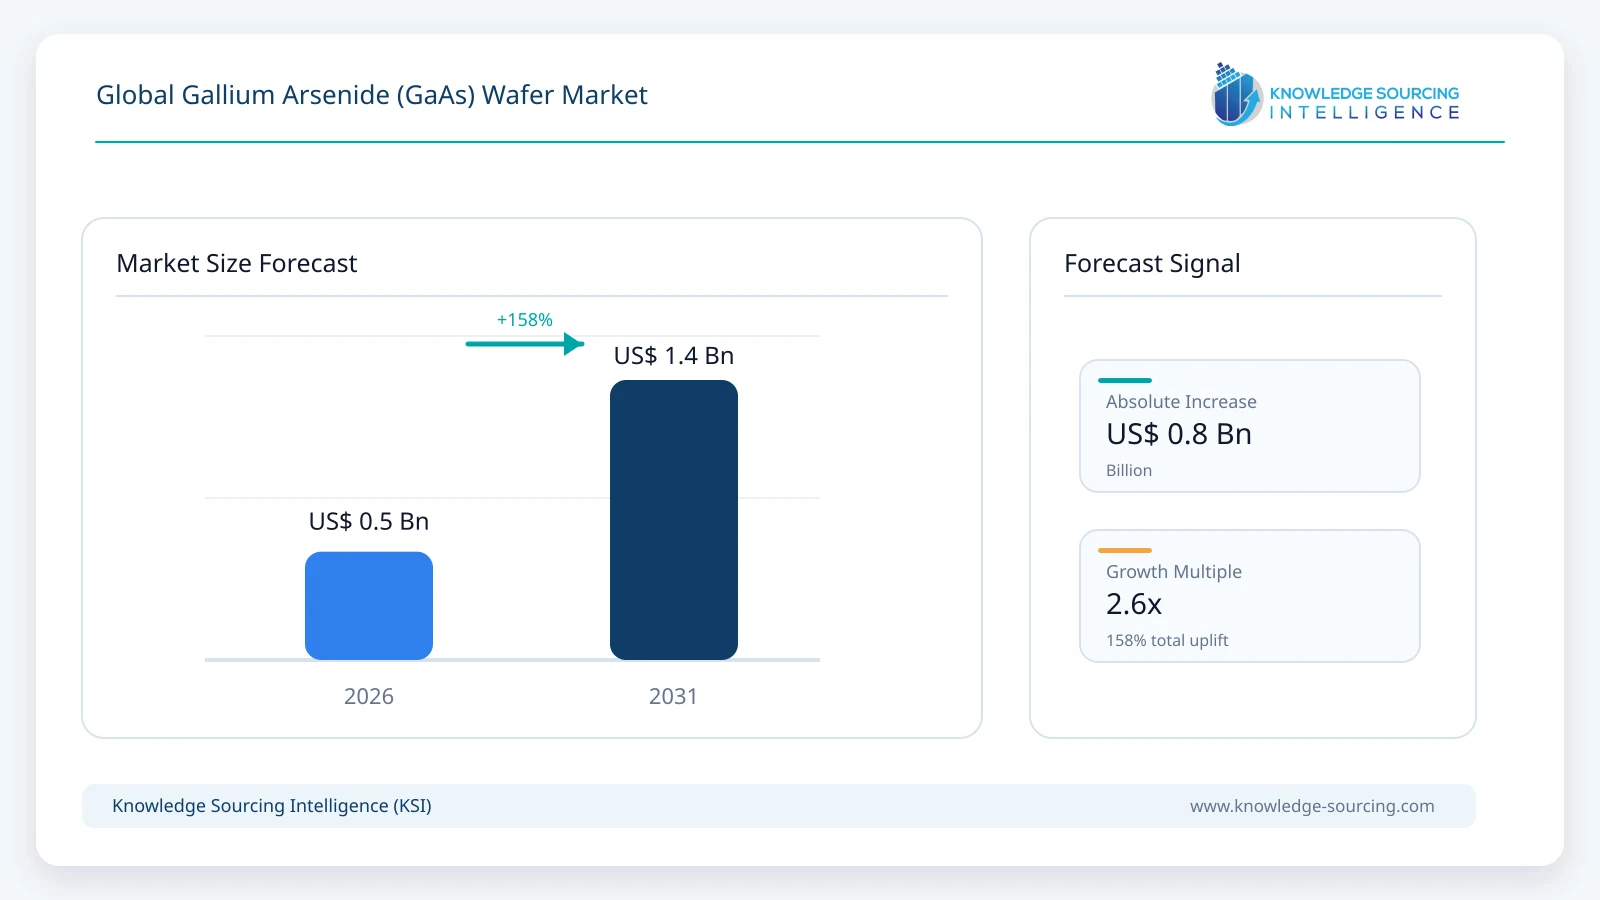
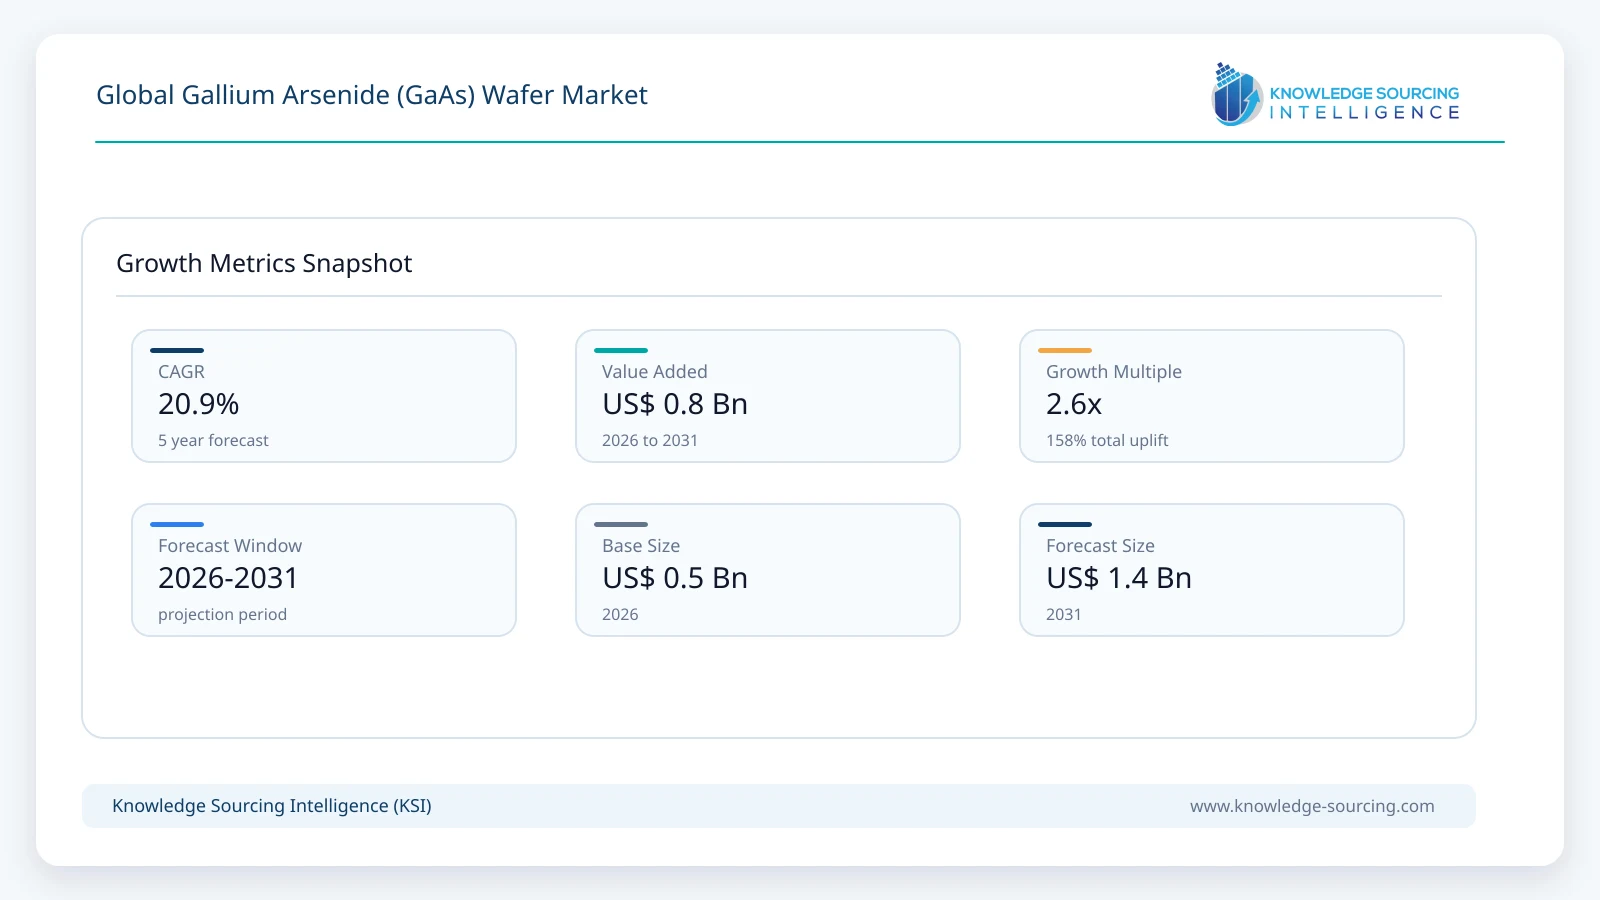
The GaAs wafer Market is forecast to grow at a CAGR of 11.3%, reaching USD 905.0 million in 2031 from USD 530.0 million in 2026.
Highlights:
- 1Semi-insulating wafers account for approximately 58% of global GaAs wafer revenue in 2026.
- 2Asia Pacific contributes roughly 57% of market value through concentrated RF and optoelectronics manufacturing.
- 3Six-inch wafers remain the commercial volume center, while eight-inch availability supports future cost reduction.
- 4AXT reported USD 6.6 million of GaAs revenue in Q2 2026, led by improving semiconducting-wafer demand.
- 5Vital Materials announced a USD 300 million InP and GaAs wafer facility in July 2026.
- 6VCSEL-based optical interconnects are creating a new AI-infrastructure demand channel for GaAs substrates.
Market Overview
GaAs remains commercially important because its direct bandgap, high electron mobility and mature III-V device ecosystem enable functions that are difficult to reproduce economically on silicon. Semi-insulating GaAs substrates are widely used beneath HBT, pHEMT and other RF device structures, while semiconducting wafers support VCSELs, LEDs, lasers, detectors and specialized photovoltaic devices. Freiberger Compound Materials supplies both semi-insulating and semiconducting GaAs wafers and identifies HBT, pHEMT, LED, laser, detector and solar applications across its VGF and LEC product range. AXT similarly supplies GaAs substrates from 1-inch through 8-inch diameters for cell-phone power amplifiers, VCSELs, 3D sensing, microLEDs, LiDAR and RF devices.
Commercial demand is not uniform across applications. AXT's 2025 annual report stated that GaAs revenue declined slightly during the year and described lower wireless and LED demand in several regions, even as selected applications improved. The pattern shifted in 2026: AXT reported USD 6.6 million of GaAs revenue in the second quarter, up from USD 5.4 million in the first quarter, with sequential growth in semiconducting wafers for industrial robotics and data-center laser applications and continuing demand for semi-insulating RF wafers. This evidence supports a recovery and diversification story, but not the same step-change growth profile that InP is experiencing from high-speed optical transceivers.
Supply is also becoming more competitive. In July 2026, Vital Materials announced a planned RMB 2 billion, approximately USD 300 million, InP and GaAs wafer production facility in Quzhou, China, designed for 4- to 6-inch products and a combined annual capacity of six million wafers. China Crystal Technologies already operates large GaAs wafer capacity and states that its Xinzhou facility can produce 200,000 4-inch wafers per month. Freiberger offers 150 mm and 200 mm semi-insulating VGF wafers, demonstrating that the market is moving beyond legacy 3- and 4-inch formats where device economics justify larger substrates.
Market Trends
AI Optical Interconnects Are Creating a New VCSEL Demand Channel
GaAs-based VCSELs are gaining a new role in short-reach optical links for AI infrastructure. Lumentum demonstrated a high-density 1060 nm VCSEL array for next-generation scale-up networks at OFC 2026, while Broadcom showcased 200G-per-lane VCSEL and near-packaged-optics technologies for AI clusters. IQE's September 2026 interim update also reported qualifications in GaAs-based optical-interconnect technologies for AI and data-center markets. This does not make GaAs the dominant material for long-haul data-center optics, where InP remains stronger, but it creates a credible incremental market for laser-grade semiconducting GaAs substrates.
Six-Inch Wafers Are Becoming the Commercial Center of Gravity
Larger wafer diameters improve device output per processed wafer and can lower unit manufacturing cost when epitaxy and fab equipment are compatible. Six-inch GaAs is established across RF and optoelectronic manufacturing, while 8-inch products are available from selected suppliers for applications including HBT and pHEMT structures. Freiberger lists both 150 mm and 200 mm semi-insulating VGF wafers, and AXT offers GaAs substrates through 8-inch diameter. Migration is slower than in silicon because compound-semiconductor fabs have long-lived equipment sets and qualification cycles, but larger diameters become more attractive as device volumes rise.
VGF Is Gaining Importance Where Low Defect Density Matters
Crystal-growth technique directly affects defect density, electrical uniformity and device yield. Freiberger describes VGF material as well suited to high-current-density devices including HBTs, LEDs and lasers because of its low axial thermal gradient and low dislocation density, while LEC remains useful for larger-area RF devices such as MESFETs and pHEMTs. As VCSEL, laser and advanced RF applications become more demanding, substrate suppliers are competing increasingly on defect control and epi-ready surface quality rather than simply on wafer availability.
GaN Is Taking Share in High-Power RF but Not Replacing GaAs Across RF
GaAs faces increasing competition from RF GaN, particularly in base stations, radar, satellite communications and other applications requiring high output power. GlobalFoundries is scaling RF GaN-on-silicon as a 200 mm manufacturing platform, illustrating the cost and power-performance pressure on GaAs. However, GaAs remains well established in handset power amplifiers, Wi-Fi front ends and many lower-power RF applications where mature HBT and pHEMT processes offer strong linearity, efficiency and manufacturing economics. The market therefore evolves through application segmentation rather than direct one-for-one substitution.
Market Drivers
RF Front-End Demand Sustains the Largest Established GaAs Substrate Base
Wireless devices continue to provide the largest established commercial base for semi-insulating GaAs. Smartphone power amplifiers, Wi-Fi components, satellite terminals and selected infrastructure devices rely on GaAs HBT and pHEMT technologies where high-frequency efficiency and linearity are critical. Freiberger identifies wireless communication as a core application for its GaAs substrates, while Sumitomo Electric supplies GaAs FETs and MMICs for radar, base stations, SATCOM and point-to-point systems. Growth is moderated by smartphone maturity and GaN competition, but higher RF complexity per device and expanding satellite connectivity support continued wafer demand.
VCSELs, Robotics and Sensing Broaden Semiconducting-Wafer Demand
Semiconducting GaAs wafers support VCSELs, laser diodes and detectors used in 3D sensing, industrial robotics, LiDAR, optical links and machine vision. AXT reported sequential growth in semiconducting GaAs wafers for industrial robotics and data-center laser applications in Q2 2026. The importance of these applications is not only their growth rate but their substrate quality requirements: laser-grade wafers demand low defect densities and highly consistent surfaces, supporting premium pricing and qualification-based supplier relationships.
China's Compound-Semiconductor Investment Expands Production and Downstream Demand
China is simultaneously a major supplier and consumer of GaAs substrates. China Crystal Technologies has built large-volume GaAs crystal and wafer capacity, Yunnan Xinyao supplies 2- to 6-inch RF- and laser-grade products, and Vital Materials is planning a new multi-million-wafer facility. Domestic RF, LED, microLED and photonics production creates downstream demand, while government emphasis on semiconductor supply-chain localization supports investment in materials and crystal-growth capability. The resulting scale places continued cost pressure on higher-cost Western suppliers but also expands the total addressable production ecosystem.
Market Restraints
GaN Competition, Cyclical Wireless Demand and Qualification Barriers Limit Growth
GaAs is not a universal high-frequency material. RF GaN is taking share in higher-power infrastructure, radar and defense applications, while silicon-based RF technologies continue to improve in cost-sensitive functions. GaAs wafer demand is also exposed to consumer-electronics cycles: AXT reported weaker GaAs sales in several wireless and LED markets during 2025 and mixed regional demand through the first half of 2026. Supplier switching is difficult because substrate quality affects epitaxial yield and device performance, so new capacity does not translate immediately into qualified commercial share. Arsenic handling and environmental controls further raise manufacturing complexity relative to silicon.
Segment Analysis
By Electrical Type - Semi-Insulating GaAs Wafer
Semi-insulating GaAs remains the largest electrical-type segment because it is the preferred substrate for many RF HBT, pHEMT, MESFET and MMIC processes. High resistivity reduces parasitic conduction and supports high-frequency device isolation. Demand is linked to handset RF front ends, Wi-Fi, satellite communications, radar and selected infrastructure applications. Semiconducting n-type and p-type wafers are smaller in current value but are expected to grow faster as VCSEL, laser, robotics, sensing and display applications expand.
By Wafer Diameter - 150 mm / 6 Inch
Six-inch wafers are estimated at approximately USD 238.5 million in 2026, making them the largest diameter segment by value. The format provides a strong balance between available crystal quality, established epitaxy equipment and device output per wafer. Four-inch products remain important in legacy and specialized lines, while 8-inch GaAs is emerging where production scale justifies the larger format. Migration remains slower than silicon because device fabs must requalify processes, tooling and epitaxial uniformity across the larger substrate.
By Manufacturing Technique - Vertical Gradient Freeze
VGF-grown wafers are estimated at approximately USD 339.2 million in 2026 and represent the largest manufacturing-technique segment. The method supports low dislocation density and strong structural uniformity, making it particularly suitable for HBT, LED, laser and other high-current-density devices. LEC remains commercially relevant for semi-insulating and selected RF products because of its long manufacturing history and suitability for certain device architectures. Supplier portfolios increasingly use both methods selectively rather than treating one process as universally superior.
By Application - RF and Wireless Communication
RF and wireless applications are estimated at approximately USD 201.4 million in 2026 and remain the largest demand segment. Smartphone power amplifiers, Wi-Fi devices, satellite terminals and microwave components create a stable base for semi-insulating substrates. Optoelectronics is expected to grow faster through 2031 as VCSELs, laser diodes, machine vision and AI-scale short-reach optical links expand. LED demand remains material but more mature, while solar and aerospace applications support smaller high-value niches.
By Geography - Asia Pacific
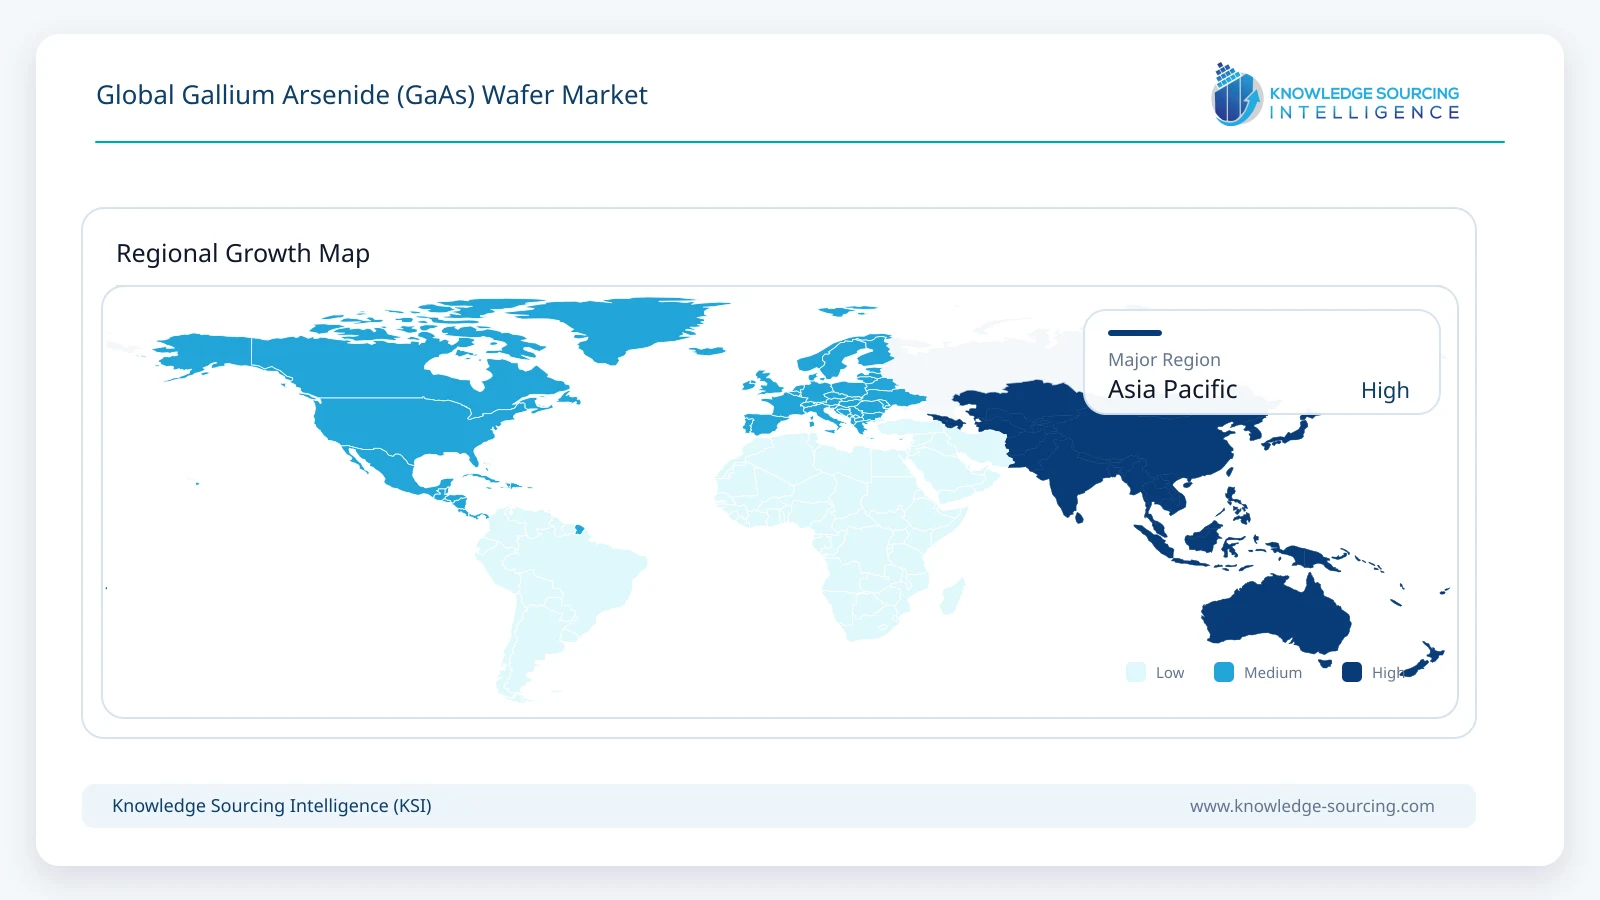
Asia Pacific is estimated at approximately USD 302.1 million in 2026 and remains the largest regional market. China, Taiwan, Japan and South Korea concentrate much of the world's RF, LED, laser and optoelectronics manufacturing, while China also has a rapidly expanding domestic substrate-supply base. North America remains strategically important through RF, aerospace, defense, VCSEL and photonics design activity, while Europe maintains high-quality substrate and device capability through companies and research ecosystems in Germany, the United Kingdom and France.
Competitive Environment
The GaAs substrate market is concentrated among specialist compound-semiconductor material suppliers rather than large silicon-wafer companies. Freiberger Compound Materials, AXT, Sumitomo Electric, Vital Materials and leading Chinese producers compete on crystal quality, defect density, electrical uniformity, diameter capability and customer qualification. China Crystal Technologies and Yunnan Xinyao strengthen China's domestic capacity, while Wafer Technology, an IQE subsidiary, provides a broader III-V substrate portfolio. The emergence of Vital Materials' planned Quzhou project adds another large-scale capacity investment to the Asian supply base.
Supplier differentiation is application-specific. RF customers prioritize semi-insulating electrical characteristics, uniformity and proven device yield; laser and VCSEL customers require very low defect densities and high surface quality; and larger-diameter users need tight flatness and thickness control across 150 mm or 200 mm substrates. Qualification cycles can be long because a substrate change affects epitaxy and downstream device performance. This gives incumbent suppliers durable customer relationships but also means announced capacity can take several years to convert into fully qualified revenue.
Recent Developments
July 2026: Vital Materials announced a roughly USD 300 million InP and GaAs wafer facility in Quzhou with planned combined capacity of six million 4- to 6-inch wafers annually.
July 2026: AXT reported USD 6.6 million of GaAs revenue in Q2, with sequentially stronger semiconducting-wafer demand for industrial robotics and data-center lasers.
March 2026: Lumentum demonstrated a high-density 1060 nm VCSEL optical-interconnect platform for next-generation AI scale-up networks.
March 2026: Broadcom showcased 200G-per-lane VCSEL and VCSEL-based near-packaged-optics technologies for large-scale AI infrastructure.
2026: IQE reported qualifications in GaAs-based optical-interconnect technologies for AI and data-center markets alongside its established wireless and sensing programs.
2026: Freiberger continued commercial availability of 150 mm and 200 mm semi-insulating VGF GaAs wafers for HBT, pHEMT and related applications.
GaAs Wafer Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 530.0 million |
| Total Market Size in 2031 | USD 905.0 million |
| Forecast Unit | Million |
| Growth Rate | 11.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Electrical Type, Wafer Diameter, Manufacturing Technique, Application, Geography |
| Companies |
|
Market Segmentation
Gallium Arsenide (GaAs) Wafer Market Segmentation:
By Electrical Type
Semi-Insulating GaAs Wafer
Semiconducting GaAs Wafer
By Wafer Diameter
Up to 3 Inch
4 Inch
6 Inch
8 Inch
By Manufacturing Technique
Vertical Gradient Freeze (VGF)
Liquid Encapsulated Czochralski (LEC)
Bridgman and Other Techniques
By Application
RF and Wireless Communication
VCSELs, Laser Diodes and Optoelectronics
LED and Display Applications
Solar Cells
Automotive and Industrial Sensing
Aerospace and Defense
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East & Africa
Israel
UAE
Saudi Arabia
Others
Asia Pacific
China
Japan
Taiwan
South Korea
India
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. RF Front-End Demand Sustains the Largest Established GaAs Substrate Base
3.1.2. VCSELs, Robotics and Sensing Broaden Semiconducting-Wafer Demand
3.1.3. China's Compound-Semiconductor Investment Expands Production and Downstream Demand
3.2. Market Restraints
3.2.1. GaN Competition, Cyclical Wireless Demand and Qualification Barriers Limit Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Semi-Insulating and Semiconducting GaAs
4.2. Vertical Gradient Freeze (VGF) Crystal Growth
4.3. Liquid Encapsulated Czochralski (LEC) Crystal Growth
4.4. Large-Diameter 150 mm and 200 mm GaAs Wafers
4.5. Epitaxy-Ready Surface Preparation and Defect Control
5. GLOBAL GALLIUM ARSENIDE (GAAS) WAFER MARKET BY ELECTRICAL TYPE
5.1. Introduction
5.2. Semi-Insulating GaAs Wafer
5.3. Semiconducting GaAs Wafer
6. GLOBAL GALLIUM ARSENIDE (GAAS) WAFER MARKET BY WAFER DIAMETER
6.1. Introduction
6.2. Up to 3 Inch
6.3. 4 Inch
6.4. 6 Inch
6.5. 8 Inch
7. GLOBAL GALLIUM ARSENIDE (GAAS) WAFER MARKET BY MANUFACTURING TECHNIQUE
7.1. Introduction
7.2. Vertical Gradient Freeze (VGF)
7.3. Liquid Encapsulated Czochralski (LEC)
7.4. Bridgman and Other Techniques
8. GLOBAL GALLIUM ARSENIDE (GAAS) WAFER MARKET BY APPLICATION
8.1. Introduction
8.2. RF and Wireless Communication
8.3. VCSELs, Laser Diodes and Optoelectronics
8.4. LED and Display Applications
8.5. Solar Cells
8.6. Automotive and Industrial Sensing
8.7. Aerospace and Defense
8.8. Others
9. GLOBAL GALLIUM ARSENIDE (GAAS) WAFER MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Others
9.5. Middle East & Africa
9.5.1. Israel
9.5.2. UAE
9.5.3. Saudi Arabia
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. Taiwan
9.6.4. South Korea
9.6.5. India
9.6.6. Australia
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Crystal-Growth and Wafer-Diameter Positioning
10.3. Capacity Expansion and Regional Supply
10.4. Qualification, Partnerships and Technology Development
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Freiberger Compound Materials GmbH
11.2. AXT, Inc.
11.3. Sumitomo Electric Industries, Ltd.
11.4. Vital Materials Co., Limited
11.5. China Crystal Technologies Co., Ltd.
11.6. Yunnan Xinyao Semiconductor Materials Co., Ltd.
11.7. IQE plc / Wafer Technology Ltd.
11.8. Xiamen Powerway Advanced Material Co., Ltd.
11.9. Semiconductor Wafer, Inc.
11.10. Xinxiang Shenzhou Crystal Technology Co., Ltd.
11.11. Qingdao Jiaying Semiconductor Co., Ltd.
11.12. IntelliEPI Inc.
11.13. Visual Photonics Epitaxy Co., Ltd.
11.14. LandMark Optoelectronics Corporation
11.15. Sumitomo Chemical Co., Ltd.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











