
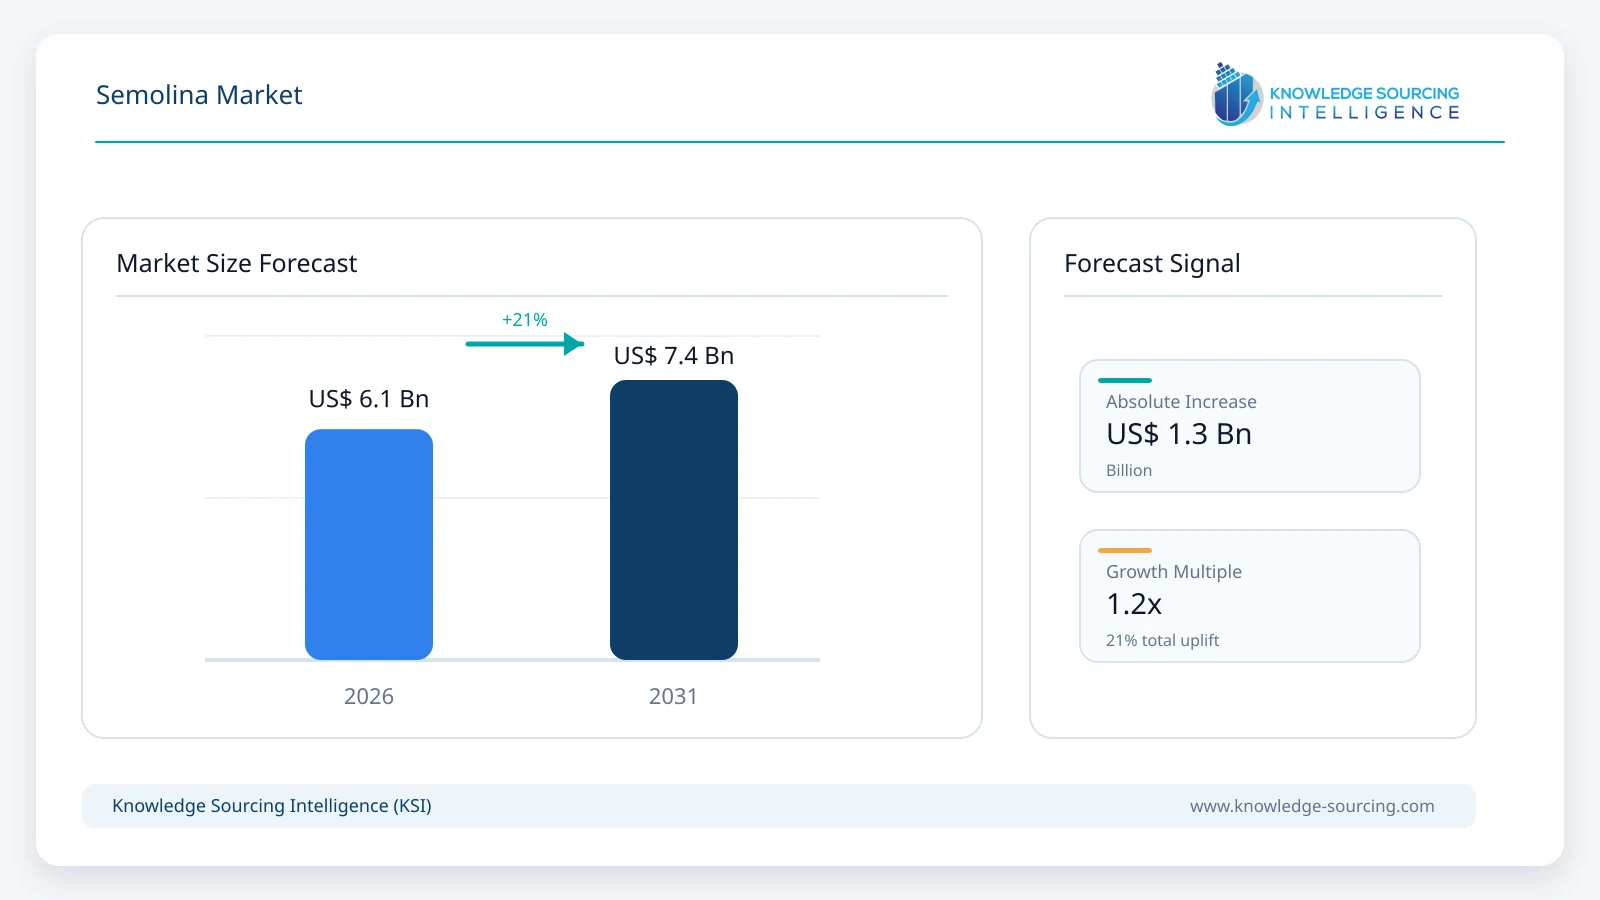
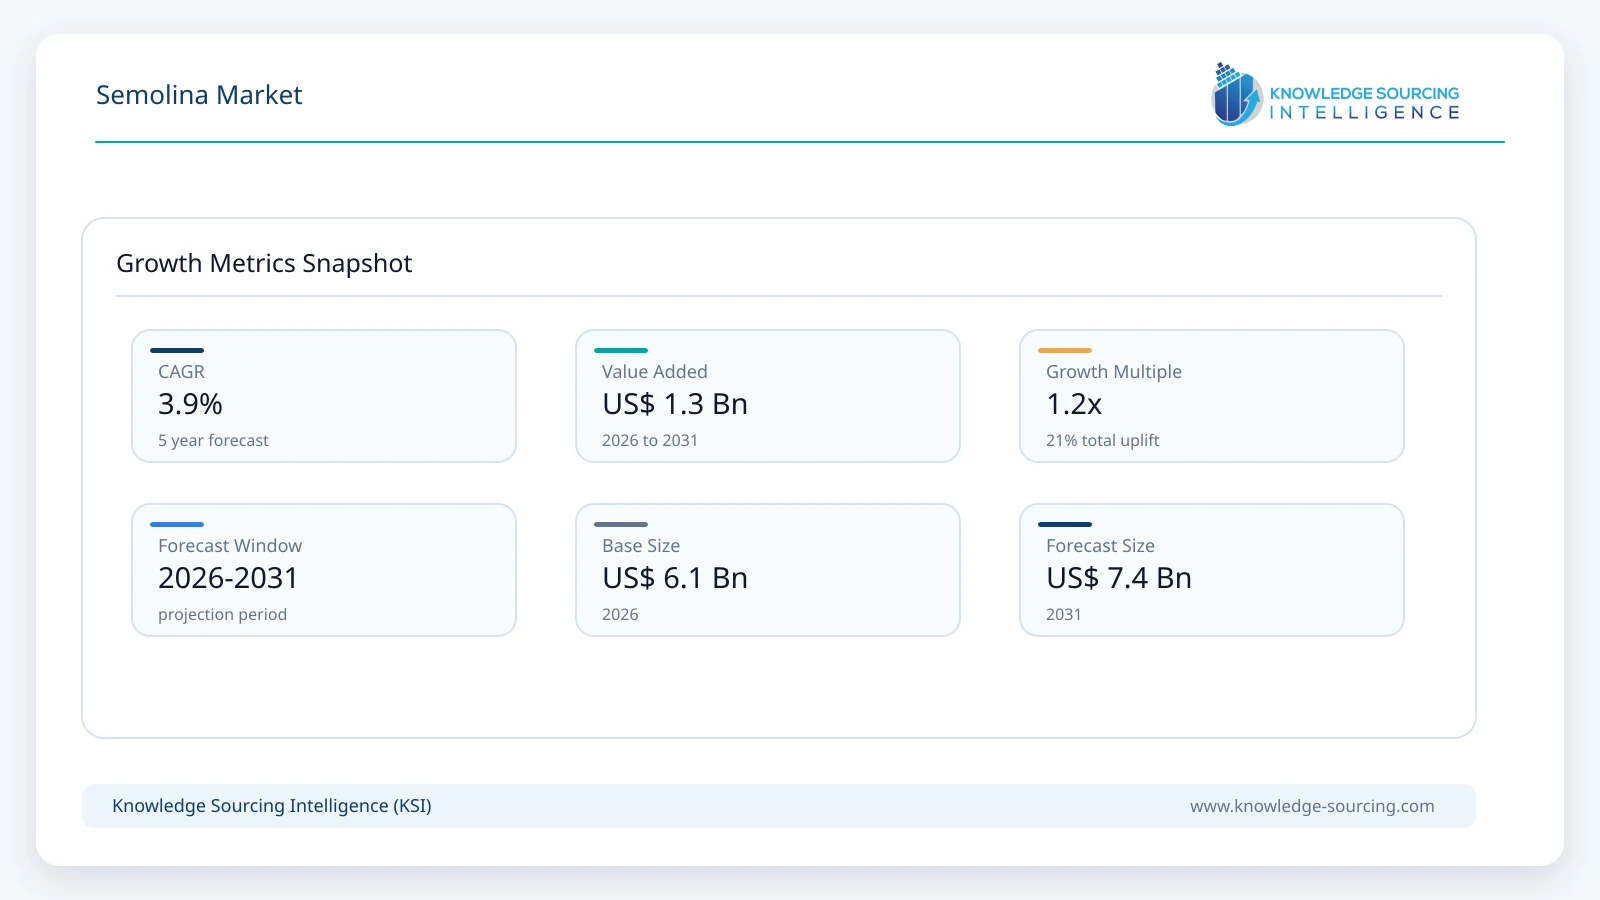
The global semolina market is expected to grow from USD 6.1 billion in 2026 to USD 7.4 billion by 2031, at a CAGR of 3.9% during the forecast period.
Highlights:
- 1Largest End-UserIndustrial pasta manufacturers remain the dominant end-user segment, as semolina's high gluten density is non-negotiable for producing shelf-stable, high-quality dry pasta that maintains texture during cooking.
- 2Regulatory ImpactMandatory country-of-origin labeling (COOL) in Italy and similar transparency initiatives in the EU have increased the demand for locally sourced durum, leading to a premium on domestic grains over imported varieties.
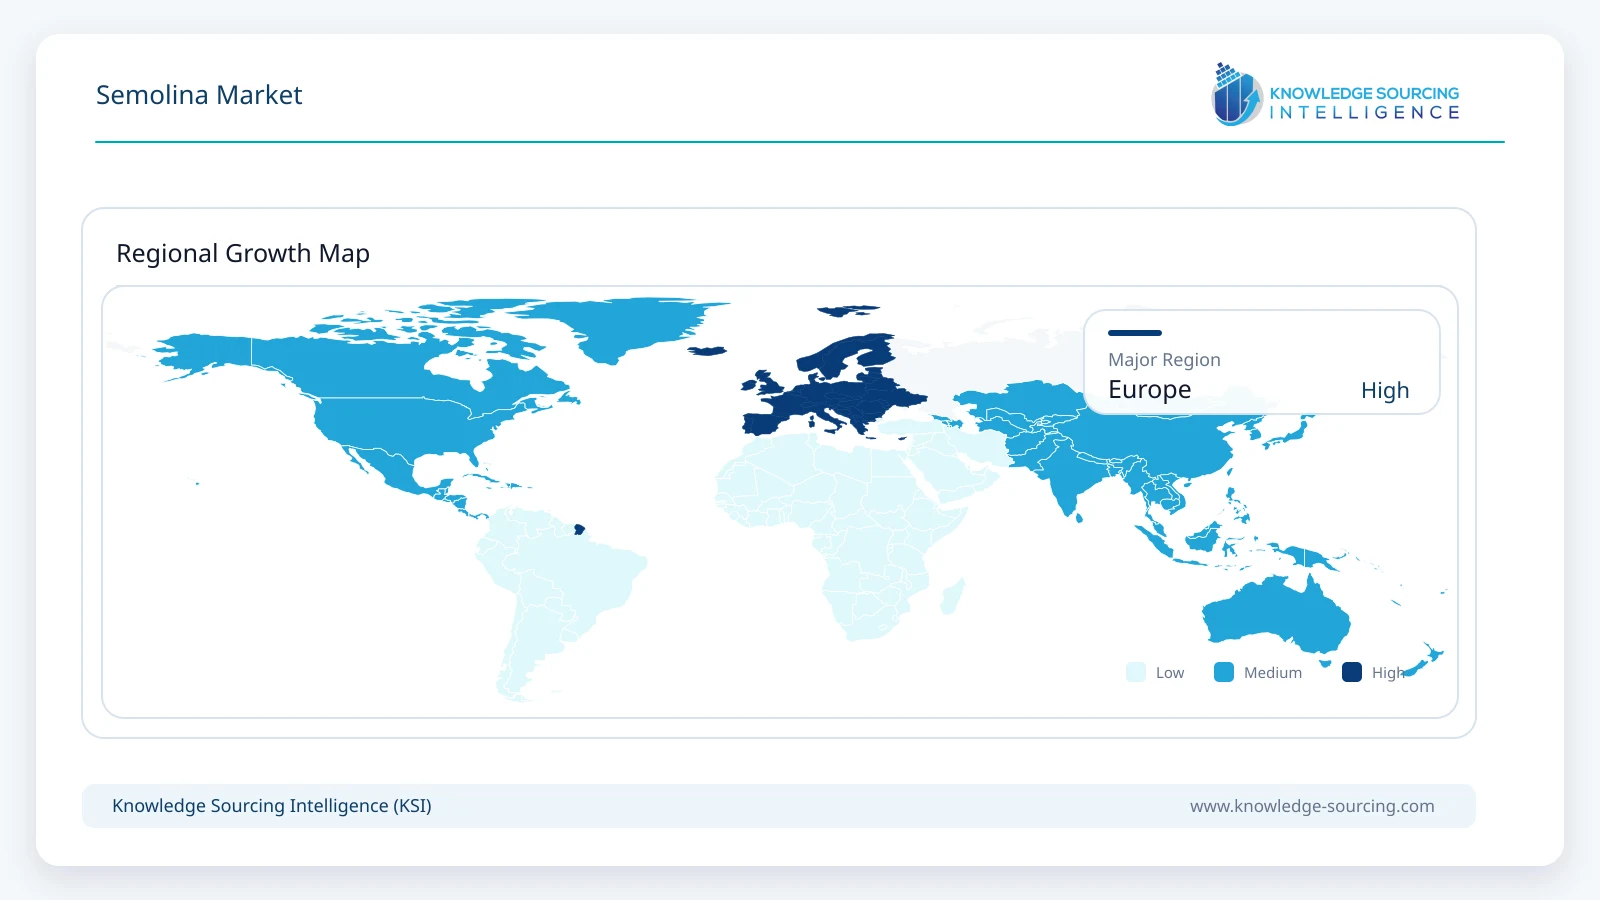
- 3Regional LeaderEurope maintains its position as the regional market leader, driven by Italy’s dual status as the world’s largest producer and consumer of semolina-based products, followed closely by North Africa.
- 4Technology TransitionThe adoption of advanced optical sorting technology in mills has enhanced the ability to remove impurities and "black spots" from semolina, directly impacting its grade and market value for premium applications.
- 5Pricing SensitivityThe market exhibits high sensitivity to the price of durum wheat; as durum typically trades at a significant premium over common bread wheat, volatility in grain markets leads to rapid shifts in manufacturer margins and retail pricing.
The structural demand for semolina is fundamentally anchored in its status as a critical raw material for the global pasta industry, which accounts for the majority of total semolina consumption. Unlike short-term dietary trends, the demand for semolina is a function of global food security and the industrialization of staple foods. The market is deeply dependent on the production cycles of durum wheat (Triticum durum), a crop highly sensitive to climatic shifts in major growing regions such as the Canadian Prairies, the Northern Plains of the United States, and the European Union. Consequently, the strategic importance of semolina lies in its high protein content and gluten strength, which provide the structural integrity required for extruded food products.
Technological evolution in the semolina market is currently focused on precision milling and digital supply chain monitoring. Innovations in "smart milling" allow processors to adjust grinding parameters in real-time to compensate for variations in grain hardness and moisture, ensuring consistent particle size distribution, a critical factor for industrial pasta extrusion. Furthermore, the industry is transitioning toward sustainable sourcing, with major processors like Ardent Mills and Barilla implementing regenerative agriculture programs to secure long-term supply resilience. Regulatory influence, particularly the European Union’s Farm to Fork strategy, is increasingly dictating the use of fertilizers and pesticides in durum cultivation, thereby altering the cost structure and demand for certified organic semolina.
Market Dynamics
Market Drivers
Institutionalized Pasta Demand: Global pasta production has reached nearly 17 million tonnes annually, creating a stable, high-volume floor for semolina demand that is resistant to economic downturns due to the product's status as an affordable staple.
Urbanization and Convenience Trends: Rapid urbanization in the Asia-Pacific region is driving the demand for instant noodles and ready-to-eat pasta products, which utilize semolina for its superior texture and cooking stability.
Nutritional Fortification Standards: Increasing government mandates for the enrichment of cereal-based products with folic acid and iron (standardized in 21 CFR 137 in the US) drive the demand for processed semolina that meets specific vitamin and mineral profiles.
Growth of Middle-Eastern and Mediterranean Cuisines: The global expansion of couscous as a healthy alternative to rice and potatoes has created new demand centers in North America and Northern Europe, specifically for medium-to-coarse grade semolina.
Market Restraints and Opportunities
Climatic Vulnerability of Durum Crops: Durum wheat is geographically concentrated; adverse weather in Canada or the Mediterranean can lead to severe supply tightness, forcing millers to explore lower-quality substitutes or wheat blends.
Expansion of Gluten-Free Alternatives: The rise of pulse-based and legume flours (chickpea, lentil) represents a structural threat to the traditional wheat semolina market, particularly in the premium health-food segment.
Logistical and Energy Costs: Milling is an energy-intensive process; rising electricity prices and transportation constraints impact the landed cost of semolina, particularly for export-dependent markets like Italy.
Opportunity in High-Protein Variants: There is a burgeoning opportunity for "high-protein" semolina blends (exceeding 13% protein content) to cater to the functional food market and the needs of artisanal pasta makers seeking specific rheological properties.
RAW MATERIAL AND PRICING ANALYSIS
The pricing of semolina is inextricably linked to the cash price of durum wheat, which typically accounts for over 80% of the total production cost. In recent years, the market witnessed a price correction following record harvests in North Africa, with standard grade durum (Ex-Works Italy) falling from approximately US$ 383/MT to US$ 316/MT. This 18% decrease reflects an oversupply cycle, though quality downgrades in Canadian crops have maintained a premium on high-protein specifications.
Supply chains are characterized by regional interdependence, where Italy remains the primary importer of high-quality Canadian durum to blend with local crops to achieve the protein levels required for "pasta di semola di grano duro." Margin management strategies among millers now include long-term forward contracting and the use of energy hedges to mitigate the volatility of processing costs. The pricing differential between conventional and organic semolina remains substantial, often exceeding 30%, as supply for certified organic durum remains tight relative to growing consumer demand in the European and North American retail sectors.
SUPPLY CHAIN ANALYSIS
The semolina supply chain is highly concentrated at the milling stage, with a small number of global agribusiness giants, such as ADM, Cargill, and Bunge, controlling significant portions of the international durum trade and processing capacity. Production is strategically located near either major growing hubs (e.g., the US Midwest and Canadian Prairies) or major consumption ports (e.g., Italian coastal mills). This concentration allows for economies of scale but leaves the industry vulnerable to regional disruptions, such as logistics bottlenecks at Great Lakes ports or Mediterranean shipping lanes.
Energy intensity is a primary concern in the "purification" stage of semolina milling, where specialized equipment separates the bran and germ from the endosperm. High energy costs in Europe have led some manufacturers to integrate renewable energy sources or modernize old milling lines to reduce kilowatt-hour-per-tonne ratios. Furthermore, transportation constraints for bulk flour products require specialized airtight pneumatic tankers or moisture-resistant packaging to prevent spoilage during transit. Integrated manufacturing strategies, where pasta plants are co-located with flour mills (as seen in Barilla’s operations), are increasingly favored to eliminate transportation costs and reduce the carbon footprint of the final product.
GOVERNMENT REGULATIONS
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
Italy (EU) | DM 26/07/2017 (Country of Origin Labeling) | Requires mandatory disclosure of where durum wheat was grown and milled, increasing demand and premiums for Italian-grown durum. |
United States | 21 CFR 137.320 (FDA Standard of Identity) | Defines semolina as being derived from durum wheat with a maximum ash content of 0.92%, ensuring product uniformity and safety for US consumers. |
Global | CODEX STAN 178-1991 (Codex Alimentarius) | Provides international standards for durum wheat semolina, facilitating global trade by harmonizing quality and safety specifications. |
KEY DEVELOPMENTS
May 2026: Crown Flour Mill, Olam Agri’s Nigerian wheat-milling business, launched Mama’s Pride Semolina, fortified with vitamins and micronutrients and designed to deliver a smooth, firm, fluffy texture for everyday meals.
February 2026: Ebro Foods reported its 2025 financial results on 25 February 2026, highlighting continued development in its fresh-pasta business and lower durum-wheat prices, relevant to semolina-based pasta production.
Increased Demand for Organic Semolina Products (2025): Growing consumer preference for organic and minimally processed foods has driven a surge in demand for organic semolina, particularly for pasta and baked goods. This trend reflects health-conscious choices and a shift toward sustainable, eco-friendly products, prompting manufacturers to expand organic semolina offerings to meet evolving dietary preferences.
Technological Advancements in Milling Processes (2024): Innovations in milling technology have improved semolina production efficiency, enhancing texture consistency and quality for pasta and couscous applications. These advancements allow producers to meet rising global demand for high-quality semolina-based products, particularly in regions with growing culinary diversity like Asia and Africa.
October 2024: International Pasta Organisation (IPO) – Reported that global pasta production reached 17 million tonnes in 2023. This data point serves as a structural indicator of the long-term volume requirements for the semolina market.
MARKET SEGMENTATION
By Type: Durum Semolina
Durum semolina remains the primary product segment, valued for its unique yellow pigment (carotenoids) and superior gluten strength. The demand for this segment is driven by the legal requirement in several countries, including Italy and France, that "dry pasta" must be made exclusively from durum semolina. Its high protein content makes it the preferred choice for industrial extrusion, as it prevents the pasta from becoming sticky or breaking during the drying and cooking processes. As consumers prioritize "clean label" and authentic Mediterranean products, the demand for pure durum semolina continues to outpace softer wheat alternatives.
By Application: Pasta
Pasta is the dominant application for semolina, with demand cycles influenced by global dietary shifts toward plant-forward and carbohydrate-stable diets. The segment's growth is supported by the expansion of the "premiumization" trend, where consumers seek pasta made from specific durum varieties or regions (e.g., Gragnano). This demand forces millers to produce "higher-spec" semolina with precise granulation and protein levels. Furthermore, the industrialization of pasta in emerging markets, such as India and China, provides a significant growth opportunity for large-scale semolina suppliers who can offer consistent, high-volume shipments.
By Distribution Channel: Hypermarkets and Supermarkets
The retail distribution of semolina is dominated by hypermarkets and supermarkets, which provide the shelf space for both private-label and branded semolina flours. These channels benefit from the consumer shift toward home-cooked, "authentic" meals, where semolina is purchased directly for making fresh pasta or traditional desserts like halva and puddings. Operational advantages for this segment include high visibility and the ability to leverage cross-promotional activities with other pasta-making ingredients, such as olive oils and sauces.
REGIONAL ANALYSIS
Europe
Europe is the anchor of the global semolina market, driven by the entrenched pasta-eating cultures of Italy, Spain, and Greece. The region’s industrial base is the most sophisticated in the world, with a high concentration of specialized durum mills. Demand is currently characterized by a transition toward organic and locally sourced grains to comply with the EU’s Green Deal objectives.
North Africa
North Africa remains a critical consumption region, particularly for the couscous segment, though it is highly dependent on imports from the EU and Canada to supplement local production during drought years.
North America
In North America, the market is dominated by the United States and Canada, which are also the primary global producers of high-quality durum. A robust industrial food sector and a growing retail market for specialty flours drive this demand.
Asia Pacific
In the Asia Pacific region, particularly India and China, the market is expanding rapidly due to the westernization of diets and the increasing use of semolina in local snacks and breakfast items (e.g., Suji in India). This region represents the most significant growth opportunity for global millers as urbanization continues to concentrate food demand.
LIST OF COMPANIES
Archer-Daniels-Midland Company
Grupo Nutresa
Conagra Brands, Inc.
Ebro Foods, S.A.
Cargill, Incorporated
Olam Agri Holdings Limited
Barilla S.p.A.
Poiatti S.p.A.
Pasta Foods Ltd.
Archer-Daniels-Midland Company (ADM)
ADM is a global leader in agricultural processing and nutrition, operating a massive network of durum mills across North America and Europe. The company’s strategy focuses on vertical integration, controlling the supply chain from grain origination to the final semolina product. ADM’s competitive advantage lies in its sophisticated logistics and risk management capabilities, which allow it to offer competitive pricing even during periods of crop volatility. Its recent acquisition of Siemer Milling’s durum assets underscores its commitment to expanding its footprint in the specialty flour segment.
Cargill, Incorporated
Cargill is a dominant force in the global grain trade, providing essential durum wheat origination and milling services to major food manufacturers worldwide. The company’s strategy is built around supply chain transparency and sustainability, with significant investments in regenerative agriculture to ensure long-term grain quality. Cargill’s geographic strength is its global reach, allowing it to source durum from multiple origins to provide millers and pasta makers with a consistent year-round supply. Its technology differentiation includes advanced proprietary milling processes that optimize starch damage and protein retention.
Barilla S.p.A.
While primarily known as the world’s leading pasta manufacturer, Barilla operates its own semolina mills to ensure total quality control over its primary raw material. Barilla’s strategy is defined by its "Good for You, Good for the Planet" initiative, which emphasizes the use of high-quality, sustainable durum. The company’s competitive advantage is its deep integration model, where it works directly with thousands of farmers via the "Durum Wheat Manifesto" to improve crop yields and quality. Barilla’s milling operations are focused on producing semolina with specific granulometry to match its diverse range of pasta shapes.
ANALYST VIEW
Global semolina demand is anchored by industrial pasta production and an expanding retail market for Mediterranean staples. While climatic volatility in durum growing regions remains a primary risk, technological advancements in milling and a structural shift toward high-protein, traceable grains offer significant growth opportunities for integrated agribusinesses and specialty processors.
Semolina Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 6.1 billion |
| Total Market Size in 2031 | USD 7.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Distribution Channel, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Durum Semolina
Soft Wheat Semolina
Others
By Application
Pasta
Couscous
Bakery Products
Soups and Sauces
Others
By Distribution Channel
Hypermarket and Supermarket
Convenience Stores
Online Retail
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK 
5. GLOBAL SEMOLINA MARKET BY TYPE
5.1. Introduction
5.2. Durum Semolina
5.3. Soft Wheat Semolina
5.4. Others
6. GLOBAL SEMOLINA MARKET BY APPLICATION
6.1. Introduction
6.2. Pasta
6.3. Couscous
6.4. Bakery Products
6.5. Soups and Sauces
6.6. Others
7. GLOBAL SEMOLINA MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Hypermarket and Supermarket
7.3. Convenience Stores
7.4. Online Retail
7.5. Others
8. GLOBAL SEMOLINA MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Type
8.2.2. By Application
8.2.3. By Distribution Channel
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Type
8.3.2. By Application
8.3.3. By Distribution Channel
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Type
8.4.2. By Application
8.4.3. By Distribution Channel
8.4.4. By Country
8.4.4.1. United Kingdom
8.4.4.2. Germany
8.4.4.3. France
8.4.4.4. Spain
8.4.4.5. Others
8.5. Middle East and Africa
8.5.1. By Type
8.5.2. By Application
8.5.3. By Distribution Channel
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. Israel
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Type
8.6.2. By Application
8.6.3. By Distribution Channel
8.6.4. By Country
8.6.4.1. China
8.6.4.2. India
8.6.4.3. Japan
8.6.4.4. South Korea
8.6.4.5. Indonesia
8.6.4.6. Taiwan
8.6.4.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Archer-Daniels-Midland Company
10.2. Grupo Nutresa
10.3. Conagra Brands, Inc.
10.4. Ebro Foods, S.A.
10.5. Cargill, Incorporated
10.6. Olam Agri Holdings Limited
10.7. Barilla S.p.A.
10.8. Poiatti S.p.A.
10.9. Pasta Foods Ltd.
List of Figures
List of Tables





Frequently asked questions
What is the projected growth of the Semolina Market from 2026 to 2031?
Market grows from $6.1 billion (2026) to $7.4 billion (2031) at 3.9% CAGR.
Who is the largest end-user in the global Semolina Market?
Industrial pasta manufacturers are the dominant end-user segment globally.
Which region holds the largest share of the Semolina Market?
Europe leads the market, driven by Italy, followed by North Africa.
What drives the demand for semolina globally?
Institutionalized pasta demand and food security are primary market drivers.
How does technology influence the Semolina Market outlook?
Smart milling, digital supply chain, and optical sorting enhance value.
What is the impact of regulation on Semolina Market costs?
EU Farm to Fork strategy and COOL initiatives dictate costs and demand.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Semolina Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-semolina-market