
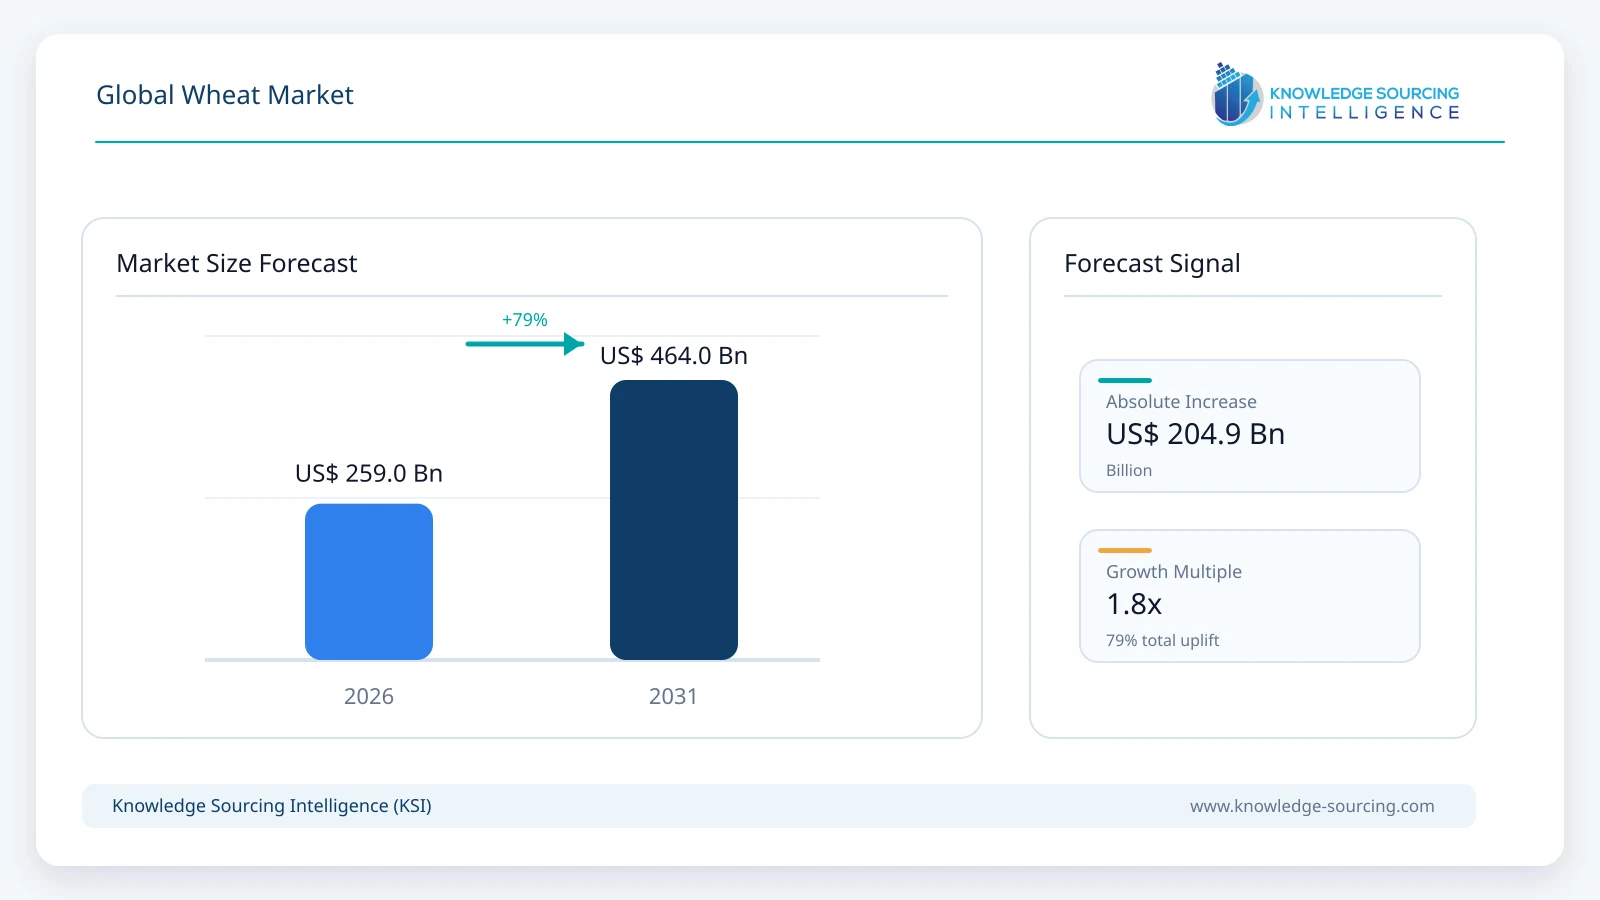
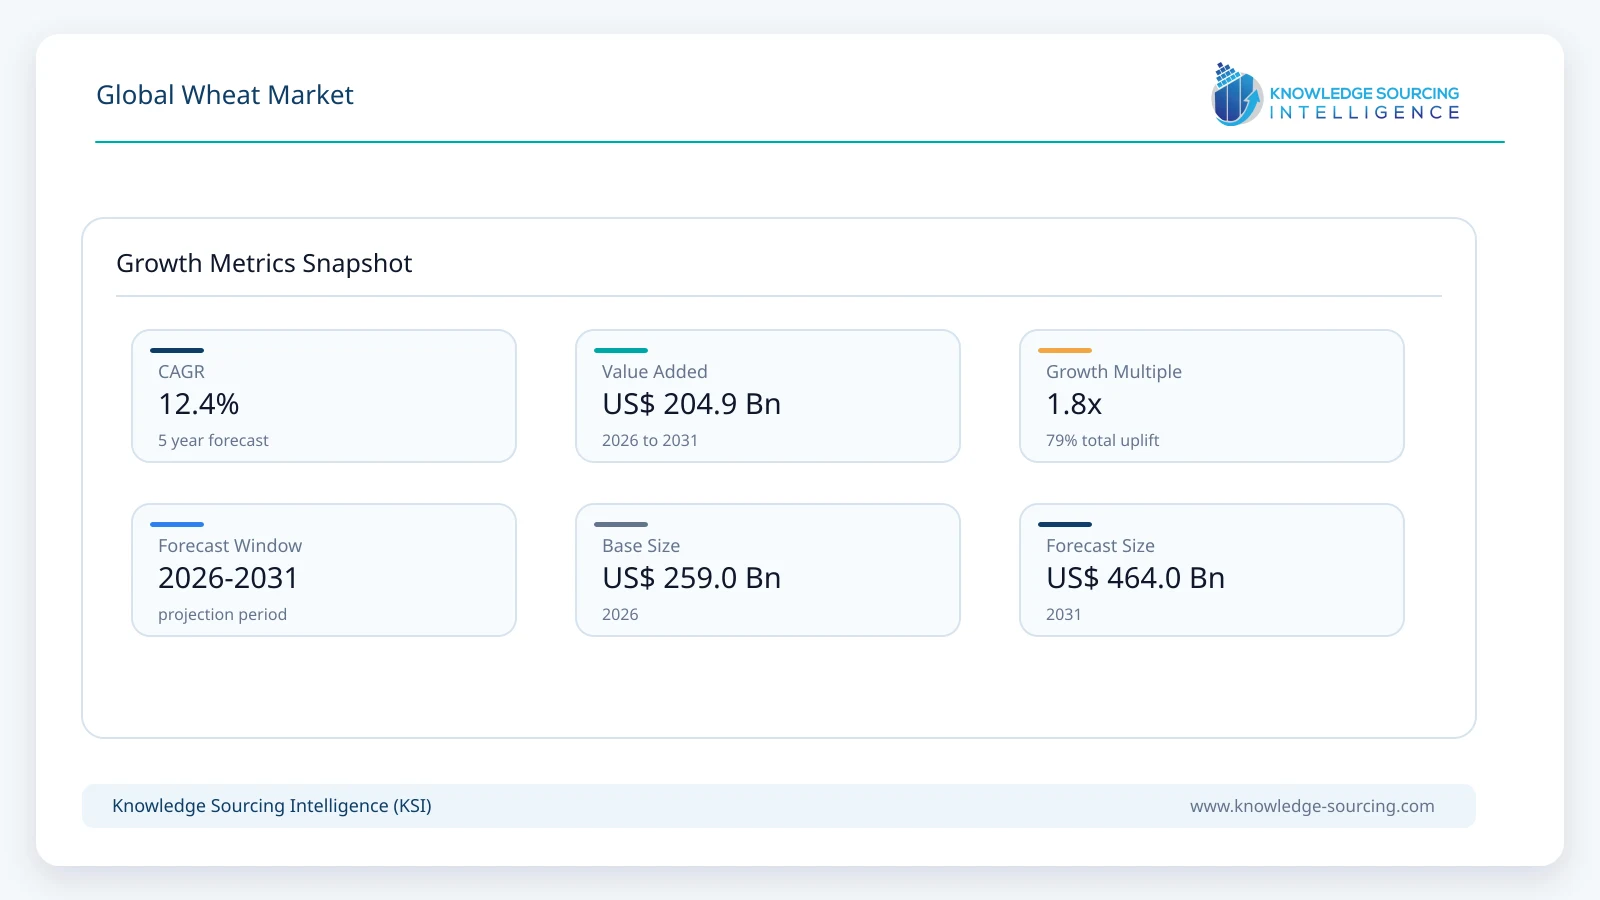
The Global Wheat market is forecast to grow at a CAGR of 12.4%, reaching USD 463.96 billion in 2031 from USD 259.04 billion in 2026.
Highlights:
- 1Major producers China, India, the EU, and Russia together account for over half of global wheat output, ensuring strong supply and market stability worldwide.
- 2Growing awareness of whole-wheat health benefits, including lower cardiovascular disease risk and better weight management, is boosting consumer demand for wheat-based products.
- 3Wheat finds extensive use in the food and beverage sector through flour, semolina, and related products derived from varieties such as hard red spring and soft white wheat.
- 4The European Union is expected to hold a major share of the global wheat market, supported by high production volumes and established agricultural infrastructure.
- 5Recent industry developments focus on regenerative agriculture, supply-chain traceability, and value-added wheat ingredients, reinforcing long-term market growth and sustainability.
Wheat is a type of grass that is cultivated worldwide mainly for its seed. It is among the most common cereals consumed by the majority of the global population. Wheat is among the most common sources of carbohydrates, vitamins, and minerals. The cereal also offers a higher amount of energy upon consumption, as it has a higher quantity of carbohydrates, and can help in managing weight. The consumption of whole wheat also lowers the risk of cardiovascular diseases.
The wheat seed is used for multiple applications, commonly in the food and beverage sector. The wheat seeds are ground for producing wheat flour or semolina. Various wheat varieties are cultivated worldwide, including hard red spring, soft white, hard wheat, and others. Hard red spring wheat is mainly cultivated in the North American region, whereas soft white wheat offers a high break and straight-grade flour yield. It contains lower ash and low starch damage.
The global wheat market is estimated to witness substantial growth in demand, mainly due to increasing wheat production worldwide. In the cultivation of wheat, China, India, the EU, and Russia are among the biggest producers, producing more than half of the global wheat. Similarly, the increasing consumer perception of wheat products' health benefits is also estimated to increase its market size globally.
Growth Drivers
Increasing global wheat production and expanding supply
A major factor supporting the global wheat market is the continued expansion of wheat production across major producing regions. Wheat remains one of the world’s most widely cultivated cereal crops, with production concentrated in Asia, Europe, and North America. According to the latest USDA Foreign Agricultural Service data, global wheat production is estimated at 843.99 million metric tons in 2025/26, up from 799.1 million metric tons in 2024/25, representing an increase of about 6%.
Production remains concentrated among a relatively small group of major producers. For 2025/26, USDA reports wheat production of 145.14 million metric tons in the European Union, 140.07 million metric tons in China, 117.95 million metric tons in India, and 90.30 million metric tons in Russia. Together, these four producers account for roughly 58% of global wheat production, highlighting their importance to international wheat supply.
India is also recording strong domestic production. The Government of India’s Third Advance Estimates for 2025–26 project wheat production at a record 122.0 million tonnes, while wheat acreage increased to approximately 33.4 million hectares. The government has also highlighted stronger procurement and production conditions, supporting domestic availability and reinforcing India’s position as a major global wheat producer.
The European Union is another significant production base. European Commission data indicate that EU wheat production reached approximately 134 million tonnes in 2025/26, compared with about 111 million tonnes in 2024/25. The Commission continues to track cereal production, yields, trade, and crop conditions through regularly updated agricultural-market datasets, reflecting the scale and importance of wheat cultivation across the region.
Growing prevalence of cardiovascular diseases
The continuing global burden of cardiovascular diseases (CVDs) is supporting interest in dietary patterns that include whole grains, creating a favorable nutritional backdrop for wheat consumption. Whole-grain wheat provides dietary fiber and other nutrients, while current dietary guidance increasingly emphasizes whole grains as part of heart-healthy eating patterns. The U.S. Department of Agriculture’s systematic review found strong evidence that dietary patterns higher in whole grains and lower in saturated fat, refined grains, and processed foods are associated with a lower risk of cardiovascular disease.
Cardiovascular diseases remain the leading global cause of death. The World Health Organization reported in July 2025 that an estimated 19.8 million people died from CVDs in 2022, representing approximately 32% of global deaths, with heart attacks and strokes accounting for 85% of these deaths. WHO also identifies unhealthy diets, including excessive intake of salt, sugar, and unhealthy fats, together with physical inactivity and obesity, among the major modifiable risk factors. This sustained disease burden is strengthening public-health emphasis on healthier dietary patterns, including greater consumption of whole grains.
Recent policy developments further reinforce this nutritional trend. In March 2026, the American Heart Association's updated dietary guidance recommended choosing foods made mostly with whole grains rather than refined grains and emphasized dietary patterns rich in fiber while limiting saturated fat, added sugars, and sodium. The U.S. Food and Drug Administration similarly states that healthy eating patterns containing whole grains are associated with improved health outcomes, including a reduced risk of cardiovascular disease.
The cardiovascular burden is also substantial across Europe. The European Commission reports that CVDs cause approximately 1.7 million deaths annually in the European Union, while the Commission and OECD launched an updated cardiovascular-health assessment in February 2026 covering risk factors, outcomes, and healthcare pathways across EU member states, Iceland, and Norway. These developments are encouraging greater attention to preventive nutrition and balanced diets, supporting opportunities for wheat-based foods, particularly products formulated around whole-grain consumption and higher dietary-fiber content.
Geographical Outlook:
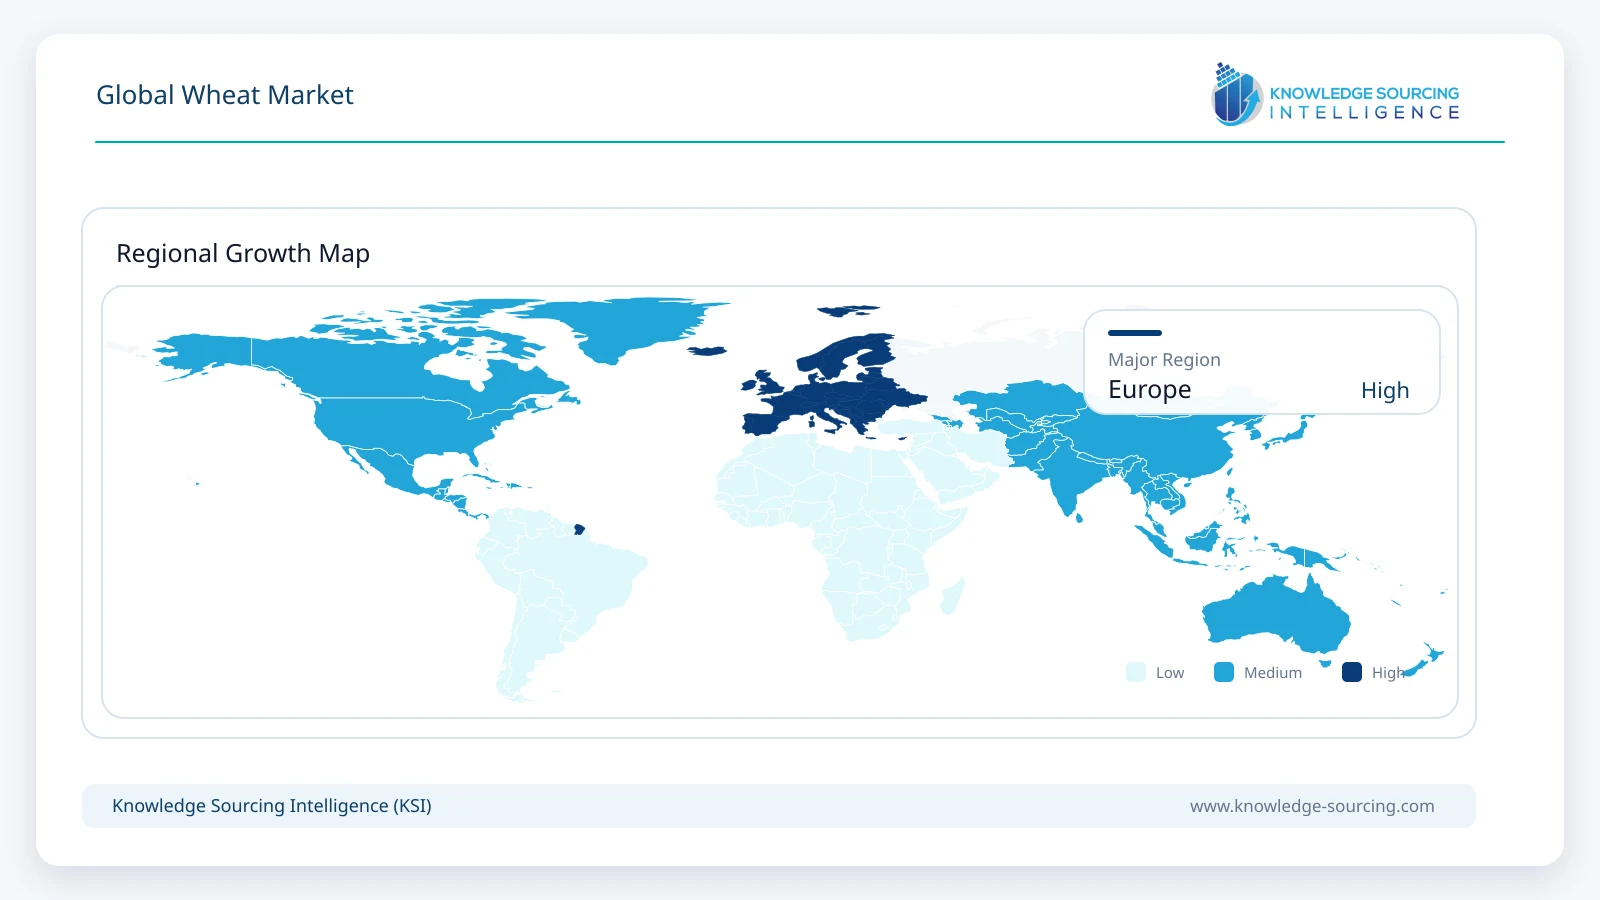
The European Union is forecasted to hold a major share of the global wheat market.
The European Union remains a major global wheat producer, with USDA reporting 145.14 million tonnes of wheat production in 2025/26, equivalent to 17.2% of global output. European Commission data indicate wheat production reached around 134 million tonnes in 2025/26, while 2026/27 production is projected at approximately 126 million tonnes.
EU wheat supply is supported by established agricultural infrastructure, extensive cultivated areas, and strong production in countries including France, Germany, Poland, Romania, and Spain. Eurostat reported 112 million tonnes of common wheat and spelt harvested in 2024, representing 43.3% of EU cereal production.
Major players and products in the global wheat market:
Shri Mahavir Group is among the leaders in manufacturing whole wheat flour and wheat processing in India. The company offers a wide range of products, including wheat flour, wheat, basmati rice, chickpeas, and quinoa seeds, among others. The company offers five categories of wheat in the market: milling wheat, lokwan wheat, sharbat wheat, durum wheat, and Australian wheat. Similarly, in the wheat flour category, the company offers five varieties: whole wheat flour, wheat flour, tandoori, semolina coarse, and semolina fine.
Shyali Products Pvt. Ltd. is an Indian agro-product manufacturer that offers a wide range of products. The company's products include dry fruits, wheat, Indian spices, tamarind pods, fresh fruits, and vegetables.
Key Developments:
September 2026: ADM advanced its Nature’s Gold™ regenerative flour programme by introducing a segregated wheat supply chain, improving farm-to-mill traceability and strengthening provenance for regenerative wheat flour customers.
July 2026: General Mills, ADM and Walmart announced a collaboration covering 40,000 Midwest wheat acres to accelerate regenerative agriculture, improve soil health, water quality, carbon sequestration and wheat supply-chain resilience.
July 2026: PureField Ingredients launched its 150,000-tonne-per-year carbon-capture and sequestration facility in Kansas and announced planning to double ethanol and carbon-sequestration capacity, increasing demand for Kansas-grown wheat.
July 2025: Manildra Group highlighted its GemMate ingredient, produced from Australian-grown fermented wheat starch, as a clean-label shelf-life extender designed to reduce bakery waste while supporting value-added wheat utilization.
Wheat Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 259.04 billion |
| Total Market Size in 2031 | USD 463.96 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Uses, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Hard Red Wheat
Hard Red Spring
Soft Red Wheat
Soft White
Hard Wheat
By Uses
Flour
Grain
By End-user
Household
Commercial/Industrial
By Geography
North America
United States
Canada
Others
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
South Korea
Taiwan
Thailand
Indonesia
Japan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key benefits for the stakeholders
2. RESEARCH METHODOLOGY  
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. The Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. GLOBAL WHEAT MARKET BY TYPE
5.1. Introduction
5.2. Hard Red Wheat
5.3. Hard Red Spring
5.4. Soft Red Wheat
5.5. Soft White
5.6. Hard Wheat
6. GLOBAL WHEAT MARKET BY USES
6.1. Introduction
6.2. Flour
6.3. Grain
7. GLOBAL WHEAT MARKET BY END-USER
7.1. Introduction
7.2. Household
7.3. Commercial/Industrial
8. GLOBAL WHEAT MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Type
8.2.2. By Uses
8.2.3. By End-User
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Others
8.3. South America
8.3.1. By Type
8.3.2. By Uses
8.3.3. By End-User
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Type
8.4.2. By Uses
8.4.3. By End-User
8.4.4. By Country
8.4.4.1. Germany
8.4.4.2. France
8.4.4.3. United Kingdom
8.4.4.4. Spain
8.4.4.5. Others
8.5. Middle East and Africa
8.5.1. By Type
8.5.2. By Uses
8.5.3. By End-User
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. UAE
8.5.4.3. Israel
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Type
8.6.2. By Uses
8.6.3. By End-User
8.6.4. By Country
8.6.4.1. China
8.6.4.2. India
8.6.4.3. South Korea
8.6.4.4. Taiwan
8.6.4.5. Thailand
8.6.4.6. Indonesia
8.6.4.7. Japan
8.6.4.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Shri Mahavir Agritech (Mahavir Group Inc.)
10.2. Shyali Products Private Limited
10.3. ADM (Archer Daniels Midland)
10.4. Cargill, Inc
10.5. Adani Wilmar (Adani Group)
10.6. Manildra Group
10.7. PureField
10.8. General Mills Inc
10.9. VAD industries
10.10. Jay Jay Agro
10.11. Ambe Group
10.12. Sarwa Foods
10.13. Gold Grain (India) Pvt. Ltd.
10.14. Maeda Foods Co., Ltd
10.15. Kumamoto Flour Milling Co., Ltd.





Frequently asked questions
What is the projected market size of the Global Wheat Market by 2031?
The Global Wheat Market is projected to reach USD 463.96 billion by 2031.
What is the forecast CAGR for the Global Wheat Market (2026-2031)?
The Global Wheat Market is forecast to grow at a 12.4% CAGR (2026-2031).
Which regions are the major producers driving global wheat supply?
China, India, the EU, and Russia are major global wheat producers.
What are the primary drivers for Global Wheat Market growth?
Increasing production and consumer health perception are primary market drivers.
How do health benefits influence Global Wheat Market demand?
Whole wheat's health benefits, like lowering cardiovascular risk, drive demand.
What are some key varieties of wheat mentioned in the report?
Hard red spring, soft white, and hard wheat varieties are cultivated globally.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Global Wheat Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-wheat-market