
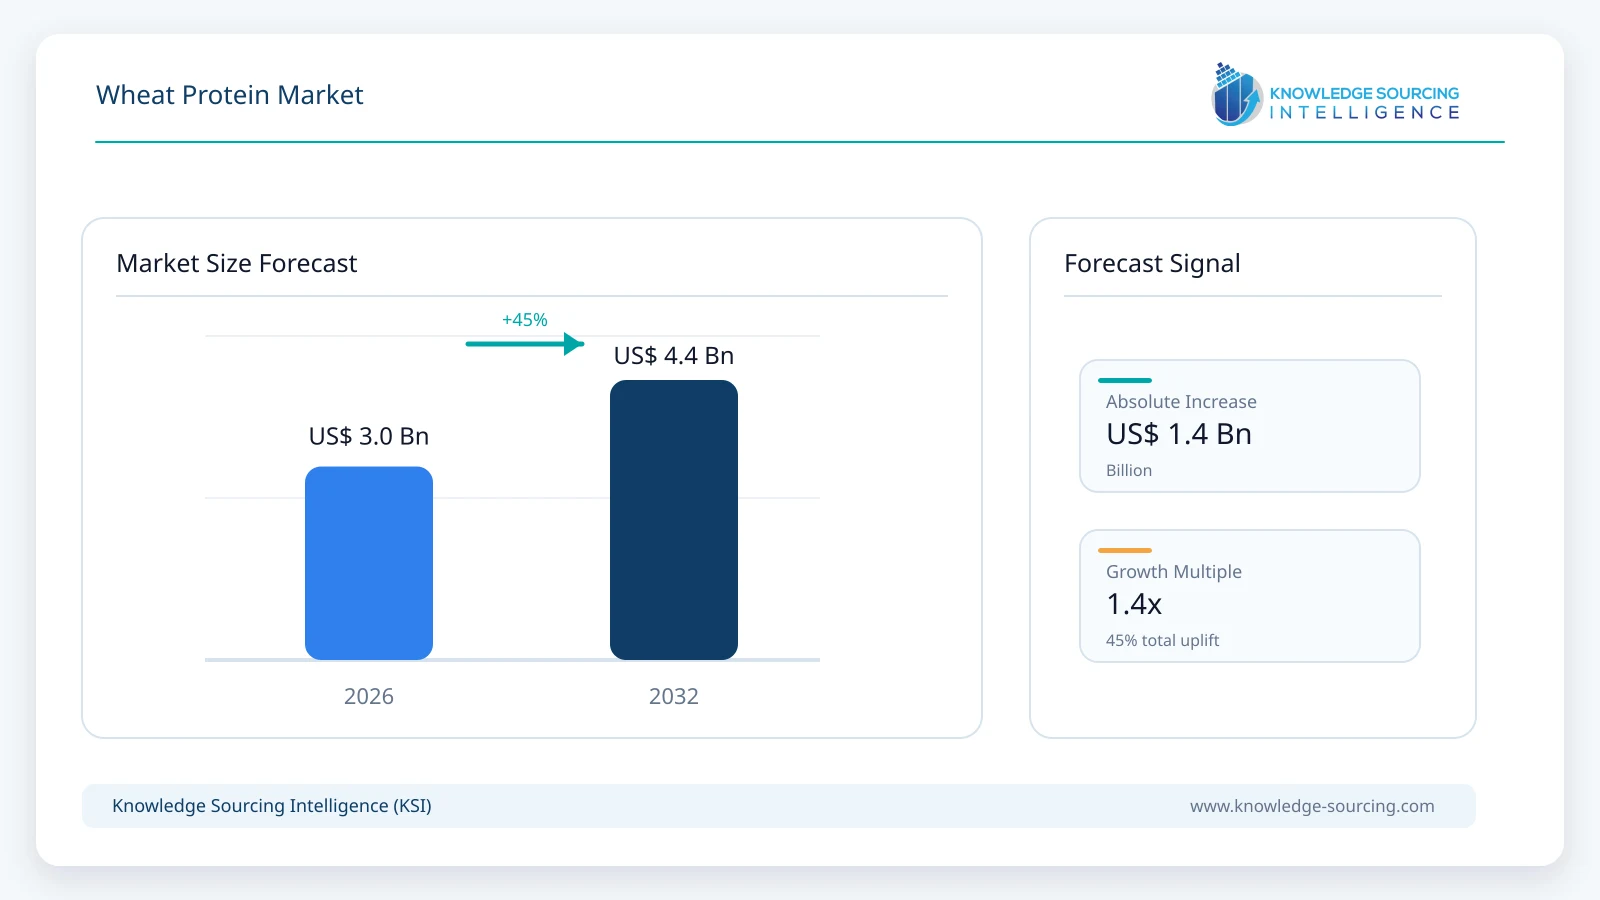
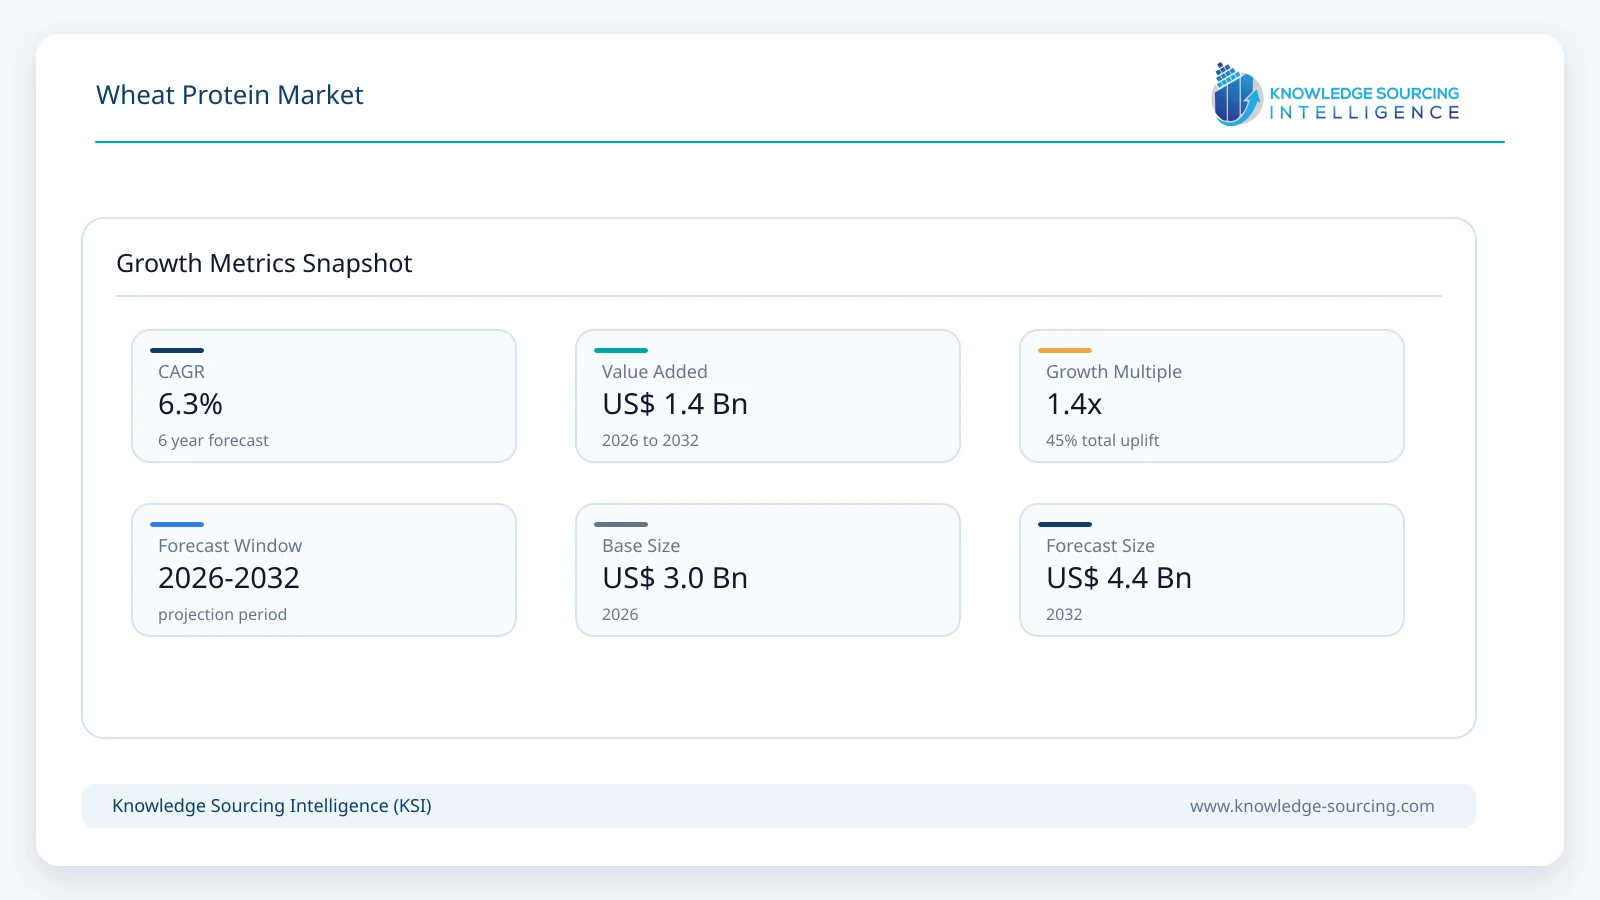
The Wheat Protein Market is projected to expand at a CAGR of 6.3%, increasing from USD 3.04 billion in 2026 to USD 4.40 billion by 2032.
Highlights:
- 1Aquafeed is estimated to represent 31.2% of global revenue in 2026, reflecting its large tonnage base and the functional importance of wheat gluten in extrusion and pellet stability.
- 2The bakery and milling application is the largest volume destination for wheat protein, supported by demand for dough strength, loaf volume and formulation consistency.
- 3Hydrolyzed and soluble wheat proteins are projected to expand at a 6.4% CAGR through 2032, reflecting their differentiated use in young-animal nutrition and dispersible formulations.
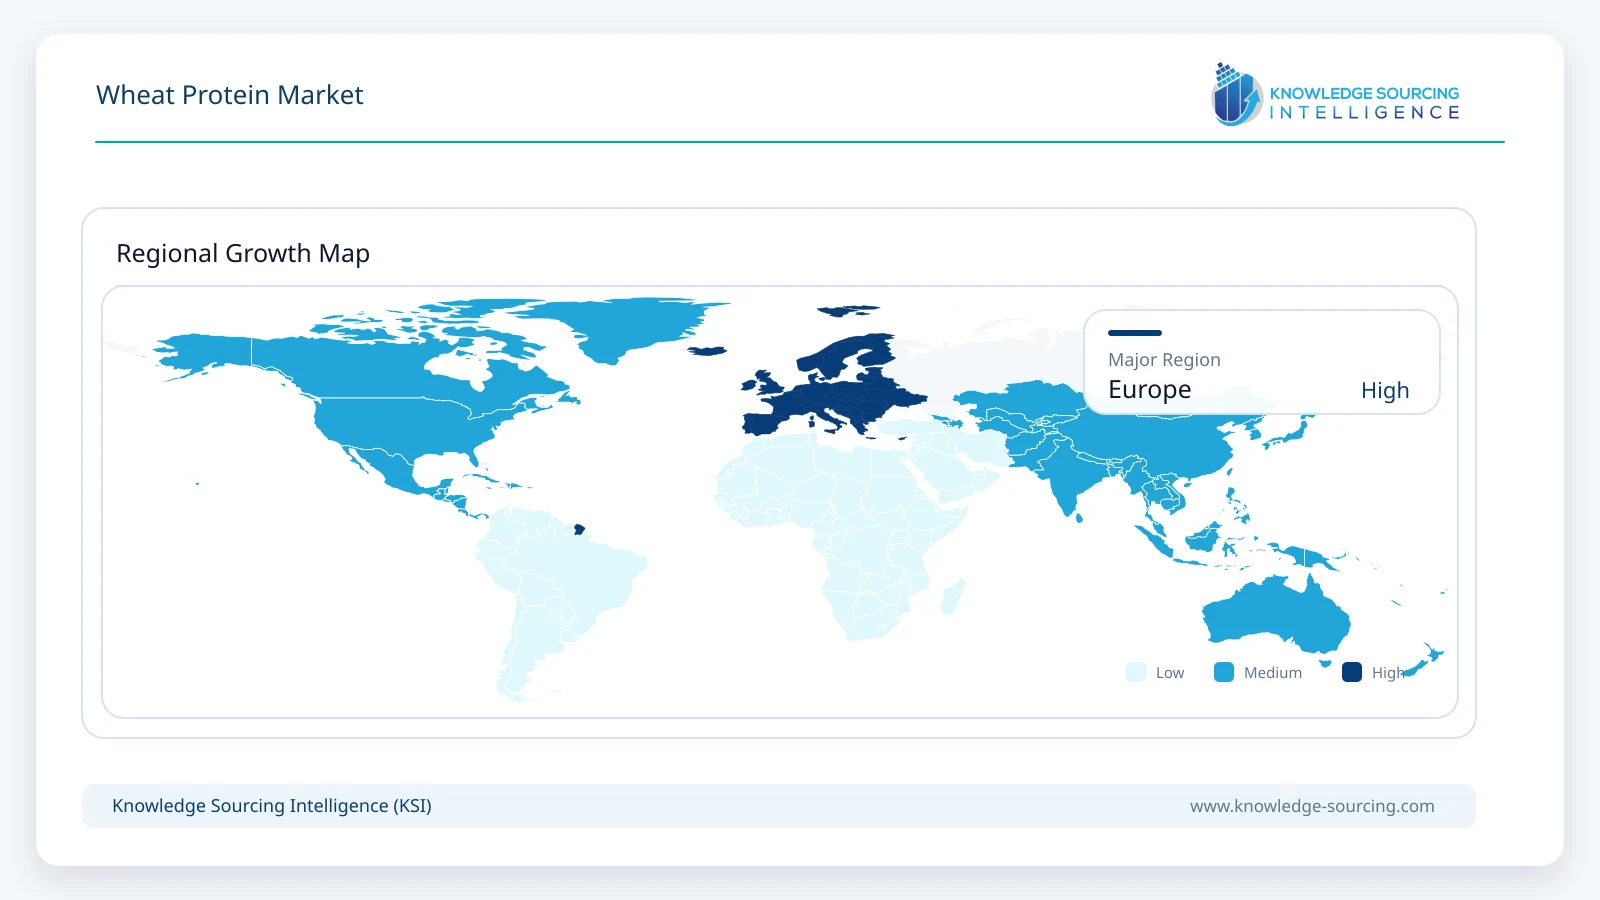
- 4Europe accounts for an estimated 57.6% of revenue by manufacturing origin in 2026, reflecting the region's concentrated wheat starch and gluten production footprint.
- 5The market remains highly exposed to contract pricing and trade remedies. Canada's September 2026 provisional duties on selected wheat gluten imports underscore how sourcing economics can shift independently of physical end-market demand.
Market Trends and Commercial Dynamics
Growth in aquaculture is changing the protein demand mix
The fastest-moving commercial demand is not necessarily in premium vegetarian meat substitutes. Wheat protein is established in fish-feed formulations because it provides concentrated digestible protein while supporting binding and stability of extruded pellets. Higher protein inclusion in a particular feed does not automatically generate more industry revenue if the formulator substitutes another protein source. Manufacturers therefore compete on formulation performance, assured specification, shipment reliability and total cost in use.
The Wheat Protein Association's 2025 figures show aquafeed reaching 450,000 tonnes, a 22% increase from the previous year. That is a stronger observed growth signal than broad statements about consumers shifting to plant-based diets. For wheat-protein suppliers, the opportunity is to secure long-duration technical approvals with aquafeed formulators, while defending prices against soy protein concentrate, marine proteins and other substitutes. Each new qualification can support recurring demand, but feed buyers remain sensitive to changes in delivered cost.
Co-production economics limit producer pricing power
Wheat gluten is generally recovered through wet processing that also yields wheat starch and other fractions. The relationship makes the market structurally different from ingredients manufactured solely to satisfy protein orders. Protein availability may increase as a starch producer operates at higher throughput, even during a period of slower protein purchasing. Conversely, maintenance shutdowns, wheat quality and energy costs can constrain supply without any change in downstream consumer demand.
Manufacturers operating integrated starch and gluten plants can spread fixed costs across multiple products, creating a commercial advantage over producers dependent on one fraction. Yet integrated capacity can also intensify pricing competition if starch-oriented production adds incremental protein volume. This is why new milling capacity should be evaluated against both installed protein separation capability and the underlying economics of starch processing, rather than counted as a direct one-for-one addition to wheat-protein demand.
Feed and food grade certification creates different customer economics
Wheat protein is sold into food applications, aquafeed, pet food and specialized animal nutrition under different product standards and qualification requirements. Bakery customers often emphasize elasticity, extensibility, flour correction and reproducibility. Aquaculture customers test pellet performance, digestibility and water stability. Soluble hydrolysates used in calf milk replacers require dispersibility and digestion-related performance. A nominally similar protein percentage therefore does not make two commercial grades interchangeable.
Procurement typically combines laboratory analysis, application trials and approved supplier lists. Producers able to supply technical-service support have an advantage in applications where failure creates production losses or feed quality problems. For customers, the selection is based on the delivered cost of performance, not the unit price of a generic protein ingredient alone. This supports differentiated revenue opportunities without assuming every ton of gluten commands a specialty-ingredient price.
Trade remedies are affecting cross-border sourcing
North American purchasing is being shaped by trade-defense actions. In September 2026, Canada's border agency made a preliminary dumping determination covering imports from Italy, Poland and the United Kingdom. The published provisional-duty schedule specified different rates for responding exporters and other suppliers. A buyer's effective landed cost can therefore change even when the underlying producer's factory price remains stable.
Canadian findings also identify substantial French production capacity and export orientation. The United States remains a major import destination, while sourcing patterns span Australia and European producers. These facts make country-level trade flows and customs unit values important controls when assessing market revenue. However, an import price is not the same as ex-works producer revenue: freight, insurance, distribution margins and specialty grades require explicit adjustment.
Premium innovation remains selective
Specialty wheat isolates and textured ingredients create useful opportunities in premium bakery systems, reformulated foods and meat analogues. Roquette's 2025 introduction of a textured wheat protein reflects the shift toward performance-based product development. These innovations expand the number of product specifications and potential use cases, but the 2025 industry breakdown shows that the bulk of demand remains in baking, aquafeed and pet food. The commercial outlook should therefore be weighted toward repeatable industrial consumption, with specialty launches contributing selective mix improvement rather than being used to explain the entire market's growth.
Market Restraints
Price competition and substitution pressure
Wheat gluten competes with alternative proteins and functional binders. In feed markets, protein digestibility, amino-acid balance and feed-pellet durability influence formulation choices. In bakery, purchasers can adjust flour blends or use other functional ingredients depending on performance requirements and cost. The commercial risk is not that wheat protein ceases to be useful, but that marginal inclusion is reduced when competing ingredients offer more attractive formulation economics.
Gluten sensitivity and allergen management
Wheat protein is unsuitable for gluten-free applications. Dedicated allergen controls, labeling and cross-contact prevention can increase operating requirements for downstream food manufacturers. Its nutritional attributes also should not be conflated with broad claims that it is universally healthier than animal protein. Market forecasts therefore require a realistic addressable customer base rather than total demand for plant-based or high-protein foods.
Commodity versus specialty pricing dispersion
Annual customs unit values differ substantially by country and supply route. Those values represent mixed grade and contract profiles and are not transferable directly to every end market. When higher-priced specialty protein is averaged with basic vital gluten, the result can materially overstate the commercial value of standard bakery or aquafeed volumes. Price assumptions also need to account for the movement of supply through distributors and the risk of counting resale revenue twice.
Segment Analysis
By Application: Aquafeed
Aquafeed represents the most commercially consequential demand transition in wheat protein. The segment is estimated at US$947.7 million in 2026 and is projected to reach US$1,644.4 million in 2032, driven by a rising production requirement for high-quality feed pellets and the value of consistent protein delivery. Wheat protein performs two functions in many feed systems: supplying concentrated protein and supporting physical pellet integrity during processing and subsequent exposure to water.
Those functions matter because feed manufacturers do not purchase protein on crude protein content alone. Pellet breakage and nutrient leaching can increase wastage and affect realized feed conversion economics. Processing conditions also vary with extrusion temperature, moisture and lipid content. A formulation that performs well with one supply grade may require adjustment if a replacement protein has different binding behavior. Such technical constraints support demand for standardized protein ingredients and repeat procurement from validated suppliers.
Cargill identifies pelletized vital wheat gluten as an important handling innovation for the aquaculture market. Roquette's VITEN gluten and soluble-protein lines address functional and nutrition requirements across aquatic and young-animal feeds. These product offerings illustrate the value of providing application-specific ingredients rather than treating all wheat protein as a uniform bulk commodity. Suppliers that combine consistent quality with processing advice can improve retention at feed manufacturers, while commodity-oriented producers face greater substitution pressure.
From a purchasing perspective, price exposure is highly material. The modeled 2026 aquafeed market corresponds to approximately 486 thousand tonnes of protein input. A US$100-per-tonne change in the realized selling price across that volume would alter annual segment expenditure by approximately US$48.6 million, before any change in physical purchasing. This sensitivity illustrates why long-term supply agreements, alternate-source qualification and freight economics can be as important as forecast feed-production growth.
Commercial growth is also affected by how much wheat protein a feed formulator can substitute for other protein concentrates. The World Bank identifies wheat gluten as a useful plant protein concentrate in aquafeeds due to its digestibility and functional characteristics, while Cargill documents its pellet-handling application. However, substitution limits depend on species, life stage, amino-acid requirements and total formulation economics. The market should not be modeled as a fixed percentage of global aquaculture output. Instead, it reflects changing inclusion, product mix and qualified supply relationships.
Regulatory developments may alter the attractiveness of different manufacturing origins. The 2026 Canadian wheat gluten proceedings demonstrate that landed prices can diverge from producer export prices when provisional duties are imposed. For feed manufacturers purchasing imported protein, this may support diversification among suppliers, alternative origin qualification or greater reliance on domestic capacity. The resulting effects are most direct for exposed importing countries and should not automatically be projected to the entire global feed market.
The segment is expected to gain relative commercial importance through the forecast period. Its expansion nevertheless depends on maintaining functional advantages against alternative proteins and on supply-chain conditions that allow producers to preserve realized pricing. For market participants, the strongest opportunity lies in reliable, technical-grade volume supply tied to established customer formulations, rather than speculative forecasts for entirely new protein applications.
By Application: Bakery and Milling
Bakery and milling remain the largest application by tonnage. The segment has a modeled 2026 revenue of US$1,226.9 million, supported by flour correction, dough elasticity and consistent baked-product performance. Buyers generally require repeatable technical specifications and competitive delivered prices. This makes the category relatively mature but commercially substantial, with growth driven by industrial production volumes and changes in formulation more than premium branding.
By Application: Pet Food and Specialty Nutrition
Pet-food applications are projected to grow at a 6.6% CAGR during 2026–2032, supported by the protein's binding performance and use in formulated animal foods. Hydrolyzed wheat proteins remain relevant to calf milk replacers and other specialist nutrition systems because they can offer solubility and dispersion properties that differ from native gluten. Product choice depends on end-use performance and protein specifications, making specialty demand less directly exposed to basic bakery-gluten pricing.
By Product: Native, Hydrolyzed and Textured Wheat Protein
Native or vital wheat gluten accounts for approximately 78.3% of modeled 2026 revenue, reflecting its extensive use across food and feed applications. Hydrolyzed proteins address soluble formulation requirements, while textured wheat proteins serve a narrower set of prepared-food applications. The categories are defined by the purchased ingredient form and must not count a protein tonne twice when further processing creates a higher-value specialty product.
Geographical Outlook
Europe
Europe is an important wheat-protein manufacturing center because of its integrated starch and gluten operations, specialized ingredient processing and export links. The manufacturing-origin market is estimated at US$1,751.5 million in 2026. Producer concentration across France, Germany, Italy and surrounding markets supports both high-volume supply and development of tailored ingredient grades. Canada’s 2026 trade review specifically identifies Tereos, Roquette and ADM as established French producers, while also documenting substantial export orientation.
The region's outlook is influenced by capacity utilization, wheat and energy economics, access to European and overseas buyers, and the extent to which suppliers can capture premiums through consistent functionality. A new milling investment does not necessarily translate into equivalent market growth. The commercial value depends on actual protein recovery, available sales contracts, the balance between food and feed grades, and the profitability of the associated starch stream.
Asia Pacific
Asia Pacific is a significant production center and an expanding outlet for industrial bakery, aquafeed and animal nutrition formulations. Its production-origin revenue is expected to rise more quickly than that of mature European producers in the central scenario. Regional supply economics are influenced by the scale of starch-processing facilities, demand from export-oriented ingredient buyers and the cost competitiveness of standardized wheat gluten. The forecast does not assume that growing wheat production automatically increases protein-isolate output, because conversion depends on specialized extraction capacity and downstream economics.
North America
North America combines an established food and animal-nutrition buyer base with domestic wheat-protein manufacturing and substantial imports. U.S. customs records show 2025 imports of roughly 165,247 tonnes of wheat gluten, illustrating the importance of overseas supply. American producers such as PureField and ADM participate in this market, but the import figures also highlight sensitivity to transport costs, origin availability and trade policy. The region's commercial outlook therefore reflects a mix of domestic utilization, customer qualification requirements and import competition rather than end-market demand alone.
Middle East and Africa
Middle Eastern and African demand is concentrated in importing markets where industrial bakeries, processed-food manufacturers and feed formulators rely on international suppliers for consistent wheat-protein performance. Saudi Arabia imported 14,487 tonnes of wheat gluten worth US$24.09 million in 2025. Türkiye purchased US$28.47 million, while Israel imported approximately US$10.51 million. These markets create opportunities for suppliers that can deliver standardized gluten functionality, predictable lead times and application support despite changing freight and currency conditions.
Egypt imported 4,891 tonnes of wheat gluten worth US$7.44 million in 2025, while South Africa purchased 3,087 tonnes valued at US$4.57 million. The United Arab Emirates also receives supplies from China, Türkiye and European producers. Commercial success in these markets depends on distributor inventories, customer qualification and delivered cost rather than domestic wheat output alone. Imported wheat protein supports bakery consistency, food formulation and selected feed uses, while the region's end-market purchasing patterns differ from the manufacturing concentration found in Europe and Asia Pacific.
Competitive Landscape
Wheat protein competition spans integrated starch processors, specialized protein manufacturers and companies supplying differentiated food and feed ingredients. Relevant manufacturers include Tereos, Roquette, Archer Daniels Midland, Cargill, MGP Ingredients, Manildra Group, PureField Ingredients, Crespel & Deiters, Kröner-Stärke, Sedamyl, AGRANA and Permolex. The businesses differ materially in product grade, processing footprint and customer mix, so revenue comparisons require a wheat-protein-specific perimeter rather than total company sales.
Roquette provides both native and soluble wheat-protein offerings for animal nutrition, while MGP supplies wheat gluten, functional isolates and textured wheat products. PureField highlights U.S.-based wheat protein manufacturing and direct sales into food and pet-food applications. Cargill and Tereos integrate protein into broader starch and ingredient operations. These distinctions influence contract strategy, customer technical support, cost allocation and exposure to international trade measures.
Competitive positioning is determined by reliable protein functionality, production economics, scale of starch co-products, geographic service capability and ability to meet end-market quality specifications. Where protein is purchased for narrowly defined technical performance, repeat approvals can strengthen supplier retention. Where the requirement is standard bulk gluten, landed price and service reliability remain decisive.
Recent Developments
October 2026: Canada's border agency published its preliminary determination detailing wheat-gluten dumping margins for exporters in Italy, Poland and the United Kingdom.
September 2026: Canada began collecting provisional anti-dumping duties on specified wheat-gluten imports following a September 17 preliminary determination.
July 2026: The Wheat Protein Association published 2025 worldwide wheat-protein demand of 1.485 million tonnes, highlighting growth in aquafeed applications.
June 2026: Canada initiated a new anti-dumping investigation into wheat-gluten imports from Italy, Poland and the United Kingdom.
June 2025: Roquette introduced NUTRALYS T WHEAT 600L, expanding its portfolio into textured wheat protein for meat-alternative formulations.
Wheat Protein Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.04 billion |
| Total Market Size in 2032 | USD 4.40 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.3% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Product Type, Application, Geography |
| Companies |
|
Market Segmentation
By Product Type
Vital / Native Wheat Gluten
Hydrolyzed / Soluble Wheat Protein
Textured and Specialty Wheat Proteins
By Application
Bakery and Milling
Aquafeed
Pet Food
Meat Alternatives
Calf Milk Replacers
Other Food and Nutrition
By Geography
North America
United States
Canada
Mexico and Others
South America
Brazil
Argentina
Others
Europe
France
Germany
United Kingdom
Italy
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Türkiye
Egypt
South Africa
Others
Asia Pacific
China
India
Japan
Thailand
Vietnam
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition and Product Boundaries
1.2. Research Scope and Exclusions
1.3. Currency, Study Period and Market Definitions
2. RESEARCH METHODOLOGY
2.1. Research Design and Source Hierarchy
2.2. Volume and Price Estimation
2.3. Company and Trade Data Triangulation
2.4. Validation, Assumptions and Scenarios
3. EXECUTIVE SUMMARY
3.1. Global Market Size and Forecast, 2026–2032
3.2. Segment and Geographic Findings
3.3. Strategic Implications
4. WHEAT PROTEIN INDUSTRY OUTLOOK
4.1. Wheat Processing and Co-product Economics
4.2. Production Capacity and Regional Trade
4.3. End-use Performance Requirements
4.4. Price and Margin Dynamics
4.5. Regulations, Allergen Management and Trade Remedies
5. MARKET DYNAMICS
5.1. Drivers
5.2. Restraints
5.3. Opportunities
5.4. Porter’s Five Forces
5.5. Value Chain Analysis
6. WHEAT PROTEIN MARKET BY PRODUCT TYPE
6.1. Vital / Native Wheat Gluten
6.2. Hydrolyzed / Soluble Wheat Protein
6.3. Textured and Specialty Wheat Proteins
7. WHEAT PROTEIN MARKET BY APPLICATION
7.1. Bakery and Milling
7.2. Aquafeed
7.3. Pet Food
7.4. Meat Alternatives
7.5. Calf Milk Replacers
7.6. Other Food and Nutrition
8. WHEAT PROTEIN MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico and Others
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. France
8.3.2. Germany
8.3.3. United Kingdom
8.3.4. Italy
8.3.5. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. United Arab Emirates
8.4.3. Türkiye
8.4.4. Egypt
8.4.5. South Africa
8.4.6. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.4.4. Thailand
8.4.5. Vietnam
8.4.6. Indonesia
8.5.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Manufacturer and Product Positioning
9.2. Capacity and Commercial Footprint
9.3. Product Launches, Partnerships and Investments
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Tereos
10.2. Roquette Frères
10.3. Archer Daniels Midland Company
10.4. Cargill, Incorporated
10.5. MGP Ingredients, Inc.
10.6. Manildra Group
10.7. PureField Ingredients
10.8. Crespel & Deiters Group
10.9. Kröner-Stärke
10.10. Sedamyl
10.11. AGRANA
10.12. Permolex Ltd.
11. APPENDIX
11.1. Assumptions
11.2. Market Data Definitions and Units
11.3. Supporting Source Register
11.4. Research Methodology
11.5. Abbreviations
Navigate
Trusted by the world's leading organizations











