
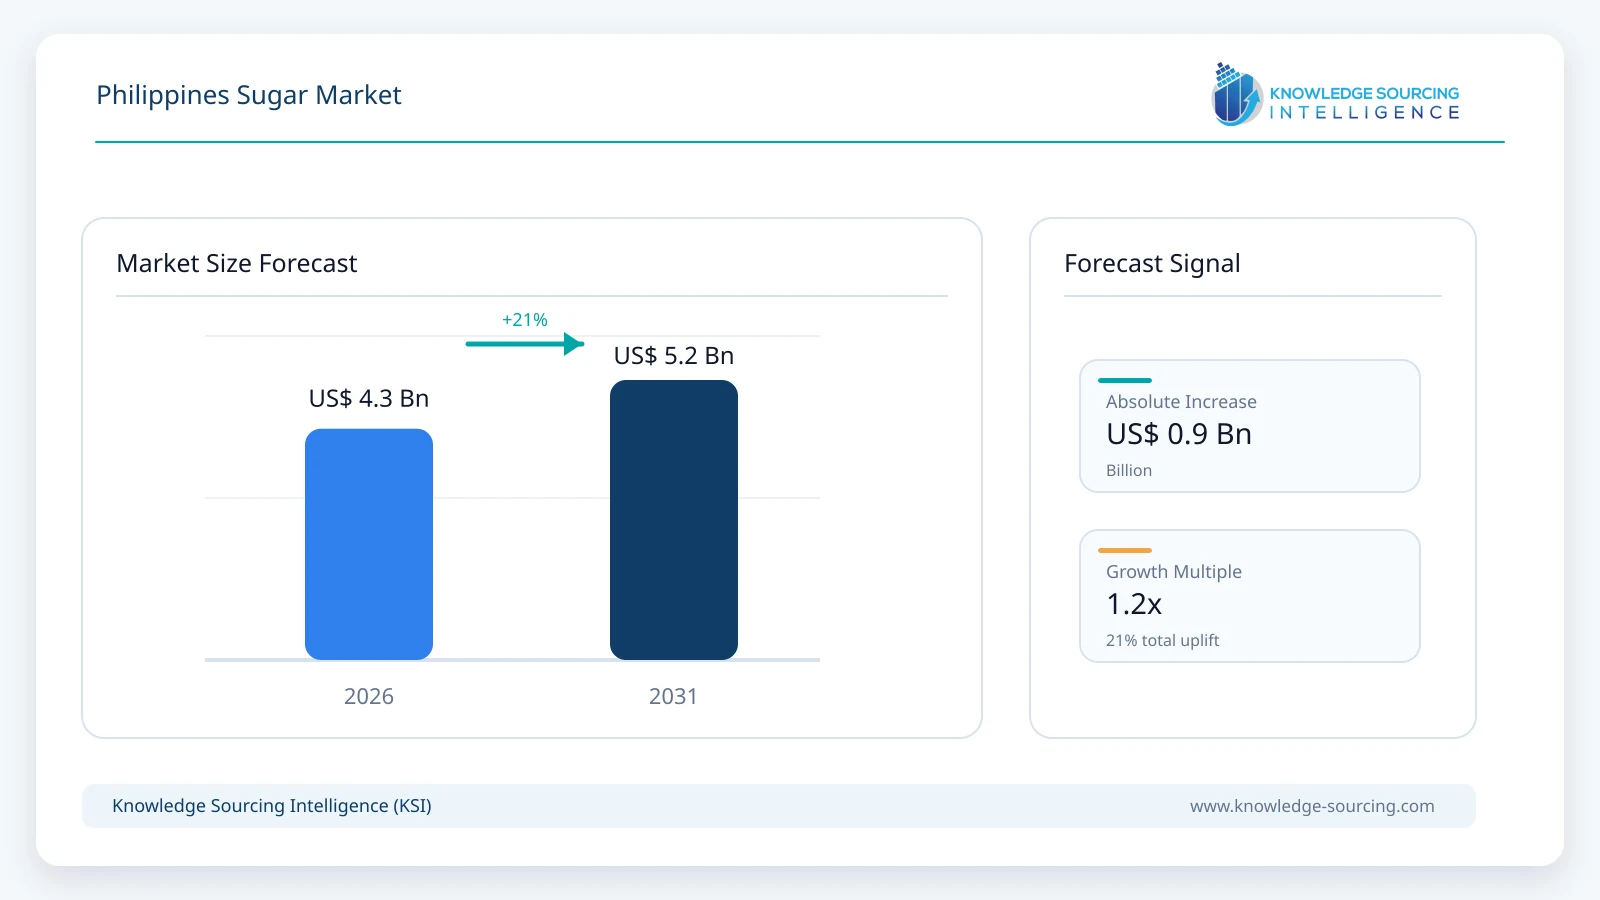
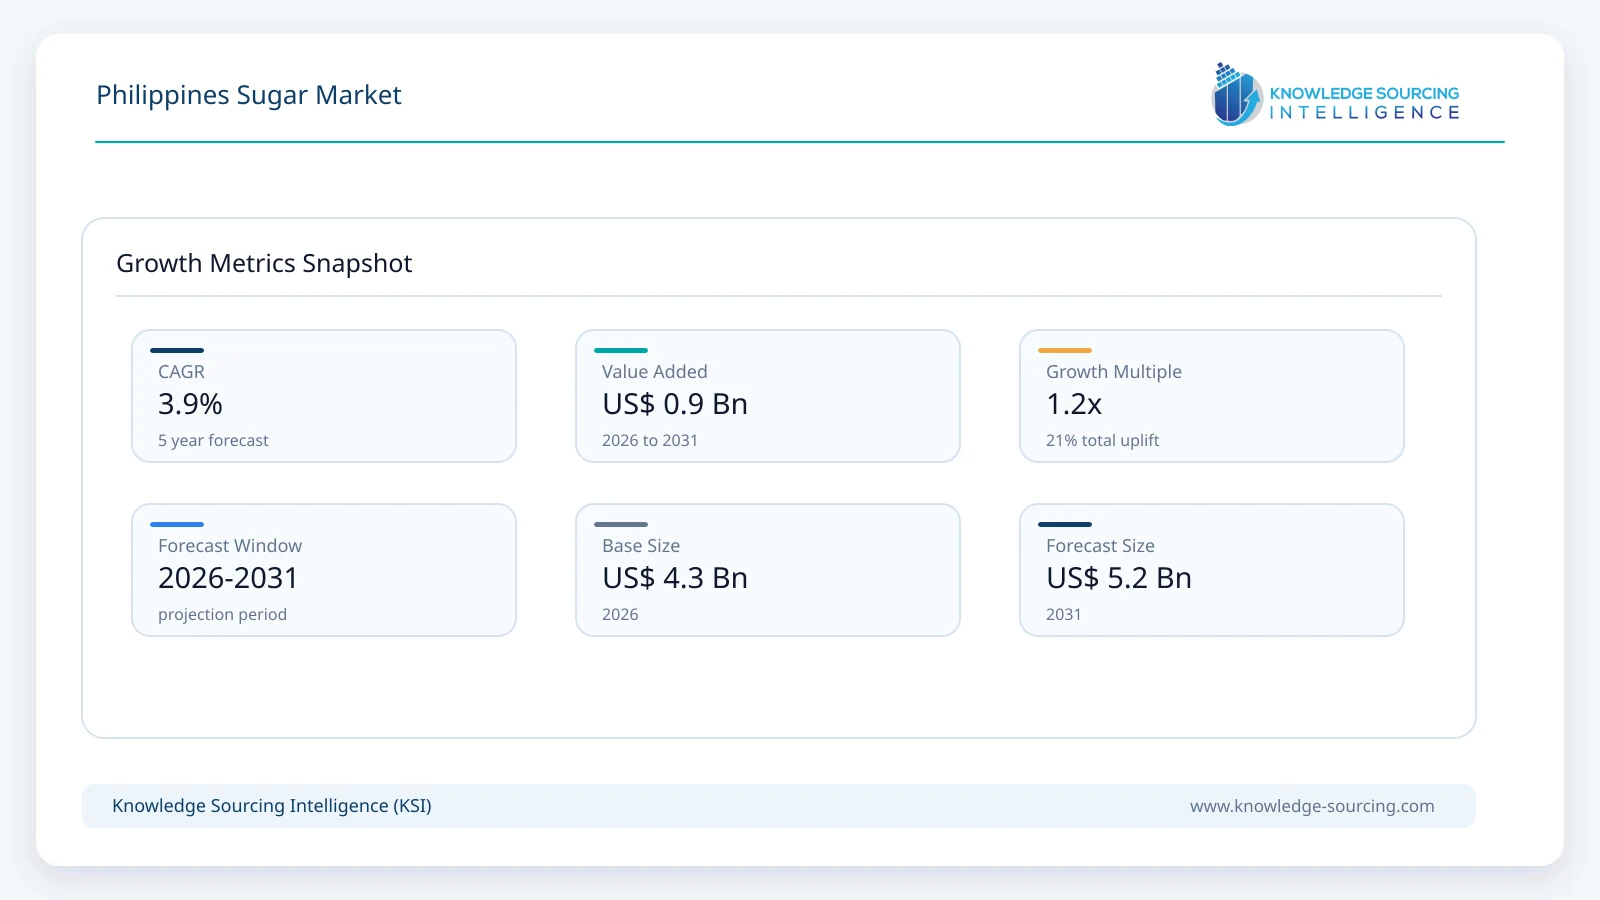
The Philippines Sugar Market is forecast to grow at a CAGR of 3.9%, reaching USD 5.17 billion in 2031 from USD 4.27 billion in 2026.
Highlights:
- 1Granulated sugar accounts for approximately 78% of total Philippine market value in 2026.
- 2Industrial food and beverage users account for approximately 50% of domestic sugar demand.
- 3USDA forecasts domestic sugar consumption at 2.3 million tonnes in marketing year 2026/27.
- 4Raw sugar production is forecast at 1.93 million tonnes for marketing year 2026/27.
- 5Liquid and syrup sugar forms are projected to grow around 6.5% annually through 2031.
Philippines Sugar Market Overview
The Philippines sugar market combines a large domestic consumption base with a tightly regulated production, trade, and inventory system. Sugarcane remains the country’s commercial production base, while domestic sugar requirements are supplied through locally produced raw and refined sugar supplemented periodically by regulated imports. USDA forecasts Philippine centrifugal sugar consumption at approximately 2.30 million metric tonnes in MY2026/27, up from an estimated 2.25 million tonnes in MY2025/26. Food and beverage manufacturers are the largest user group, accounting for around half of domestic demand, while household and institutional users account for the remaining consumption.
Production conditions remain less predictable than consumption. USDA forecasts centrifugal sugar production at approximately 1.93 million tonnes in MY2026/27, compared with an estimated 1.95 million tonnes in MY2025/26, as potential El Niño conditions and limited expansion of sugarcane acreage constrain output. Around 400,000 hectares are expected to remain under sugarcane, while land conversion, irrigation limitations, weather disruption and pest incidence restrict the ability of production to expand at the same pace as industrial demand.
Industry concentration also creates supply-chain exposure. Negros Occidental accounts for around 60% of national sugarcane production, making national supply particularly sensitive to weather and pest conditions in the region. SRA data for the 2025-2026 crop year showed 408,205 hectares under sugarcane by early May 2026, with 25 registered sugar centrals and 12 registered refineries. The concentration of milling and refining infrastructure creates operating scale but also increases the importance of inter-island logistics, inventory management, and government intervention during periods of supply imbalance.
Major Market Drivers
Expansion of Food and Beverage Manufacturing
Industrial food and beverage processing is the most important demand driver for sugar in the Philippines. Beverage manufacturers, confectionery companies, preserved-fruit processors, bakeries and other packaged-food producers account for approximately 50% of domestic sugar demand. USDA expects total consumption to continue increasing through MY2026/27 as population growth and manufactured food consumption offset weakness in some household purchasing categories.
Soft drinks represent a particularly important industrial outlet because carbonated beverages and other sweetened products are distributed across both urban and rural areas through modern retail, sari-sari stores, and foodservice channels. Manufacturers have adapted pack sizes to maintain affordability, helping sustain sugar-containing beverage volumes despite household price sensitivity. Confectionery demand is also expected to expand as product variety and promotional activity increase. This supports faster growth in industrial sugar demand than in direct household consumption during the forecast period.
Population Growth and Foodservice Consumption
Population growth provides a stable underlying demand base for sugar and sugar-containing products. Household demand remains significant, while restaurants, bakeries, hotels, institutional kitchens and other foodservice users create additional recurring requirements. USDA’s latest assessment divides domestic demand broadly into industrial users at 50%, households at 32% and institutional users at 18%, illustrating that sugar consumption extends well beyond retail packs purchased directly by consumers.
Foodservice growth also supports demand for processed beverages, bakery products, desserts and confectionery supplied through commercial channels. This gradually increases the importance of bulk and directly contracted sugar relative to small retail packaging, particularly among larger beverage and food manufacturers.
Major Market Restraints
Weather, Pest and Geographic Production Concentration
The principal supply-side restraint is the concentration of sugarcane production in areas exposed to rainfall variability, typhoons and crop disease. USDA forecasts lower production in MY2026/27 partly because of potential El Niño conditions, which can accelerate cane maturity while reducing cane volume and sugar content. During the 2023-2024 El Niño period, Philippine sugarcane production declined materially, demonstrating the sensitivity of the crop to prolonged dry conditions.
Pest pressure has added another layer of risk. More than 7,400 hectares were affected by red-striped soft scale insect infestation by the fourth quarter of 2025, while the pest can materially reduce sugar content in affected cane. Typhoon-related damage also affected more than 53,000 hectares of sugarcane in late 2025, with Negros Occidental bearing a significant share of the losses. The concentration of national output in Negros therefore magnifies the effect of localized production shocks.
Limited Yield Expansion and High Farm Input Costs
Long-term production growth is constrained by limited land availability, uneven irrigation access and high operating costs. USDA expects sugarcane area to remain near 400,000 hectares in MY2026/27, with conversion of agricultural land limiting meaningful acreage expansion. This places greater emphasis on productivity improvement rather than land expansion.
Farmer economics remain challenging when sugar prices weaken while fertilizer, fuel and labour costs remain elevated. USDA reported a decline in mill-site raw sugar prices during MY2025/26 even as farmers faced higher operating costs. Lower returns can reduce investment in inputs, irrigation and farm mechanisation, which in turn limits yield improvement and increases dependence on government support programs.
Philippines Sugar Market Trends
Industrial Demand Is Becoming More Important to Market Growth
Industrial users already account for roughly half of domestic sugar consumption and are expected to become increasingly important through 2031. Beverage, confectionery, preserved fruit and bakery manufacturers typically purchase in larger quantities and are more sensitive to refined sugar availability than individual households. This makes refinery utilisation, bulk supply contracts and regulated import availability increasingly important to the commercial market.
Trade Policy Is Being Used to Balance Farmer and Consumer Interests
The Philippine sugar market remains highly policy-dependent. Government decisions influence whether domestic sugar is classified for local consumption, reserve stocks or export and determine when imported sugar can enter the market. In January 2026, SRA issued Sugar Order No. 3 authorising up to 100,000 metric tonnes of raw sugar for export under the U.S. sugar quota, intended partly to reduce excess domestic raw sugar availability and support mill-site prices.
At the same time, the Department of Agriculture extended the general sugar import moratorium through December 2026 to prioritise domestic producers and prevent excessive supply from depressing local prices. The combination of export allocation and restricted imports demonstrates how policy is being used to manage supply rather than allowing domestic prices to track world markets directly.
Artificial Sweeteners Are Receiving Greater Regulatory Attention
Alternative sweeteners have become increasingly relevant to the sugar market as beverage and processed-food manufacturers evaluate formulation costs and sugar-reduction strategies. On August 8, 2026, SRA issued Sugar Order No. 5 establishing guidelines for the importation of artificial sweeteners covered by specified ASEAN tariff classifications. The order reflects the growing importance of monitoring non-sugar sweetener supply when assessing domestic sugar demand.
Digital Monitoring Is Increasing Supply-Chain Transparency
SRA continues expanding digital monitoring across sugar stocks, warehouse registration, release orders and production reporting. The agency’s monitoring framework covers raw sugar, refined sugar, inventories, warehouse movements and imported sugar clearances. Better monitoring improves visibility over national availability and allows policy intervention to respond more quickly to shifts in production, imports and consumption.
Segment Analysis:
By Form
Granulated Sugar
Granulated sugar accounts for approximately 78% of Philippine sugar market value in 2026, making it the dominant commercial form. Its position reflects broad use across beverage production, confectionery, baking, food processing, institutional kitchens and household consumption.
The segment is projected to continue expanding in absolute value through 2031 but to lose a small amount of market share as liquid sugar and syrup-based forms expand faster within large-scale food and beverage manufacturing. Granulated sugar nevertheless remains the industry’s core product because it can be sold directly to households or converted into more specialised downstream formulations.
By End Use
Food and Beverage Processing
Food and beverage processing accounts for approximately 50% of domestic sugar demand in 2026 and represents the largest end-use category. USDA identifies beverages, preserved fruits and confectionery among the major industrial users, while bakery and other packaged-food applications add further demand.
The segment is projected to grow at approximately 4.7% annually through 2031, modestly faster than the overall market. Expansion is supported by packaged-food production, beverage distribution, foodservice demand and continued population growth. Industrial users also require consistent specification and supply reliability, making refined sugar inventories and direct procurement arrangements commercially important.
By Sales Channel
Direct and Bulk Industrial Sales
Direct and bulk industrial sales account for approximately 51% of market value in 2026 and remain the largest sales channel. Major beverage, confectionery, food-processing and institutional buyers typically procure sugar through contracted supply arrangements, millers, refiners, traders or authorised distributors rather than through consumer retail channels.
The channel is expected to gain modest share through 2031 as industrial food and beverage demand expands faster than household consumption. Government-controlled imports and reserve-stock programs also tend to have their greatest commercial impact on larger industrial users that require consistent refined sugar availability.
Production and Supply Outlook
The Philippine sugar industry remains almost entirely dependent on sugarcane. USDA records zero domestic beet sugar production across its current Philippine supply-and-demand balance, making sugarcane the relevant agricultural production base for market analysis.
SRA statistics showed approximately 1.72 million tonnes of raw sugar and 554,609 tonnes of refined sugar produced by May 3, 2026, although these figures represented the crop year only through that reporting date. USDA’s full-year estimate places MY2025/26 raw sugar production at approximately 1.95 million tonnes and MY2026/27 at 1.93 million tonnes.
Production growth therefore remains significantly slower than demand growth. The long-term market increasingly depends on higher cane yields, improved irrigation, better pest management and more efficient milling rather than substantial expansion in planted area.
Pricing and Trade Outlook
Domestic sugar prices do not move directly with global benchmark prices because SRA controls classifications, imports and export allocations. This regulatory structure can protect farmers from periods of low international prices but can also create local price premiums when domestic supply tightens.
USDA reported that raw sugar mill-site prices declined during MY2025/26 even though retail sugar prices fell much more slowly. Excess refined inventories, weak mill-site bidding and elevated farmer costs created pressure on producer margins. Imported refined sugar from ASEAN suppliers can potentially enter at significantly lower landed costs than prevailing Philippine retail prices, which explains the government’s cautious approach to import timing.
Trade policy is therefore expected to remain a significant market variable through 2031, with import and export decisions calibrated around domestic stocks, producer prices and industrial supply requirements.
Competitive Landscape
The Philippines sugar industry is characterised by a combination of integrated milling and refining companies, independent sugar centrals, trading organisations and diversified food manufacturers with sugar operations. Competition depends heavily on milling capacity, refinery access, proximity to cane-growing areas, logistics capability and relationships with planters.
Victorias Milling Company remains one of the best-known integrated sugar companies in Negros, while Universal Robina Corporation participates through its sugar and renewables operations. Binalbagan-Isabela Sugar Company, Central Azucarera de Tarlac, Hawaiian-Philippine Company, Busco Sugar Milling Company and other regional operators contribute significant milling or refining capacity.
The industry’s structure differs from a conventional branded consumer-goods market because much of the commercial volume moves through industrial contracts, sugar traders and wholesale distribution. Competitive positioning therefore depends more on cane supply, recovery rates, refinery utilisation, logistics and regulatory participation than on consumer branding alone.
Recent Developments
August 8, 2026: SRA issued Sugar Order No. 5 establishing guidelines for artificial sweetener imports.
March 9, 2026: SRA ended acceptance of applications under the 2025-2026 voluntary local raw sugar purchase program.
January 9, 2026: SRA authorised up to 100,000 metric tonnes of raw sugar exports under the 2026 U.S. quota.
December 21, 2025: The Department of Agriculture extended the sugar import moratorium through December 2026.
Market Outlook
The Philippines sugar market is expected to expand, supported primarily by food and beverage manufacturing, population growth and sustained institutional consumption. Growth remains moderate because sugar is already a mature household commodity and because production expansion is constrained by acreage, yield and weather conditions.
Industrial demand increases in importance through the forecast period, while household consumption grows more slowly. Granulated sugar remains the dominant form, although liquid and syrup products gain share among larger processors seeking efficient bulk handling and consistent formulation.
Supply remains the key uncertainty. USDA forecasts domestic consumption above domestic raw sugar production in MY2026/27, implying continued reliance on inventory management and periodic trade intervention. Government policy is therefore expected to remain central to the market’s balance between producer profitability, industrial supply security and consumer affordability.
Philippines Sugar Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.27 billion |
| Total Market Size in 2031 | USD 5.17 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Form , End-Use, Sales Channel |
| Companies |
|
Market Segmentation
By Form
· Granulated Sugar
· Powdered Sugar
· Liquid Sugar and Syrup
By End Use
· Food and Beverage Processing
· Household and Retail Consumption
· Institutional and Foodservice
By Sales Channel
· Direct and Bulk Industrial Sales
· Wholesale and Offline Retail
· Online Retail
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Philippines Sugar Market Size, 2026-2031
1.3. Production and Consumption Outlook
1.4. Sugar Form Outlook
1.5. End-Use Outlook
1.6. Sales Channel Outlook
1.7. Analyst View
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Historical and Forecast Period
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of Beverage, Confectionery and Processed Food Manufacturing
3.1.2. Population Growth and Rising Foodservice Sugar Consumption
3.1.3. SRA Supply Management Supporting Domestic Availability
3.1.4. Growth of Liquid and Specialty Sugar for Industrial Processing
3.2. Market Restraints
3.2.1. Weather, Pest and Production Concentration in Negros
3.2.2. Limited Cane Area Expansion, Low Yield and Rising Farm Input Costs
3.2.3. Alternative Sweeteners and Sugar-Reduction Reformulation
3.2.4. Trade Policy Uncertainty and Domestic Price Distortions
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Strategic Recommendations
4. PHILIPPINES SUGAR PRODUCTION AND SUPPLY OUTLOOK
4.1. Sugarcane Area and Harvested Area
4.2. Raw Sugar Production
4.3. Refined Sugar Production
4.4. Sugarcane Yield and Sugar Recovery
4.5. Milling Capacity
4.6. Refining Capacity
4.7. Inventory and Buffer Stock
4.8. Production Concentration in Negros
4.9. Weather and Pest Risk
5. PHILIPPINES SUGAR TRADE AND PRICING OUTLOOK
5.1. Domestic Supply and Demand Balance
5.2. Raw Sugar Imports and Exports
5.3. Refined Sugar Imports
5.4. U.S. Tariff-Rate Quota
5.5. Mill-Site Price Trends
5.6. Retail Sugar Price Trends
5.7. Import Parity and Domestic Price Premium
5.8. SRA Sugar Classification and Quedan System
6. REGULATORY AND POLICY OUTLOOK
6.1. Sugar Regulatory Administration
6.2. Sugarcane Industry Development Act
6.3. Domestic Sugar Allocation Policy
6.4. Import and Export Programs
6.5. Reserve and Buffer Stock Policy
6.6. Artificial Sweetener Import Regulation
6.7. Sugar Monitoring System Digitalisation
7. PHILIPPINES SUGAR MARKET BY FORM
7.1. Introduction
7.2. Granulated Sugar
7.3. Powdered Sugar
7.4. Liquid Sugar and Syrup
8. PHILIPPINES SUGAR MARKET BY END USE
8.1. Introduction
8.2. Food and Beverage Processing
8.2.1. Beverages
8.2.2. Confectionery
8.2.3. Bakery and Processed Foods
8.2.4. Preserved Fruits and Other Food Processing
8.3. Household and Retail Consumption
8.4. Institutional and Foodservice
9. PHILIPPINES SUGAR MARKET BY SALES CHANNEL
9.1. Introduction
9.2. Direct and Bulk Industrial Sales
9.3. Wholesale and Offline Retail
9.4. Online Retail
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Victorias Milling Company, Inc.
11.2. Universal Robina Corporation
11.3. Binalbagan-Isabela Sugar Company, Inc.
11.4. Central Azucarera de Tarlac, Inc.
11.5. Hawaiian-Philippine Company
11.6. Busco Sugar Milling Company, Inc.
11.7. Crystal Sugar Company, Inc.
11.8. First Farmers Holding Corporation
11.9. Sagay Central, Inc.
11.10. Lopez Sugar Corporation
11.11. Raw Brown Sugar Milling Company, Inc.
11.12. Central Azucarera Don Pedro, Inc.
12. APPENDIX
Navigate
Trusted by the world's leading organizations











