
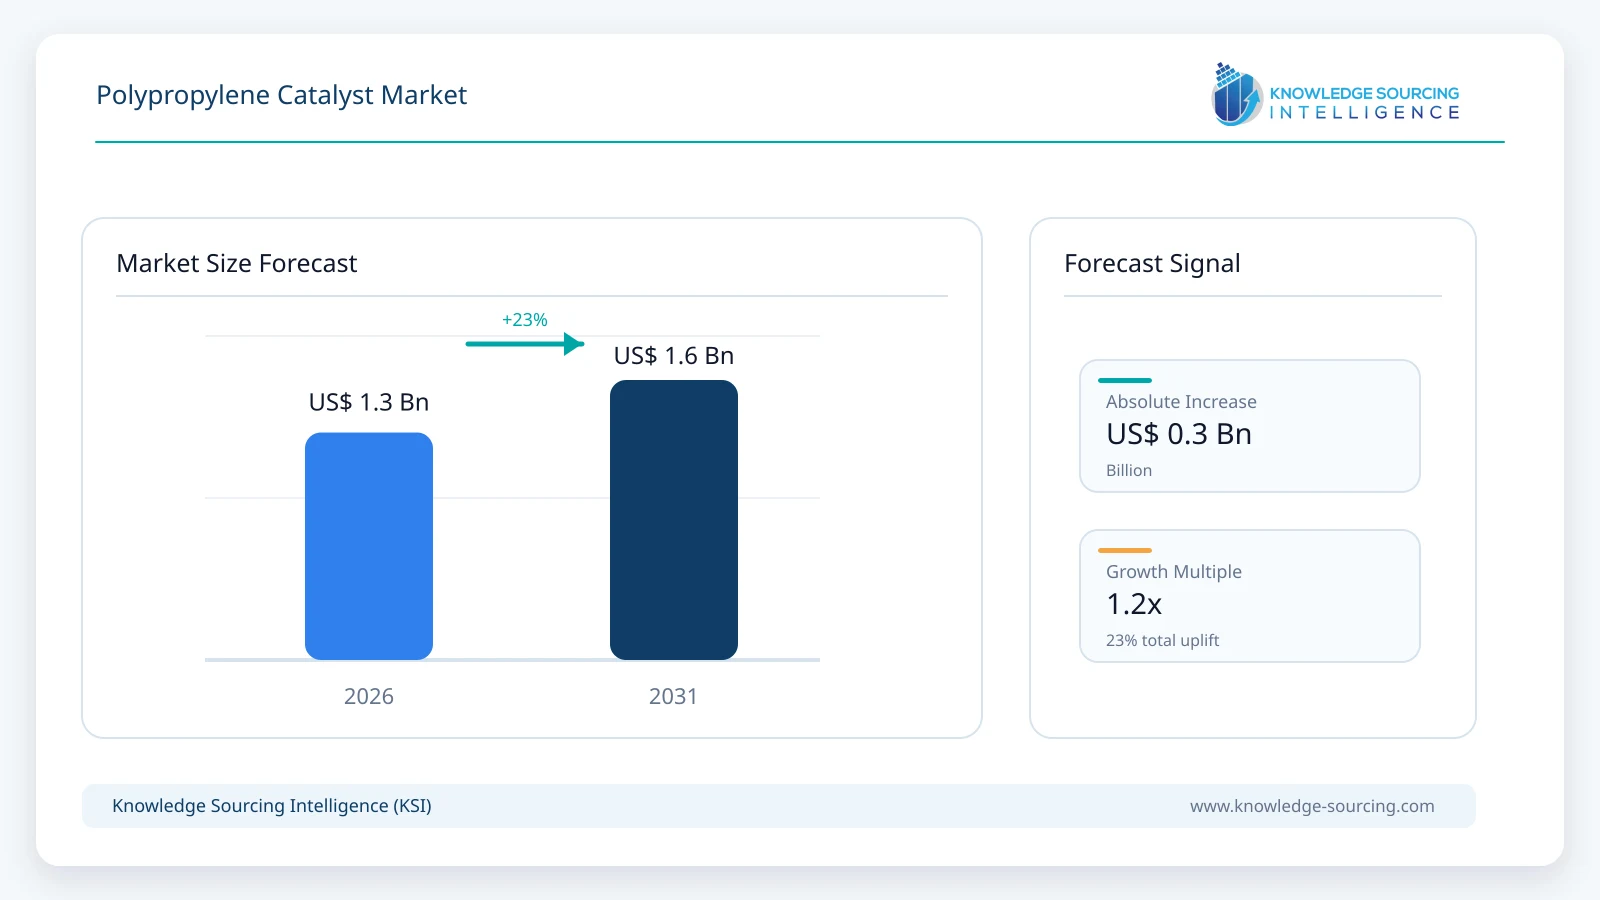
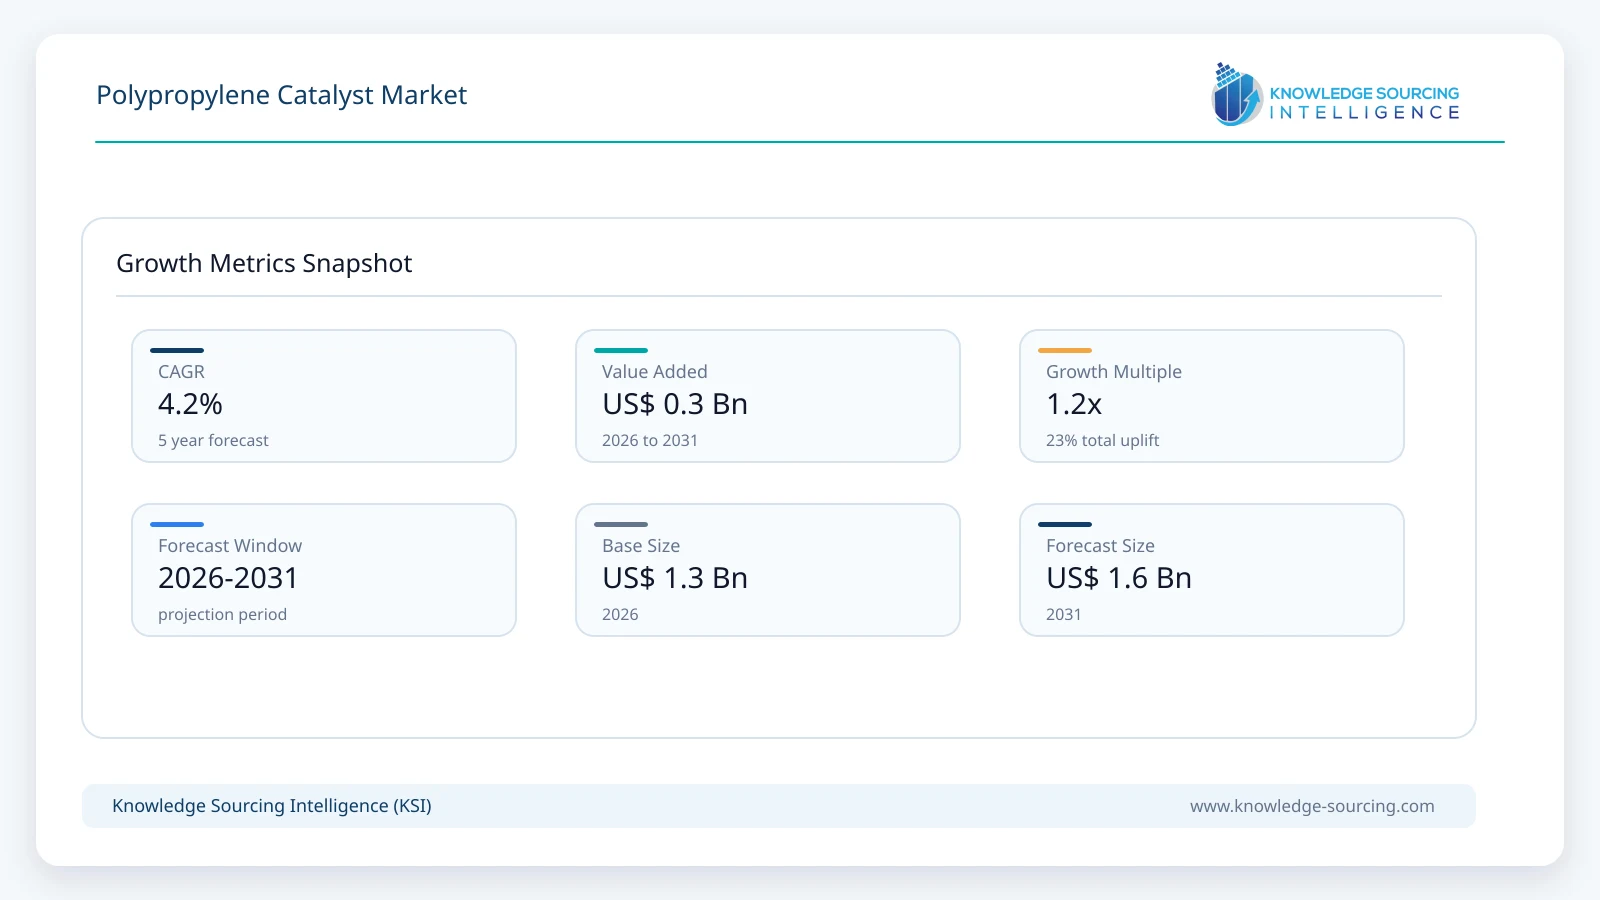
The Polypropylene Catalyst market is forecast to grow at a CAGR of 4.2%, reaching USD 1.6 billion in 2031 from USD 1.3 billion in 2026.
Highlights:
- 1The automotive industry is increasing use of polypropylene for lightweight components.
- 2Innovations in catalyst technologies are improving polypropylene recyclability.
- 3Emerging economies are expanding production capacities and urbanization.
- 4Producers are focusing on eco-friendly catalyst solutions to meet regulations.
Polypropylene catalysts are initiators and regulators of the polymerization process, which changes propylene monomer into a polymer of polypropylene. They determine most properties of the final polypropylene product: its molecular weight, stereoregularity, and crystallinity. The two types of catalysts commonly used in the process are Ziegler-Natta and metallocene, the latter being the less applied type. These catalysts are crucial in producing a wide variety of polypropylene products with tailored properties to meet the diverse needs of various industries.
The increasing focus on sustainability is also influencing the market as innovations in catalyst technologies are being driven. The producers are focusing on developing catalysts that enable the production of recyclable and eco-friendly polypropylene to match environmental regulations and consumer demands. The emerging economies are rapidly industrializing and urbanizing, adding to the market growth by raising their polypropylene production capacities. These trends, along with improvements in catalyst performance and product customization, are all contributing to the steady expansion of the polypropylene catalyst market globally.
Market Drivers
Increasing Demand in the Automotive Industry
The expanding automotive industry drives the polypropylene catalyst market highly due to increasing demand for lightweight, durable, and cost-effective materials. It is critical in reducing vehicle weight, enhancing fuel efficiency, and fulfilling stringent environmental regulations, particularly with the emergence of electric vehicles (EVs). Considering its strength, chemical resistance, and recyclability, it is widely used for interior components, exterior bumpers, fenders, and battery housings for electric vehicles. Advanced catalyst technologies allow the production of high-performance polypropylene with tailored properties, with the potential to enhance toughness and aesthetics.
According to the International Organization of Motor Vehicle Manufacturers (OICA), global motor vehicle production reached approximately 96.4 million units in 2025, representing a 3.9% increase from 92.7 million units in 2024. This growth reflects continued activity across major automotive manufacturing economies, including China, the United States, Japan, and India. As vehicle manufacturers pursue lightweight construction, improved material efficiency, and more sustainable vehicle designs, polypropylene remains an important material for automotive interiors and components. Porsche Engineering, in a company-published article dated July 5, 2025, highlighted polypropylene's role in vehicle interior applications because of its relatively low cost, ease of processing, and recyclability. These applications may support demand for polypropylene and, consequently, the catalysts used in its production, although the extent of this impact depends on automotive material selection and broader polypropylene demand.
Advancements in Technology
Technological advancement in polypropylene catalysts has greatly improved the efficiency, sustainability, and versatility of the production process. Innovations such as SSCs have control polymer properties with higher yield and faster cycles, while the Ziegler-Natta catalyst has improved reactivity, selectivity, and lower environmental impact.
These innovations enhance the quality and purity of polypropylene and tend to make production more efficient and environment-friendly by using less waste and emissions. Moreover, improved catalysts allow higher recyclability of polypropylene, which helps in working towards global sustainability goals and enhances the overall value of advanced catalyst technologies.
Market Restraints:
High production costs for advanced catalysts and regulatory pressures for more sustainable processes are the major challenges for the polypropylene catalyst market. The competition from alternative materials and biopolymers limits polypropylene's market share. Fluctuating raw material prices and dependence on the petrochemical industry add to the risks. Additionally, technological gaps in recycling and a lack of skilled professionals hamper efficiency and growth. Market consolidation restricts competition, which slows innovation. These factors collectively have been constraining the polypropylene catalyst market’s growth.
Geographical Analysis:
The polypropylene catalyst market is segmented into five regions worldwide
Geography-wise, the market of polypropylene catalysts is divided into North America, South America, Europe, the Middle East and Africa, and Asia Pacific. Rapid industrialization and urbanization, especially in countries like China and India, drive the Asia Pacific polypropylene catalyst market due to increased demand from the packaging, automotive, and textile industries. Furthermore, the region has a strong manufacturing base and competitive export advantage for boosting polypropylene catalyst consumption. Packaging industry growth is largely being driven by e-commerce and retail development, mainly for cost-effectiveness, making polypropylene their material of choice. In addition, the automotive industry’s expansion with rising consumer demand for EVs will promote the market. Due to government investments in infrastructure and production lines, the increased usage of materials in applications is assured. For example, Invest India claims that the Indian construction market will reach USD 1.4 trillion by 2025, whereas the cities alone will contribute 70% of the national GDP.
Demand from the automotive, packaging, and construction industries continues to support the North American polypropylene value chain. The automotive sector's requirement for lightweight, durable plastic components and the growing emphasis on recycled materials are creating opportunities for polypropylene applications. In July 2026, PureCycle Technologies and Motherson announced the successful production of an automotive bumper prototype incorporating 30% recycled polypropylene. The prototype was manufactured at Motherson's facility in Tuscaloosa, Alabama, and underwent climate and mechanical performance testing, demonstrating progress in incorporating recycled polypropylene into demanding automotive applications. These developments highlight the potential for polypropylene materials in vehicle components and circular manufacturing initiatives. However, recycled polypropylene adoption does not directly establish increased catalyst consumption, as demand for virgin resin, recycling technologies, and polymer production processes can evolve differently. Overall, investment in material performance, lightweighting, and recycling provides relevant indicators for the regional polypropylene industry.
The European polypropylene catalyst market is supported by demand from automotive manufacturing, packaging, and construction, alongside investment in recyclable and high-performance polymer materials. In May 2025, Borealis announced an investment of more than EUR 100 million in a new high-melt-strength polypropylene production line at its Burghausen facility in Germany. Scheduled to start up in the second half of 2026, the line is designed to triple the company's supply capability for recyclable polypropylene foam solutions used in automotive, consumer product, and building applications. In September 2025, Borealis also announced that its compounding line in Beringen, Belgium, had become fully operational, producing recycled polypropylene and polyethylene compounds for demanding applications, including mobility and consumer products. These investments demonstrate the region's focus on improving polymer production capabilities and expanding circular material solutions. Continued demand for high-performance polypropylene, combined with investments in production technology and recycling, provides a basis for assessing the European catalyst market's development. Nevertheless, these company announcements demonstrate activity across the polypropylene value chain rather than directly quantifying catalyst demand.
Recent Developments
September 2026: Clariant updated its PolyMax™ 600 product information, reaffirming its fifth-generation, phthalate-free Ziegler–Natta catalyst as a commercially available alternative for polypropylene production with strong hydrogen response and isotacticity control.
February 2026: Clariant updated its official PolyMax™ 500 product information, detailing the catalyst’s activity, isotacticity control, and applicability across major polypropylene production processes, including bulk-loop and gas-phase technologies.
October 2025: Clariant featured its PolyMax™ 600 phthalate-free polypropylene catalyst, jointly developed with Lummus Novolen Technology, at K 2025, highlighting improved catalyst activity and polymer performance.
July 2025: SIBUR and Lomonosov Moscow State University announced development of Russia’s first metallocene polypropylene catalyst, targeting innovative polymer grades for medical, transportation, and packaging applications.
Polypropylene catalyst market scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.3 billion |
| Total Market Size in 2031 | USD 1.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Production Process, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Ziegler-Natta Catalyst
Metallocene Catalyst
Others
By Production Process
Bulk Process
Gas-Phase Process
Slurry Phase
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Rest of Europe
Middle East and Africa
Saudi Arabia
United Arab Emirates
Rest of the Middle East and Africa
Asia-Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Rest of Asia-Pacific
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key benefits for the stakeholders
2. RESEARCH METHODOLOGY  
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Increasing Demand in the Automotive Industry
4.1.2. Advancements in Technology
4.2. Market Restraints
4.2.1. High Production Costs
4.2.2. Competition from Alternative Materials
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. The Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. POLYPROPYLENE CATALYST MARKET BY TYPE
5.1. Introduction
5.2. Ziegler Natta Catalyst
5.3. Metallocene Catalyst
5.4. Others
6. POLYPROPYLENE CATALYST MARKET BY PRODUCTION PROCESS
6.1. Introduction
6.2. Bulk Process
6.3. Gas-Phase Process
6.4. Slurry Phase
6.5. Others
7. POLYPROPYLENE CATALYST MARKET BY GEOGRAPHY
7.1. Global Overview
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Rest of South America
7.4. Europe
7.4.1. United Kingdom
7.4.2. Germany
7.4.3. France
7.4.4. Italy
7.4.5. Spain
7.4.6. Rest of Europe
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. United Arab Emirates
7.5.3. Rest of the Middle East and Africa
7.6. Asia-Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Taiwan
7.6.6. Thailand
7.6.7. Indonesia
7.6.8. Rest of Asia-Pacific
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. ExxonMobil Chemical
9.2. Riogen
9.3. Borealis
9.4. W.R. Grace
9.5. Clariant
9.6. Ineos
9.7. Toho Titanium Co., Ltd.
9.8. Japan Polypropylene Corporation
9.9. LyondellBasell Industries
9.10. Mitsui Chemicals
9.11. Lummus Technology





Frequently asked questions
What is the projected market size and growth rate for polypropylene catalysts?
Market forecast to reach $1.6 billion by 2031, growing at 4.2% CAGR.
What are the primary growth drivers for the Polypropylene Catalyst Market?
Automotive demand, catalyst innovation, and emerging economies are key drivers.
Which industry is significantly driving polypropylene catalyst demand?
The automotive industry, for lightweight and EV components, is a major driver.
What types of catalysts are commonly used in polypropylene production?
Ziegler-Natta and metallocene are the commonly used catalyst types.
How is sustainability influencing the Polypropylene Catalyst Market?
Focus is on eco-friendly, recyclable catalysts meeting environmental regulations.
What properties of polypropylene do these catalysts determine?
They determine molecular weight, stereoregularity, and crystallinity of polypropylene.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Polypropylene Catalyst Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/polypropylene-catalyst-market