
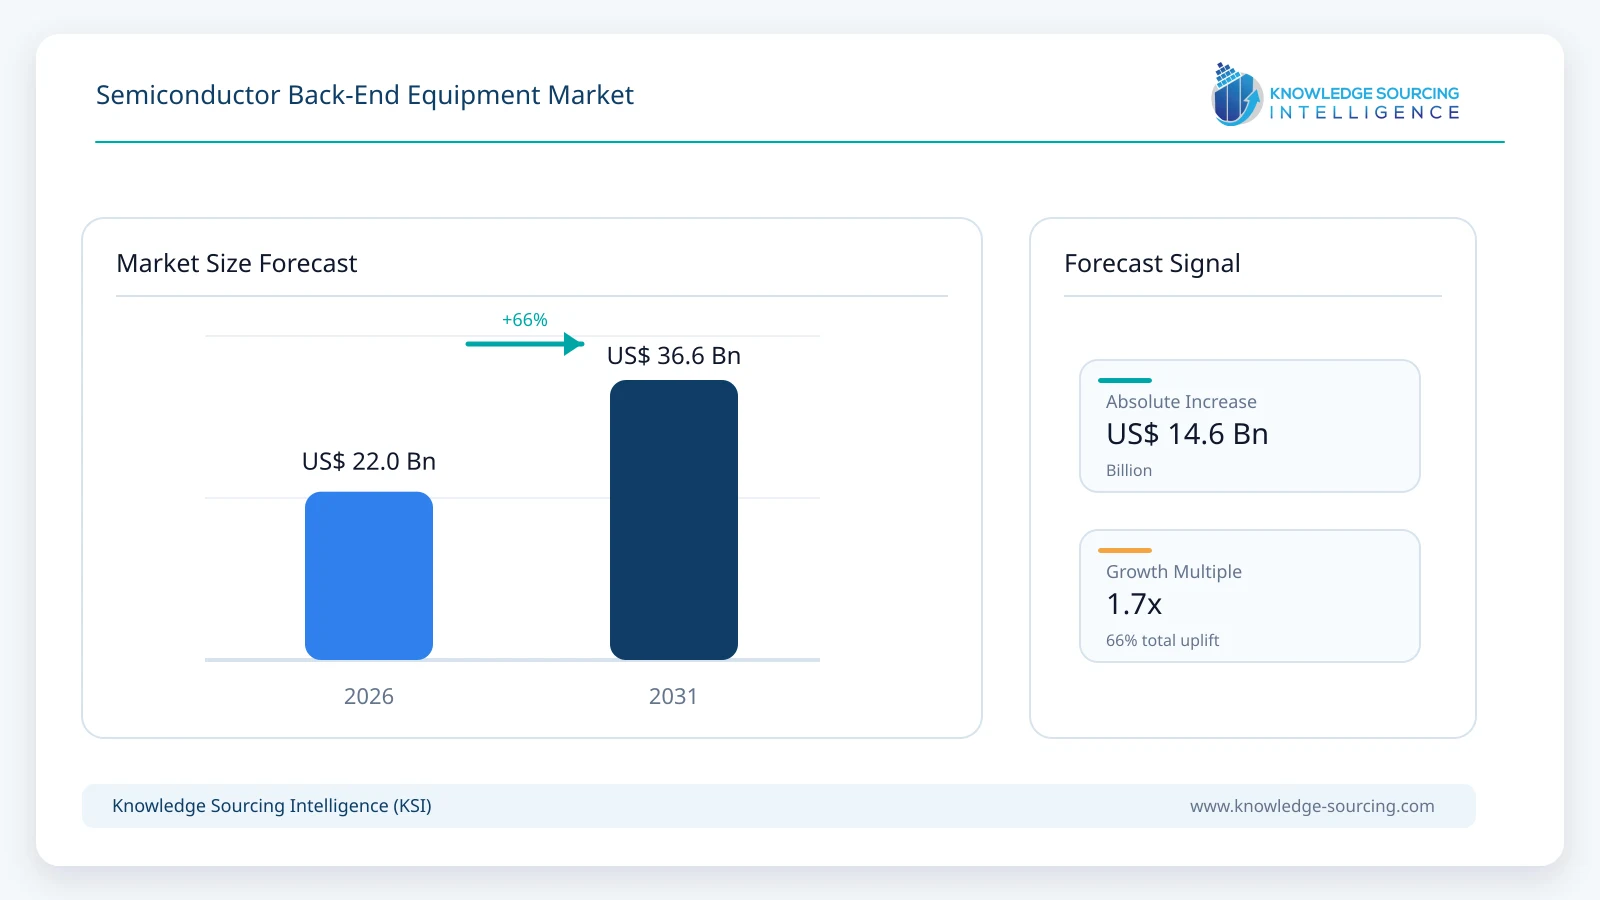
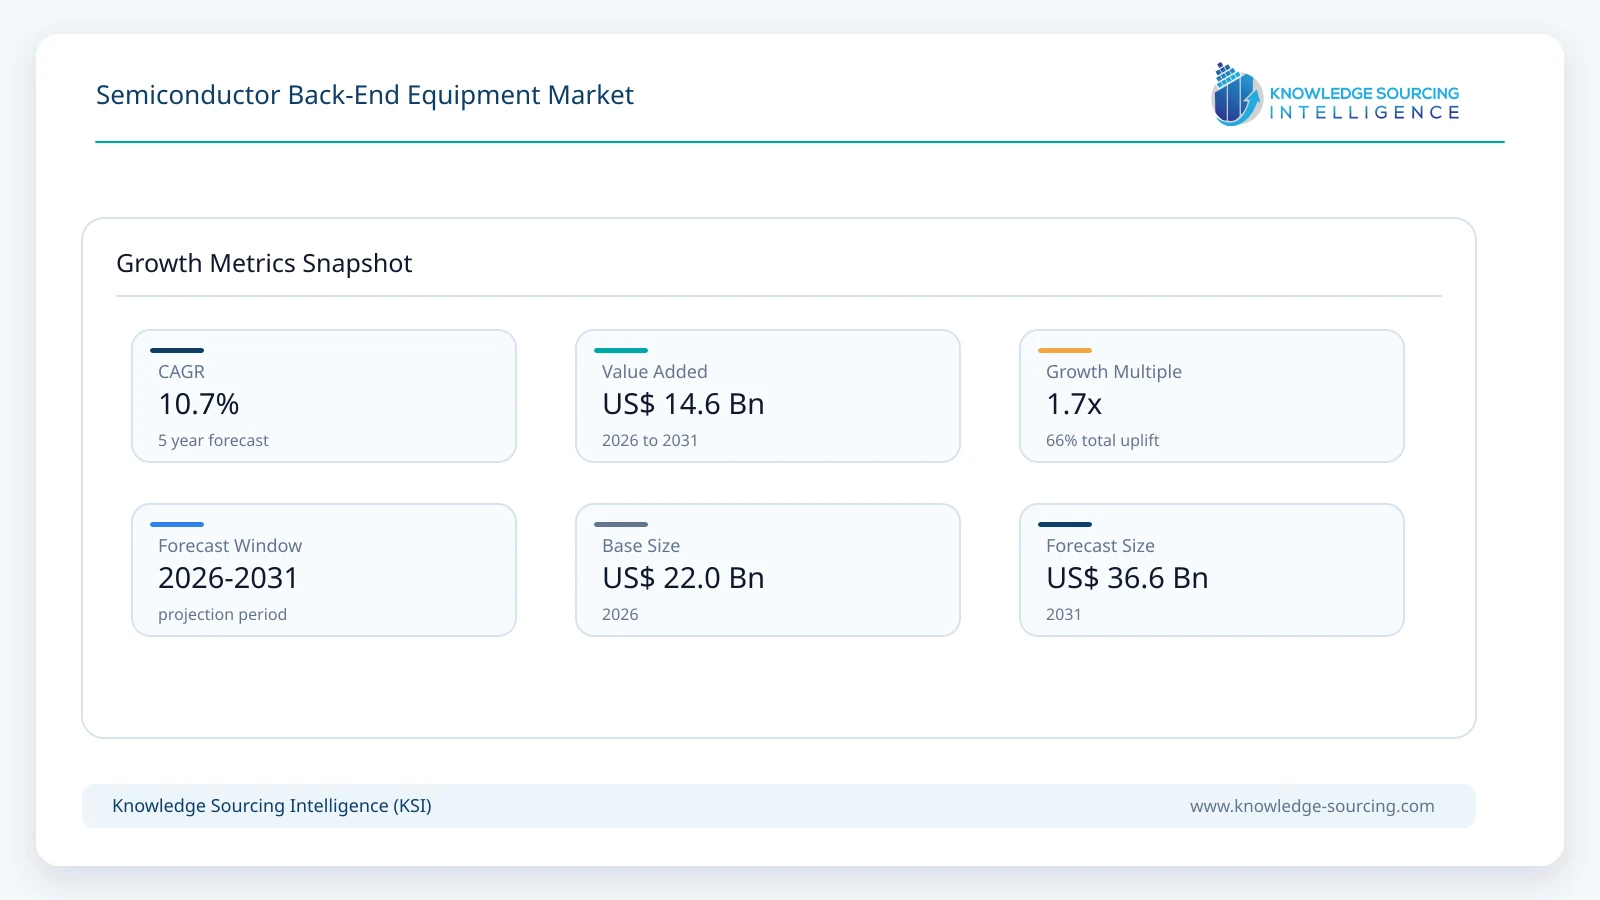
The Semiconductor Back-End Equipment Market is expected to register a CAGR of 10.7%, increasing from USD 22.0 billion in 2026 to USD 36.6 billion by 2031.
Highlights:
- 1Semiconductor test equipment represents approximately 70% of back-end equipment spending in 2026.
- 2Advanced bonding equipment is projected to grow above 20% annually through 2031.
- 3OSAT companies account for approximately 45% of equipment demand in 2026.
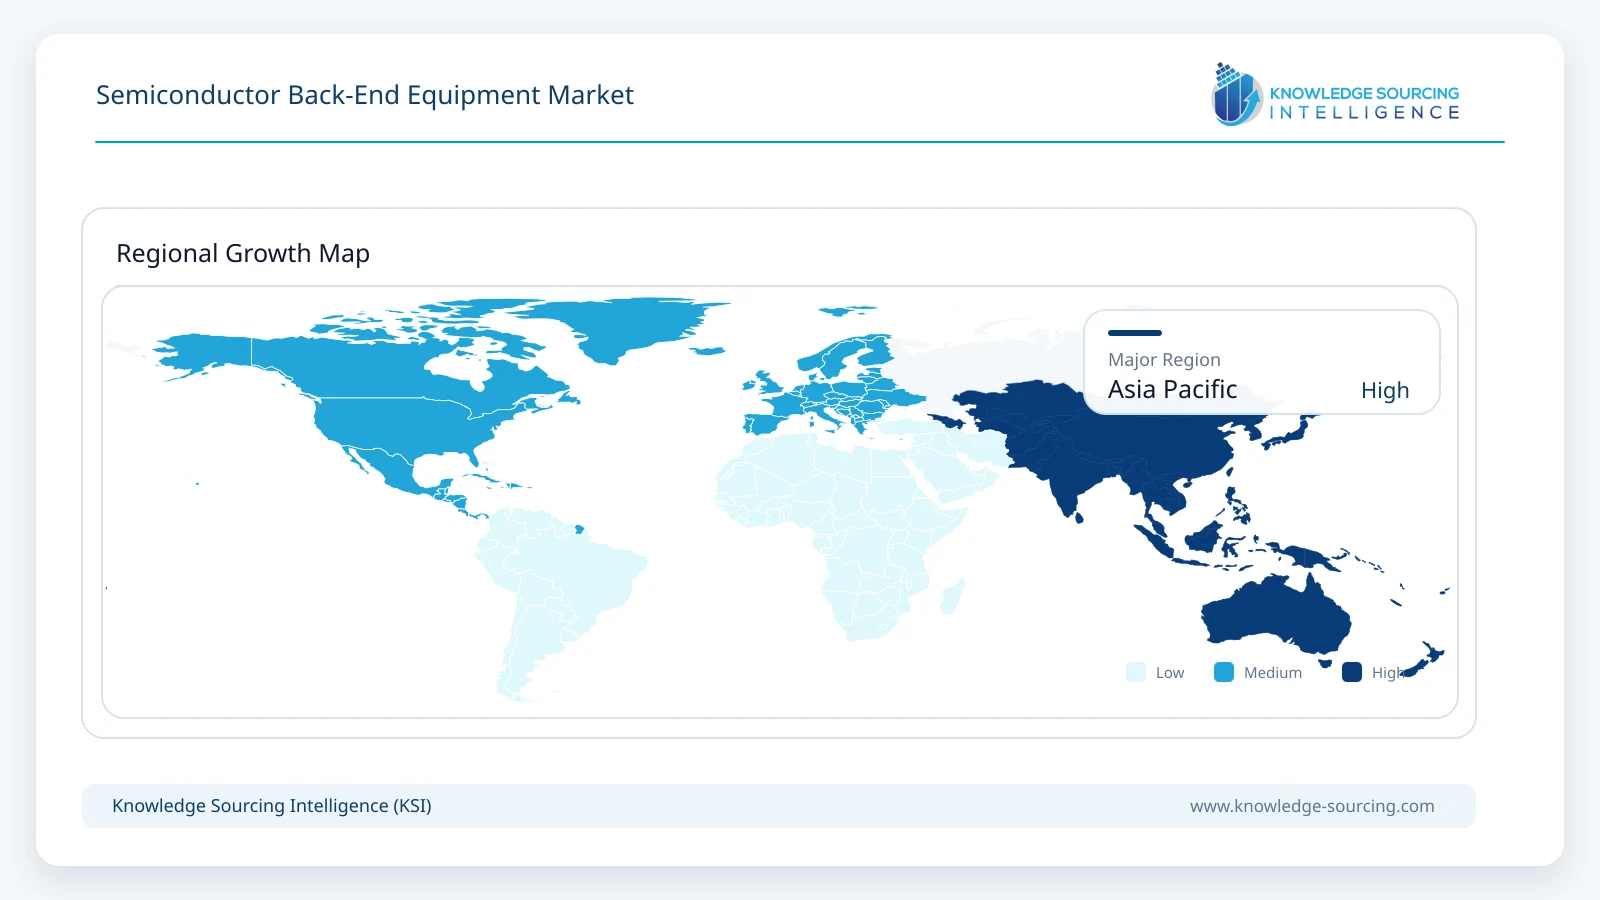
- 4Asia Pacific contributes more than 80% of global back-end equipment spending in 2026.
- 5HBM and AI accelerators are increasing test intensity and advanced packaging requirements.
- 6Hybrid and thermo-compression bonding gain share as interconnect pitches continue shrinking.
Semiconductor back-end equipment includes systems used after wafer fabrication to test, separate, assemble, package, inspect and qualify semiconductor devices before shipment. Major processes include wafer probing and sort, dicing and singulation, die and wire bonding, flip-chip and thermo-compression bonding, molding and encapsulation, package inspection, metrology, handling and final electrical test. These processes increasingly influence semiconductor performance, reliability and manufacturing economics as device architectures shift toward chiplets, high-bandwidth memory, heterogeneous integration and three-dimensional packaging.
Artificial intelligence has materially changed the demand outlook for back-end equipment. SEMI forecasts semiconductor test equipment sales of USD 15.3 billion in 2026, increasing 31% year over year, while assembly and packaging equipment sales are projected to reach USD 6.7 billion, up 9.6%. Combined spending places the market at approximately USD 22.0 billion in 2026. SEMI expects continued investment through 2028 as AI, HBM and increasingly complex semiconductor architectures require more testing and packaging equipment.
The equipment mix is changing alongside package architecture. Leading AI accelerators increasingly combine logic dies, HBM stacks, interposers and multiple supporting components within the same package. These structures require tighter placement tolerances, finer interconnects, advanced bonding, three-dimensional inspection and more extensive testing than conventional single-die packages.
Back-end manufacturing is consequently becoming a more strategic part of semiconductor production. Foundries are expanding advanced packaging capabilities, memory manufacturers are increasing HBM capacity and outsourced semiconductor assembly and test companies are investing in increasingly sophisticated packaging and testing lines. The boundary between conventional wafer fabrication and back-end processing is becoming less distinct where wafer-level packaging, hybrid bonding and chip-to-wafer integration are involved.
Major Market Drivers
AI and HBM Are Increasing Semiconductor Test Intensity
Artificial intelligence accelerators and high-bandwidth memory devices require substantially more complex electrical testing than conventional semiconductor products. More semiconductor dies are incorporated within individual packages, interconnect density is increasing and package failures become more expensive as several high-value devices are assembled together. This increases the importance of wafer sort, memory testing, system-level testing and final package qualification.
Teradyne’s Semiconductor Test business has experienced strong AI-related demand, particularly across compute and memory applications. HBM and advanced DRAM architectures require additional testing because memory stacks must meet demanding bandwidth, reliability and thermal requirements before integration into high-value accelerator packages.
Advantest is similarly benefiting from higher-performance semiconductor architectures. Expansion in AI and high-performance computing is increasing the technical complexity of test programs and the number of test operations required throughout semiconductor manufacturing.
Test demand is therefore growing faster than semiconductor unit volumes alone would indicate. Higher device values, tighter performance tolerances and more complex package architectures increase the amount of testing equipment required per unit of semiconductor output, supporting sustained investment through the forecast period.
Advanced Packaging Is Moving Into High-Volume Manufacturing
Chiplets, 2.5D integration, HBM stacking and heterogeneous semiconductor packages increasingly require bonding processes that are more precise than conventional die attach. Thermo-compression bonding is already being deployed for high-performance logic and memory packages, while hybrid bonding is progressing toward wider production adoption as interconnect dimensions continue to shrink.
ASMPT’s advanced packaging portfolio spans thermo-compression bonding, hybrid bonding, high-precision flip-chip assembly and photonics applications. Besi has also experienced strong demand for hybrid bonding, datacenter and advanced packaging applications as semiconductor manufacturers expand AI-related capacity.
Advanced packaging changes equipment requirements because manufacturers need tighter die-placement accuracy, precise temperature and force management, improved process control and higher throughput without sacrificing yield. These requirements support above-market growth for advanced bonding, inspection and metrology systems through 2031.
Major Market Restraints
Semiconductor Capital Spending Remains Cyclical and Customer-Concentrated
Back-end equipment demand can change rapidly when semiconductor manufacturers adjust capacity plans. Equipment suppliers typically serve a relatively small number of large IDMs, foundries, memory manufacturers and OSAT companies, making quarterly equipment demand sensitive to individual customer investment cycles.
The current AI investment cycle is supporting strong advanced packaging and test spending, but automotive, industrial, consumer and mainstream computing markets can follow different demand patterns. Equipment utilization and investment can therefore diverge significantly across semiconductor applications.
Suppliers concentrated in mature packaging processes may experience weaker order conditions even while AI-related equipment categories expand. The market remains exposed to inventory corrections, utilization rates and changes in semiconductor capital-expenditure plans.
Qualification Requirements Slow Adoption of New Back-End Processes
Back-end equipment must satisfy demanding yield, repeatability, throughput and reliability requirements before entering high-volume semiconductor production. Small alignment, bonding or contamination errors can affect complete packages containing multiple high-value dies.
New technologies such as hybrid bonding, advanced optical inspection and new test architectures therefore undergo extended qualification programs before customers deploy them at scale. These programs can involve equipment suppliers, foundries, memory manufacturers, materials companies and OSAT providers.
Successful equipment suppliers must demonstrate production uptime, process repeatability, yield performance and integration with surrounding manufacturing systems in addition to basic technical capability. Qualification requirements consequently slow the replacement of established equipment platforms even when newer technologies offer significant performance advantages.
Semiconductor Back-End Equipment Market Trends
Thermo-Compression and Hybrid Bonding Are Reshaping Assembly
Conventional wire bonding remains important across analog, power, automotive and mature-node semiconductor applications. However, high-performance AI and HBM packages increasingly require chip-to-chip, chip-to-wafer and chip-to-substrate connections with substantially smaller interconnect pitches.
Thermo-compression bonding provides greater control over fine-pitch interconnects and is being deployed across advanced memory and logic packaging. Hybrid bonding reduces interconnect dimensions further by directly bonding metal and dielectric surfaces, supporting future three-dimensional semiconductor architectures.
The transition therefore expands rather than immediately replaces existing bonding equipment categories. Wire bonding retains substantial high-volume demand while advanced bonding captures a progressively larger share of capital spending.
Inspection Is Moving Toward Three-Dimensional Process Control
Advanced semiconductor packages contain structures that cannot be adequately characterized through conventional two-dimensional inspection. Package warpage, bump height, die placement, interconnect geometry and buried defects increasingly require three-dimensional metrology and higher-resolution inspection.
Onto Innovation qualified its Dragonfly G5 system for 2.5D AI packaging applications in April 2026. The platform combines advanced optics, illumination and analytical algorithms for package inspection.
Inspection and metrology are therefore shifting from primarily final quality-control functions toward continuous process-control steps integrated throughout the packaging workflow.
Co-Packaged Optics Is Creating New Assembly and Test Requirements
AI computing systems are placing greater pressure on electrical interconnects between processors, memory and networking components. Co-packaged optics and silicon photonics address part of this constraint by positioning optical components closer to compute devices.
These architectures create new equipment requirements because semiconductor dies, photonic devices and optical components must be assembled and tested at extremely high precision. Back-end equipment suppliers are consequently expanding photonics-related bonding, alignment and test capabilities.
Advantest and OpenLight announced collaboration in June 2026 on silicon photonics testing for high-volume manufacturing, reflecting the growing convergence between conventional semiconductor test and photonic-device qualification.
Foundries Are Expanding Their Role in Advanced Packaging
Foundries historically concentrated primarily on wafer fabrication while OSAT companies performed a large proportion of semiconductor packaging and final testing. This division is becoming less distinct as leading foundries expand 2.5D, 3D and wafer-level packaging capacity.
Foundry participation increases demand for advanced bonding, inspection, wafer-level packaging and process-control equipment adjacent to front-end manufacturing. Equipment companies therefore increasingly serve foundries alongside traditional OSAT and IDM customers.
This development is particularly important for AI accelerators, where advanced logic fabrication, HBM integration and complex packaging increasingly need to be planned as one manufacturing architecture.
Market Segmentation Analysis
By Equipment Type
Advanced Bonding Equipment
Advanced bonding equipment, including flip-chip, thermo-compression and hybrid bonding systems, is among the fastest-growing equipment categories through 2031. Demand is driven by HBM stacking, chiplet integration and increasingly dense logic-memory packages used for artificial intelligence and high-performance computing.
The segment remains smaller than semiconductor test equipment in absolute value but is projected to increase from approximately 7% of global back-end equipment value in 2026 to around 11% by 2031.
Placement accuracy, thermal control, bond-force management and throughput are becoming critical purchasing criteria. ASMPT and Besi maintain strong positions in this transition, while additional semiconductor-equipment companies are expanding capabilities for chip-to-wafer, wafer-to-wafer and die-to-die bonding.
By End User
Outsourced Semiconductor Assembly and Test Companies
OSAT companies account for approximately 45% of global back-end equipment demand in 2026, making them the largest end-user group. Major OSAT companies operate large-scale packaging and test facilities serving fabless semiconductor companies, IDMs and foundries.
Their equipment requirements range from conventional wire bonding, die attach and molding to high-density flip-chip, wafer-level packaging, HBM-related assembly and advanced electrical testing. Increasing package complexity requires many OSAT companies to invest across multiple equipment categories simultaneously.
Foundries are projected to record stronger equipment growth through 2031 as advanced packaging moves closer to wafer fabrication. However, OSAT companies retain the largest overall equipment demand because of their extensive manufacturing capacity and broad customer bases.
Semiconductor Back-End Equipment Market by Geography
Asia Pacific
Asia Pacific accounts for more than 80% of global semiconductor back-end equipment spending in 2026. The region combines leading-edge logic and packaging capacity in Taiwan, memory and HBM manufacturing in South Korea, large-scale semiconductor manufacturing in China and Japan, and substantial assembly and test ecosystems across Southeast Asia.
Malaysia is one of the world’s major semiconductor assembly and test locations, supported by extensive multinational manufacturing operations. Singapore combines wafer fabrication, advanced manufacturing, semiconductor equipment activity and regional supply-chain operations. Vietnam is emerging as an increasingly important semiconductor assembly, packaging and test location, while the Philippines and Thailand retain established back-end manufacturing bases.
India remains smaller in current equipment demand but is gaining relevance as new semiconductor assembly, test and packaging projects move toward production. Its inclusion separately within the 2026–2031 regional forecast reflects the expected expansion of domestic semiconductor manufacturing capacity.
Taiwan, China and South Korea remain the largest individual equipment markets, while Southeast Asia contributes an increasingly important diversification opportunity for global semiconductor companies.
Competitive Landscape
The semiconductor back-end equipment market includes semiconductor test specialists, assembly-equipment suppliers, singulation companies and process-control vendors.
Advantest and Teradyne hold strong positions in semiconductor automatic test equipment, particularly across advanced logic, memory and AI applications. ASMPT has a broad packaging portfolio spanning wire bonding, flip-chip, thermo-compression bonding and emerging hybrid-bonding applications.
Besi is strongly positioned in die attach, thermo-compression and hybrid bonding, while Kulicke & Soffa maintains an important position in conventional wire bonding and advanced packaging. DISCO is a major supplier of wafer dicing, grinding and singulation equipment, while TOWA participates in molding and packaging systems.
Tokyo Seimitsu provides semiconductor probing and production equipment. Onto Innovation and KLA supply inspection and metrology systems increasingly relevant to advanced packaging. HANMI Semiconductor has expanded its position in HBM-related thermo-compression bonding, while Applied Materials is increasing its involvement in advanced packaging and hybrid-bonding process technologies.
Competitive differentiation increasingly depends on exposure to AI-related packaging, HBM test, hybrid bonding, high-resolution inspection and photonics rather than equipment breadth alone.
Recent Developments
July 2026: ASMPT announced major chip-to-substrate thermo-compression bonding tool wins as AI-related advanced packaging investment accelerated.
July 2026: Besi reported strong demand from hybrid bonding, photonics and datacenter applications during the first half of 2026.
June 2026: Advantest and OpenLight announced collaboration on silicon photonics test solutions for high-volume manufacturing.
May 2026: ASMPT established an Advanced Packaging Technology Advisory Council covering HBM, heterogeneous integration, photonics and advanced packaging architectures.
April 2026: Onto Innovation announced qualification of its Dragonfly G5 system for 2.5D AI packaging applications.
February 2026: ASMPT secured an order for ultrafine-pitch chip-to-wafer thermo-compression bonding systems using its Active Oxide Removal technology.
Market Outlook
The semiconductor back-end equipment market is expected to grow supported by a structural increase in semiconductor packaging complexity.
Test remains the largest equipment category as AI accelerators, HBM and increasingly complex chiplet architectures require more extensive electrical qualification. Advanced bonding and inspection equipment grow substantially faster from smaller bases as package interconnects become denser and semiconductor integration moves vertically.
Conventional die attach, wire bonding, molding and related equipment retain significant demand across automotive, industrial, analog, power and consumer semiconductors. The market therefore develops through simultaneous investment in advanced AI-related packaging and a substantial mainstream semiconductor packaging base.
OSAT companies remain the largest end-user category, while foundries gain share as advanced packaging becomes increasingly integrated with leading-edge semiconductor manufacturing. Asia Pacific continues to dominate geographically, with Southeast Asian countries gaining importance alongside the established Northeast Asian semiconductor centres.
Semiconductor Back-end Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 22.0 billion |
| Total Market Size in 2031 | USD 36.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Equipment Type, End-User, Geography |
| Companies |
|
Market Segmentation
By Equipment Type
Wafer Probe and Sort Equipment
Dicing and Singulation Equipment
Die Attach and Conventional Die Bonding Equipment
Wire Bonding Equipment
Advanced Bonding Equipment
Flip-Chip Bonding
Thermo-Compression Bonding
Hybrid Bonding
Molding, Encapsulation and Packaging Equipment
Inspection and Metrology Equipment
Final Test and Handler Equipment
By End-User
Outsourced Semiconductor Assembly and Test Companies
Integrated Device Manufacturers
Foundries and Advanced Packaging Foundries
Research, Pilot Lines and Others
By Geography
Americas
United States
Others
Europe, Middle East and Africa
Germany
Netherlands
France
Others
Asia Pacific
China
Taiwan
South Korea
Japan
Malaysia
Singapore
Vietnam
Philippines
Thailand
India
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary Research Framework
2.4. Secondary Research Framework
2.5. Data Triangulation
2.6. Forecast Methodology
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Rising Test Intensity for AI Accelerators and HBM
4.1.2. High-Volume Adoption of 2.5D, 3D and Heterogeneous Packaging
4.1.3. Expansion of Advanced Packaging Capacity by Foundries and OSAT Companies
4.1.4. Increasing Process-Control Requirements at Smaller Interconnect Pitches
4.2. Market Restraints
4.2.1. Cyclical Semiconductor Capital Expenditure
4.2.2. Customer Concentration Across Large IDMs, Foundries and OSATs
4.2.3. Long Qualification Cycles for New Packaging Equipment
4.2.4. Yield and Process-Control Challenges in Advanced Packaging
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Semiconductor Equipment Trade and Export-Control Environment
4.7. Strategic Recommendations
5. TECHNOLOGICAL OUTLOOK
5.1. Thermo-Compression Bonding
5.2. Hybrid Bonding
5.3. Chip-to-Wafer and Wafer-to-Wafer Bonding
5.4. HBM Assembly and Test
5.5. Chiplet and Heterogeneous Integration
5.6. 2.5D and 3D Packaging
5.7. Fan-Out Packaging
5.8. Advanced Optical Inspection
5.9. 3D Metrology
5.10. Co-Packaged Optics and Silicon Photonics Test
5.11. AI-Enabled Process Control and Yield Management
6. SEMICONDUCTOR BACK-END EQUIPMENT MARKET BY EQUIPMENT TYPE
6.1. Introduction
6.2. Wafer Probe and Sort Equipment
6.3. Dicing and Singulation Equipment
6.4. Die Attach and Conventional Die Bonding Equipment
6.5. Wire Bonding Equipment
6.6. Advanced Bonding Equipment
6.6.1. Flip-Chip Bonding
6.6.2. Thermo-Compression Bonding
6.6.3. Hybrid Bonding
6.7. Molding, Encapsulation and Packaging Equipment
6.8. Inspection and Metrology Equipment
6.9. Final Test and Handler Equipment
7. SEMICONDUCTOR BACK-END EQUIPMENT MARKET BY END USER
7.1. Introduction
7.2. Outsourced Semiconductor Assembly and Test Companies
7.3. Integrated Device Manufacturers
7.4. Foundries and Advanced Packaging Foundries
7.5. Research, Pilot Lines and Others
8. SEMICONDUCTOR BACK-END EQUIPMENT MARKET BY GEOGRAPHY
8.1. Americas
8.1.1. United States
8.1.2. Others
8.2. Europe, Middle East and Africa
8.2.1. Germany
8.2.2. Netherlands
8.2.3. France
8.2.4. Others
8.3. Asia Pacific
8.3.1. China
8.3.2. Taiwan
8.3.3. South Korea
8.3.4. Japan
8.3.5. Malaysia
8.3.6. Singapore
8.3.7. Vietnam
8.3.8. Philippines
8.3.9. Thailand
8.3.10. India
8.3.11. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Advantest Corporation
10.2. Teradyne, Inc.
10.3. ASMPT Limited
10.4. BE Semiconductor Industries N.V.
10.5. Kulicke & Soffa Industries, Inc.
10.6. DISCO Corporation
10.7. TOWA Corporation
10.8. Tokyo Seimitsu Co., Ltd.
10.9. Onto Innovation Inc.
10.10. KLA Corporation
10.11. HANMI Semiconductor Co., Ltd.
10.12. Applied Materials, Inc.
11. APPENDIX
Navigate
Trusted by the world's leading organizations











