
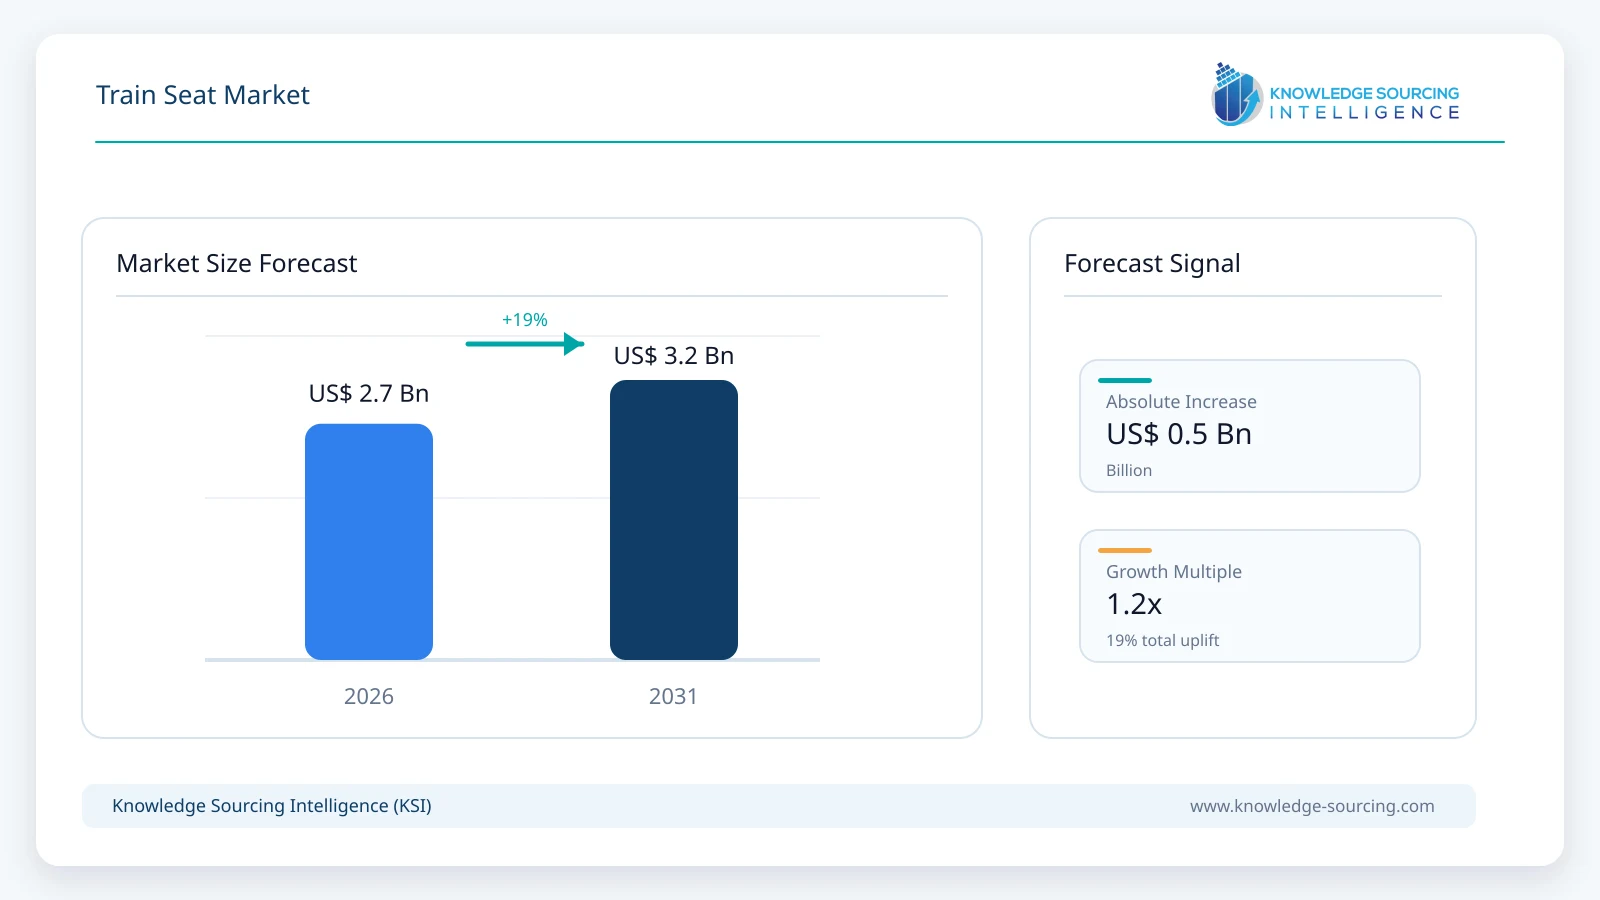
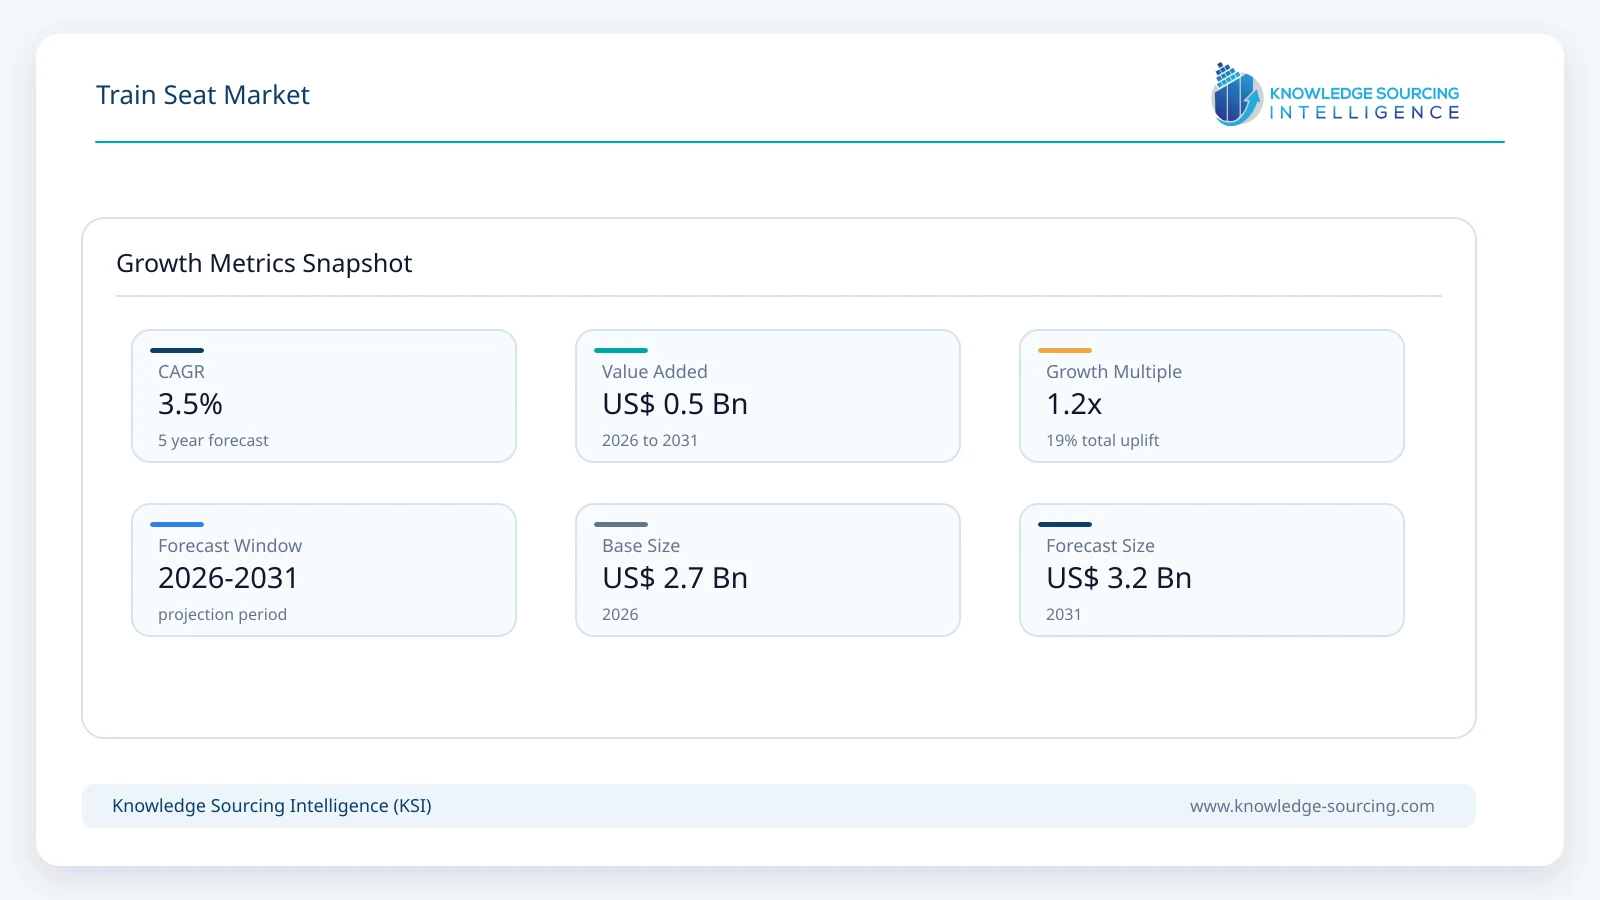
The Train Seat Market is forecast to grow at a CAGR of 3.5%, reaching USD 3.20 billion in 2031 from USD 2.70 billion in 2026.
Highlights:
- 1Regular and fixed seats account for approximately 56% of global train-seat revenue in 2026.
- 2Inter-city and high-speed seating is projected to grow at approximately 4.6% annually through 2031.
- 3Conventional passenger-train seating generates about USD 0.95 billion of global market value in 2026.
- 4Asia Pacific accounts for approximately 46% of global train-seat revenue in 2026.
- 5Lightweight, modular and recyclable seat architectures are becoming important procurement differentiators.
- 6Refurbishment programs create recurring demand beyond new rolling-stock production cycles.
Train seats combine structural frames, cushions, upholstery, armrests, tables, mounting systems and optional power or passenger-interface features. Requirements vary sharply by service type. Metro and commuter operators prioritize high passenger density, vandal resistance, low maintenance and short dwell-time circulation, while inter-city and high-speed operators place greater emphasis on ergonomics, recline, privacy, tray tables, power access and premium-class differentiation. GRAMMER, for example, offers separate city, regional, high-speed and very-high-speed seating architectures, illustrating how seat design is increasingly optimized by operating environment rather than standardized across a fleet.
Safety qualification is a major entry barrier. European rolling stock commonly requires compliance with EN 45545 fire-behavior requirements for materials and components, while North American transit projects reference NFPA 130 fire-life-safety requirements. Seat suppliers also need to meet project-specific crashworthiness, structural-load, accessibility and toxicity criteria. This means a product is rarely sold as a generic seat: the frame, cushion, upholstery, fixings and accessories are validated as part of a defined vehicle and interior configuration. Aftermarket demand therefore favors suppliers able to preserve interfaces with legacy mounting systems while modernizing comfort, materials or weight.
Market Trends
Lightweight and Recyclable Seat Architectures Are Moving From Concept to Fleet Trials
Weight reduction has become commercially relevant because each kilogram removed from a rail interior can reduce traction energy requirements over the life of a fleet and increase design flexibility elsewhere in the vehicle. Suppliers are also under pressure to reduce mixed-material assemblies that are difficult to recycle. GRAMMER positions its UBILITY ONE architecture around lightweight construction and more sustainable materials, while BORCAD is preparing its VERSIO regional and commuter seat with reduced plastic content. In the United Kingdom, Quantum Seating and Spinks advanced the EcoSeat concept into a Great Western Railway trial in 2026. The system replaces conventional polyurethane foam with a pocket-spring structure intended to improve recyclability while maintaining rail safety and comfort requirements.
Seat Platforms Are Becoming More Modular Across Vehicle Classes
Rail operators increasingly want interior systems that can be refreshed without redesigning the entire seat structure. Modular armrests, tables, headrests, interchangeable covers and standardized mounting interfaces allow operators to alter passenger density or service class during refurbishment. This is especially valuable for long-life rolling stock, which can remain in service for several decades and undergo multiple interior refresh cycles. Suppliers such as GRAMMER, COMPIN FAINSA and BORCAD maintain separate seat families that can be configured for regional, commuter and long-distance applications, while Alstom describes a build-to-print supplier model that emphasizes localization and project-specific interior integration.
Market Drivers
Rolling-Stock Expansion and Higher Rail Utilization Sustain New-Build Seat Demand
Rail investment remains the principal structural driver because every new passenger vehicle requires a full interior package. China expanded its high-speed network to roughly 50,400 km by the end of 2025 and carried 4.255 billion railway passengers during the year. The government has indicated a target of about 60,000 km of high-speed rail by 2030. Europe is also moving toward a larger high-speed network: the European Commission estimates that completing the trans-European high-speed rail network by 2040 will require about EUR 345 billion in infrastructure investment, alongside separate rolling-stock financing. Although infrastructure expenditure does not translate directly into seat revenue, fleet growth and additional service frequencies create the underlying vehicle demand from which seat orders arise.
Fleet Modernization and Refurbishment Create a Recurring Aftermarket
The replacement market is important because seat shells, cushions, upholstery, tables and fittings experience heavy daily use long before a rail vehicle reaches the end of its technical life. Operators therefore refurbish seats to improve comfort, accessibility, fire performance or cabin appearance while extending fleet service. Spain provides a recent example: COMPIN FAINSA Iberia was awarded a 2026 contract worth about EUR 2.84 million to supply seats for the regionalization of Renfe Series 447 trains. India also shows both new-build and replacement demand, with Oriental Rail Infrastructure receiving multiple Indian Railways seat orders during 2026. These programs reduce market dependence on the timing of entirely new train platforms.
Market Restraint
Long Qualification Cycles and Project-Specific Standards Limit Rapid Supplier Substitution
Train seats are safety-critical interior components whose commercial cycle can be much longer than the production cycle for ordinary furniture or automotive trim. Suppliers may need to meet fire, smoke, toxicity, crashworthiness, structural-load, accessibility and vehicle-interface requirements before a product is accepted. A seat qualified for one rolling-stock platform cannot automatically be transferred to another because mounting geometry, passenger clearances, materials, tables, armrests and accessories can change the tested configuration. This raises engineering costs, favors incumbents with proven references and can delay new entrants even when they offer a lower-cost design. It also makes procurement sensitive to project delays, rolling-stock certification schedules and operator budget cycles.
Segment Analysis
By Type - Regular and Fixed Seats
Regular and fixed seats remain the largest type, with the segment estimated at approximately USD 1.51 billion in 2026. Their scale comes from metros, commuter trains, regional services and standard-class conventional coaches where capacity, robustness and maintenance economics take priority over extensive recline mechanisms. Folding seats are used selectively around wheelchair spaces, vestibules and flexible passenger areas, while recliner and premium seat systems carry higher unit values in inter-city, high-speed and first-class cabins. Reclining seats are expected to outpace the overall market because new high-speed and premium-service projects place greater value on comfort, power access, privacy and adjustable ergonomics.
By Material - Foam and Polyurethane-Based Cushion Systems
Foam and polyurethane-based cushioning remains the dominant material system in conventional rail seating because it combines shape flexibility, comfort, durability and established fire-retardant formulations. The segment is projected to approach USD 1.5 billion in market value by 2031 when seat assemblies are classified by primary cushioning material. However, the material mix is beginning to change. Recyclability requirements are encouraging suppliers to reduce difficult-to-separate foam and plastic combinations, while projects such as Quantum Seating and Spinks' EcoSeat are testing spring-based alternatives. Leather and synthetic-leather surfaces remain concentrated in premium and easy-clean applications, while technical textiles continue to dominate high-utilization regional and urban fleets.
By Train Type - Conventional Passenger Trains
Conventional passenger trains account for the largest current revenue pool, generating approximately USD 0.95 billion in 2026. The segment includes long-distance and standard passenger coaches that are not separately classified as metro, commuter or dedicated inter-city/high-speed fleets. These vehicles often use a mix of fixed and reclining seats and create substantial refurbishment demand because operators extend fleet life through repeated interior upgrades. Inter-city and high-speed trains are projected to grow faster through 2031 as China continues network expansion, Europe advances high-speed investment plans and India expands premium chair-car and sleeper services. Metro and commuter systems remain a large-volume market but typically use simpler, lower-value seat architectures.
By Geography - Asia Pacific
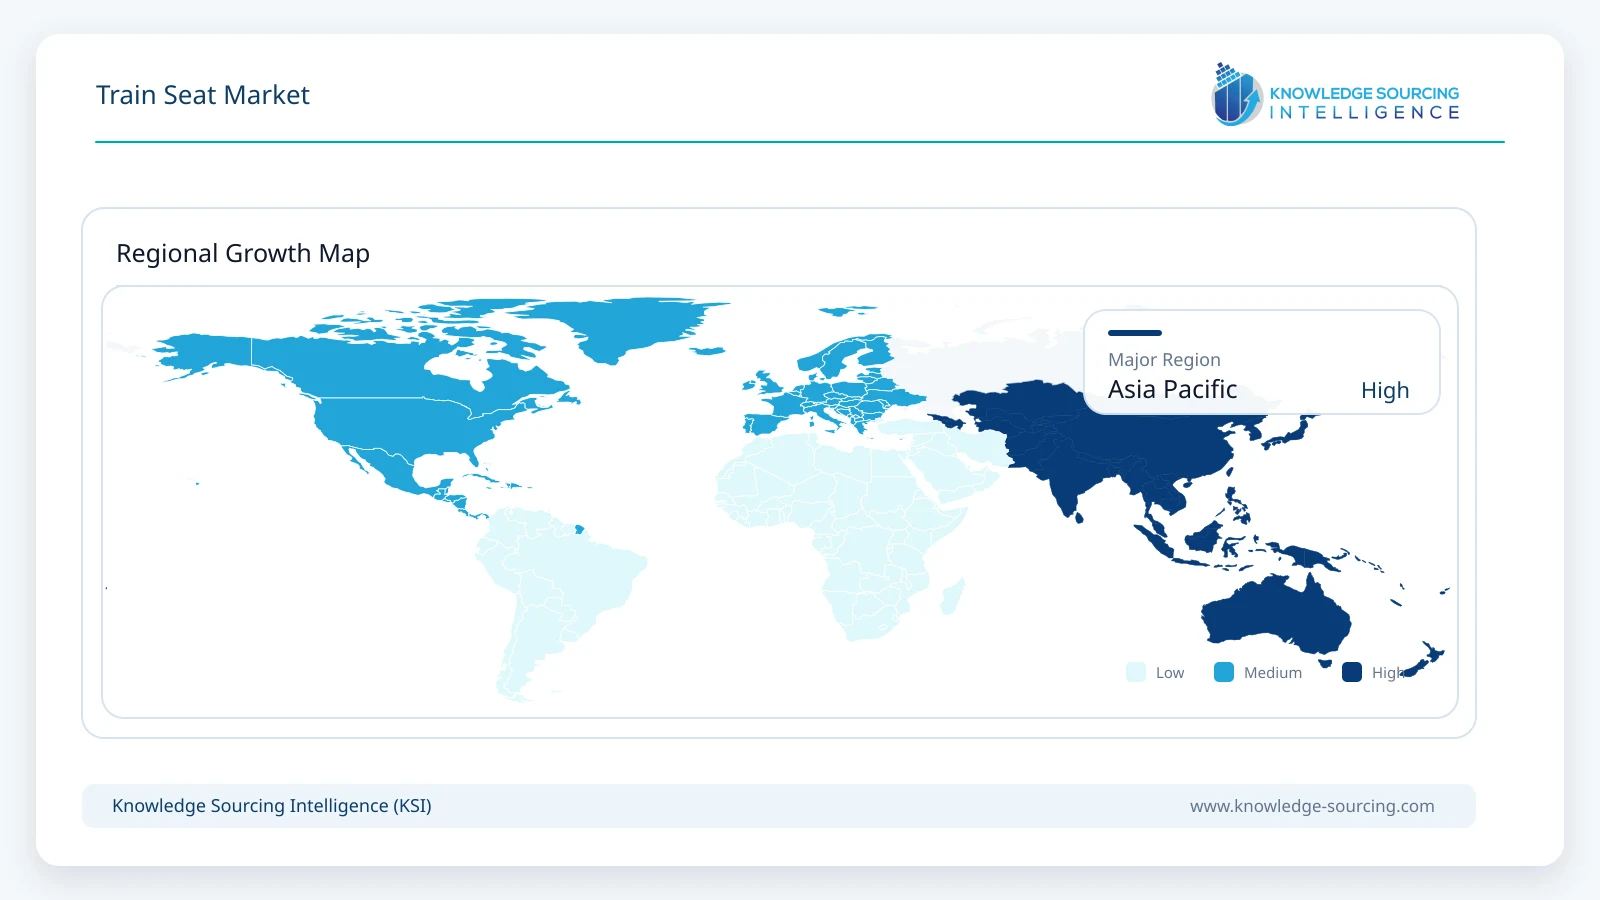
Asia Pacific is estimated to account for approximately 46% of global train-seat revenue in 2026 and is projected to reach about USD 1.50 billion by 2031. China is the largest underlying rail-volume driver, supported by the world's largest high-speed network and record passenger traffic. India is another important growth market: as of March 12, 2026, Indian Railways was operating 162 Vande Bharat chair-car services and had begun sleeper operations, while additional fleet introduction remains ongoing. Regional manufacturing is also deepening through companies such as TM FAINSA Railway in India, KTK Group and other Asian interior suppliers. Europe remains the main center for premium rail-seat engineering and refurbishment, while North America contributes through commuter, inter-city and transit fleet replacement programs.
Competitive Environment
The market combines established European rail-seat specialists, diversified transport-seating companies and regional manufacturers tied closely to domestic rolling-stock programs. GRAMMER has a broad portfolio spanning city, regional, high-speed and very-high-speed rail. Kiel, COMPIN FAINSA, BORCAD, FISA and Lazzerini are important European specialists, while KTK Group has expanded through rail-interior manufacturing and the acquisition of Saira operations. In India, TM FAINSA Railway and Oriental Rail Infrastructure participate directly in domestic seat and coach-interior supply. North American competition includes Freedman Seating and United Safety & Survivability, alongside specialist suppliers serving transit and passenger-rail programs.
Competition increasingly centers on program references, engineering support, local production and lifecycle cost rather than the seat shell alone. Rolling-stock OEMs may use build-to-print arrangements with qualified suppliers, making localization and manufacturing repeatability important. At the same time, operators increasingly evaluate weight, recyclability, ease of cover replacement, vandal resistance, passenger ergonomics and compatibility with power or information interfaces. Suppliers able to support both new-build and fleet-refurbishment programs are positioned to smooth revenue across rolling-stock cycles and maintain customer relationships over the multi-decade life of a train fleet.
Recent Developments
September 2026: Oriental Rail Infrastructure received a INR 58.5 million order from Modern Coach Factory, Raebareli, for 54 sets of seats for LHB non-AC chair-car coaches, with delivery scheduled by January 2027.
September 2026: BORCAD announced the VERSIO regional and commuter seat for its planned world premiere at InnoTrans 2026, emphasizing ergonomic flexibility and reduced use of plastic parts.
June 2026: COMPIN FAINSA Iberia was awarded a roughly EUR 2.84 million Renfe contract for seats used in the regionalization of Series 447 trains in Valladolid.
April 2026: Quantum Seating reported a Great Western Railway trial of its recyclable EcoSeat technology, developed with Spinks as an alternative to conventional polyurethane-foam seat construction.
April 2026: Indian Railways permanently expanded the Mumbai-Ahmedabad Vande Bharat service from 16 to 20 coaches, adding three AC Chair Car coaches and one Executive Class coach.
Train Seat Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.70 billion |
| Total Market Size in 2031 | USD 3.20 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Material, Train Type, Geography |
| Companies |
|
Market Segmentation
By Type
Regular / Fixed
Folding
Recliner
Others
By Material
Leather
Vinyl / Synthetic Leather
Foam and Polyurethane-Based Systems
Technical Textiles and Other Materials
By Train Type
Conventional Passenger Trains
Metro and Subway Trains
Regional and Commuter Trains
Inter-City and High-Speed Trains
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Rolling-Stock Expansion and Higher Rail Utilization Sustain New-Build Seat Demand
3.1.2. Fleet Modernization and Refurbishment Create a Recurring Aftermarket
3.2. Market Restraint
3.2.1. Long Qualification Cycles and Project-Specific Standards Limit Rapid Supplier Substitution
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Lightweight Seat Structures
4.2. Recyclable and Low-Foam Seat Architectures
4.3. Modular Seat Platforms and Quick-Change Components
4.4. Connected Passenger Features and Power Integration
5. TRAIN SEAT MARKET BY TYPE
5.1. Introduction
5.2. Regular / Fixed
5.3. Folding
5.4. Recliner
5.5. Others
6. TRAIN SEAT MARKET BY MATERIAL
6.1. Introduction
6.2. Leather
6.3. Vinyl / Synthetic Leather
6.4. Foam and Polyurethane-Based Systems
6.5. Technical Textiles and Other Materials
7. TRAIN SEAT MARKET BY TRAIN TYPE
7.1. Introduction
7.2. Conventional Passenger Trains
7.3. Metro and Subway Trains
7.4. Regional and Commuter Trains
7.5. Inter-City and High-Speed Trains
7.6. Others
8. TRAIN SEAT MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. GRAMMER AG
10.2. Franz Kiel GmbH
10.3. COMPIN FAINSA
10.4. BORCAD cz s.r.o.
10.5. FISA Fabbrica Italiana Sedili Autoferroviari S.r.l.
10.6. Freedman Seating Company
10.7. Quantum Seating Ltd.
10.8. Transcal Ltd.
10.9. McConnell Seats
10.10. Rescroft Ltd.
10.11. Lazzerini S.r.l.
10.12. KTK Group Co., Ltd.
10.13. United Safety & Survivability Corporation
10.14. Oriental Rail Infrastructure Limited
10.15. TM FAINSA Railway Pvt. Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











