
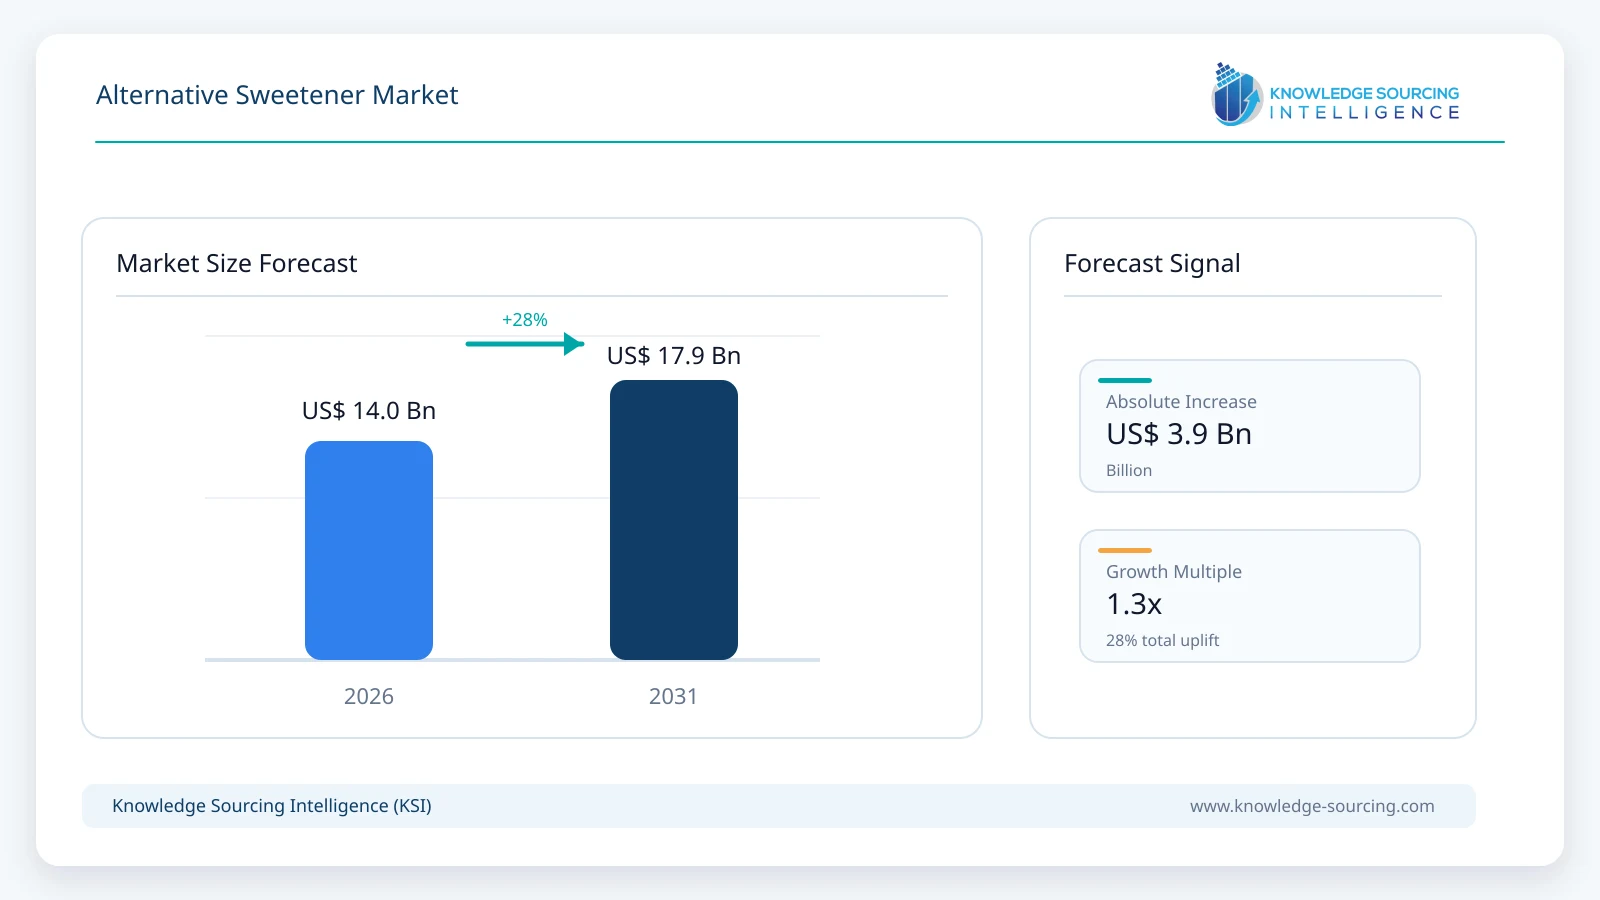
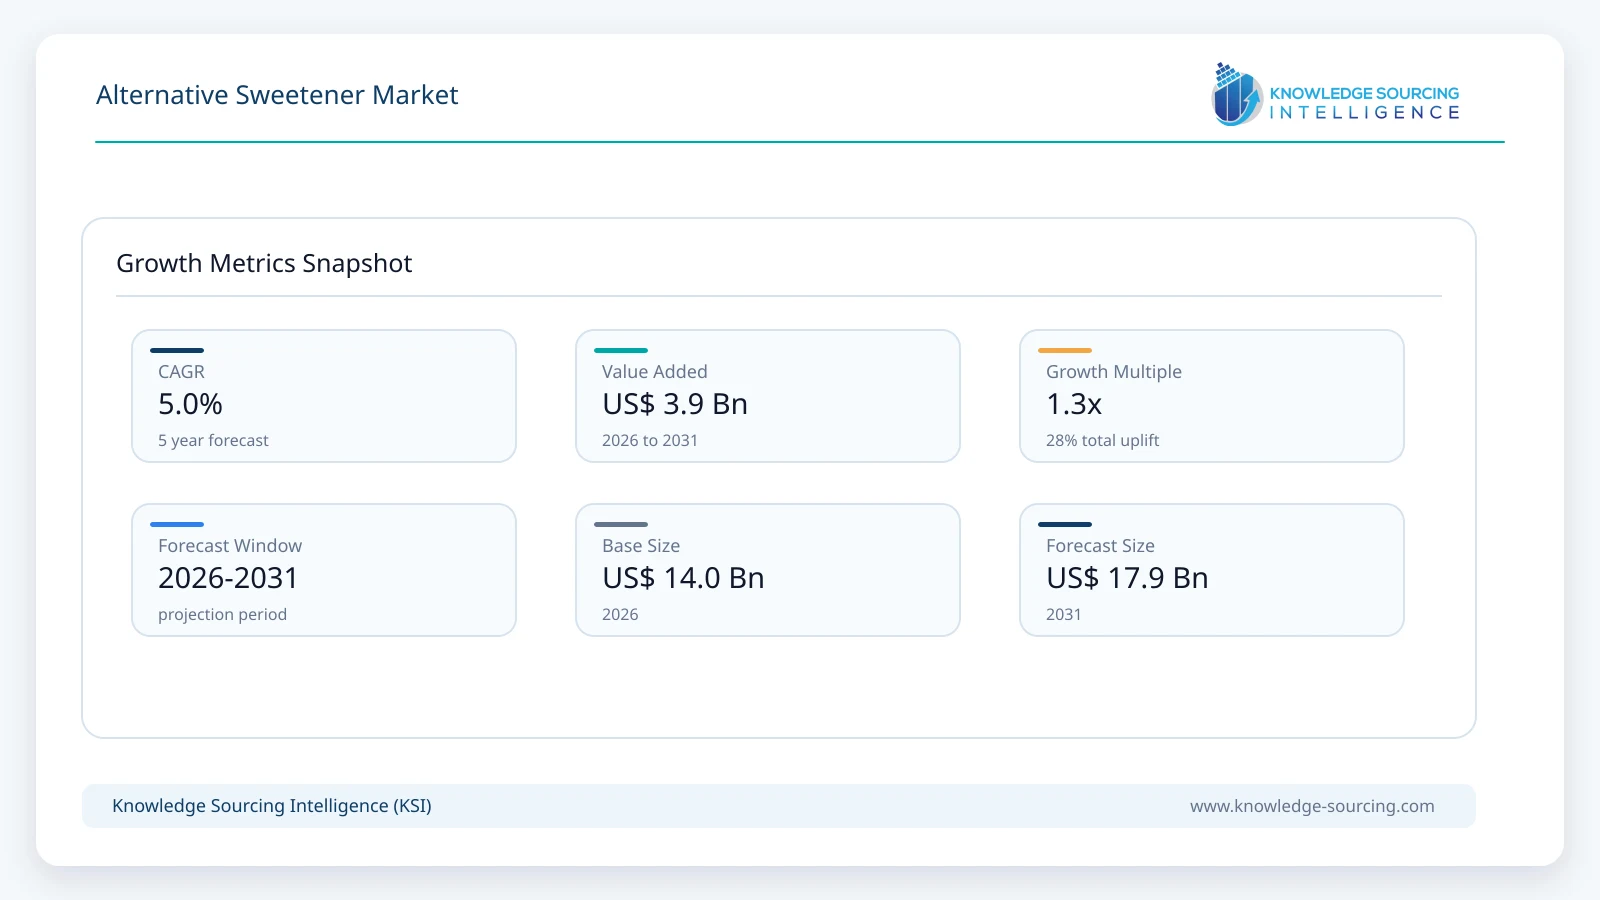
The Alternative Sweetener Market, at a 5.0% CAGR, is projected to increase from USD 14.0 billion in 2026 to USD 17.9 billion in 2031.
Highlights:
- 1Rising health consciousness drives strong consumer preference for low-calorie and sugar-free options to support weight management and reduce risks of lifestyle diseases.
- 2Shift toward natural and plant-based alternatives like stevia, monk fruit, and allulose gains momentum due to clean-label demands and perceptions of greater safety and sustainability.
- 3Food and beverage reformulation accelerates as manufacturers incorporate alternative sweeteners to create healthier products while preserving taste and functionality.
- 4Regulatory support and innovation encourage adoption through sugar-reduction policies and advancements in sweetener technologies for improved performance and appeal.
Alternative sweeteners are becoming increasingly significant as government entities and global public health officials have become increasingly concerned about the adverse impacts of high levels of sugar consumption. A clear correlation can be established linking excessive free sugars with the development of obesity, type 2 diabetes, cardiovascular diseases, and dental issues; consequently, governments are encouraging their populations to engage in lower sugar diets through regulatory frameworks.
In response to this issue, numerous food regulators have developed guidelines to regulate alternative sweetener use in consumer products. For example, in India, the Food Safety and Standards Authority of India (FSSAI) specifies a list of non-sugar sweeteners, including, but not limited to, steviol glycosides, sucralose, aspartame, acesulfame potassium, and saccharin, all of which have been assigned acceptable daily intake (ADI) limits, along with food labelling laws that require the use of these products.
The bar chart shows the projected rise in global obesity, increasing from 540 million in 2010 to 1,130 million by 2030. This dramatic increase emphasises the growing global health challenge posed by overweight and obesity. Rising obesity rates drive demand for low-calorie and sugar-reduced products, creating significant opportunities for the alternative sweetener market. Manufacturers are increasingly incorporating sweeteners like sucralose, stevia, and aspartame to meet health-conscious consumer needs and comply with sugar reduction policies. The trend highlights the crucial role of alternative sweeteners in promoting healthier diets and supporting public health initiatives worldwide.
Market Dynamics
Market Drivers
During the anticipation period, the rising health consciousness among consumers and the growing prevalence of diabetes and obesity will support the growth of the global alternative sweetener market.
Alternative sweeteners in food applications can be used in bulk as well as on an individual level in place of sucrose or fructose. Due to this, Alternative sweeteners are beneficial substitutes for sugar in a variety of commodities, such as chewing gum, sweets, ice cream, baked goods, and fruit spreads. They also work nicely in yoghurt, fillings and frostings, canned fruit, and beverages. Moreover, they are used in mouthwashes, toothpaste, and pharmaceuticals, including throat lozenges and cough syrups.
Sugar polyols have a positive impact on one’s health. In addition to their distinct functional qualities and clean, sweet flavour, polyols provide significant health advantages. They have fewer calories and do not raise blood sugar levels, which is a major benefit. Some sugar substitutes, such as xylitol and sorbitol, have anti-cavity properties and prevent tooth decay, which makes them perfect for products such as toothpaste, mints and chewing gums. The prevalence of obesity, diabetes, and metabolic syndrome has increased, and this, combined with increased consumer knowledge, has resulted in the positive growth of Alternative sweeteners with lower calorific content. According to the International Diabetes Federation (IDF) 2025 Diabetes Atlas, an estimated 589 million adults aged 20–79 were living with diabetes worldwide in 2024, representing 11.1% of the global adult population. This figure is projected to increase to approximately 853 million by 2050. The IDF also estimates that diabetes caused 3.4 million deaths among adults aged 20–79 in 2024, while approximately 252 million adults with diabetes remained undiagnosed. These figures highlight the growing global burden of diabetes and the increasing need for effective prevention, diagnosis, and long-term disease management.
Demand for alternative sweeteners is being supported by product innovation focused on sugar reduction, low-calorie formulations, and maintaining the taste and functionality of conventional sugar. Companies are introducing sweetener blends and reformulating food and beverage products to meet these requirements. For instance, in June 2026, Truvia announced the launch of Truvia Allulose Plus Stevia Sweetener & Monk Fruit Sweetener, a zero-calorie-per-serving blend combining allulose, stevia, and monk fruit. According to the company, the product measures one-to-one like sugar and is designed for use in beverages, baking, and everyday recipes. In July 2026, Daesang Corporation showcased its alternative sweetener portfolio at IFT FIRST 2026, highlighting its Sweevero brand and allulose ingredient solutions for low-sugar and low-calorie food applications. These company announcements demonstrate continued innovation in alternative sweeteners, particularly through blended formulations designed to improve sweetness, taste, and product versatility.
Expansion of the Processed and Packaged Food Industry
Food processing is being marketed by government agencies as part of their economic and industrial policies to reduce food waste and to improve both shelf life and food chain resiliency. As pre-packaged foods continue to grow in availability across urban and semi-urban geographic areas, food manufacturers have focused on developing standards, controlling costs, and developing long-lasting products. In doing so, manufacturers are increasingly turning to artificial sweeteners, which are chemically stable, can provide sweetness in very small quantities, and do not readily ferment/degrade over time.
Artificial sweeteners also simplify large-scale production from a manufacturing standpoint, as they provide consistent sweetness across large batches, reduce dependence on raw ingredients, and continue to offer desirable flavours in low-calorie/diet item categories. Therefore, artificial sweeteners are becoming more common in mass-produced segments of the food industry (i.e., soft drinks/dairy alternatives/baked goods,/readymade snacks/pharmaceutical syrups).
With the continued pressure from the government to implement formal food supply chains and packaged nutrition programs, the volume of industrial food production will increase. This increase directly affects the demand for inexpensive, stable, and easy-to-monitor ingredients for compliance, which continues to keep artificial sweeteners a central component of the processed food industry’s processing strategies.
This chart highlights the scale of metabolic health challenges in the United States, with 38 million people living with diabetes and 98 million adults having prediabetes in 2025. Such high prevalence creates sustained demand for low-sugar and sugar-free food options, directly supporting the expansion of the processed and packaged food industry. Food manufacturers reformulate products to meet dietary needs while maintaining taste and shelf life. This trend drives the growth of the artificial sweetener market, as these ingredients provide sweetness without added calories, enabling mass production of healthier snacks, beverages, and ready-to-eat foods for a health-conscious population.
Market Segmentation
By Source: Natural
Based on the source, the alternative sweetener market is divided into natural and synthetic. The improvement in living standards driven by improved disposable income and transition towards a healthier lifestyle has impacted consumer choice of food ingredients, with preference for products offering low-calorie and similar nutrition gaining traction. Hence, naturally derived sweetener prevents high blood sugar, insulin resistance, and obesity, which are among the common health issues globally. With efforts to reduce such overall metabolic risk, the demand for natural sweeteners is set to pick up pace.
Additionally, the growing outdoor exercise and physical health culture is booming in major regional markets. For instance, according to the “STADA Health Report 2025,” which interviewed nearly 2,000 consumers covering 22 European countries, 56% of respondents lead a healthy life while 57% follows a healthy diet. Such ongoing health consciousness has also accelerated the demand for plant-based ingredients in functional food and drink products that meet the current lifestyle shift.
Moreover, major market players are investing to expand their portfolio to meet evolving taste preferences. For instance, Cargill Inc.’s naturally-derived low/No calorie sweetener are non-cariogenic and ideal for adding taste to sugar-free products. , the company’s high-intensity sweeteners, namely “EverSweet”, “Truvia”, and “ViaTech” sweetener, are derived from the stevia plant and are zero-calorie ingredients for confectionery and beverages.
Furthermore, companies are engaging in innovations that have provided new growth prospects for naturally-derived sweeteners. Case in point, in July 2025, Layn Natural Ingredients launched its plant-based sweetener “SteviUP M2” that offers a sugar-like taste with low lingering sweetness. Reviewed by the Food and Drug Administration as GRAS (Generally Recognized as Safe), the product can be used as a general-purpose sweetener for food and beverage applications. Additional factors, such as regulatory polices to bolster clean-label manufacturing, followed by innovation to explore usage in other fields such as pharmaceuticals, have further paved the way for future market expansion.
Regional Analysis:
Asia Pacific Market Analysis
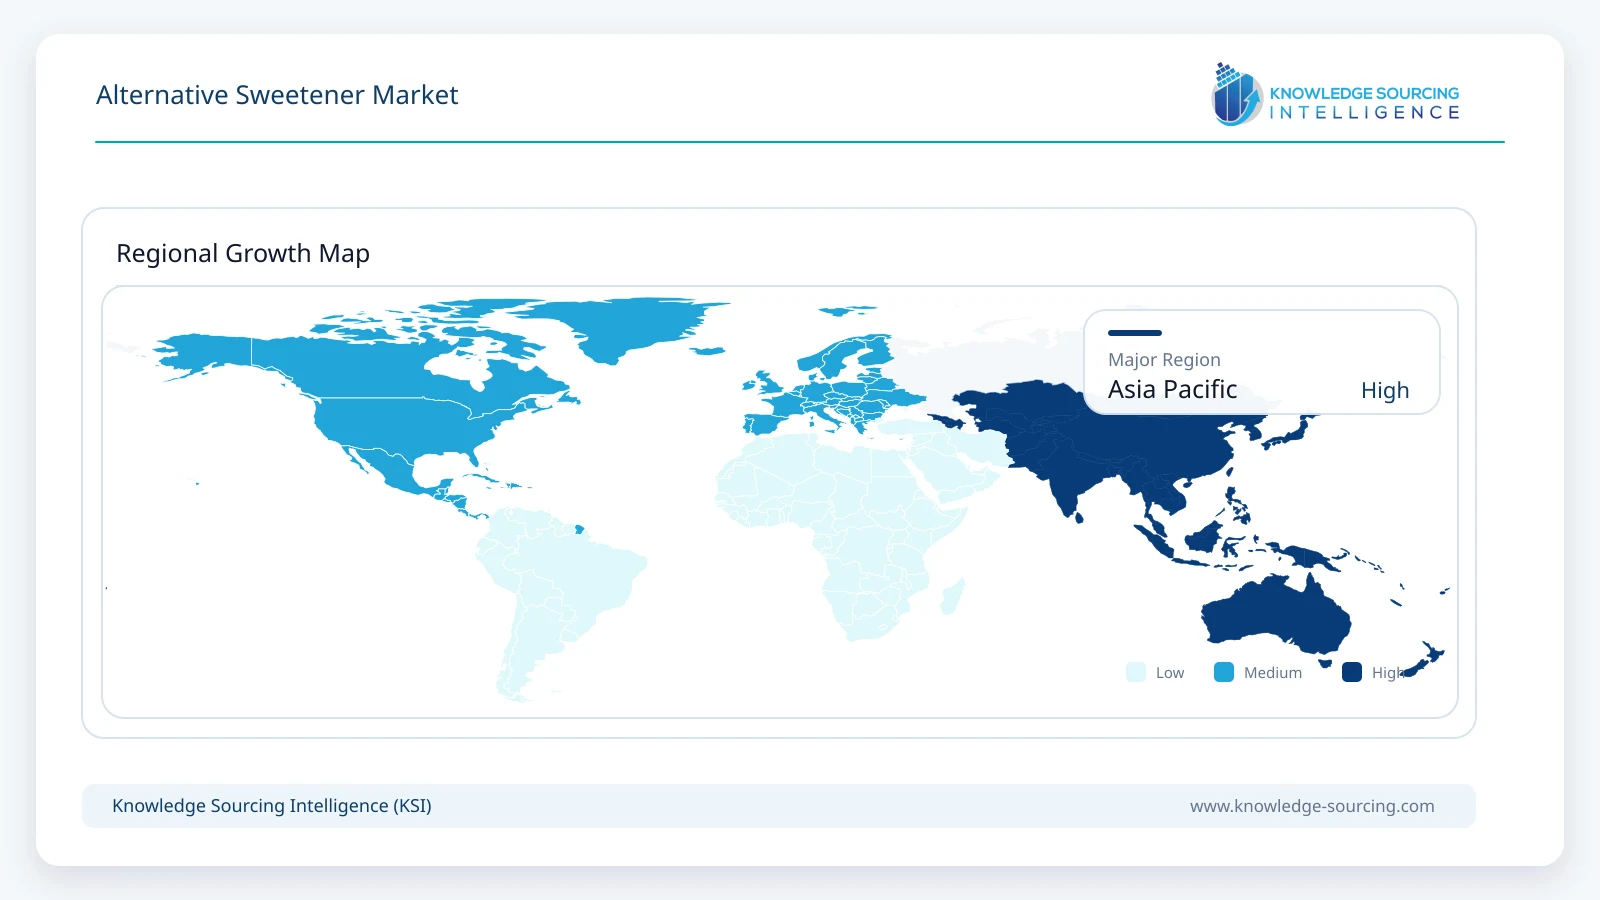
The Asia Pacific region is anticipated to hold a significant market share in Alternative sweeteners. This region will witness high growth during the forecast period owing to the growing health consciousness, increased urbanisation, and rising disposable income. Alternative sweeteners are in increasing demand in emerging economies like China and India. The market is expanding in this region due to factors such as changing eating patterns and growing demand for low-calorie food and beverages. Alternative sweeteners do not affect the blood sugar level, making them a great fit for diabetic patients. Therefore, the rising prevalence of diabetes in countries such as India and China is propelling demand in this region.
According to the statistics presented by the International Diabetes Federation, 8.3 per cent of Indian adults, or more than 74 million people, had diabetes in 2021. This number is expected to reach 124.8 million by 2045. 13 per cent of Chinese adults, or more than 140 million people, had diabetes in 2021. This number is expected to reach 174.4 million by 2045. Also, the rise of new companies along with the existence of key market players in the Asia Pacific countries is fueling demand. Prime markets in the Asia Pacific region are India, China, Japan, South Korea, Thailand, Taiwan and Indonesia.
North America: the US Market Analysis
The dynamic consumer landscape in the United States is emphasizing clean-label options that reflect their sustainable lifestyle. With the growing prevalence of chronic diseases, such as diabetes and obesity, consumers are seeking to reduce their sugar intake for wellness and preventive nutrition. According to the “World Obesity Atlas 2025”, nearly 75% of U.S. adults had high body mass index (BMI), while 44% are living with obesity. Additionally, the same source also stated that the total strength of adults with high BMI is set to reach 212.13 million by 2030.
Similarly, according to the Centers for Disease Control and Prevention, nearly 40 million individuals in the United States are diagnosed with diabetes, with research studies indicating that the prevalence has witnessed a constant growth over the years. Such prevalence has further influenced consumers’ choices towards low-calorie food items, and with alternative sweeteners offering similar taste with reduced sugar content, such health benefits are driving their usage in food applications.
Moreover, as the food and beverage sector is innovating to meet varied consumer demand, these innovations are set to provide new growth prospects in the US market. Likewise, the growing consumption of confectionery has further driven market expansion, as alternative sweeteners are used in candies, gums, and chocolates to stabilize sweetness and texture. According to the National Confectioners Association, total confectionery sales stood at USD 54.2 billion, with projected sales expected to reach up to USD 70.4 billion by 2029.
The strong presence of leading market participants, including Cargill Inc., Archer Daniels Midland Company, and International Flavors & Fragrances (IFF), has supported market development through ongoing efforts to strengthen their competitive positions and expand their product offerings. Furthermore, the U.S. government’s Dietary Guidelines for Americans, 2025–2030, may support market growth by encouraging greater awareness of nutrient-rich food choices, potentially creating additional opportunities for naturally derived nutrients across food, dietary supplement, and health-related applications.
Key Developments:
June 2026: Manus unveiled its monk fruit sweetener produced through industrial biomanufacturing at commercial scale in the United States, establishing a domestic supply alternative to conventionally sourced monk fruit.
June 2026: Truvia launched Allulose Plus Stevia Sweetener & Monk Fruit Sweetener, combining three sweetening ingredients in a zero-calorie-per-serving blend designed for 1:1 sugar replacement.
February 2026: Saraya announced a redesigned package for Lakanto S, an erythritol-and-monk-fruit sweetener, with the updated product scheduled for phased release from March 4, 2026.
February 2026: Tate & Lyle and Manus launched Yume™, introducing Yume M Stevia Sweetener, a bioconverted Reb M ingredient produced at Manus’ Georgia facility for sugar reduction.
Alternative Sweetener Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 14.0 billion |
| Total Market Size in 2031 | USD 17.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Source, Form, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product Type
Sucralose
Aspartame
Saccharin
Acesulfame Potassium
Others
By Source
Natural
Synthetic
By Form
Powders/Granules
Liquid
Tablets
By Application
Food and Beverage
Bakery and Confectionery
Dairy Products
Others
Pharmaceuticals
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
Japan
China
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ALTERNATIVE SWEETENER MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Sucralose
5.3. Aspartame
5.4. Saccharin
5.5. Acesulfame Potassium
5.6. Others
6. ALTERNATIVE SWEETENER MARKET BY SOURCE
6.1. Introduction
6.2. Natural
6.3. Synthetic
7. ALTERNATIVE SWEETENER MARKET BY FORM
7.1. Introduction
7.2. Powders/Granules
7.3. Liquid
7.4. Tablets
8. ALTERNATIVE SWEETENER MARKET BY APPLICATION
8.1. Introduction
8.2. Food and Beverage
8.2.1. Bakery and Confectionery
8.2.2. Dairy Products
8.2.3. Others
8.3. Pharmaceuticals
8.4. Others
9. ALTERNATIVE SWEETENER MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Product Type
9.2.2. By Source
9.2.3. By Form
9.2.4. By Application
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Product Type
9.3.2. By Source
9.3.3. By Form
9.3.4. By Application
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Product Type
9.4.2. By Source
9.4.3. By Form
9.4.4. By Application
9.4.5. By Country
9.4.5.1. United Kingdom
9.4.5.2. Germany
9.4.5.3. France
9.4.5.4. Spain
9.4.5.5. Others
9.5. Middle East and Africa
9.5.1. By Product Type
9.5.2. By Source
9.5.3. By Form
9.5.4. By Application
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. UAE
9.5.5.3. Israel
9.5.5.4. Others
9.6. Asia Pacific
9.6.1. By Product Type
9.6.2. By Source
9.6.3. By Form
9.6.4. By Application
9.6.5. By Country
9.6.5.1. Japan
9.6.5.2. China
9.6.5.3. India
9.6.5.4. South Korea
9.6.5.5. Indoensia
9.6.5.6. Thailand
9.6.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Cargill, Incorporated
11.2. Archer Daniels Midland Company
11.3. Ingredion Incorporated
11.4. Tate and Lyle plc
11.5. Ajinomoto Co., Inc.
11.6. Roquette Frères
11.7. International Flavors and Fragrances Inc. (IFF)
11.8. GLG Life Tech Corporation
11.9. Heartland Food Products Group
11.10. Celanese Corporation
11.11. Morita Kagaku Kogyo Co., Ltd.
11.12. Kerry Group plc
11.13. Amai Proteins Ltd.
12. RESEARCH METHODOLOGY
List of Figures
List of Tables





Frequently asked questions
What is the projected market value of alternative sweeteners by 2031?
The Alternative Sweetener Market is projected to reach USD 17.9 billion by 2031.
What is the forecasted CAGR for the Alternative Sweetener Market (2026-2031)?
The Alternative Sweetener Market is projected to grow at a 5.0% CAGR from 2026 to 2031.
What are the primary drivers of Alternative Sweetener Market growth?
Rising health consciousness, obesity, diabetes, and regulatory support are key drivers.
What significant trend is observed in alternative sweetener adoption?
Shift towards natural, plant-based options like stevia, monk fruit, and allulose.
How do regulations influence the Alternative Sweetener Market?
Regulatory support and sugar-reduction policies encourage adoption and innovation.
Why are alternative sweeteners becoming increasingly significant globally?
They address adverse impacts of high sugar consumption and rising obesity rates.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Alternative Sweetener Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/alternative-sweetener-market