
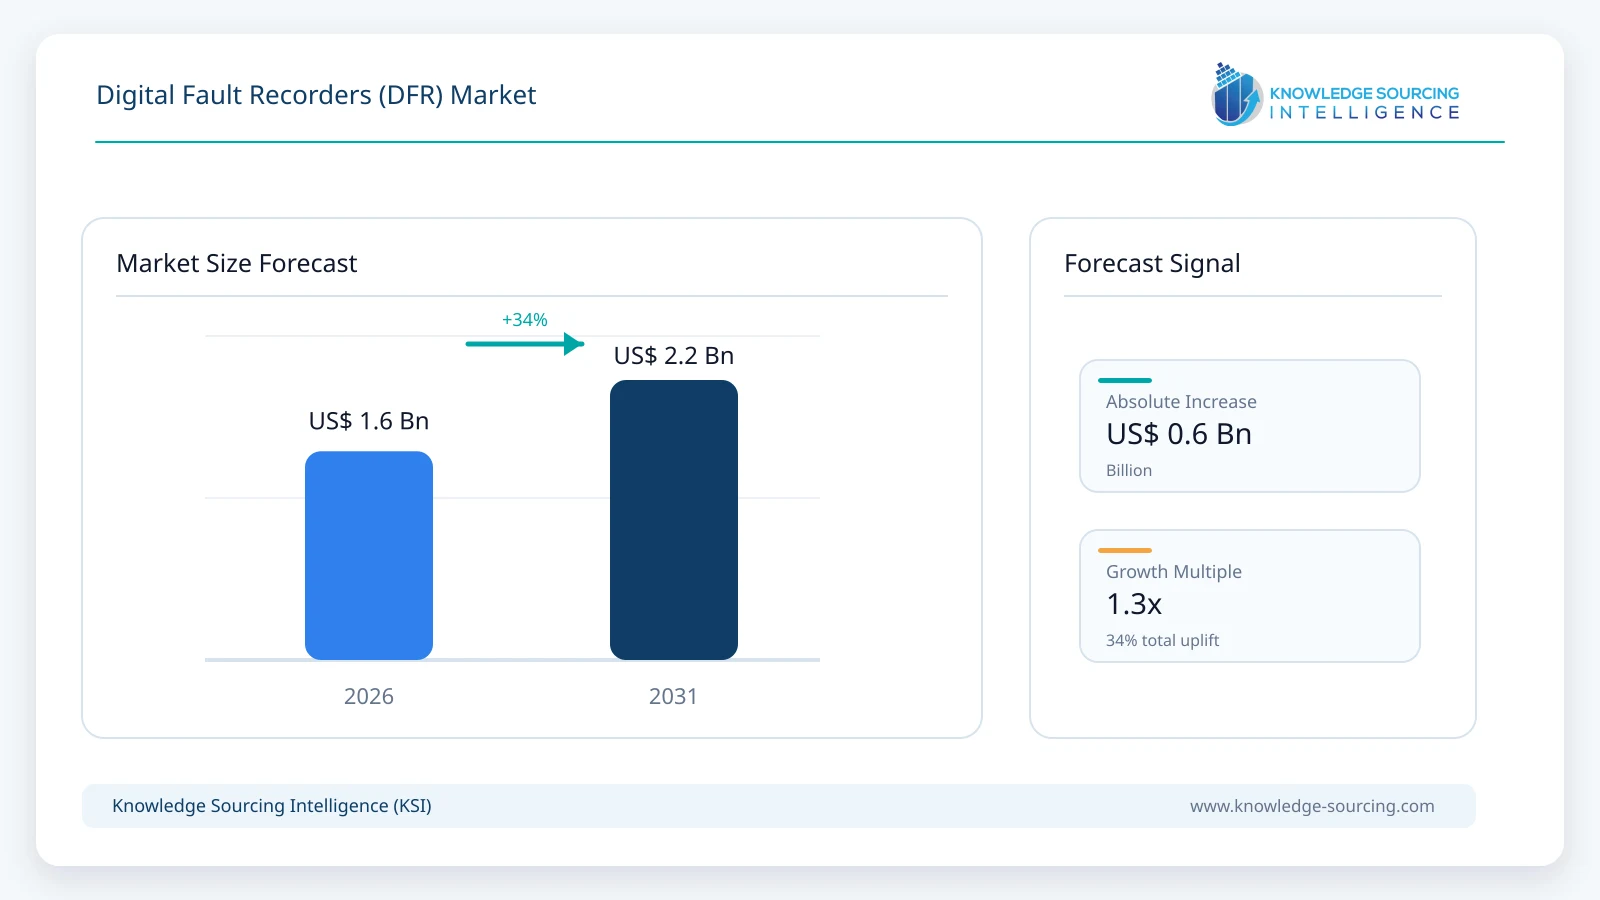
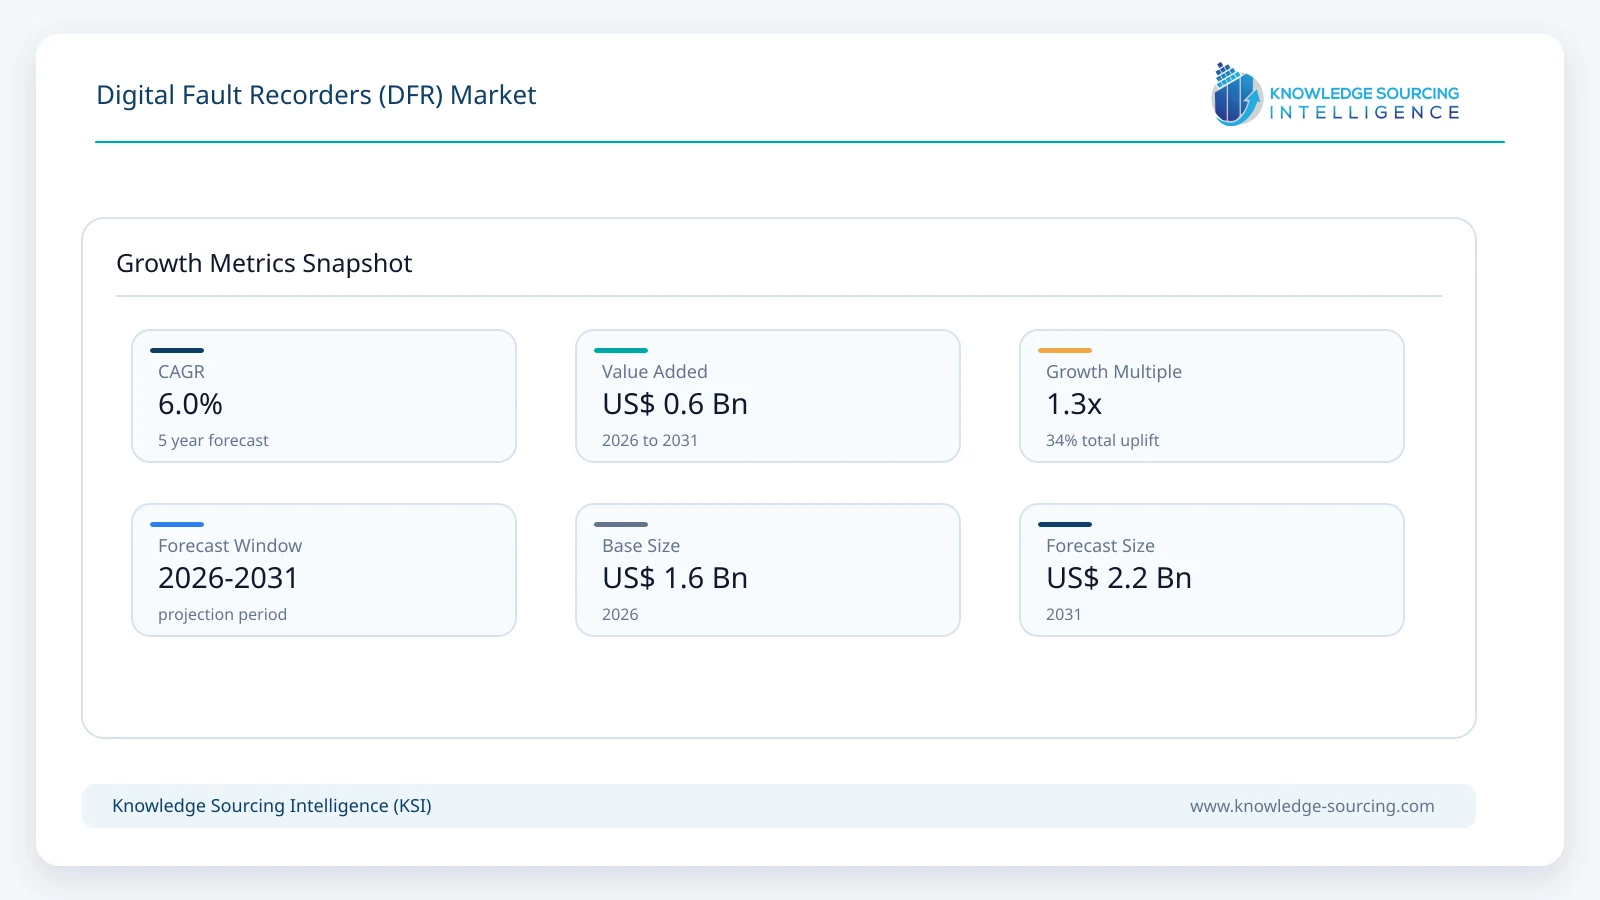
The Digital Fault Recorders Market is forecast to grow at a CAGR of 6.05%, increasing from USD 1.61 billion in 2026 to USD 2.16 billion by 2031.
Highlights:
- 1High-speed disturbance recording accounts for approximately 52% of global DFR market value in 2026, supported by its central role in detailed transient and protection-system fault analysis.
- 2Equipment deployed above 220 kV represents approximately 46% of market value in 2026 as high-voltage transmission networks require extensive disturbance-monitoring and system-event analysis.
- 3Transmission applications account for approximately 49% of market value in 2026, supported by grid expansion, renewable integration and reliability requirements across interconnected power systems.
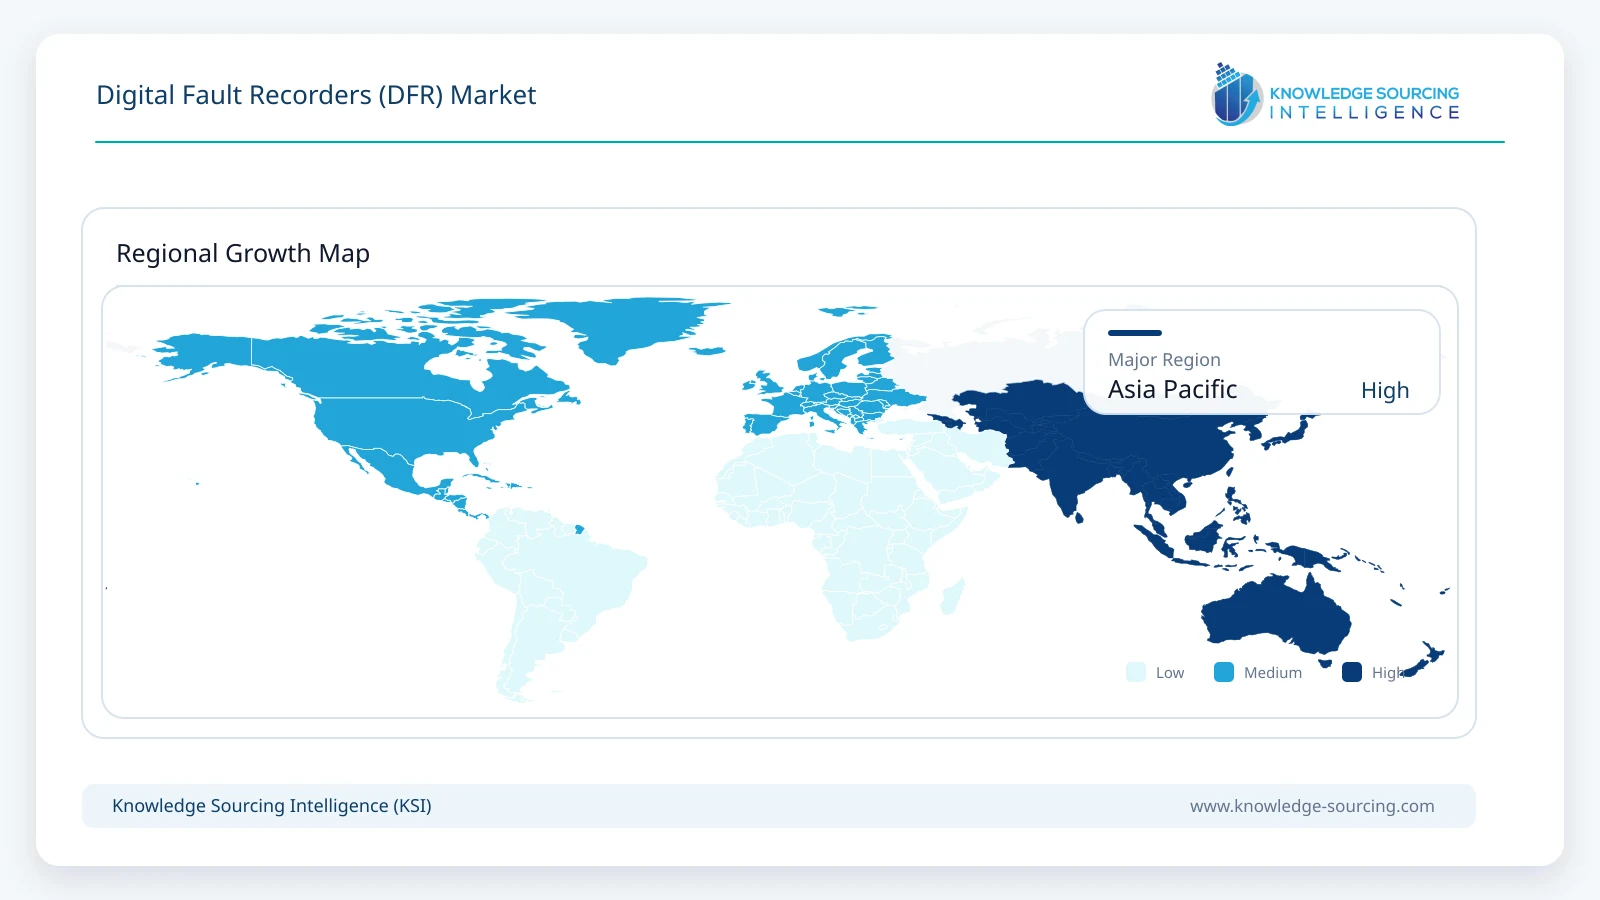
- 4Asia Pacific represents approximately 34% of global DFR market value in 2026 and is expected to strengthen its position as China, India and other regional markets expand transmission infrastructure.
- 5Multifunction DFR platforms increasingly combine transient fault recording with PMU, power-quality, sequence-of-events and continuous disturbance recording capabilities.
DFRs record voltage, current, frequency, binary status, and other power-system information during disturbances, providing engineers with the detailed evidence required to determine fault sequence, protection-system operation, and system behaviour. IEEE C37.2 formally recognizes digital fault recorders, dynamic disturbance recorders, disturbance-monitoring equipment, sequence-of-events recorders and phasor measurement units as distinct power-system functions, while modern commercial devices increasingly integrate several of these capabilities within one platform.
The underlying market environment is strengthening as grid investment accelerates globally. The IEA estimates that annual grid spending is approaching USD 550 billion in 2026, up nearly 20% year over year, while approximately USD 400 billion had been invested annually in recent years. Electricity 2026 estimates that investment must rise by around 50% by 2030 to meet growing electricity demand and relieve network congestion. More than 2,500 GW of renewable generation, storage and large-load projects are currently waiting in grid connection queues worldwide, increasing the need for transmission expansion, substation modernization and advanced monitoring equipment.
Market Trends
Multifunction Recorders Are Replacing Standalone Monitoring Devices
Digital fault recorders are increasingly being designed as multifunction power-system monitoring platforms rather than devices dedicated to a single transient-recording function. GE Vernova’s Reason RPV311 combines fault recording, disturbance recording, continuous waveform and RMS recording, sequence-of-events recording, power-quality monitoring, PMU functionality and travelling-wave fault location within one architecture. Siemens’ SIPROTEC 7KE85 similarly combines fast-scan and slow-scan fault recording with continuous recording, trend recording, power-quality measurement and PMU functionality.
The trend reduces the number of independent devices required in modern substations and allows utilities to correlate fault, waveform, event, and synchrophasor information within a common platform. AMETEK’s TR-3000 and DR-300 follow the same approach by integrating transient fault recording, dynamic disturbance recording, sequence-of-events, PMU and power-quality capabilities while supporting conventional hard-wired signals and IEC 61850 virtual inputs. This integration increases the value of software, storage, communications and analysis capability within each installation and supports gradual migration from dedicated DFR hardware toward broader disturbance-monitoring systems.
Continuous Waveform Recording Is Reducing Dependence on Trigger Settings
Traditional DFRs depend heavily on correctly configured triggers to capture disturbances. A fault that does not exceed a predetermined threshold can therefore occur without producing the desired record. Continuous waveform recording reduces this limitation by retaining high-resolution data regardless of whether a specific event condition is detected. Elspec’s G5DFR continuously records waveform signals at 1,024 samples per cycle, while AMETEK’s recorders combine event triggering with continuous transient oscillography to provide information from periods before and after disturbances.
The development is especially relevant to grids containing inverter-based resources, power electronics and rapidly changing loads because some disturbances may not resemble conventional short-circuit events. Continuous recording also supports post-event investigation when engineers do not know beforehand which signal will prove important. Greater storage capacity, data compression and automated retrieval are making this approach increasingly practical, shifting DFR systems from event-triggered forensic devices toward persistent grid-monitoring infrastructure.
IEC 61850 and Digital Substations Are Changing Recorder Architecture
Digital substations are reducing reliance on extensive hard-wired analogue and binary connections by transmitting sampled values and status information across standardized communications networks. Modern DFR suppliers are therefore integrating IEC 61850 Station Bus, GOOSE and Process Bus capabilities directly into recorders. GE Vernova’s RPV311 supports IEC 61850-8-1 and sampled-value connectivity, while AMETEK’s TR-3000 and DR-300 support both conventional inputs and IEC 61850 virtual signals within common recording functions.
This architecture can reduce copper cabling and allow one recorder to acquire data from a larger number of intelligent electronic devices. It also increases demand for precise time synchronization because digital records from several devices must be aligned before system events can be reconstructed accurately. Precision Time Protocol, GPS, IRIG-B and related synchronization technologies are consequently becoming core DFR capabilities. The transition supports higher-value multifunction systems but also increases the software, cybersecurity and communications expertise required for successful deployment.
Market Drivers
Global Grid Investment Is Increasing
Electricity-network expansion is the strongest structural driver for DFR demand because every new or upgraded transmission network creates additional requirements for disturbance monitoring, protection analysis and operational visibility. The IEA estimates that global grid investment is approaching USD 550 billion in 2026 and must continue increasing as electricity demand, renewable generation, battery storage and large data-center loads expand. More than 2,500 GW of generation, storage and large-load projects are already stalled in connection queues, while around 1.5 million kilometres of new transmission lines were built globally during the previous decade.
Transmission investment is particularly important because DFR deployments are more common and higher value at major substations and interconnected high-voltage networks where detailed disturbance information is essential following system events. The IEA estimates transmission investment reached approximately USD 140 billion in 2023 and will need to exceed USD 200 billion annually by the mid-2030s under existing policy settings. New substations, line upgrades and higher-voltage interconnections therefore create recurring opportunities for DFR hardware, communications, software and system integration.
Renewable and Inverter-Based Generation Is Increasing Disturbance-Monitoring Requirements
Power-system behaviour is becoming more complex as solar, wind, batteries and other inverter-based resources account for a larger proportion of electricity supply. The IEA expects wind and solar to increase from approximately 17% of global electricity generation currently to 27% by 2030, while utilities must simultaneously accommodate battery storage, electric vehicles and concentrated loads such as data centers.
Inverter-based resources can respond to disturbances differently from traditional synchronous generators, increasing the importance of high-resolution voltage, current, and frequency data when system events occur. NERC’s disturbance-monitoring framework in North America has been evolving specifically to address changes associated with inverter-based resources, with disturbance data remaining central to root-cause analysis and future reliability actions. AMETEK also identifies distributed and inverter-based resources as important applications for its disturbance recorders, reinforcing the role of DFR systems in monitoring increasingly power-electronics-dominated grids.
Reliability Standards Require High-Quality Disturbance Data
Disturbance-monitoring requirements provide a relatively durable demand base because major transmission-system operators must preserve sufficient data to investigate system events. NERC standards require disturbance-monitoring capabilities that address fault recording, dynamic disturbance recording and sequence-of-events information, including voltage, current, frequency and power measurements.
Commercial products increasingly advertise direct alignment with these requirements. AMETEK’s TR-3000 is designed to meet PRC-002 disturbance-monitoring requirements, while modern SEL DFR architectures provide high-speed fault records, continuous disturbance data and synchronized system-wide recording. Siemens’ 7KE85 extends the same concept across medium-, high- and extra-high-voltage networks. Regulatory requirements are particularly influential in transmission markets because utilities need dependable and retrievable records following major grid disturbances regardless of whether the equipment produces an immediate operating benefit during normal conditions.
Market Restraints
Protection Relays and Multifunction IEDs Can Absorb Fault-Recording Functions
One of the principal restraints is that digital fault recording increasingly exists as a function within protection relays, power-quality monitors and other intelligent electronic devices rather than requiring a dedicated recorder for every installation. ABB’s REX610 protection and control relay, for example, incorporates fault-recording capability capable of storing records for the latest 32 fault events. Siemens protection devices also include internal fault memories and event-recording capabilities that can be analysed using common software tools.
This integration reduces the addressable market for standalone DFRs at smaller substations and distribution installations where the number of channels and required recording duration are limited. Dedicated systems retain a stronger position at large transmission substations, generating stations and complex industrial networks because they can provide larger channel counts, synchronized multi-device recording, longer storage and independent monitoring. The market therefore grows more strongly in high-value applications than in basic distribution-level fault recording.
Grid Project Delays Can Postpone Recorder Procurement
DFR demand depends partly on the timing of transmission lines, substations and generation projects. Grid construction remains subject to lengthy permitting, transformer and cable shortages, utility financing constraints and multi-year project schedules. The IEA reports that cables can require two to three years to procure and large transformers as much as four years, with average lead times almost doubling since 2021.
Delays in major grid projects can shift DFR orders even when long-term investment plans remain intact because fault recorders are generally installed during the later stages of substation construction or refurbishment. Financially constrained utilities in developing economies may also prioritize transformers, switchgear and lines before investing in advanced monitoring functions. This creates uneven annual ordering patterns despite the underlying expansion of grid infrastructure.
Segment Analysis
By Recording Mode: High-Speed Disturbance Recording
High-speed disturbance recording represents approximately USD 839 million in 2026 and is projected to reach around USD 1.165 billion by 2031, representing a CAGR of approximately 6.8%. The category remains the largest recording mode because waveform-level voltage and current information is essential for investigating short circuits, relay operations, switching events and fast grid disturbances. Elspec identifies high-speed disturbance recording as one of the three principal DFR recording mechanisms, alongside low-speed disturbance and steady-state recording, while Kinkei’s AMX-2200 uses high-speed sampling of 3,840 Hz in 60 Hz systems and 3,200 Hz in 50 Hz systems.
Modern systems extend considerably beyond these sampling rates. KoCoS SHERLOG platforms provide sampling rates up to 200 kHz, while Siemens’ 7KE85 supports configurable high-speed recording alongside slower and continuous recorders. High-speed recording therefore continues to command the largest share even as continuous and low-speed monitoring functions become increasingly integrated into the same devices.
By Voltage: Greater than 220 kV
The greater-than-220 kV segment is estimated at approximately USD 742 million in 2026 and is projected to reach about USD 1.057 billion by 2031, representing growth of approximately 7.3% annually. The category benefits from expansion of high-voltage and extra-high-voltage transmission systems where disturbances can propagate across large interconnected areas and where post-event analysis carries greater reliability importance. The IEA identifies accelerating investment in high- and ultra-high-voltage transmission projects as countries expand long-distance power transfer and connect renewable generation.
Commercial equipment is designed specifically for this environment. Siemens positions the SIPROTEC 7KE85 for medium-, high- and extra-high-voltage substations and power plants, while GE Vernova’s RPV311 includes PMU, travelling-wave fault-location and process-bus capabilities aimed at wide-area and digital-substation applications. Lower-voltage systems remain a substantial installed market, but integrated protection relays and power-quality devices increasingly absorb basic recording functions at these levels.
By Installation: Transmission
Transmission represents approximately USD 791 million in 2026 and is projected to reach around USD 1.122 billion by 2031, producing a CAGR of approximately 7.2%. The segment accounts for the largest portion of DFR expenditure because high-voltage transmission substations require extensive synchronized disturbance monitoring and typically use higher channel counts and more sophisticated functionality than distribution installations. Transmission systems also face rapid structural change as renewable generation, battery storage and new industrial loads alter power flows and increase interconnection requirements.
Global transmission spending is already increasing, with the IEA reporting approximately USD 140 billion of investment in 2023 and substantial further expansion required through the next decade. DFR products from GE Vernova, Siemens, AMETEK, ERLPhase and KoCoS are explicitly designed for major transmission and substation applications, often combining fault recording with PMU, sequence-of-events and power-quality functions. Distribution installations continue to expand but rely more frequently on embedded fault-recording functions inside protection relays and compact monitoring equipment.
Regional Outlook
Asia Pacific
Asia Pacific accounts for an estimated USD 549 million of global DFR market value in 2026 and is projected to reach approximately USD 798 million by 2031, representing growth of about 7.8% annually. The region’s position is supported by extensive transmission investment in China, India and Southeast Asia and by the rapid expansion of renewable generation requiring additional grid interconnections. India alone has more than 120 GW of interregional transfer capacity and is continuing to expand both interstate and intrastate transmission systems under its Green Energy Corridor programmes as non-fossil generation capacity increases.
China remains one of the world’s largest grid investors, while Indonesia’s long-term system plan includes tens of thousands of kilometres of additional transmission and distribution infrastructure. Asia Pacific also hosts established recorder manufacturers including Kinkei System Corporation and a large installed base of substations requiring modernization. Continued digital-substation deployment, higher-voltage interconnections and grid expansion allow the region to increase its share of global DFR expenditure through 2031.
Competitive Environment and Analysis
The digital fault recorders market combines major power-grid technology companies with specialist monitoring and protection suppliers. Siemens offers the SIPROTEC 7KE85 as a dedicated multifunction fault recorder across medium-, high- and extra-high-voltage applications, while GE Vernova provides both dedicated DFR and multifunction DFR-plus-PMU platforms including Reason DR60 and RPV311. AMETEK Power Instruments competes through the TR-3000 and DR-300 recorder families, with particular emphasis on PRC-002 compliance and IEC 61850 connectivity. Elspec differentiates through continuous waveform recording and high-resolution data acquisition, while KoCoS combines digital fault recording with power-quality and grid-stability monitoring.
ERLPhase’s TESLA recorders combine multiple recording timeframes with sampled-value, PMU and continuous-data capabilities, while Kinkei integrates DFR, DDR, PMU and sequence-of-events functions in the AMT-7000. LogicLab offers dedicated DFR and DFR-plus-PMU configurations for medium- and high-voltage substations. Competition increasingly centers on multifunction integration, continuous recording, IEC 61850 compatibility, time synchronization, cybersecurity, automated data retrieval and software-based event analysis rather than recording hardware alone.
Recent Developments
August 2026: Elspec released G5DFR firmware version 1.2.5.14, adding updated PMU configuration frames, selectable int16 synchrophasor encoding and COMTRADE file generation triggered through GOOSE events.
July 2026: Elspec updated its G5 multifunction DFR platform around continuous waveform recording at 1,024 samples per cycle and centralized deep fault analysis.
April 2026: GE Vernova released RPV311 Configurator version 2.0.0.3 for its multifunction digital fault recorder and PMU platform.
February 2026: KoCoS published its current EPPE fault-recorder and power-quality platform specifications, with sampling rates up to 200 kHz and integrated transient and dynamic recording.
September 2025: AMETEK introduced new software and firmware for its TR-3000 and DR-300 digital fault recorders, adding Precision Time Protocol support and enhanced synchronized Ethernet communications.
2025: Qualitrol expanded promotion of its IDM+ multifunction disturbance recorder, which integrates six recording functions including fast and slow disturbance recording, PMU and travelling-wave fault location.
Market Outlook
The global digital fault recorders market growth remains closely linked to transmission and substation investment as utilities accommodate higher electricity demand, renewable generation, storage and increasingly complex power flows.
Transmission remains the leading installation category as utilities expand high-voltage networks and deploy more sophisticated disturbance-monitoring systems at strategically important substations. Asia Pacific strengthens its global position through transmission investment in China, India and other regional markets and reaches approximately USD 798 million by 2031.
The technology itself is also becoming broad, as dedicated fault recorders increasingly combine PMU, sequence-of-events, power-quality and continuous disturbance functions with IEC 61850 communications and precise network-based time synchronization. This integration limits the need for multiple standalone devices but raises the value and functionality of individual recorder installations. Through 2031, competitive advantage is expected to depend increasingly on software-based analysis, continuous waveform availability, interoperability with digital-substation architectures and the ability to manage large volumes of synchronized disturbance data.
Digital Fault Recorders Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.61 billion |
| Total Market Size in 2031 | USD 2.16 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 6.05% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Recording Mode, Voltage, Installation, Geography |
| Companies |
|
Market Segmentation
By Recording Mode
High-Speed Disturbance Recording
Low-Speed Disturbance Recording
Steady-State Recording
By Voltage
Up to 66 kV
66 to 220 kV
Greater than 220 kV
By Installation
Generation
Transmission
Distribution
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Digital Fault Recorders Market Size, 2026-2031
3.3. Recording Mode Outlook
3.4. Voltage Outlook
3.5. Installation Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Increasing Global Grid Investment
4.1.2. Expansion of Renewable and Inverter-Based Generation
4.1.3. Reliability Standards Requiring High-Quality Disturbance Data
4.2. Market Restraints
4.2.1. Integration of Recording Functions into Protection Relays and Multifunction IEDs
4.2.2. Grid Project Delays and Long Equipment Procurement Cycles
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Grid Reliability Standards and Regulatory Environment
5. TECHNOLOGICAL OUTLOOK
5.1. Continuous Waveform Recording
5.2. Multifunction DFR and PMU Integration
5.3. IEC 61850 Process Bus
5.4. Precision Time Protocol and Synchronized Recording
5.5. Automated Fault and Event Analysis
5.6. Travelling-Wave Fault Location
6. DIGITAL FAULT RECORDERS MARKET BY RECORDING MODE
6.1. High-Speed Disturbance Recording
6.2. Low-Speed Disturbance Recording
6.3. Steady-State Recording
7. DIGITAL FAULT RECORDERS MARKET BY VOLTAGE
7.1. Up to 66 kV
7.2. 66 to 220 kV
7.3. Greater than 220 kV
8. DIGITAL FAULT RECORDERS MARKET BY INSTALLATION
8.1. Generation
8.2. Transmission
8.3. Distribution
9. DIGITAL FAULT RECORDERS MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. United Kingdom
9.3.4. Spain
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Indonesia
9.5.6. Thailand
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. GE Vernova
11.2. Siemens AG
11.3. AMETEK Power Instruments
11.4. Elspec Ltd.
11.5. Schweitzer Engineering Laboratories, Inc.
11.6. ERLPhase Power Technologies Ltd.
11.7. Qualitrol Company LLC
11.8. KoCoS Messtechnik AG
11.9. Kinkei System Corporation
11.10. LogicLab s.r.l.
11.11. ABB Ltd.
11.12. Ducati Energia S.p.A.
11.13. E-Max Instruments
11.14. Prosoft-Systems Ltd.
11.15. Mehta Tech, Inc.
12. APPENDIX
Navigate
Trusted by the world's leading organizations











