
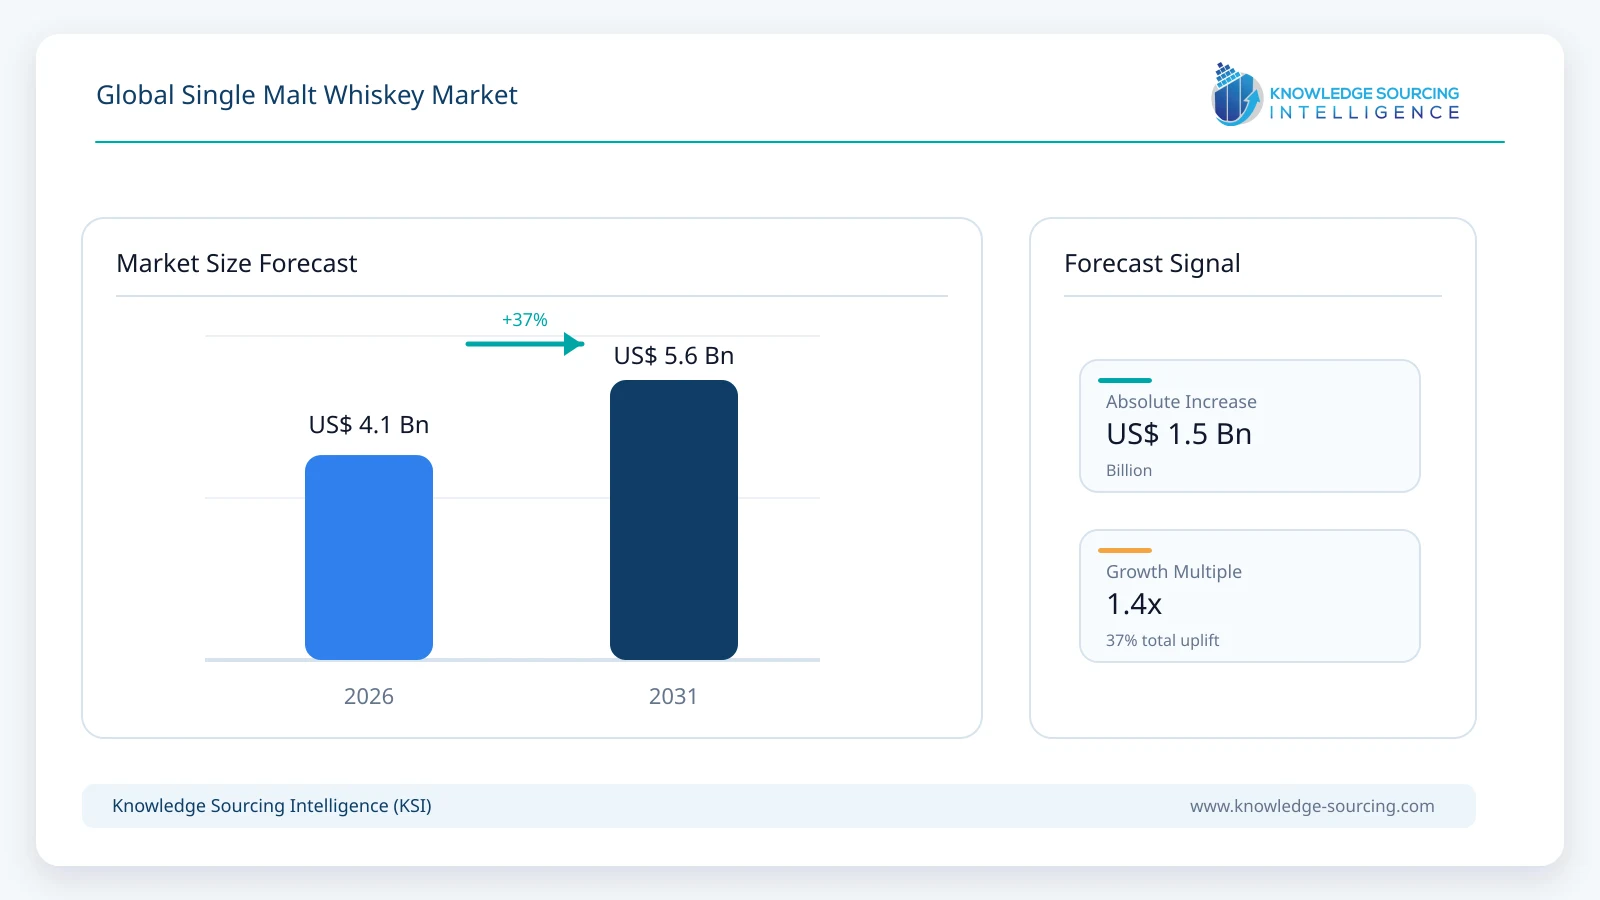
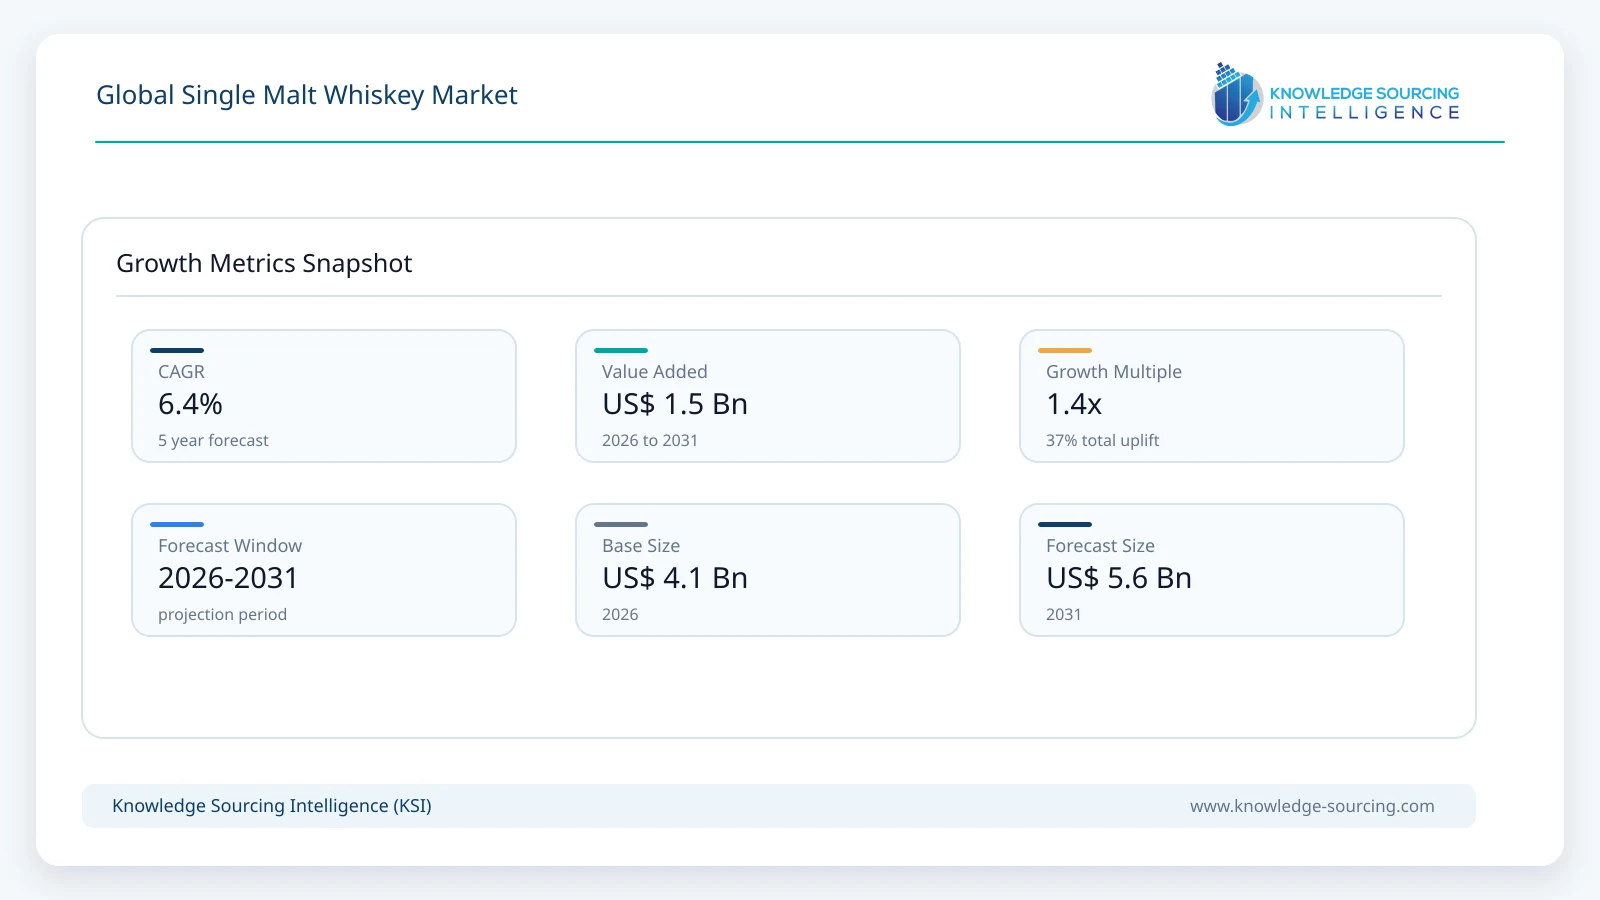
The global Single Malt Whiskey Market is forecast to expand at a CAGR of approximately 6.4%, reaching USD 5.63 billion in 2031 from USD 4.12 billion in 2026.
Highlights:
- 1Scotch single malt accounts for approximately 67% of global market value in 2026.
- 2Indian single malt is projected to grow at approximately 17% annually through 2031.
- 3American single malt gains momentum following formal regulatory recognition in the United States.
- 4Online sales are projected to grow above 15% annually from a relatively small base.
- 5Asia Pacific increases from approximately 29% of market value in 2026 to 35% by 2031.
- 6Travel retail gains importance for limited releases and high-value single malt expressions.
Single malt whiskey is produced at a single distillery using malted grain, with production requirements determined by the rules of the country or protected geographical category under which the product is sold. Scotch single malt remains the largest and most internationally established category, but Indian, Japanese, American and Irish single malts are increasingly expanding consumer choice and altering the competitive structure of the market.
The premium end of the whiskey industry experienced a more challenging trading environment during 2025. Scotch Whisky Association data shows that global Scotch whisky exports declined 1.8% in value during the year, while single malt Scotch exports declined 6% to approximately GBP 1.6 billion. The decline reflected weaker premium-spirit demand across several established markets, including China and France, together with tariff and macroeconomic pressures.
The medium-term outlook is nevertheless supported by substantial structural changes. India is emerging both as a major consumer market for imported Scotch and as an increasingly important producer of premium domestic single malt. Japan continues to occupy a strong prestige position, while the establishment of a formal American single malt whisky standard provides U.S. producers with a clearer category identity. Premium brands are also expanding through limited editions, distinctive cask finishes, luxury packaging and travel-retail exclusives rather than relying entirely on core age-statement products.
Major spirits groups are allocating greater strategic attention to luxury whisky. Diageo has consolidated brands priced above USD 100 under its Luxury Group, while Edrington continues concentrating its portfolio around ultra-premium spirits including The Macallan, Highland Park and The Glenrothes. Indian companies such as Radico Khaitan and Piccadily Agro are similarly using Rampur and Indri to move from traditional domestic spirits manufacturing into internationally positioned premium whisky.
Major Market Drivers
Expansion of Premium Single Malt Production Beyond Scotland
Scotland remains the industry’s principal origin, but single malt is increasingly becoming a global premium whiskey format rather than a category associated almost exclusively with Scotch. India, Japan, the United States and Ireland are developing distinctive production identities and building export-oriented portfolios.
India is particularly important. Radico Khaitan positions Rampur Indian Single Malt across a range extending from premium expressions to extremely limited luxury releases, while Piccadily Agro has expanded Indri through core, peated, limited-edition and travel-retail variants. Piccadily reported gross revenue of INR 1,143 crore in FY2025-26, increasing 28%, while its branded alcoholic-beverage business continued strong growth into FY2027.
The United States also gained a clearer commercial framework after the Alcohol and Tobacco Tax and Trade Bureau established American Single Malt Whisky as a formal standard of identity effective January 19, 2025. Qualifying products must be made from 100% malted barley, distilled entirely at one U.S. distillery and mashed, distilled and aged in the United States.
These developments broaden the market beyond traditional Scotch consumers. Indian and American producers can compete through climate, cask selection and local production character rather than attempting to replicate Scottish whisky directly, creating additional premium-price opportunities.
Trade Liberalization and Wider Access to Major Whisky Markets
Import duties materially influence international single malt pricing because the category frequently operates at premium and super-premium price points. Reductions in tariffs can therefore alter both retail affordability and the commercial viability of wider brand distribution.
The UK-India Comprehensive Economic and Trade Agreement entered into force on July 15, 2026. Under the agreement, India’s tariff on qualifying UK whisky falls from 150% to 75% initially and is scheduled to decline to 40% from year ten. India represents one of the largest long-term opportunities for Scotch because of its extensive whisky-consuming population and rapidly expanding premium-spirit segment.
Improved market access is particularly relevant to single malt because imported products have historically faced substantial price escalation in India. Lower duties can allow producers to broaden portfolios beyond the very highest-income consumers while maintaining premium positioning.
At the same time, international travel continues to support discovery and premium purchases. Distillers increasingly develop expressions specifically for airports and duty-free locations, using travel retail as a controlled environment for limited editions and premium brand presentation.
Major Market Restraints
Long Maturation Cycles Constrain Supply Flexibility
Single malt production requires manufacturers to commit working capital years before finished products generate revenue. Scotch whisky must be matured in oak casks in Scotland for at least three years, while many commercially important expressions are aged considerably longer. Producers therefore cannot respond rapidly to sudden increases in consumer demand.
Luxury releases create an even more significant inventory constraint. Casks aged for 15, 18, 25 years or longer were produced under demand conditions that may have been very different from those prevailing when the whisky is eventually bottled. Once mature inventory is depleted, it cannot be replenished quickly.
This favors established distillers with substantial inventories and diversified cask stocks. Diageo has more than 10 million Scotch whisky casks maturing in Scotland across its wider portfolio, while companies such as Edrington and William Grant & Sons maintain long-established maturation programs supporting their premium single malt brands.
Newer Indian and American distillers face a different challenge. Strong brand growth can outpace aged inventory, forcing producers to carefully balance export expansion, domestic availability and the introduction of older expressions.
Premium Consumer Demand Remains Sensitive to Economic and Trade Conditions
Single malt operates primarily within premium and luxury spirits, exposing the market to discretionary-spending cycles more than mass-market whisky categories. Consumers can postpone purchases, move toward lower-priced expressions or reduce consumption frequency when economic confidence weakens.
The 2025 decline in Scotch exports illustrates this sensitivity. Trade friction affected the United States, while premium demand softened across several international markets. American spirits faced similar pressure, with total U.S. spirits exports falling 3.8% in 2025 amid trade disputes and weaker shipments to several established markets.
Producers consequently need portfolios that span accessible premium products, core age statements and luxury limited editions rather than depending solely on ultra-premium demand. Geographic diversification is also becoming more important as demand conditions increasingly vary across China, the United States, India, Europe and other large spirits markets.
Single Malt Whiskey Market Trends
Indian Single Malt Is Becoming a Distinct International Category
Indian single malt is evolving from a domestic curiosity into a recognizable international premium-whisky segment. Higher maturation temperatures create different aging characteristics from Scotland, enabling Indian distillers to build products around local climate and production identity rather than imitating Scotch.
Indri, Rampur, Paul John and Amrut have established international distribution and expanded their premium portfolios. Radico Khaitan describes Rampur as a global luxury brand with products spanning multiple price tiers, while Piccadily has rapidly developed additional Indri expressions and international distribution.
The segment remains much smaller than Scotch but is projected to gain the largest share increase through 2031. Growth comes from a combination of domestic premiumization and exports to established whisky markets.
Cask Finishing Is Becoming a Major Source of Product Differentiation
Single malt producers are increasingly using secondary maturation and finishing to create distinct expressions without abandoning recognizable distillery character. Sherry, wine, port, rum and other cask types allow distillers to introduce additional flavor profiles and limited releases.
The Macallan’s product strategy remains closely tied to sherry-seasoned oak, while Glenfiddich introduced its XS collection using Oloroso, Moscatel and Pedro Ximénez finishes. Aberfeldy released a 15-year-old expression finished in Bolgheri red-wine casks during October 2025.
Indian producers are adopting similar experimentation. Indri Rudhira, introduced in March 2026, uses Pineau des Charentes cask maturation, illustrating how newer whisky regions are using unconventional finishing to establish distinct brand identities.
Travel Retail Is Becoming a Product-Development Channel
Airport duty-free has evolved beyond simply providing tax-advantaged access to standard whisky portfolios. Distillers increasingly use travel retail to introduce exclusive casks, city editions, larger formats and limited expressions that create scarcity and encourage collecting.
Piccadily launched Indri Ilika in June 2026 specifically for global travel retail, while earlier City Series products were developed around individual duty-free locations.
Travel retail is particularly suitable for single malt because purchasers are often internationally mobile consumers already familiar with premium spirits. Exclusive releases also reduce direct price comparison with domestic retail channels.
American Single Malt Is Developing a Formal Market Identity
The adoption of a federal definition gives American single malt a more consistent identity for retailers, consumers and international buyers. Previously, U.S. producers could make malt whisky but lacked a dedicated nationally defined category comparable to Scotch single malt.
The new standard requires production at one U.S. distillery and 100% malted barley while allowing broader oak-barrel practices than Scotch. This gives American producers room to develop regional maturation and cask styles while communicating a consistent category definition.
American single malt remains relatively small in global value but is projected to be one of the fastest-growing origin categories through 2031.
Single Malt Whiskey Market Segmentation Analysis
By Origin
Scotch Single Malt
Scotch accounts for approximately 67% of global single malt whiskey market value in 2026, making it by far the largest origin category. Its position is supported by internationally protected geographical status, extensive aged inventories, globally recognized distilleries and long-established distribution.
The competitive base is broad. Diageo operates Talisker, Lagavulin, The Singleton, Mortlach and other malt brands, while Pernod Ricard owns The Glenlivet and Aberlour. William Grant & Sons operates Glenfiddich and The Balvenie, Edrington owns The Macallan, Highland Park and The Glenrothes, and Suntory Global Spirits owns Bowmore, Laphroaig, Auchentoshan and Glen Garioch.
Scotch remains the largest category through 2031 but its share is projected to moderate toward approximately 61% as Indian, American and Japanese single malt grow faster. This reflects diversification of the market rather than declining relevance of Scotch, which continues to dominate international premium single malt distribution.
By Distribution Channel
Specialist Retailers
Specialist alcohol and whisky retailers account for approximately 29% of market value in 2026, making them the largest individual distribution channel. Single malt purchasing often involves considerably more product comparison than mass-market spirits because consumers evaluate distillery, origin, age statement, cask type, alcohol strength and limited-edition status.
Specialist stores therefore provide a level of assortment and product knowledge that general grocery retail frequently cannot match. They are also important for independent bottlings, rare releases and premium expressions that sell in lower volumes.
Their market share gradually moderates as online and travel-retail channels expand, but specialist retailers remain central to enthusiast and collector purchasing through 2031. The physical retail environment also supports tastings, recommendations and relationship-based selling, which remain important in a category where consumers frequently experiment with unfamiliar distilleries.
Single Malt Whiskey Market by Geography
Asia Pacific
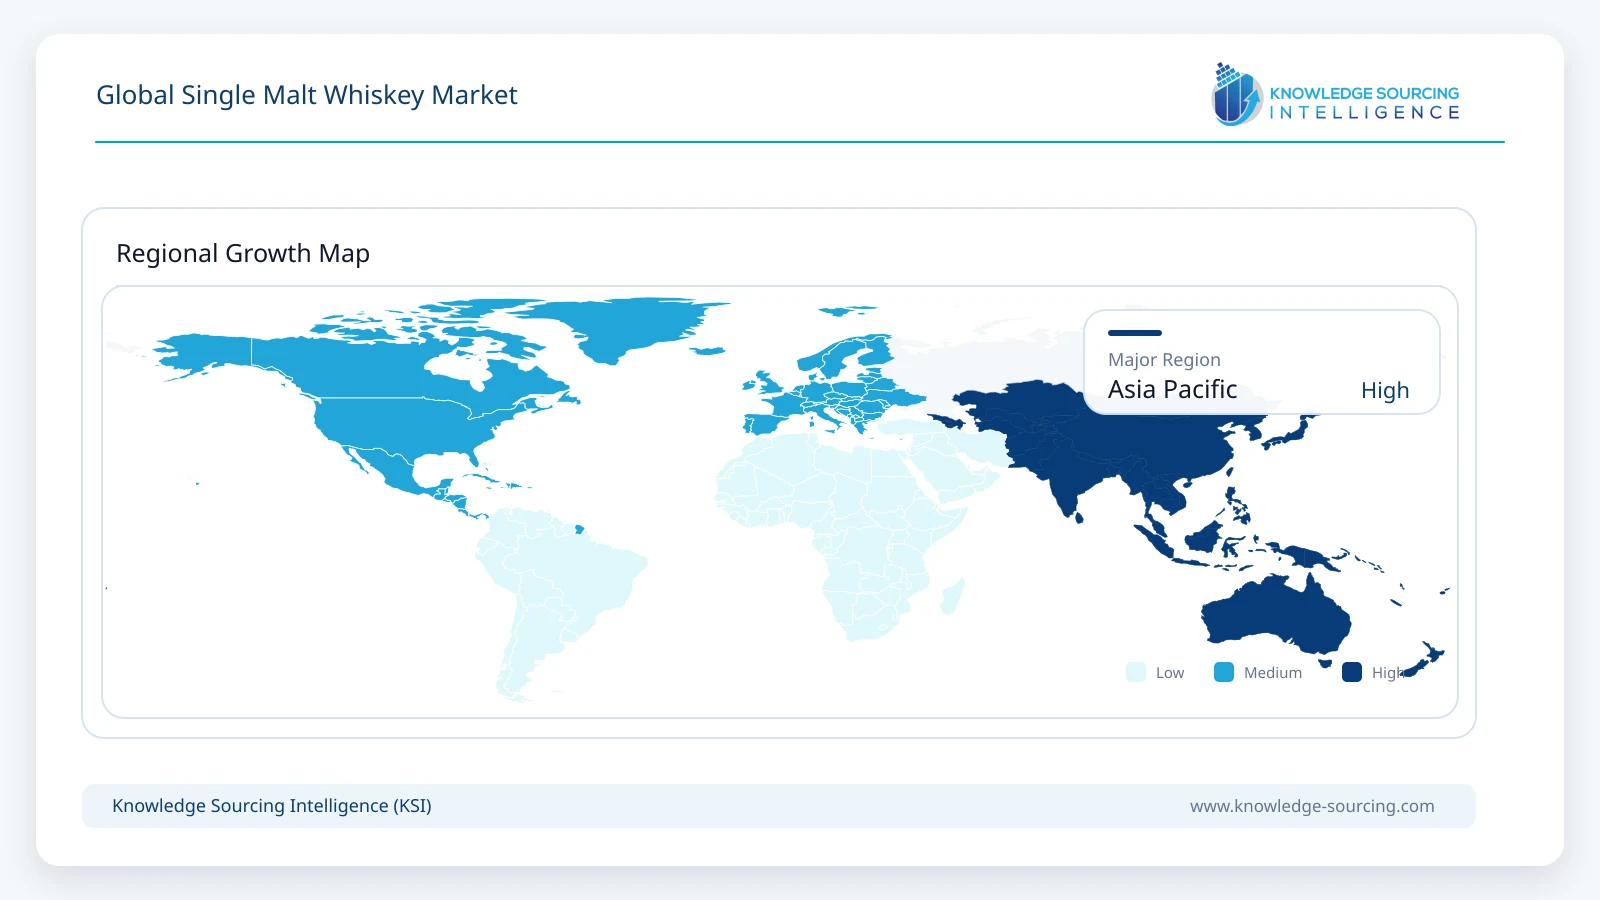
Asia Pacific accounts for approximately 29% of global single malt whiskey market value in 2026 and is projected to become the largest growth contributor through 2031.
The region combines major consuming markets with several increasingly important production origins. Japan has an established international reputation for premium whisky, India is emerging rapidly in both consumption and production, and China remains an important luxury-spirits market despite recent demand volatility. Australia and parts of Southeast Asia also support premium whiskey consumption through specialist retail and travel channels.
The UK-India trade agreement improves access for Scotch while domestic brands continue to expand, creating a market in which imported and locally produced single malts can grow simultaneously. Japanese brands such as Yamazaki and Hakushu maintain substantial international prestige, while Indian producers are moving into higher age statements and limited editions.
Asia Pacific is projected to represent approximately 35% of market value by 2031, overtaking more mature regions in incremental revenue contribution.
Competitive Landscape
The single malt whiskey market combines large global spirits groups with family-owned distillers and rapidly expanding producers from newer whisky origins.
Diageo maintains one of the broadest Scotch malt portfolios through Talisker, Lagavulin, The Singleton, Cardhu, Mortlach and other distilleries. Pernod Ricard competes through The Glenlivet, Aberlour and additional malt brands, while William Grant & Sons owns Glenfiddich and The Balvenie.
Edrington is particularly concentrated at the luxury end through The Macallan, Highland Park and The Glenrothes. Suntory Global Spirits participates across Scottish and Japanese single malts including Bowmore, Laphroaig, Yamazaki and Hakushu. Bacardi owns Aberfeldy, Aultmore, Craigellachie and Royal Brackla, while Brown-Forman owns The GlenDronach, Benriach and Glenglassaugh.
Indian competition is strengthening. Radico Khaitan’s Rampur, Piccadily Agro’s Indri, John Distilleries’ Paul John and Amrut Distilleries have expanded India’s presence in premium single malt. These producers increasingly compete internationally on origin, climate and cask character rather than primarily on lower pricing.
Competitive strategy is therefore becoming more segmented. Large Scotch producers leverage age inventories, heritage and global distribution, while newer producers rely on distinctive maturation environments, experimentation and faster-growing domestic premium markets.
Recent Developments
August 2026: Suntory Global Spirits’ Bowmore introduced the Captivo Collection comprising two 20-year-old Islay single malts developed with Snarkitecture.
August 2026: The Macallan introduced the sixth and final Harmony Collection release, comprising Inspired by Fresh Coconut and Inspired by Toasted Coconut single malts.
July 2026: The UK-India trade agreement entered into force, beginning the staged reduction of Indian tariffs on qualifying UK whisky.
June 2026: Piccadily Agro launched Indri Ilika as a travel-retail-exclusive Indian single malt expression.
April 2026: The Macallan introduced a 79-year-old single malt into its Red Collection.
March 2026: Indri and The Dram Club launched Indri Rudhira, matured in Pineau des Charentes casks.
February 2026: William Grant & Sons introduced a new global visual identity for Glenfiddich as part of a wider repositioning of the single malt brand.
Market Outlook
The global single malt market is expected to maintain mid-single-digit value growth through 2031 despite near-term volatility in premium spirits demand.
Scotch retains market leadership, supported by heritage, extensive aged stocks and international distribution. Its relative share gradually declines as Indian and American single malt grow considerably faster and Japanese products maintain strong luxury positioning.
Product development increasingly concentrates on cask finishing, limited editions, higher age statements and travel-retail exclusives. These formats allow producers to generate higher value from established distillery brands while appealing to collectors and enthusiasts.
Distribution also evolves. Specialist retailers remain important for discovery and high-value purchasing, but online and travel retail increase their share. Asia Pacific provides the strongest geographic growth as India develops simultaneously into a larger import destination and an internationally recognized single malt producer.
Single Malt Whiskey Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.12 billion |
| Total Market Size in 2031 | USD 5.63 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Origin, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Origin
Scotch Single Malt Whisky
Indian Single Malt Whisky
Japanese Single Malt Whisky
American Single Malt Whisky
Irish Single Malt Whiskey
Others
By Distribution Channel
On-Trade
Bars and Pubs
Hotels and Restaurants
Whisky Lounges and Others
Off-Trade
Specialist Retailers
Supermarkets and Hypermarkets
Travel Retail and Duty-Free
Online
Convenience and Other Retail
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
France
Germany
Spain
Italy
Netherlands
Others
Middle East and Africa
UAE
South Africa
Israel
Others
Asia Pacific
India
Japan
China
Australia
South Korea
Singapore
Taiwan
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary Research Framework
2.4. Secondary Research Framework
2.5. Data Triangulation
2.6. Forecast Methodology
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Premium Single Malt Production Beyond Scotland
4.1.2. Trade Liberalization and Improved Access to Major Whisky Markets
4.1.3. Growth of Premium and Luxury Whisky Consumption
4.1.4. Expansion of Travel Retail and Specialist Distribution
4.2. Market Restraints
4.2.1. Long Maturation Cycles and Limited Aged Inventory
4.2.2. Sensitivity of Premium Spirits to Consumer Spending
4.2.3. Tariff and International Trade Volatility
4.2.4. High Working-Capital Requirements for Aged Whisky Production
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Regulatory and Geographical Indication Environment
4.7. Strategic Recommendations
5. PRODUCT AND INDUSTRY TRENDS
5.1. Indian Single Malt Expansion
5.2. American Single Malt Category Development
5.3. Japanese Single Malt Premiumization
5.4. Cask Finishing and Secondary Maturation
5.5. Age-Statement and Luxury Releases
5.6. Limited and Collector Editions
5.7. Travel-Retail Exclusives
5.8. Distillery Tourism and Brand Experiences
6. GLOBAL SINGLE MALT WHISKEY MARKET BY ORIGIN
6.1. Introduction
6.2. Scotch Single Malt Whisky
6.3. Indian Single Malt Whisky
6.4. Japanese Single Malt Whisky
6.5. American Single Malt Whisky
6.6. Irish Single Malt Whiskey
6.7. Others
7. GLOBAL SINGLE MALT WHISKEY MARKET BY DISTRIBUTION CHANNEL
7.1. On-Trade
7.1.1. Bars and Pubs
7.1.2. Hotels and Restaurants
7.1.3. Whisky Lounges and Others
7.2. Off-Trade
7.2.1. Specialist Retailers
7.2.2. Supermarkets and Hypermarkets
7.2.3. Travel Retail and Duty-Free
7.2.4. Online
7.2.5. Convenience and Other Retail
8. GLOBAL SINGLE MALT WHISKEY MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. United Kingdom
8.3.2. France
8.3.3. Germany
8.3.4. Spain
8.3.5. Italy
8.3.6. Netherlands
8.3.7. Others
8.4. Middle East and Africa
8.4.1. UAE
8.4.2. South Africa
8.4.3. Israel
8.4.4. Others
8.5. Asia Pacific
8.5.1. India
8.5.2. Japan
8.5.3. China
8.5.4. Australia
8.5.5. South Korea
8.5.6. Singapore
8.5.7. Taiwan
8.5.8. Thailand
8.5.9. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Product Launches and Portfolio Expansion
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Diageo plc
10.2. Pernod Ricard SA
10.3. Suntory Global Spirits
10.4. William Grant & Sons Ltd.
10.5. The Edrington Group Limited
10.6. Bacardi Limited
10.7. Brown-Forman Corporation
10.8. LVMH Moët Hennessy Louis Vuitton SE
10.9. Davide Campari-Milano N.V.
10.10. Radico Khaitan Limited
10.11. Piccadily Agro Industries Limited
10.12. John Distilleries Pvt. Ltd.
11. APPENDIX
Navigate
Trusted by the world's leading organizations











