
The global mustard oil market is forecast to grow from USD 11.8 billion in 2026 to USD 15.1 billion by 2031, representing a CAGR of approximately 5.1% during the forecast period.
Highlights:
- 1Brown mustard oil accounts for approximately 76% of global mustard oil market value in 2026, reflecting its dominant position across Indian and Bangladeshi cooking applications.
- 2Household cooking accounts for approximately 75% of global market value in 2026, supported by established everyday consumption across northern and eastern India and Bangladesh.
- 3Offline channels account for approximately 84% of global mustard oil sales in 2026, although quick commerce and e-commerce are becoming increasingly important for premium packaged products.
- 4Asia Pacific accounts for approximately 93% of global mustard oil market value in 2026, reflecting the concentration of both consumption and crushing capacity in South Asia.
- 5India accounts for approximately 78% of global market value in 2026, making domestic seed production, edible-oil prices and branded-market development central to the global outlook.
Mustard oil is an edible or multipurpose oil produced primarily from brown, black or yellow/white mustard seeds through mechanical pressing, cold pressing and other commercially accepted extraction processes. The market includes packaged and loose mustard oil used for household cooking, foodservice, food processing and selected personal-care applications. Rapeseed oil is included only where it is produced and marketed commercially as mustard oil, as occurs in parts of South Asia, rather than where low-erucic rapeseed oil is sold separately as canola or rapeseed oil.
USDA's February 2026 assessment forecasts India's 2025/26 rapeseed-oil consumption at approximately 4.0 million tonnes, with domestic production of approximately 4.2 million tonnes. In Bangladesh, edible oil extracted from rapeseed and mustard seeds is commercially marketed as mustard oil, with USDA forecasting approximately 550,000 tonnes of domestic consumption and 700,000 tonnes of production in 2025/26.
India's Department of Consumer Affairs reported an all-India average retail price for packed mustard oil of approximately Rs 202 per kilogram on September 16, 2026. India and Bangladesh form the core consumption base for the global mustard oil market, with additional demand concentrated in Nepal and South Asian diaspora markets.
Growth through 2031 is expected to come from a combination of moderate consumption increases, branded-market conversion and premiumization. AWL Agri Business reported strong momentum in its mustard-oil portfolio during FY2025/26 and continued expanding higher-value cold-pressed offerings, illustrating the movement of the category toward branded and differentiated products.
Market Trends
Packaged and Branded Mustard Oil Is Taking Share From Loose Oil
The transition from loose and locally crushed oil toward packaged branded products remains one of the most important structural developments in the market. Large manufacturers compete increasingly on purity, standardized pungency, packaging convenience and brand trust rather than only price.
India's prohibition on the retail blending of mustard oil with other edible oils has reinforced the emphasis on pure mustard oil. FSSAI prohibited mustard oil in multi-source edible vegetable oil manufactured from June 8, 2021, and subsequently directed enforcement authorities to monitor compliance at manufacturing and market levels.
Large FMCG companies benefit from extensive distribution and quality-control systems, while specialist brands such as P Mark continue to compete on long-standing mustard expertise. The development is gradually formalizing a category that still contains numerous local crushers and regional brands.
Cold-Pressed Products Are Moving Into Mainstream Branded Portfolios
Kachi ghani and other cold-pressed products increasingly occupy premium positions within the mustard-oil category. Premiumization is occurring through extraction method, seed quality, purity, packaging and flavor differentiation.
AWL Agri Business expanded its premium portfolio through cold-pressed mustard oil during FY2025/26, while Tata Simply Better and Dabur also market cold-pressed mustard-oil products. Puri Oil Mills maintains a portfolio spanning traditional kachi ghani, organic, fortified, light and yellow mustard oils.
The trend increases average category value without requiring equivalent growth in consumption volume. It also creates space for specialist products targeting consumers willing to pay more for minimally processed oils and stronger product differentiation.
Yellow Mustard Oil Is Emerging as a Distinct Consumer Proposition
Manufacturers are increasingly differentiating mustard oil by seed variety and pungency. Yellow mustard provides a milder flavor profile than the stronger brown-mustard oils traditionally associated with many North and East Indian cuisines.
AWL Agri Business launched Fortune Yellow Mustard Oil in August 2026, initially targeting Delhi NCR and urban markets in Punjab and Haryana, while Nutrica has also expanded into yellow mustard oil. P Mark maintains both yellow mustard and reduced-pungency mustard-oil products in its portfolio.
The development allows manufacturers to target consumers who value the characteristics of mustard oil but prefer lower pungency. This could gradually widen penetration into households and regions where conventional mustard oil has historically faced flavor barriers.
Quick Commerce Is Becoming More Relevant to Packaged Oil Distribution
Mustard oil remains predominantly an offline retail category, but e-commerce and quick-commerce platforms are becoming more important for branded and premium offerings. The channel is particularly suited to one-litre and other household packs, allowing consumers to compare brands, processing claims and pricing without relying exclusively on neighborhood retailers.
Fortune's 2026 yellow mustard-oil launch includes quick-commerce distribution as part of its expansion strategy, while newer packaged brands increasingly use digital retail to build distribution before establishing broad physical store coverage.
Online penetration remains below categories such as supplements or electronics because edible oil is a high-frequency household staple and traditional retail remains deeply established. However, digital channels provide manufacturers with an increasingly effective route for premium and differentiated launches.
Market Drivers
Structural Household Consumption Provides a Large Recurring Demand Base
Mustard oil remains a routine cooking medium across large parts of northern and eastern India, Bangladesh and Nepal, creating a recurring consumption base that is less dependent on short-term food trends.
USDA estimates India's rapeseed-oil consumption at approximately 4.0 million tonnes in 2025/26, while Bangladesh consumes approximately 550,000 tonnes of rapeseed/mustard oil. In Bangladesh, USDA notes that mustard oil has become increasingly price competitive with soybean oil following higher domestic production.
Household demand is reinforced by applications including frying, pickling, curries and traditional regional dishes. Growth is therefore moderate but supported by a substantial established consumer base.
Government Support for Rapeseed-Mustard Production Strengthens Domestic Supply
India's National Mission on Edible Oils-Oilseeds is designed to increase domestic oilseed production and reduce the country's dependence on imported edible oils. The programme focuses explicitly on rapeseed-mustard alongside groundnut, soybean, sunflower and sesame.
The mission targets increasing primary oilseed production from 39 million tonnes in 2022/23 to 69.7 million tonnes by 2030/31 through higher-yielding varieties, expanded cultivation, seed systems and value-chain clusters. More than 600 value-chain clusters have been identified, while support also covers post-harvest infrastructure and oil mills.
Mustard-oil processors can benefit from higher domestic seed availability, improved productivity and additional processing infrastructure as these initiatives progress.
Greater Consumer Attention to Purity Supports Organized Brands
Edible-oil adulteration has historically reduced consumer confidence in loose oils, providing established packaged brands with an opportunity to differentiate around traceability, quality control and standardized production.
FSSAI's prohibition on blending mustard oil for retail multi-source edible oils strengthened the regulatory distinction between pure mustard oil and edible-oil blends. Packaged manufacturers increasingly reinforce this through purity positioning, branded sourcing and standardized packaging.
This is particularly important in urban and higher-income markets, where consumers may accept a premium for assurance around source, processing and product consistency. The shift supports branded-market growth even when aggregate consumption expands more gradually.
Market Restraints and Challenges
Mustard Oil Remains Exposed to Seed and Edible-Oil Price Volatility
Mustard seed is an agricultural commodity whose production depends on planted area, yields and seasonal weather. USDA reduced its early 2025/26 forecast for Indian rapeseed production after farmers shifted acreage toward wheat, although favorable weather and higher oil content continued supporting oil output.
Mustard oil also competes directly with soybean, sunflower, palm and groundnut oils. Consumers can change oils when relative prices widen substantially, particularly outside regions where mustard oil has the strongest culinary preference.
The Department of Consumer Affairs reported packed mustard oil at approximately Rs 202 per kilogram in September 2026, above soybean and palm oil prices during the same period. Persistent price premiums can constrain consumption growth among price-sensitive households.
Erucic-Acid Requirements Restrict Expansion in Some International Food Markets
Traditional expressed mustard oil can contain considerably more erucic acid than regulatory limits permitted for general edible oils in several Western markets.
The U.S. FDA's April 2026 import alert states that expressed mustard oil may contain 20-40% erucic acid and allows detention without physical examination unless appropriate evidence demonstrates that the product does not contain unsafe levels. The European Union currently applies a maximum erucic acid level of 50 g/kg specifically to mustard oil, compared with 20 g/kg for most other vegetable oils and fats.
These requirements constrain expansion of traditional high-erucic mustard oil as a mainstream cooking oil in some markets. International demand therefore remains concentrated in compliant products, specialty channels and markets with established South Asian consumption.
Segment Analysis
By Type: Brown Mustard Oil
Brown mustard oil is projected to generate approximately USD 11.2 billion by 2031, remaining the largest product type throughout the forecast period. Brown or Indian mustard, particularly Brassica juncea, is closely associated with the strong pungency expected by consumers across major Indian and Bangladeshi markets.
The segment benefits from entrenched household use and a large existing crushing infrastructure. Brown mustard also supports the kachi ghani positioning used by many leading branded oils, allowing producers to differentiate products through seed sourcing, first-press claims and pungency levels.
Yellow mustard grows faster from a smaller base as manufacturers target consumers looking for milder flavor, while black mustard remains important in selected culinary and specialty applications. Brown mustard nevertheless retains the largest value pool because it remains central to everyday consumption in the industry's largest markets.
By Application: Household Cooking
Household cooking is projected to generate approximately USD 11.3 billion by 2031, remaining the largest application for mustard oil. Demand is concentrated across northern and eastern India, Bangladesh and Nepal, where mustard oil is used regularly for frying, curries, vegetable preparation, pickling and other traditional foods.
The segment is increasingly moving toward packaged products as households place greater emphasis on purity and branded quality. Manufacturers also differentiate within household cooking through kachi ghani, cold-pressed, yellow mustard, organic and fortified variants.
Foodservice and food processing form the next major demand pool, particularly for regional cuisine and pickling. Personal-care applications remain commercially relevant, but the food market continues to determine the overall direction of mustard-oil consumption.
By Distribution Channel: Offline
Offline distribution is projected to generate approximately USD 12.0 billion by 2031, remaining the principal route to market. Kirana stores, supermarkets, wholesalers and regional grocery networks continue to handle the majority of household edible-oil purchases in India, Bangladesh and Nepal.
The importance of offline retail is reinforced by mustard oil's position as a recurring household staple rather than an occasional premium purchase. Leading manufacturers therefore depend on extensive distributor and retailer networks to achieve meaningful market penetration beyond major cities.
Online channels gain share through 2031 as quick-commerce platforms expand and brands increasingly launch premium products digitally. However, neighborhood retail remains structurally important, particularly in rural and semi-urban markets.
Major Region: Asia Pacific
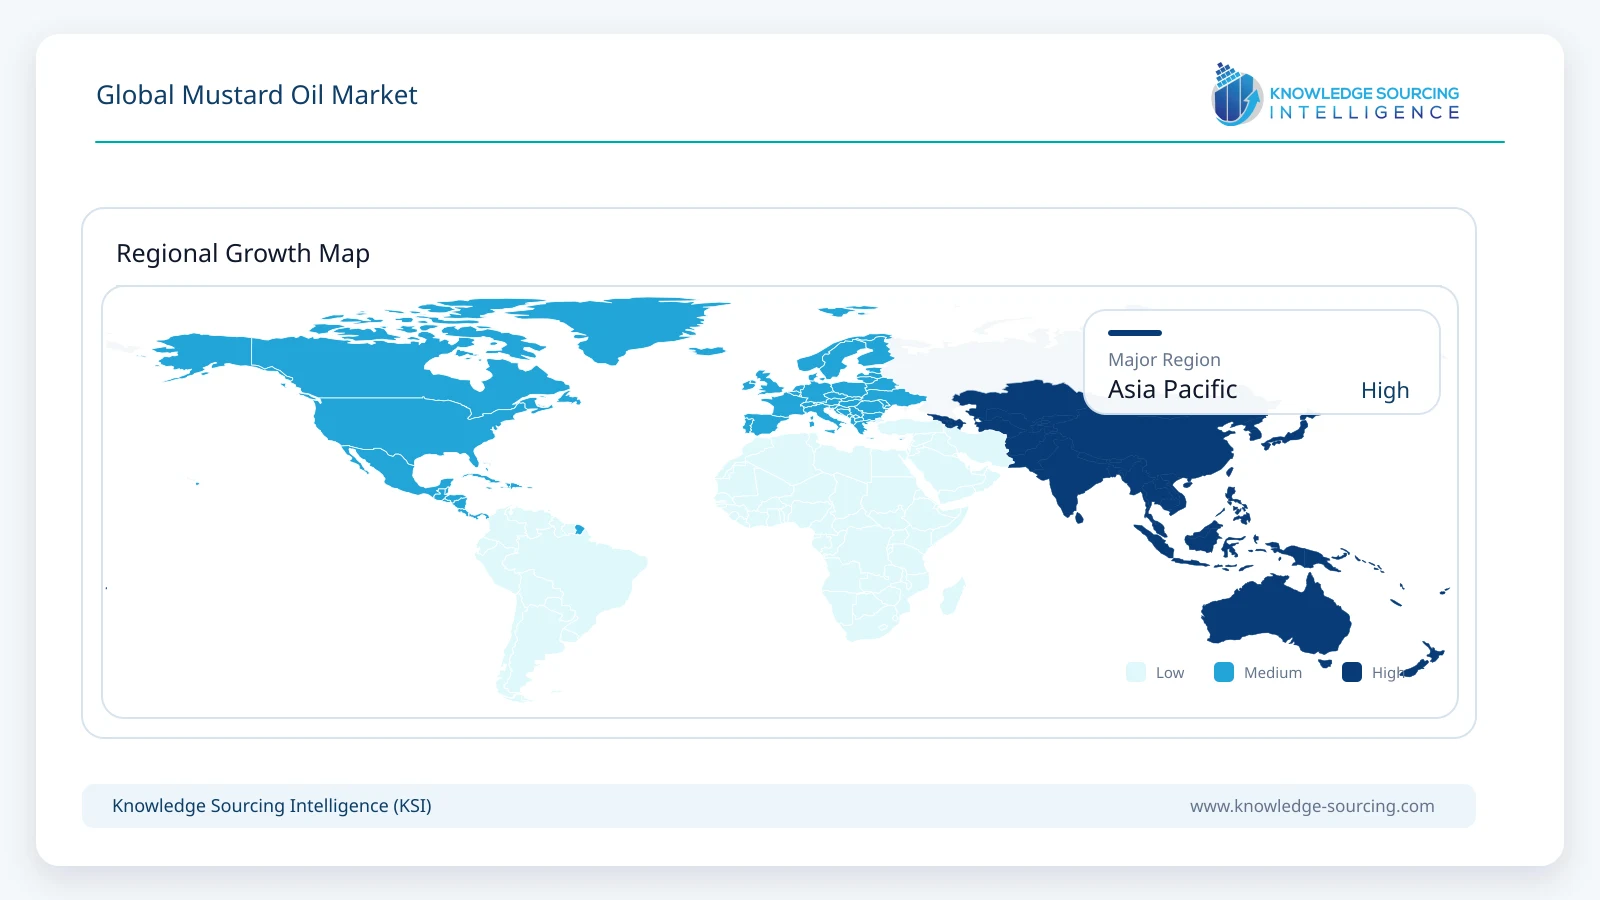
Asia Pacific is projected to generate approximately USD 14.0 billion in mustard oil revenue by 2031, maintaining overwhelming leadership through the forecast period. India and Bangladesh account for the majority of global demand and contain the principal crushing and seed-production ecosystem.
India produces more than four million tonnes of rapeseed oil annually, while Bangladesh is increasing mustard and rapeseed crushing and expects approximately 700,000 tonnes of oil production in 2025/26.
Regional growth is increasingly driven by branded-market conversion, premiumization and improvements in oilseed productivity. Bangladesh, Nepal and South Asian diaspora-linked export markets provide additional opportunities around the dominant Indian base.
Major Country: India
India is projected to generate approximately USD 11.5 billion in mustard oil revenue by 2031, remaining the largest individual national market.
The country's market combines large-scale household consumption with domestic mustard cultivation, regional oil mills and increasingly consolidated branded competition. AWL Agri Business participates through Fortune, while companies such as B.L. Agro, Emami Agrotech, Mother Dairy, Patanjali Foods and Puri Oil Mills maintain substantial regional and national positions.
Government oilseed policy provides a further structural influence. NMEO-Oilseeds is intended to increase domestic production, improve seed availability and expand processing infrastructure through 2030/31. At the consumer end, yellow-mustard, cold-pressed and quick-commerce products are increasing differentiation within a category that has historically competed primarily on purity, pungency and price.
Competitive Environment and Analysis
The mustard oil market remains fragmented despite increasing branded-market penetration. Large FMCG and edible-oil companies compete with specialist mustard-oil manufacturers, regional processors and numerous local crushing units.
AWL Agri Business participates through Fortune and maintains a strong position in India's branded edible-oil market. B.L. Agro operates Bail Kolhu alongside its broader Nourish food portfolio, while Emami Agrotech, Mother Dairy's Dhara, Patanjali Foods and Puri Oil Mills maintain established consumer brands.
Competition increasingly depends on distribution reach, seed sourcing, purity, pungency consistency and product differentiation rather than basic oil availability. Cold-pressed products allow manufacturers to move into premium price bands, while yellow mustard and reduced-pungency products target consumers outside the strongest traditional mustard-oil regions.
Bangladesh has a distinct competitive structure. USDA identifies Partex Group, PRAN Foods, City Group, ACI and Orion among major participants in the country's rapeseed/mustard-oil sector. Large producers coexist with numerous local crushing mills using domestic and imported seeds.
Industry formalization is likely to continue through 2031, but regional preferences and the economics of local crushing mean smaller manufacturers will remain important alongside national brands.
Recent Developments
August 2026: AWL Agri Business expanded the Fortune portfolio with Fortune Yellow Mustard Oil, initially focusing on Delhi NCR and urban Punjab and Haryana, with retail and quick-commerce distribution.
April 2026: BN Agritech's Nutrica expanded its cooking-oil portfolio with Nutrica Yellow Mustard Oil, targeting consumers seeking an unrefined, milder mustard-oil offering.
FY2025/26: AWL Agri Business expanded its premium edible-oil portfolio with cold-pressed mustard oil under the Fortune Premio range across selected markets and digital channels.
June 2025: Bunge India refreshed its Gagan edible-oil portfolio, which includes Kacchi Ghani Mustard Oil and conventional mustard oil, through dealer-focused expansion in northern India.
October 2024: The Government of India approved the National Mission on Edible Oils-Oilseeds, with a Rs 10,103 crore outlay through 2030/31 and specific support for rapeseed-mustard production.
Market Outlook
The global mustard oil market demonstrates steady growth, supported by strong consumer demand, established culinary applications, and a well-developed production base. Growth remains concentrated in South Asia, where mustard oil has deeply established culinary usage and an extensive domestic production base.
India continues to determine overall market performance through domestic rapeseed-mustard output, edible-oil pricing and household consumption. Bangladesh provides a second sizeable consumption base, while Middle Eastern, European and North American demand is supported mainly by South Asian communities and specialty-food channels.
The competitive emphasis increasingly shifts toward packaged purity, cold-pressed processing, yellow mustard variants, standardized pungency and stronger digital distribution. Government efforts to increase Indian oilseed production can improve the long-term raw-material environment, while branded manufacturers continue widening product portfolios and distribution.
The market therefore develops through a combination of stable household consumption, greater organized-market penetration and higher-value product formats.
Mustard Oil Market Scope:
| Report Metric | Details |
|---|---|
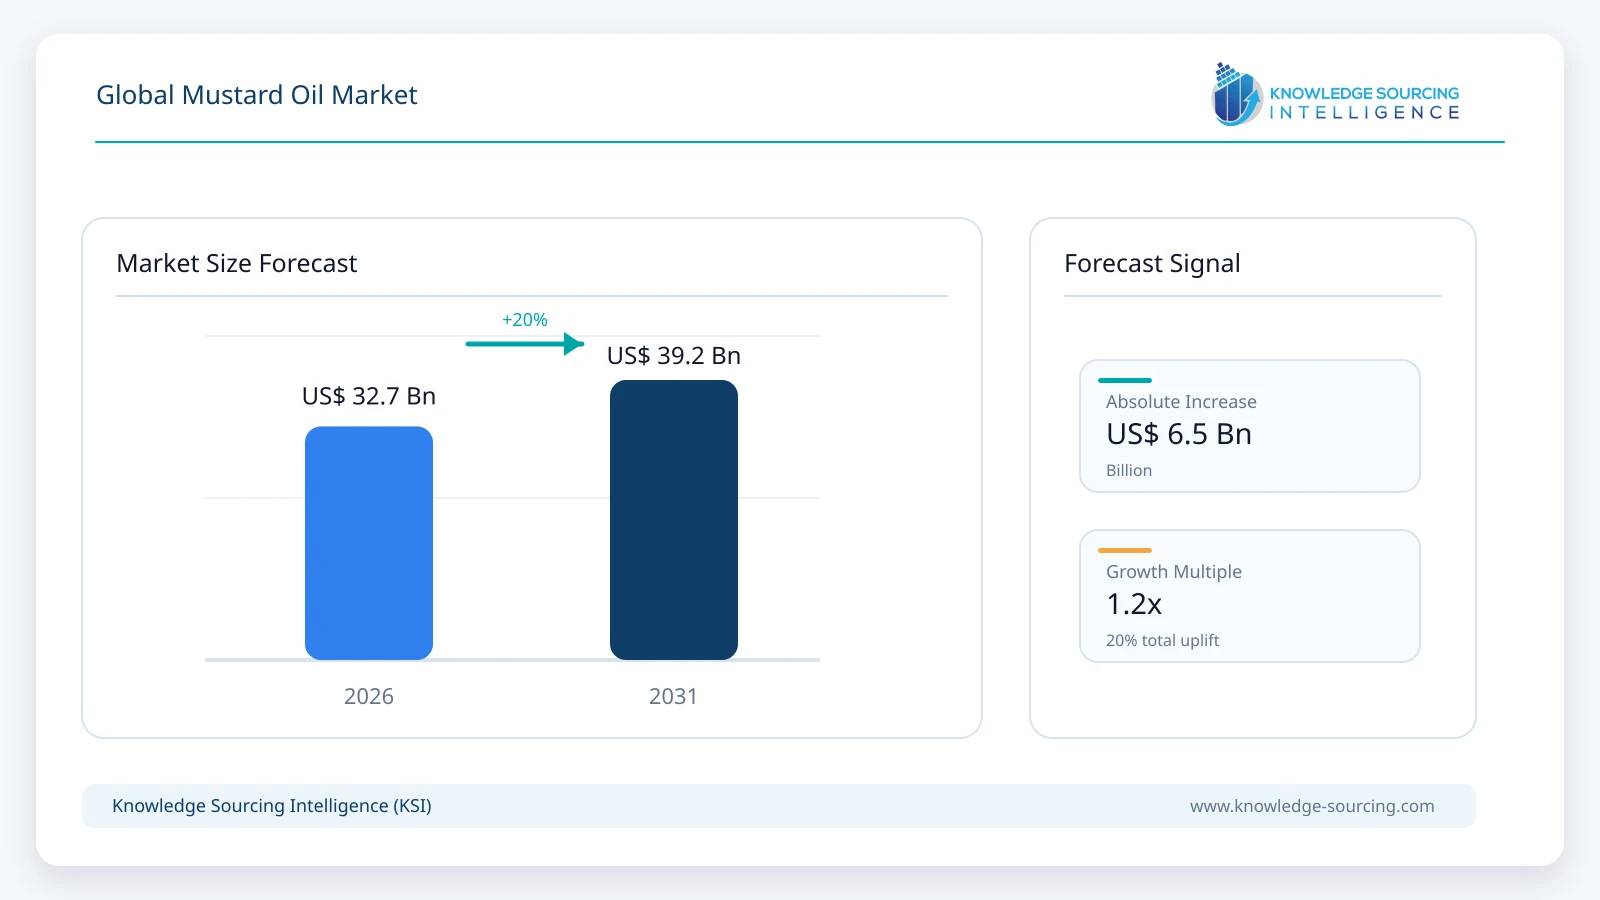
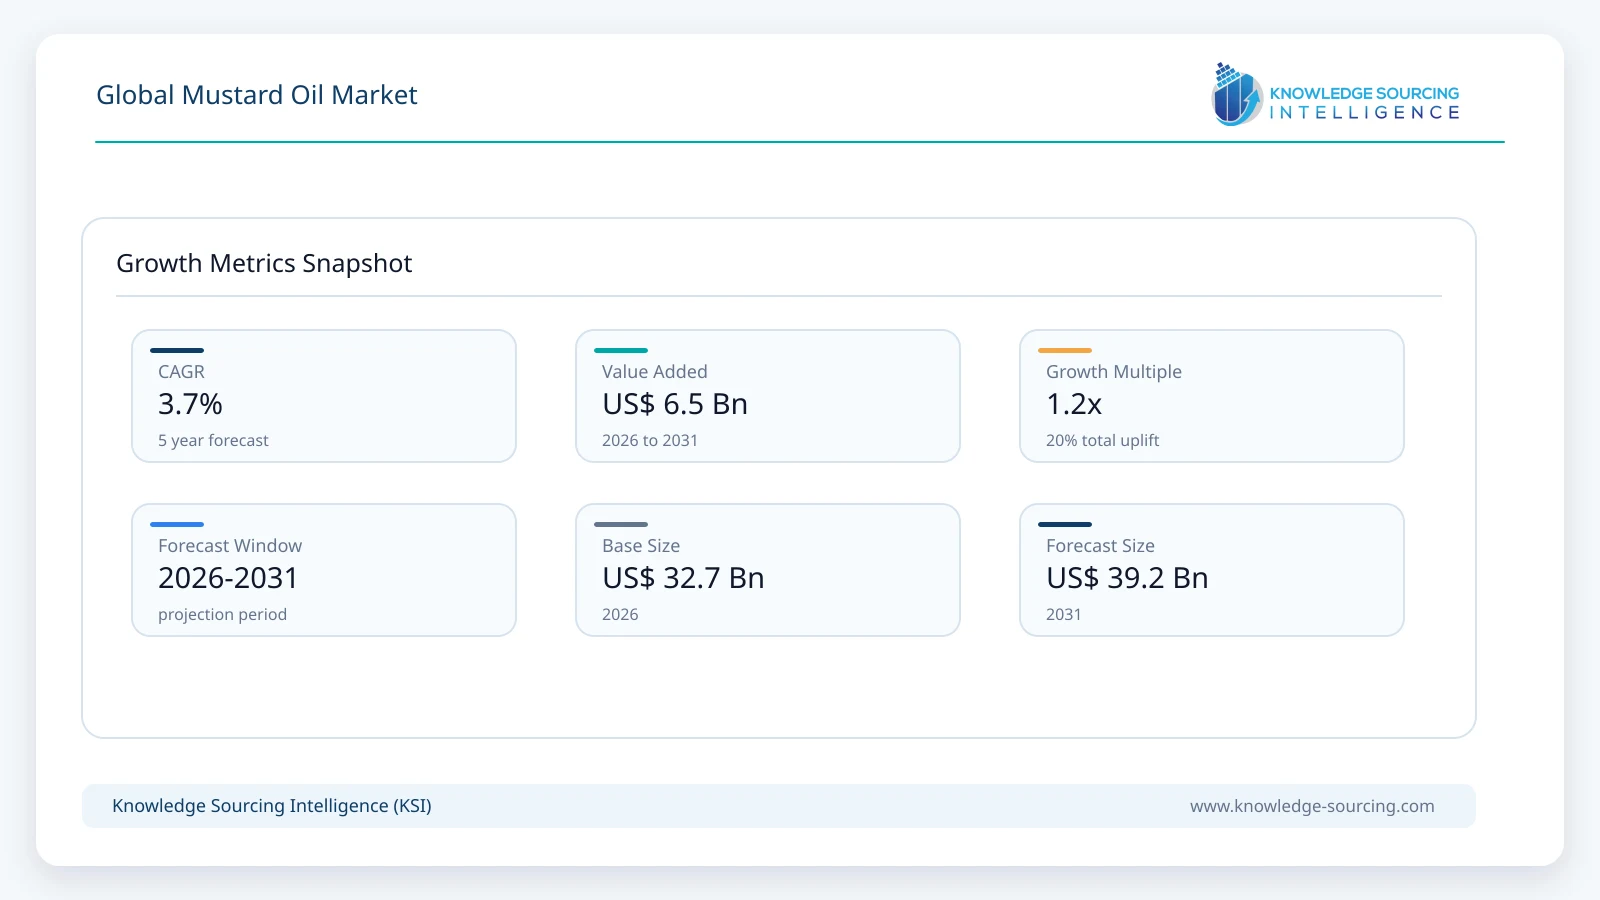
| Total Market Size in 2026 | USD 32.7 billion |
| Total Market Size in 2031 | USD 39.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Type
Brown Mustard Oil
Black Mustard Oil
Yellow/White Mustard Oil
By Application
Household Cooking
Foodservice and Food Processing
Personal Care and Traditional Massage
Industrial and Other Applications
By Distribution Channel
Offline
Traditional Grocery Stores
Supermarkets and Hypermarkets
Wholesale and Institutional Channels
Others
Online
E-commerce Marketplaces
Quick Commerce
Direct-to-Consumer
By Geography
North America
United States
Canada
Others
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Others
Middle East and Africa
United Arab Emirates
Saudi Arabia
Qatar
South Africa
Others
Asia Pacific
India
Bangladesh
Nepal
China
Australia
Others
Table of Contents
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Mustard Seed Production and Crushing Outlook
3.7. Raw Material and Pricing Analysis
3.8. Kachi Ghani and Cold-Pressed Oil Trends
3.9. Regulatory and Erucic Acid Environment
3.10. Packaged and Branded Market Transition
3.11. Strategic Recommendations
4. MUSTARD OIL MARKET BY TYPE
4.1. Introduction
4.2. Brown Mustard Oil
4.3. Black Mustard Oil
4.4. Yellow/White Mustard Oil
5. MUSTARD OIL MARKET BY APPLICATION
5.1. Introduction
5.2. Household Cooking
5.3. Foodservice and Food Processing
5.4. Personal Care and Traditional Massage
5.5. Industrial and Other Applications
6. MUSTARD OIL MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Offline
6.2.1. Traditional Grocery Stores
6.2.2. Supermarkets and Hypermarkets
6.2.3. Wholesale and Institutional Channels
6.2.4. Others
6.3. Online
6.3.1. E-commerce Marketplaces
6.3.2. Quick Commerce
6.3.3. Direct-to-Consumer
7. MUSTARD OIL MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Application
7.2.3. By Distribution Channel
7.2.4. By Country
7.2.4.1. United States
7.2.4.2. Canada
7.2.4.3. Others
7.3. South America
7.3.1. By Type
7.3.2. By Application
7.3.3. By Distribution Channel
7.3.4. By Country
7.3.4.1. Brazil
7.3.4.2. Argentina
7.3.4.3. Others
7.4. Europe
7.4.1. By Type
7.4.2. By Application
7.4.3. By Distribution Channel
7.4.4. By Country
7.4.4.1. United Kingdom
7.4.4.2. Germany
7.4.4.3. France
7.4.4.4. Others
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Application
7.5.3. By Distribution Channel
7.5.4. By Country
7.5.4.1. United Arab Emirates
7.5.4.2. Saudi Arabia
7.5.4.3. Qatar
7.5.4.4. South Africa
7.5.4.5. Others
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Application
7.6.3. By Distribution Channel
7.6.4. By Country
7.6.4.1. India
7.6.4.2. Bangladesh
7.6.4.3. Nepal
7.6.4.4. China
7.6.4.5. Australia
7.6.4.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Branded Market Positioning
8.3. Regional and Local Crusher Competition
8.4. Product and Processing Innovation
8.5. Mergers, Acquisitions, Agreements, and Collaborations
8.6. Competitive Dashboard
9. COMPANY PROFILES
9.1. AWL Agri Business Limited
9.2. B.L. Agro Industries Limited
9.3. Patanjali Foods Limited
9.4. Emami Agrotech Limited
9.5. Mother Dairy Fruit & Vegetable Pvt. Ltd.
9.6. Puri Oil Mills Limited
9.7. B P Oil Mills Limited
9.8. Pansari Group
9.9. BN Agritech Limited
9.10. Tata Consumer Products Limited
9.11. Dabur India Limited
9.12. Bunge India
9.13. Shree Mangal Proteins Limited
9.14. Partex Star Group
9.15. PRAN-RFL Group
10. APPENDIX
10.1. Market Definition and Scope
10.2. Currency
10.3. Assumptions
10.4. Base and Forecast Years
10.5. Research Methodology
10.6. Segment Modelling
10.7. Data Triangulation and Validation
10.8. Abbreviations
Navigate
Trusted by the world's leading organizations











