
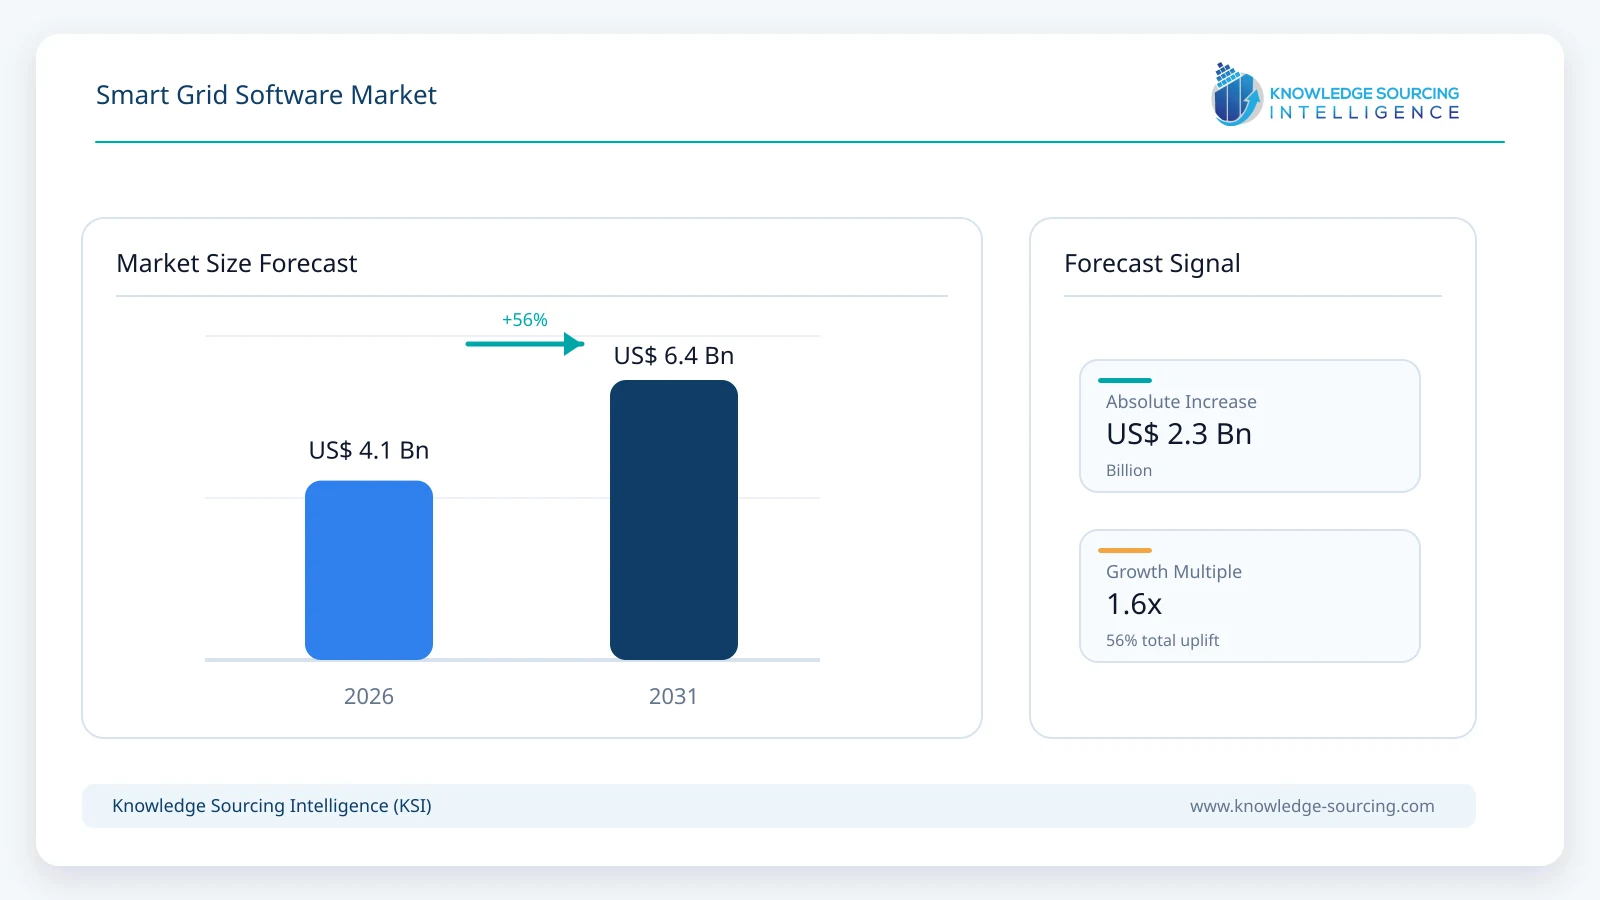
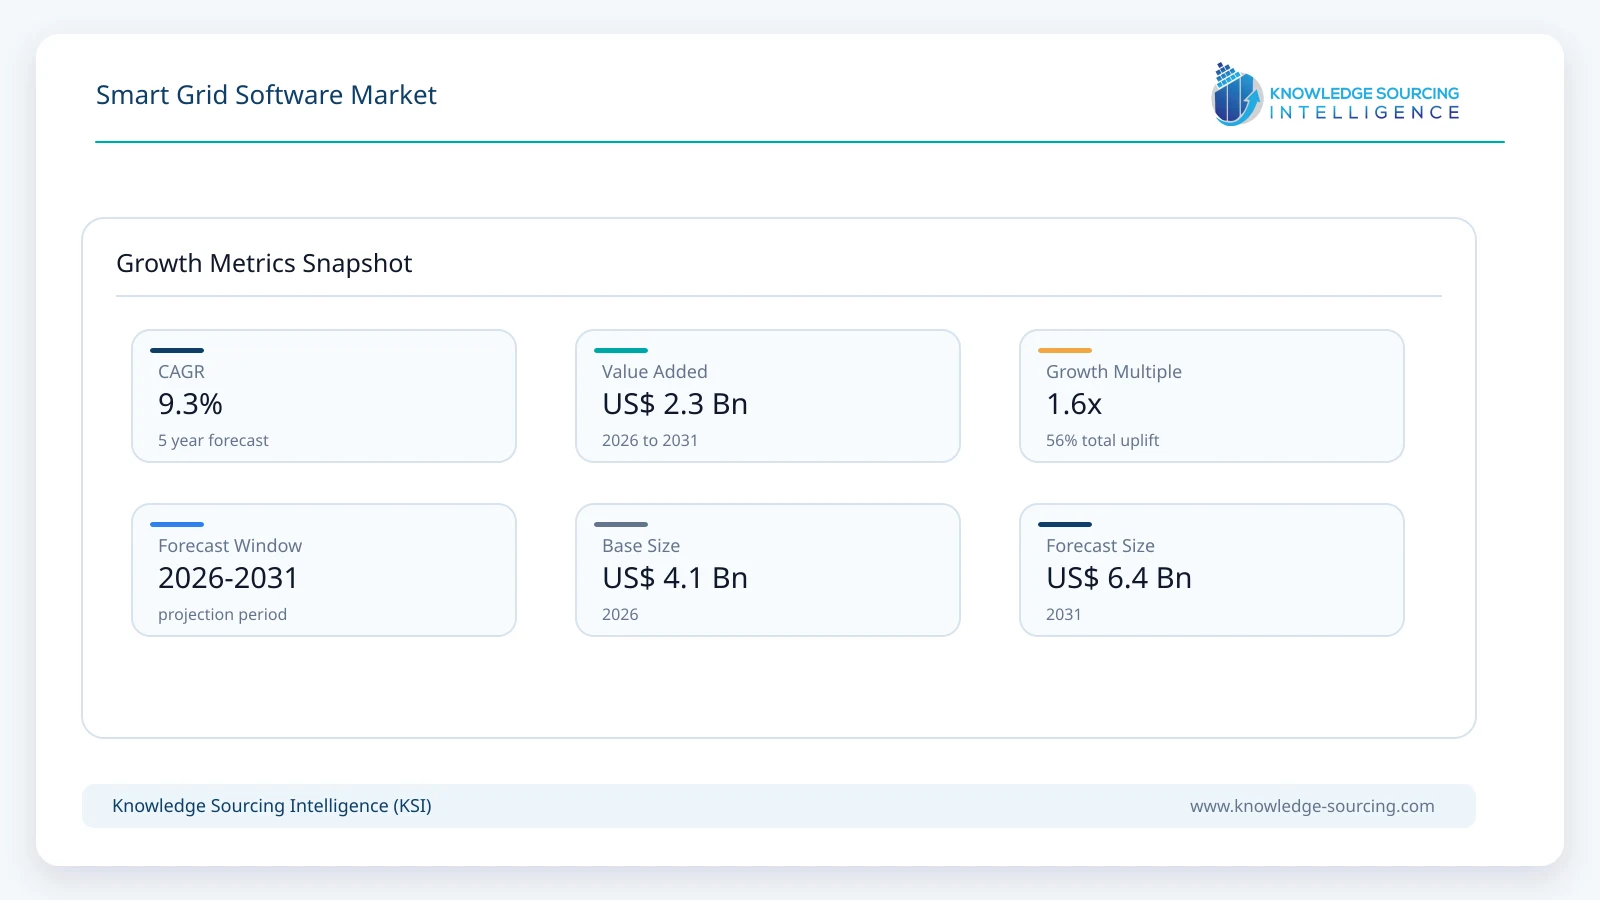
The smart grid software market is forecast to grow at a CAGR of 9.3%, reaching USD 6.4 billion in 2031 from USD 4.1 billion in 2026.
Highlights:
- 1Distribution Management System software accounts for approximately 24% of market value in 2026 and remains the largest software-type segment through 2031.
- 2Grid Security is projected to expand at approximately 13.0% CAGR, the fastest rate among the major software categories as utilities expose more operational assets to digital networks.
- 3Deployment and Maintenance represents approximately 43% of service-related market value in 2026, reflecting the integration complexity of utility IT and operational-technology environments.
- 4Support and Maintenance gains share through 2031, supported by recurring software upgrades, cybersecurity requirements and cloud-based operations.
- 5Distribution Management is the largest application segment in 2026, while demand-response software gains importance as EVs, batteries and distributed generation expand.
- 6Asia Pacific is projected to grow at approximately 12.6% CAGR, increasing from about 25% of market value in 2026 to 29% by 2031.
Utilities are moving from conventional supervisory systems toward more integrated software environments capable of coordinating renewable generation, distributed energy resources, advanced meters, electric-vehicle loads and increasingly dynamic electricity demand.
Smart grid software is becoming the operational layer connecting physical grid assets with real-time data and automated decision-making. Distribution management systems, network-management platforms, meter-data applications, grid analytics, demand-response software and cybersecurity tools increasingly need to operate as an interconnected stack rather than as isolated utility applications. GE Vernova’s GridOS portfolio, for example, combines applications for grid orchestration, renewable integration, network lifecycle management and distributed-energy-resource management, illustrating how grid software is broadening from individual control applications toward platform-based operations.
The same trend is visible across other large vendors. Siemens is extending Gridscale X as a common digital foundation for planning and operation and announced the next evolution of the platform in 2026, including AI-powered transmission planning capabilities. Schneider Electric continues to position EcoStruxure Grid around DER integration, grid optimisation, cloud applications and asset intelligence. These developments support the KSI view that smart-grid software growth is increasingly tied to grid complexity rather than merely to new smart-meter installations.
Market Growth Drivers and Trends
Distributed Energy Resources Are Increasing the Need for Real-Time Distribution Management
Distribution networks were historically designed for one-way electricity flows from central generation toward customers. Rooftop solar, batteries, electric vehicles and other distributed resources are changing that architecture by introducing variable generation and controllable loads at the grid edge. Utilities therefore need software capable of estimating network conditions, forecasting distributed-resource behaviour and adjusting operations before local constraints become reliability problems.
Schneider Electric explicitly positions its smart-grid offering around DER integration and grid-to-prosumer operations, while GE Vernova’s GridOS renewable-management portfolio includes applications for distributed energy resources and EV planning. These commercial portfolios support KSI’s assumption that Distribution Management System software grows faster than conventional metering-related platforms and increases its market share through 2031.
AI Is Moving from Grid Analytics into Operational Decision Support
Artificial intelligence is increasingly being incorporated into planning, condition assessment, forecasting and real-time decision support. Siemens’ 2026 Grid Software Summit introduced the next evolution of Gridscale X and AI-powered, agentic capabilities for transmission planning, while PSI Software is introducing AI-based decision support across grid-control and network-planning products.
This changes the role of grid analytics. Instead of simply presenting historical information, software increasingly needs to predict network states, identify likely constraints and recommend or automate operational responses. PSI’s August 2026 deployment for four E.ON grid companies provides a practical example: its software continuously combines network models, schedules and forecast data to generate predictive grid-state assessments.
KSI therefore expects grid analytics to remain a major application category while AI capabilities become embedded across DMS, network management, asset management and security rather than remaining a standalone software product.
Grid-Edge Intelligence Is Extending Software Beyond the Control Center
Smart-grid intelligence is increasingly moving closer to the meter, transformer and feeder. Landis+Gyr’s Revelo platform combines high-resolution sensing with edge computing, while its broader architecture integrates devices, communications, data and utility software. The company reorganized its strategy in 2026 around Connected Platforms and Grid Intelligence and highlighted software, analytics, AI-enabled applications and flexibility management as important growth areas.
This architecture reduces the need to send every data point back to a central system before action can occur. Edge applications can detect voltage issues, identify anomalies and support demand-management decisions closer to the source, strengthening the relationship between AMI data and higher-value grid-management software.
Demand Flexibility Is Becoming a Grid-Capacity Resource
Utilities increasingly need alternatives to traditional network reinforcement as electrification raises local peak loads. Demand-response software can shift or curtail electricity use, allowing utilities to use flexible loads as a grid-management resource. Landis+Gyr’s demand-response platform, for example, uses software, smart devices and two-way communication to manage peaks and integrate intermittent renewable generation.
EV charging, batteries, heat pumps and flexible commercial loads increase the addressable base for these systems. KSI therefore projects Demand Response applications to expand at approximately 10.7% annually through 2031, increasing their contribution to smart-grid software spending by the end of the forecast period.
Utilities Are Moving Toward Platform-Based and Cloud-Enabled Grid Software
Legacy utility environments often contain separate systems for meter data, outage management, network control, asset management and customer operations. Vendors are increasingly consolidating these applications onto shared data and software platforms. Oracle Utilities Smart Grid Gateway, for example, links meter-data and device-management applications while integrating with Oracle’s network-management and outage systems.
GE Vernova, Siemens and PSI are pursuing similar platform strategies. Cloud deployment improves scalability and can reduce infrastructure-management requirements, but the more important benefit is the ability to share data across applications. This architecture becomes increasingly valuable as utilities need consistent grid models spanning planning, operations and customer-owned resources.
Market Restraints
Legacy Utility Systems Increase Integration Complexity
Utilities often operate control systems, GIS, meter-data platforms and customer-information systems that were installed at different times and use different data models. Smart-grid software therefore rarely operates as a simple standalone installation. Integration requires interfaces with operational technology, enterprise IT and field equipment while maintaining continuous grid operations.
The resulting implementation cost is one reason deployment and maintenance remains the largest service category in the KSI model. Utilities cannot replace all legacy infrastructure simultaneously, forcing vendors to support staged migrations and mixed software environments.
Cybersecurity Requirements Raise Development and Operating Costs
As operational grid systems become more connected, the attack surface expands. Software now communicates with smart meters, substations, distributed resources and increasingly cloud-hosted platforms, making authentication, encryption, access management and vulnerability monitoring central product requirements.
KSI therefore projects Grid Security to be the fastest-growing software-type category, but security also functions as a restraint because compliance and cyber-hardening increase the cost and complexity of deployment.
Utility Procurement Cycles Remain Long
Electric utilities operate critical infrastructure and typically require extensive testing, regulatory review and integration validation before replacing core operational systems. Large DMS, outage-management or network-management projects can therefore require multi-year procurement and implementation cycles.
This slows the conversion of technology innovation into revenue compared with ordinary enterprise software markets. New AI and cloud capabilities still need to meet reliability and regulatory expectations before they can influence live grid operations.
Data Quality Limits Advanced Analytics
AI and advanced grid management depend on accurate network models and field data. Missing asset records, incorrect connectivity information and inconsistent meter or GIS data can materially reduce the value of sophisticated software.
Utilities therefore often need data-cleaning and modelling work before they can use predictive grid applications effectively. This increases project cost and can delay advanced automation even when the underlying software is commercially available.
Smaller Utilities Face Budget and Skills Constraints
Advanced grid applications require engineering expertise, cybersecurity resources and ongoing software-management capability. Smaller municipal and cooperative utilities may find it harder to justify or support large enterprise platforms despite facing similar renewable-integration and reliability challenges.
Cloud services and standardized platforms can lower the barrier, but affordability and workforce availability remain meaningful constraints, particularly in developing markets.
Smart Grid Software Market Segmentation Analysis
By Software Type
Distribution Management System
Distribution Management System software accounts for approximately 24% of market value in 2026, equivalent to about USD 0.98 billion. DMS platforms increasingly coordinate voltage management, switching, distributed resources, outage information and grid-state estimation rather than functioning solely as traditional control-room applications.
The segment is projected to reach approximately USD 1.60 billion by 2031, increasing its share to around 25%. Greater distributed-generation penetration and bidirectional power flows make distribution-system visibility increasingly important through the end of the forecast period.
Advanced Metering Infrastructure
AMI-related software represents approximately 20% of the market in 2026, supported by meter-data management, device integration and associated utility applications. Oracle Smart Grid Gateway and Landis+Gyr’s MDMS demonstrate the continuing need to process data from large meter fleets and connect that information with operational and customer applications.
The segment grows more slowly than DMS and security software because AMI is already relatively mature in several developed utility markets. Its share therefore moderates to approximately 18% by 2031 even as absolute spending continues to rise.
Grid Asset Management
Grid Asset Management represents approximately 14% of market value in 2026 and retains a similar share through 2031. Digital asset-health and maintenance applications help utilities prioritize inspection and replacement decisions across transformers, substations and other infrastructure.
As utilities face rising capital requirements, software that extends useful asset life or improves maintenance prioritization becomes more valuable. The category therefore grows broadly in line with the overall market.
Network Management System
Network Management System software accounts for approximately 13% of the market in 2026 and remains structurally important across transmission and distribution operations. Oracle’s current NMS architecture includes integration with outage operations and Grid Edge DERMS functionality, indicating how conventional network-management software is expanding toward distributed-resource coordination.
Grid Security
Grid Security represents approximately 11% of market value in 2026 and is projected to expand at about 13.0% CAGR through 2031. Its share rises to roughly 13% as utilities increase digital connectivity across operational systems.
The segment’s faster growth reflects both the expansion of connected assets and the higher strategic importance of cyber resilience. Security increasingly becomes an embedded requirement across every major smart-grid software deployment rather than an optional add-on.
Substation Automation and Billing & Customer Information Systems
Substation Automation software continues growing as digital substations and remote operations expand, but it loses modest share relative to newer analytics and security applications. Billing and Customer Information Systems remain an important integration layer, particularly where time-of-use pricing, distributed resources and demand-response programs require more sophisticated customer interactions.
By Service Type
Deployment and Maintenance
Deployment and Maintenance accounts for approximately 43% of service-related value in 2026, making it the largest category. Smart-grid software projects require integration across GIS, SCADA, AMI, enterprise systems and field devices, giving implementation partners and vendor professional-services teams an important role.
The category reaches approximately USD 2.62 billion by 2031 but loses modest share as the installed base shifts expenditure toward recurring support and software maintenance.
Support and Maintenance
Support and Maintenance is projected to grow at approximately 12.5% CAGR through 2031, making it the fastest-growing service segment. The share rises from around 32% in 2026 to approximately 37% by the end of the forecast period.
The change reflects larger installed software estates, continuous security updates, cloud operations and regular model or application upgrades. Utilities increasingly need continuous support rather than occasional maintenance around major version releases.
Consulting
Consulting remains important during grid-modernisation planning, system architecture and procurement but grows more slowly than recurring support. As utilities accumulate internal digital capabilities and standardized products mature, a larger share of spending moves toward implementation and long-term operation.
By Application
Distribution Management
Distribution Management is the largest application segment with approximately a 25% share in 2026. Increasing DER penetration and the need for low-voltage visibility make distribution networks the most active area of grid digitisation.
KSI projects the segment to reach approximately 26% of market value by 2031, supported by integrated DMS, DERMS and grid-edge management.
Energy Management Systems
Energy Management Systems account for approximately 23% of the market in 2026. These platforms remain critical for balancing generation, transmission and load across larger utility systems and increasingly incorporate renewable forecasting and advanced analytics.
Grid Analytics
Grid Analytics represents approximately 20% of market value in 2026. AI is broadening the segment from historical reporting toward predictive planning, anomaly detection and operational decision support.
PSI’s predictive grid-state forecasting for E.ON and Siemens’ agentic transmission-planning capabilities are strong examples of this transition.
Outage Management
Outage Management remains a core reliability application and accounts for approximately 17% of market value in 2026. Integration with AMI and network models improves fault detection and restoration, but the segment grows somewhat more slowly than demand-response and cybersecurity applications.
Demand Response
Demand Response is projected to grow at approximately 10.7% CAGR through 2031. Greater EV, battery and flexible-load penetration allows utilities to treat demand as a dispatchable grid resource rather than purely as an uncontrollable requirement.
This increases the importance of software capable of identifying available flexibility, communicating with devices and verifying customer response during grid events.
Geographical Outlook
North America
North America represents approximately 35% of market value in 2026, making it the largest regional market. High AMI penetration, utility grid-modernisation programs, DER adoption and large technology vendors support continued software investment.
The region is projected to reach approximately USD 2.05 billion by 2031, although its share moderates to about 32% as Asia Pacific grows more rapidly.
Europe
Europe accounts for approximately 27% of global market value in 2026. Renewable integration, cross-border electricity markets, EV adoption and increasingly active distribution networks support demand for grid management and flexibility software.
Projects such as PSI’s predictive grid-state deployment across E.ON distribution companies show how European utilities are moving toward forecast-driven operations rather than relying solely on real-time monitoring.
Asia Pacific
Asia Pacific is projected to grow at approximately 12.6% CAGR through 2031, making it the fastest-growing major region in the KSI model. Its share increases from roughly 25% in 2026 to about 29% by the end of the forecast period.
China’s grid digitalisation, India’s smart-meter and distribution-modernisation programmes, and growing grid complexity across Japan, South Korea, Australia and Southeast Asia create a broad software opportunity. PSI’s decision to showcase grid-control, planning and AI software at Enlit Asia 2026 and Landis+Gyr’s expansion of its edge-app ecosystem in Australia illustrate the increasing commercial focus on the region.
South America and Middle East & Africa
South America remains smaller but benefits from renewable integration and distribution-modernisation programs, particularly in Brazil. Middle East & Africa similarly represents a smaller share, with demand concentrated around utility digitisation, renewable integration and large-scale grid infrastructure programs.
Both regions retain broadly stable shares in the KSI model while growing with overall smart-grid software adoption through 2031.
Recent Developments
August 2026: PSI Software received final acceptance for the PSIaso/DSO subproject deployed across four E.ON grid companies. The solution provides predictive grid-state forecasting by combining network models with schedule and forecast data. The deployment supports KSI’s growth assumptions for grid analytics and distribution-management software.
August 2026: Landis+Gyr expanded its Edge Application Ecosystem in Australia by adding Future Grid and Operational Technology Solutions. The ecosystem enables applications to run closer to the grid edge and supports real-time optimisation, reinforcing the shift from centralized meter-data collection toward distributed grid intelligence.
June 2026: Landis+Gyr reorganized its business around Connected Platforms and Grid Intelligence, highlighting software, analytics, flexibility management and AI-enabled applications as major growth areas. The move supports KSI’s view that software and analytics are becoming a larger strategic component of AMI and grid-edge platforms.
April 2026: Landis+Gyr joined EPRI’s Open Power AI Consortium, which is developing open-source AI models, datasets and testing environments for utility applications. This directly supports the increasing use of AI within grid analytics, forecasting and operational decision-making.
April 2026: PSI and partners completed testing of an Energy Internet of Things platform designed for distributed and IT-secure control of electricity distribution networks. PSI served as the platform architect, integrating participating systems through standardized interfaces. The project supports the market’s movement toward secure, distributed grid-control architectures.
March 2026: Festival Hydro selected Landis+Gyr’s Revelo platform for approximately 23,000 customers in Ontario, combining advanced grid sensing with energy-management capability. The development shows how AMI investments are increasingly being justified by grid visibility and flexibility rather than meter-reading alone.
2026: Siemens announced the next evolution of Gridscale X, including AI-powered and agentic transmission-planning capabilities built around the PSS E platform. The development provides evidence that advanced planning and operational AI are moving into established utility-software suites.
Competitive Environment
The competitive landscape consists of traditional grid-technology suppliers, enterprise utility-software vendors, meter and communications companies, specialist DER-management companies and software integrators. Siemens, Schneider Electric and GE Vernova have particularly broad portfolios spanning planning, operations, network management and renewable integration. Oracle brings meter-data, customer, asset and network-management applications, while Landis+Gyr combines grid-edge devices with increasingly software-led intelligence.
PSI Software competes as a specialized grid-control and optimisation software provider, while Smarter Grid Solutions focuses strongly on DER management and distributed-energy orchestration. Itron combines AMI, grid-edge intelligence and distributed-energy-management capabilities.
Competitive advantage increasingly depends on three capabilities: maintaining a high-quality common network model, integrating multiple legacy and field systems, and providing advanced analytics without compromising operational reliability. Vendors that can combine cloud flexibility with utility-grade cybersecurity and high-availability control functionality are best positioned as software becomes more central to grid operations.
Smart Grid Software Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.1 billion |
| Total Market Size in 2031 | USD 6.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Software Type, Service Type, Application, Geography |
| Companies |
|
Market Segmentation
By Software Type
Advanced Metering Infrastructure
Grid Asset Management
Distribution Management System
Network Management System
Substation Automation
Grid Security
Billing and Customer Information System
By Service Type
Consulting
Deployment and Maintenance
Support and Maintenance
By Application
Energy Management Systems
Distribution Management
Outage Management
Demand Response
Grid Analytics
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
United Kingdom
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Rest of Asia Pacific
South America
Brazil
Argentina
Rest of South America
Middle East and Africa
Saudi Arabia
Israel
Rest of Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
3.8. Product Pipeline Analysis
3.9. Incidence and Prevalence Analysis
3.10. Patent Analysis
4. TECHNOLOGICAL OUTLOOK
5. SMART GRID SOFTWARE MARKET BY SOFTWARE TYPE
5.1. Introduction
5.2. Advanced Metering Infrastructure
5.3. Grid Asset Management
5.4. Distribution Management System
5.5. Network Management System
5.6. Substation Automation
5.7. Grid Security
5.8. Billing and Customer Information System
6. SMART GRID SOFTWARE MARKET BY SERVICE TYPE
6.1. Introduction
6.2. Consulting
6.3. Deployment and Maintenance
6.4. Support and Maintenance
7. SMART GRID SOFTWARE MARKET BY APPLICATION
7.1. Introduction
7.2. Energy Management Systems
7.3. Distribution Management
7.4. Outage Management
7.5.Demand Response
7.6. Grid Analytics
8. SMART GRID SOFTWARE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Spain
8.5.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Chetu
10.2. Schneider Electric
10.3. Smarter Grid Solutions
10.4. Oracle
10.5. IBM
10.6. Globema
10.7. Accenture
10.8. Landis+Gyr
10.9. PSI Software AG
10.10. Siemens
10.11. NVIDIA Corporation
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











