
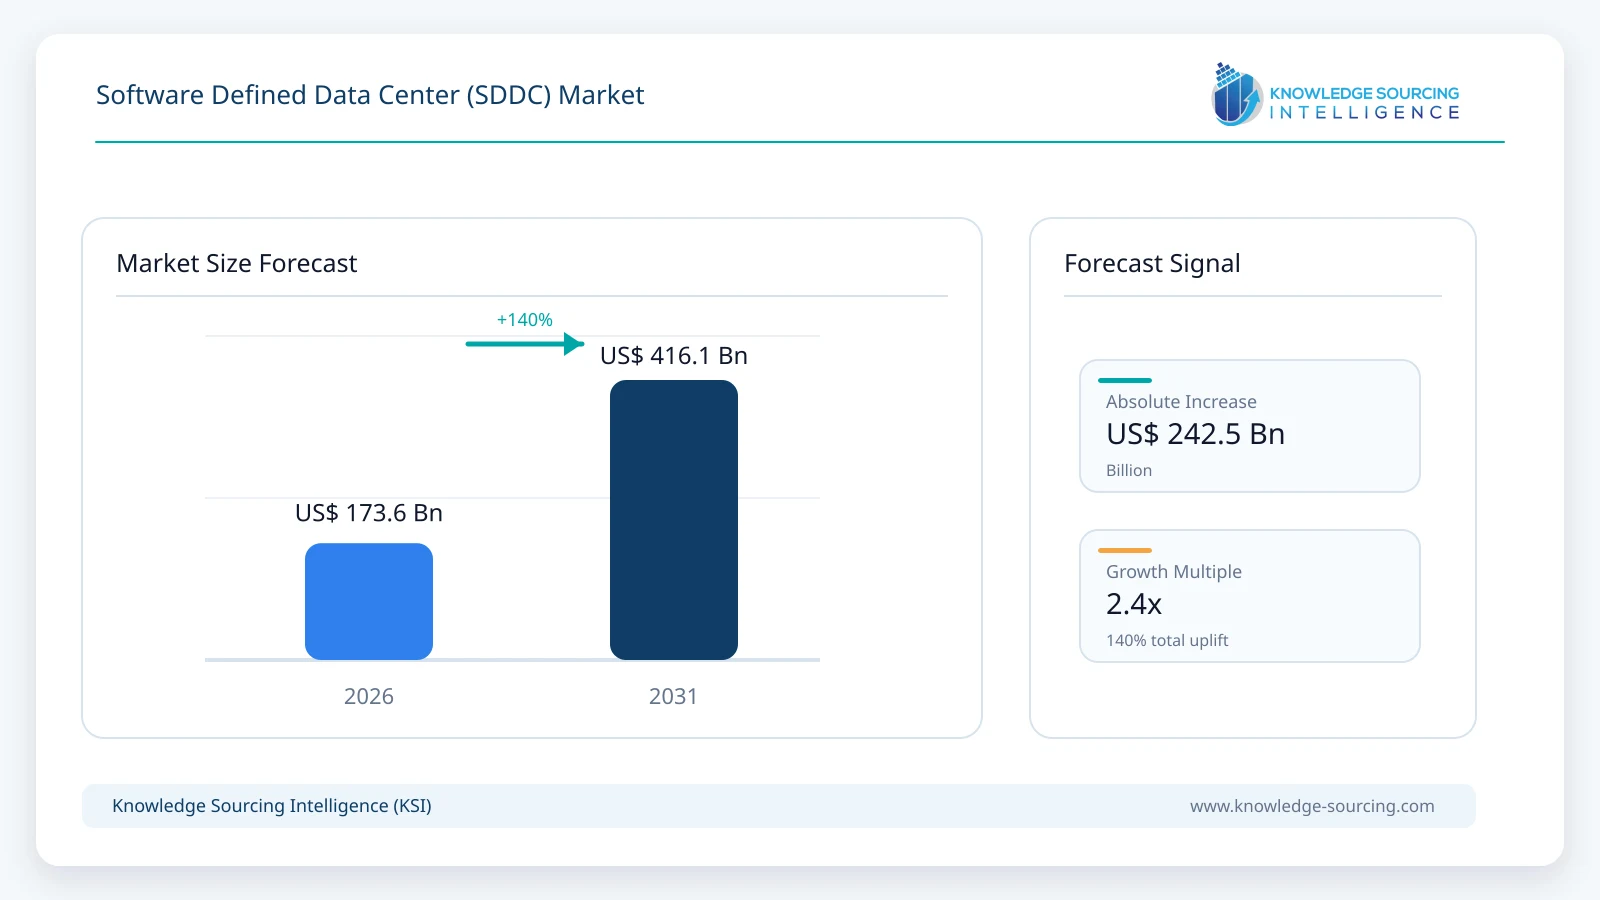
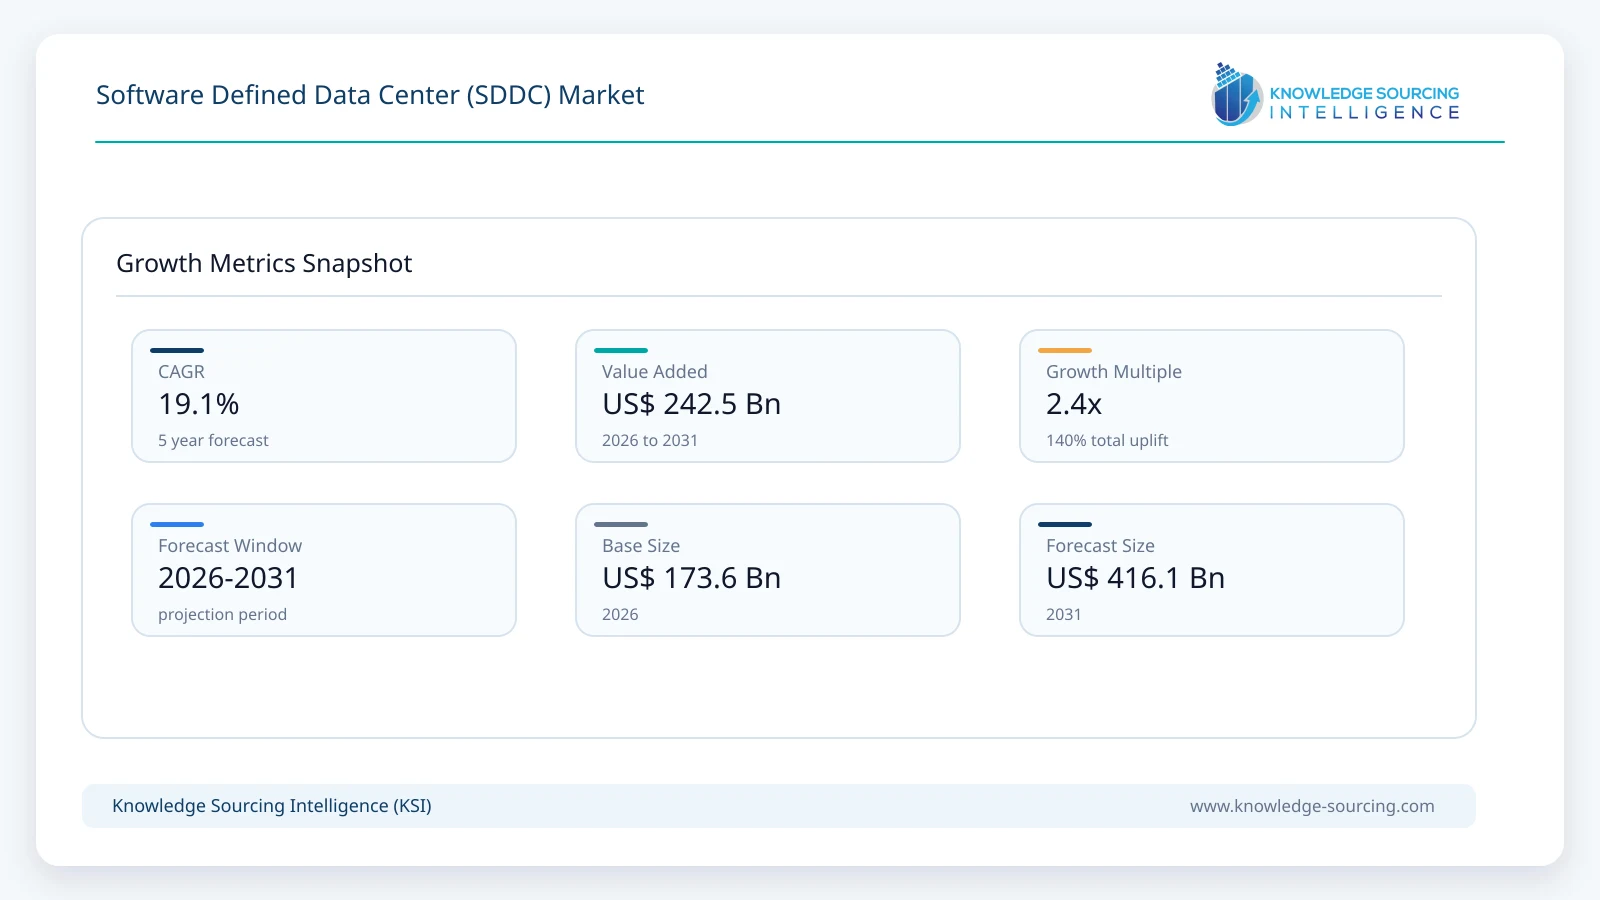
The Software-Defined Data Center (SDDC) market is forecast to grow at a CAGR of 19.11%, reaching USD 416.10 billion in 2031 from USD 173.56 billion in 2026.
Highlights:
- 1Rising enterprise adoption of hybrid cloud infrastructure remains the primary demand catalyst for Software Defined Data Center deployments.
- 2Software-Defined Network (SDN) solutions continue to represent a commercially important technology segment due to increasing network automation requirements.
- 3Asia Pacific presents substantial investment opportunities supported by hyperscale data center expansion and enterprise cloud adoption.
- 4AI-assisted infrastructure management and policy-driven automation are reshaping data center operations and procurement priorities.
- 5Cybersecurity regulations and data governance requirements are increasing demand for centrally managed software-defined infrastructure.
- 6Competition is shifting toward integrated platforms combining virtualization, orchestration, cybersecurity, and cloud management capabilities.
The Software Defined Data Center (SDDC) market represents the transition from hardware-centric data center architecture to an environment where compute, storage, networking, and management resources are abstracted, virtualized, and centrally controlled through software. An SDDC integrates software-defined compute (SDC), software-defined networking (SDN), software-defined storage (SDS), automation platforms, and orchestration tools to create highly adaptable infrastructure capable of supporting modern enterprise workloads. The approach enables organizations to allocate resources dynamically, improve infrastructure utilization, simplify operations, and reduce manual intervention across physical and hybrid environments.
Demand for SDDC solutions is being shaped by enterprise modernization initiatives, the expansion of hybrid and multi-cloud deployments, and increasing investment in artificial intelligence (AI), analytics, and containerized applications. Organizations are no longer purchasing infrastructure solely to expand computing capacity; procurement decisions increasingly prioritize operational flexibility, application portability, security, and automation. Enterprises seek infrastructure capable of supporting continuously changing business requirements without extensive hardware replacement cycles, making software-defined architectures an attractive investment.
Cloud service providers remain among the largest buyers of SDDC technologies because software-driven infrastructure enables efficient provisioning across geographically distributed data centers while reducing operational complexity. Colocation providers are also deploying software-defined capabilities to differentiate service offerings, improve tenant management, and increase infrastructure utilization. Large enterprises across banking, telecommunications, healthcare, manufacturing, retail, and government sectors continue replacing legacy infrastructure with programmable environments that support business continuity and application scalability.
Industry economics further support adoption. Organizations are seeking to optimize capital expenditure by extending hardware lifecycles while improving resource efficiency through virtualization and automation. Instead of deploying dedicated infrastructure for individual workloads, enterprises increasingly rely on pooled computing resources managed through centralized software platforms. This operating model supports faster deployment cycles and lower administrative overhead.
Technology suppliers compete by offering integrated infrastructure platforms combining virtualization software, automation capabilities, cybersecurity, cloud management, and AI-enabled monitoring. Compatibility with public cloud environments, open APIs, container orchestration platforms, and cybersecurity frameworks has become an important purchasing criterion. Buyers increasingly evaluate vendors based on interoperability, lifecycle management capabilities, operational visibility, and total cost of ownership rather than hardware performance alone.
Market Drivers
Growing Hybrid and Multi-Cloud Infrastructure Adoption
Organizations increasingly operate workloads across private infrastructure, public cloud platforms, and edge environments. Managing these heterogeneous environments through conventional hardware-centric architectures creates operational inefficiencies and inconsistent resource allocation. SDDC platforms provide centralized policy management, workload mobility, and unified orchestration across multiple environments.
Large enterprises are investing in infrastructure capable of supporting business continuity while maintaining flexibility in application deployment. Vendors continue expanding cloud integration capabilities, enabling customers to manage virtualized resources regardless of deployment location. This trend strengthens recurring software licensing and subscription revenue opportunities.
Rising Demand for Infrastructure Automation
Data center operations have become considerably more complex due to virtualization, containerized applications, AI workloads, and distributed computing environments. Manual configuration introduces operational delays and increases the likelihood of configuration errors.
Organizations therefore prioritize infrastructure automation, policy-based provisioning, and intelligent workload management. Suppliers respond by incorporating AI-enabled monitoring, automated resource optimization, predictive maintenance, and lifecycle management into SDDC platforms. These capabilities reduce administrative costs while improving infrastructure availability.
Expansion of AI and High-Performance Computing Workloads
Artificial intelligence training, inference, advanced analytics, and scientific computing require infrastructure capable of allocating compute, networking, and storage resources dynamically. Traditional architectures often struggle to maintain utilization efficiency across changing workload demands.
Software-defined infrastructure enables resource pools to be adjusted according to workload requirements, improving utilization without requiring proportional hardware expansion. Enterprises investing in AI initiatives increasingly include software-defined management capabilities within broader infrastructure procurement strategies.
Increasing Enterprise Cybersecurity Requirements
Cybersecurity has become a major purchasing consideration for infrastructure modernization. Organizations require centralized visibility, policy enforcement, workload isolation, and automated compliance management across distributed infrastructure.
Software-defined networking and virtualization platforms support network segmentation, zero-trust architecture implementation, automated security policy deployment, and continuous monitoring. These capabilities strengthen infrastructure resilience while helping organizations comply with industry regulations.
Market Restraints and Challenges
Integration Complexity with Legacy Infrastructure
Many enterprises continue operating legacy applications that depend on traditional hardware configurations. Migrating these environments into software-defined architectures often requires substantial planning, application redesign, and compatibility testing.
Large-scale migration projects increase implementation timelines and consulting expenses, particularly for organizations operating mission-critical workloads. Vendors increasingly offer migration assessment services and phased deployment strategies to reduce implementation risk.
Skills Shortage Across Infrastructure Automation
Successful SDDC deployment requires expertise spanning virtualization, software-defined networking, cloud orchestration, cybersecurity, automation, and infrastructure programming. Many organizations face shortages of professionals capable of managing these integrated environments.
The resulting dependence on external implementation partners increases deployment costs and extends project schedules. Vendors continue expanding certification programs and managed service offerings to address workforce limitations.
Cybersecurity Risks Associated with Centralized Management
Although software-defined infrastructure strengthens security management, centralized orchestration platforms become attractive targets for cyberattacks. Misconfigured automation policies or compromised administrative credentials can affect multiple infrastructure components simultaneously.
Organizations therefore invest heavily in privileged access management, encryption, continuous monitoring, and security validation. Suppliers continue enhancing platform security through identity management integration and automated compliance verification.
Vendor Lock-In Concerns
Organizations increasingly seek infrastructure flexibility that supports evolving business requirements. Some proprietary software ecosystems limit interoperability between hardware platforms or cloud providers, creating concerns regarding long-term procurement flexibility.
Enterprise buyers increasingly evaluate vendors based on open standards support, API compatibility, container integration, and workload portability before making infrastructure investment decisions.
Major Segment Analysis
Software-Defined Network (SDN)
Software-Defined Network solutions represent one of the most commercially important components within the Software Defined Data Center market because networking increasingly determines infrastructure agility, workload mobility, and security effectiveness. As enterprises expand hybrid cloud operations, conventional network management methods struggle to support dynamic application deployment and distributed computing environments.
Enterprise buyers prioritize SDN solutions capable of automating network configuration, enforcing centralized security policies, improving traffic visibility, and supporting application-aware networking. Telecommunications operators, cloud providers, financial institutions, and large multinational enterprises remain among the leading adopters due to their complex networking requirements.
Competition within this segment extends beyond networking performance. Vendors differentiate through automation capabilities, cybersecurity integration, interoperability with cloud platforms, programmable interfaces, and support for containerized applications. Integration with AI-enabled traffic optimization and policy-driven network orchestration further strengthens commercial value.
Revenue opportunities continue expanding as organizations modernize existing data centers while constructing new facilities capable of supporting AI workloads, edge computing, and multi-cloud connectivity.
Regional Analysis
North America
North America remains a leading market due to high enterprise cloud adoption, substantial hyperscale data center investment, and early deployment of virtualization technologies. Large technology companies, financial institutions, healthcare providers, and government agencies continue modernizing infrastructure to improve operational efficiency. Strict cybersecurity requirements further support demand for centralized infrastructure management.
Europe
European adoption is supported by enterprise modernization initiatives, sustainability objectives, and regulatory requirements governing cybersecurity and data protection. Organizations prioritize infrastructure capable of supporting operational resilience while maintaining compliance with regional regulations. Investment continues across financial services, manufacturing, telecommunications, and public administration sectors.
Asia Pacific
Asia Pacific represents one of the fastest-expanding regional markets due to rapid cloud adoption, expanding digital economies, government-supported data center investment, and increasing enterprise IT expenditure. China, Japan, India, South Korea, Taiwan, and Southeast Asian economies continue expanding hyperscale infrastructure while enterprises accelerate modernization projects to support AI, e-commerce, and digital services.
Middle East and Africa
The region is witnessing increased investment in cloud infrastructure, smart city initiatives, telecommunications modernization, and government digital programs. Gulf countries continue supporting domestic data center expansion through national technology strategies, while enterprises seek infrastructure capable of supporting secure digital services and public sector modernization.
South America
Brazil leads regional adoption through financial services modernization, telecommunications investment, and enterprise cloud migration. Organizations continue replacing legacy infrastructure to improve operational efficiency despite budget constraints and varying economic conditions. Regional adoption remains influenced by infrastructure availability, skilled workforce development, and enterprise investment priorities.
Competitive Landscape
The Software Defined Data Center market exhibits competition among diversified enterprise infrastructure providers, virtualization software developers, networking specialists, and cloud platform vendors. Hewlett Packard Enterprise Development LP, Dell Technologies Inc., Cisco Systems, Inc., Oracle Corporation, IBM Corporation, Fujitsu Limited, Arista Networks, Inc., VMware LLC (Broadcom Inc.), Nutanix, Inc., Microsoft Corporation, and DataDirect Networks (DDN) compete through integrated infrastructure portfolios rather than standalone products.
Competition emphasizes platform interoperability, hybrid cloud integration, cybersecurity capabilities, infrastructure automation, AI-enabled operations, and lifecycle management. Strategic partnerships with cloud providers, systems integrators, semiconductor manufacturers, and enterprise software vendors strengthen ecosystem compatibility. Geographic expansion, subscription-based software models, and managed infrastructure services continue influencing competitive positioning as customers increasingly seek long-term technology partners rather than individual hardware suppliers.
Recent Developments
April 2026: Nutanix and NetApp announced a strategic alliance to integrate NetApp Intelligent Data Infrastructure with the Nutanix Cloud Platform, providing customers with simplified virtualization modernization, faster VM migration, and flexible software-defined infrastructure across on-premises and cloud environments.
February 2026: Cisco launched new AI infrastructure innovations, including Cisco Silicon One G300, AgenticOps enhancements, and expanded AI networking and security capabilities, strengthening software-defined data center infrastructure for large-scale AI and enterprise cloud deployments.
January 2026: Cisco, Pure Storage, and Nutanix announced the general availability of FlashStack with Nutanix, delivering a jointly validated converged infrastructure platform that simplifies deployment of software-defined data center environments with integrated compute, storage, and virtualization capabilities.
Regulatory and Policy Environment
The Software Defined Data Center market operates within an increasingly complex regulatory framework covering cybersecurity, data protection, operational resilience, and digital infrastructure security. Regulations including the European Union's NIS2 Directive, General Data Protection Regulation (GDPR), the Digital Operational Resilience Act (DORA), and national cybersecurity frameworks encourage organizations to strengthen infrastructure governance and operational visibility.
Government cloud adoption initiatives, national digital infrastructure programs, and cybersecurity strategies continue supporting investment in modern data center technologies. Compliance requirements increasingly emphasize workload monitoring, identity management, encryption, auditability, disaster recovery, and infrastructure resilience.
Industry standards developed by organizations including ISO, the National Institute of Standards and Technology (NIST), and the Cloud Security Alliance influence procurement specifications by defining security, risk management, and operational best practices. Vendors increasingly incorporate compliance automation and reporting capabilities within software-defined management platforms to simplify regulatory adherence.
Outlook and Strategic Implications
Demand for Software Defined Data Center solutions is expected to remain supported by enterprise infrastructure modernization, AI deployment, hybrid cloud expansion, and cybersecurity investment. Organizations will increasingly prioritize software-driven infrastructure capable of adapting to changing workload requirements while maintaining operational efficiency and regulatory compliance.
Procurement decisions are expected to emphasize integrated platforms offering virtualization, networking, storage management, automation, AI-enabled operations, and security within unified environments. Buyers will continue evaluating suppliers based on interoperability, lifecycle management, subscription flexibility, and cloud compatibility rather than isolated infrastructure performance.
Investment priorities are expected to include autonomous infrastructure operations, predictive resource optimization, container-native networking, and edge computing integration. Technology suppliers capable of combining software innovation with comprehensive infrastructure ecosystems and global service capabilities are likely to strengthen their competitive position.
At the same time, implementation complexity, cybersecurity risks, workforce shortages, and interoperability challenges will continue influencing purchasing decisions. Organizations that balance modernization objectives with phased deployment strategies, governance frameworks, and workforce development are expected to achieve stronger operational outcomes while maximizing long-term infrastructure value.
Software Defined Data Center (SDDC) Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 173.56 billion |
| Total Market Size in 2031 | USD 416.10 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.11% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution, End-User, Geography |
| Companies |
|
Market Segmentation
By Solution
- Software-Defined Compute (SDC)
- Software-Defined Network (SDN)
- Software-Defined Storage (SDS)
- Data Center Management and Automation
- Others
By End-User
- Cloud Service Providers
- Colocation Providers
- Enterprises
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- Germany
- France
- United Kingdom
- Spain
- Others
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Israel
- Others
- Asia Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Thailand
- Indonesia
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. SOFTWARE-DEFINED DATA CENTER (SDDC) MARKET BY SOLUTION
5.1. Introduction
5.2. Software-Defined Compute (SDC)
5.3. Software-Defined Network (SDN)
5.4. Software-Defined Storage (SDS)
5.5. Data Center Management and Automation
5.6. Others
6. SOFTWARE-DEFINED DATA CENTER (SDDC) MARKET BY END-USER
6.1. Introduction
6.2. Cloud Service Providers
6.3. Colocation Providers
6.4. Enterprises
7. SOFTWARE-DEFINED DATA CENTER (SDDC) MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Solution
7.2.2. By End-User
7.2.3. By Country
7.2.3.1. United States
7.2.3.2. Canada
7.2.3.3. Mexico
7.3. South America
7.3.1. By Solution
7.3.2. By End-User
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.2. Argentina
7.3.3.3. Others
7.4. Europe
7.4.1. By Solution
7.4.2. By End-User
7.4.3. By Country
7.4.3.1. Germany
7.4.3.2. France
7.4.3.3. United Kingdom
7.4.3.4. Spain
7.4.3.5. Others
7.5. Middle East and Africa
7.5.1. By Solution
7.5.2. By End-User
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.2. United Arab Emirates
7.5.3.3. Israel
7.5.3.4. Others
7.6. Asia Pacific
7.6.1. By Solution
7.6.2. By End-User
7.6.3. By Country
7.6.3.1. China
7.6.3.2. Japan
7.6.3.3. India
7.6.3.4. South Korea
7.6.3.5. Taiwan
7.6.3.6. Thailand
7.6.3.7. Indonesia
7.6.3.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Hewlett Packard Enterprise Development LP
9.2. Dell Technologies Inc.
9.3. Cisco Systems, Inc.
9.4. Oracle Corporation
9.5. IBM Corporation
9.6. Fujitsu Limited
9.7. Arista Networks, Inc.
9.8. VMware LLC (Broadcom Inc.)
9.9. Nutanix, Inc.
9.10. Microsoft Corporation
9.11. DataDirect Networks (DDN)
Navigate
Trusted by the world's leading organizations











