
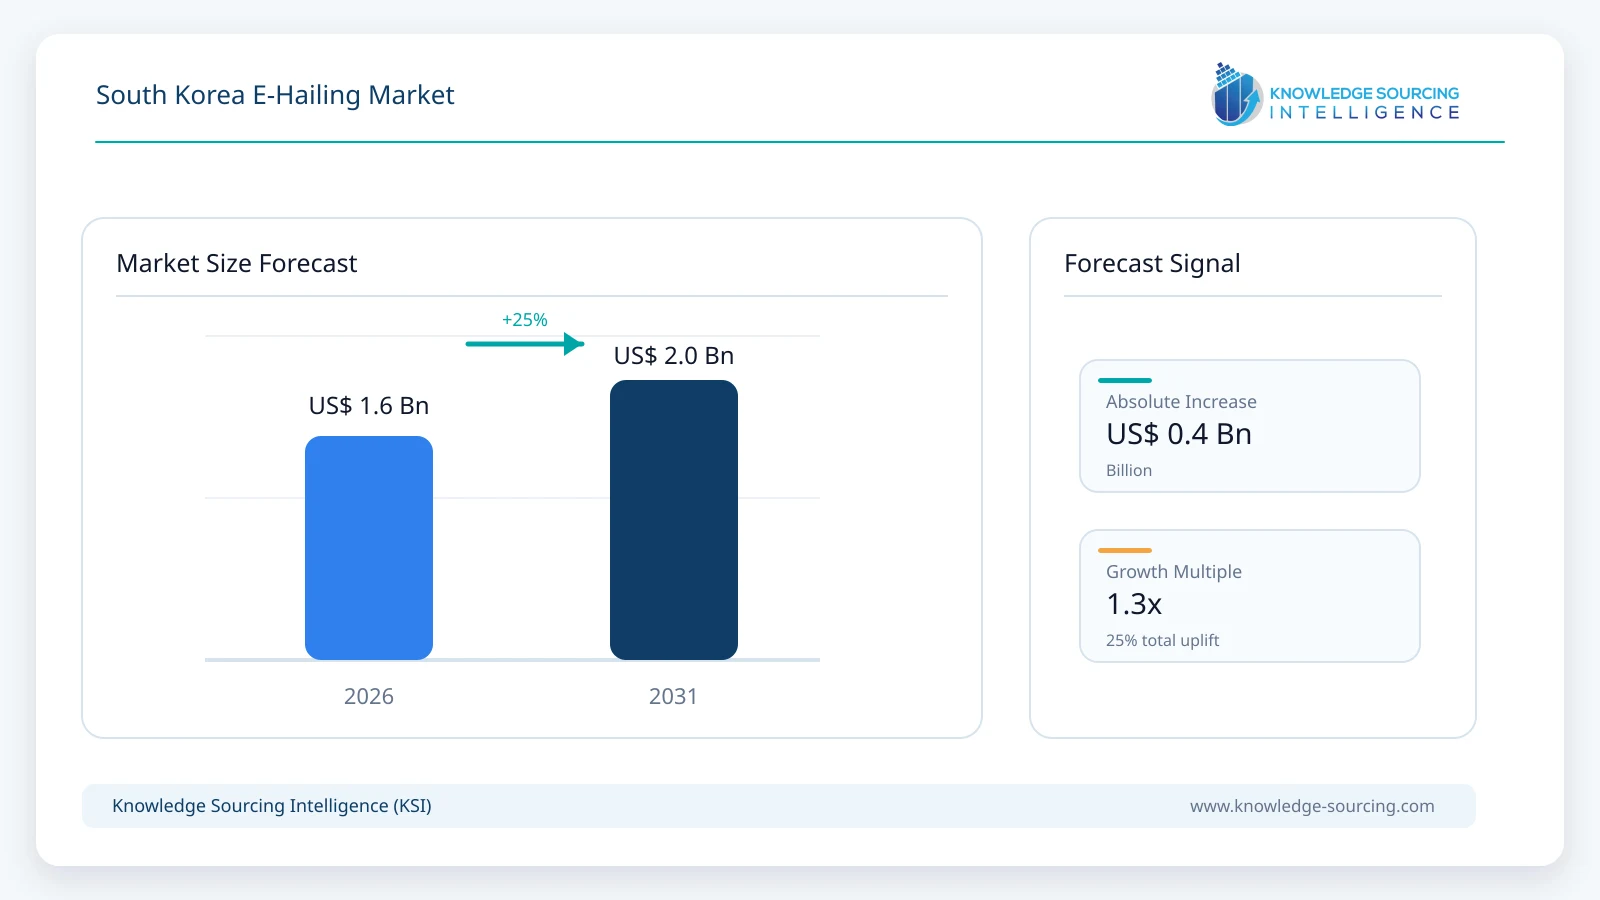
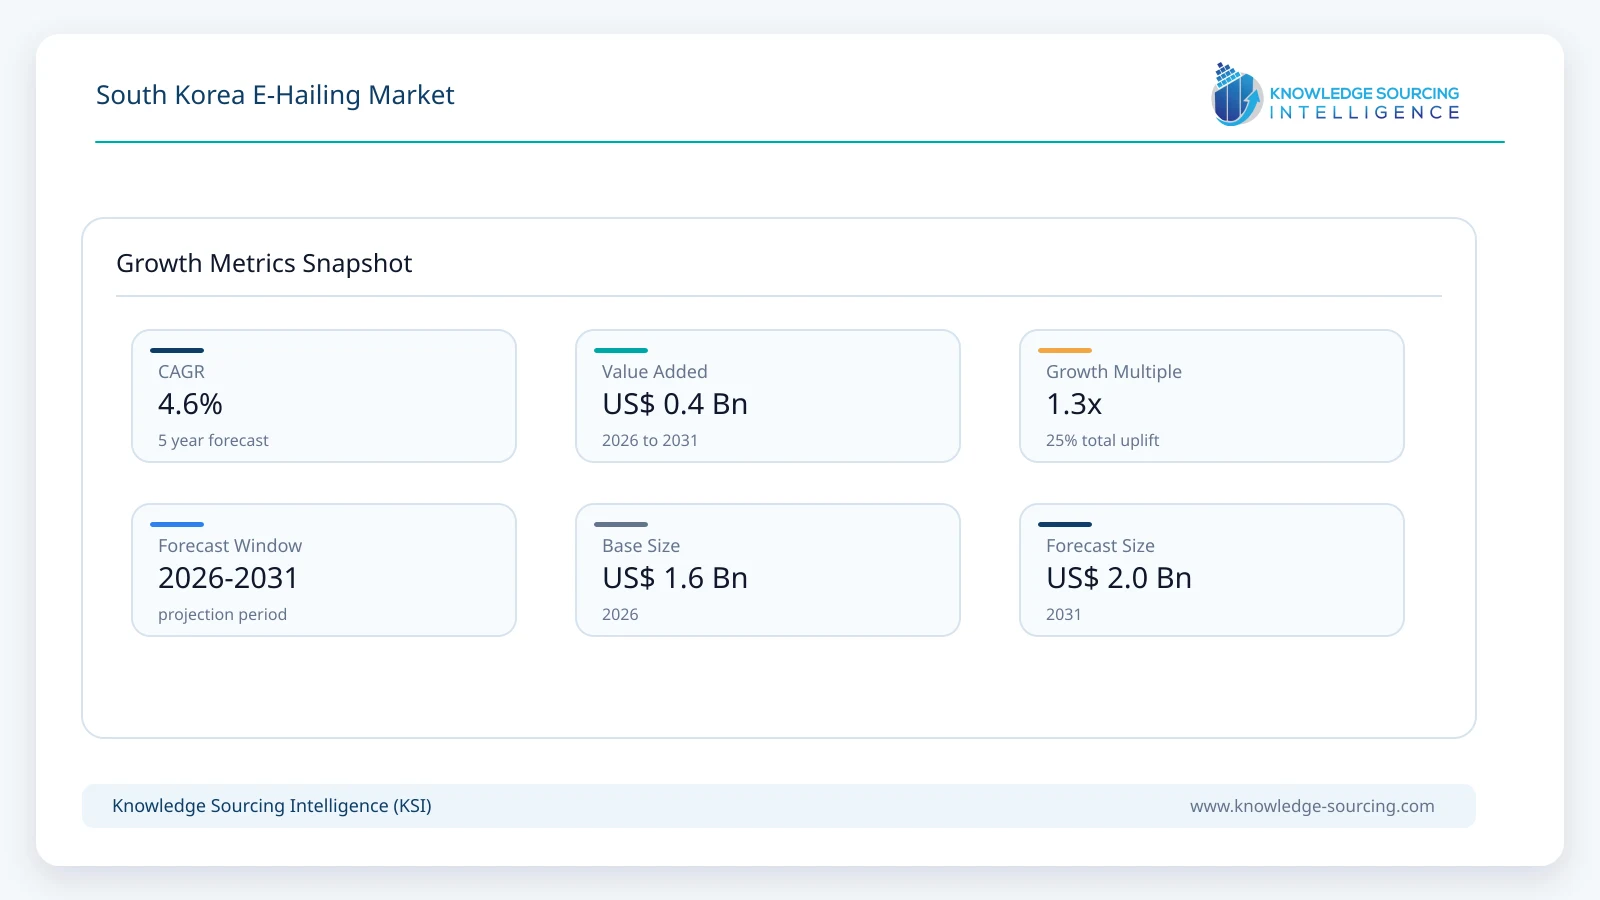
The South Korean E-Hailing market is forecast to grow at a CAGR of 4.6%, reaching USD 2.00 billion in 2031 from USD 1.60 billion in 2026.
Highlights:
- 1On-Demand/Immediate Ride accounts for approximately 82% of market value in 2026, while Pre-booked/Reserved Ride increases its contribution through 2031 as airport, business and premium travel expand.
- 2Mobile App-Based Booking represents approximately 95% of market value in 2026 and remains the principal interface for taxi discovery, dispatch, payment and service selection.
- 3Standard Taxi accounts for approximately 79% of vehicle-class market value in 2026, while Premium/Deluxe, Van/Minivan, Luxury and Autonomous Taxi services gain share through the forecast period.
- 4Individual Consumers account for approximately 82% of market value in 2026, while Corporate Customers grow faster as digital billing, reservations and centralized travel management become more common.
- 5Seoul remains the largest regional market, with Gyeonggi providing the second-largest demand base and Incheon benefiting from airport-related travel.
- 6Kakao T’s average taxi dispatch time reached 6.6 seconds in the first half of 2025 and its boarding success rate reached 94%, demonstrating the importance of platform density and matching efficiency.
- 7Seoul expanded its paid late-night autonomous taxi fleet to 19 vehicles in August 2026, providing an early commercial test of autonomous vehicles within an established ride-hailing platform.
The market is developing primarily through deeper digital integration of South Korea’s established taxi industry rather than through rapid expansion of privately operated ride-sharing vehicles. Mobile platforms increasingly manage taxi discovery, dispatch, estimated arrival times, payments and service selection, while differentiated products such as larger vehicles, premium taxis, advance reservations, corporate mobility and services for international travellers increase the value generated from the same underlying licensed taxi supply. Kakao Mobility reported that average Kakao T taxi dispatch time had declined to 6.6 seconds in the first half of 2025, while the proportion of taxi calls resulting in a completed boarding reached 94%. Automatic payment accounted for 74% of completed Kakao T taxi trips, indicating that digital platforms are increasingly controlling the complete transaction rather than functioning only as a vehicle-search tool.
On-demand and immediate bookings continue to provide the largest share of market activity, accounting for an estimated 82% of market value in 2026, but reserved rides are expected to grow faster through 2031. The change reflects the expansion of airport transfers, business travel, premium vehicles and planned journeys where customers value guaranteed pickup and greater vehicle choice. Kakao T provides reservations for Venti and Black services, while TADA combines real-time dispatch with advance reservations for business, travel, events and other planned journeys. Uber Taxi has similarly expanded the range of services available beyond conventional midsize taxis, including faster-dispatch, electric and premium options.
The booking interface remains overwhelmingly mobile. Mobile App-Based Booking represents an estimated 95% of digitally mediated taxi market value in 2026 and is projected to increase further through the forecast period as location data, automatic payment, ride tracking and vehicle selection become more deeply integrated. At the same time, the market is developing alternative access routes for customers who are less comfortable using smartphone applications. Kakao Mobility’s 02-114 assisted taxi service allows passengers to request a Kakao T taxi by telephone through an operator and had expanded to daily nationwide coverage by August 2026. The coexistence of advanced app-based services and assisted calling shows that digitalisation is broadening the taxi market without requiring every user to interact with the technology in the same way.
Technology is also beginning to change the vehicle layer. Seoul’s Gangnam late-night autonomous taxi programme transitioned from free testing to paid operation in April 2026 after recording 7,754 rides during approximately 17 months of pilot operations. The fleet subsequently expanded to 19 vehicles in August, while cumulative rides reached 15,140 by July 31, including 6,176 trips after paid operation began. Autonomous taxis remain a very small part of the total market, but their integration directly into Kakao T creates a commercially relevant pathway from conventional digital taxi dispatch toward automated mobility.
Market Growth Drivers and Trends
Higher Dispatch Efficiency Is Strengthening App-Based Taxi Usage
The principal driver of South Korea’s e-hailing market is the improvement in reliability achieved when a large taxi fleet and passenger base are coordinated through a digital platform. Customers are more likely to use a taxi application repeatedly when estimated waiting times are short and a high proportion of requests result in an actual vehicle assignment. Kakao Mobility’s 2025 data show the extent to which dispatch performance has improved: average assignment time declined from 19.87 seconds when the service launched in 2015 to 6.6 seconds in the first half of 2025, while the boarding success rate increased from 77% to 94%. The company’s automatic-dispatch franchise model also records stronger assignment performance for short-distance trips and destinations that taxi drivers have historically been less willing to serve.
The commercial effect extends beyond convenience. Better matching reduces empty vehicle movement, increases driver utilisation and makes the platform more useful during periods when passengers would otherwise attempt to hail taxis from the street. These network effects are difficult for smaller platforms to replicate because service quality depends simultaneously on passenger demand, driver participation and matching technology. Market growth through 2031 is therefore expected to come partly from a larger proportion of conventional taxi journeys being captured digitally rather than from equivalent growth in the underlying number of taxi trips.
Differentiated Taxi Services Are Increasing Revenue per Journey
South Korean e-hailing platforms increasingly offer several vehicle and service levels instead of a single standard taxi product. Kakao Mobility provides conventional midsize taxis alongside Venti large-vehicle and Black premium services, while Uber Taxi offers Standard Taxi, Speed Call, Green electric vehicles and Deluxe Taxi. Seoul’s regulated taxi system also recognizes different fare structures for standard, premium and branded vehicles, including Kakao Venti and i.M.
The resulting product differentiation allows operators to address different willingness-to-pay levels without relying solely on higher standard taxi fares. Customers travelling in groups or with luggage can choose larger vehicles, business travellers can reserve premium rides, and passengers needing faster assignment can select paid priority-dispatch products. The forecast therefore assumes that Standard Taxi remains dominant but gradually loses share to Premium/Deluxe Taxi, Van/Minivan and Luxury Taxi services. This shift increases market value even where underlying passenger-trip growth remains moderate.
Tourism and International Travel Are Expanding the Addressable User Base
International travellers have different requirements from domestic passengers because they may not have a Korean mobile number, may be unfamiliar with local destinations and can face language or payment barriers. Digital taxi services reduce these frictions by providing destination search, fare estimates, translated communication and foreign payment support before the passenger enters the vehicle. Seoul’s transportation guidance specifically identifies app-based taxi booking as useful for international visitors because users can confirm the expected fare and destination in advance.
Kakao Mobility’s k.ride extends this model specifically to overseas travellers. The service supports English, Japanese and Chinese interfaces, destination search and automatic translation across 133 languages, international card and mobile payments and Standard, Comfort, Deluxe and Luxury vehicle classes. Incheon benefits particularly from airport-related mobility, while Seoul, Busan and Jeju combine tourism with business and leisure travel. International passenger demand also supports reserved rides and larger vehicles because airport journeys frequently involve luggage, groups and predetermined travel times.
Corporate Mobility Is Becoming More Structured
Business travel represents a smaller demand pool than personal mobility but generates attractive transaction characteristics because journeys are more likely to include airports, business districts, premium vehicles and scheduled pickups. Digital platforms also simplify corporate administration by replacing individual paper receipts with centralized payment and electronic trip records. Kakao T Business allows companies to set employee groups, spending limits and usage conditions, and can automatically transfer trip information into corporate management systems. Business customers can request multiple taxis, reserve vehicles and choose between midsize, premium and large-capacity services without requiring employees to install a separate application.
Corporate Customers account for an estimated 13% of market value in 2026 and are projected to reach approximately 15% by 2031. The increase remains moderate because individual consumers continue to account for most taxi journeys, but the segment grows faster as digital mobility becomes more closely integrated with expense management, employee travel policies and centralized corporate payment.
Autonomous Mobility Is Progressing from Trial to Paid Service
Autonomous taxis represent the most technologically significant development in the market even though current commercial volumes remain small. Seoul began operating the Gangnam late-night autonomous taxi programme in September 2024 and converted it to paid service on April 6, 2026. By February 2026, the service had completed 7,754 rides, and Seoul expanded the fleet from three to seven active vehicles before commercial operation began.
Expansion accelerated during the second half of 2026. Kakao Mobility increased the number of its own Seoul autonomous vehicles from two to six in August and extended operation into traffic-vulnerable protection zones, while the broader Gangnam late-night fleet expanded to 19 vehicles. Passengers continue to request autonomous taxis through Kakao T using the same booking process as conventional taxis, which reduces the need for operators to build a separate customer-acquisition platform. Kakao Mobility and Kia are also collaborating on dedicated autonomous-service vehicles, with vehicle supply for pilot programmes planned during 2026 and longer-term development of purpose-built autonomous mobility vehicles.
Market Restraints
Regulated Fare Structures Limit Pricing Flexibility
South Korea’s taxi platform market operates within a regulated passenger-transport framework, which limits the ability of platforms to use unrestricted dynamic pricing. Seoul’s standard midsize taxi fare remains based on a regulated structure, with a daytime base fare of KRW 4,800 for the first 1.6 kilometres and defined distance, time, late-night and out-of-city surcharges. Premium and branded taxi categories can operate different fare structures, but these are still governed within the regulatory framework.
This means that platform operators cannot rely on fare increases as the primary mechanism for improving economics during peak demand. Revenue growth instead depends more heavily on increasing ride volume, securing sufficient driver supply, introducing premium products and developing ancillary services.
Driver Availability Can Restrict Platform Fulfilment
Digital matching improves the use of existing taxi supply but does not create additional drivers when demand exceeds available capacity. Late-night periods, major events, adverse weather and journeys to less-preferred destinations can still produce longer waiting times or lower assignment rates. Smaller platforms face a greater challenge because limited network density reduces the probability that a suitable driver will be close to the passenger.
Kakao Mobility’s emphasis on automated allocation and its franchise-taxi structure reflects the importance of controlling this constraint. The company’s data show that automatically dispatched franchise vehicles achieved higher assignment success for short-distance and less-preferred destinations than the broader taxi pool. Autonomous vehicles could eventually provide supplementary supply, but the current fleet remains too small to materially alter national driver availability during the forecast period.
Strong Public Transportation Limits Taxi Substitution
South Korea’s extensive metro, rail and bus networks provide a strong alternative to taxi travel for routine commuting and high-volume urban movement. E-hailing therefore does not address the same structural transportation gap that drove extremely rapid ride-hailing penetration in cities with less developed public transport.
The market is better positioned for journeys where direct point-to-point mobility provides a clear advantage, including late-night trips, airport transfers, luggage-heavy travel, corporate journeys, groups, premium travel and areas where public transport requires multiple connections. This keeps the overall market growth rate moderate even as the digital share of taxi booking continues to increase.
Regulatory Approval Can Slow New Operating Models
South Korea’s Passenger Transport Service Act distinguishes between platform transportation businesses, platform franchise businesses and platform brokerage businesses. Platform transportation businesses require authorization, while platform franchise businesses require licensing and approved business plans. The framework provides regulatory clarity but also means that new operating models cannot be introduced solely through software development.
The constraint becomes particularly important for autonomous mobility, new vehicle categories and services that alter the relationship between platforms and existing taxi operators. Seoul has repeatedly emphasized consultation with the taxi industry while expanding its autonomous taxi programme, indicating that commercial deployment will remain gradual rather than being determined by technology readiness alone.
Digital Access Is Not Universal Across Passenger Groups
Mobile applications dominate e-hailing transactions, but reliance on app-based booking can exclude passengers who are less comfortable with smartphones. The issue is particularly relevant among older passengers and users who require assistance entering destinations or managing digital payment.
Platform companies and municipal transport providers are therefore developing assisted alternatives. Kakao Mobility’s 02-114 service allows passengers to call an operator who then books a Kakao T taxi on their behalf. By August 2026 the service was operating nationwide every day between 8 a.m. and 7 p.m., demonstrating that digital dispatch can expand without requiring the passenger to use an application directly. Tmoney Mobility has developed a similar combination of telephone and app-based taxi access through regional integrated-call services.
South Korea E-Hailing Market by Service Type
On-Demand/Immediate Ride accounts for approximately USD 1.31 billion, or 82% of market value, in 2026. The segment reflects the dominant consumer use case in which passengers request the nearest available taxi for immediate travel. Increasing dispatch efficiency, automatic payment and location-based pickup improve the attractiveness of this model, while the large existing licensed-taxi fleet provides the physical supply required to support short response times.
Pre-booked/Reserved Ride represents approximately 15% of market value in 2026 and is projected to increase to around 18% by 2031. Airport transfers, corporate journeys, premium taxi use, group travel and important scheduled events support faster growth because customers value guaranteed vehicle availability more highly than they do for routine urban journeys. Kakao T supports reservations for premium and larger vehicle services, while TADA explicitly positions advance booking around travel, business, weddings, golf and other planned journeys.
Other e-hailing services account for approximately 3% of market value and include specialized or emerging services that do not fit directly within immediate or reserved taxi travel.
South Korea E-Hailing Market by Booking Mode
Mobile App-Based Booking accounts for approximately 95% of market value in 2026 and is projected to increase toward 97% by 2031. GPS location, destination search, real-time vehicle tracking, automatic payment, vehicle selection and trip records are most easily integrated through smartphones, making the mobile application the natural interface for frequent e-hailing users.
Web-Based Booking accounts for approximately 2% of market value, with usage concentrated around specialized reservation and travel services. Assisted and Other Digital Booking Channels account for the remaining approximately 3%. These channels remain commercially important despite their smaller share because telephone-assisted services extend digital taxi dispatch to passengers who do not use smartphone applications independently.
South Korea E-Hailing Market by Vehicle Class
Standard Taxi accounts for approximately 79% of market value in 2026 and remains the largest vehicle category through 2031. The segment provides the widest vehicle availability and addresses routine personal, commuting and short-distance journeys where customers prioritize fast dispatch and predictable fares over vehicle differentiation.
Premium/Deluxe Taxi accounts for approximately 9%, while Van/Minivan represents around 6%. Both categories are projected to gain share as platforms increase airport, group, family and corporate travel. Luxury Taxi represents approximately 2–3% and remains concentrated in high-value business, VIP and tourism applications. Kakao’s k.ride and domestic platform services already allow customers to choose between standard, larger-capacity and premium vehicle categories.
Autonomous Taxi contributes less than 1% of market value in 2026 but records the fastest percentage growth through 2031. Its share remains limited by fleet size, regulation and operating zones, but paid deployment in Gangnam creates a commercial base from which larger services can develop.
South Korea E-Hailing Market by End-User
Individual Consumers account for approximately 82% of market value in 2026 and remain the dominant end-user group. Personal trips include commuting, social travel, late-night journeys, shopping, tourism and airport transport, creating a high-frequency transaction base across large urban areas.
Corporate Customers account for approximately 13% in 2026 and increase toward 15% by 2031 as centralized billing, reservations, premium taxi use and employee travel management expand. Government/Public Sector users represent approximately 3%, while other users account for the remaining market.
Geographical Outlook
Seoul accounts for approximately 38% of South Korea’s e-hailing market value in 2026, making it the largest regional market. Dense passenger demand, business activity, tourism, premium taxi availability and the concentration of autonomous mobility trials allow platforms to maintain high vehicle utilization and introduce differentiated services at meaningful scale. Seoul also provides the country’s most developed premium taxi environment, with separate structures for conventional, deluxe, large-vehicle and branded taxi services.
Gyeonggi accounts for approximately 26% and represents the second-largest market. Its substantial population and extensive commuter relationship with Seoul generate high cross-boundary travel demand, although lower density across some areas makes vehicle positioning more difficult than in central Seoul. Incheon represents approximately 9%, with Incheon International Airport increasing the contribution of reserved, premium and larger-capacity rides.
Busan accounts for approximately 8%, supported by tourism, business travel and its large urban population. Daegu, Daejeon and Gwangju collectively represent around 10%, while Jeju accounts for approximately 4%. Jeju has a relatively small resident population but gains disproportionate e-hailing opportunity from tourism, airport transfers and planned travel. Other regions account for the remaining market and gradually increase their digital booking penetration as national platform coverage broadens.
Recent Developments
August 2026, Seoul expanded its Gangnam late-night autonomous taxi fleet from seven to 19 vehicles. The service had completed 15,140 rides between September 2024 and July 31, 2026, including 6,176 journeys after paid operation began in April.
August 2026, Kakao Mobility expanded its internally developed Seoul autonomous fleet from two to six vehicles and extended operation into traffic-vulnerable protection zones. Passengers continue to access the service directly through Kakao T rather than through a separate autonomous-vehicle application.
August 2026, Kakao Mobility reported continued expansion of its 02-114 assisted taxi-booking service. The system allows passengers to call an operator who books a Kakao T taxi on their behalf and had expanded to nationwide daily operation, increasing digital dispatch access among passengers who do not independently use apps.
July 2026, Kakao Mobility and Kia announced cooperation on vehicles designed specifically for autonomous mobility services. The companies plan to integrate vehicle platforms with Kakao Mobility’s autonomous technology and operational requirements, with vehicle supply for demonstration programmes beginning during 2026.
April 2026, Seoul converted the Gangnam late-night autonomous taxi programme from free testing to paid operation following 7,754 rides during the pilot phase.
Competitive Environment
The South Korean e-hailing market is led by platforms that combine digital dispatch with access to licensed taxi supply. Kakao Mobility holds the strongest operating position through Kakao T, supported by network density, automated assignment, automatic payment, premium vehicle products, corporate mobility and integration with autonomous taxi services. Its 2025 operating data, including 6.6-second average dispatch time and a 94% boarding success rate, illustrate the scale advantage available to a platform that can aggregate both passenger demand and taxi supply.
Uber Taxi provides the principal global-platform alternative and competes through Standard Taxi, Speed Call, Green and Deluxe services as well as the familiarity of the wider Uber platform among international users. TADA remains a direct specialist competitor in Seoul, combining real-time calling and reservations with a positioning around comfort and planned mobility. i.M provides branded premium and large-vehicle taxi services with flexible fare structures, while Tmoney GO Onda combines taxi-industry participation with app and regional call-dispatch services. Tmoney’s wider position in taxi payment infrastructure also gives it direct integration with Kakao T, Uber, TADA, Onda and regional taxi applications.
Competition through 2031 is expected to depend less on basic application availability and more on dispatch success, driver participation, reserved travel, premium vehicle supply, international-user accessibility, corporate integration and autonomous mobility. Platforms with large established networks are advantaged in routine taxi dispatch, while smaller operators can remain competitive by concentrating on differentiated vehicle classes or specific travel occasions.
Analyst View
South Korea’s e-hailing market is entering a more mature stage in which growth depends less on persuading consumers to use taxi applications for the first time and more on increasing the proportion and value of taxi journeys managed through digital platforms. Kakao T’s dispatch and payment data indicate that mobile platforms have already become deeply embedded in the taxi transaction, while expansion into reservations, business travel, larger vehicles and international-user services creates additional revenue opportunities around an established transport network.
Immediate taxi hailing remains the largest service type, mobile applications account for almost all digitally mediated bookings and standard taxis continue to generate the majority of market value. The mix nevertheless becomes more diversified as reservations, corporate mobility, premium vehicles and larger-capacity taxis grow faster than the core standard service.
Autonomous taxis represent a longer-term structural opportunity rather than a major near-term revenue pool. The important development in 2026 is not the number of autonomous vehicles itself, but the transition from demonstration to paid service and their integration into the same Kakao T interface used for conventional taxis. If operating zones, regulatory approval and fleet economics improve, the existing platform infrastructure gives autonomous fleets a direct path to commercial demand. The strongest e-hailing platforms through 2031 are therefore likely to be those that combine reliable conventional taxi dispatch with higher-value services and new vehicle technologies without increasing friction for the passenger.
South Korea E-Hailing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.60 billion |
| Total Market Size in 2031 | USD 2.00 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Service Type, Booking Mode, Vehicle Class, End-User, Geography |
| Companies |
|
Market Segmentation
By Service Type
On-Demand/Immediate Ride
Pre-booked/Reserved Ride
Other E-Hailing Services
By Booking Mode
Mobile App-Based Booking
Web-Based Booking
Assisted/Other Digital Booking Channels
By Vehicle Class
Standard Taxi
Premium/Deluxe Taxi
Van/Minivan
Luxury Taxi
Autonomous Taxi
Others
By End-User
Individual Consumers (B2C)
Corporate Customers (B2B)
Government/Public Sector
Others
By Geography
Seoul
Gyeonggi
Incheon
Busan
Daegu
Daejeon
Gwangju
Jeju
Other Regions
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. SOUTH KOREA E-HAILING MARKET BY SERVICE TYPE
5.1. Introduction
5.2. On-Demand/Immediate Ride
5.3. Pre-booked/Reserved Ride
5.4. Other E-Hailing Services
6. SOUTH KOREA E-HAILING MARKET BY BOOKING MODE
6.1. Introduction
6.2. Mobile App-Based Booking
6.3. Web-Based Booking
6.4. Assisted/Other Digital Booking Channels
7. SOUTH KOREA E-HAILING MARKET BY VEHICLE CLASS
7.1. Introduction
7.2. Standard Taxi
7.3. Premium/Deluxe Taxi
7.4. Van/Minivan
7.5. Luxury Taxi
7.6. Autonomous Taxi
7.7. Others
8. SOUTH KOREA E-HAILING MARKET BY END-USER
8.1. Introduction
8.2. Individual Consumers (B2C)
8.3. Corporate Customers (B2B)
8.4. Government/Public Sector
8.5. Others
9. SOUTH KOREA E-HAILING MARKET BY GEOGRAPHY
9.1. Introduction
9.2. Seoul
9.3. Gyeonggi
9.4. Incheon
9.5. Busan
9.6. Daegu
9.7. Daejeon
9.8. Gwangju
9.9. Jeju
9.10. Other Regions
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Kakao Mobility Corp.
11.2. Uber Technologies Inc.
11.3. VCNC Co., Ltd. (TADA)
11.4. KST Mobility Co., Ltd. (i.M Taxi)
11.5. Tmoney Mobility Co., Ltd. / Onda
11.6. TABA
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











