
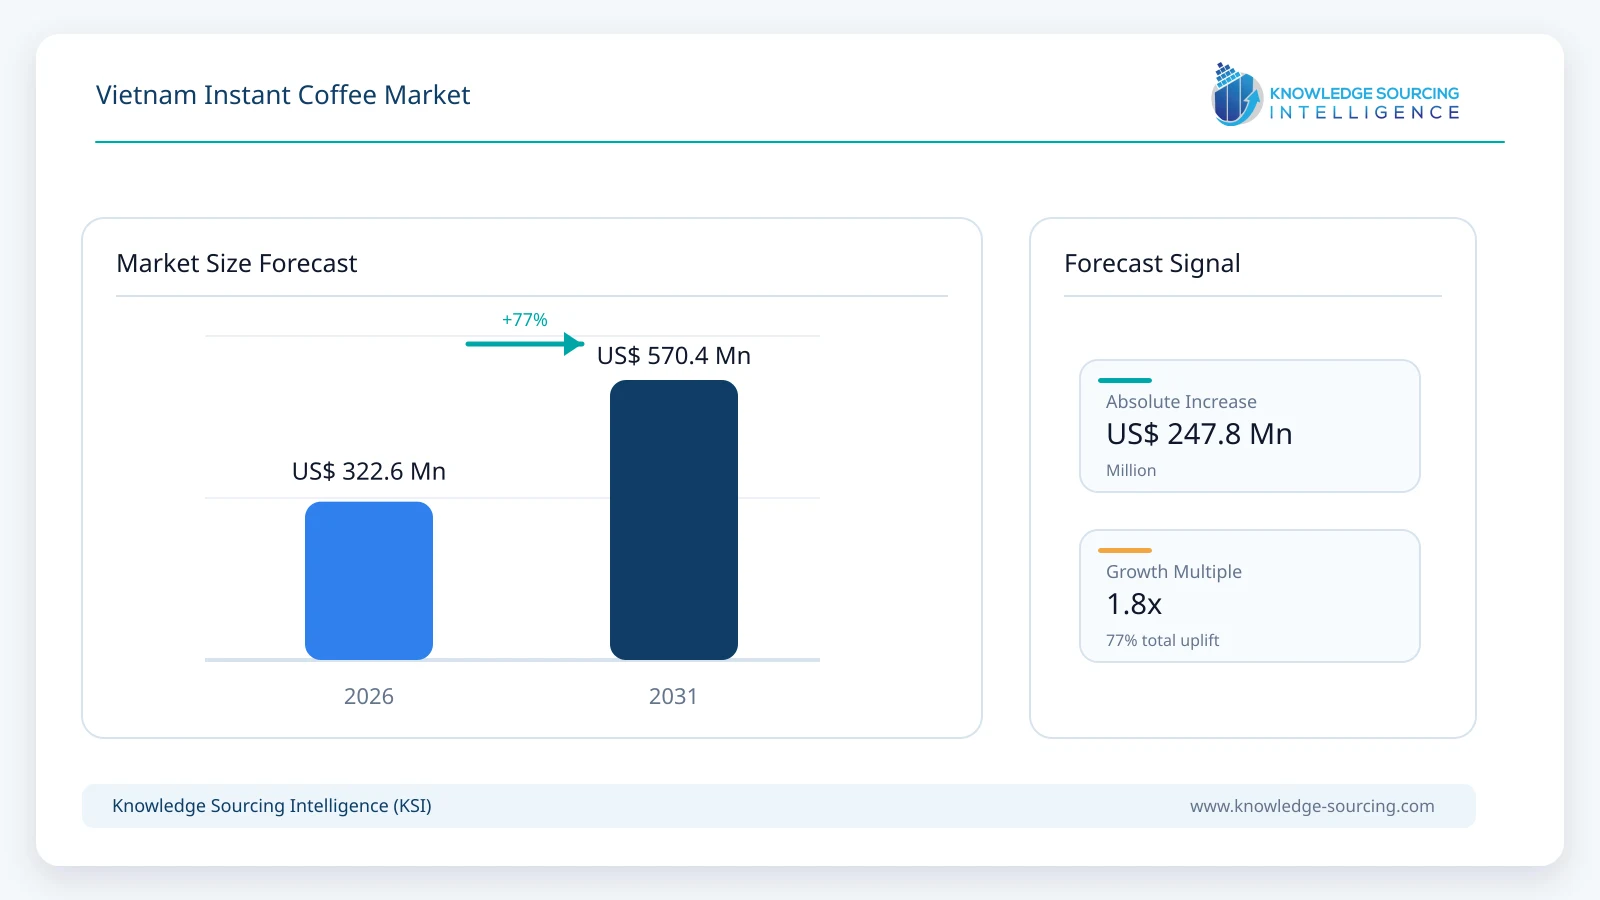
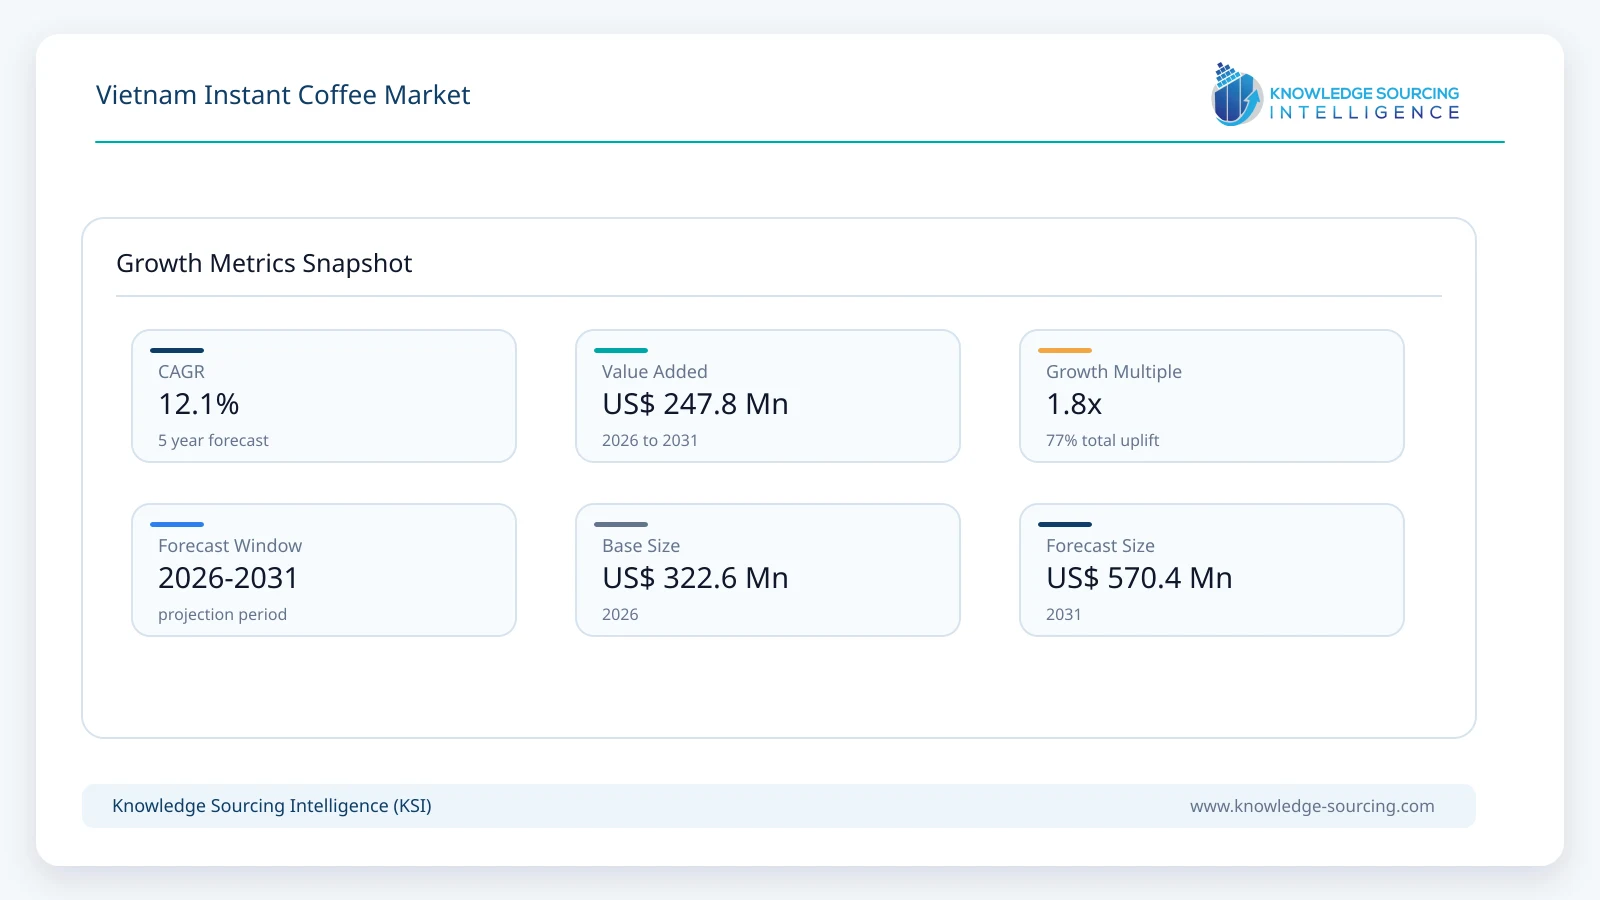
The Vietnam Instant Coffee market is forecast to grow at a CAGR of 12.1%, reaching USD 570.4 million in 2031 from USD 322.6 million in 2026.
Highlights:
- 1Spray-dried coffee accounts for approximately 58% of instant coffee revenue in 2026.
- 2Freeze-dried instant coffee is projected to grow approximately 17.3% annually through 2031.
- 33-in-1 and premixed coffee accounts for approximately 64% of market value in 2026.
- 4Online sales rise from approximately 17% market share in 2026 to 25% by 2031.
- 5USDA forecasts soluble and roasted coffee exports at 3.55 million bags in MY2026/27.
Vietnam’s instant coffee market is supported by an unusually strong connection between domestic consumption, locally available Robusta coffee and a growing soluble-coffee processing industry serving international customers. Mass-market 3-in-1 sachets remain central to domestic consumption, while manufacturers are simultaneously increasing production of pure soluble, freeze-dried and higher-value products for local premium consumers and export customers. The result is a market in which volume remains anchored in affordable instant mixes, while a disproportionate share of incremental value comes from premium formulations, improved processing technology and international sales.
The raw-material base remains a major competitive advantage. USDA forecasts Vietnam’s MY2026/27 coffee production at 32.5 million 60-kg bags green-bean equivalent, including 31.4 million bags of Robusta and 1.1 million bags of Arabica. Domestic coffee consumption is forecast at 5.0 million bags, while the country’s expanding processing industry is becoming increasingly important to export value. USDA estimates soluble and roasted coffee exports at 3.4 million bags in MY2025/26, up 19% from the previous marketing year, and forecasts a further increase to 3.55 million bags in MY2026/27. VICOFA estimates these processed products now account for approximately 13% of Vietnam’s total coffee exports.
This processing shift supports the existing thesis that instant coffee is developing from a primarily convenience-led domestic product into a more important value-added manufacturing industry. Tata Consumer Products is adding freeze-dried capacity in Vietnam for international demand, Trung Nguyên Legend is expanding processing in Dak Lak, and established processors such as Nestlé, An Thai and CCL Products already operate significant soluble-coffee capabilities. An Thai alone reports production capacity exceeding 10,000 tonnes per year each for spray-dried coffee and 3-in-1 coffee, alongside more than 3,000 tonnes of freeze-dried capacity.
Major Market Drivers
Expansion of Value-Added Coffee Processing and Exports
The strongest structural driver is Vietnam’s movement from green-bean exports toward more processed coffee products. Soluble coffee allows processors to capture manufacturing, formulation and branding value in addition to the agricultural value of the bean itself. USDA expects soluble and roasted exports to increase again in MY2026/27 after an estimated 19% expansion during MY2025/26, supported by additional processing capacity and strong Asian demand.
Investment activity reinforces this shift. Tata Consumer Products states that additional freeze-dried capacity in Vietnam is progressing and is expected to be commissioned and commercialised in the following financial year. Trung Nguyên Legend began construction in June 2026 on a new coffee manufacturing project and an expansion of its existing facility in Dak Lak, while Phúc Sinh launched a VND 500 billion agricultural processing centre in July 2026 intended to increase deep processing of coffee and other crops. These investments expand Vietnam’s ability to sell higher-value coffee rather than depending predominantly on raw beans.
Convenience Consumption and Product Premiumization
Instant coffee remains well aligned with Vietnamese consumption patterns because single-serve sachets provide low preparation time, consistent taste and accessible prices. The existing Vinacafé and Wake-Up portfolios illustrate how important 2-in-1 and 3-in-1 products remain in the domestic market, with multiple products positioned around milk coffee, regional taste profiles and flavoured formulations.
At the same time, premiumization is broadening the category beyond conventional sweetened mixes. Pure soluble coffee, freeze-dried products, lower-sugar formulations and specialty Robusta products are becoming more relevant as consumers gain exposure to higher-quality coffee. USDA notes that Vietnamese consumers are increasingly purchasing premium Robusta, Arabica and specialty coffee and experimenting with modern preparation methods. This shift allows manufacturers to increase value per serving even while traditional 3-in-1 remains the largest formulation category.
Major Market Restraints
Robusta Price Volatility, Climate Risk and Rising Farm Costs
Vietnamese instant coffee manufacturers benefit from proximity to Robusta supply, but this also exposes them directly to agricultural volatility. USDA reported that fertilizer and fuel costs had risen by approximately 30% and labour costs by 33% compared with the previous year in its May 2026 assessment. Coffee production in the Central Highlands also remains exposed to drought, rainfall variability and ageing plantations. Approximately 30% of the country’s coffee area was estimated to consist of trees aged 20 years or more that require renewal to maintain productivity and quality.
Higher or volatile green-coffee costs are especially challenging for low-priced instant sachets because manufacturers cannot always pass raw-material inflation directly to consumers. Freeze-dried production also carries higher processing and energy requirements, creating a second layer of cost pressure for premium processors.
Traceability and Export Compliance Requirements
Export-oriented processors increasingly need farm-level traceability, quality controls and documentation that smaller operators may find difficult to implement economically. This is particularly relevant for Europe. Following EU legislative amendments, the EUDR will apply from 30 December 2026 to large and medium operators, with later application for most micro and small operators. In July 2026, the European Commission also added soluble coffee specifically to the EUDR product scope, with those newly added products becoming subject to the regulation from 30 December 2027.
The requirement strengthens the advantage of processors with direct farmer relationships, geolocation systems and established sustainability certification. It can also increase sourcing and administrative costs throughout the supply chain.
Vietnam Instant Coffee Market Trends
Freeze-Dried Capacity Is Expanding
Vietnam’s soluble-coffee industry has historically relied heavily on spray drying because it supports high-volume production at comparatively lower cost. Freeze drying is gaining importance as processors target customers willing to pay more for aroma retention and improved sensory quality.
Tata Consumer Products’ FY2025-26 reporting specifically identifies a targeted addition of freeze-dried capacity in Vietnam to meet international demand. An Thai already produces both spray-dried and freeze-dried coffee, while CCL Products operates its Ngon Coffee manufacturing plant in Dak Lak. The modeled freeze-dried segment is therefore projected to expand materially faster than the market average through 2031.
Processed Coffee Is Taking a Larger Role in Export Growth
Vietnam’s coffee export model remains dominated by green beans, but processed coffee is increasing its contribution. USDA forecasts soluble and roasted coffee exports at 3.55 million bags in MY2026/27 and notes that additional processing capacity and strong Asian demand are supporting this expansion.
Trade agreements also improve access to several markets. Vietnam’s Ministry of Industry and Trade has highlighted the role of RCEP and other FTAs in helping Vietnamese coffee producers expand processed and higher-quality exports rather than competing primarily on raw-bean volume.
Specialty and Lower-Sugar Instant Products Are Broadening the Category
Traditional sweetened coffee mixes remain important, but manufacturers are introducing products that address changing health and taste preferences. Pure soluble coffee, lower-sugar mixes, white coffee, regional formulations and premium Robusta products allow brands to target consumers who want convenience without relying exclusively on traditional 3-in-1 formulations.
This creates a faster-growing value pool outside the largest mass-market sachet category and supports premium pricing for products positioned around bean origin, processing method or improved aroma.
Supply-Chain Traceability Is Becoming a Commercial Capability
Sustainability certification and traceability are moving from corporate responsibility programs into procurement requirements. USDA estimates that approximately 40% of Vietnam’s coffee area had attained sustainability certifications such as Rainforest Alliance, Fairtrade, 4C or UTZ by 2025.
Nestlé’s Nescafé Plan provides one example of this transition. In June 2026 the company reported that 53% of its global green coffee purchases in 2025 came from farmers adopting regenerative agriculture practices, with Vietnam remaining a major sourcing market within the program.
Vietnam Instant Coffee Market Segmentation Analysis
By Type
Spray-Dried Instant Coffee
Spray-dried instant coffee accounts for approximately 58% of Vietnam’s instant coffee market value in 2026, making it the largest processing type. The format supports high-volume production and remains well suited to mainstream 3-in-1 sachets and industrial soluble-coffee requirements where cost efficiency is important.
Vietnam already has substantial spray-drying capacity close to Robusta-growing areas. An Thai reports more than 10,000 tonnes of annual spray-dried instant coffee capacity, while several domestic and foreign processors operate similar extraction and drying facilities. Spray-dried coffee continues increasing in absolute value through 2031, although its market share declines as freeze-dried products expand faster.
By Product Formulation
3-in-1 and Premixed Coffee
3-in-1 and related premixes account for approximately 64% of market value in 2026, remaining the largest formulation category. Their position reflects low preparation time, accessible serving prices and strong consumer familiarity with sweet milk-coffee profiles.
Vinacafé and Wake-Up maintain broad portfolios of 2-in-1 and 3-in-1 products, while Trung Nguyên’s G7 and other domestic brands reinforce the segment’s competitive intensity. The category continues growing through 2031 but gradually loses share to pure soluble, freeze-dried and specialty formulations as household purchasing power and coffee sophistication increase.
By Distribution Channel
Offline Retail
Offline retail accounts for approximately 70% of market value in 2026, remaining the largest sales channel. Instant coffee is sold extensively through traditional grocery outlets, supermarkets, convenience stores and modern retail chains, making widespread physical distribution critical for mass-market brands.
The channel continues expanding in value through 2031, although its market share declines as e-commerce grows faster. Online sales are modeled to increase from approximately 17% of market value in 2026 to 25% by 2031 as younger consumers use digital channels to purchase premium, imported and specialty coffee products.
Production and Processing Geography
Vietnam’s coffee supply remains concentrated in the Central Highlands. USDA identifies Dak Lak, Gia Lai, Kon Tum, Dak Nông and Lâm Dong among the country’s key producing provinces and forecasts approximately 644,000 hectares of harvested Robusta area in MY2026/27. Dak Lak remains particularly important because it combines a large raw-material base with established processors including Trung Nguyên and An Thai.
Manufacturing is not confined to growing areas. Bình Duong and Dong Nai also play important roles because of industrial infrastructure and proximity to southern logistics corridors. Tata Coffee Vietnam operates in Bình Duong, while Nestlé’s Tri An facility is located in Dong Nai and serves both domestic and international markets.
Competitive Landscape
Vietnam’s instant coffee market combines multinational manufacturers, large domestic consumer brands and B2B soluble-coffee processors. Nestlé participates through Nescafé and an integrated sourcing and manufacturing network. Trung Nguyên competes through G7 and a vertically integrated coffee ecosystem, while Vinacafé Bien Hoa and Wake-Up give Masan Consumer substantial exposure to the mainstream instant-coffee segment.
Tata Coffee Vietnam, An Thai and CCL Products’ Ngon Coffee operation are particularly important in B2B soluble production. Their capabilities span spray-dried, freeze-dried, agglomerated coffee and extracts intended for global customers. King Coffee, Me Trang and other Vietnamese brands compete through domestic retail and international distribution.
Competition is therefore developing on two levels. Consumer-facing brands compete on taste, price, sachet formats and distribution, while B2B processors compete on drying technology, capacity, quality consistency, certifications, raw-material access and export logistics.
Recent Developments
July 2026: Phúc Sinh launched its new agricultural export production and processing centre in Lâm Dong with an investment of approximately VND 500 billion. The facility is designed to increase deep processing of coffee, pepper and other agricultural products.
July 2026: The European Commission updated the EUDR product scope to add soluble coffee. Newly added products become subject to the regulation from December 30, 2027.
June 2026: Trung Nguyên Legend began construction of its Energy Coffee Factory and expansion of its existing coffee plant at Tân An 2 Industrial Cluster in Dak Lak.
Market Outlook
Vietnam’s instant coffee market is positioned for double-digit expansion as domestic convenience consumption combines with rapidly developing soluble-coffee manufacturing. The country’s Robusta base gives processors strong access to raw material, while investments in extraction, spray drying and freeze drying increase the proportion of coffee sold in higher-value processed form.
Mass-market 3-in-1 products remain the largest formulation through 2031, but pure soluble, premium and specialty products gain share. Spray-dried coffee remains the largest processing type, while freeze-dried coffee grows materially faster as manufacturers target premium and export customers. Online sales also increase their contribution as specialty products become easier to distribute outside traditional retail.
Vietnam Instant Coffee Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 322.6 million |
| Total Market Size in 2031 | USD 570.4 million |
| Forecast Unit | Million |
| Growth Rate | 12.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Product Formulation, Distribution Channel |
| Companies |
|
Market Segmentation
By Type
Spray-Dried Instant Coffee
Freeze-Dried Instant Coffee
Agglomerated and Other Instant Coffee
By Product Formulation
3-in-1 and Premixed Coffee
Pure Soluble Coffee
Specialty and Flavored Instant Coffee
By Distribution Channel
Offline
Retail
Foodservice and Institutional
Online
Production and Processing Geography
Dak Lak
Lâm Dong
Dak Nong
Gia Lai
Bình Duong
Dong Nai
Other Processing Locations
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Vietnam Instant Coffee Market Size, 2026-2031
1.3. Processing Type Outlook
1.4. Product Formulation Outlook
1.5. Distribution Channel Outlook
1.6. Supply and Processing Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Historical and Forecast Period
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of Soluble and Roasted Coffee Exports and Deep-Processing Capacity
3.1.2. Convenience-Led Domestic Demand for 2-in-1 and 3-in-1 Coffee
3.1.3. Premiumization Through Freeze-Dried, Pure Soluble and Specialty Robusta Products
3.1.4. FTA-Led Access to Asian and International Processed-Coffee Markets
3.2. Market Restraints
3.2.1. Robusta Price Volatility, Climate Risk and Rising Farm Input Costs
3.2.2. High Energy and Capital Requirements for Advanced Soluble-Coffee Processing
3.2.3. Export Traceability, EUDR and International Food-Safety Compliance Costs
3.2.4. Competition from Freshly Brewed, Café and Ready-to-Drink Coffee Formats
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Strategic Recommendations
4. RAW MATERIAL, SUPPLY AND PRICING OUTLOOK
4.1. Vietnam Coffee Production
4.2. Robusta Supply Outlook
4.3. Arabica Supply Outlook
4.4. Green Coffee Prices
4.5. Processor Procurement Strategies
4.6. Processing Cost and Energy Exposure
4.7. Coffee Import Requirements for Processing
5. TRADE AND REGULATORY OUTLOOK
5.1. Green Coffee Exports
5.2. Soluble and Roasted Coffee Exports
5.3. Major Export Destinations
5.4. EVFTA, CPTPP and RCEP
5.5. EU Deforestation Regulation
5.6. Traceability and Sustainability Certification
5.7. Food-Safety and Quality Requirements
6. TECHNOLOGICAL OUTLOOK
6.1. Coffee Extraction Technology
6.2. Spray Drying
6.3. Freeze Drying
6.4. Agglomeration
6.5. Aroma Recovery
6.6. Energy-Efficient Processing
6.7. Traceability and Digital Supply-Chain Systems
7. VIETNAM INSTANT COFFEE MARKET BY TYPE
7.1. Introduction
7.2. Spray-Dried Instant Coffee
7.3. Freeze-Dried Instant Coffee
7.4. Agglomerated and Other Instant Coffee
8. VIETNAM INSTANT COFFEE MARKET BY PRODUCT FORMULATION
8.1. Introduction
8.2. 3-in-1 and Premixed Coffee
8.3. Pure Soluble Coffee
8.4. Specialty and Flavored Instant Coffee
9. VIETNAM INSTANT COFFEE MARKET BY DISTRIBUTION CHANNEL
9.1. Introduction
9.2. Offline
9.2.1. Retail
9.2.2. Foodservice and Institutional
9.3. Online
10. PRODUCTION AND PROCESSING GEOGRAPHY
10.1. Dak Lak
10.2. Lâm Dong
10.3. Dak Nong
10.4. Gia Lai
10.5. Bình Duong
10.6. Dong Nai
10.7. Other Processing Locations
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Nestlé S.A.
12.2. Trung Nguyên Legend Group
12.3. Vinacafé Bien Hoa Joint Stock Company
12.4. Tata Coffee Vietnam Company Limited
12.5. An Thai Group
12.6. CCL Products (Ngon Coffee)
12.7. TNI King Coffee
12.8. Me Trang Coffee
12.9. Phúc Sinh Corporation
12.10. Simexco Daklak
12.11. Outspan Vietnam
12.12. Intimex Group
13. APPENDIX
Navigate
Trusted by the world's leading organizations











