
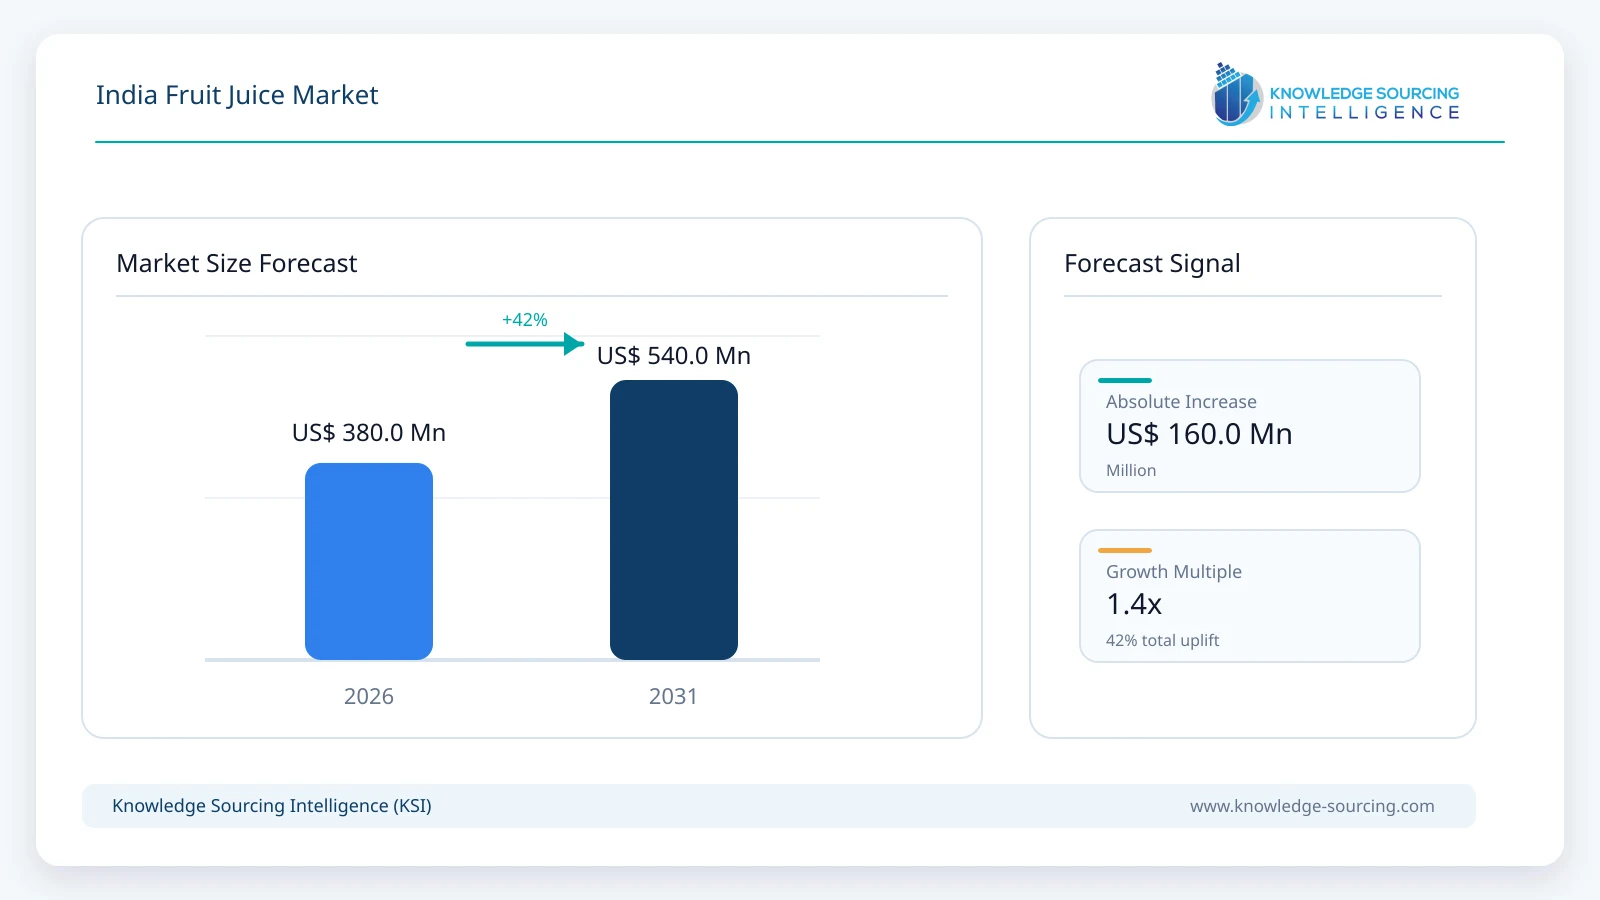
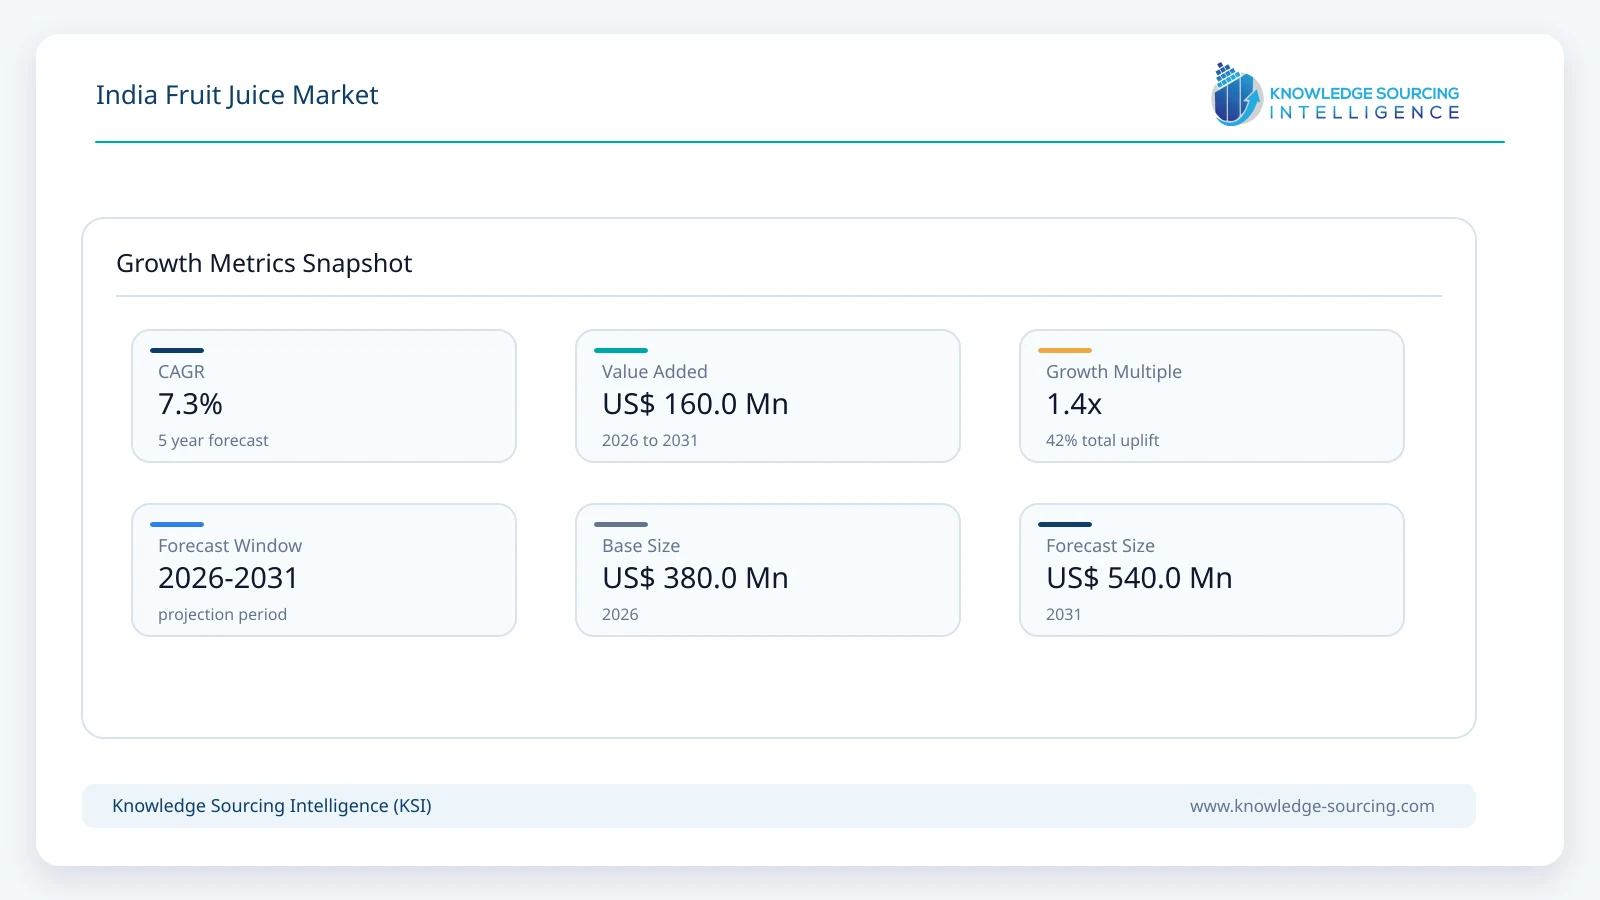
The India Fruit Juice Market is expected to grow at a robust CAGR of 7.3%, reaching a market size of USD 540 million in 2031 from USD 380 million in 2026.
Highlights:
- 1Fruit drinks account for approximately 47% of India fruit juice market value in 2026 and remain the largest product category.
- 2Mango represents approximately 41% of market value by flavour in 2026, supported by established national beverage brands and domestic fruit availability.
- 3Plastic bottles account for approximately 46% of market value by packaging format in 2026 due to their use across single-serve and family-sized products.
- 4Offline channels represent approximately 86% of market value in 2026 and remain central to mass-market beverage distribution.
- 5Mumbai accounts for approximately 16% of market value among the city segmentation in 2026, making it the largest individual city market.
The market covers packaged fruit drinks, juices and nectars sold for direct consumption through retail, foodservice and digital channels. The Food Safety and Standards Authority of India separately recognizes thermally processed fruit nectars and thermally processed fruit beverages, fruit drinks and ready-to-serve fruit beverages, making formulation and fruit content important elements of product classification and commercial positioning.
India has a substantial domestic raw-material base for fruit processing. According to the Ministry of Agriculture & Farmers Welfare’s final horticulture estimates released in March 2026, fruit production increased by 4.13% to 117.65 million tonnes in 2024-25 from 112.98 million tonnes in 2023-24. The Ministry attributed the increase partly to higher production of banana, mango, mandarin, papaya, guava, watermelon and jackfruit.
APEDA also reports, based on FAO data, that India ranks first globally in the production of bananas, mangoes including mangosteens and guavas, and papayas. This production base supports sourcing for several of the fruits most commonly used in packaged beverages.
India also maintains an established processed-fruit export industry. According to APEDA data sourced from the Directorate General of Commercial Intelligence and Statistics, India exported approximately USD 662.79 million of processed fruits, juices and nuts in FY2026. Major destinations included the Netherlands, the United States, the United Arab Emirates, Saudi Arabia and the United Kingdom.
Market Trends
Premium and Higher-Fruit-Content Products Are Expanding
The Indian market is becoming increasingly differentiated between mainstream refreshment-oriented fruit drinks and products positioned around greater fruit content, reduced added sugar and premium ingredients. Traditional fruit drinks continue to generate substantial volume, but manufacturers are widening portfolios to address consumers seeking different nutritional, taste and price propositions.
Dabur provides a visible example of this change. In its Q1 FY2026-27 results, the company reported 42% growth in Real Activ Juices and 73% growth in its coconut-water portfolio. Dabur stated that its premium beverage portfolio was continuing to gain scale despite weather-related disruption at the beginning of the quarter.
Product composition is also becoming a stronger point of differentiation. Manufacturers increasingly distinguish 100% juice, no-added-sugar products, nectars and fruit drinks rather than presenting all fruit beverages under a common proposition. This allows companies to maintain high-volume affordable products while developing premium portfolios targeted at consumers paying greater attention to ingredients and nutritional information.
The development is widening the addressable market rather than simply shifting demand from one category to another. Mainstream mango and mixed-fruit beverages can continue addressing impulse and refreshment consumption, while premium juice propositions compete more directly with health-oriented beverages and at-home breakfast products.
Mango Remains Central While Flavour Portfolios Broaden
Mango continues to occupy a distinctive position in India’s packaged fruit beverage industry. Major brands including Maaza, Frooti, Slice and Real have established mango offerings across mass-market retail, while domestic agricultural availability provides processors with access to a large mango crop and established pulp-processing capacity.
According to APEDA, citing FAO data, India is the world’s leading producer of mangoes including mangosteens and guavas. The combination of production availability and strong consumer familiarity makes mango difficult to displace as the leading flavour within packaged fruit beverages.
Coca-Cola India’s current Maaza formulation illustrates the category’s established scale. The company identifies Maaza Original as a ready-to-serve fruit drink containing 18.8% mango pulp and offers it across cartons, returnable glass bottles, PET bottles and cans.
Portfolios are nevertheless becoming more diverse. Apple, orange, mixed fruit, guava, litchi and pomegranate increasingly appear across premium and mainstream product ranges. Broader flavour availability allows companies to address different taste preferences and reduces dependence on a single fruit proposition, particularly in premium juice portfolios.
Packaging Is Becoming More Closely Aligned With Consumption Occasion
Manufacturers increasingly use packaging architecture to address different consumption occasions, price points and retail channels. Plastic bottles remain central because they can be offered in small impulse packs, medium-sized resealable formats and large household packs.
Coca-Cola India’s Maaza portfolio illustrates this approach. The company lists 200 ml cartons, 200 ml and 250 ml returnable glass bottles, PET bottles ranging from 250 ml to 1.75 litres and several can formats. The same product can therefore address low-ticket impulse purchases, family consumption and foodservice demand without requiring a different core formulation.
Aseptic cartons remain important for juices and nectars associated with home consumption and ambient shelf life. Cans occupy a smaller position but support convenience and premium presentation, while glass retains relevance in selected foodservice and returnable-pack systems.
Packaging competition through 2031 is therefore likely to focus less on replacing one material completely and more on optimizing pack sizes and formats around specific consumption occasions.
Market Drivers
India’s Large Fruit Production Base Supports Processing
India’s agricultural base provides a structural advantage for domestic fruit processing. According to final estimates released by the Ministry of Agriculture & Farmers Welfare in March 2026, India produced 117.65 million tonnes of fruit during 2024-25, representing growth of 4.13% from the previous year.
The production base spans mango, banana, citrus, guava, papaya, apple, grapes, litchi and several other fruits relevant to beverage formulation. Domestic availability allows processors to source substantial volumes locally and supports India-specific flavour portfolios.
Mango is particularly important because fruit can be processed into pulp during the harvest season and subsequently used throughout the year. This reduces the need for beverage production to follow the fresh-fruit season directly and supports large national brands with consistent formulations.
The wider processing industry provides additional evidence of established infrastructure. According to APEDA and DGCIS, exports of processed fruits, juices and nuts reached approximately USD 662.79 million during FY2026. Although the export category includes products beyond packaged retail juice, it demonstrates the scale of India’s processing, preservation, packaging and fruit-ingredient ecosystem.
Broad Retail Distribution Increases Product Accessibility
Fruit beverages depend heavily on route-to-market capability because a large proportion of consumption occurs through neighbourhood shops, convenience outlets, supermarkets, foodservice establishments and impulse purchases. Companies with existing non-alcoholic beverage distribution infrastructure can therefore achieve significant advantages in availability and refrigeration.
Varun Beverages provides an indication of the scale of India’s beverage-distribution environment. During Q1 2026, the company reported 14.4% year-on-year sales-volume growth in India while continuing to use pack upsizing and targeted price points to expand consumption. Its wider portfolio spans carbonated beverages, juice-based drinks, sports beverages and packaged water.
Digital availability increasingly complements these physical networks. Major beverage brands are sold through grocery marketplaces and quick-commerce platforms, improving access to premium juice products, multipacks and household-sized packs. Coca-Cola India’s Maaza page, for example, provides direct purchase options through BigBasket, Blinkit, Flipkart and Amazon.
Online sales remain much smaller than offline distribution, but they remove some of the shelf-space limitations facing premium or less frequently purchased flavours and can improve product discovery among urban consumers.
Product Innovation Is Creating Additional Consumption Occasions
Fruit ingredients are increasingly being incorporated into products that sit between conventional juice, refreshment and functional beverages. Manufacturers are using coconut water, smoothies, carbonation, pulp, reduced-sugar formulations and premium fruit blends to extend beverage portfolios.
Dabur’s growth in Real Activ and coconut water demonstrates increasing activity in health-oriented beverage formats. The company’s approach allows it to maintain the large Real franchise while creating separate propositions for consumers seeking higher-value beverages.
Innovation also improves the ability of companies to address consumption occasions outside breakfast or conventional juice usage. Smaller single-serve formats can compete for immediate refreshment, while larger no-added-sugar or 100% juice packs are more strongly associated with planned household consumption.
This portfolio expansion is particularly relevant in large urban markets where modern retail, foodservice and digital channels provide greater opportunities for differentiated products to gain visibility alongside mainstream fruit drinks.
Market Restraints
Fruit Content and Added Sugar Affect Product Positioning
Fruit beverages can differ substantially in fruit content, added sugar and formulation, making clear product positioning increasingly important. FSSAI separately recognizes fruit nectar and thermally processed fruit beverages, fruit drinks and ready-to-serve fruit beverages within India’s product standards.
Consumers therefore cannot assume that every beverage carrying fruit imagery or flavouring has the same nutritional composition. Coca-Cola India, for example, identifies Maaza Original as a ready-to-serve fruit drink containing 18.8% mango pulp and lists 13.3 grams of added sugar per 100 ml.
This distinction becomes more commercially important as consumers scrutinize labels and differentiate conventional refreshment products from juices positioned around higher fruit content or no added sugar. Manufacturers need to maintain taste and affordability while responding to these preferences, creating additional formulation and pricing complexity.
The issue does not necessarily reduce overall fruit-beverage consumption. Instead, it increases the importance of portfolio segmentation and transparent positioning between mainstream fruit drinks, nectars and premium juice products.
Weather Influences Both Fruit Supply and Beverage Consumption
Fruit beverage manufacturers are exposed to weather conditions at both ends of the value chain. Agricultural conditions influence crop volume, fruit quality and procurement costs, while rainfall and temperature affect immediate beverage demand.
Companies can reduce agricultural volatility through pulp inventories, multiple suppliers and regional sourcing, but fruit processing cannot eliminate crop-related risk completely. Mango and citrus availability can vary by season and production region, influencing input costs and purchasing requirements.
Weather can also affect consumer demand during key selling periods. Dabur reported that rain-related disruption affected the beginning of Q1 FY2026-27 before its beverages business recovered during the remainder of the quarter.
This exposure makes beverage portfolios with several formats and consumption occasions more resilient than those dependent primarily on warm-weather impulse demand.
Segment Analysis
By Type: Fruit Drink
Fruit drinks are projected to reach approximately USD 245 million by 2031 and remain the largest product type through the forecast period. Their position reflects established national brands, broad retail availability and pricing that allows manufacturers to address a wider consumer base than many premium juice products.
FSSAI’s separate regulatory treatment of fruit drinks and fruit nectars reflects important differences in formulation and fruit content. Mainstream fruit drinks can therefore compete primarily around flavour, refreshment and affordability, while juice products increasingly compete around higher fruit content and nutritional positioning.
Juices are expected to gain relative importance as companies expand no-added-sugar and premium portfolios, while nectar retains a meaningful position between the two categories. The market is therefore likely to maintain several distinct product tiers rather than shift uniformly toward one formulation.
By Flavor: Mango
Mango-flavoured products are projected to reach approximately USD 218 million by 2031. The segment benefits from the combination of strong domestic fruit availability, established consumer familiarity and large beverage franchises developed over several decades.
According to APEDA, India occupies a leading global position in mango production. This provides processors with access to an extensive domestic pulp supply chain and supports year-round packaged-beverage production after seasonal processing.
Mango also spans a particularly wide range of price points and package formats. Maaza alone is offered in carton, PET, returnable-glass and can formats, demonstrating the flavour’s ability to serve household, foodservice and immediate-consumption occasions.
Other flavours continue expanding, particularly in premium juice portfolios, but mango remains structurally advantaged by scale, sourcing and brand recognition.
By Packaging Format: Plastic Bottles
Plastic bottles are projected to generate approximately USD 240 million in market value by 2031. Their position is supported by flexibility across small impulse packs, resealable medium formats and larger household packs.
Current commercial portfolios show how extensively PET is used across price points. Coca-Cola offers Maaza in PET bottles ranging from 250 ml to 1.75 litres in addition to other packaging formats.
Aseptic cartons remain important for ambient household juice and nectar products, where long shelf life and established consumer association with juice provide commercial advantages. Cans and glass bottles retain narrower roles across convenience, foodservice and selected premium propositions.
The packaging market is consequently expected to remain multi-format even as PET maintains the largest individual position.
By Distribution Channel: Offline
Offline channels are projected to account for approximately USD 445 million of market value by 2031. India’s traditional retail network remains crucial to immediate-consumption beverage sales, while supermarkets, convenience stores and foodservice outlets add further physical points of purchase.
Large beverage producers benefit from established distribution systems covering multiple beverage categories. This lowers the incremental cost of extending juice-based products into existing routes and refrigeration networks.
Online and quick-commerce platforms are expected to gain share more rapidly from a smaller base. Their importance is particularly strong for household replenishment, premium juice products and flavours that may not receive significant shelf space in smaller neighbourhood stores.
The development of digital channels therefore supplements rather than displaces physical distribution through 2031.
By Cities: Mumbai
Mumbai is projected to generate approximately USD 82 million of India fruit juice market value by 2031, remaining the largest individual city market. Its position reflects a combination of population density, relatively high household expenditure, extensive foodservice activity and broad availability of both mainstream and premium beverage products.
The city’s retail environment allows companies to sell fruit beverages across traditional stores, supermarkets, convenience formats, restaurants, cafés and rapid-delivery platforms. This supports both low-price single-serve beverages and higher-value juice products aimed at planned household consumption.
Delhi represents another major market, supported by its large consumer base and substantial foodservice and modern-retail presence. Bengaluru, Hyderabad and Chennai are increasingly important for premium and digitally distributed beverage products, while Kolkata and Ahmedabad remain significant regional markets.
The Cities segmentation therefore remains commercially useful because packaged beverage penetration, channel mix and premium-product availability can vary substantially among India’s large metropolitan markets. The category is retained consistently across the report scope, segmentation and Table of Contents.
Competitive Environment and Analysis
India’s fruit juice market includes domestic FMCG companies, multinational beverage groups and specialist premium brands. Dabur participates through Real and Real Activ, while ITC operates B Natural and adjacent fruit-based beverage products. Coca-Cola competes through Maaza and Minute Maid, while PepsiCo’s Indian beverage portfolio includes fruit-oriented brands such as Slice and Tropicana. Parle Agro maintains a major mango franchise through Frooti.
Competitive strategies increasingly involve portfolio segmentation rather than offering a single fruit beverage proposition. Dabur’s reported growth in Real Activ indicates increasing demand for premium health-oriented formats alongside the company’s mainstream Real products.
Coca-Cola uses extensive package differentiation around Maaza, offering cartons, returnable glass, PET and cans to address different price points and consumption occasions. The ability to place the same brand across traditional retail, foodservice and digital platforms strengthens national reach.
Hector Beverages competes through Paper Boat, while Wingreens World operates Raw Pressery in the premium segment. Storia, Fresca, Mapro, Rasna and other suppliers expand the range of fruit-based beverages available across regional and digital channels.
Competition through 2031 is expected to depend on several factors simultaneously: fruit content, pricing, flavour, packaging convenience, distribution reach and the ability to develop premium propositions without losing mass-market volume. Manufacturing location and supply-chain efficiency also become more important as companies seek faster service to high-consumption urban markets.
Recent Developments
July 2026: Dabur reported 42% growth in Real Activ Juices and 73% growth in its coconut-water portfolio during Q1 FY2026-27, while its overall beverages business returned to positive mid-single-digit growth.
July 2026: ITC expanded its fruit-based beverage activity through B Natural Coconut Cola, combining coconut water with a carbonated beverage proposition.
May 2026: ITC expanded its beverage portfolio with mango and berry smoothies under the Sunfeast brand.
April 2026: Varun Beverages reported continued volume growth in India while using pack upsizing and targeted price points across its broader beverage portfolio.
February 2026: Dabur began construction of a new manufacturing facility in Tamil Nadu, with future phases intended to include Real Juice production.
Market Outlook
The India fruit juice market is forecast to increase. Growth is expected to come from both wider penetration of mainstream packaged fruit beverages and faster expansion of premium juices, no-added-sugar products and differentiated fruit-based formats.
Fruit drinks remain the largest product category, supported by affordable price points and established brands, while higher-fruit-content juices gradually strengthen their position. Mango continues to lead the flavour mix because of India’s large domestic crop, established pulp-processing infrastructure and high consumer familiarity.
Plastic bottles retain the largest packaging position because manufacturers can use the format across numerous serving sizes and channels. Offline retail continues to account for the majority of sales, although e-commerce and quick commerce gain importance for household purchases and premium products.
City-level demand remains concentrated in India’s large metropolitan markets. Mumbai maintains the largest individual city position, while Delhi, Bengaluru, Hyderabad, Chennai, Kolkata and Ahmedabad collectively represent a substantial portion of packaged juice consumption. Faster digital-delivery adoption is also improving the economics of launching differentiated products in large cities before expanding them more widely.
The underlying fruit-processing base remains supportive. According to the Ministry of Agriculture & Farmers Welfare, India’s fruit production reached 117.65 million tonnes in 2024-25, while APEDA and DGCIS report processed fruit, juice and nut exports of approximately USD 662.79 million in FY2026.
The market therefore enters the forecast period with both a substantial agricultural supply base and increasingly diverse consumer demand. Companies capable of combining mass-market distribution with higher-value innovation are positioned to capture the strongest opportunities through 2031.
India Fruit Juice Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 380 million |
| Total Market Size in 2031 | USD 540 million |
| Forecast Unit | Million |
| Growth Rate | 7.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Flavor, Packaging Format, Distribution Channel, Cities |
| Companies |
|
Market Segmentation
By Type
Fruit Drink
Juice
Nectar
By Flavor
Mango
Apple
Orange
Lychee
Others
By Packaging Format
Plastic Bottles
Tetra Pack
Cans
By Distribution Channel
Online
Offline
By Cities
Mumbai
Delhi
Kolkata
Bengaluru
Chennai
Hyderabad
Ahmedabad
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. India Fruit Juice Market Size, 2026-2031
3.3. Type Outlook
3.4. Flavor Outlook
3.5. Packaging Format Outlook
3.6. Distribution Channel Outlook
3.7. City Outlook
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. India’s Large Fruit Production Base
4.1.2. Broad Retail Distribution and Product Accessibility
4.1.3. Product and Format Innovation
4.2. Market Restraints
4.2.1. Fruit Content, Added Sugar and Product Positioning
4.2.2. Agricultural and Weather-Related Volatility
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Regulatory and Product Standards Environment
5. INDIA FRUIT JUICE MARKET BY TYPE
5.1. Fruit Drink
5.2. Juice
5.3. Nectar
6. INDIA FRUIT JUICE MARKET BY FLAVOR
6.1. Mango
6.2. Apple
6.3. Orange
6.4. Lychee
6.5. Others
7. INDIA FRUIT JUICE MARKET BY PACKAGING FORMAT
7.1. Plastic Bottles
7.2. Tetra Pack
7.3. Cans
8. INDIA FRUIT JUICE MARKET BY DISTRIBUTION CHANNEL
8.1. Online
8.2. Offline
9. INDIA FRUIT JUICE MARKET BY CITIES
9.1. Mumbai
9.2. Delhi
9.3. Kolkata
9.4. Bengaluru
9.5. Chennai
9.6. Hyderabad
9.7. Ahmedabad
9.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Dabur India Limited
11.2. ITC Limited
11.3. PepsiCo India Holdings Pvt. Ltd.
11.4. Parle Agro Private Limited
11.5. Coca-Cola India Private Limited
11.6. Hector Beverages Private Limited
11.7. Wingreens World Private Limited
11.8. Mapro Foods Private Limited
11.9. Hamdard Laboratories (India)
11.10. Patanjali Ayurved Limited
11.11. Storia Foods & Beverages Private Limited
11.12. Fresca Juices
11.13. Rasna International Private Limited
11.14. Mania Juices
11.15. Rus Organic
12. APPENDIX
Navigate
Trusted by the world's leading organizations











