
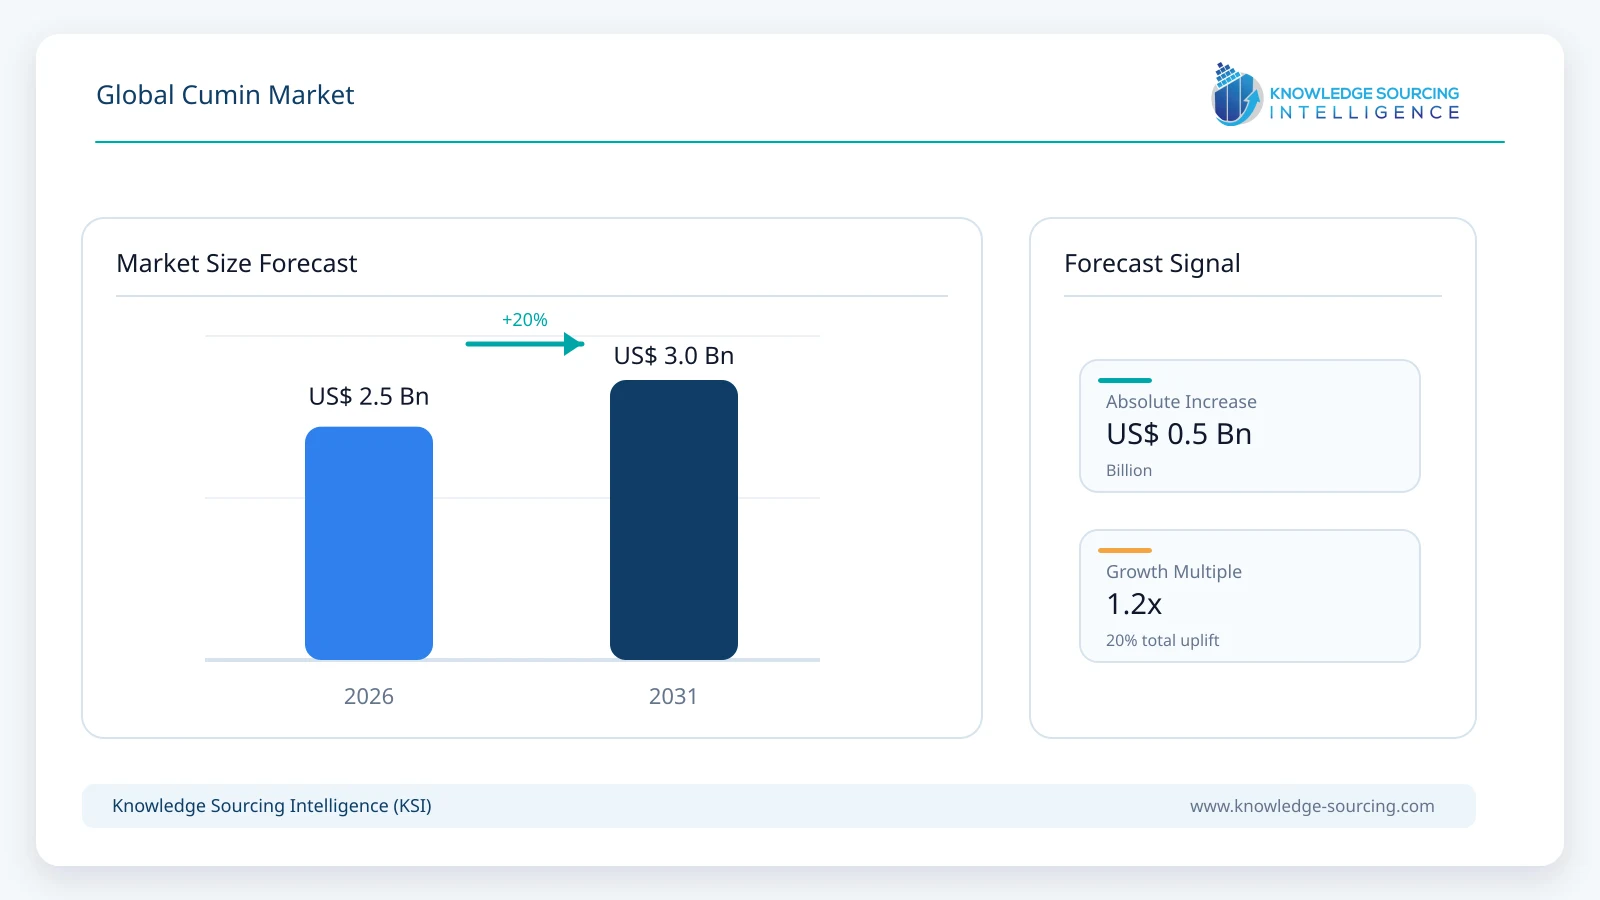
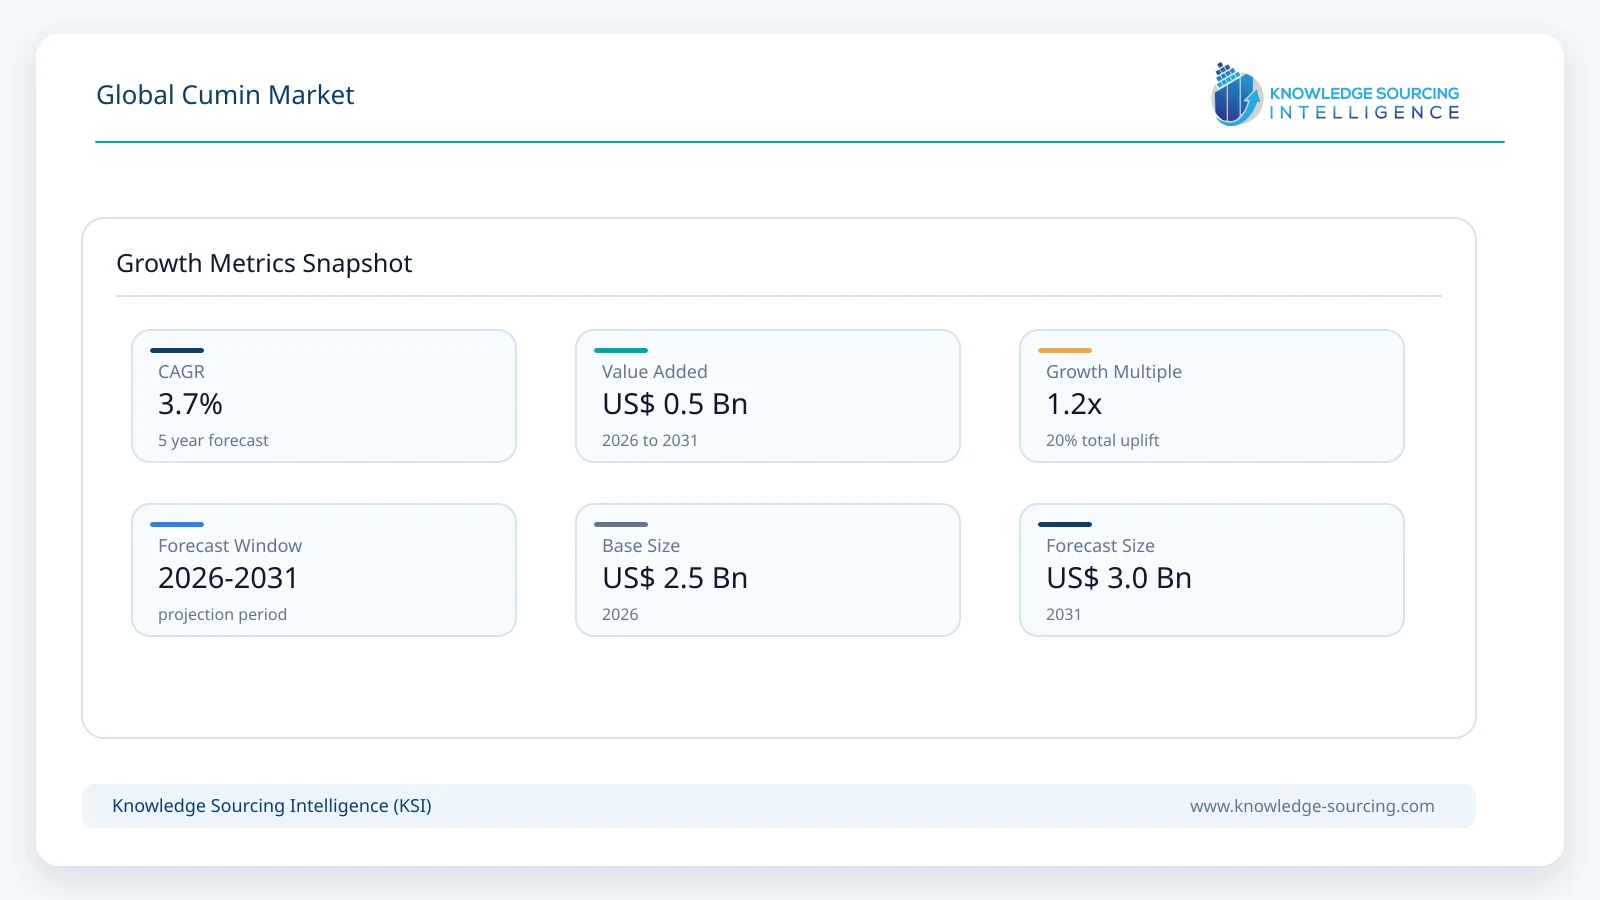
The global cumin market is forecast to grow at a CAGR of 3.7%, reaching USD 3.0 billion in 2031 from USD 2.5 billion in 2026.
Highlights:
- 1Whole cumin seed accounts for approximately 54% of global market value in 2026.
- 2Ground cumin is projected to grow at approximately 5.3% annually through 2031.
- 3Food applications represent approximately 86% of global cumin demand in 2026.
- 4Asia Pacific accounts for approximately 54% of global cumin market value in 2026.
- 5India’s cumin production is estimated at 1.143 million tonnes during 2025-26.
- 6India exported 196,800 tonnes of cumin worth USD 524.22 million in 2025-26.
Market Overview
Cumin is produced from the dried fruit of Cuminum cyminum and is widely used as a whole seed, ground spice, and source of aromatic oil. It is an established ingredient across Indian, Middle Eastern, North African, Mexican and other cuisines and has become increasingly integrated into packaged foods, seasoning blends, sauces, ready meals and foodservice formulations globally. The market growth is being complemented by expanding industrial food applications, greater consumption of regional cuisines outside their traditional markets, and growth in branded and processed spice products.
India remains central to global cumin supply. Spices Board data estimates Indian cumin production at 1.143 million tonnes in 2025-26, compared with approximately 1.164 million tonnes in 2024-25. Cultivated area remained exceptionally large at approximately 1.543 million hectares, with Rajasthan and Gujarat accounting for nearly all reported production. Rajasthan’s 2025-26 output is estimated at approximately 693,939 tonnes and Gujarat at about 446,000 tonnes.
International trade demonstrates both the importance and volatility of the crop. India exported 196,800 tonnes of cumin valued at USD 524.22 million in 2025-26, compared with 229,881 tonnes valued at USD 732.35 million in 2024-25. Cumin still represented approximately 12% of India’s total spice-export earnings during 2025-26, making it one of the country’s most commercially important exported spices.
The market is also becoming increasingly quality-oriented. International buyers require greater consistency in purity, pesticide residues, microbial safety, moisture, and traceability. Whole seeds remain important for direct culinary consumption and bulk international trade, while ground cumin is expanding faster through seasoning blends and industrial formulations. Food applications continue to dominate overall demand, with cumin oil and specialized extracts providing smaller opportunities in nutraceutical and personal-care applications.
Major Market Drivers
Globalization of Cumin-Based Cuisines and Industrial Food Formulations
Cumin is moving beyond traditional household consumption as Indian, Middle Eastern, Mexican, North African, and Mediterranean flavor profiles become increasingly common in packaged foods and foodservice. Seasoning blends, curry preparations, sauces, taco seasonings, meat products, ready meals and snack formulations use cumin to provide a recognizable warm and aromatic flavor profile. Industrial food manufacturers also require standardized ingredients with consistent particle size and sensory characteristics, supporting demand for processed and ground cumin.
The transition from household preparation toward packaged seasoning systems increases value addition because cumin must be cleaned, graded, processed, ground, blended, and packaged to defined specifications. Ground cumin is particularly suitable for industrial recipes where manufacturers require even dispersion and repeatable flavor performance across production batches. While whole seed remains the largest form in 2026, ground cumin grows more quickly and is projected to increase its global market share through 2031.
Foodservice expansion reinforces this demand. International restaurant concepts increasingly operate standardized menus across multiple countries, requiring consistent spice specifications and dependable supply rather than opportunistic commodity purchasing. This supports larger processors capable of meeting microbiological, residue, and traceability requirements across multiple markets.
Expansion of Branded, Processed and Export-Compliant Cumin Supply
The cumin trade is progressively moving toward processed products with defined purity, food-safety and traceability characteristics. International buyers increasingly require suppliers to demonstrate pesticide-residue compliance, microbiological control and documented processing conditions. This favors exporters with cleaning, grading, testing, traceability and controlled processing capabilities.
India’s Spices Board continues to strengthen commercial linkages around seed spices. On March 11, 2026, it organized a buyer-seller meeting in Ahmedabad focused on seed spices and highlighted Gujarat’s position as a major producing region and Unjha APMC as one of Asia’s largest seed-spice markets. The event was designed to strengthen connections among growers, exporters and buyers and improve export opportunities for products including cumin.
Stricter import requirements can increase processing costs but also create opportunities for suppliers capable of delivering compliant material consistently. This gradually separates international trade into standard commodity cumin and higher-value products supported by testing, certification, processing, and supply-chain documentation.
Major Market Restraints
Production Concentration and Weather-Driven Supply Volatility
Global cumin availability is highly dependent on India, particularly the production belts of Rajasthan and Gujarat. The crop requires favorable weather during planting, flowering and harvesting, making yields sensitive to temperature, rainfall and unseasonal weather. A poor crop in these states can influence global prices because alternative producing regions do not provide comparable volumes.
Spices Board data shows the scale of this concentration. Rajasthan and Gujarat together accounted for approximately 1.140 million tonnes of India’s estimated 1.143 million tonnes of cumin production in 2025-26. Such concentration exposes processors, exporters and international buyers to localized climatic conditions and changes in planting decisions.
Supply variability also affects working-capital requirements. Processors may increase inventory after harvest to secure raw material, while food manufacturers can experience higher procurement costs when crop conditions tighten availability. Conversely, strong crops can place pressure on farm-gate prices. This agricultural cycle limits the predictability of market value even when underlying consumption grows steadily.
Pesticide-Residue Compliance and Increased Border Controls
Residue compliance has become one of the most important constraints affecting Indian cumin exports to Europe. Commission Implementing Regulation (EU) 2026/194, adopted on January 28, 2026, maintains cumin seeds and crushed or ground cumin from India under increased controls for pesticide residues, with a 30% frequency of identity and physical checks.
India’s Spices Board also operates a monitoring mechanism for cumin exports to the European Union. Its June 2025 circular requires pesticide-residue testing for specified consignments and links export clearance with compliance with applicable EU standards.
Testing, segregation and supply-chain documentation increase costs for exporters, particularly smaller suppliers. Rejected consignments can also create significant financial exposure. The regulatory environment consequently favors integrated processors and exporters with laboratory access, farm-level sourcing controls and established traceability systems.
Market Trends
Ground Cumin Is Expanding Faster Than Whole Seed
Whole cumin remains central to international trade and household consumption, but demand for ground cumin is increasing more rapidly. Food processors and seasoning manufacturers value ground products for their ease of incorporation, dosage consistency and suitability for standardized recipes.
Growth is particularly evident in packaged seasoning mixes, ready meals, snacks, processed meats and sauces. Manufacturers increasingly require specified particle size, moisture and sensory characteristics rather than purchasing undifferentiated ground spice.
Grinding quality is also becoming more important because excessive processing heat can affect aroma. Modern processors therefore use controlled grinding and temperature-management techniques to retain volatile flavor compounds and improve product consistency.
Traceability and Residue-Controlled Supply Are Becoming Purchasing Requirements
Food safety is becoming a more important differentiator in international cumin trade. European controls on Indian cumin illustrate the shift from visual quality grading toward chemical-residue verification and documented supply-chain control.
The European Union’s January 2026 regulation subjects Indian whole and ground cumin to 30% physical and identity checks for pesticide residues. Buyers serving regulated markets consequently place greater emphasis on supplier qualification, testing protocols and traceability.
This trend supports contract sourcing and closer relationships between exporters, processors and growers. Large international customers increasingly seek consistency across multiple harvest seasons rather than relying only on spot-market purchases.
Value Addition Is Increasing Through Processing and Packaging
The cumin value chain is moving beyond raw seed exports through cleaned, graded, ground, sterilized and packaged products. Branded cumin sold in consumer packs captures greater value than bulk agricultural material, while industrial processors can differentiate through purity, microbiological quality and customized grinding specifications.
This trend is particularly relevant in India, where the domestic market is shifting gradually from loose spices toward packaged and branded products. Exporters are also increasing investment in processing and packaging to serve food manufacturers and retailers directly.
International Market Access Is Becoming More Structured
Government and industry initiatives increasingly focus on connecting producers with international buyers and improving compliance with importing-country requirements. The March 2026 Spices Board buyer-seller meeting in Gujarat focused specifically on seed spices and the commercial role of Unjha.
Trade requirements are also broadening beyond Europe. During June 2026, India’s Spices Board issued additional guidance concerning the registration and export of whole spices to China, reflecting the growing importance of formal regulatory access across major destination markets.
Segment Analysis:
By Type
Whole Cumin Seed
Whole cumin seed accounts for approximately 54% of global cumin market value in 2026, making it the largest product type. Whole seeds retain their aroma for longer periods because the essential oil remains protected within the seed until crushing, grinding or cooking. This makes them important in household cooking, traditional foodservice and bulk international trade.
Whole cumin is also easier for buyers to inspect visually for foreign matter and general quality before further processing. Large processors frequently purchase whole seed and conduct cleaning, grading, microbial treatment and grinding according to customer specifications.
The segment remains the largest through 2031, although its share declines toward approximately 50% as ground cumin and cumin-derived products grow more rapidly.
By Application
Food Industry
The food industry accounts for approximately 86% of global cumin market value in 2026 and remains the dominant application throughout the forecast period. Cumin is used across seasoning blends, curry products, meat preparations, savory snacks, ready meals, sauces, bakery products and foodservice recipes.
The broad geographic acceptance of cumin supports stable demand. It is embedded in Indian and Middle Eastern cuisine while also forming an important component of Mexican and Latin American seasoning systems. Industrial food production increases demand for standardized ground products, while restaurants and households continue purchasing both whole and ground forms.
Food applications are projected to reach approximately USD 2.52 billion by 2031. Their percentage share moderates slightly as pharmaceutical, nutraceutical and personal-care applications expand from smaller bases.
By Geography
Asia Pacific
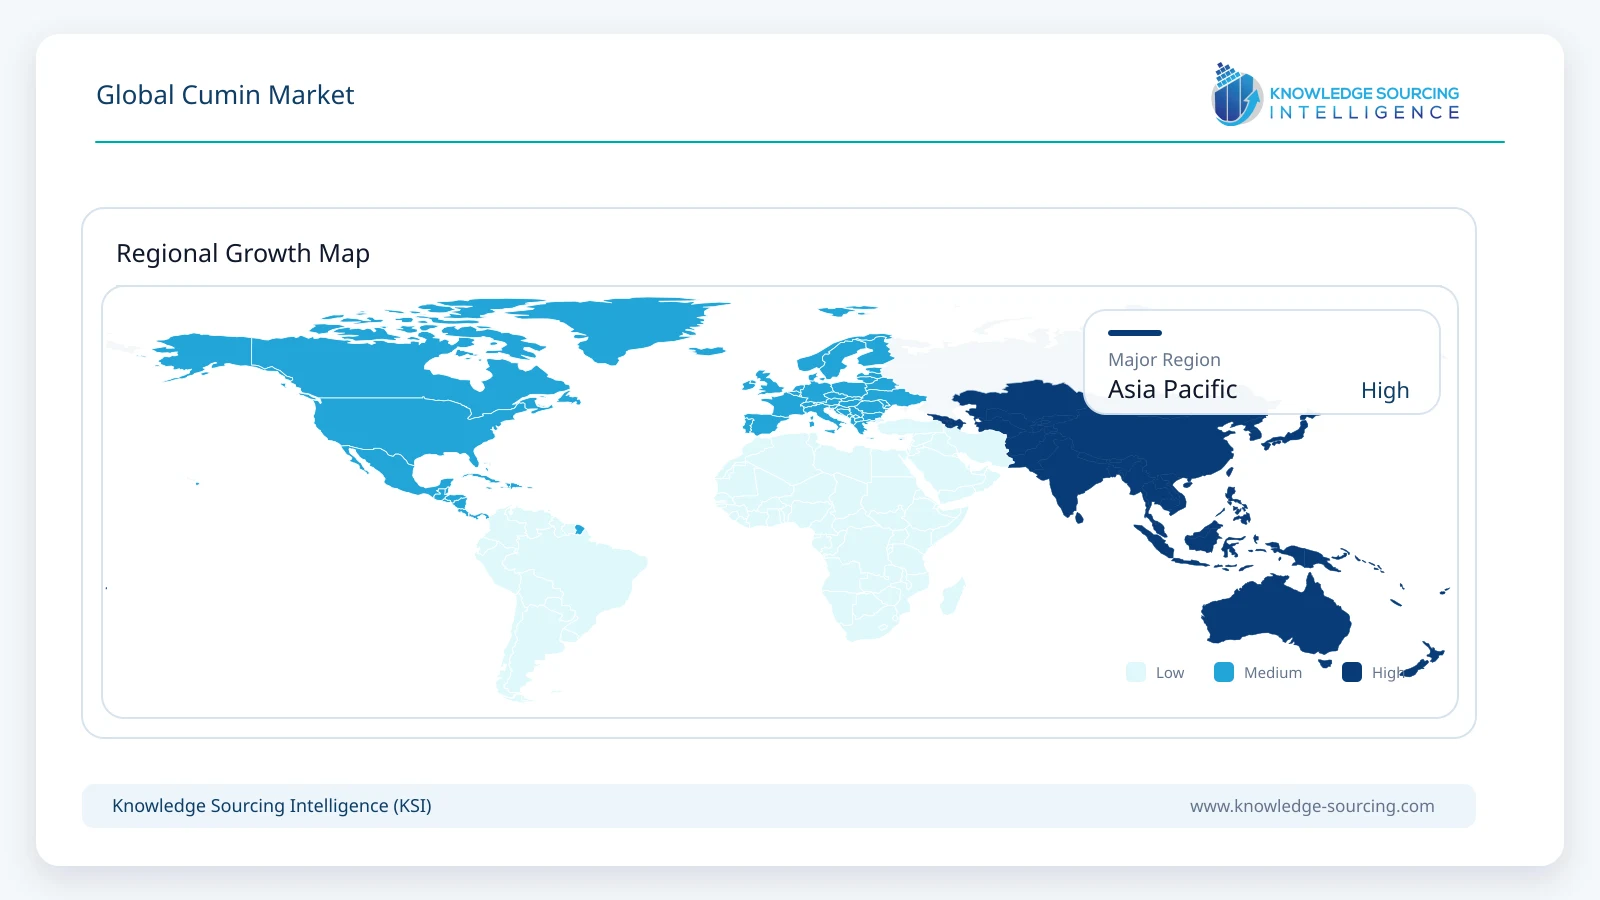
Asia Pacific accounts for approximately 54% of global cumin market value in 2026, making it the largest regional market. India forms the core of both regional consumption and international supply, supported by the extensive production base in Rajasthan and Gujarat and major trading centres such as Unjha.
India’s 2025-26 cumin production is estimated at approximately 1.143 million tonnes, including around 693,939 tonnes from Rajasthan and 446,000 tonnes from Gujarat.
The region also benefits from high household spice consumption, expansion of branded spice products and continued growth in packaged foods. China and Southeast Asian markets provide additional opportunities through food processing and international cuisine adoption.
Asia Pacific is projected to increase to approximately 55% of global cumin market value by 2031, supported by domestic consumption, processing activity and India’s continued role as the principal international supply base.
Competitive Landscape
The cumin industry remains fragmented across growers, agricultural traders, cleaning and processing companies, spice exporters and branded food companies. Competitive positioning depends heavily on access to raw material, purity, residue compliance, microbiological control, processing capacity and relationships with international buyers.
Indian exporters benefit from proximity to Rajasthan and Gujarat production centres and the Unjha trading ecosystem. Companies including Savaliya Agri Commodity Export Pvt. Ltd., Kore Agro International, Abhyuday Industries, Dhaval Agri Exports LLP and Shimla Hills Offerings participate in the processing and export market, while Everest and Badshah operate primarily through branded spice products.
The regulatory environment is increasing the competitive importance of testing and traceability. Companies serving Europe and other highly regulated markets need to maintain pesticide-residue control and documented sourcing systems. Larger processors can also differentiate through value-added ground cumin, customized specifications, private-label packaging and other processed formats.
Recent Developments
June 24, 2026: India’s Spices Board issued a trade advisory for exporters of whole spices to China, strengthening registration and compliance procedures for suppliers targeting the Chinese market.
May 19, 2026: Spices Board production estimates placed India’s 2024-25 cumin crop at approximately 1.143 million tonnes from about 1.543 million hectares.
March 11, 2026: Spices Board India organized a buyer-seller meeting in Ahmedabad focused on seed spices, highlighting Gujarat’s production base and the importance of the Unjha trading market.
January 28, 2026: The European Commission adopted Implementing Regulation (EU) 2026/194, maintaining a 30% frequency of identity and physical checks for pesticide residues on cumin seeds and ground cumin imported from India.
2025-26: India exported 196,800 tonnes of cumin valued at USD 524.22 million, compared with 229,881 tonnes valued at USD 732.35 million during 2024-25.
Market Outlook
Cumin remains a mature agricultural spice category, but growth is supported by wider consumption of international cuisines, expansion in packaged seasoning products and greater use of processed cumin in industrial food manufacturing.
Whole cumin seed remains the largest product type, while ground cumin records stronger growth as food manufacturers prioritize convenience and standardized ingredient specifications. Cumin oil and other derivatives expand faster from a small base but remain niche relative to conventional spice consumption.
Food applications continue to dominate the market, with pharmaceutical, nutraceutical and personal-care applications providing additional opportunities but do not alter cumin’s primary positioning as a food ingredient through 2031.
India remains critical to global supply, making crop conditions in Rajasthan and Gujarat an important determinant of international availability and pricing. Stricter residue controls also increase the value of testing, traceability, and controlled processing. Asia Pacific therefore remains the largest market and supply region through the forecast period.
Cumin Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.5 billion |
| Total Market Size in 2031 | USD 3.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
Market Segmentation
By Type
Whole Cumin Seed
Ground Cumin Seed
Cumin Seed Oil
By Application
Food Industry
Savory Dishes and Seasoning Blends
Bakery Products
Others
Pharmaceutical and Nutraceutical Industry
Cosmetics and Personal Care Industry
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Turkey
Egypt
Others
Asia Pacific
India
China
Japan
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary Research Framework
2.4. Secondary Research Framework
2.5. Data Triangulation
2.6. Forecast Methodology
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Global Expansion of Cumin-Based Cuisines and Industrial Food Formulations
4.1.2. Expansion of Branded and Processed Spice Products
4.1.3. Increasing Demand for Export-Compliant and Traceable Cumin
4.1.4. Growth of Foodservice and Packaged Seasoning Applications
4.2. Market Restraints
4.2.1. Production Concentration in Rajasthan and Gujarat
4.2.2. Weather-Driven Crop and Price Volatility
4.2.3. Pesticide-Residue Testing and Import Compliance Costs
4.2.4. Fragmented Agricultural Supply Chains
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Raw Material and Pricing Analysis
4.7. Government Regulations
4.8. Strategic Recommendations
5. GLOBAL CUMIN MARKET BY TYPE
5.1. Introduction
5.2. Whole Cumin Seed
5.3. Ground Cumin Seed
5.4. Cumin Seed Oil
6. GLOBAL CUMIN MARKET BY APPLICATION
6.1. Food Industry
6.1.1. Savory Dishes and Seasoning Blends
6.1.2. Bakery Products
6.1.3. Others
6.2. Pharmaceutical and Nutraceutical Industry
6.3. Cosmetics and Personal Care Industry
7. GLOBAL CUMIN MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. United Kingdom
7.3.2. Germany
7.3.3. France
7.3.4. Italy
7.3.5. Spain
7.3.6. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. UAE
7.4.3. Turkey
7.4.4. Egypt
7.4.5. Others
7.5. Asia Pacific
7.5.1. India
7.5.2. China
7.5.3. Japan
7.5.4. South Korea
7.5.5. Taiwan
7.5.6. Thailand
7.5.7. Indonesia
7.5.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Savaliya Agri Commodity Export Pvt. Ltd.
9.2. Kore Agro International
9.3. Abhyuday Industries
9.4. Dhaval Agri Exports LLP
9.5. Shimla Hills Offerings
9.6. Moonlite Foods Inc.
9.7. Ashapurna Spices
9.8. Mahavir Spices
9.9. Bhoomi Food and Spices Industry
9.10. Badshah Masala
9.11. Everest Food Products Pvt. Ltd.
9.12. McCormick & Company, Inc.
10. APPENDIX
Navigate
Trusted by the world's leading organizations











