
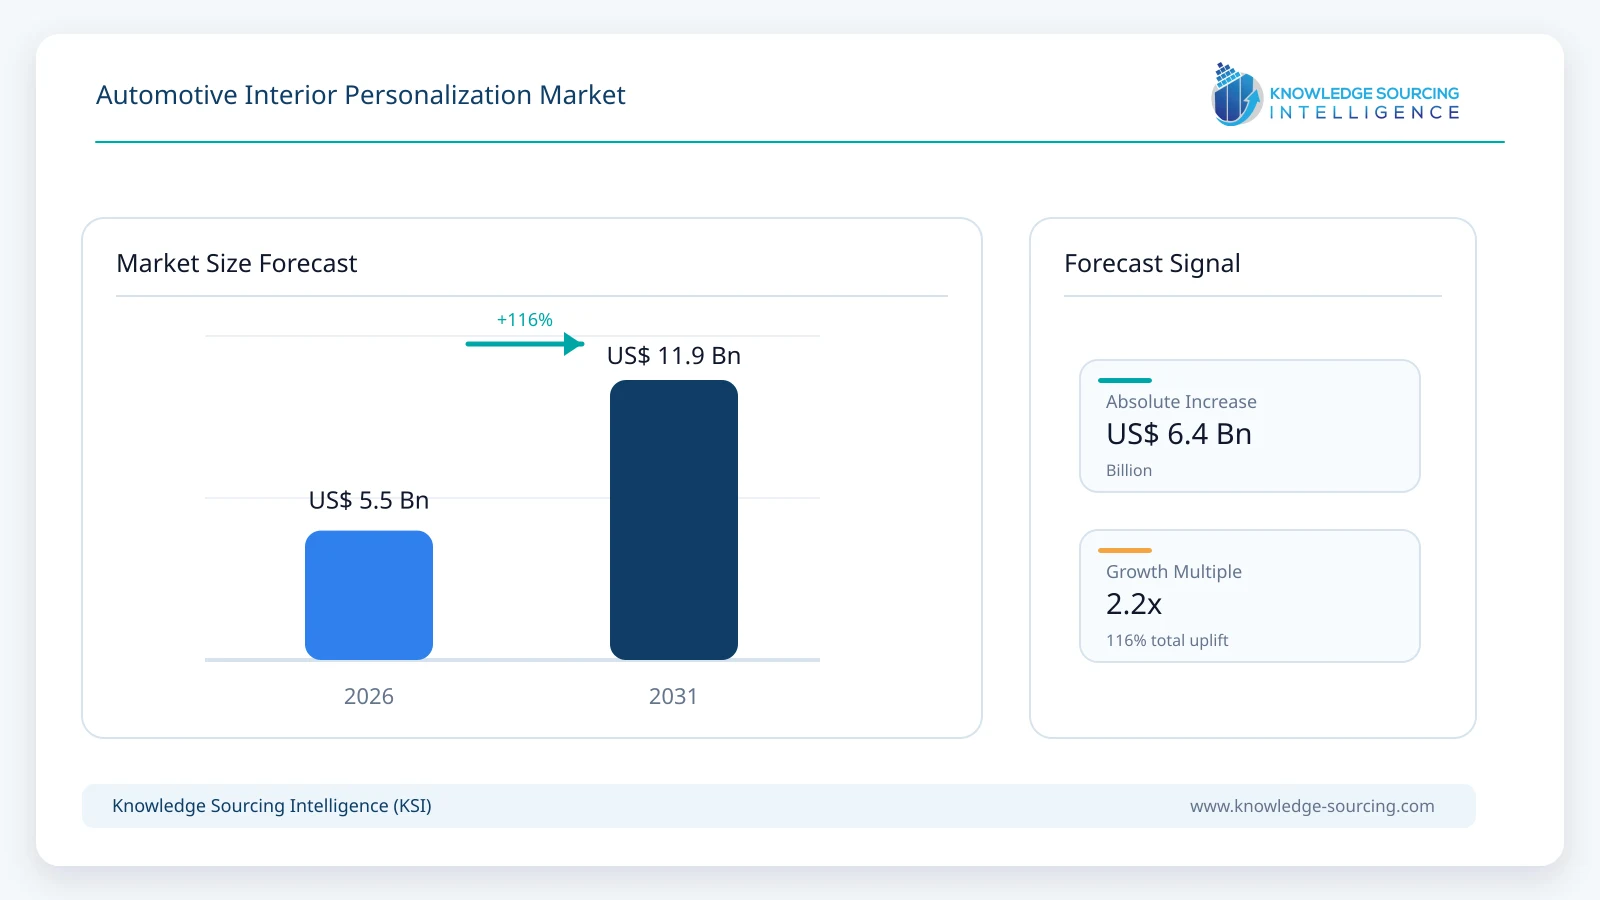
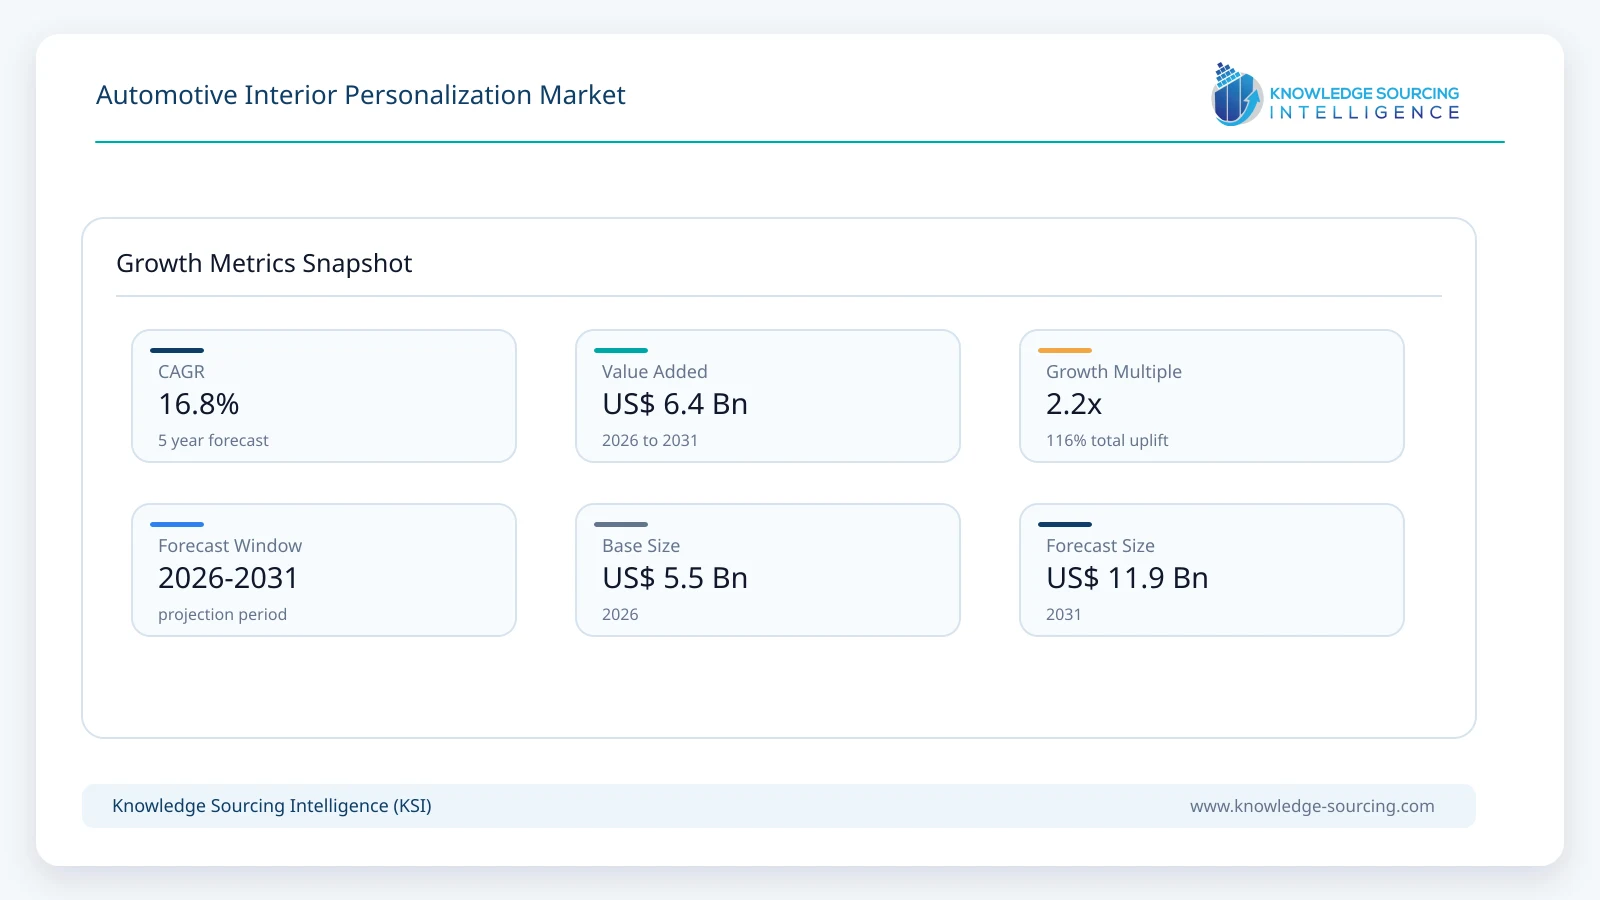
The Automotive Interior Personalization Market is projected to expand at a CAGR of 16.8%, increasing from USD 5.5 billion in 2026 to USD 11.9 billion by 2031.
Highlights:
- 1Comfort and seating personalization represents an estimated 22% of 2026 market value, encompassing qualifying bespoke seating finishes and user-specific seat and comfort settings.
- 2Interior trim and material personalization contributes approximately 25% of 2026 value, reflecting the realized premium from customized cabin surface packages.
- 3Infotainment and connectivity personalization accounts for approximately 22% in 2026 and is expected to gain share as user profiles and display themes become more accessible.
- 4Passenger vehicles generate an estimated 88% of 2026 market value, with high-content premium models and increasingly configurable mainstream vehicles supporting demand.
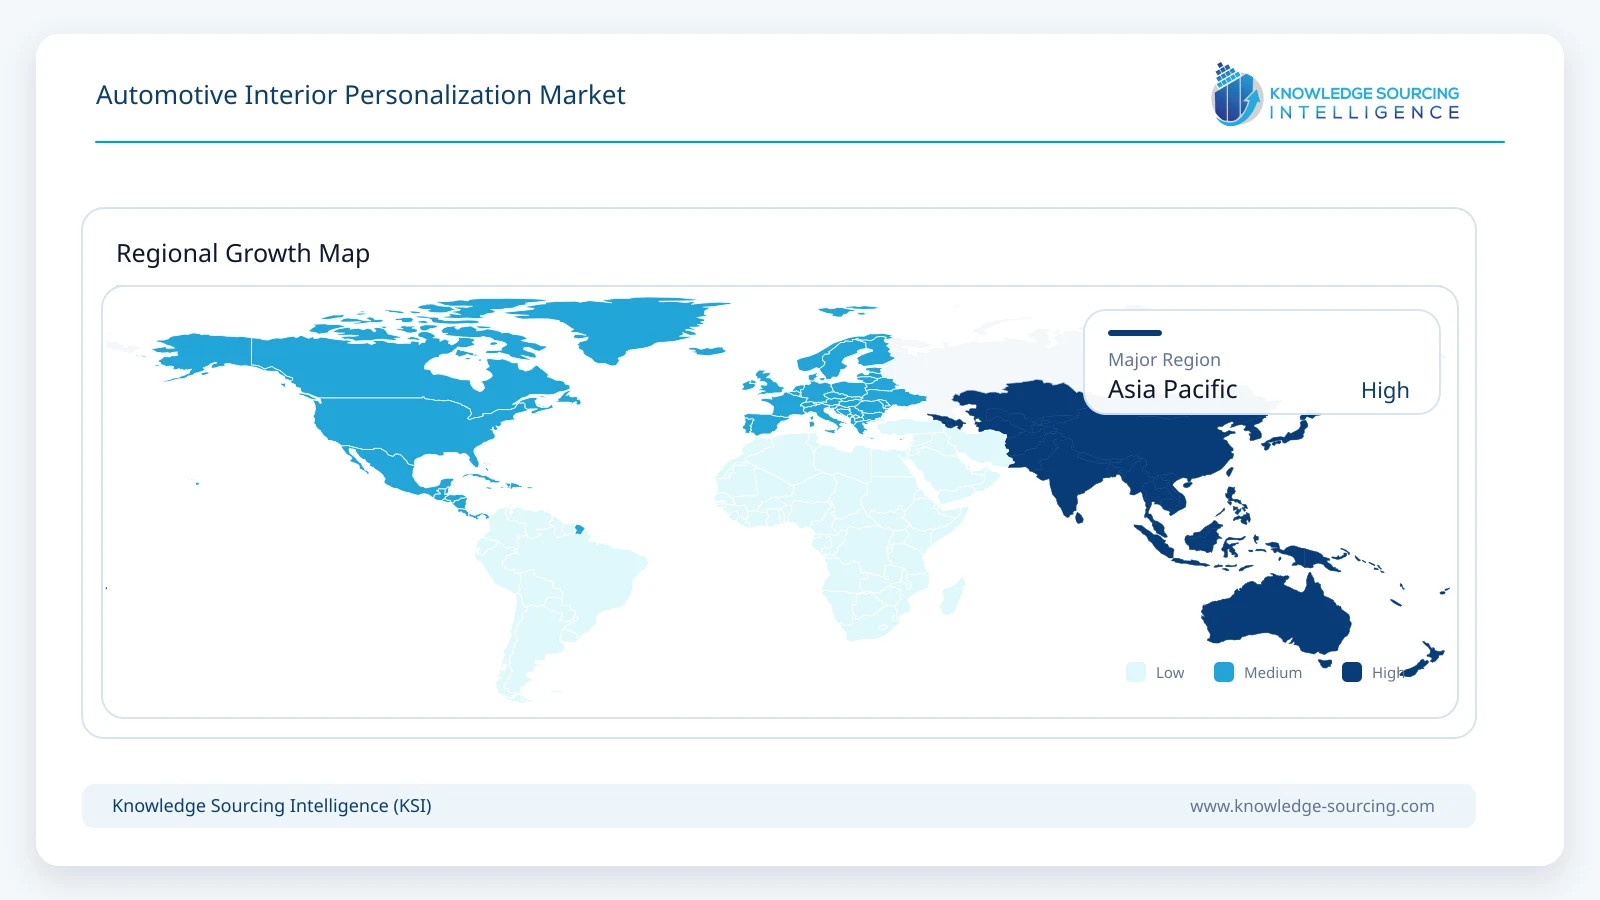
- 5Asia Pacific is estimated to account for 43% of global value in 2026, while Europe remains important for premium materials and bespoke specification programs.
- 6AI and adaptive personalization are projected to gain within the enabling-technology mix, although user profiles and fixed design packages remain important throughout the forecast period.
Interior personalization includes the added value of optional upholstery and decorative variants, programmable cabin interfaces, retained occupant preferences, and individualized comfort or sensory controls. Demand is concentrated in passenger vehicles, where automakers use customized interiors to distinguish premium models and higher-content versions of mainstream vehicles.
Physical specification and software-led customization increasingly appear together in the same vehicle programs. The 2026 BMW 7 Series combines BMW Individual leather and interior finishes with customizable BMW Operating System X displays and identity-linked settings. Porsche Cayenne Electric offers a broad selection of interior combinations, decorative accents, and screen themes, while Lexus uses Sensory Concierge to coordinate lighting and fragrance. These examples show how factory-selected cabin materials and software-adjustable functions can jointly shape customer value without requiring a completely different vehicle platform.
Market Overview
Personalization starts before vehicle delivery when buyers select upholstery materials, stitching, trim treatments, color palettes and cabin packages from an automaker configuration system. Mercedes-Benz MANUFAKTUR and BMW Individual demonstrate the role of factory-approved design programs in premium automobiles. Standardized option architectures enable suppliers to combine distinctive surfaces with shared underlying seat, door and cockpit structures. Such programs increase the value of interior specification while imposing tighter requirements for material matching, validation and production scheduling.
Occupant-adjustable personalization extends cabin differentiation into daily vehicle use. Individual accounts, keys and smartphones can recall seat positions and preferred interface settings; programmable lighting, displays and audio then provide additional choices without changing physical hardware. BMW Panoramic iDrive and Porsche Digital Interaction bring user-selectable themes to central displays, while HARMAN develops personal listening zones for cabins occupied by multiple passengers. The commercial contribution comes from feature software, controls and attributable customized content rather than from the full value of the connected displays and sound systems.
The distinction between static and dynamic customization affects supplier economics. Decorative surface variants generate material, tooling and manufacturing revenue, whereas profile-based cabin functions require embedded software, calibration and system integration. Interior suppliers including Yanfeng, FORVIA, Lear and Toyota Boshoku participate through configurable components and integrated cabin technology. Electronics and audio specialists participate through narrower technologies, leaving automakers responsible for coordination and a consistent occupant experience.
Automotive production also establishes the scale over which personalization features can spread. OICA reported 96.4 million vehicles manufactured globally in 2025, with production increasingly concentrated in Asia. High-volume vehicle programs can support greater personalization penetration when the additional per-vehicle cost remains contained. The commercial value of customization nevertheless varies widely between basic display profiles and high-priced bespoke upholstery or multi-function cabin options.
Market Trends
Factory-Customized Materials Are Being Integrated with Digital Themes
Porsche Cayenne Electric combines differentiated upholstery and decorative interior selections with a Themes application that changes the visual appearance of several cabin displays. BMW 7 Series likewise offers BMW Individual trim combinations alongside customizable interface colors, widgets, and account-specific settings. Consistent color and design coordination between digital and physical surfaces gives automakers a stronger differentiation proposition than standalone upholstery or wallpaper choices. Interior suppliers must therefore align physical material programs with the evolving requirements of electronics and interface teams.
Factory configuration remains the principal purchasing route for high-value material upgrades because premium upholstery and décor normally enter the vehicle during production. Digital themes provide greater flexibility after delivery, but software-related revenue depends on how the feature is priced and packaged. The combined approach supports coordinated design programs without implying that all personalization functions create recurring subscription sales.
Multi-Occupant Profiles Are Extending Beyond the Driver
Connected vehicles increasingly need to accommodate multiple occupant preferences within one shared cabin. BMW Operating System X supports identifiable user accounts, while HARMAN Ready StreamShare enables individual media zones alongside shared listening and cabin communication. These capabilities address the differing needs of drivers, front-seat passengers and rear-seat occupants, particularly in family and premium vehicles. Software and control interfaces become more important as personalization expands from the driver to the entire cabin.
Personalization across seats, audio, displays and climate introduces requirements for occupant recognition, default behavior and secure preference storage. Reliable operation is particularly important when several users enter the same vehicle or when internet connectivity is unavailable. Automotive manufacturers consequently need robust onboard profile handling rather than assuming every function can depend on cloud services.
Adaptive Sensory Environments Are Developing in Higher-Value Vehicles
Lexus introduced Sensory Concierge for the new NX in September 2026, using configurable cabin lighting and fragrance to shape the interior atmosphere. Yanfeng XiM27 demonstrates a broader approach combining seating, audio, climate and adaptive lighting within a scenario-driven cabin concept. The new NX announcement concerns a vehicle planned for introduction from late 2026, while XiM27 is a functional concept rather than evidence of confirmed full-scale production fitment. Different commercialization stages should remain visible when assessing the growth outlook for advanced personalized environments.
More coordinated functions can raise engineering and integration value even when the underlying lighting and HVAC systems are already present. Premium vehicle lines are likely to adopt multi-function sensory profiles earlier because higher equipment prices support additional software and hardware complexity. Mainstream diffusion depends on modular control architectures, customer usability and the ability to reuse existing actuators and electronics.
Segment Analysis
By Personalization Type: Interior Trim and Material Personalization
Interior trim and material personalization accounts for approximately 25% of automotive interior personalization market value in 2026. The segment includes qualifying premiums for specified upholstery, stitching, dashboard inserts, door-surface finishes and other approved cabin options. The largest gains arise where manufacturers offer a coordinated material package rather than isolated components. Mercedes-Benz MANUFAKTUR, BMW Individual and Porsche Exclusive Manufaktur demonstrate the continuing commercial role of carefully differentiated interior materials in premium vehicle purchasing.
Materials-based customization is expected to expand in absolute value through 2031, although the segment may lose share to faster-growing digital and coordinated comfort functions. Individualized interiors require additional inventory control, surface qualification and manufacturing discipline, limiting the economics of very large variant lists. Flexible trim technologies and modular decorative inserts can reduce the cost of offering design choices across shared vehicle platforms.
By Personalization Type: Infotainment and Connectivity Personalization
Infotainment and connectivity personalization represents approximately 22% of the 2026 market and is expected to account for a larger share in 2031. Saved media preferences, screen themes, personalized content, linked accounts and configurable vehicle applications contribute to the category. Porsche Digital Interaction and BMW Operating System X show that software-driven customization can alter cabin appearance and user interaction without changing display hardware. Vehicle-wide profile architectures support growing penetration as connected cockpit systems expand through mid-range passenger models.
The commercial trajectory depends on dependable account management, interface integration and a clear distinction between standard functionality and separately priced customization. HARMAN individualized audio technology broadens the potential range of passenger-specific digital services. Manufacturers that can deploy common software components across multiple model lines are better positioned to manage upgrade costs and support personalized experiences over the vehicle life cycle.
By Technology: AI and Adaptive Personalization
AI, machine-learning and adaptive personalization technologies form an emerging share of the market because production implementations remain less widespread than stored profiles, selection-based settings and static trim packages. Yanfeng XiM27 illustrates AI-adaptive seating and personalized environmental controls, while Lexus Sensory Concierge demonstrates a coordinated sensory approach without necessarily relying on predictive learning. The distinction matters because an adaptive cabin experience is not automatically an AI-powered product. Demand should increase as automakers add context awareness and preference learning to established control architectures.
Automotive AI personalization requires reliable interaction between occupant inputs and existing vehicle controllers. Profile security, false personalization triggers and ease of manual override can determine customer acceptance. Higher-value deployments are most likely where suppliers can use common software interfaces for seats, lighting, climate, infotainment and audio, limiting the need for dedicated hardware in every function.
By Vehicle Type: Passenger Vehicles
Passenger vehicles account for an estimated 88% of automotive interior personalization value in 2026 because passenger-car manufacturers sell the largest range of design, comfort and entertainment options. Premium sedans, SUVs and electric crossovers carry high specification values, while connected features are spreading through upper trims of mainstream vehicles. The wider availability of configurable display themes and seat-memory settings supports penetration beyond luxury models. Commercial vehicles participate mainly through driver profiles, seating comfort and infotainment customization, with fewer opportunities for bespoke decorative packages.
Battery electric vehicles are important to the adoption of programmable cabin functions, but propulsion is not a separate vehicle-type category. Electric passenger cars and electric commercial vehicles remain within their respective vehicle classes. Automakers can position interior personalization as part of an electric-model identity, particularly when software-defined control and large digital interfaces are already standard vehicle features.
Market Drivers
Expansion of Factory-Configured Cabin Variants
Automakers are offering broader interior color, upholstery, trim and design-package choices on shared vehicle platforms. The 2026 BMW 7 Series combines BMW Individual Merino leather selections with configurable digital interfaces, while Porsche Cayenne Electric offers multiple interior, accent and trim options. Each additional combination can increase revenue from higher-value specification packages, provided suppliers can manage color matching and manufacturing complexity. Increasing variation in higher-volume premium trims therefore supports personalization value without a proportional increase in complete vehicle production.
Growth of Linked Driver and Occupant Profiles
BMW Operating System X and established connected cockpit architectures allow driver preferences to persist across multiple vehicle functions. Linked profiles reduce the need to reset seat positions, display layouts, audio preferences and climate settings whenever a shared vehicle changes occupants. Automotive suppliers benefit when a common profile architecture controls several cabin functions rather than a single dedicated feature. Wider profile adoption supports software and integration revenue while giving manufacturers a practical way to differentiate equipment grades.
Migration of Premium Features into Higher-Volume Vehicles
Mainstream connected vehicles increasingly offer configurable ambient lighting, instrument themes, saved user profiles and differentiated interior décor packages. Standardized controllers and software reuse reduce the incremental engineering needed to introduce these functions across several trims. The move is not uniform because lower-cost vehicles remain sensitive to additional materials, embedded electronics and validation expense. Penetration growth is therefore expected to come from upper mainstream trims first, followed by selective deployment in broader passenger-vehicle programs.
Integration of Personalized Sensory and Comfort Functions
Lexus Sensory Concierge and HARMAN personal audio technology demonstrate a shift from isolated choices to coordinated cabin environments. Lighting, fragrance, audio, seat settings and climate controls can be adjusted individually or through stored scenes according to occupant preferences. Multi-function personalization creates additional integration work at the system and software level, although the complete value of seats, HVAC units and loudspeakers does not belong to this market. Suppliers with cross-domain experience are positioned to capture more personalization-related design content.
Software-Defined Interfaces and Update Capability
A programmable cockpit allows automakers to refresh themes, widgets, infotainment preferences and selected software-enabled cabin functions after the vehicle has left the factory. Porsche screen themes and BMW user-specific displays illustrate software customization layered on standardized hardware. Over-the-air functions improve the economic life of personalization software, but customers still need clear benefits and stable operation. The combination of persistent accounts and reusable digital services supports higher recurring development and integration expenditure through 2031.
Market Restraints
Fragmented Configurations and Manufacturing Complexity
Increasing interior design variants multiplies the number of upholstery, décor, stitching, surface-finish and interface combinations that manufacturers must develop and validate. Color-harmony requirements and supplier coordination can become difficult when several regional plants build the same vehicle. Excessive choice also increases inventory exposure and the risk of slow-moving variants. Automotive manufacturers consequently limit combinations or package options together, constraining the breadth of customization available in mass-market vehicles.
Privacy, Consent and Profile Portability Requirements
Identity-linked personalization may use account data, behavioral preferences, voice interactions and in some cases cabin sensing. Privacy rules require appropriate consent, transparent handling and secure processing of personal information. Profile portability across vehicles and drivers adds further account-management and software-maintenance complexity. OEMs that cannot demonstrate reliable consent controls may have to restrict features or operate them locally, reducing the value of cross-vehicle personalization.
Cost and Fitment Constraints in Entry-Level Segments
Decorative stitching, additional trim materials, illuminated surfaces and richer cockpit controls raise per-vehicle content cost. Many entry-level buyers prioritize safety, core connectivity and operating expense over individualized interior details. A profitable configuration must therefore balance a visible customer benefit with manageable tooling, material and software costs. The cost barrier is greatest where suppliers lack platform reuse or where low equipment take rates limit economies of scale.
Cross-Domain Integration and Functional Reliability
A single personalization profile may need to command seats, climate, lighting, displays, media and occupant-identification subsystems supplied by different vendors. Interfaces must handle incomplete user profiles, multiple passengers, connectivity interruptions and vehicle safety states without inconsistent behavior. New integrated demonstrations do not automatically indicate production fitment at scale. Integration and validation requirements can delay deployment even when the individual cabin features are technically mature.
Uncertain Monetization of Digital Customization
Automakers can offer software themes, profile settings and audio experiences either as standard features, paid packages or post-sale upgrades. Consumer willingness to pay for visual changes alone is less certain than demand for tangible comfort or premium materials. Software subscriptions may face resistance when customers regard personalization as an included vehicle function. The forecast therefore depends more on equipment penetration and attributable content value than on speculative recurring digital purchases.
Regional Outlook
Asia Pacific
Asia Pacific is estimated to account for approximately 43% of the automotive interior personalization market in 2026, supported by high vehicle-manufacturing activity and demand for connected passenger cabins. China combines large vehicle production with strong competition in electric and digitally equipped passenger vehicles, encouraging manufacturers to expand display themes, lighting profiles and multi-occupant digital features. Japan and South Korea support advanced interior technology development through established automotive electronics and cabin-component supplier networks. India provides a longer-term opportunity as connected convenience features spread through higher-value passenger-vehicle trims.
Supplier activity in Asia Pacific also covers integrated cabin systems and design materials. Yanfeng is developing scenario-driven occupant experiences, while Toyota Boshoku and other regional suppliers participate in seat, trim and interior integration. The regional market is projected to retain the largest share through 2031, although equipment take rates and per-vehicle personalization values differ considerably between premium electric vehicles and cost-sensitive mass-market passenger models.
Europe
European demand is supported by premium automakers offering a wide variety of upholstery, surface finishes, interior accent packages and configurable vehicle functions. BMW Individual, Mercedes-Benz MANUFAKTUR and Porsche Exclusive Manufaktur provide established routes for higher-value factory personalization. BMW and Porsche are also integrating user-selectable interface themes, profiles and coordinated cabin settings into contemporary vehicle generations. The combination of craftsmanship-led design programs and digital personalization supports comparatively high specification values per equipped vehicle.
European suppliers face pressure to control the manufacturing complexity associated with numerous interior options. Modular decorative systems, digital order configuration and standardized software components can improve the economics of personalizing different vehicles from common architectures. Privacy and software-security requirements also influence the development of identity-linked accounts and connected cabin functions, especially when driver preferences are synchronized between vehicles.
Competitive Landscape
The automotive interior personalization market includes suppliers of configurable seating, decorative materials, illuminated surfaces, cockpit software, passenger audio and multi-function integration. FORVIA, Yanfeng, Lear, Toyota Boshoku, Adient, Antolin and DRÄXLMAIER participate through interior components and surface technologies, while HARMAN, Visteon and Panasonic Automotive address digital interfaces and personalized cabin features. Gentherm focuses on thermal comfort systems and Novem participates in premium decorative trim. Competition reflects the different roles of material suppliers, integrators and electronics specialists rather than a single homogeneous supplier group.
Yanfeng XiM27 demonstrates a multi-function integration direction by combining personalized seating and cabin environmental controls with other smart-interior technologies. HARMAN offers a more focused position in individualized audio and connected user experiences. The supplier strategies differ in commercialization maturity, and concept-level integration should not be interpreted as evidence of equivalent volume production. Automakers retain substantial control over brand-specific user interfaces, material choices and the final cabin experience.
Supplier differentiation increasingly depends on controlling variation without sacrificing cost, durability or reliability. Materials suppliers need production-grade appearance consistency, while software suppliers need secure profiles and predictable behavior across several vehicle platforms. Companies that can provide validated components with flexible design or interoperable control architectures should be better positioned to serve both factory-customized interiors and increasingly programmable cabins.
Recent Developments
September 2026: Porsche widened Cayenne Electric interior personalization with the Extended Interior Style Package, including further upholstery and decorative-stitching choices; premium custom-trim content can grow independently of software features.
September 2026: Lexus announced the new NX with Sensory Concierge, coordinating interior lighting and fragrance; the development supports integrated sensory customization, while rollout is scheduled to begin from late 2026.
June 2026: Yanfeng unveiled XiM27, a functioning production-ready concept with AI-adaptive seats and individually managed cabin conditions; the platform illustrates supplier capability, not confirmed series-program revenue.
April 2026: BMW presented the updated 7 Series with BMW Individual Merino interior options and Operating System X identity-linked themes, demonstrating physical and digital customization in the same nameplate.
January 2026: HARMAN introduced personalized, software-driven in-car audio technologies and Ready StreamShare for individualized and shared listening; the announcement expands OEM-ready software functionality.
September 2025: Porsche detailed the Cayenne Electric with differentiated interior color packages, decorative materials and screen-theme choices, connecting build-time design options with user-adjustable digital appearance.
Market Outlook
Automotive interior personalization is projected to extend from high-priced material packages and individual seat-memory functions into a broader combination of design, comfort, digital interface and sensory choices. Interior trim and seating packages should remain important sources of revenue, while connected profiles, infotainment themes and adaptive personalization gain share. Factory-selected décor and software-led customization will continue to coexist because consumers use both methods to differentiate their vehicles.
Asia Pacific is expected to remain the largest regional market as connected features spread across a substantial vehicle production base. European premium manufacturers are likely to preserve high per-vehicle value through coordinated materials and factory configuration, alongside growing digital personalization. Product strategies will need to accommodate different customer spending patterns across high-volume and luxury vehicle segments.
The competitive position of suppliers will depend on validated surface options, interoperable cabin-control software and disciplined management of personalization variants. Personalization packages that combine useful comfort functions with configurable interface and trim choices are better placed to command incremental value than cosmetic features offered in isolation. Through 2031, growth will depend on penetration and actual buyer acceptance rather than on the availability of customization technology alone.
Automotive Interior Personalization Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.5 billion |
| Total Market Size in 2031 | USD 11.9 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 16.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Personalization Type, Primary Technology / Delivery, Vehicle Type, Propulsion |
| Companies |
|
Market Segmentation
By Personalization Type
Comfort and Seating Personalization
Ambient Lighting Personalization
Infotainment and Connectivity Personalization
Climate-Control Personalization
Interior Trim and Material Personalization
Voice, Gesture and HMI Personalization
By Primary Technology / Delivery
Physical Specification and Decorative Customization
Sensor- and Rule-Based Personalization
Cloud-Connected Profile and Personalization Services
AI, Machine-Learning and Adaptive Personalization
By Vehicle Type
Passenger Vehicles
Light Commercial Vehicles
Medium And Heavy Commercial Vehicles
By Propulsion
Internal Combustion and Mild-Hybrid Vehicles
Hybrid and Plug-In Hybrid Vehicles
Battery Electric Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Israel
Others
Asia Pacific
China
India
South Korea
Taiwan
Thailand
Indonesia
Japan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of Factory-Configured Cabin Variants
3.1.2. Growth of Linked Driver and Occupant Profiles
3.1.3. Migration of Premium Features into Higher-Volume Vehicles
3.1.4. Integration of Personalized Sensory and Comfort Functions
3.1.5. Software-Defined Interfaces and Update Capability
3.2. Market Restraints
3.2.1. Fragmented Configurations and Manufacturing Complexity
3.2.2. Privacy, Consent and Profile Portability Requirements
3.2.3. Cost and Fitment Constraints in Entry-Level Segments
3.2.4. Cross-Domain Integration and Functional Reliability
3.2.5. Uncertain Monetization of Digital Customization
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Factory Design and Configuration Systems
4.2. User Identity and Saved Preference Management
4.3. Sensor and Rule-Based Cabin Control
4.4. Connected Profile Synchronization
4.5. AI and Context-Aware Personalization
4.6. Cross-Domain Cabin Experience Integration
5. AUTOMOTIVE INTERIOR PERSONALIZATION MARKET BY PERSONALIZATION TYPE
5.1. Introduction
5.2. Comfort and seating personalization
5.3. Ambient lighting personalization
5.4. Infotainment and connectivity personalization
5.5. Climate-control personalization
5.6. Interior trim and material personalization
5.7. Voice, gesture and HMI personalization
6. AUTOMOTIVE INTERIOR PERSONALIZATION MARKET BY PRIMARY TECHNOLOGY / DELIVERY
6.1. Introduction
6.2. Physical specification and decorative customization
6.3. Sensor- and rule-based personalization
6.4. Cloud-connected profile and personalization services
6.5. AI, machine-learning and adaptive personalization
7. AUTOMOTIVE INTERIOR PERSONALIZATION MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Passenger Vehicles
7.3. Light Commercial Vehicles
7.4. Medium And Heavy Commercial Vehicles
8. AUTOMOTIVE INTERIOR PERSONALIZATION MARKET BY PROPULSION
8.1. Introduction
8.2. Internal combustion and mild-hybrid vehicles
8.3. Hybrid and plug-in hybrid vehicles
8.4. Battery electric vehicles
9. AUTOMOTIVE INTERIOR PERSONALIZATION MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Personalization Type
9.2.2. By Vehicle Type
9.2.3. By Technology
9.2.4. By Country
9.2.4.1. United States
9.2.4.2. Canada
9.2.4.3. Mexico
9.3. South America
9.3.1. By Personalization Type
9.3.2. By Vehicle Type
9.3.3. By Technology
9.3.4. By Country
9.3.4.1. Brazil
9.3.4.2. Argentina
9.3.4.3. Others
9.4. Europe
9.4.1. By Personalization Type
9.4.2. By Vehicle Type
9.4.3. By Technology
9.4.4. By Country
9.4.4.1. Germany
9.4.4.2. France
9.4.4.3. United Kingdom
9.4.4.4. Spain
9.4.4.5. Others
9.5. Middle East and Africa
9.5.1. By Personalization Type
9.5.2. By Vehicle Type
9.5.3. By Technology
9.5.4. By Country
9.5.4.1. Saudi Arabia
9.5.4.2. United Arab Emirates
9.5.4.3. Israel
9.5.4.4. Others
9.6. Asia Pacific
9.6.1. By Personalization Type
9.6.2. By Vehicle Type
9.6.3. By Technology
9.6.4. By Country
9.6.4.1. China
9.6.4.2. India
9.6.4.3. South Korea
9.6.4.4. Taiwan
9.6.4.5. Thailand
9.6.4.6. Indonesia
9.6.4.7. Japan
9.6.4.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Yanfeng Automotive Interiors
11.2. FORVIA
11.3. Lear Corporation
11.4. Toyota Boshoku Corporation
11.5. Adient plc
11.6. Antolin
11.7. DRÄXLMAIER Group
11.8. HARMAN International
11.9. Gentherm Incorporated
11.10. Visteon Corporation
11.11. Panasonic Automotive Systems
11.12. Novem Group
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits to Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











