Automotive Dashboard Market Trends, Size & Growth By Dashboard Architecture (Conventional Instrument-Panel Dashboards, Electronics-Ready and Smart-Surface Dashboards, Display-Dominant and Minimalist Dashboards), Integrated Content (Substrate, Carrier and Structural Interfaces, Surface, Skin and Decorative Trim, Display and HMI Integration, Air Vent and HVAC Interfaces, Passenger-Airbag and Safety Interfaces, Storage, Glove Box and Utility Integration), Surface Type (Hard-Molded Dashboards, Soft-Touch and Premium Surfaced Dashboards, Smart and Illuminated Functional Surfaces), Material Platform (Polymer and Polymer-Composite Assemblies, Natural-Fiber and Sustainable Composite Assemblies, Premium Multi-Material Assemblies), Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, Buses and Specialty Vehicles), and Geography
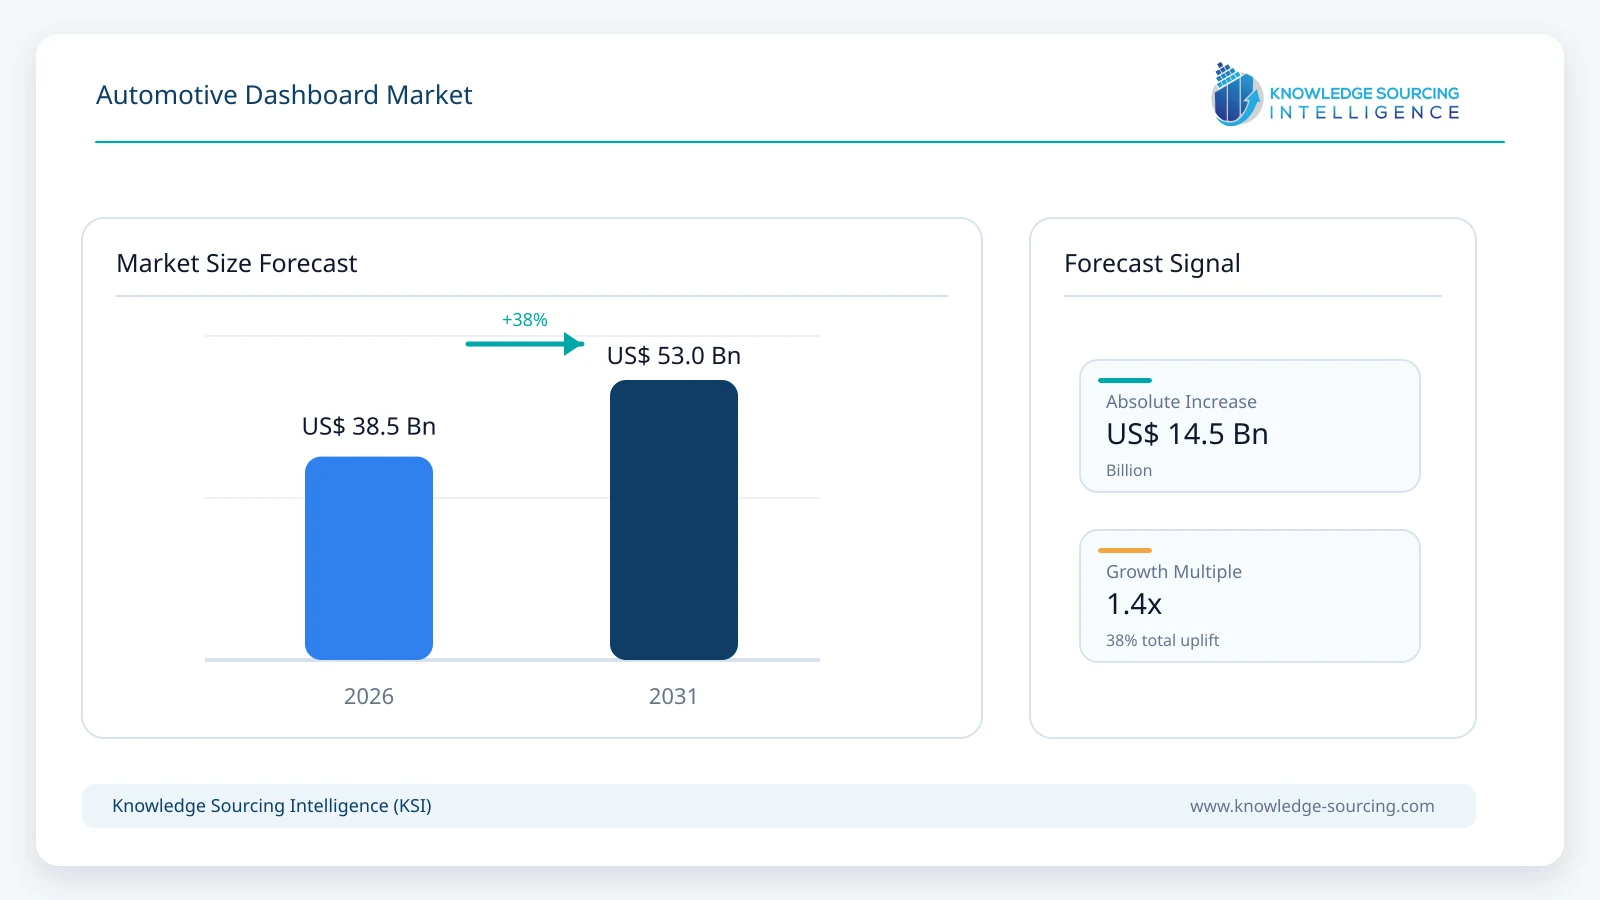
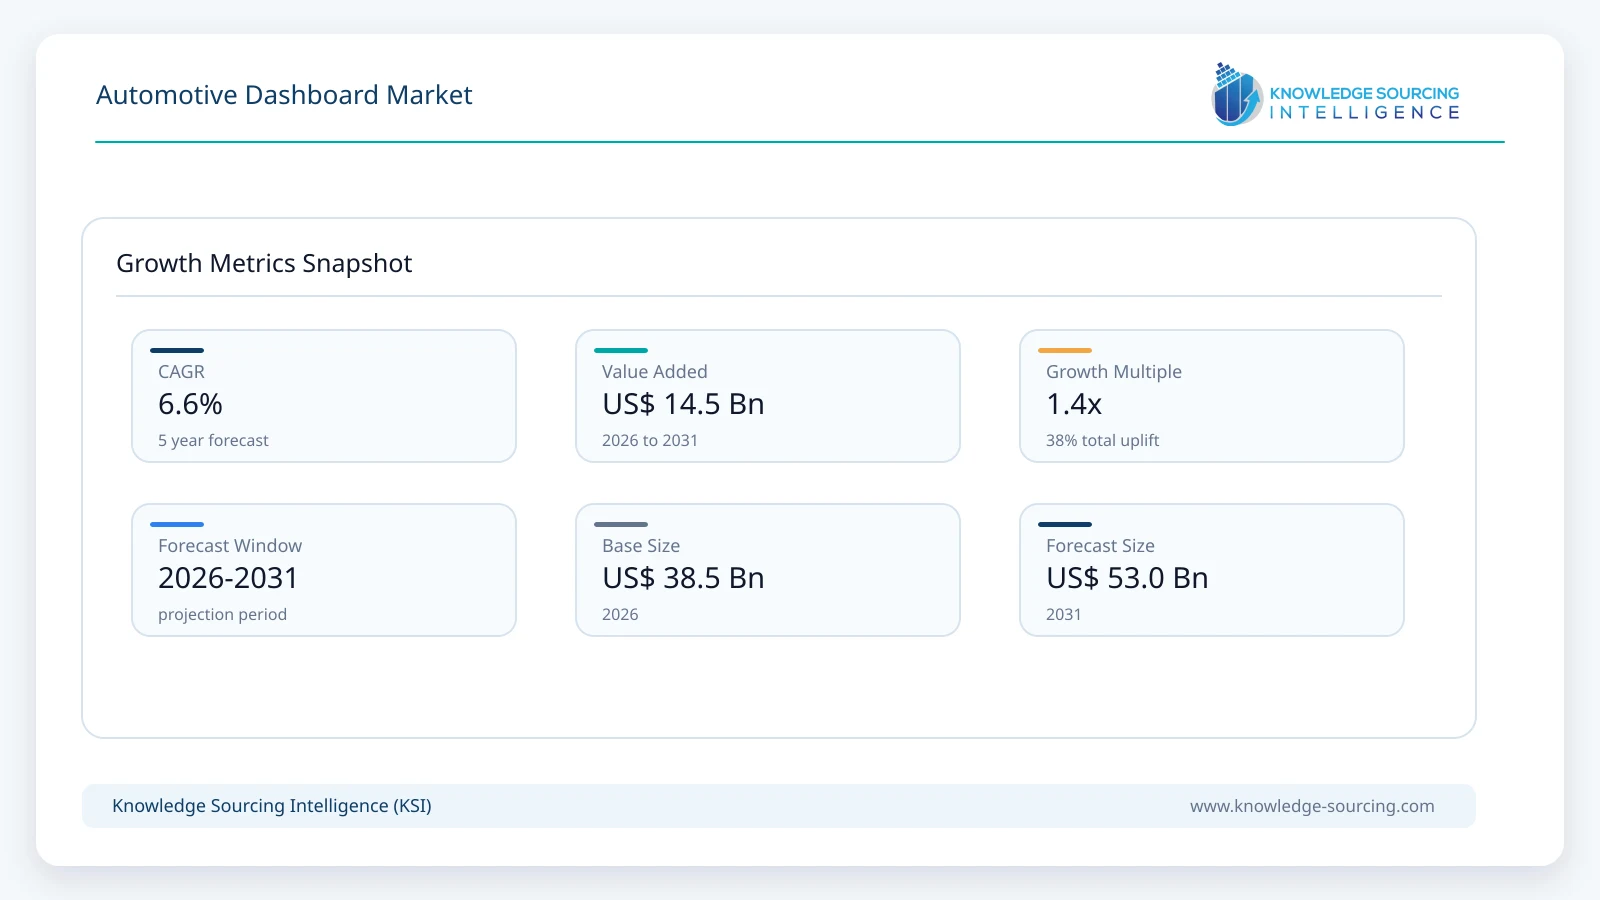
The automotive dashboard market is forecast to grow at a CAGR of 6.6%, reaching approximately USD 53.0 billion by 2031 from USD 38.5 billion in 2026.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Key Highlights
• Electronics-ready and smart-surface dashboards account for approximately 52% of global market value in 2026 as displays, hidden controls, ambient lighting and integrated HMI migrate into the instrument-panel surface.
• Dashboard substrates, carriers and structural interfaces represent approximately 35% of 2026 market value because every instrument panel requires a rigid load-bearing architecture for displays, vents, glove boxes, trim and passenger-airbag integration.
• Soft-touch and premium surfaced dashboards account for approximately 43% of market value in 2026, supported by increasing use of foamed skins, wrapped surfaces, decorative films and high-quality grains across mid-range and premium vehicles.
• Polymer and polymer-composite dashboard assemblies represent approximately 74% of global market value in 2026 due to the dominance of injection-molded thermoplastics, foamed substrates, natural-fiber composites and decorated polymer surfaces.
• Passenger vehicles account for approximately 94% of global market value in 2026 because dashboards are most feature-rich in passenger cars, SUVs, crossovers and MPVs.
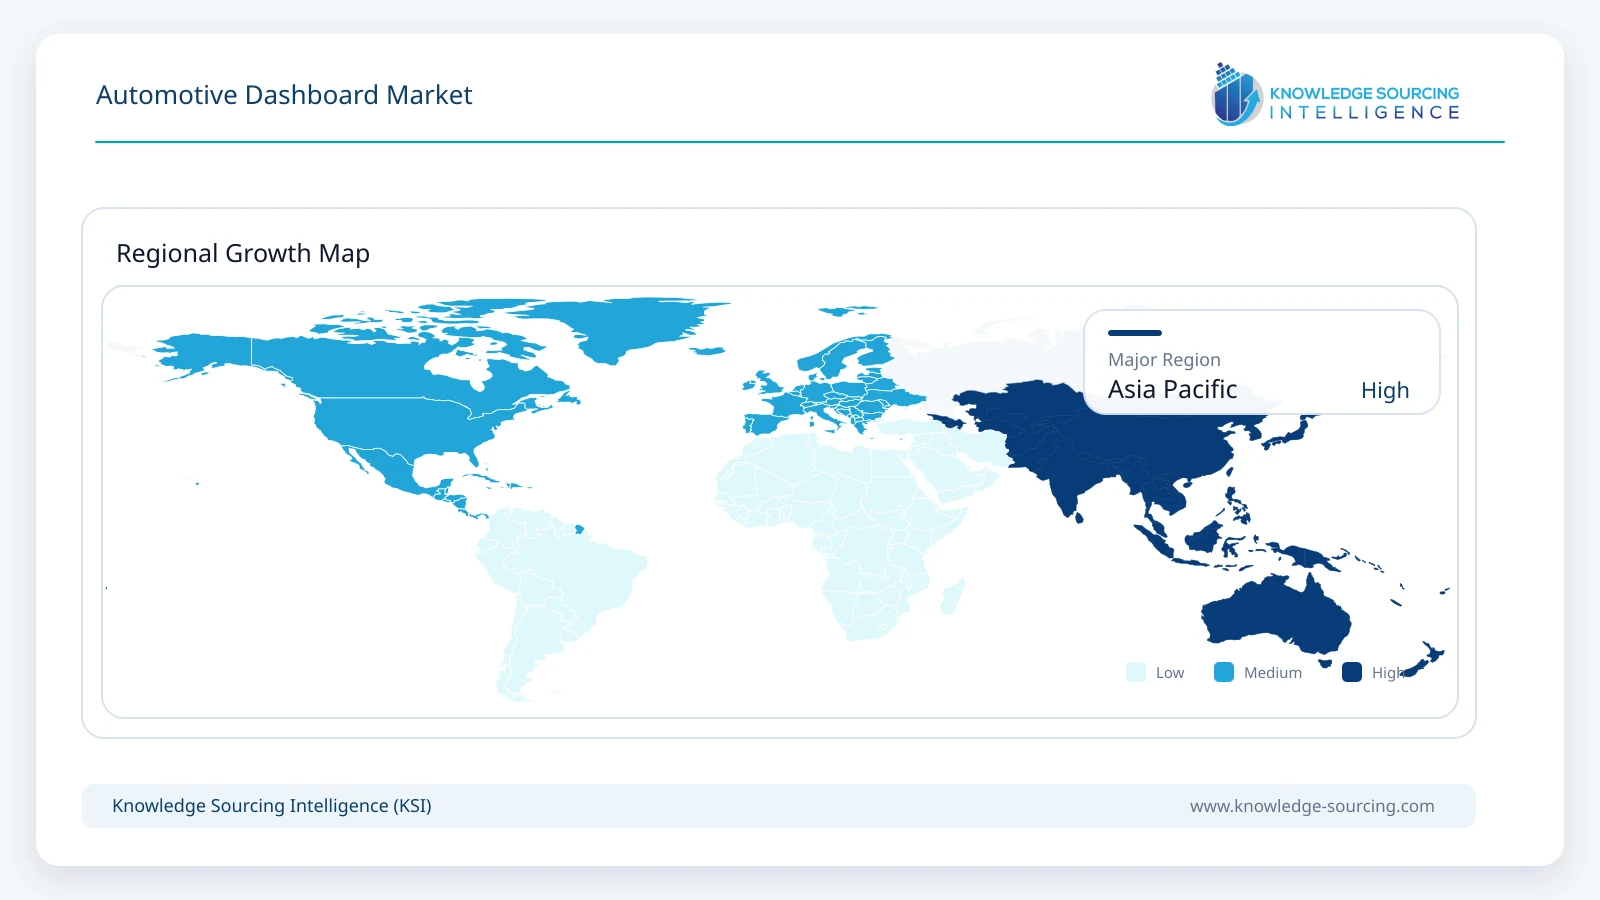
• Asia Pacific represents approximately 46% of global market value in 2026, supported by the scale of vehicle production and particularly rapid adoption of large displays and smart interior surfaces in China.
Dashboard architecture is moving beyond a molded instrument-panel structure with separate switchgear and display apertures toward an integrated visual and functional surface that combines large screens, hidden controls, ambient or informative lighting, advanced air outlets and increasingly sustainable material systems. This transition is increasing the engineering value of the dashboard because structural carriers, visible surfaces, display packaging and HMI interfaces now need to be designed as one coordinated front-cabin architecture.
Electronics-ready packaging and vehicle-specific manufacturing remain central to supplier competitiveness as dashboards accommodate pillar-to-pillar displays, driver-monitoring cameras, high-output vents, passenger airbags and touch-sensitive surfaces while meeting crash, glare, thermal and craftsmanship requirements. Yanfeng, FORVIA, Antolin, Marelli, IAC and other interior suppliers are investing in lighter carriers, smart surfaces, large-display integration and sustainable materials, while large molds, foaming or skinning processes, decorative technologies and airbag validation keep the component highly tooling intensive. Suppliers that combine surface quality, structural engineering, electronics-ready integration and local production are therefore positioned to capture higher content as the dashboard becomes a more important brand-defining cabin surface.
Market Overview
The dashboard is the central architectural surface across the front passenger compartment, carrying the instrument cluster and center display, housing air vents and glove-box openings, framing the steering and passenger areas and providing the deployment path for the passenger airbag. Its construction typically combines a rigid substrate or carrier with hard-molded surfaces, foam-backed skins, slush-molded layers, wrapped materials or decorative films depending on vehicle positioning. The complete assembly must reconcile styling, ergonomics, crash performance, reflection control, thermal stability and manufacturability, while natural-fiber reinforcement and recycled polymers are increasingly used in hidden carriers where they can reduce mass and lifecycle emissions without changing visible craftsmanship.
Digitalization and integrated air management are reshaping the dashboard surface at the same time. Wide displays and clusters occupy more of the cross-car span, while hidden-until-lit controls, touch or force sensing and illuminated information reduce reliance on conventional buttons; Marelli, Yanfeng and Antolin all provide technologies that integrate display, lighting or HMI functions directly into instrument-panel surfaces. Slim, concealed and distributed vents are also replacing prominent louver assemblies on selected premium dashboards, requiring HVAC airflow, display packaging, airbag geometry and surface design to be coordinated earlier in vehicle development rather than engineered as separate subsystems.
Market Trends
Large Displays Are Reshaping Dashboard Geometry
Instrument clusters, center information displays and passenger screens are growing in size and are increasingly connected into wide or continuous visual surfaces. Marelli's HorizonView and Visteon's multi-display programs illustrate how display architecture is becoming a defining input to dashboard geometry rather than an accessory added after the panel is designed.
Large-format displays increase structural and thermal demands because the dashboard must control vibration and alignment across a wider span while preserving glare-conscious positioning, ventilation paths and passenger-airbag clearances. Suppliers with strong structural and surface integration therefore gain importance as screen area expands.
Smart Surfaces Are Reducing Mechanical Switch Content
Touch, force sensing, hidden graphics and haptic feedback are being embedded directly into instrument-panel surfaces. Antolin's 2026 collaboration with UltraSense is designed around configurable solid-state HMI that combines touch and force sensing with visual and haptic feedback, while Yanfeng and Marelli offer smart interior surfaces that remain visually clean until functions are activated.
Smart-surface integration improves styling freedom by reducing openings, bezels and standalone switches, but it also adds validation around accidental activation, illumination uniformity, temperature behavior and tactile response. More electronics and software responsibility therefore moves into the dashboard supply chain.
Sustainable Dashboard Carriers Are Moving toward Higher-Volume Adoption
Dashboard substrates are large molded parts and therefore offer meaningful opportunities for recycled polymers, natural-fiber composites and lower-density structures. FORVIA positions its instrument panels around modular architectures and sustainable materials, while Yanfeng offers natural-fiber and lightweight substrate technologies designed to reduce mass and carbon footprint.
Sustainable-material substitution is advancing fastest in hidden structural layers where visible grain and color requirements are less restrictive. Recycled polymers and natural-fiber composites still require validation for stiffness, dimensional stability, odor, VOC emissions and passenger-airbag deployment before replacing conventional resins at scale.
Hidden and Informative Lighting Is Becoming Part of the Dashboard Surface
Ambient lighting is evolving from decorative light strips into an information and interaction layer. Marelli's informative smart-surface technology allows programmable illuminated information to appear through decorative surfaces, while Yanfeng integrates lighting and display functions into instrument-panel zones.
Informative lighting increases dashboard value because surfaces, optics, electronics and graphics must be engineered together. It can support warnings, navigation or personalization without separate visible hardware, but uniform brightness and day/night readability require sophisticated optical integration.
Dashboard Architecture Is Becoming More Packaging-Efficient
Automakers are seeking thinner dashboards with larger perceived cabin space, particularly in EVs where the absence of some traditional powertrain packaging constraints creates new interior proportions. Lightweight cross-car structures, foam-molded substrates and compact vents help reduce panel depth while preserving stiffness and surface quality.
Packaging-efficient dashboards increasingly use hidden displays and integrated vents to reduce protruding hardware. The resulting thinner architecture uses fewer standalone components but requires tighter coordination across structure, HVAC, electronics and decorative surfaces.
Segment Analysis
By Dashboard Architecture: Electronics-Ready and Smart-Surface Dashboards
Electronics-ready and smart-surface dashboards are the largest architecture by value because a growing share of new vehicles integrates digital displays, hidden controls, ambient lighting, charging interfaces and electronic sensors directly into the instrument-panel design. The dashboard substrate is engineered from the start around these functions, even when the electronic modules are procured separately.
Electronics-ready and smart-surface dashboards represent approximately USD 20.02 billion in 2026 and could approach USD 30 billion by 2031. Growth will remain strongest in EVs and premium vehicles, while lower display and sensor costs move these architectures into high-volume mid-market models.
By Integrated Content: Substrate, Carrier and Structural Interfaces
Dashboard substrates and structural interfaces form the largest integrated-content group because every dashboard needs a rigid architecture to support visible surfaces, displays, vents, glove boxes, passenger-airbag openings and mounting points. Injection-molded polypropylene and engineered polymer carriers remain dominant, with metal or composite reinforcement used where additional stiffness is required.
Substrates, carriers and structural interfaces account for approximately USD 13.48 billion in 2026. Value should rise through 2031 as larger screens and thinner dashboard profiles increase structural requirements, while lightweight and sustainable carriers add material-engineering content.
By Surface Type: Soft-Touch and Premium Surfaced Dashboards
Soft-touch dashboards use foam-backed skins, wrapped materials, slush-molded surfaces, decorative films or other premium layers to improve tactile quality and perceived craftsmanship. They are widely used across premium vehicles and increasingly in upper-midrange segments where the dashboard is a major customer touchpoint.
Soft-touch and premium surfaced dashboards represent approximately USD 16.56 billion in 2026 and could exceed USD 23 billion by 2031. Growth will be supported by personalization, sustainable synthetic materials and integrated illuminated surfaces, although hard-molded dashboards will remain important in cost-sensitive vehicles.
By Material Platform: Polymer and Polymer-Composite Assemblies
Thermoplastics dominate dashboard construction because they allow complex geometry, integrated ribs, low mass and economical high-volume molding. Polypropylene, ABS, TPO and related compounds are used across substrates, skins and trim, while natural fibers and recycled resins are increasingly added to reduce carbon footprint.
Polymer and polymer-composite assemblies account for approximately USD 28.49 billion in 2026. Their share is expected to remain high through 2031, but composition will shift toward recycled, bio-based and lower-density materials alongside design strategies that reduce part thickness and simplify end-of-life separation.
By Vehicle Type: Passenger Vehicles
Passenger vehicles dominate dashboard demand because they combine the highest global production volume with the strongest adoption of digital displays, premium surfaces, ambient lighting and integrated HMI. SUVs and crossovers are particularly important because their larger cabins and higher average transaction prices support more dashboard content.
Passenger vehicles account for approximately USD 36.19 billion of market value in 2026 and could approach USD 50 billion by 2031. Commercial vehicles will continue to require durable dashboards with storage and driver-information interfaces, but passenger platforms will drive most value growth from digitalization and premiumization.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Drivers
Expansion of Large Displays and Digital HMI
Dashboard design increasingly revolves around instrument clusters, center displays and passenger screens. Larger display areas require dedicated mounting structures, decorative integration, cable routing and thermal management, increasing the engineering and content value of the instrument panel.
As wide displays move from premium vehicles into mainstream models, dashboard suppliers benefit from higher structural complexity and greater integration responsibility even when the display electronics are supplied by a separate Tier 1.
Premiumization of Visible Interior Surfaces
Consumers frequently judge vehicle quality through the dashboard because it occupies the largest continuous visible surface in the front cabin. OEMs are therefore investing in better grains, soft-touch skins, decorative inserts, stitched surfaces, lighting and tighter fit-and-finish.
Interior premiumization raises average dashboard value through foamed skins, wrapped surfaces, decorative inserts, lighting and tighter fit-and-finish. Suppliers with advanced surface-processing capabilities benefit particularly in SUVs and Chinese EVs, where cabin design is a major differentiation point.
SEGMENT SHARE DISTRIBUTION (ILLUSTRATIVE)
Market Share Breakdown — By Dashboard Architecture
Automakers are reducing standalone buttons and seeking cleaner visual layouts. Integrating touch, force and haptic controls into the dashboard allows software-configurable HMI while reducing mechanical openings and separate switch assemblies.
Integrated controls increase demand for functional films, illumination, sensing electronics and surface integration because HMI must operate reliably through the decorative layer. Dashboard suppliers consequently take a larger role in interface development and validation.
Lightweighting and Low-Carbon Material Requirements
Dashboards are large plastic-intensive assemblies, making them a logical target for recycled resins, natural-fiber reinforcement and thinner structural designs. Lower mass supports vehicle efficiency, while sustainable materials contribute to OEM lifecycle-emissions targets.
The strongest lightweighting opportunities are in carriers that reduce mass and virgin-polymer use without changing visible quality or passenger-airbag behavior. Suppliers with validated recycled, natural-fiber or lower-density compounds can differentiate themselves during new-platform sourcing.
EV Interior Architecture and Cabin-Space Optimization
Electric vehicles give designers greater freedom in cabin proportions and encourage thinner, visually lighter dashboards that create a sense of space. EV brands also use wide displays, hidden vents and minimal physical controls to reinforce a technology-oriented design language.
EV cabin packaging increases the importance of lightweight substrates, integrated airflow and surface electronics within a thinner cross-car envelope. Suppliers that preserve stiffness, airbag performance and perceived quality while reducing panel depth are well positioned in new EV programs.
Market Restraints
High Tooling Cost and Long Platform-Specific Development Cycles
Dashboards require some of the largest interior injection molds, skin tools and assembly fixtures in the vehicle. Their geometry is closely tied to the windshield, steering system, airbag, HVAC and display package, making tooling highly platform specific.
Late changes to styling, display packaging or electronics can force expensive mold revisions because dashboard tooling is committed around vehicle-specific geometry well before launch. High upfront investment therefore increases exposure when launches slip or production volumes fall below plan.
Passenger-Airbag and Crash-Performance Constraints
The dashboard must support safe passenger-airbag deployment across a wide range of temperatures and material-aging conditions. Skin, foam, decorative layers and substrate geometry must tear or move in a controlled manner without producing hazardous fragments.
Passenger-airbag requirements constrain material substitution near the deployment zone because new surfaces, skins and hidden HMI must behave predictably during deployment. The resulting validation burden can slow sustainable-material and smart-surface innovation compared with non-critical trim.
Thermal, Glare and Durability Challenges around Large Displays
Wide displays and illuminated surfaces increase heat generation and solar exposure at the top of the instrument panel. Dashboard materials must resist warpage, discoloration and gloss changes while maintaining precise display alignment.
Windshield reflections and direct glare constrain gloss, material finish and screen angle around large displays. These optical requirements increase development cost because thermal, structural and visibility performance must be resolved together.
Cost Pressure on High-Volume Molded Components
Dashboard substrates and hard trim remain highly cost-sensitive despite increasing complexity. OEMs continue to demand annual productivity improvements, while resin, energy and labor inflation can pressure supplier margins.
Premium surfaces and smart-HMI can improve revenue per dashboard but also add warranty and quality risk under aggressive OEM cost targets. Suppliers therefore need automation, part-count reduction and strong variant control to protect profitability.
Recycling Complexity in Multi-Layer Smart Dashboards
Modern dashboards combine polymer carriers, foams, skins, decorative films, displays, lighting, electronics, metal reinforcement and adhesives. These material combinations are difficult to separate at end of life.
Design-for-disassembly and mono-material concepts can improve circularity, but they must remain compatible with passenger-airbag performance, surface quality and high-volume assembly. Circular design therefore remains a system-level engineering trade-off rather than a simple material substitution.
Regional Outlook
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Asia Pacific
Asia Pacific is the largest automotive dashboard market, supported by high vehicle production in China, Japan, South Korea and India. China is the strongest technology driver because domestic EV manufacturers increasingly use pillar-to-pillar displays, hidden controls, integrated lighting and minimalist instrument-panel designs as visible product differentiators.
Yanfeng has a particularly strong regional position in instrument panels and smart surfaces, while Marelli, Antolin, FORVIA, Toyota Boshoku and other global suppliers maintain significant engineering and manufacturing operations across the region. Yanfeng's XiM27, with a panoramic head-up display integrated into the instrument panel and touch-interactive surfaces, illustrates the direction of high-value dashboard development.
Asia Pacific growth through 2031 will reflect both vehicle production and rising dashboard content. China should remain the fastest adopter of smart dashboards, while India and Southeast Asia support demand for cost-optimized panels with gradually increasing digital content.
Europe
Europe is a major high-value dashboard market due to premium vehicle production, advanced surface engineering and strong sustainability requirements. European OEMs frequently specify soft-touch surfaces, decorative materials, low-carbon substrates and precise integration of displays and HVAC outlets.
FORVIA and Antolin have strong positions in instrument panels and interior surfaces, while Marelli provides large-display and smart-surface technologies that can be integrated into dashboards. FORVIA's January 2026 award with a major European automaker included tailored instrument panels, reinforcing continued investment in large integrated interior programs.
European dashboard growth will be driven more by content per vehicle than by unit production, with sustainable materials, smart HMI, premium surfaces and larger displays increasing value. The region should remain an important development base for recycled and natural-fiber carriers.
Competitive Landscape
The automotive dashboard market is led by large interior suppliers with capabilities in instrument-panel substrates, skins, decorative surfaces, airbag integration and high-volume assembly. Yanfeng, FORVIA, Antolin, Marelli, International Automotive Components, Toyota Boshoku and Motherson compete across global OEM platforms, while regional suppliers add strength in specific material and molding technologies.
Yanfeng combines instrument-panel engineering with smart surfaces and cockpit electronics integration. FORVIA differentiates through modular instrument-panel architecture, low-carbon materials and surface activation. Antolin is expanding solid-state HMI integration, while Marelli combines dashboard and cockpit structures with large displays and informative or interactive smart surfaces.
Competitive advantage increasingly depends on industrializing large displays, hidden lighting and smart controls without compromising craftsmanship or passenger-airbag performance. These features require tighter coordination between plastics, optics and electronics than conventional dashboards.
A broad manufacturing footprint remains important because dashboards are bulky, platform specific and usually supplied close to vehicle assembly plants. Suppliers need localized molding, foaming, wrapping and assembly capacity with reliable tooling launch and quality management across derivatives.
Recent Developments
• 8 September 2026: Antolin and UltraSense Systems announced a next-generation Smart Surface HMI initiative for a future global vehicle platform, combining touch and force sensing with visual and haptic feedback for integrated interior surfaces including instrument-panel applications.
• 29 June 2026: Yanfeng unveiled the production-ready XiM27 smart cabin, featuring a 35.4-inch panoramic head-up display integrated into the instrument panel, fold-away steering and touch-interactive illuminated surfaces.
• 3 June 2026: Visteon announced that its 12.3-inch narrow-border driver display entered the all-new Lexus ES, using an ultra-slim construction designed for seamless integration into premium cockpit and dashboard environments.
• 26 May 2026: Smart Eye and Visteon introduced an LCD instrument cluster with an integrated driver-monitoring camera positioned behind the display, addressing a key packaging challenge for clean dashboard design.
• 9 April 2026: Marelli announced its Auto China 2026 in-cabin showcase featuring instrument-panel demonstrators with ambient lighting, smart-surface functions and advanced large-display technologies for software-defined vehicles.
• 29 January 2026: FORVIA announced significant new business with a major European automaker that includes tailored instrument panels, strengthening its production pipeline for sustainable and integrated dashboard systems.
Market Outlook
The automotive dashboard market is expected to expand from approximately USD 38.5 billion in 2026 to about USD 53.0 billion by 2031. Physical dashboard substrates and surfaces will remain the core value pool, but the fastest growth will come from display-ready architectures, smart surfaces, hidden lighting and premium material integration.
Dashboard design is expected to become visually simpler but technically more complex as fewer switches, thinner air outlets and larger screens shift electronics beneath the surface. Engineering content can therefore increase even as the visible number of physical components falls.
Asia Pacific will remain the largest regional market, while Europe continues to generate high value per vehicle through premium surfaces and sustainable material adoption. Supplier success will depend on combining large-part manufacturing expertise with electronics-ready packaging, safe airbag integration, lightweight materials and consistent high-quality surfaces.