
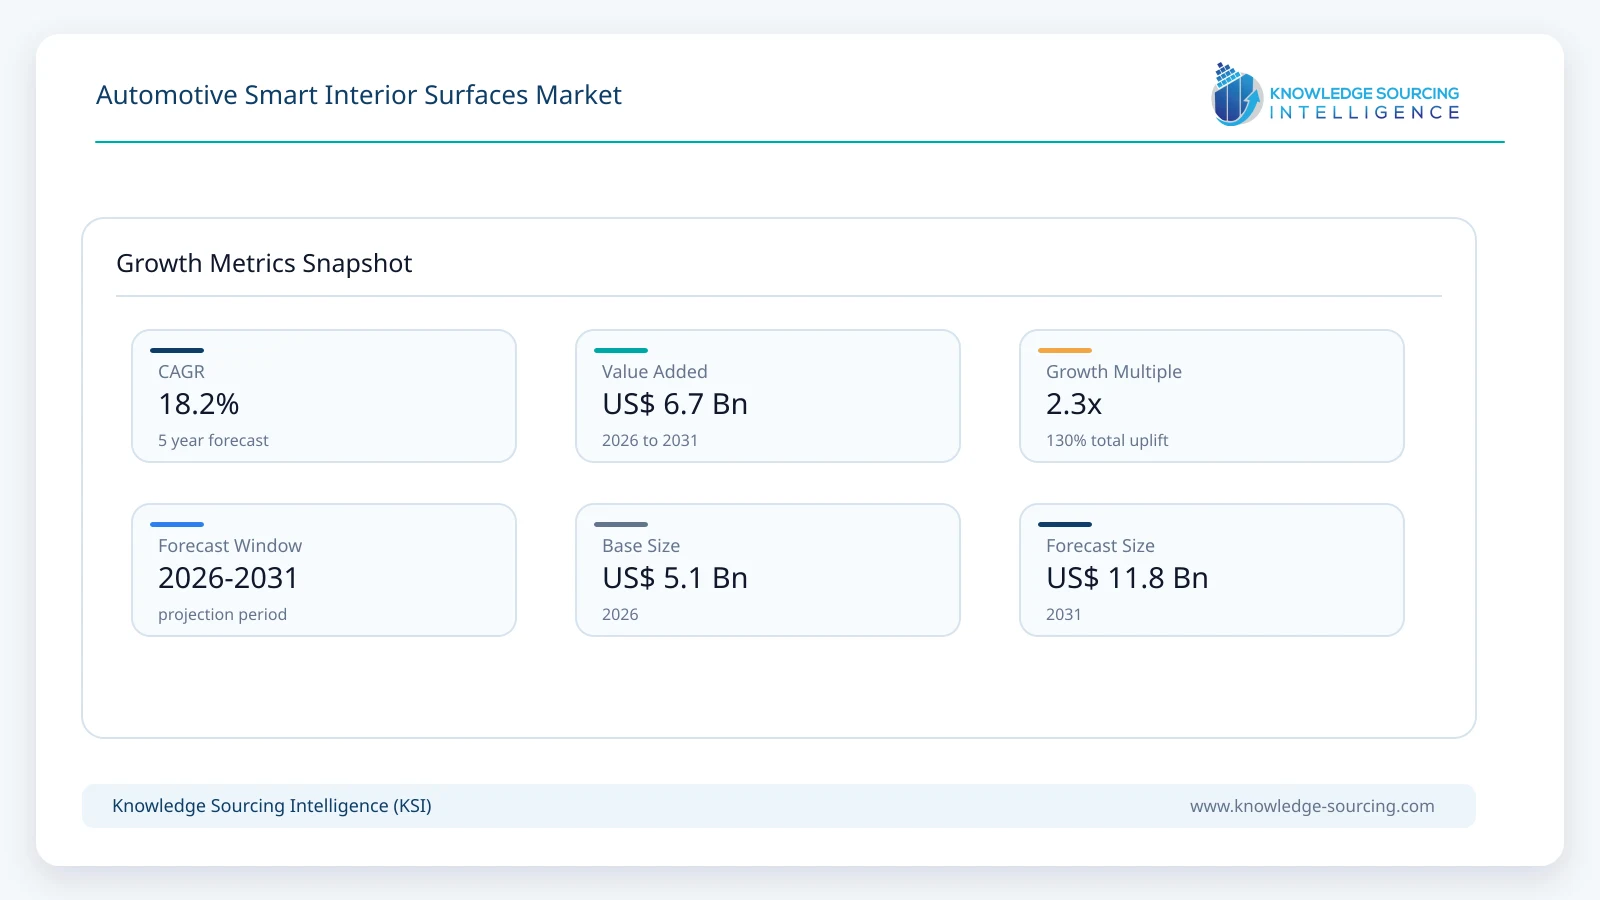
The Automotive Smart Interior Surfaces Market is projected to expand at a CAGR of 18.2%, increasing from USD 5.10 billion in 2026 to USD 11.75 billion by 2031.
Highlights:
- 1Door panels and door-surface trim account for an estimated 38% of 2026 global market value because they accommodate broad functional surfaces, lighting and concealed controls.
- 2Illumination and personalization represent approximately 38% of 2026 demand, while combined sensing and multifunctional surfaces gain share through 2031.
- 3In-mold structural electronics are estimated to represent 23% of supplier value in 2026 and are projected to reach 35% by 2031 as awarded programs and production capabilities broaden.
- 4Asia Pacific represents an estimated 48% of 2026 value, supported by regional vehicle output and rapid smart-cabin development cycles.
- 5Automotive qualification and process yield remain central to the economics of integrating circuitry into finished trim surfaces.
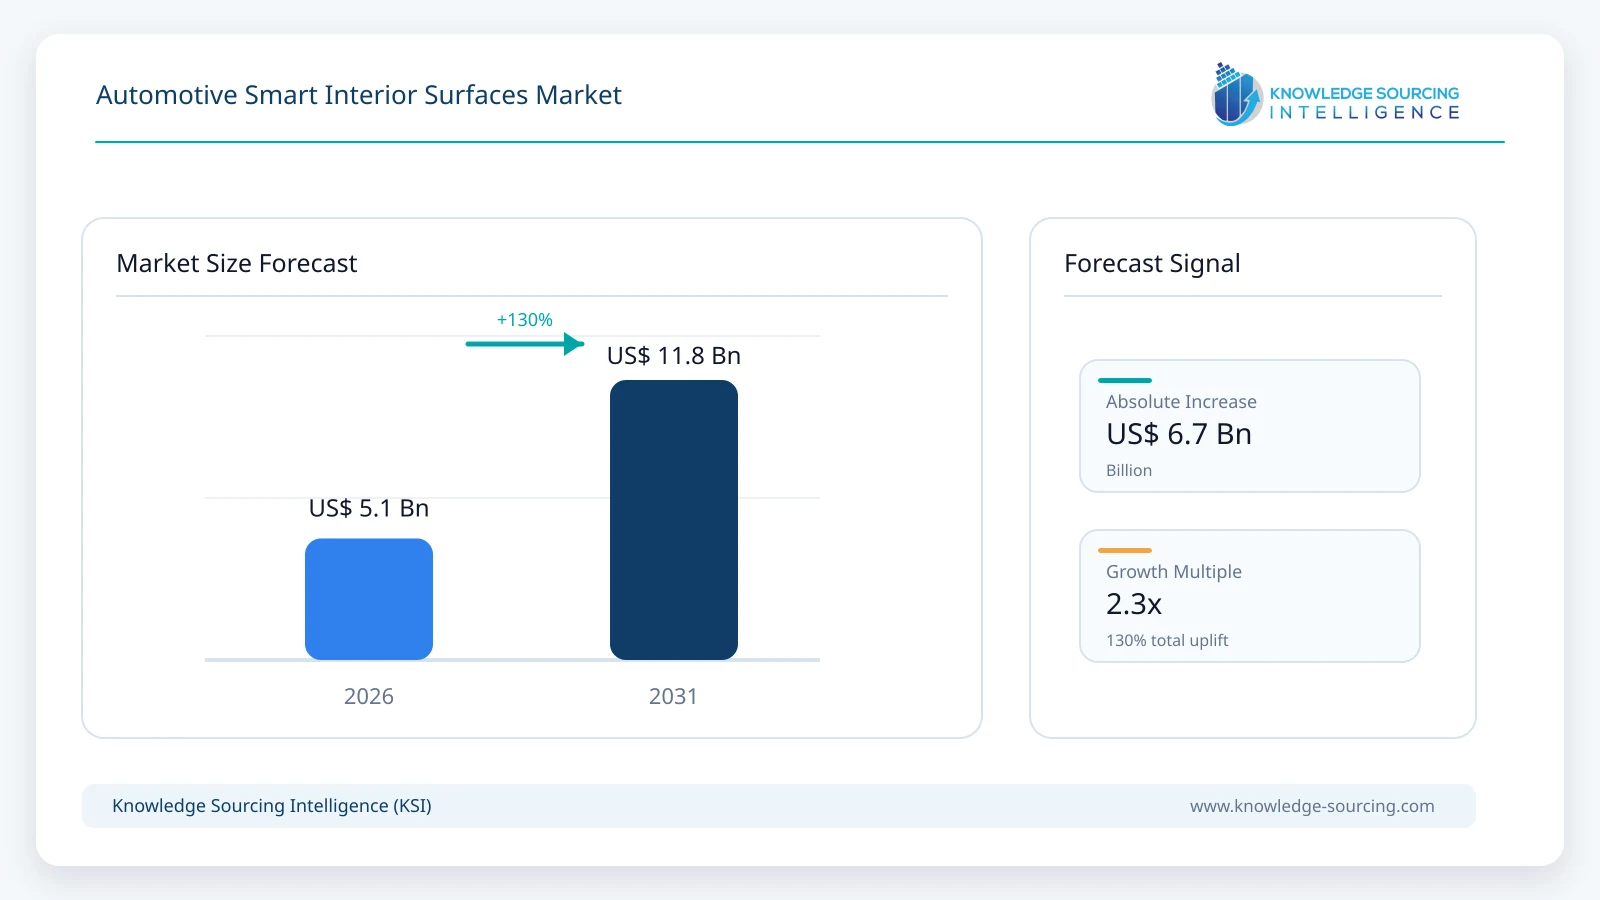
Finished cabin surface assemblies that incorporate illumination, interactive control, sensing, or visible status communication account for the principal supplier revenue. Growth comes from greater electronic content per surface and wider fitment across vehicle ranges, rather than vehicle production alone.
Smart-surface manufacturing brings traditionally separate disciplines into the same component. Decorative skins, capacitive electrodes, force sensors, light guides, conductive traces and local controllers must remain functional after forming, molding, lamination and vehicle installation. A surface that appears continuous and uncluttered to an occupant may require demanding optical calibration, electromagnetic compatibility testing and a process that prevents electronics damage during molding.
Valeo announced an awarded premium-automaker interior program in January 2026 that will use TactoTek in-mold structural electronics and an automated high-volume manufacturing approach. Motherson expanded the same technology ecosystem through an IMSE license in May 2026. Separately, Toyota Boshoku confirmed large-area illuminated door trim for the Lexus ES in June 2026. These developments show different commercialization routes: an OEM award, a manufacturing license, and a specified vehicle application.
Market Overview
Smart interior surfaces incorporate optical, electronic, or sensing capability into the material layers and molded parts that occupants see and touch. The product category includes illuminated door skins, patterned or hidden-until-lit dashboard surfaces, integrated console controls and active decorative panels. A finished part may contain several layers of polymers, films and electronics, but its commercial value is delivered through the qualified functional assembly rather than the individual material layers considered separately.
Marelli classifies its smart-surface offerings as decorative, informative and interactive, illustrating how integrated illumination can provide ambience, communicate vehicle state or work with occupant controls. Nissha offers in-mold electronic modules that place touch sensors and functional layers within molded panels, while Preh supports active haptic feedback in smart surfaces and central controls. Surface-integrated electronics are becoming a meaningful differentiator for Tier 1 suppliers that previously competed chiefly through material finish and trim quality.
Door panels, instrument panels and consoles are especially important because their broad visible areas allow lighting, tactile feedback and concealed controls to be combined without adding separate switch housings. Embedded functions shift both engineering responsibility and value toward suppliers that can coordinate optical properties, electronics, production tooling, software interfaces and warranty performance.
Market Trends
In-Mold Electronics Are Changing the Trim Supply Chain
Valeo's January 2026 premium-OEM award specifies in-mold structural electronics for integrated interior lighting and local circuitry. The planned automated line illustrates the move from surface electronics demonstrations toward qualified production programs, although the announcement does not disclose full program revenue or vehicle fitment. Thin conductive and optical layers can reduce separate fixtures and wiring, provided the supplier can deliver stable forming yields and robust electrical contacts after injection molding.
Motherson's May 2026 IMSE licensing agreement broadens industrial access to molded smart-surface manufacturing beyond individual technology specialists. The ability to combine standardized functional-film processes with regional automotive program execution is commercially important for vehicles assembled across several countries.
Door Trim Is Becoming a Larger Electronic Surface
Toyota Boshoku confirmed in June 2026 that its illuminated large-area door-trim design was adopted in the new Lexus ES, using surface materials and transmission technology for uniform lighting and animated effects. This is stronger evidence of vehicle-level application than an exhibition concept.
Large visible panels are difficult optical and electronic products because reflected daylight, color matching, local hot spots, light-guide thickness, and surface texture can affect quality. Suppliers with polymer-processing, optical engineering and electronics competencies can capture a greater share of the assembly, although warranty and replacement costs also increase when multiple functions are consolidated.
Hidden Controls Are Entering Functional Trim
Antolin and UltraSense announced on 8 September 2026 an integrated Smart Surface HMI initiative for a future global vehicle platform. The work combines capacitive and force sensing with visual and haptic feedback, while Antolin is responsible for integration and industrialization. The collaboration establishes a relevant development direction, but it should not be described as an already launched OEM production program.
Hidden control zones can reduce the number of mechanical openings in a decorative part, but their usability depends on tactile confirmation, accidental-activation rejection, and controls that remain recognizable in demanding driving conditions. Surface electronics suppliers must therefore coordinate design, electronics and human factors rather than rely on appearance alone.
Segment Analysis
By Surface Location: Door and Side-Trim Surfaces
Door and side-trim surfaces account for an estimated 38% of 2026 supplier value because passenger doors provide large, highly visible areas that can house illuminated graphics, window and seating controls, warning cues and interactive feedback. The combination of area, occupant reach and premium design relevance supports higher electronic content than many smaller cabin surfaces. Door applications must nevertheless meet stringent abuse, moisture, cleaning and operating-cycle requirements.
Toyota Boshoku's Lexus ES illuminated door trim demonstrates a documented vehicle application, whereas Antolin and UltraSense are developing next-generation controls that may extend the available functionality of future door and console programs. The projected market mix gradually shifts toward consoles and other multi-input surfaces because they can combine more electronic functions per installed assembly, even as door areas remain the largest single location.
By Surface Function: Illumination and Personalization
Illumination and personalization represent approximately 38% of smart-surface supplier value in 2026, reflecting established commercial use of backlit skins, light guides and variable ambient features in premium passenger vehicles. Light-transmitting surfaces can preserve a uniform appearance when inactive and display coordinated patterns or vehicle-state information when energized. Such components may use either conventional LED modules behind decorative layers or more advanced embedded-electronics architectures.
Interactive sensing and information feedback gain relative weight as 2031 approaches because OEMs are asking visible interior surfaces to replace separate controls and communicate more vehicle functions. Suppliers able to tune tactile feel, lighting response and control sensitivity in one qualified part can capture more value per vehicle. Decorative lighting retains a significant installed base, but faster growth is associated with integration of functions that occupants actually operate or depend upon.
By Technology: In-Mold Structural Electronics
In-mold structural electronics are estimated to represent 23% of the 2026 integration-technology mix and 35% in 2031 as more suppliers industrialize conductive film inserts and molded surface electronics. The format enables thin, conformal components without separate circuit enclosures, a practical benefit in curved doors, dashboards and consoles. Production risk remains concentrated in film placement, stretching, connection integrity and thermal cycling rather than in the appearance of the finished panel alone.
Valeo's announced manufacturing investment and Motherson's technology licensing illustrate complementary routes to scale IMSE production. Nissha's in-mold electronics portfolio also demonstrates how functional films and electronic parts can be integrated into curved molded structures.
By Surface Material: Molded Polymer and Decorated Substrates
Molded polymer and decorated surface carriers account for an estimated 58% of 2026 value because injection-molded and decorated interior substrates provide structural control, cost efficiency and compatibility with electronic inserts. Their use spans instrument-panel sections, center consoles, door trim and small decorative control panels.
Functional films and optical layers grow faster through 2031 as OEMs specify concealed icons, patterned illumination and laminated conductors. Material selection nevertheless depends on heat aging, scratch resistance, dimensional stability and light transmission; these requirements keep conventional polymer substrates commercially relevant.
By Supplier Model: Integrated Smart-Surface Assemblies
Integrated smart-surface assemblies represent an estimated 42% of revenue in 2026, rising to 54% by 2031 as OEMs seek finished panels that can be installed, tested and warranted as a single unit. The approach moves purchasing responsibility toward surface integrators capable of managing electronics, tooling, decoration and quality across several vendors. Larger contracts can capture a higher share of supplier value, but they also increase the integrator's exposure to functional failures and service costs.
Functional-film, sensor and circuit specialists remain essential to the supply chain, particularly when an established interior supplier purchases electronic elements rather than manufacturing them internally. TactoTek provides an enabling technology and licensing route, while other suppliers contribute sensing, optics or surface materials.
Market Drivers
Reduction of Visible Mechanical Controls
Instrument panels, door inserts and center consoles increasingly incorporate hidden control zones that allow OEMs to reduce exposed switch packs without removing everyday functions. Embedded touch sensing and haptic response preserve an interface at the point of contact while freeing design space for continuous decorative surfaces.
Embedded surface controls shift supplier value toward trim assemblies with validated electronics rather than the decorative films that merely cover conventional control modules. Adoption is strongest where control reliability and driver usability can be demonstrated over automotive temperature and vibration cycles.
Premium Cabin Differentiation and Feature Migration
Premium vehicles continue using electronically lit surfaces and integrated trim controls to distinguish cabin variants, while scalable lighting and circuit architectures support selective adoption on mid-range models. Door-light signatures, translucent icons and animated status functions offer differentiation without redesigning every structural panel.
Standardized circuit films, optical parts and molded carriers reduce the incremental cost of offering additional trim grades. Suppliers that can control variant complexity are better positioned to gain volume without exposing OEMs to excessive inventory and part-number proliferation.
Commercialization of In-Mold Electronic Manufacturing
Valeo's awarded IMSE-based program and Motherson's technology-licensing arrangement support broader availability of formed electronic surfaces from established automotive suppliers. Their commercial importance lies in creating industrial supply routes that combine decoration, circuitry, molding and final inspection.
Automated integration can eliminate separate brackets and circuit housings for selected features, although cost benefits depend on scrap rates and production quality. Continued supplier investment should therefore shift demand from prototypes toward qualified, repeatable components over the forecast period.
Expansion of Functional Cabin Illumination
Toyota Boshoku's large-area Lexus ES illuminated door trim and FORVIA HELLA's September 2026 adaptive RGB interior lighting concept illustrate how lighting surfaces can support visual communication alongside ambience. In the commercial-vehicle concept, warning and status indications are designed to complement existing information displays rather than replace them. Lighting-based interaction provides an additional route to value growth when installed surfaces serve several interior functions.
Surface integrators can increase the value of a single panel when decorative lighting is supplemented by vehicle-status cues, hidden input icons or driver-attention guidance. The economics improve most when these functions share existing optics and a local controller instead of requiring separate hardware for every effect.
Electrified and Digitally Coordinated Cabin Platforms
Battery-electric and hybrid platforms increasingly support electronically coordinated occupant functions, cabin themes and configurable feature packages. Electronically active door, console and dashboard trims provide physical points of interaction that complement digital cockpit controls without requiring the full cockpit hardware value to be included in surface trim revenue.
Cross-platform software coordination supports updates to lighting behaviors and interface states, but physical trim hardware still requires complete vehicle-level qualification. Revenue therefore follows installed electronic surfaces and their attributable integration, not the value of all software-defined vehicle platforms.
Market Restraints
High Functional-Surface Qualification Costs
Smart surfaces combine polymer aging, abrasion, gloss, electrical safety, EMC and interface performance within one part approval process. A defect in an embedded film or sensor may require replacement of a larger decorated assembly, increasing potential warranty cost compared with a stand-alone switch.
OEM qualification schedules can lengthen when newly integrated systems must pass simultaneous surface and electronics validation. Smaller programs may retain conventional controls until suppliers demonstrate repeatable production yields and repair economics.
Capacitive and Haptic Usability Limitations
Touch-sensitive surfaces can be difficult to operate without visual attention when a driver expects the physical landmark of a conventional button. Gloves, moisture, vibration and unintended hand contact create additional reliability requirements for concealed surface controls.
Suppliers are incorporating force sensing and haptic feedback to improve confidence, but every added function raises bill-of-materials complexity. Programs with safety-critical controls may limit the use of fully hidden interfaces or retain physical alternatives.
Electronics Yield and Repair Complexity
In-mold electronics and laminated circuit technologies require reliable connections, precision placement and process windows that protect circuits during forming and molding. A cosmetic reject can also scrap an electronic layer, while an electrical reject can waste a finished decorative carrier.
Repair and replacement economics become more difficult when an electronics fault is inseparable from a door or console surface. Suppliers need robust testability, modular connectors, and failure analysis before scalable production advantages can be realized.
Material and Thermal Performance Constraints
High-temperature cycling, direct sunlight, ultraviolet exposure, and repeated cabin-cleaning chemicals can affect decorative films, adhesives, optical layers, and touch-sensor calibration. Combinations of soft-touch skins and electronic layers may introduce delamination or light-transmission variation over product life.
Prototype electronic surface assemblies may require extensive redesign for durability and process stability before OEM launch approval. Material restrictions are particularly important in door and dashboard applications with broad visible surfaces and tight color consistency requirements.
Price Pressure and Fragmented Supplier Accountability
High-volume automotive platforms impose recurring price-down requirements while smart-surface suppliers must integrate components sourced from optical, semiconductor, film and molded-plastic partners. Cost control becomes difficult when development responsibility is split among companies with different quality systems and commercial agreements.
Integrated Tier 1 suppliers can simplify accountability, yet smaller electronics specialists often provide the core innovation. Contracts need clear boundaries for tooling, software interfaces, warranty responsibilities and revision control to avoid delayed launches.
Regional Outlook
Asia Pacific
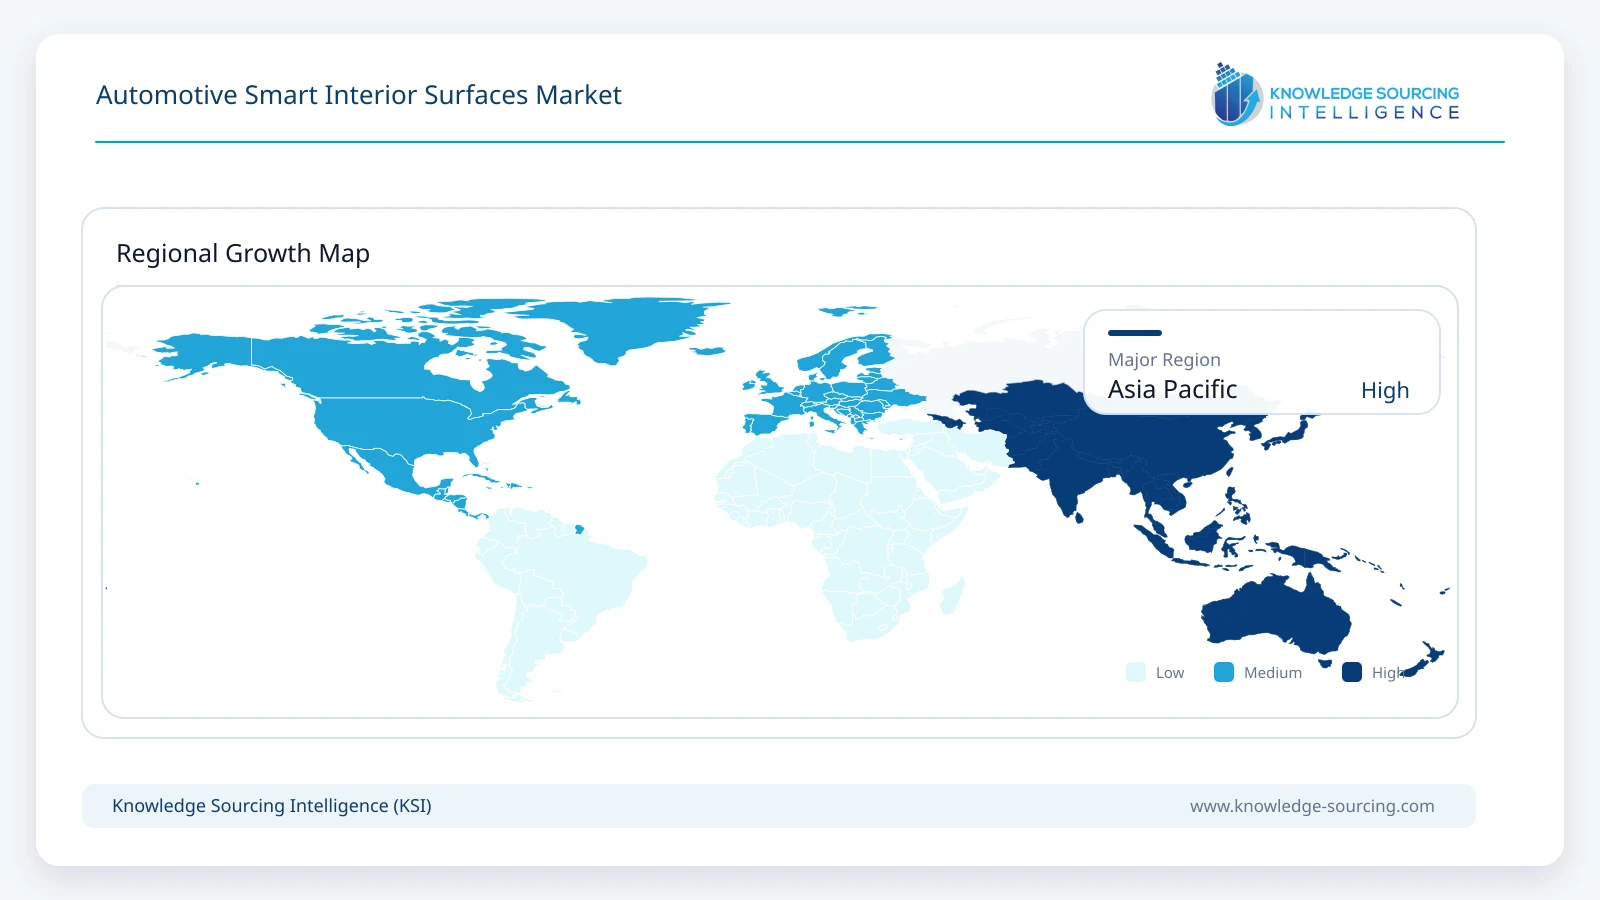
Asia Pacific accounts for approximately 48% of 2026 global smart interior surface value, supported by the region's vehicle-production scale and demand for electronics-rich cabins in China, Japan and South Korea. Chinese OEMs frequently use broad illuminated surfaces and concealed controls as visible signs of cabin differentiation, while regional electronics and optical suppliers shorten the path between concept iteration and production sourcing. The resulting supplier ecosystem supports high-volume programs as well as fast-moving premium and electric-vehicle launches.
Toyota Boshoku's specified Lexus ES illuminated-door application and Nissha's mobility-focused functional films illustrate Japanese strength in surface materials and manufacturing precision. Yanfeng's XiM27 drivable concept demonstrates further design possibilities through touch-interactive illuminated materials, but should not be counted as an announced OEM series-production program.
Europe
Europe remains a high-value smart interior surfaces market because major vehicle manufacturers emphasize tactile quality, coherent lighting design and reliable interfaces across premium platforms. Valeo, Antolin and FORVIA HELLA combine automotive program capabilities with lighting, materials and HMI development, while Continental Surface Solutions provides translucent surface materials that support hidden illumination. Higher surface functionality can preserve supplier content even where European vehicle-production growth is relatively modest.
European supplier programs face demanding qualification for electromagnetic compatibility, functional behavior, chemical exposure, material consistency and serviceability. Antolin's development work with UltraSense demonstrates the interest in integrated sensing and feedback, while Valeo's IMSE program shows a separate manufacturing-led route.
Competitive Landscape
Competition in smart interior surfaces spans global interior Tier 1 suppliers, automotive lighting groups, HMI component companies and materials specialists. Antolin, Yanfeng, Motherson and Toyota Boshoku bring large-part integration and vehicle-program experience; Valeo and FORVIA HELLA contribute lighting and electronics; and TactoTek, Nissha, UltraSense and Preh add enabling capabilities in in-mold electronics, films, sensing and tactile interfaces. Suppliers differ substantially in their ability to deliver a finished, warranted cabin component.
Valeo's awarded IMSE program provides tangible evidence of OEM procurement for integrated electronics and lighting, while Antolin's UltraSense collaboration concerns a future-platform development initiative rather than a released vehicle program. Continental Surface Solutions offers the Xpreshn Hylite translucent surface platform, illustrating how material technology can determine which electronic functions are practical behind a premium skin. These distinctions matter when comparing supplier readiness and revenue opportunity.
Smart-surface procurement increasingly requires coordination among polymer processors, circuit and film specialists, optical engineers and local control electronics providers. OEMs are likely to favor suppliers that can demonstrate consistent manufacturing yields, coherent visual quality and clear warranty responsibility across several vehicle variants.
Recent Developments
8 September 2026: Antolin and UltraSense advanced a smart-surface HMI development initiative for a future global vehicle platform, combining touch and force sensing with visual and haptic feedback.
29 June 2026: Yanfeng unveiled the drivable XiM27 smart-cabin concept, incorporating integrated surfaces and coordinated electronics as part of a broader cabin architecture.
11 June 2026: Toyota Boshoku announced that its large-area illuminated door trim had been adopted for the new Lexus ES, combining surface transmission and dynamic illumination.
21 May 2026: Motherson signed a license for TactoTek IMSE technology to support industrial-scale smart-surface manufacturing for automotive applications.
20 January 2026: Valeo announced a premium-automaker program award for an interior lighting solution using TactoTek IMSE, with a high-volume manufacturing approach.
16 April 2026: Continental Surface Solutions presented its SPACE D interior design concept in North America, including the translucent Xpreshn Hylite surface platform for lighting and HMI applications. The showcase was a materials concept, not a declared vehicle production award.
Market Outlook
The automotive smart interior surfaces market is projected to expand from approximately USD 5.10 billion in 2026 to USD 11.75 billion in 2031 as illuminated door skins, sensor-enabled consoles and electronically functional dashboard trims become more common. Growth is tied to rising functional content per vehicle and a shift toward integrated assemblies rather than simply increased vehicle production. Mature illumination products will retain material demand, but smart interfaces and embedded electronics will make a larger contribution to incremental supplier value.
In-mold structural electronics, laminated functional films and local controller integration are expected to reshape the economics of smart-surface production. OEMs will pursue cleaner cabin designs, while suppliers will need to control forming yield, surface finish, interface reliability and long-term repairability. The value captured by a finished smart surface is likely to rise where one qualified component substitutes for separate switches, lamps or decorative panels.
Asia Pacific is expected to remain the largest market through 2031, supported by vehicle production and rapid technology adoption, while Europe remains important for premium integration and product engineering. Companies able to combine repeatable manufacturing with optical performance, tactility and electronics quality will be better positioned for larger contracts. Qualification schedules and material-sourcing constraints will continue to separate production-ready platforms from concept demonstrations.
Automotive Smart Interior Surfaces Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.10 billion |
| Total Market Size in 2031 | USD 11.75 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 18.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | By Surface Location, Primary Surface Function, Integration Technology, Surface Material Platform |
| Companies |
|
Market Segmentation
By Surface Location
Door and Side-Trim Surfaces
Instrument Panel and Dashboard Surfaces
Center and Floor Console Surfaces
Headliner and Overhead Surfaces
Pillars and Other Functional Surfaces
By Primary Surface Function
Illumination and Personalization
Touch and Haptic Control
Status, Warning and Information
Embedded Proximity and Occupant Sensing
Multifunctional Surface Systems
By Integration Technology
Conventional PCB and LED Modules
Laminated Circuits and Functional Foils
In-Mold Structural Electronics
Printed and Other Embedded Electronics
By Surface Material Platform
Molded Polymer and Decorated Substrates
Soft-Touch Skins and Synthetic Leather
Functional Films and Optical Layers
Textiles and Light-Permeable Soft Surfaces
Natural-Fiber and Other Sustainable Platforms
By Supplier Model
Integrated Smart-Surface Assemblies
Surfaces with Modular Electronics
Functional-Foil and Electronics Subassemblies
By Vehicle Type
Passenger Vehicles
Light Commercial Vehicles
Medium and Heavy Commercial Vehicles and Buses
By Propulsion
Internal-Combustion-Only Vehicles
Hybrid and Plug-In Hybrid Vehicles
Battery Electric Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Forecast, 2026–2031
1.3. Segment and Regional Highlights
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Reduction of Visible Mechanical Controls
3.1.2. Premium Cabin Differentiation and Feature Migration
3.1.3. Commercialization of In-Mold Electronic Manufacturing
3.1.4. Expansion of Functional Cabin Illumination
3.1.5. Electrified and Digitally Coordinated Cabin Platforms
3.2. Market Restraints
3.2.1. High Functional-Surface Qualification Costs
3.2.2. Capacitive and Haptic Usability Limitations
3.2.3. Electronics Yield and Repair Complexity
3.2.4. Material and Thermal Performance Constraints
3.2.5. Price Pressure and Fragmented Supplier Accountability
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. In-Mold Structural Electronics
4.2. Capacitive, Force and Haptic Sensing
4.3. Translucent and Hidden-Until-Lit Surfaces
4.4. Functional Films and Printed Circuits
4.5. Surface Lighting and Optical Integration
4.6. Zonal Integration and Electronic Diagnostics
5. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY SURFACE LOCATION
5.1. Introduction
5.2. Door and Side-Trim Surfaces
5.3. Instrument Panel and Dashboard Surfaces
5.4. Center and Floor Console Surfaces
5.5. Headliner and Overhead Surfaces
5.6. Pillars and Other Functional Surfaces
6. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY PRIMARY SURFACE FUNCTION
6.1. Introduction
6.2. Illumination and Personalization
6.3. Touch and Haptic Control
6.4. Status, Warning and Information
6.5. Embedded Proximity and Occupant Sensing
6.6. Multifunctional Surface Systems
7. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY INTEGRATION TECHNOLOGY
7.1. Introduction
7.2. Conventional PCB and LED Modules
7.3. Laminated Circuits and Functional Foils
7.4. In-Mold Structural Electronics
7.5. Printed and Other Embedded Electronics
8. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY SURFACE MATERIAL PLATFORM
8.1. Introduction
8.2. Molded Polymer and Decorated Substrates
8.3. Soft-Touch Skins and Synthetic Leather
8.4. Functional Films and Optical Layers
8.5. Textiles and Light-Permeable Soft Surfaces
8.6. Natural-Fiber and Other Sustainable Platforms
9. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY SUPPLIER MODEL
9.1. Introduction
9.2. Integrated Smart-Surface Assemblies
9.3. Surfaces with Modular Electronics
9.4. Functional-Foil and Electronics Subassemblies
10. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY VEHICLE TYPE
10.1. Introduction
10.2. Passenger Vehicles
10.3. Light Commercial Vehicles
10.4. Medium and Heavy Commercial Vehicles and Buses
11. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY PROPULSION
11.1. Introduction
11.2. Internal-Combustion-Only Vehicles
11.3. Hybrid and Plug-In Hybrid Vehicles
11.4. Battery Electric Vehicles
12. AUTOMOTIVE SMART INTERIOR SURFACES MARKET BY GEOGRAPHY
12.1. North America
12.1.1. United States
12.1.2. Canada
12.1.3. Mexico
12.2. South America
12.2.1. Brazil
12.2.2. Argentina
12.2.3. Others
12.3. Europe
12.3.1. Germany
12.3.2. United Kingdom
12.3.3. France
12.3.4. Italy
12.3.5. Spain
12.3.6. Others
12.4. Middle East and Africa
12.4.1. Saudi Arabia
12.4.2. UAE
12.4.3. South Africa
12.4.4. Others
12.5. Asia Pacific
12.5.1. China
12.5.2. Japan
12.5.3. South Korea
12.5.4. India
12.5.5. Indonesia
12.5.6. Thailand
12.5.7. Others
13. COMPETITIVE ENVIRONMENT AND ANALYSIS
13.1. Major Players and Strategy Analysis
13.2. Market Share Analysis
13.3. Mergers, Acquisitions, Agreements and Collaborations
13.4. Competitive Dashboard
14. COMPANY PROFILES
14.1. Antolin
14.2. Yanfeng Automotive Interiors
14.3. Valeo
14.4. Marelli
14.5. Toyota Boshoku Corporation
14.6. Toyoda Gosei Co., Ltd.
14.7. Motherson Group
14.8. FORVIA HELLA
14.9. TactoTek Oy
14.10. Nissha Co., Ltd.
14.11. Continental Surface Solutions
14.12. UltraSense Systems, Inc.
15. APPENDIX
15.1. Currency
15.2. Assumptions
15.3. Base and Forecast Years Timeline
15.4. Key Benefits for Stakeholders
15.5. Research Methodology
15.6. Abbreviations
Navigate
Trusted by the world's leading organizations











