
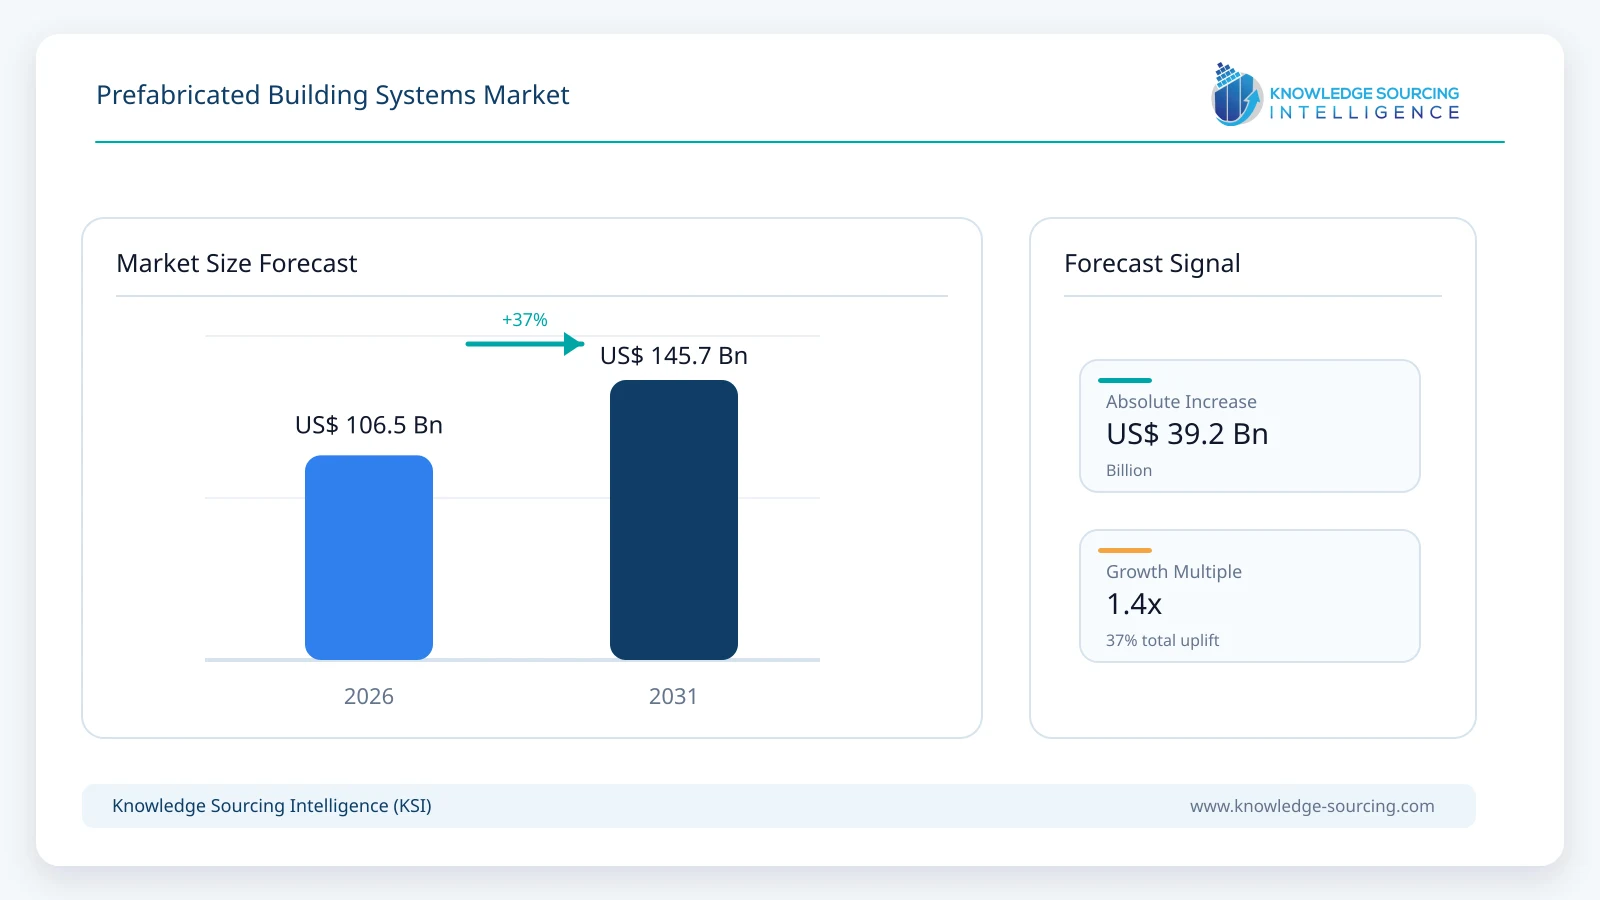
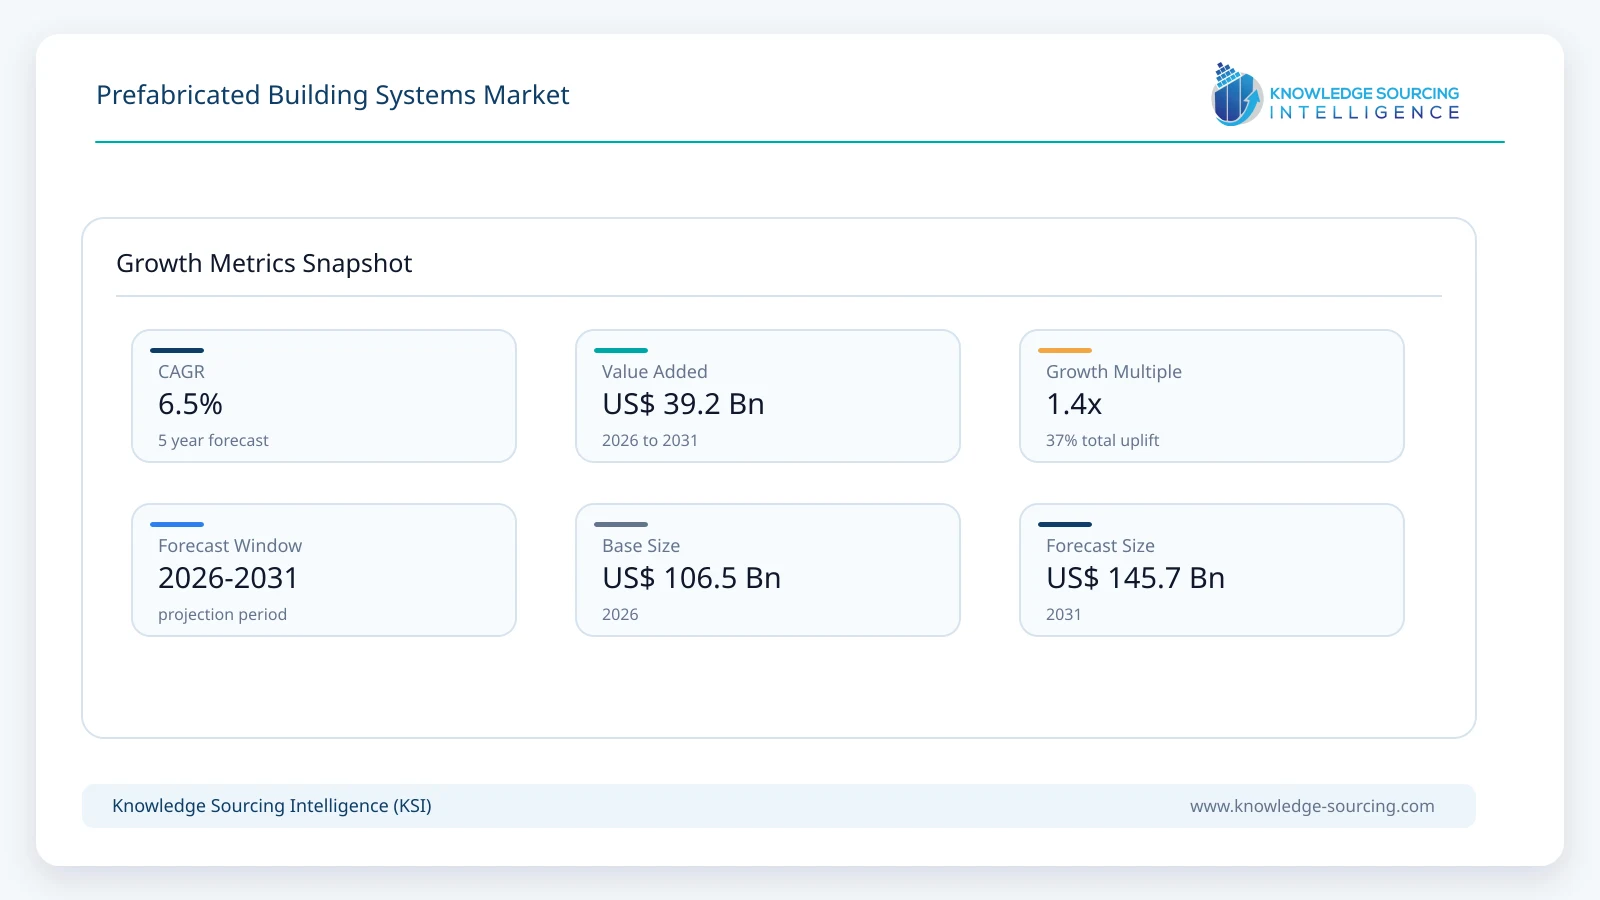
The global prefabricated building systems market is forecast to grow from USD 106.50 billion in 2026 to USD 145.70 billion in 2031, representing a CAGR of 6.47% over the forecast period.
Highlights:
- 1Metal systems account for approximately 44.0% of global prefabricated building systems revenue in 2026.
- 2Panel systems represent approximately 43.0% of global 2026 market revenue.
- 3Residential applications account for approximately 52.0% of global prefabricated building systems revenue in 2026.
- 4Asia Pacific represents approximately 44.0% of global 2026 market revenue.
- 5Factory-built housing and modular infrastructure remain the largest commercial value pools, while mass timber and hybrid prefabrication are expanding in public, healthcare and commercial projects.
- 6The competitive landscape is shifting toward vertically integrated design-manufacture-installation models rather than general contractors using prefabrication only at project level.
Current supplier scale supports a market above USD 100 billion. Champion Homes generated approximately USD 2.66 billion of fiscal 2026 revenue from factory-built housing and related operations, while Cavco generated USD 2.25 billion in fiscal 2026. ATCO Structures & Logistics generated CAD 1.28 billion in 2025, with modular structures representing a major part of segment activity. Daiwa House and Sekisui House operate at substantially larger scale across industrialized and factory-assisted construction, while Modulaire Group operates more than 330,000 modular space and portable-storage units across 23 countries.
Market participation spans several distinct categories, including volumetric modular manufacturers, factory-built housing producers, pre-engineered metal building suppliers and mass-timber system providers. General contractors increasingly use prefabricated components in project delivery, but the core commercial market remains centered on companies that design, manufacture, supply or integrate standardized off-site building systems. This distinction is important because the economics of factory utilization, logistics, repeatable design and product certification differ materially from conventional project-based construction.
Growth through 2031 is supported by construction-labor shortages, demand for faster project delivery, tighter quality control, public-sector infrastructure needs, housing shortages and sustainability goals. Growth is moderated by transportation constraints, factory-capacity requirements, local building-code differences and the risk of underutilized manufacturing capacity when project pipelines weaken.
Prefabricated Building Systems Market Trends
Permanent Modular Construction Moves Beyond Temporary Space
Modern modular systems are increasingly used for permanent schools, healthcare buildings, offices, defence facilities and residential projects rather than only temporary accommodation. Wernick, Portakabin, ATCO Structures and Modulaire Group all market permanent modular solutions alongside relocatable or hire fleets. This expands the addressable market into higher-value buildings with longer design lives and more complex finishes.
Hybrid Prefabrication Becomes More Common
Complex buildings increasingly combine volumetric modules with site-built or panelized sections. Portakabin describes hybrid modular construction as a way to use modules for repeatable spaces while retaining conventional construction for bespoke or heavy-infrastructure areas. Healthcare and education are particularly suited to this approach because repetitive rooms can be factory-built while specialist spaces remain site constructed.
Mass Timber Expands the Material Mix
Cross-laminated timber and other engineered wood systems are gaining share in residential, education and commercial buildings. Stora Enso's Ybbs mill reached one million cubic metres of CLT delivered in June 2026, demonstrating the scale achieved by prefabricated timber construction. High factory precision and lighter structural weight make mass timber increasingly relevant to low-carbon building strategies.
Circular and Relocatable Building Models Gain Importance
Relocatable modular fleets support reuse and asset life extension rather than one-time construction. Modulaire Group continues to position its business around a circular 'Loops within Loops' model, while Wernick and ATCO also support hire, refurbishment and redeployment. This is widening the economic case for prefabrication in sectors with changing space requirements.
Prefabrication Expands into High-Complexity Infrastructure
Healthcare, data centers, defence and high-tech construction increasingly use prefabricated pods, MEP modules, precast assemblies and modular support buildings. Skanska's 2026 projects show off-site fabricated exam-room pods and multi-service MEP modules being used to reduce on-site congestion and shorten schedules. These applications raise technical requirements but also increase the value of off-site systems.
Global Prefabricated Building Systems Market Segment Analysis
By Material Type
Metal
Metal-based prefabricated building systems are estimated at approximately USD 46.86 billion in 2026. The segment is the largest material category because steel frames and metal panels are widely used across volumetric modular buildings, pre-engineered industrial structures, workforce accommodation, schools, commercial facilities and relocatable buildings. Steel provides high strength-to-weight performance, standardized fabrication and long transport durability, while factory welding and bolted connections support rapid site assembly. Nucor Building Systems, BlueScope Buildings, Zamil Steel, Kirby Building Systems, ATCO Structures, Wernick and Modulaire Group all use steel-based structural systems across major product lines. Metal is expected to remain the largest material category through 2031 despite faster growth in mass timber.
By System Type
Panel System
Panel systems are estimated at approximately USD 45.80 billion in 2026. The segment includes factory-manufactured wall, floor and roof panels in steel, timber, concrete and composite formats that are transported to site and assembled into the final structure. Panelization is widely used because it captures a large share of off-site productivity benefits without requiring the transport of fully volumetric modules. It is particularly important in housing, industrial buildings and mass-timber projects, where standardized panels can be manufactured at high throughput and assembled quickly. Panel systems also integrate effectively with hybrid construction, allowing conventional foundations and cores to be combined with factory-produced building envelopes and structural elements.
By Application
Residential
Residential applications are estimated at approximately USD 55.38 billion in 2026. Housing remains the largest application because factory-built homes, modular homes, panelized housing and industrialized housing systems address affordability, labor availability and construction-speed constraints across multiple regions. Champion Homes sold 26,622 homes in fiscal 2026 and generated USD 2.66 billion of revenue, while Cavco generated USD 2.25 billion in fiscal 2026 and continues to expand manufacturing capacity. Daiwa House and Sekisui House maintain large industrialized-housing operations in Japan and international markets. Residential prefabrication is expected to remain the largest application through 2031 as housing shortages and cost pressures support factory-based production.
By Geography
Asia Pacific
Asia Pacific is estimated at approximately USD 46.86 billion in 2026. The region combines major industrialized-housing markets in Japan, large-scale construction demand in China and India, extensive prefabricated manufacturing capability and rising adoption of modular infrastructure across Australia and Southeast Asia.
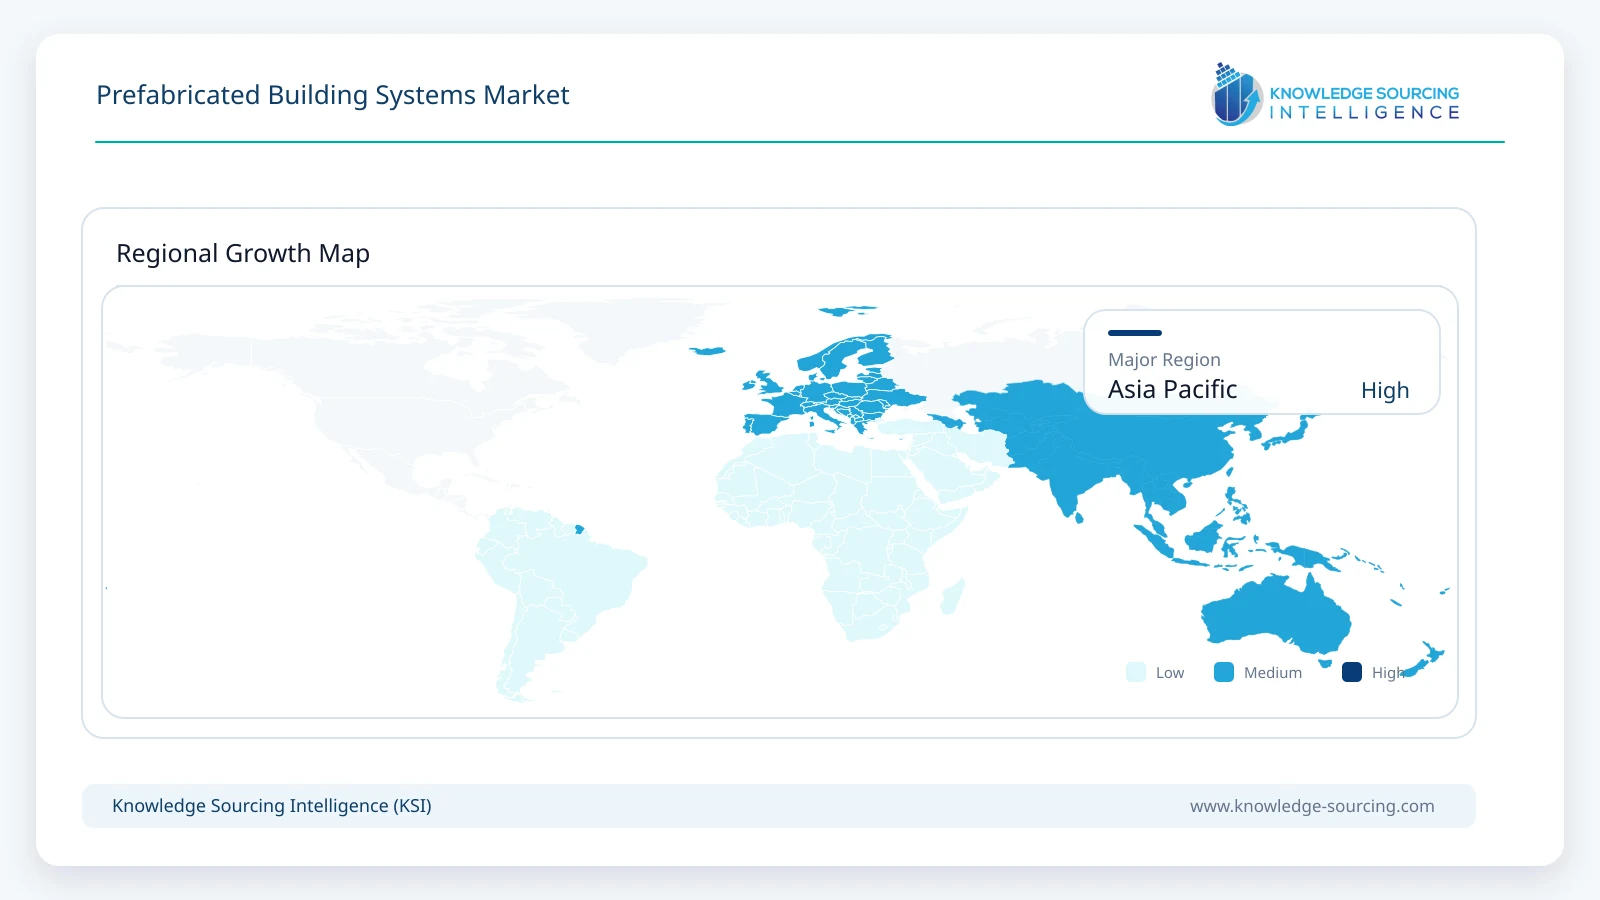
Daiwa House and Sekisui House are long-established industrialized-construction companies, while ATCO and Modulaire Group operate significant Australian modular businesses. Urbanization, manufacturing investment, public infrastructure and labor-productivity requirements are expected to keep Asia Pacific the largest regional market through 2031.
Market Drivers
Construction Labor Shortages
Prefabrication shifts labor from dispersed construction sites into repeatable factory processes, reducing dependence on scarce on-site trades and improving productivity. This is particularly important in North America, Europe, Japan and other markets facing aging workforces.
Need for Faster Project Delivery
Off-site manufacturing can proceed in parallel with foundation and site work, shortening overall project schedules. Speed is a major advantage in schools, healthcare, defence, data centers and workforce accommodation where capacity is often needed quickly.
Housing Affordability and Supply Constraints
Factory-built housing can reduce construction time, material waste and site labor compared with conventional methods. Housing shortages are therefore creating policy and commercial support for manufactured and modular homes.
Quality and Process Standardization
Controlled manufacturing environments allow repeatable quality checks, tighter tolerances and standardized workflows. This can reduce weather disruption and improve consistency across multi-site building programs.
Sustainability and Material Efficiency
Factory production improves material utilization and supports reuse of modular assets. Timber systems also provide lower-carbon structural options, while modular fleets can be relocated and refurbished rather than demolished.
Market Restraints
High Factory Investment
Prefabricated construction requires manufacturing facilities, specialized equipment and engineering systems. Underutilized factories can become financially burdensome when project pipelines weaken.
Transportation and Module-Size Constraints
Volumetric modules must comply with road transport limits and site-access conditions. Long distances or constrained urban sites can reduce the economic advantage of factory manufacture.
Building-Code and Certification Differences
Building standards vary by country and jurisdiction, limiting the ability to use one standardized design globally without engineering changes and local approvals.
Design Freeze Requirements
Factory production rewards early design decisions. Late changes can disrupt manufacturing schedules and reduce the speed advantage compared with conventional construction.
Perception and Financing Barriers
Some buyers and lenders still associate prefabricated buildings with temporary or lower-quality construction. Modern permanent modular systems have improved materially, but market education remains necessary in some segments.
Competitive Landscape
The market is fragmented across several business models. Daiwa House and Sekisui House combine industrialized construction with broader housing and real-estate operations. ATCO Structures, Modulaire Group, Wernick Group, Portakabin and Mobile Modular specialize in modular and relocatable space. Champion Homes and Cavco are major factory-built housing producers, while Nucor Building Systems, BlueScope Buildings, Zamil Steel and Kirby Building Systems focus on pre-engineered metal buildings. Stora Enso and KLH Massivholz supply engineered timber systems used in prefabricated construction.
The competitive landscape differs materially by business model. Modular manufacturers compete on factory throughput, design flexibility and installation capability; factory-built housing companies compete on standardized residential production and distribution; pre-engineered building suppliers compete on structural efficiency and project scale; and mass-timber suppliers compete on engineering support, carbon performance and prefabrication precision. General contractors influence adoption through project specifications, but the principal market participants are the companies that manufacture or commercialize the prefabricated systems themselves.
Competitive advantage depends on factory utilization, design standardization, logistics capability, local approvals and the ability to deliver projects from design through installation. Rental and relocatable providers also benefit from asset utilization and refurbishment capability, while permanent modular providers compete on architectural flexibility, lifecycle performance and compliance with conventional building standards.
Recent Developments
September 2026: Cavco introduced the Grande Arbor, described as the first HUD-code manufactured home built without a conventional steel chassis, reflecting continued innovation in factory-built residential systems.
July 2026: Portakabin was appointed to deliver the first Cadet Super Centre in the East Midlands, providing modular training and office facilities for the East Midlands Reserve Forces and Cadets Association.
June 2026: Stora Enso's Ybbs mill in Austria reached one million cubic metres of cross-laminated timber delivered, demonstrating the increasing scale of prefabricated mass-timber construction.
May 2026: Wernick opened a new Inverness depot following more than GBP 25 million of investment in Scotland over five years, expanding its modular hire and building network.
May 2026: Cavco announced a new manufacturing facility in El Mirage, Arizona, expanding factory-built housing capacity.
May 2026: ATCO Structures reported multiple new modular awards, including work linked to mining developments, data-center construction, defence and a 1,052-person dormitory lodge for the Stibnite Gold Project.
Market Outlook
The prefabricated building systems market is expected to maintain mid-single-digit growth through 2031 as off-site construction gains share across housing, public infrastructure, commercial buildings and industrial facilities. Growth will be driven by labor productivity, schedule certainty and the need to increase construction output without proportional growth in site labor.
Metal systems and panelized construction will remain the largest revenue pools, while mass timber and hybrid modular construction are expected to gain share in applications where carbon performance and architectural flexibility are important. Permanent modular buildings will continue to narrow the quality and design gap with conventional construction.
Asia Pacific will remain the largest regional market, supported by industrialized housing and construction scale, while North America and Europe continue to expand modular housing, healthcare, education and high-tech applications. Suppliers with strong factory utilization, engineering capability, local approval expertise and integrated installation networks are best positioned.
Global Prefabricated Building Systems Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 106.50 billion |
| Total Market Size in 2031 | USD 145.70 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.47% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Material Type, System Type, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Material Type
Metal
Timber
Concrete
Composite and Other Materials
By System Type
Panel System
Volumetric / Cellular System
Skeleton / Frame System
Combined / Hybrid System
By Application
Residential
Commercial
Industrial
Education and Healthcare
Infrastructure, Defence and Workforce Accommodation
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Construction Labor Shortages
4.1.2. Need for Faster Project Delivery
4.1.3. Housing Affordability and Supply Constraints
4.1.4. Quality and Process Standardization
4.1.5. Sustainability and Material Efficiency
4.2. Market Restraints
4.2.1. High Factory Investment
4.2.2. Transportation and Module-Size Constraints
4.2.3. Building-Code and Certification Differences
4.2.4. Design Freeze Requirements
4.2.5. Perception and Financing Barriers
5. PREFABRICATED BUILDING SYSTEMS MARKET BY MATERIAL TYPE
5.1. Metal
5.2. Timber
5.3. Concrete
5.4. Composite and Other Materials
6. PREFABRICATED BUILDING SYSTEMS MARKET BY SYSTEM TYPE
6.1. Panel System
6.2. Volumetric / Cellular System
6.3. Skeleton / Frame System
6.4. Combined / Hybrid System
7. PREFABRICATED BUILDING SYSTEMS MARKET BY APPLICATION
7.1. Residential
7.2. Commercial
7.3. Industrial
7.4. Education and Healthcare
7.5. Infrastructure, Defence and Workforce Accommodation
8. PREFABRICATED BUILDING SYSTEMS MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. United Kingdom
8.3.2. Germany
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. South Korea
8.5.5. Australia
8.5.6. Southeast Asia
8.5.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Modular and Factory-Built Housing Positioning
9.3. Pre-Engineered and Panelized Building Systems
9.4. Timber and Hybrid Prefabrication
9.5. Rental, Reuse and Circular Business Models
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. Daiwa House Industry Co., Ltd.
10.2. Sekisui House, Ltd.
10.3. ATCO Structures
10.4. Modulaire Group
10.5. Wernick Group
10.6. Portakabin
10.7. McGrath RentCorp / Mobile Modular
10.8. Champion Homes, Inc.
10.9. Cavco Industries, Inc.
10.10. Nucor Building Systems
10.11. BlueScope Buildings
10.12. Zamil Steel Pre-Engineered Buildings
10.13. Kirby Building Systems
10.14. Stora Enso Building Solutions
10.15. KLH Massivholz GmbH
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Abbreviations





Frequently asked questions
What is the projected market size for prefabricated building systems by 2031?
The Prefabricated Building Systems Market is projected to reach USD 145.70 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for the market from 2026 to 2031?
The Prefabricated Building Systems Market is forecast to grow at a 6.47% CAGR.
Which material type holds the largest market share in 2026?
Metal systems accounted for approximately 44.0% of 2026 market revenue.
Which application segment dominates the Prefabricated Building Systems Market in 2026?
Residential applications account for 52.0% of 2026 global revenue.
Which geographic region holds the largest market share in 2026?
Asia Pacific represents approximately 44.0% of global 2026 market revenue.
What are the primary growth drivers for the Prefabricated Building Systems Market?
Labor shortages, faster delivery, quality control, and housing needs drive growth.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Prefabricated Building Systems Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/prefabricated-building-systems-market