
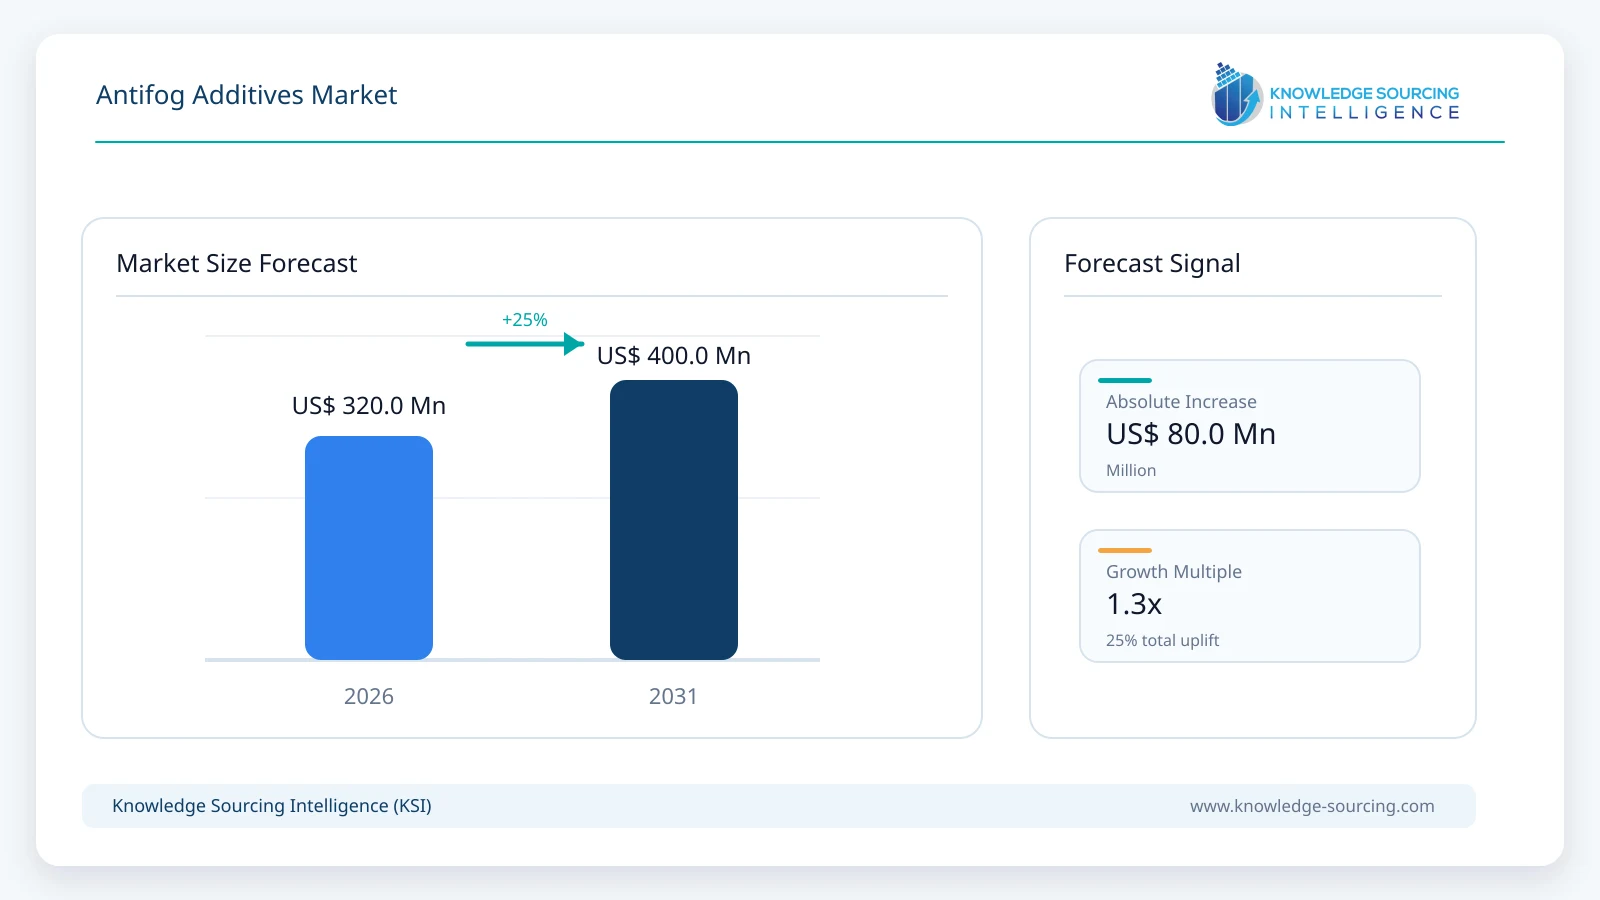
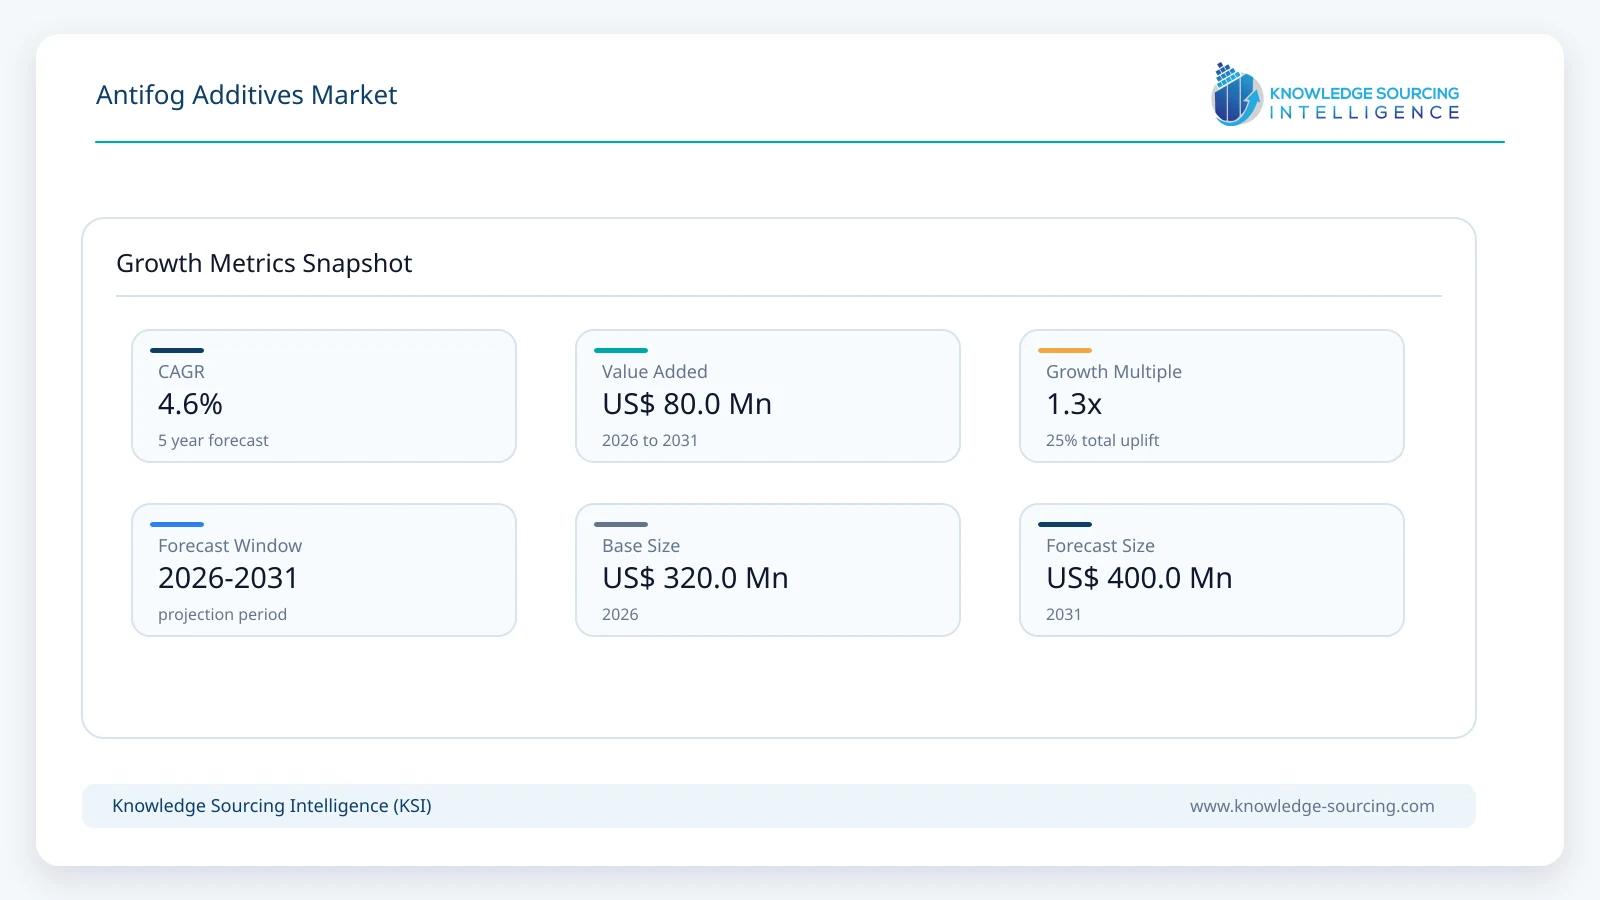
The antifog additives market is forecast to grow at a CAGR of 4.6%, reaching USD 400.0 million in 2031 from USD 320.0 million in 2026.
Highlights:
- 1Packaging manufacturers are increasingly incorporating antifog additives to improve visibility in food packaging films.
- 2Food producers are increasingly adopting antifog solutions to maintain product visibility and enhance consumer appeal.
- 3Polymer processors are developing advanced antifog formulations for agricultural films and refrigerated packaging applications.
- 4Manufacturers are prioritizing compatible antifog additives to improve film performance and meet evolving packaging requirements.
The antifog additives market is supported by the demand for transparent plastic films used in food packaging, agricultural production, and other moisture-sensitive applications. Antifog additives are functional ingredients incorporated into polymer films or applied as coatings to reduce the formation of discrete water droplets on transparent surfaces. Condensation can obscure the contents of a package or reduce the amount of light passing through a greenhouse film. Antifog formulations address this issue by modifying surface tension, allowing condensed moisture to spread into a more uniform layer and improving visual clarity.
The market's development is closely associated with the performance requirements of flexible packaging, fresh-food distribution, and protected agriculture. Packaging converters need films that maintain visibility under changing temperatures and humidity, while greenhouse operators require materials that allow adequate light transmission. The effectiveness of an antifog additive depends on the polymer substrate, additive concentration, migration characteristics, processing conditions, storage temperature, and intended application. Consequently, a formulation designed for chilled food packaging may not deliver equivalent performance in a greenhouse film or a different polymer system.
Antifog additives include glycerol esters, polyglycerol esters, sorbitan esters of fatty acids, ethoxylated sorbitan esters, polyoxyethylene esters, and other application-specific chemistries. Commercial products may be supplied as concentrated additives or incorporated into polymer-compatible masterbatches. Product selection depends on fogging conditions, processing requirements, food-contact regulations, optical performance, and compatibility with other additives. Plant-based and food-grade formulations are also available, although the suitability of any product must be assessed against its technical documentation and applicable regulatory approvals.
Avient's Cesa™ antifog portfolio addresses food packaging and horticultural films, while Palsgaard's Einar® products cover polyethylene, polypropylene, and selected coating applications. These product portfolios illustrate how suppliers are addressing different polymer systems and performance requirements rather than relying on a single universal formulation. Official product information is available from Avient and Palsgaard.
According to Eurostat's 2025 edition of Key Figures on the European Food Chain, the European Union produced 258 million tonnes of cereals, 162 million tonnes of raw milk, and 21 million tonnes of pigmeat in 2024. These production volumes demonstrate the scale of the regional food system and the importance of packaging, storage, and distribution infrastructure. They are indirect indicators of potential packaging demand rather than direct measurements of antifog additive consumption.
The OECD-FAO Agricultural Outlook 2025–2034 projects global agricultural and fish production to increase by approximately 14% over the decade. The outlook identifies productivity improvements and growing demand for animal-source foods as important contributors to this expansion. These developments support the longer-term relevance of food packaging and protected agriculture, although the relationship between agricultural output and antifog additive sales depends on packaging formats, film penetration, and formulation requirements.
Antifog Additives Market Growth Drivers:
Rising demand from the agriculture industry
Protected agriculture is an important application area for antifog additives because condensation on greenhouse films can reduce transparency and interfere with the transmission of light to crops. Under suitable growing conditions, films that limit the formation of discrete droplets can improve the optical environment inside a greenhouse. The commercial benefit depends on factors such as crop type, greenhouse design, climate, film thickness, additive durability, and the frequency of condensation. Antifog additives therefore form part of a broader set of technologies used to improve protected-cultivation performance.
Government agricultural statistics demonstrate the scale of activity that underpins this application. India's Ministry of Agriculture and Farmers Welfare reported that horticultural production reached approximately 369.1 million tonnes in 2024–25 in its third advance estimates. The ministry also reported that foodgrain production increased from 265.0 million tonnes in 2013–14 to 357.7 million tonnes in 2024–25. These figures indicate substantial agricultural production, but they should not be interpreted as direct evidence of antifog additive sales or as proof that all production growth requires greenhouse films.
Antifog additives are particularly relevant where producers use protected cultivation to manage humidity, temperature, pests, or seasonal growing conditions. Greenhouse films must balance light transmission, mechanical durability, weather resistance, and service life. An additive that improves transparency but compromises film strength, processing stability, or long-term performance may not be commercially suitable. Suppliers therefore need to demonstrate performance under the intended operating conditions.
Another factor is the need to use agricultural inputs efficiently. The OECD-FAO Agricultural Outlook 2025–2034 projects global cereal production to grow by approximately 1.1% annually through 2034, with yield improvements contributing more than increases in harvested area. This broader focus on productivity can support interest in protected-cultivation technologies, although the outlook does not quantify antifog film adoption. For the antifog additives market, the most relevant opportunities are consequently associated with documented greenhouse-film installations, film-converter activity, and demand for higher-performance agricultural plastics.
Growing demand from the packaging industry
Food packaging is another major application area because condensation frequently occurs when packaged products move between production, refrigerated storage, transportation, and retail display. Water droplets can obscure fresh produce, meat, prepared foods, and other products sold in transparent containers or films. Antifog additives help maintain visibility by encouraging moisture to spread across the film surface instead of remaining as separate droplets.
Eurostat's Key Figures on the European Food Chain, published in December 2025, provides recent official evidence of the scale of food production and distribution in Europe. The EU produced 21 million tonnes of pigmeat and 162 million tonnes of raw milk in 2024. These figures highlight the importance of packaging and cold-chain systems for food products, but the volume of food produced does not translate directly into demand for antifog additives. Packaging material, product format, storage conditions, and the share of applications requiring antifog performance all affect actual consumption.
The OECD-FAO Agricultural Outlook 2025–2034 also projects global meat production to reach approximately 406 million tonnes in carcass-weight equivalent by 2034, representing an increase of about 13% from the estimated 2024 level. Poultry is expected to account for a substantial share of additional meat production. This expansion may support demand for suitable food packaging films, including formulations that maintain clarity in chilled or moisture-prone conditions. Nevertheless, antifog additives are not required in every meat package, and their adoption depends on the packaging technology selected by processors and converters.
Packaging manufacturers are also evaluating formulations that meet food-contact requirements while maintaining mechanical, optical, and barrier properties. Palsgaard's official product information describes plant-based, food-grade antifog additives for polyethylene and polypropylene films, as well as a coating solution for selected polymers. Avient's Cesa™ antifog products address food packaging and horticultural applications. These examples demonstrate active commercial product availability and the importance of matching additive performance to the final packaging structure.
For manufacturers, the opportunity is not limited to increasing food output. It also includes the replacement of existing formulations, improvements in processing efficiency, and the development of products suitable for different hot-fog and cold-fog conditions. However, longer shelf life, food-waste reduction, or improved food safety should be claimed only where supported by application-specific evidence. Antifog performance improves visibility; it does not independently guarantee microbial control or prevent food spoilage.
Advancements in antifog additive formulations
Formulation development is creating opportunities for suppliers to differentiate products through performance, regulatory suitability, and compatibility with specific polymers. Antifog additives must achieve the required surface effect without causing unacceptable haze, blocking, changes in coefficient of friction, or deterioration in other film properties. The formulation must also remain effective under the temperature, humidity, and storage conditions expected in the final application.
Polyglycerol esters, glycerol esters, sorbitan-based compounds, and other surface-active chemistries are used in different antifog formulations. Their performance varies with molecular structure, concentration, polymer compatibility, and migration behaviour. Some products are designed for internal incorporation into a polymer, whereas others are formulated for surface coating. These approaches should not be treated as interchangeable because their processing methods, performance characteristics, and regulatory considerations differ.
Plant-based feedstocks and food-contact suitability are increasingly visible in suppliers' product positioning. Palsgaard describes its Einar® antifog portfolio as plant-based and food-grade, with products for polyethylene, polypropylene, and selected coated-film applications. Such claims must be interpreted product by product: a plant-derived feedstock does not automatically establish that a finished formulation is biodegradable, compostable, or environmentally superior throughout its life cycle.
Manufacturers are also developing complementary polymer additives to address processability, surface properties, and regulatory requirements. In January 2026, Avient announced an expansion of its Hiformer™ non-PFAS process-aid portfolio into Asia with two new liquid grades for polyolefin film applications. The announcement concerns processing aids, not a new antifog product, but it illustrates broader innovation in film-additive formulations and the relevance of regional technical support for packaging converters.
For the antifog additives market, the key commercial opportunity is the development of products that meet defined performance requirements while preserving the mechanical, optical, and processing characteristics of the film. Validation through technical data, application trials, and appropriate food-contact documentation remains essential before a formulation can be considered suitable for a particular end use.
Antifog Additives Market Restraints:
The antifog additives market faces technical, economic, and regulatory challenges. The first is formulation compatibility. An additive must perform effectively in the selected polymer without creating unacceptable changes in transparency, mechanical strength, sealing performance, friction, or other surface properties. A formulation that works well in one film structure may require adjustment for another polymer, processing method, or storage condition. This can increase testing requirements and lengthen qualification cycles for converters and brand owners.
Another consideration is performance durability. Internal antifog additives generally need to reach the film surface to influence condensation. Their effectiveness can therefore depend on migration behaviour, temperature, humidity, and the composition of the polymer. If the additive migrates too slowly, performance may not develop quickly enough; if its behaviour is unsuitable for the application, the desired effect may not persist for the required period. Surface-coated formulations have different requirements, including coating uniformity, drying, adhesion, and compatibility with downstream processes.
Regulatory compliance is particularly important for food-contact applications. Manufacturers must confirm that the selected formulation complies with the relevant rules in the intended market and that any claims concerning food-contact suitability are supported by the appropriate documentation. Regulatory approval in one jurisdiction should not automatically be assumed to apply in another. Reformulation, testing, documentation, and customer qualification can add cost and complexity.
Environmental considerations may also affect product selection. Buyers increasingly assess feedstock sourcing, chemical composition, packaging recyclability, and the compatibility of additives with recycling processes. However, the environmental performance of an antifog additive cannot be determined solely from whether its feedstock is plant-based. A credible assessment requires evidence about the complete formulation, its intended use, and relevant life-cycle impacts. Alternative packaging materials can also influence demand, although transparent plastics may continue to offer functional advantages in specific applications.
Finally, the market is exposed to fluctuations in raw-material prices, competition among additive suppliers, and the availability of technically qualified alternatives. Customers may seek lower-cost formulations or reduce additive loading where performance permits. Suppliers must therefore demonstrate consistent results, provide application support, and balance product cost against the performance required by film manufacturers and end users.
Antifog Additives Market Geographical Outlook:
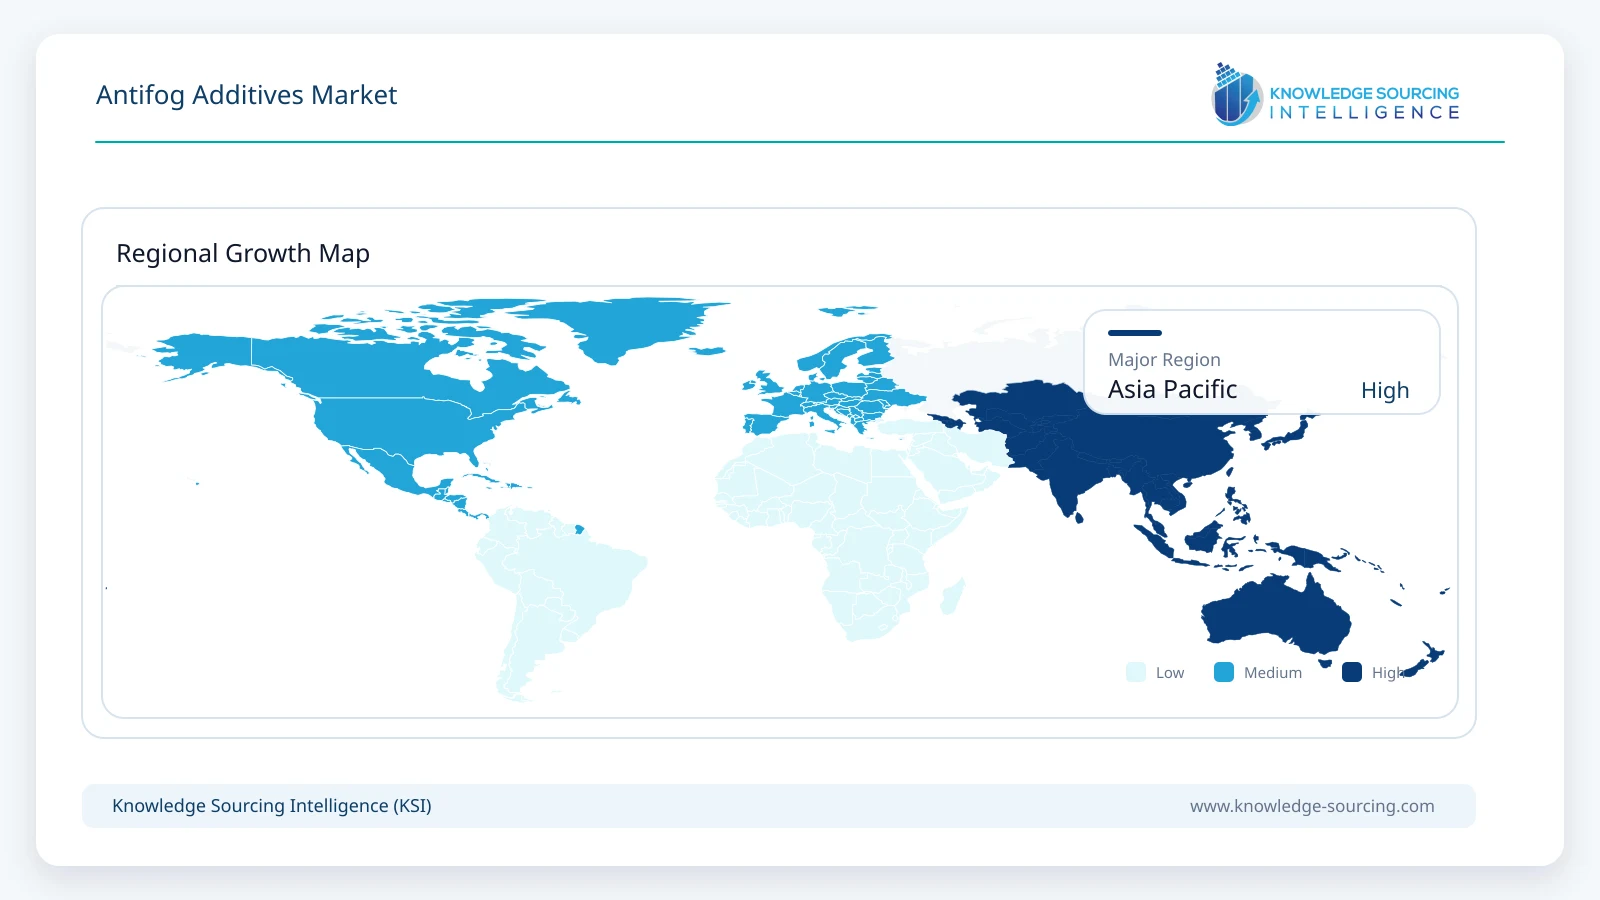
Asia-Pacific is positioned for significant market opportunities during the forecast period.
Asia-Pacific is an important region for antifog additives because it combines large agricultural systems, substantial food production, growing urban populations, and a broad plastics-converting industry. China, India, Japan, South Korea, Thailand, and Indonesia have different agricultural structures and packaging requirements, creating opportunities across greenhouse films, fresh-food packaging, and other moisture-sensitive applications. However, the relative size and growth of the antifog additives market in each country must be established through direct market data rather than inferred solely from population or agricultural output.
India offers a relevant example of the agricultural scale underlying regional demand. The Ministry of Agriculture and Farmers Welfare's third advance estimates for 2024–25 placed horticultural production at approximately 369.1 million tonnes. The ministry's March 2026 communication also highlighted the increase in foodgrain and horticultural production over the longer term. These government statistics provide a sound basis for discussing India's agricultural and food-supply ecosystem, but they do not establish the amount of agricultural land under protected cultivation or the volume of antifog additives consumed.
Food processing and packaging infrastructure are additional considerations for the Indian market. As processors expand distribution beyond local markets, packaging formats must accommodate handling, transport, storage, and retail presentation. Antifog formulations may be relevant to transparent packages for chilled or moisture-prone products, provided the packaging design requires this function. Demand will depend on the penetration of modern packaging, the types of polymers used, and the specifications selected by film converters and food manufacturers.
China also represents an important market to evaluate because of its extensive food production, manufacturing capacity, and plastics-conversion industries. Japan and South Korea provide additional opportunities where specialised packaging materials and technical film performance are important. Southeast Asian markets may benefit from agricultural production, food processing, and regional manufacturing supply chains. The actual contribution of these countries to market revenue should be supported by verified sales, production, trade, or company-level evidence.
The OECD-FAO Agricultural Outlook 2025–2034 projects global agricultural and fish production to expand by approximately 14% over the decade. It identifies middle-income regions, including parts of Asia, as important contributors to agricultural growth. This creates a relevant demand context for packaging and agricultural-film suppliers, but the forecast does not specifically rank Asia-Pacific as the largest antifog additives market. Any claim that the region will dominate should be supported by the report's own regional market estimates.
North America
North America presents opportunities through food packaging, greenhouse production, and an established polymer-additives industry. The United States, Canada, and Mexico have different crop profiles, climatic conditions, manufacturing networks, and food distribution requirements. Demand for antifog additives is likely to be concentrated in applications where transparent films must maintain clarity under chilled storage or humid growing conditions. Suppliers also need to address the relevant food-contact requirements and technical specifications for each market.
Europe
Europe is an important market to assess because of its established food-processing industry, greenhouse cultivation, and emphasis on packaging performance and material compliance. Eurostat reported that EU agricultural output in 2024 included €72.0 billion from vegetables and horticultural products, €78.6 billion from milk, and €46.8 billion from pigs. These production values provide context for the region's agricultural and food industries, but they do not directly measure demand for antifog additives. Product adoption depends on packaging specifications, polymer choice, and the relevant regulatory requirements.
European converters and additive suppliers must also evaluate the implications of packaging-waste rules, food-contact requirements, and broader material-efficiency objectives. The effect of these policies on antifog formulations will depend on the particular material and application. It would be inaccurate to assume that every regulatory change automatically favours or restricts antifog additives.
South America
South America offers potential demand through agricultural production, fresh-food distribution, and food-processing industries, particularly in Brazil and Argentina. Greenhouse and agricultural-film requirements vary according to crop type, climate, and production methods. Packaging applications also depend on the development of cold chains, retail distribution, and local film-converting capacity. Market estimates should distinguish direct additive sales from the value of the wider agricultural-plastics or packaging industries.
Middle East and Africa
The Middle East and Africa provide opportunities associated with protected agriculture, high-temperature environments, food imports, and investment in food supply chains. In water-constrained locations, controlled-environment agriculture can be relevant to food-production strategies, while clear greenhouse films may require effective condensation management. Nevertheless, climatic conditions alone do not establish demand. Investment in greenhouse infrastructure, suitable film materials, supply-chain capacity, and product economics will influence the adoption of antifog additives.
Antifog Additives Market Key Developments:
May 2026: Cosmo First confirmed its anti-fog transparent BOPET lidding film launch in its FY2026 results announcement, documenting the product as a specialty films development.
April 2026: Avient announced the launch of Hiformer™ Slip + Antistatic for biaxially oriented polypropylene films in Latin America. The formulation combines slip and antistatic functionality to simplify film production. This is an adjacent film-additive development, not an antifog product launch, and is relevant primarily as evidence of continued innovation in polymer-film processing.
February 2026: Cosmo Films launched its sealable, peelable transparent anti-fog BOPET lidding film, featuring a condensation-resistant coating for refrigerated and fresh-food packaging.
February 2026: Emery Oleochemicals announced that it had received an EcoVadis Silver Medal for sustainability performance, placing it among the top 15% of organisations assessed over the preceding 12 months, according to the company. This is a corporate sustainability development rather than an antifog-specific product launch. Its relevance to this market is limited to broader supplier sustainability considerations and should not be interpreted as evidence of new antifog capacity or sales.
January 2026: Avient announced the expansion of its Hiformer™ non-PFAS process-aid portfolio into Asia with two new liquid grades for polyolefin film applications, including food packaging and agricultural films. The announcement concerns processing aids rather than a new antifog additive, but it demonstrates ongoing product development in the wider film-additives sector.
Antifog Additives Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 320.0 million |
| Total Market Size in 2031 | USD 400.0 million |
| Forecast Unit | Million |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Application
Agricultural Films
Food Packaging Films
Other Applications
By Type
Glycerol Esters
Polyglycerol Esters
Sorbitan Esters of Fatty Acids
Ethoxylated Sorbitan Esters
Polyoxyethylene Esters
Other Antifog Additive Chemistries
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Rest of Europe
Middle East and Africa
Saudi Arabia
United Arab Emirates
Rest of the Middle East and Africa
Asia-Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Rest of Asia-Pacific
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency and Units
1.6. Assumptions and Limitations
1.7. Base Year and Forecast Period
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary and Secondary Research
2.4. Market Sizing and Forecasting Methodology
2.5. Data Validation and Research Limitations
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
3.3. Market Size and Growth Outlook
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Rising Demand for Antifog Additives in Agricultural Films
4.1.2. Growing Demand for Antifog Additives in Food Packaging Films
4.1.3. Advancements in Antifog Additive Formulations
4.2. Market Restraints and Challenges
4.2.1. Environmental and Regulatory Considerations
4.2.2. Formulation Compatibility and Performance Limitations
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. ANTIFOG ADDITIVES MARKET BY APPLICATION
5.1. Introduction
5.2. Agricultural Films
5.3. Food Packaging Films
5.4. Other Applications
6. ANTIFOG ADDITIVES MARKET BY TYPE
6.1. Introduction
6.2. Glycerol Esters
6.3. Polyglycerol Esters
6.4. Sorbitan Esters of Fatty Acids
6.5. Ethoxylated Sorbitan Esters
6.6. Polyoxyethylene Esters
6.7. Other Antifog Additive Chemistries
7. ANTIFOG ADDITIVES MARKET BY GEOGRAPHY
7.1. Global Overview
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Rest of South America
7.4. Europe
7.4.1. United Kingdom
7.4.2. Germany
7.4.3. France
7.4.4. Italy
7.4.5. Spain
7.4.6. Rest of Europe
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. United Arab Emirates
7.5.3. Rest of the Middle East and Africa
7.6. Asia-Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Taiwan
7.6.6. Thailand
7.6.7. Indonesia
7.6.8. Rest of Asia-Pacific
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Partnerships, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Avient
9.2. Corbion
9.3. Emery Oleochemicals
9.4. Evonik Industries AG
9.5. Guangzhou CARDLO Biotechnology Co., Ltd.
9.6. Palsgaard
9.7. PCC Chemax, Inc.
9.8. Rapidmasterbatches
9.9. SILIBASE Silicone
9.10. Surya Masterbatches
9.11. Ultra-Plas Corporation
9.12. Cargill
9.13. Ashland Inc.
9.14. Biesterfeld AG
9.15. Primex Plastics Corporation
9.16. Tosaf





Frequently asked questions
What is the projected market size and growth rate for antifog additives?
Market to reach USD 400.0 million in 2031, growing at 4.6% CAGR.
What are the primary applications driving the Antifog Additives Market?
Food packaging, agricultural films, and refrigerated packaging drive market demand.
Which types of antifog additives are commonly utilized?
Glycerol esters, polyglycerol esters, and sorbitan esters are common chemistries.
How do antifog additives enhance visual clarity in packaging?
They modify surface tension, allowing condensed moisture to spread uniformly.
What factors influence antifog additive performance?
Polymer substrate, concentration, migration, processing, and application are key factors.
Which companies are noted for their antifog additive portfolios?
Avient (Cesa™) and Palsgaard (Einar®) offer diverse product portfolios.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Antifog Additives Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/antifog-additives-market