
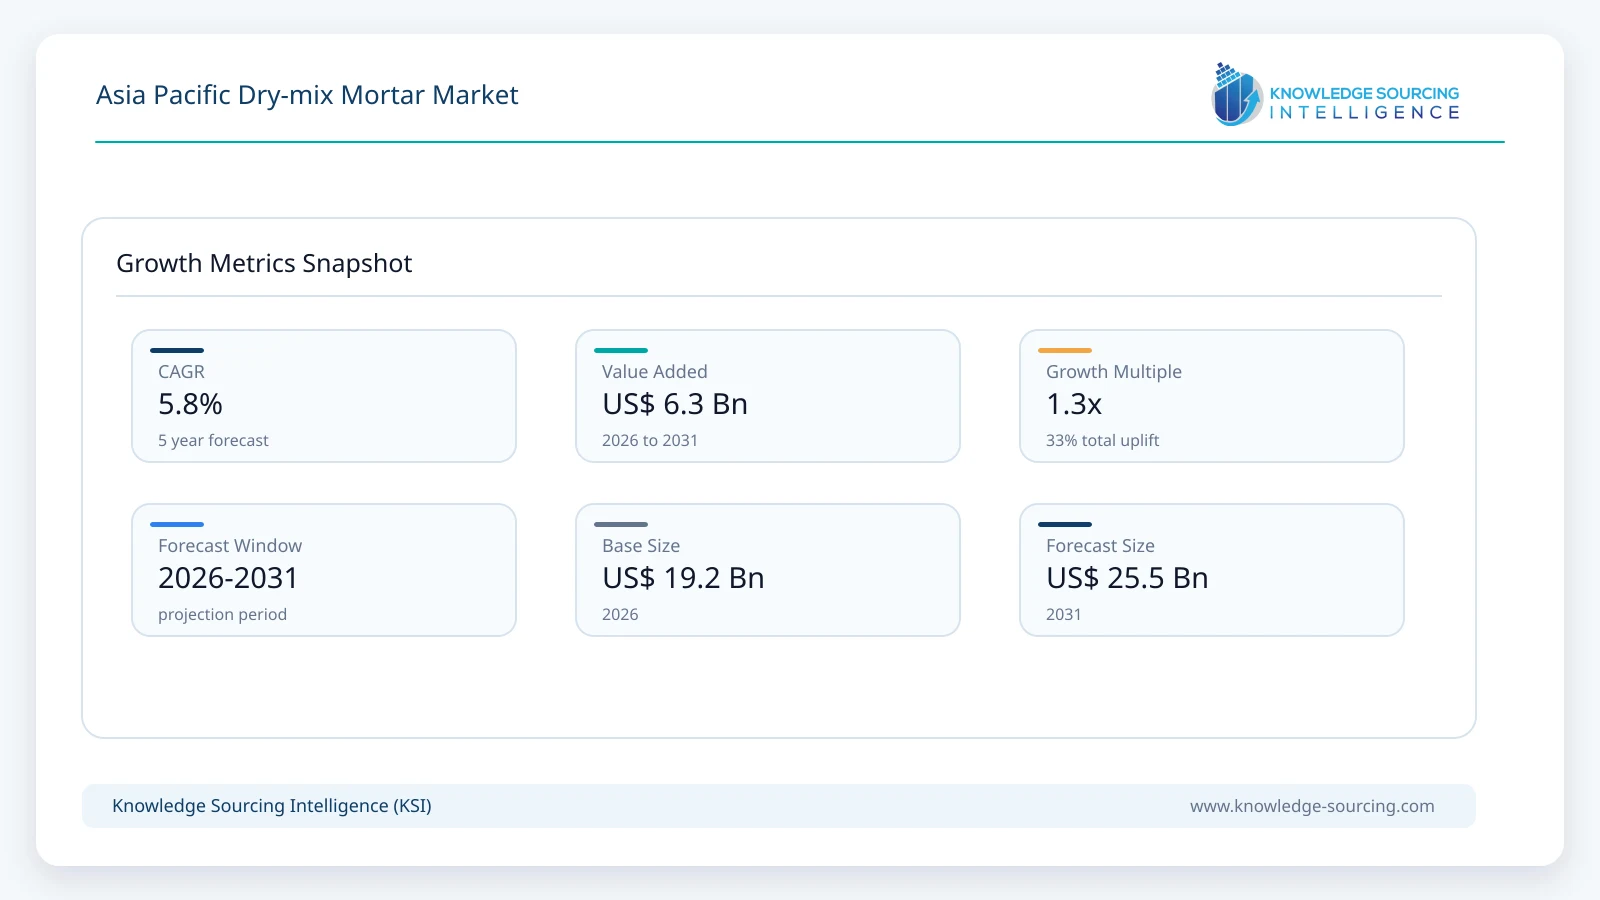
The Asia Pacific Dry-mix Mortar Market is expected to expand at a CAGR of 5.84%, reaching USD 25.5 billion in 2031 from USD 19.2 billion in 2026.
Highlights:
- 1Plaster remains the largest application, representing approximately 31.8% of 2026 sales.
- 2Residential projects account for about 52.3% of regional demand across construction uses.
- 3China retains the leading installed production and distribution base despite property-sector weakness.
- 4India gains market weight through factory-blended products and wider contractor adoption.
- 5Polymer-modified tile, façade and repair systems support stronger value growth than basic mixes.
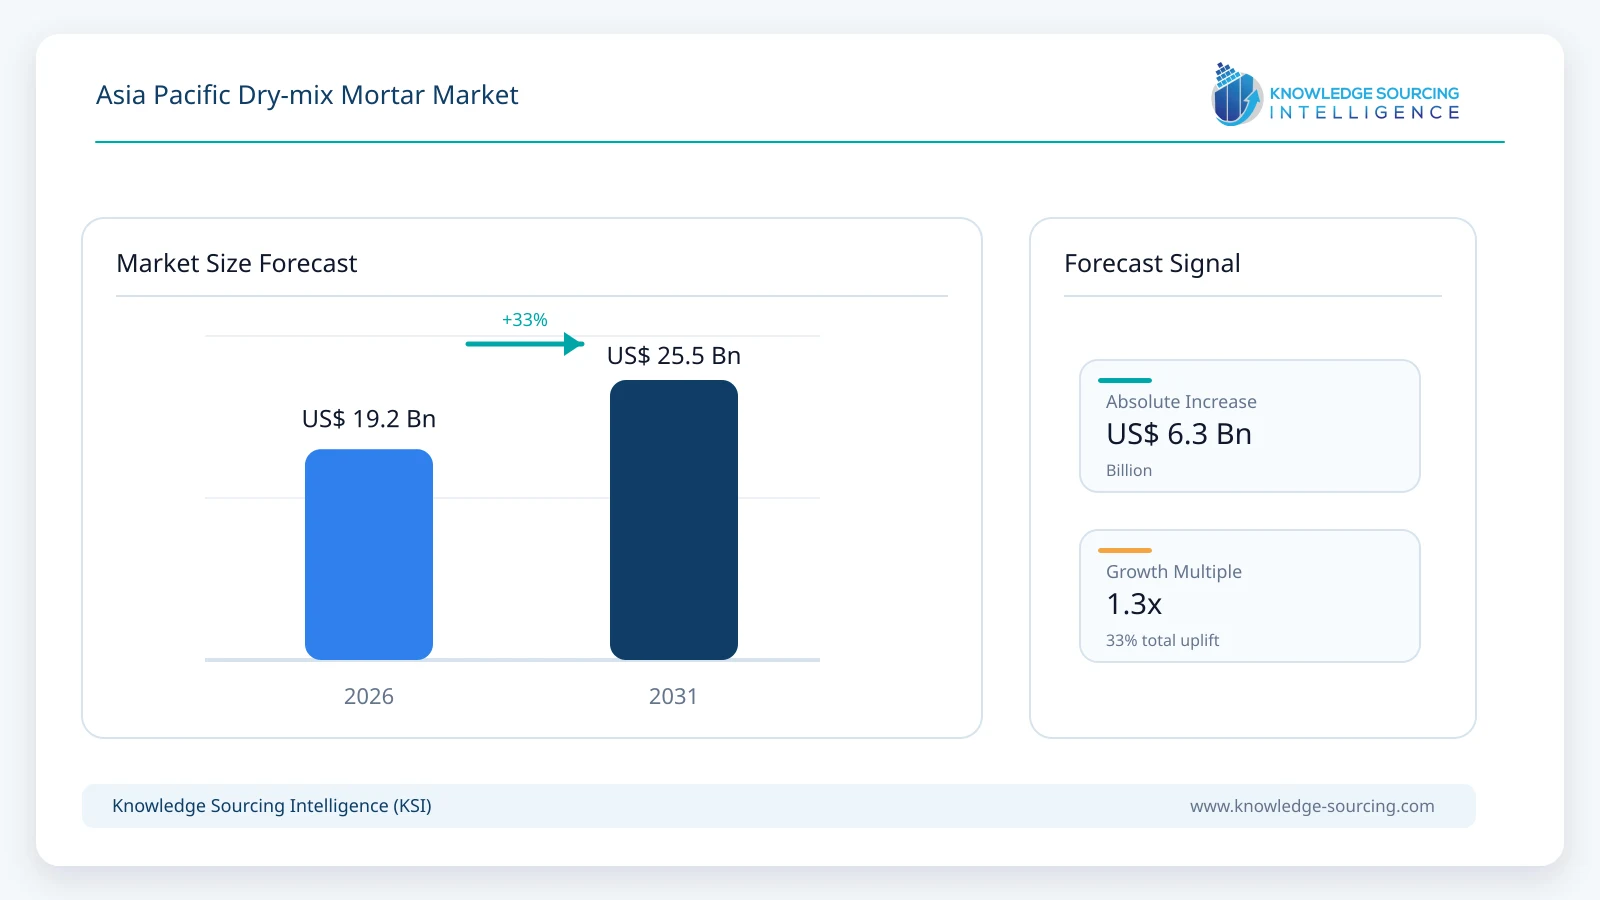
Dry-mix mortar is supplied as factory-proportioned cementitious or gypsum-based powder and made ready for application by adding a prescribed quantity of water on site. The principal traded products include masonry and plaster mortars, renders, tile adhesives, grouts, cementitious waterproofing slurries, repair mortars and dry formulations for insulation finishing systems. Producers earn revenue from finished mixes sold to construction distributors, project contractors and building owners; cement, sand, polymer additives and completed building systems are not additional revenues within the same product sale.
China continues to provide substantial production scale, although weaker developer activity has shifted supplier attention toward refurbishment and specification-driven repairs. UltraTech distributes ready plaster, tile adhesive and grout products in India, while Sika opened new blending facilities in China and Singapore in 2025 and confirmed a mortar plant in Bangladesh in 2026. These investments support manufacturing close to construction sites, a practical requirement for heavy, relatively low-value bulk products. Application-specific formulations increasingly determine value: high-adhesion tile systems, repair mortars and waterproofing materials typically command different prices and approval requirements from commodity wall plaster.
Market Overview
Factory-proportioned mortar is attractive where contractors must control bond strength, layer thickness, water demand and repeatability across multiple sites. In plastering and masonry, the alternative is commonly a site-prepared cement-sand blend whose quality depends on labor practice and local aggregate grading. A packaged mortar can reduce material inconsistency and shorten preparation time, although the cost advantage depends on local labor rates, construction methods and the available supply of suitable sand. For specialty applications, the importance of uniformity is higher because tile slip, façade cracking and water ingress can generate expensive rework.
Manufacturers have established different positions along the product-performance spectrum. UltraTech sells Readiplast, Fixoblock, Tilefixo and PowerGrout, linking basic construction-material channels to specialist dry-mix products. Sika operates across tile adhesives, grout, waterproofing and repair formulations; its Indonesian Bekasi capacity expansion and newer China, Singapore and Bangladesh sites reinforce a regional blending model. Bostik supplies cement-based tile adhesives in India, while SCG has introduced additional mortar formulations in Indonesia. Commercial differentiation comes from product certification, application support and reliable batch quality as much as access to raw cement.
China’s investment cycle requires suppliers to distinguish new residential construction from maintenance and finishing work. The National Bureau of Statistics recorded a 17.2% fall in real estate development investment and a 20.4% fall in new starts in 2025, reinforcing the pressure on standard building mortars. India and Southeast Asia offer broader demand for new building stock, although they remain price-sensitive and fragmented. Localized packing, technical training and contractor distribution influence the rate at which industrial mortars displace on-site mixing.
Market Trends
Tile-System Specifications Are Shifting Value Toward Modified Formulations
Large-format ceramic and vitrified tiles impose higher demands on bonding, deformability and working time than conventional small wall tiles. Cement-based tile adhesives offered by Bostik, Sika and other producers use performance additives to manage those requirements, and premium grades can carry higher realized prices per kilogram than commodity render. Contractors nevertheless choose products according to substrate, tile dimensions and water exposure, not simply the most expensive formulation.
India and Southeast Asia provide growth as organized retailers and project contractors make manufacturer-defined tile systems more visible. Wider use of adhesives also supports matched grouts and waterproofing layers, but those products must be attributed only to their own finished-material sales and not counted again as part of the tile adhesive.
Dry-mortar Plants Are Moving Closer to Construction Demand
Sika’s January 2025 openings in Singapore and Xi’an and its February 2026 Bangladesh facility demonstrate the importance of local processing, blending and dispatch. Bulk premixed mortar has substantial freight exposure, so a plant near an active metropolitan or industrial corridor can serve contractors more economically than imported finished bags. Centralized production also allows tighter control of sand drying, dosage and blending.
Capacity announcements do not necessarily establish immediate sales volumes. Newly commissioned sites need building-material approvals, distributor relationships and practical applicator training before utilization matures, particularly where traditional site-mixed mortar has an entrenched cost position.
Renovation and Concrete Repair Are Offsetting Parts of China’s New-Build Slowdown
Chinese property development remained under pressure in 2025, but the installed building and infrastructure base still requires façade renewal, concrete repairs, waterproofing and interior refurbishment. Mortar suppliers can address this activity through higher-specification repair and finishing systems even when demand for basic masonry mortar softens. The commercial mix shifts toward technical service and approved installation systems rather than a direct recovery in construction starts.
China’s weakness should not be confused with uniformly declining Asia-Pacific consumption. Sika’s October 2026 trading statement recorded strong organic growth outside its Chinese construction business, reflecting different construction cycles in India and parts of Southeast Asia.
Application Productivity Is Influencing Product Selection
Consistent factory-made plaster and render can be prepared using controlled water dosing and applied with mechanized mixing or pumping equipment. Industrialized application becomes valuable on repetitive apartment, hotel and industrial-building work where a predictable finish reduces labor variability. UltraTech’s packaged plaster portfolio and the broader Sika range illustrate how ready-formulated mixes connect materials supply with site productivity.
The value proposition is conditional. Small residential contractors may continue buying cement and sand separately where manual labor remains inexpensive or packaged products are difficult to obtain. Suppliers therefore need viable pack sizes, contractor demonstrations and reliable retail availability rather than relying entirely on laboratory productivity claims.
Lower-impact Mix Design Is Entering Product Development
Producers are evaluating lower-clinker binders, locally sourced fillers and reduced-material-loss formulations in response to customer environmental specifications. Factory batching may limit site wastage, but dry mortar still incorporates cement and typically requires energy for aggregate drying. Its environmental performance therefore depends on formulation, freight distance and the application achieved rather than a blanket claim that all dry mixes are low carbon.
SCG has identified low-carbon construction materials and specialist mortar applications in its product strategy. For purchasers, reliable third-party declarations and installed performance will matter increasingly alongside cost, especially in institutional buildings and high-specification industrial projects.
Segment Analysis
By Application: Plaster
Plaster is the largest use of factory-blended mortar in Asia-Pacific construction because interior walls and ceilings account for extensive finished surface area in housing and commercial buildings. Contractors value predictable coverage, workability and adhesion, particularly when multiple teams must deliver consistent finishes. Ready plaster also reduces the number of separate materials stored and blended on-site, although basic cement-sand alternatives remain competitive in small informal projects.
The plaster category is expected to approach USD 7.35 billion by 2031. India’s Readiplast and other packaged plaster ranges support broader contractor familiarity, while factory-produced gypsum construction plaster offers a different formulation route for interior applications. The segment remains volume-intensive, but higher-margin opportunities increasingly involve smoother finishing grades, lower-shrinkage performance and better mechanized application compatibility.
By End-User Industry: Residential
Residential construction represents the principal end-user pool because the cumulative area requiring masonry bedding, interior plaster, tiling and wet-area waterproofing is substantial. The market nonetheless behaves differently across Asia-Pacific: Chinese apartment construction has contracted, whereas Indian housing and Southeast Asian urban development support new areas of application. The category accounts for approximately USD 10.05 billion in 2026, with its value supported by basic mortar volumes as well as the increased use of packaged tiling and repair systems.
Residential demand is not determined by new house completions alone. Existing buildings generate recurring purchases for bathrooms, kitchens, façades and surface repairs. Producers serving the residential channel need products that can be distributed through building-material merchants, sold in manageable pack sizes and applied by smaller contractors without specialized on-site mixing equipment. Those requirements reward distribution coverage and consistent instructions, while limiting adoption of expensive formulations where customers cannot identify the performance benefit.
Market Drivers
Factory-controlled Quality in Repetitive Building Work
Prefabricated cementitious mixes offer repeatable constituent proportions and factory-checked grading, important where several subcontractors work on the same building. A contractor ordering plaster, render and masonry grades from a qualified producer can reduce variability in layer strength and application consistency. That advantage is especially tangible when subcontractors face rework penalties or tight commissioning schedules.
Large projects can therefore shift demand away from hand batching even without major increases in completed floor space. Supplier support must still include guidance on curing, surface preparation and water dosing, because reliable factory composition does not eliminate installation defects.
Growth in India’s Urban and Infrastructure Construction
India provides a widening installation base for packaged block-jointing mortar, ready plaster and technical grouts as residential blocks, logistics facilities and infrastructure assets move through construction. UltraTech’s dry-mix portfolio spans masonry, tiling and precision grouting, showing that the opportunity extends beyond one specialty product.
Better local distribution and broader contractor training could increase the portion of projects specified with factory blends. Demand is likely to vary by state, project type and contractor sophistication; the forecast does not presume that every construction site abandons conventional mixing.
Specialized Tile and Waterproofing Systems
Cementitious adhesives and waterproofing slurries are commonly specified alongside modern ceramic finishes, wet-area detailing and external cladding. Bostik’s India portfolio includes cement-based adhesives tailored to different substrates and performance requirements, while Sika’s Xi’an facility produces tile adhesives and cementitious waterproofing products.
Project owners may accept higher material value where poor bond or water ingress creates expensive maintenance. Growth therefore reflects product mix improvement as well as construction activity, especially in projects requiring warranties or documented material performance.
Investment in Local Blending and Distribution Capacity
Sika’s investment in Singapore, China, Bangladesh and Indonesia illustrates the advantage of operating near demand centers. Dry mortar is costly to move over long distances relative to its price, and local production supports regional sand sourcing, language-specific packaging and shorter replenishment cycles.
Local plants can broaden reliable supply outside capital cities and reduce dependence on imported finished formulations. Their commercial impact depends on utilization and the maturity of project channels; a new site is not itself proof that consumption has increased by its rated capacity.
Repair, Renovation and Building-envelope Maintenance
Existing bridges, factories, residential buildings and commercial premises need repair grouts, façade mortars, patching compounds and waterproofing materials throughout their operating lives. These uses are less directly tied to the current year’s private housing starts than commodity wall plaster or masonry mortar.
Concrete protection and renovation formulations offer producers a means of serving maintenance budgets through specification-led products. Demand depends on the ability to demonstrate compatible substrates, durability and dependable installer practice rather than simply substituting dry powder for site-made mortar.
Market Restraints
Weak Chinese Property Development and Contractor Liquidity
China’s 2025 residential development indicators confirm an extended construction downturn, with fewer new starts and building completions. Standard mortars sold into new apartment projects are exposed directly to that reduction, while delayed developer payments can strain distributors and subcontractors.
Repair and infrastructure uses can offset some volume, but neither has the same application mix as new residential building. Suppliers are consequently more cautious about commodity capacity and may favor technical finishes or regional diversification.
Price Advantage of Site-mixed Cement and Sand
Informal and small-scale builders often buy cement and sand separately because materials are familiar, readily available and perceived to be inexpensive. Bagged dry mortar carries factory processing, packaging and distribution costs that can make its per-tonne price noticeably higher than basic field mixes.
Even where lower waste and faster application reduce total job cost, those savings may not accrue to the same contractor who purchases the material. This split between purchase budget and lifecycle value slows adoption in price-sensitive projects.
Raw-material Quality and Freight Sensitivity
Factory-made mortar requires controlled fine-aggregate grading, reliable cement properties and appropriate chemical additives. Differences in regional sand supply, moisture, particle size and polymer input availability make exact formulations difficult to reproduce across distant plants.
Producers must invest in aggregate drying, blending controls and storage, while finished-product freight limits economical delivery radius. Heavy basic grades are more exposed to transport charges than high-value specialty grouts or adhesives.
Installation Discipline and Qualification Burdens
Technical dry mortars can underperform when substrate cleaning, water dosage, open time or curing do not follow instructions. Tile adhesives, repair compounds and waterproofing slurries are particularly sensitive to application conditions, and failed projects can generate reputational costs for suppliers.
Contractor training, standards compliance and field testing therefore add commercial effort. In regions with fragmented small builders, product availability may spread faster than the necessary installation competence.
Cement Carbon Footprint and Product Cost Pressures
Dry-mix mortar is not automatically a low-emission product: ordinary grades remain cement-intensive, and industrial production consumes fuel or electricity to dry and classify aggregate. Restrictions on quarrying and rising energy or packaging costs can raise the cost of finished mixes.
Lower-clinker or waste-minimizing formulations may help, but suppliers must verify strength, durability and workability when changing constituents. Projects that demand lower embodied carbon can therefore require additional testing and documentation before new formulations win approval.
Regional Outlook
China
China contributes approximately 57.8% of Asia-Pacific dry-mix mortar sales in 2026, reflecting the country’s extensive installed construction stock, large mortar-processing network and established demand for ready-mixed wall and tile systems. The depth of its market is not evidence of strong current construction growth. National statistics recorded steep falls in new real-estate development and residential building starts in 2025, while Sika’s trading releases describe a double-digit contraction in its China construction business during parts of 2026.
Regional suppliers must increasingly use differentiated tile adhesives, repair formulations and renovation products to offset subdued commodity plaster demand. China’s modeled sales reach about USD 13.75 billion in 2031; its share eases as faster-growing India and other Asian markets gain scale. The outcome depends on stabilization of private construction and on continuing infrastructure and existing-building maintenance expenditure.
India
India is positioned to record the strongest growth among the countries separately identified in the KSI geographical structure, with modeled dry-mix mortar revenue increasing at approximately 10.1% annually through 2031. UltraTech’s ready plaster, masonry mortar, tile adhesive and grout families provide an established local product range, while Saint-Gobain’s Jhagadia plaster investment demonstrates additional industrial formulation capacity. Large commercial and infrastructure projects increasingly favor consistency, specified bond strength and shorter site preparation time.
Market share increases from roughly 16.9% in 2026 to 20.6% in 2031, reflecting both additional constructed floor area and greater penetration of factory-blended material within applicable projects. Nevertheless, India has a pronounced distinction between major urban contracting groups and smaller price-focused builders. Product availability, contractor education and regional raw-material sourcing will determine whether manufactured mortar gains share beyond premium developments and large organized projects.
Competitive Landscape
The competitive field contains multinational construction-chemical suppliers, cement producers that have moved downstream into formulated products, and domestic mortar specialists. Sika competes through broad product systems and multiple regional manufacturing sites; Saint-Gobain’s Weber and related construction businesses emphasize ready mortars, tile setting and building finishing; MAPEI and ARDEX operate heavily in higher-specification installation systems. UltraTech and SCG connect factory mortar products to established cement and building-material distribution networks. Bostik offers focused construction adhesives, while local companies can compete through pricing, short delivery routes and contractor relationships.
Specialty mortar competition differs from the pricing contest for standard wall plaster. Cement, admixture, sealant and ready-mix concrete businesses coexist within many construction groups, but dry-mix manufacturers win individual specifications through dependable installation performance and product availability. Basic grades compete on freight, packaging and distribution, whereas tile adhesives, waterproofing slurries and repair mortars require product testing, substrate compatibility and application support. Suppliers offering both standard mixes and qualified specialty systems can supply several phases of a construction project.
Recent Developments
23 October 2026: Sika reported that Asia-Pacific sales declined 2.3% in local currencies during the first nine months of 2026, while organic growth outside its Chinese construction business reached 7.7%, indicating sharply different conditions across regional construction-product markets.
3 February 2026: Sika announced a new facility at Narayanganj, Bangladesh, producing concrete admixtures and mortars and supporting the company’s high-performance tile adhesive offering.
22 July 2025: SCG Indonesia announced six new mortar variants introduced during June 2025, widening its range of factory-prepared construction materials for Indonesian building applications.
22 May 2025: Saint-Gobain announced a plaster manufacturing facility in Jhagadia, Gujarat, combining its Gyproc and Formula businesses to supply construction and technical plaster markets.
16 January 2025: Sika announced new mortar manufacturing facilities in Singapore and Xi’an, China; the Xi’an operation includes tile adhesive and cementitious waterproofing formulations.
Market Outlook
Future mortar spending will be shaped by the balance between conventional construction volumes and higher-value specialized formulations. China can remain the largest revenue contributor without recovering its previous property-development momentum, provided that renovation, repair and infrastructure projects absorb part of the loss in standard plaster and masonry applications. India, Indonesia and other developing Asian economies have more scope for new installations, particularly as modern distribution and standard specifications improve access to packaged materials.
The most defensible long-term gains are likely to come from broader factory-mix penetration in repetitive work and from tile, waterproofing and concrete-repair products whose performance can be verified. Mortar suppliers will need to manage cement price exposure, plant utilization and distribution economics while investing in application support. The market’s growth will therefore reflect mix improvement and operational efficiency as well as net additions to regional building stock.
Asia Pacific Dry-mix Mortar Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 19.2 billion |
| Total Market Size in 2031 | USD 25.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.84% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, End-user Industry, Country |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Application
Grouts
Plaster
Render
Tile Adhesive
Water Proofing Slurries
Insulation and Finishing Systems
Concrete Protection and Renovation
Other Applications
By End-user Industry
Residential
Commercial
Infrastructural
Others
By Country
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Rest of Asia-Pacific
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Growth, 2026–2031
1.3. Leading Applications and Market Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Currency and Forecast Timeline
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Factory-controlled Quality in Repetitive Building Work
3.1.2. Growth in India’s Urban and Infrastructure Construction
3.1.3. Specialized Tile and Waterproofing Systems
3.1.4. Investment in Local Blending and Distribution Capacity
3.1.5. Repair, Renovation and Building-envelope Maintenance
3.2. Market Restraints
3.2.1. Weak Chinese Property Development and Contractor Liquidity
3.2.2. Price Advantage of Site-mixed Cement and Sand
3.2.3. Raw-material Quality and Freight Sensitivity
3.2.4. Installation Discipline and Qualification Burdens
3.2.5. Cement Carbon Footprint and Product Cost Pressures
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Standards and Environmental Considerations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Factory Batching and Aggregate Drying
4.2. Polymer Modification and Workability Control
4.3. Mechanized Application and Quality Assurance
4.4. Lower-impact Cementitious Formulations
5. ASIA PACIFIC DRY-MIX MORTAR MARKET BY APPLICATION
5.1. Introduction
5.2. Grouts
5.3. Plaster
5.4. Render
5.5. Tile Adhesive
5.6. Water Proofing Slurries
5.7. Insulation and Finishing Systems
5.8. Concrete Protection and Renovation
5.9. Other Applications
6. ASIA PACIFIC DRY-MIX MORTAR MARKET BY END-USER INDUSTRY
6.1. Introduction
6.2. Residential
6.3. Commercial
6.4. Infrastructural
6.5. Others
7. ASIA PACIFIC DRY-MIX MORTAR MARKET BY COUNTRY
7.1. Regional Overview
7.2. China
7.3. India
7.4. Japan
7.5. South Korea
7.6. Taiwan
7.7. Thailand
7.8. Indonesia
7.9. Rest of Asia-Pacific
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Agreements, Acquisitions and Capacity Expansion
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Sika AG
9.2. Compagnie de Saint-Gobain S.A. (Weber)
9.3. MAPEI S.p.A.
9.4. ARDEX Group
9.5. UltraTech Cement Limited
9.6. Bostik SA (Arkema)
9.7. The Siam Cement Public Company Limited (SCG)
9.8. MCON Rasayan India Limited
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size of Asia Pacific dry-mix mortar by 2031?
The Asia Pacific Dry-mix Mortar Market is projected to reach USD 25.5 billion by 2031.
What is the expected CAGR for the Asia Pacific dry-mix mortar market?
The Asia Pacific Dry-mix Mortar Market is expected to expand at a 5.84% CAGR.
Which application segment is largest in the Asia Pacific dry-mix mortar market?
Plaster remains the largest application, representing 31.8% of 2026 sales.
Which country has the leading production base in Asia Pacific dry-mix mortar?
China retains the leading installed production and distribution base.
What types of projects drive most regional dry-mix mortar demand?
Residential projects account for approximately 52.3% of regional demand.
What product types support stronger value growth in the market?
Polymer-modified tile, façade, and repair systems support stronger value growth.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Asia Pacific Dry-mix Mortar Market - Strategic Insights and Forecasts (2026–2031). https://www.knowledge-sourcing.com/report/asia-pacific-dry-mix-mortar-market