
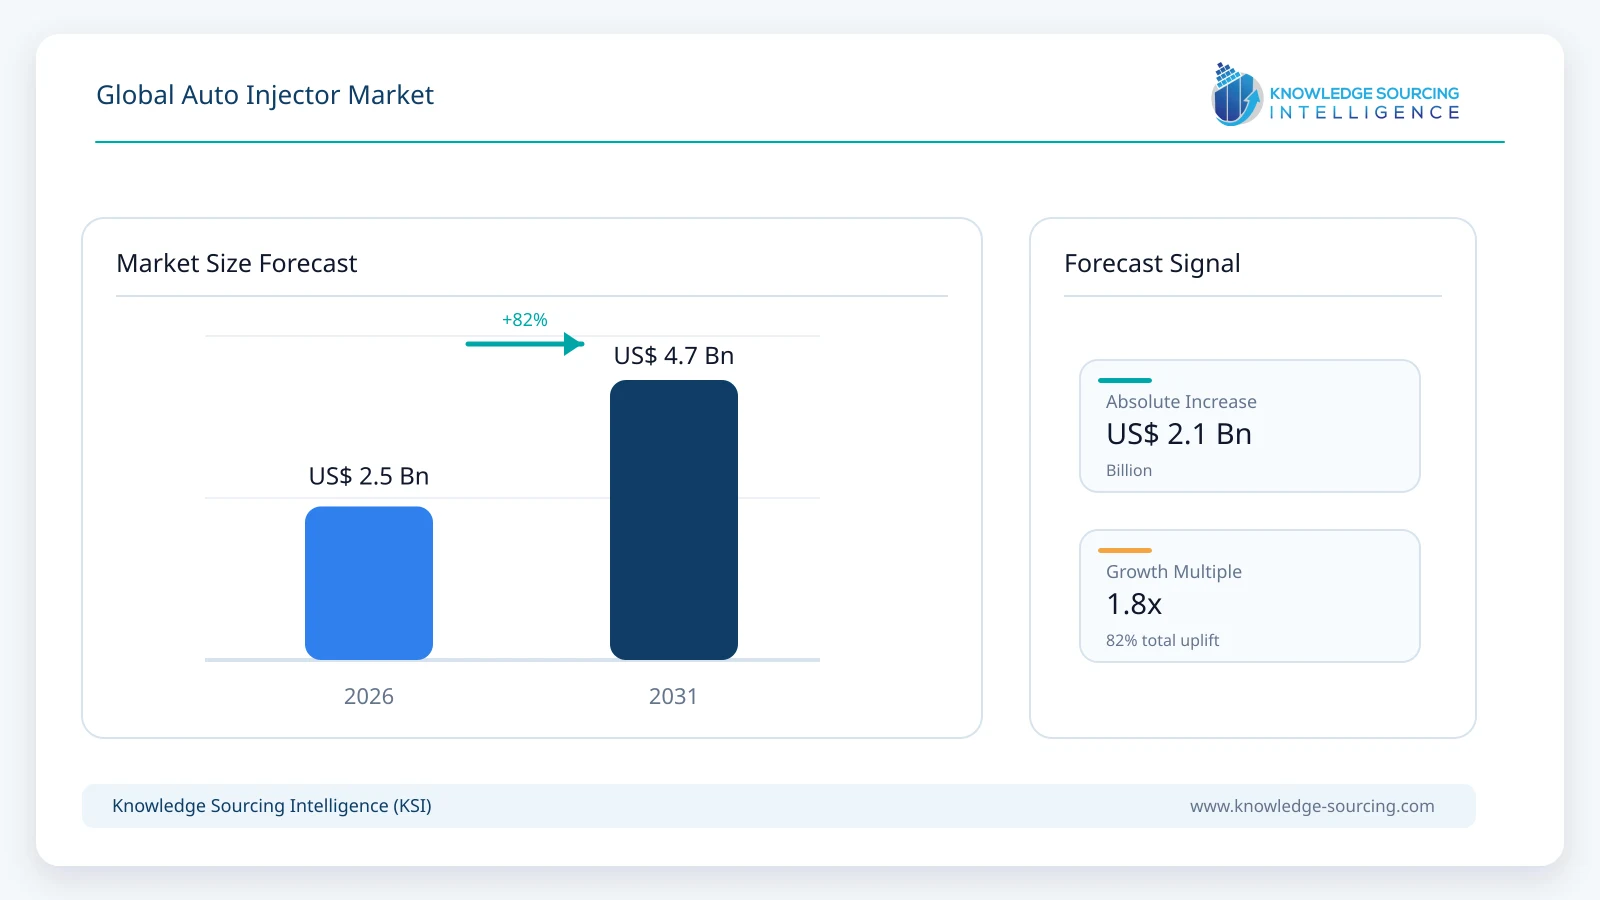
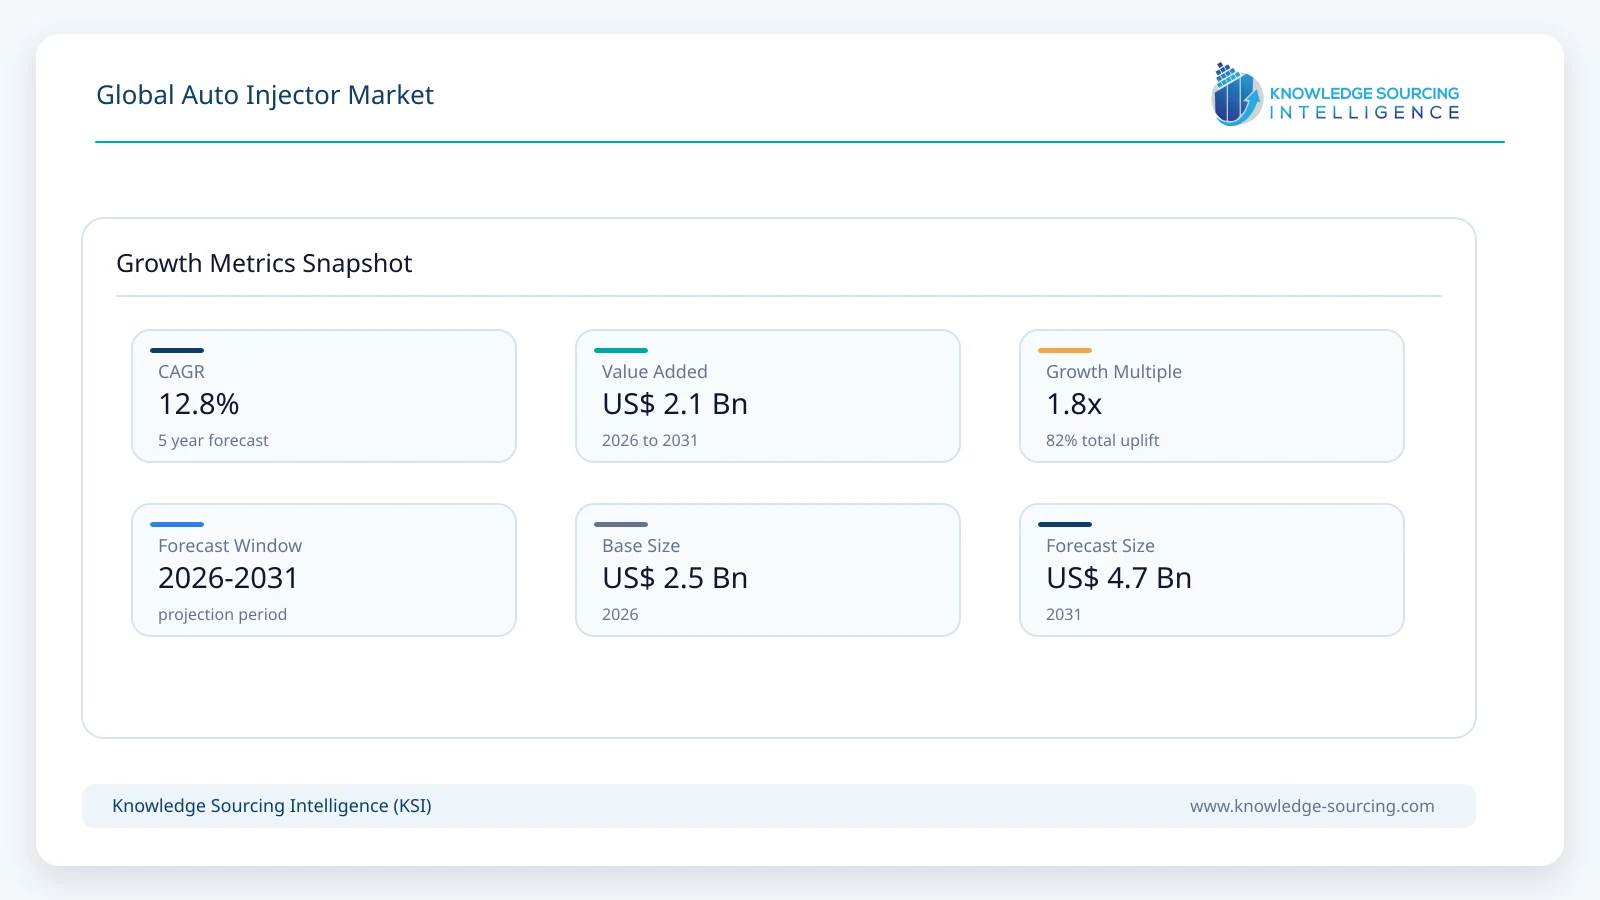
The global auto-injector market is expected to grow at a CAGR of 12.8%, reaching a market size of USD 4.65 billion in 2031 from USD 2.55 billion in 2026.
Highlights:
- 1Disposable autoinjectors account for approximately 82.0% of global auto-injector revenue in 2026.
- 2Devices with injection volumes up to 1 mL account for approximately 54.0% of 2026 revenue.
- 3Autoimmune and inflammatory disorders account for approximately 39.0% of 2026 market revenue.
- 4Homecare and self-administration account for approximately 86.0% of 2026 market demand.
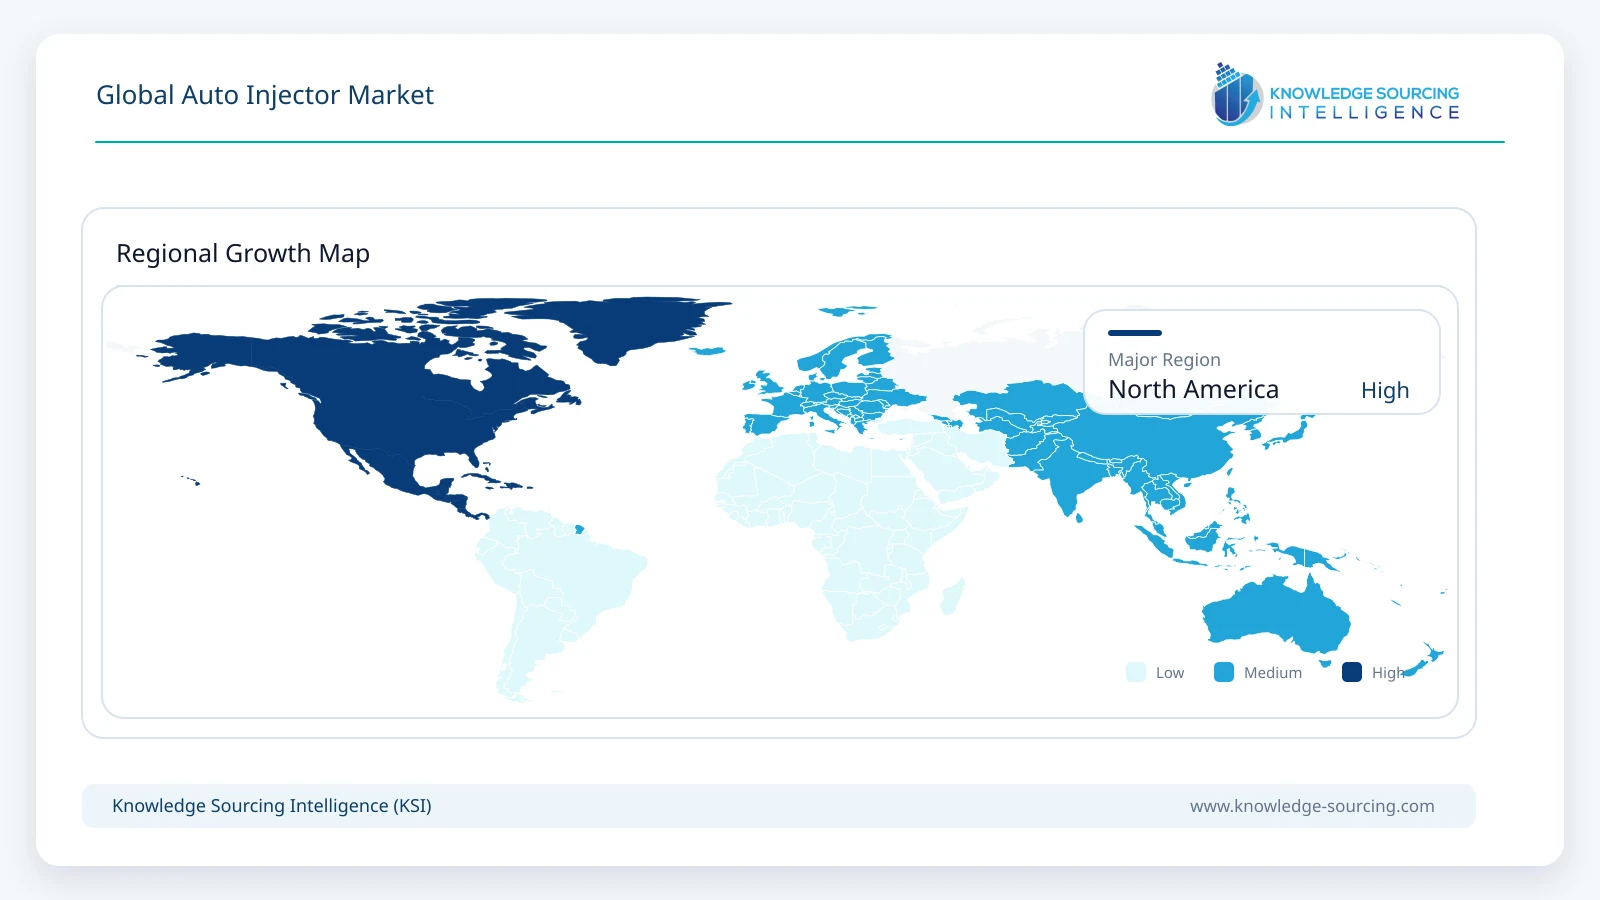
- 5North America accounts for approximately 42.0% of global auto-injector revenue in 2026.
Market Overview
Commercial scale is increasing as pharmaceutical companies shift more injectable therapies toward self-administration and adopt established device platforms to reduce development time. SHL Medical reports that its autoinjectors reach patients at a rate of more than 178 million units per year and that it has shipped 1.5 billion devices cumulatively. Ypsomed reported CHF 601.5 million of Delivery Systems revenue in FY2025/26, with commercial autoinjector sales increasing 33.6%.
Demand is increasingly shaped by chronic therapies that require repeat dosing outside hospitals. Autoimmune diseases, cardiometabolic conditions, severe allergy, neurological disorders, and other biologic indications are moving toward patient-administered formats. Device suppliers are responding with 2.25 mL platforms, high-viscosity designs, dual-chamber concepts, connected injectors, and reusable architectures. At the same time, pharmaceutical customers are placing greater emphasis on reliable final assembly, device-container compatibility, human-factors engineering, sustainability, and multi-site manufacturing resilience.
Market Drivers and Trends
Expansion of biologics, biosimilars, and self-administered therapies
Biologic medicines increasingly require subcutaneous delivery, and many therapies that once depended on clinic administration are being redesigned for self-injection. The same trend is visible in biosimilars, where differentiated device presentation can improve convenience and product acceptance. The commercial pipeline therefore creates recurring demand not only for the injector housing and drive mechanism but also for engineering, tooling, final assembly, and lifecycle support. Pharmaceutical companies increasingly select established platform devices to reduce development risk and accelerate combination-product programs.
GLP-1 demand is reshaping manufacturing scale
Rapid growth in cardiometabolic therapies is increasing pressure on the injection-device supply chain. SHL Medical opened a USD 220 million manufacturing facility in South Carolina in 2025 and states that its highest production capacity exceeds 800 million units per year. Ypsomed is also expanding production in Europe, China, and the United States. The significance of these investments is broader than any single drug class: automated molding, assembly, inspection, and global second-source capacity can subsequently support autoimmune, neurological, and other high-volume biologic programs.
Sustainability is encouraging reusable and lower-material platforms
Single-use autoinjectors remain commercially dominant because they are simple for patients and straightforward to integrate with prefilled syringes. However, the growth of weekly or more frequent chronic therapies increases the volume of plastic and spring components entering the waste stream. Suppliers including Ypsomed, Jabil, Phillips-Medisize, Nemera, and Elcam Drug Delivery Devices are developing reusable or partially reusable concepts. Adoption will depend on regulatory acceptance, device economics, cleaning-free cartridge approaches, and whether pharmaceutical companies can preserve usability while reducing disposable material.
Market Restraints
Combination-product development and validation remain demanding
An autoinjector is not interchangeable with a generic consumer device. Spring force, injection time, viscosity, needle depth, break-loose and glide forces, container tolerances, dose completion feedback, and human-factors performance must work with a specific drug and primary container. Changes to the syringe, stopper, formulation, or device can trigger additional verification and regulatory work. These requirements can lengthen development cycles and raise switching costs once a platform is selected.
Capacity concentration and quality failures can disrupt launches
High-volume autoinjector manufacturing depends on precision injection molding, automated assembly, component qualification, and controlled supply chains. Demand can therefore concentrate around a limited number of proven suppliers. Device malfunctions or manufacturing deviations have direct patient-safety implications and can lead to recalls, remediation, or program delays. Pharmaceutical companies increasingly mitigate this exposure through second-source strategies, duplicated tooling, regional manufacturing, and earlier scale-up planning.
Segment Analysis
By Type - Disposable Autoinjectors
Disposable autoinjectors generated an estimated USD 2.09 billion in 2026. They remain the principal device type because the drug container and actuation mechanism are supplied as an integrated, single-use combination product that requires minimal preparation by the patient. Commercial adoption is supported by established platform families, high-volume automated assembly, and broad use across biologic and emergency therapies. Pharmaceutical companies also favor mature disposable platforms when development timelines, device validation, and patient usability are central to launch planning.
By Injection Volume - Up to 1 mL
Auto-injectors with injection volumes up to 1 mL generated an estimated USD 1.38 billion in 2026. The subsegment remains the largest because a substantial installed base of commercial drug-device combinations is designed around standard 1 mL prefilled syringe formats. Existing filling lines, validated container systems, and mature device architectures continue to support this format even as higher-volume 2.25 mL and larger platforms gain adoption for concentrated biologics and longer-duration injections.
By Therapy Area - Autoimmune and Inflammatory Disorders
Autoimmune and inflammatory disorders generated an estimated USD 0.99 billion in 2026. The segment is supported by recurring self-administered biologics used in rheumatoid arthritis, psoriasis, inflammatory bowel disease, and related chronic conditions. Frequent dosing schedules, long treatment durations, and the commercial importance of patient convenience make autoinjectors a preferred presentation for several originator biologics and biosimilars in this therapy group.
By End-Use Setting - Homecare and Self-Administration
Homecare and self-administration generated an estimated USD 2.19 billion in 2026. Auto-injectors are primarily designed to simplify dosing outside clinical settings through fixed-dose delivery, concealed needles, audible or visual completion cues, and limited preparation steps. Growth in chronic biologic treatment and the shift of suitable therapies away from hospitals continue to reinforce home use as the dominant setting for the device category.
Geographic Analysis
North America
North America generated an estimated USD 1.07 billion in 2026. The region combines high biologic utilization, broad adoption of patient self-administration, strong drug-device development activity, and significant manufacturing investment. The United States remains the principal national market, supported by large commercial therapy volumes and a dense pharmaceutical and medical-device ecosystem.
Competitive Environment
Competition is concentrated among specialist injection-device companies, diversified medical-device suppliers, and contract manufacturers with proprietary platforms. SHL Medical and Ypsomed have substantial commercial scale in autoinjectors. BD, West Pharmaceutical Services, Phillips-Medisize, Jabil, Nemera, medmix/Haselmeier, Gerresheimer, and Stevanato Group combine device engineering with pharmaceutical-industry manufacturing capabilities. Other participants differentiate through specific mechanisms, emergency-use expertise, or platform architectures. Pharmaceutical customers generally prioritize proven commercial validation, capacity, regulatory support, compatibility with standard primary containers, and the ability to support both clinical and commercial volumes.
Competitive differentiation increasingly depends on commercially validated platform families, reliable primary-container compatibility, human-factors performance, high-volume manufacturing, regulatory support, and the ability to supply multiple geographies. Suppliers with proven commercial scale and flexible architectures are positioned to capture new programs as pharmaceutical companies broaden self-injection portfolios.
Recent Developments
August 2026: SHL Medical marked 20 years of uninterrupted DAI production, reporting more than 880 million cumulative DAI units shipped across more than 20 combination products.
May 2026: Ypsomed reported FY2025/26 Delivery Systems revenue of CHF 601.5 million and 33.6% growth in commercial autoinjector sales, alongside 44 newly won customer projects.
January 2026: Kaléo expanded its leadership team while reiterating its focus on drug-delivery technology and autoinjector innovation for emergency and preparedness applications.
2025: SHL Medical opened its new USD 220 million North Charleston manufacturing facility to expand U.S. autoinjector production capacity.
Market Outlook
The auto-injectors market should sustain low-double-digit growth through 2031 as pharmaceutical pipelines shift more injectable therapies toward at-home administration. The strongest volume contribution is expected from disposable devices, but the product-development agenda is moving toward higher viscosity, larger volumes, reusable systems, digital support, and lower material intensity. Capacity expansion by established suppliers is likely to reduce some supply constraints while also increasing competition for large pharmaceutical programs.
Through 2031, value creation will increasingly come from higher-volume platforms, reusable architectures, connected-device options, and geographically diversified manufacturing. Suppliers that combine commercial validation with scalable assembly and support for multiple primary-container formats should remain well positioned as self-administered therapies expand.
Auto Injector Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.55 billion |
| Total Market Size in 2031 | USD 4.65 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Injection Volume, Therapy Area, End-Use Setting, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Disposable Autoinjectors
Reusable and Multi-Use Autoinjectors
By Injection Volume
Up to 1 mL
1–2.25 mL
Above 2.25 mL
By Therapy Area
Autoimmune and Inflammatory Disorders
Cardiometabolic and Endocrine Disorders
Anaphylaxis and Emergency Medicine
Neurology
Other Therapies
By End-Use Setting
Homecare and Self-Administration
Hospitals and Clinics
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1 Market Definition and Scope
1.2 Device-Market Boundary and Exclusions
1.3 Base and Forecast Period
2. MARKET CONTEXT
2.1 Commercialization and Device-Platform Landscape
2.2 Regulatory and Manufacturing Environment
3. EXECUTIVE SUMMARY
3.1 Market Size and Growth
3.2 Key Findings
4. MARKET DYNAMICS
4.1 Growth Drivers
4.2 Market Restraints
4.3 Technology and Sustainability Trends
5. AUTO-INJECTORS MARKET BY TYPE
5.1 Disposable Autoinjectors
5.2 Reusable and Multi-Use Autoinjectors
6. MARKET BY INJECTION VOLUME
6.1 Up to 1 mL
6.2 1–2.25 mL
6.3 Above 2.25 mL
7. MARKET BY THERAPY AREA
7.1 Autoimmune and Inflammatory Disorders
7.2 Cardiometabolic and Endocrine Disorders
7.3 Anaphylaxis and Emergency Medicine
7.4 Neurology
7.5 Other Therapies
8. MARKET BY END-USE SETTING
8.1 Homecare and Self-Administration
8.2 Hospitals and Clinics
9. MARKET BY GEOGRAPHY
9.1 North America
9.1.1 United States
9.1.2 Canada
9.1.3 Mexico
9.2 South America
9.2.1 Brazil
9.2.2 Argentina
9.2.3 Others
9.3 Europe
9.3.1 Germany
9.3.2 France
9.3.3 United Kingdom
9.3.4 Italy
9.3.5 Others
9.4 Middle East and Africa
9.4.1 Saudi Arabia
9.4.2 UAE
9.4.3 South Africa
9.4.4 Others
9.5 Asia Pacific
9.5.1 China
9.5.2 Japan
9.5.3 India
9.5.4 South Korea
9.5.5 Australia
9.5.6 Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1 Platform Positioning
10.2 Manufacturing Capacity and Commercial Validation
10.3 Partnerships and Recent Developments
11. COMPANY PROFILES
11.1 SHL Medical AG
11.2 Ypsomed AG
11.3 Becton, Dickinson and Company
11.4 Stevanato Group S.p.A.
11.5 Owen Mumford Ltd.
11.6 Phillips-Medisize, LLC
11.7 Jabil Inc.
11.8 Nemera
11.9 medmix AG
11.10 West Pharmaceutical Services, Inc.
11.11 Gerresheimer AG
11.12 Midas Pharma GmbH
11.13 Kindeva Drug Delivery L.P.
11.14 Halozyme Therapeutics, Inc.
11.15 Elcam Drug Delivery Devices (E3D)
11.16 Kaléo, Inc.
12. APPENDIX
12.1 Currency
12.2 Market Definitions
12.3 Definitions and Abbreviations





Frequently asked questions
What is the projected market size of the global auto-injector market by 2031?
The Global Auto Injector Market is projected to reach USD 4.65 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for 2026-2031?
The Global Auto Injector Market is expected to grow at a 12.8% CAGR during this period.
Which region holds the largest revenue share in the auto-injector market?
North America accounts for approximately 42.0% of 2026 global revenue.
What type of auto-injectors dominates market revenue?
Disposable autoinjectors account for 82.0% of 2026 global revenue.
Which therapeutic area significantly contributes to auto-injector market revenue?
Autoimmune and inflammatory disorders account for 39.0% of 2026 revenue.
What are the primary drivers of auto-injector market growth?
Expansion of biologics, biosimilars, and self-administered therapies are key drivers.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Auto Injector Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-auto-injector-market