
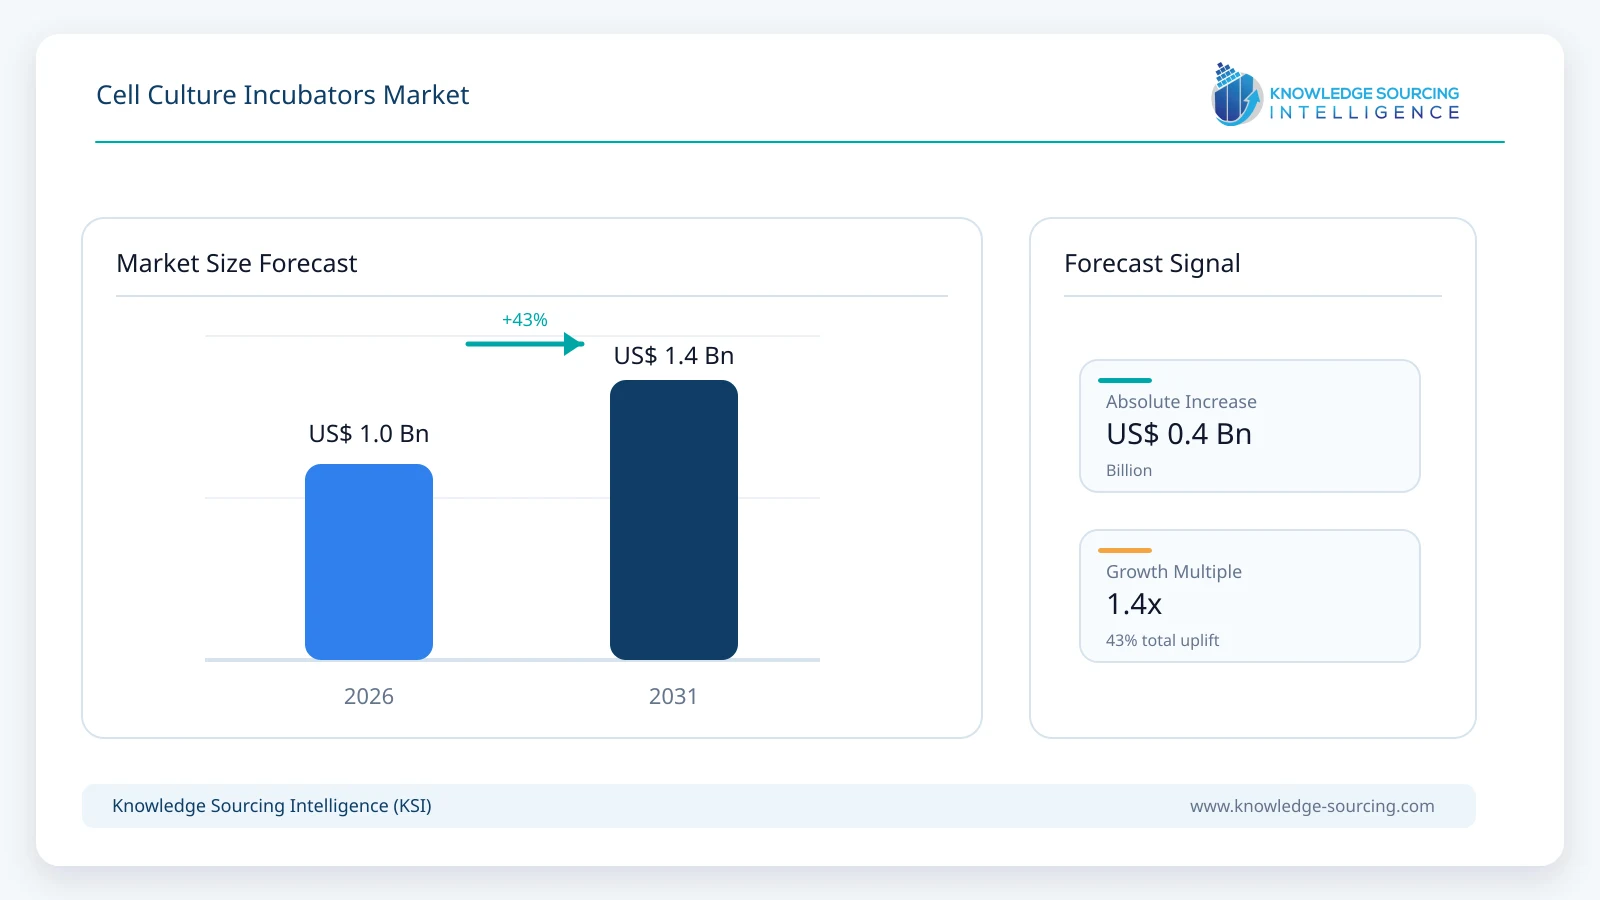
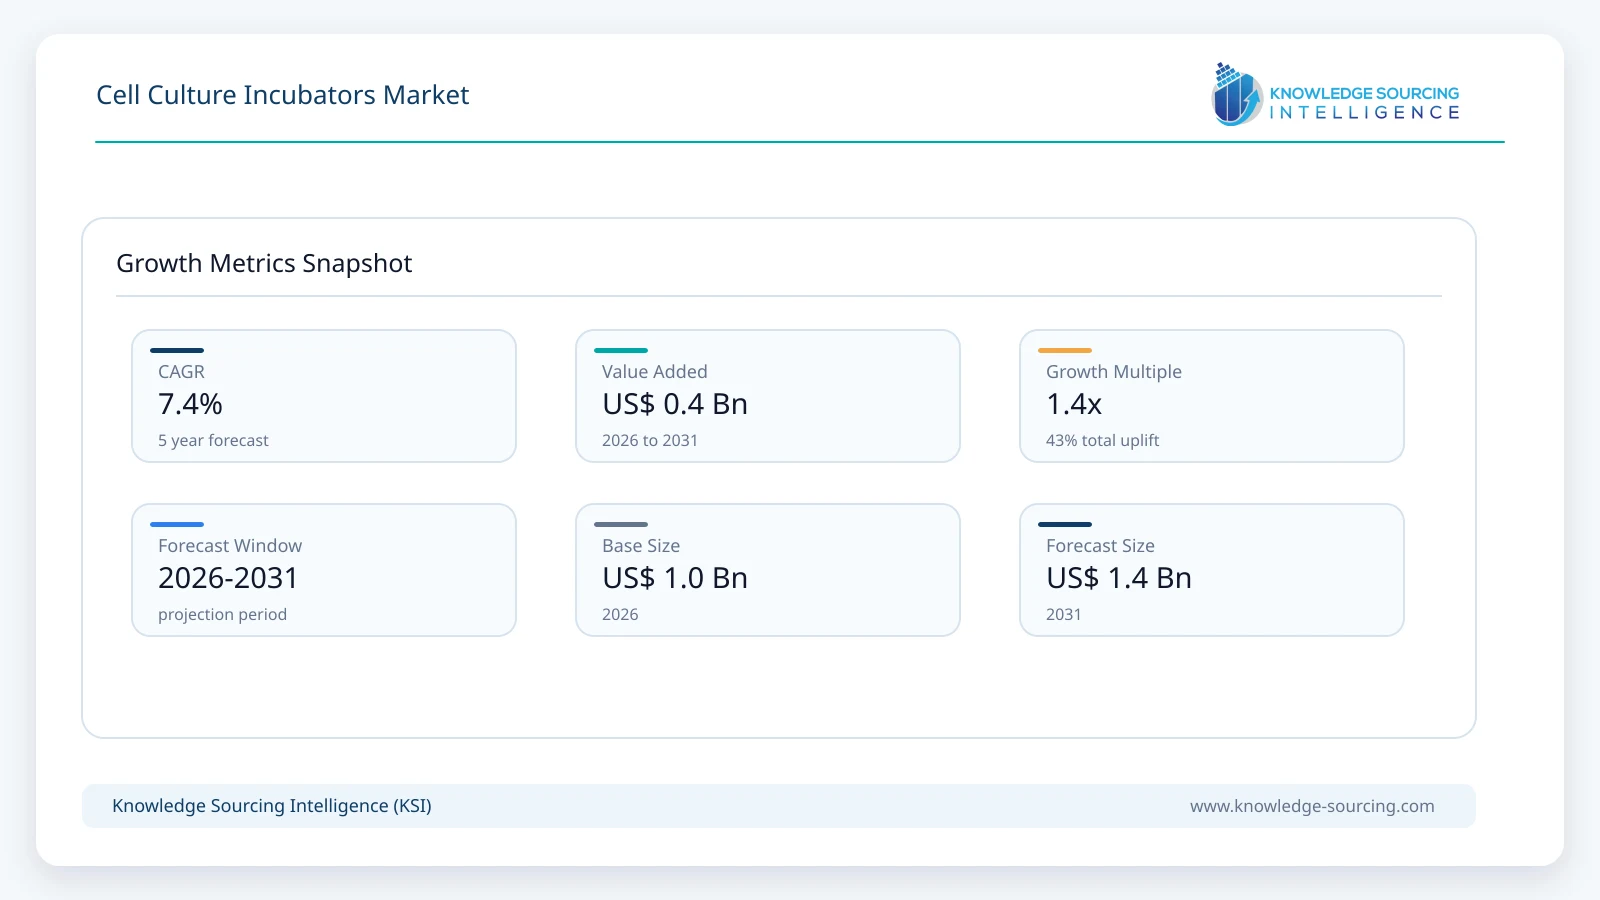
The cell culture incubators market is estimated at USD 1.67 billion in 2026 and is forecast to reach approximately USD 2.38 billion in 2031, representing a CAGR of 7.3% during the forecast period.
Highlights:
- 1CO2 incubators account for approximately USD 0.67 billion, or 68% of estimated 2026 market value.
- 2Mid-capacity 100-200 liter systems represent approximately USD 0.52 billion of 2026 demand.
- 3Biopharmaceutical and cell-therapy applications contribute roughly USD 0.38 billion in 2026 market value.
- 4Pharmaceutical and biotechnology companies account for approximately USD 0.41 billion of 2026 end-user demand.
- 5North America represents approximately USD 0.36 billion, or 37% of estimated 2026 market value.
- 6Product differentiation is shifting toward contamination control, active humidity, cleanroom compatibility, remote monitoring and automation-ready operation.
The market covers controlled-atmosphere incubators used primarily for mammalian cell, tissue, organoid, embryo and related cell-culture workflows, including CO2 incubators, multi-gas and hypoxia systems, and compact specialty incubation platforms. General microbiology incubators without controlled gas environments, plant growth chambers, neonatal incubators, standalone shakers and bioreactors are excluded.
Market Overview
Cell culture incubators are becoming more specialized as cell-based research moves from routine two-dimensional culture toward organoids, stem cells, cell and gene therapy, long-duration assays and automated workflows. The core purchasing requirement remains stable control of temperature, CO2, and humidity, but the commercial value of premium systems increasingly depends on how quickly conditions recover after repeated door openings, how effectively contamination is controlled, and whether the incubator can operate inside regulated or automated environments. These requirements are particularly important when cultures are high-value, slow-growing or difficult to replace.
The market is therefore moving beyond basic temperature-controlled cabinets. Thermo Fisher's Vios iDx cleanroom-compatible systems combine 180°C sterilization, HEPA filtration and factory documentation for GMP environments, while Eppendorf's CellXpert C170i is designed around sub-five-minute temperature and CO2 recovery, low gas consumption and cleanroom/GMP compatibility. PHCbi introduced the Cell-IQ series in June 2026 with active hybrid humidification that restores humidity roughly twice as fast as previous models after a door opening. These features reduce variability in media evaporation, contamination risk and recovery time, turning incubation performance into a reproducibility and workflow issue rather than only an equipment specification.
Capital cost is only one part of the buying decision. Laboratories also evaluate gas consumption, replacement filters and UV lamps, cleaning labor, sterilization downtime, validation documentation, chamber capacity per floor area and the risk of losing valuable cultures. Eppendorf states that its CellXpert C170i can operate at less than one liter of CO2 per day without door openings and provides up to 25% more usable space through a fanless design. PHCbi's 2026 Cell-IQ platform uses approximately three-hour hydrogen-peroxide decontamination cycles, while Thermo Fisher's Vios iDx platform combines high-temperature sterilization with cleanroom documentation. The market is consequently shifting toward lifecycle economics and process assurance rather than simple purchase-price competition.
Demand expands as laboratories replace older incubators with higher-control platforms, cell and gene therapy facilities adopt cleanroom-compatible equipment, and organoid, stem-cell and long-duration culture workflows increase the value of stable humidity and rapid parameter recovery. Growth remains moderate in conventional academic replacement demand but is stronger in regulated biopharma, advanced-therapy and specialized clinical workflows.
Cell Culture Incubators Market Trends
Contamination Control Is Moving from an Accessory Feature to a Procurement Requirement
For high-value cell cultures, contamination can destroy weeks of work and force laboratories to repeat qualification, expansion or assay runs. Manufacturers are therefore competing on the time and completeness of decontamination rather than only chamber temperature accuracy. Thermo Fisher states that its Vios iDx platform reaches 180°C throughout the chamber and is independently validated to a 12-log sterility assurance level, while its in-chamber HEPA filtration restores ISO Class 5 air quality within five minutes after a 30-second door opening. BINDER, Eppendorf and Memmert also use 180°C sterilization approaches in current CO2-incubator portfolios. The commercial consequence is a shift toward designs that reduce contamination risk without recurring consumables or long periods of laboratory downtime.
Humidity Control Is Becoming a Reproducibility Metric
Long-duration cell culture and multi-well plate workflows are sensitive to evaporation because loss of water changes media osmolality and can create position-dependent variation across plates. In June 2026, PHCbi introduced the Cell-IQ CO2 incubator family with active hybrid humidification controlled at 80-90% relative humidity. PHCbi states that the system restores humidity approximately twice as fast as previous models after door openings and pairs the feature with UV-LED sterilization and hydrogen-peroxide decontamination of roughly three hours. Active humidity therefore has a direct commercial role in high-throughput screening, organoid culture and other workflows where evaporation-induced variability can increase repeat testing and sample loss.
Automation Is Changing Incubator Mechanical Design
Cell-therapy and high-throughput laboratories are progressively integrating robotic material handling, automated imaging and closed production steps. Conventional incubator doors and manual access patterns can become a bottleneck in these systems. Thermo Fisher offers Vios iDx automated-door configurations intended for robotic integration, while digital platforms from Eppendorf, PHCbi and Memmert provide remote monitoring, event logging and alarm management. Automation-ready incubation is commercially important because incubators are no longer isolated instruments; they increasingly form part of an integrated cell-culture workflow in which door actuation, sample transfer, environmental logging and operator access must be coordinated with other equipment.
Operating Cost Is Shifting Attention to Gas Use, Filters and Chamber Utilization
The recurring operating cost of an incubator can be material across a large laboratory fleet. Eppendorf reports CO2 consumption below one liter per 24 hours for its CellXpert C170i under closed-door conditions and states that its fanless architecture can provide up to 25% more usable chamber space while avoiding internal fan-associated HEPA filters that require periodic replacement. These economics matter in facilities operating dozens or hundreds of incubators, where gas consumption, replacement parts, maintenance labor and laboratory floor area accumulate over the equipment life. The resulting procurement decision increasingly compares total capacity delivered per square meter and per year rather than the sticker price of an individual cabinet.
Specialized Incubation Is Expanding Beyond Standard 5% CO2 Culture
Demand is broadening toward hypoxia, organoid, stem-cell and embryo workflows that require control of oxygen as well as CO2 and temperature. Current Eppendorf CellXpert configurations offer optional oxygen control, Memmert's 2026 ICO platform supports 1-20% oxygen control, and ASTEC offers compact systems for IVF and multi-gas culture. Esco Medical launched the MIRI M multiroom IVF incubator in June 2025 with up to 18 independent movable chambers that maintain temperature and gas control and can remain stable while undocked for up to 30 minutes. This creates a higher-value specialty segment in which chamber architecture and workflow isolation matter more than gross internal volume.
Segment Analysis
By Product Type - CO2 Incubators
CO2 incubators are estimated at approximately USD 0.67 billion in 2026, representing about 68% of global market value. They remain the standard platform for mammalian cell culture because bicarbonate-buffered media typically require controlled CO2 concentration, high humidity and stable temperature. Demand spans academic research, pharmaceutical development, cancer and immunology studies, stem-cell work, cell therapy and IVF. Premium CO2 systems increasingly add high-temperature sterilization, copper-alloy or stainless-steel interiors, HEPA filtration, humidity sensing, segmented inner doors and remote monitoring, raising average selling prices above basic research-grade cabinets.
By Capacity - 100-200 Liters
The 100-200 liter category is estimated at approximately USD 0.52 billion in 2026, or 53% of the market. This range balances usable shelf capacity with stackability and manageable recovery times, making it the default configuration for many pharmaceutical, biotechnology and academic laboratories. Current mainstream platforms include approximately 165-180 liter systems from Thermo Fisher, Eppendorf, PHCbi, Benchmark Scientific and other suppliers. The segment benefits from laboratory fleet standardization because a common chamber size simplifies space planning, preventive maintenance, spare-part stocking and validation across multiple rooms or sites.
By Application - Biopharmaceutical and Cell-Therapy Research and Manufacturing
Biopharmaceutical and cell-therapy applications represent approximately USD 0.38 billion in 2026 market value, or 39% of the market. Incubators are used for cell-line development, assay development, process characterization, seed expansion, potency testing, cell-therapy development and controlled culture steps performed outside larger bioreactors. The segment carries a higher specification burden than routine research because GMP compatibility, cleanability, audit trails, qualification services and contamination control can influence equipment selection. The increasing use of sensitive primary cells, organoids and engineered immune cells further raises the cost of environmental instability or contaminated cultures.
By End User - Pharmaceutical and Biotechnology Companies
Pharmaceutical and biotechnology companies account for approximately USD 0.41 billion, or 42% of estimated 2026 demand. These buyers typically operate multiple incubators across discovery, analytical development, cell-line development, process development and manufacturing-support laboratories. Procurement decisions therefore consider fleet standardization, service response, calibration support, validation documentation, connectivity and replacement-part availability in addition to unit performance. Large buyers can also favor suppliers that provide adjacent equipment such as biosafety cabinets, freezers, cell-processing systems and laboratory monitoring, reducing the number of vendors used across a controlled workflow.
By Geography - North America
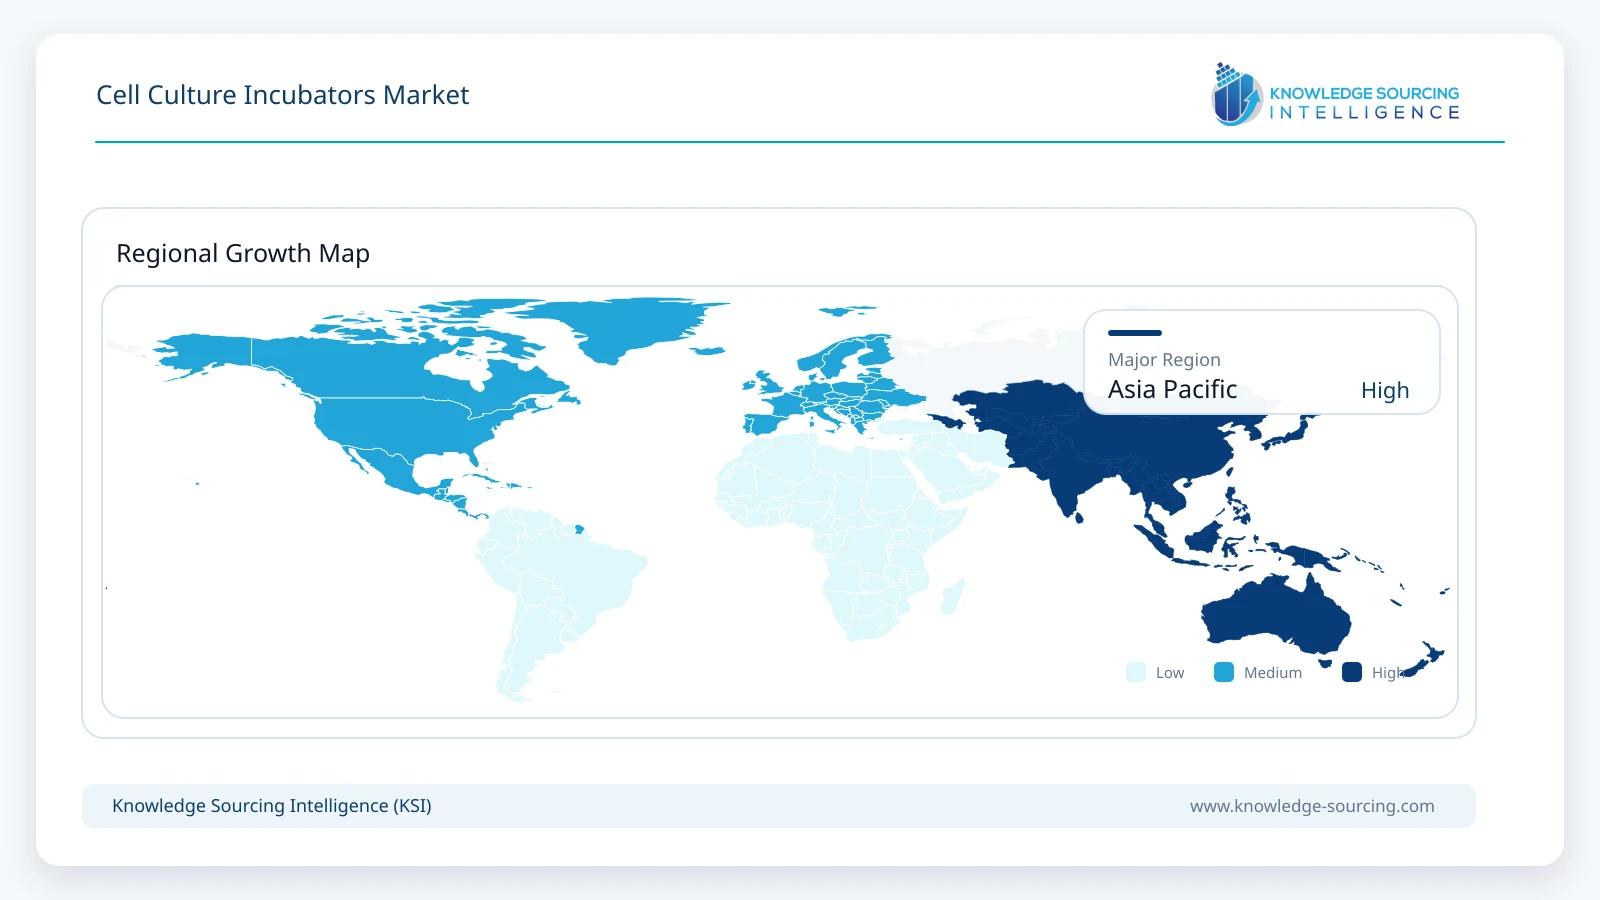
North America is estimated at approximately USD 0.36 billion in 2026, representing around 37% of global market value. Demand is supported by the concentration of biotechnology and pharmaceutical R&D, cell and gene therapy programs, academic biomedical research and fertility laboratories in the United States and Canada. The region also has strong installed bases for Thermo Fisher, PHCbi, Eppendorf, NuAire, Sheldon Manufacturing and Caron, increasing access to local service and validation support. Replacement demand is increasingly directed toward higher-specification platforms with remote monitoring, contamination-control features and cleanroom compatibility rather than simple capacity additions.
Market Drivers
Expansion of cell and gene therapy increases demand for cleanroom-compatible and contamination-controlled incubation.
Organoid, stem-cell and long-duration culture workflows increase the value of active humidity and rapid recovery.
Biopharmaceutical R&D and assay automation support larger fleets of connected, standardized incubators.
IVF laboratories continue to adopt compact multi-chamber systems that reduce environmental disturbance during access.
Replacement of older laboratory equipment supports premium systems with lower gas use, remote monitoring and automated sterilization.
Market Restraints
Premium cleanroom-compatible and actively humidified systems carry materially higher acquisition and validation costs than basic research incubators.
High-temperature sterilization and decontamination cycles can temporarily remove equipment from service and require workflow planning.
Gas supply, calibration, preventive maintenance and sensor replacement add recurring operating costs across large installed fleets.
Academic and smaller diagnostic laboratories may extend equipment replacement cycles when existing incubators continue to meet basic performance requirements.
Specialized IVF and cell-therapy incubators create fragmented requirements that limit complete platform standardization across all workflows.
Competitive Environment
The market combines large life-science equipment suppliers with specialist incubation manufacturers. Thermo Fisher Scientific, PHCbi and Eppendorf compete through broad cell-culture ecosystems and service coverage, while BINDER, Memmert, NuAire and Sheldon Manufacturing maintain dedicated incubation portfolios. Esco combines research CO2 incubators with IVF systems, and specialist suppliers such as ASTEC, Labotect and N-BIOTEK address compact, IVF, multi-gas and large-capacity niches. Benchmark Scientific, Heal Force and BIOBASE broaden competition at value and mid-range price points.
Competitive differentiation increasingly depends on measurable recovery performance, decontamination time, chamber utilization, sensor stability, humidity control, remote monitoring and qualification support. In 2026, PHCbi used active humidity as a platform differentiator, while Memmert launched a next-generation ICO series integrated with its myChamber digital ecosystem. Eppendorf emphasizes low gas consumption and usable chamber volume, and Thermo Fisher differentiates its cleanroom-compatible CTS line through ISO Class 5/GMP documentation and automation-ready configurations. The competitive battleground is therefore shifting from basic temperature-and-CO2 control toward reproducibility, compliance and workflow integration.
Recent Developments
June 2026: PHC Corporation of North America launched the Cell-IQ CO2 incubator series with active hybrid humidification, 80-90% humidity control, UV-LED sterilization and hydrogen-peroxide decontamination cycles of around three hours.
March 2026: Memmert launched the next-generation ICO CO2 incubator, integrating active humidity control, optional oxygen control, remote monitoring and the new myChamber digital ecosystem.
March 2025: PHCbi launched the MCO-171AICUVD-PA next-generation high-heat CO2 incubator with antimicrobial copper-alloy stainless steel and contamination-control features.
August 2025: Esco introduced the CelCulture Touch CO2 incubator platform with touchscreen controls, data visualization, 90°C moist-heat or 180°C dry-heat sterilization options and ULPA-based air filtration.
June 2025: Esco Medical launched the MIRI M multiroom IVF incubator with up to 18 independent movable chambers and controlled CO2, O2, and temperature conditions.
Market Outlook
Cell culture incubator demand through 2031 will be shaped less by basic laboratory expansion and more by the migration toward higher-value cell models, regulated workflows and connected laboratories. Standard CO2 incubators will remain the largest segment, but growth will increasingly come from systems that control humidity and oxygen, support cleanroom operation, document environmental performance and integrate with automated handling or digital monitoring. Suppliers that reduce contamination risk and lifecycle operating cost while maintaining reproducible recovery after routine access are likely to capture a larger share of replacement and advanced-therapy demand.
Cell Culture Incubators Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.67 billion |
| Total Market Size in 2031 | USD 2.38 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Capacity, Application, End User, Geography |
| Companies |
|
Market Segmentation
By Product Type
CO2 Incubators
Multi-Gas and Hypoxia Incubators
IVF and Compact Specialty Incubators
Shaking and Other Specialized Incubators
By Capacity
Below 50 Liters
50-99 Liters
100-200 Liters
Above 200 Liters
By Application
Biopharmaceutical and Cell-Therapy Research and Manufacturing
Stem Cell and Regenerative Medicine
Cancer Research and Drug Discovery
IVF and Reproductive Medicine
Clinical Diagnostics and Other Applications
By End User
Pharmaceutical and Biotechnology Companies
Academic and Research Institutes
IVF and Fertility Clinics
Hospitals, Diagnostic Laboratories and CROs
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Currency and Assumptions
2. RESEARCH METHODOLOGY
2.1. Secondary Research
2.2. Company and Product Validation
2.3. Market Estimation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Contamination-Control Economics
4.4. Humidity, Gas Recovery and Reproducibility
4.5. Automation and Digital Monitoring
4.6. Lifecycle Cost and Laboratory Utilization
5. CELL CULTURE INCUBATORS MARKET BY PRODUCT TYPE
5.1. CO2 Incubators
5.2. Multi-Gas and Hypoxia Incubators
5.3. IVF and Compact Specialty Incubators
5.4. Shaking and Other Specialized Incubators
6. CELL CULTURE INCUBATORS MARKET BY CAPACITY
6.1. Below 50 Liters
6.2. 50-99 Liters
6.3. 100-200 Liters
6.4. Above 200 Liters
7. CELL CULTURE INCUBATORS MARKET BY APPLICATION
7.1. Biopharmaceutical and Cell-Therapy Research and Manufacturing
7.2. Stem Cell and Regenerative Medicine
7.3. Cancer Research and Drug Discovery
7.4. IVF and Reproductive Medicine
7.5. Clinical Diagnostics and Other Applications
8. CELL CULTURE INCUBATORS MARKET BY END USER
8.1. Pharmaceutical and Biotechnology Companies
8.2. Academic and Research Institutes
8.3. IVF and Fertility Clinics
8.4. Hospitals, Diagnostic Laboratories and CROs
8.5. Others
9. CELL CULTURE INCUBATORS MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Australia
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Product and Technology Positioning
10.2. Cleanroom and Validation Capabilities
10.3. Digital Monitoring and Automation Readiness
10.4. Service and Lifecycle-Cost Competition
11. COMPANY PROFILES
11.1. Thermo Fisher Scientific Inc.
11.2. PHC Holdings Corporation
11.3. Eppendorf SE
11.4. BINDER GmbH
11.5. Memmert GmbH + Co. KG
11.6. NuAire, Inc.
11.7. Esco Lifesciences Group
11.8. Sheldon Manufacturing, Inc.
11.9. Benchmark Scientific, Inc.
11.10. Caron Products & Services, Inc.
11.11. ASTEC Co., Ltd.
11.12. Labotect Labor-Technik GmbH
11.13. N-BIOTEK, Inc.
11.14. Heal Force Bio-Meditech Holdings Limited
11.15. BIOBASE Group
12. APPENDIX
12.1. Market Definition and Exclusions
12.2. Assumptions
12.3. Abbreviations
Navigate
Trusted by the world's leading organizations











