
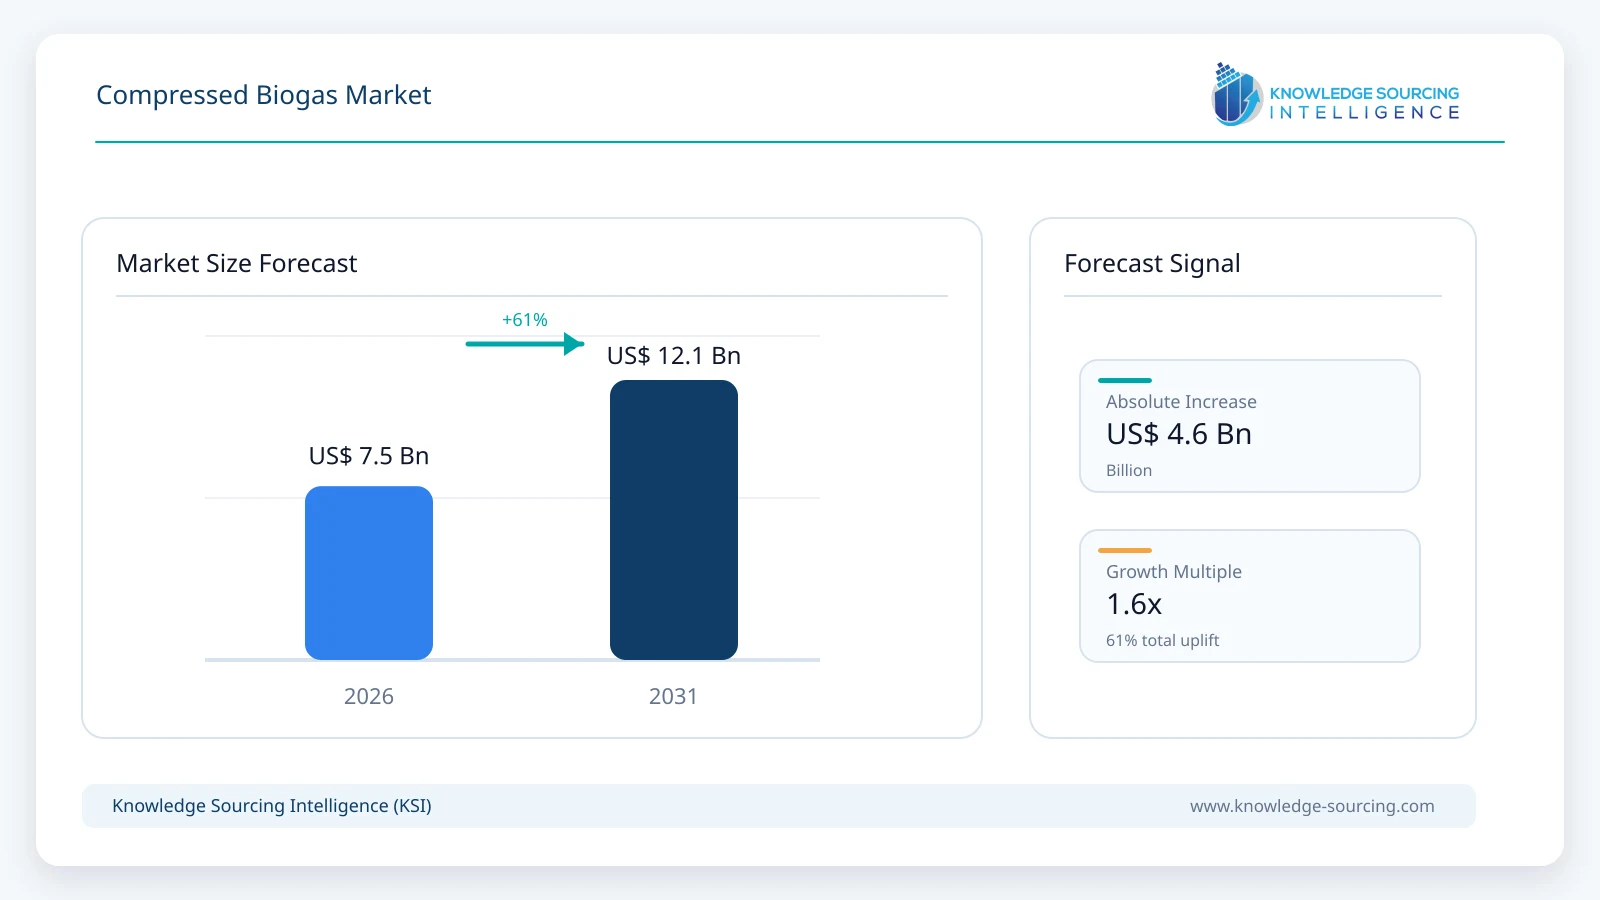
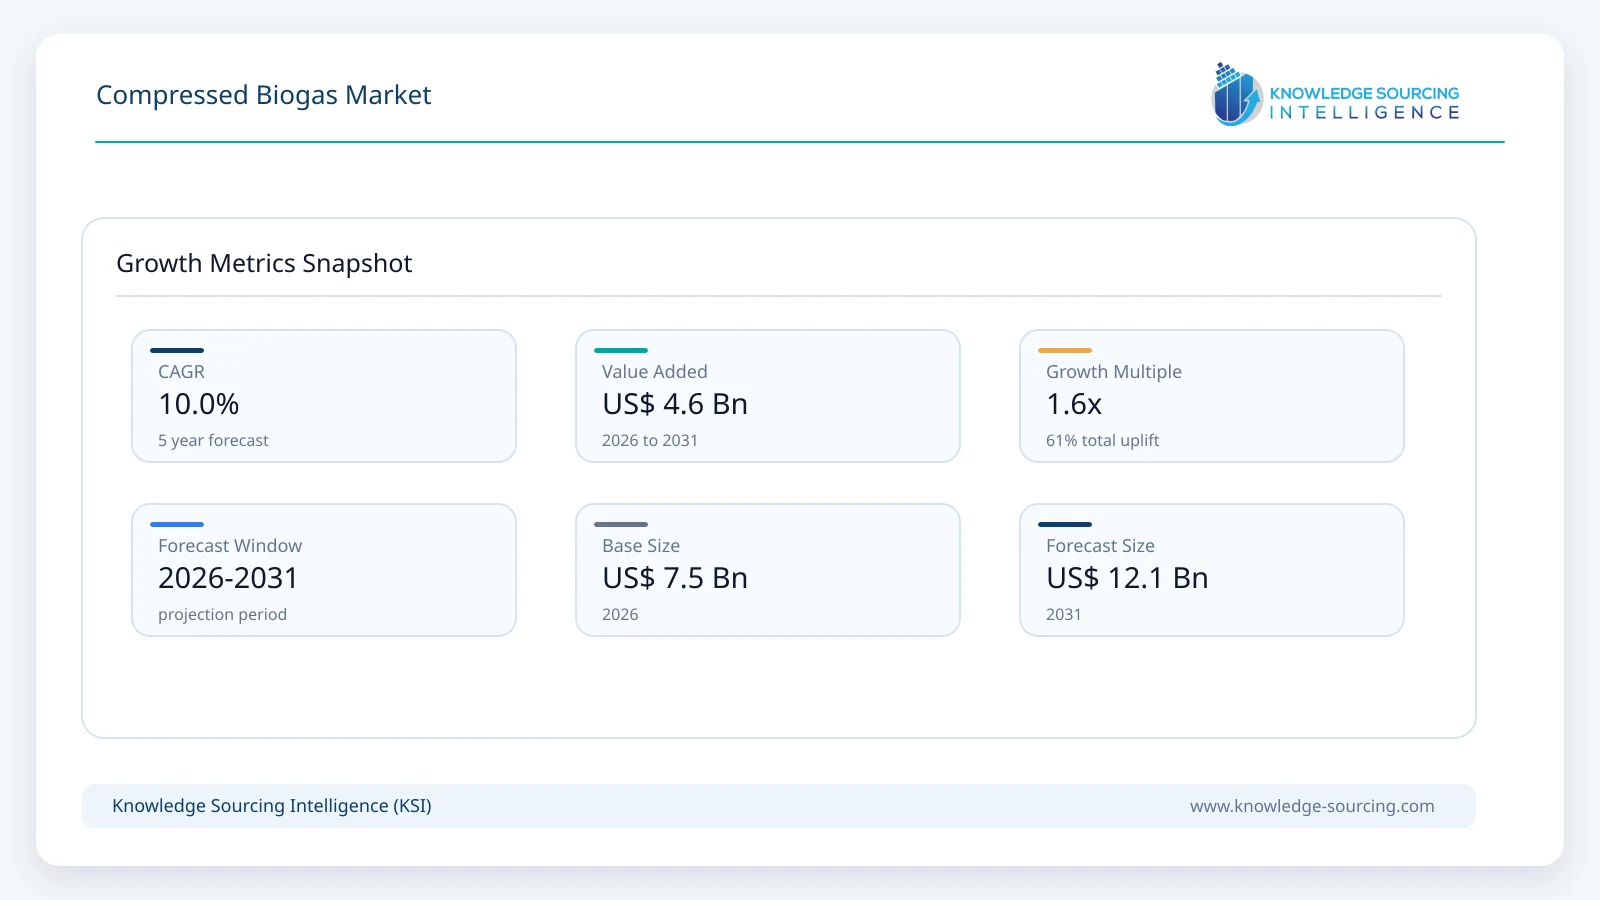
The Compressed Biogas Market is projected to grow from USD 7.48 billion in 2026 to USD 12.05 billion by 2031, at a CAGR of 10.0% during forecast period.
Highlights:
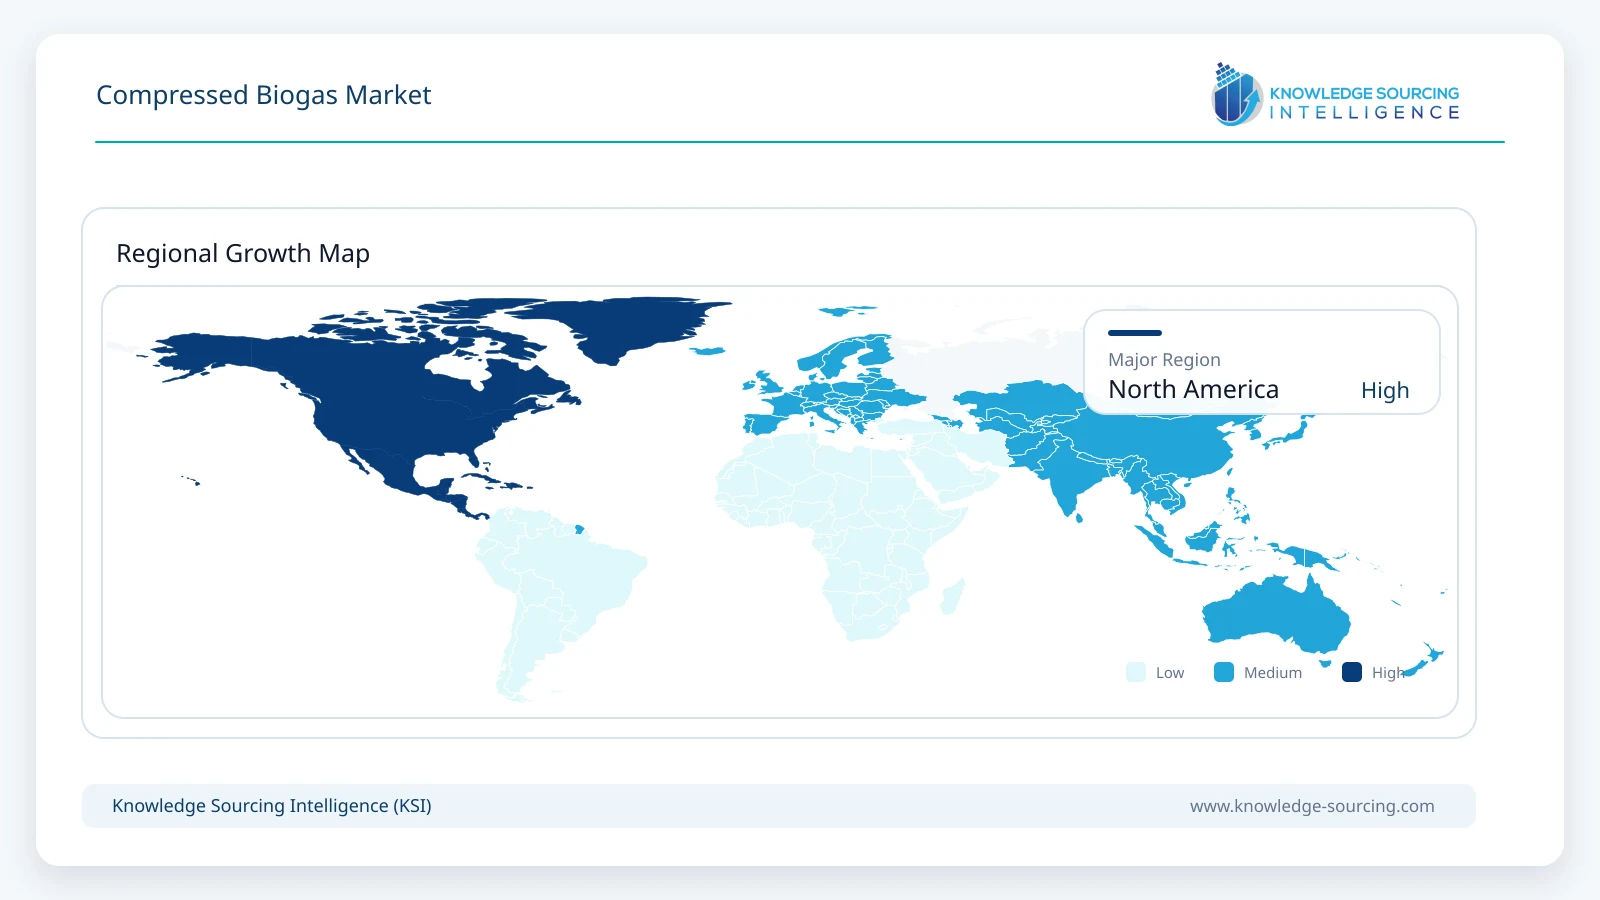
- 1Asia-Pacific is expected to be the fastest growing region whereas North America accounted for the highest share in 2026.
- 2Vehicle fuel was the leading application in the Indian CBG market in 2026.
- 3A key demand catalyst is the national CBG programme with plant-development target and blending requirement for city gas distributors (CGD) in India.
- 4Municipal solid waste, agricultural residues and animal manure are the main feedstocks, with leading feedstock varying by region and study.
The primary feedstocks for biogas and compressed biogas (CBG) production in India include agricultural residues, animal manure, and municipal solid waste. Municipal solid waste and agricultural residues are major feedstock sources, supported by urban waste generation and the availability of paddy straw. By application, vehicle fuel is the leading end use, followed by industrial applications, cooking fuel, and city gas distribution.
Key growth drivers include the expanding adoption of CBG in commercial transport fleets, investments in advanced biogas upgrading technologies, integration of CBG into city gas distribution networks, decentralized renewable energy production, and rising demand for low-carbon industrial fuels. Major market trends include increased utilization of agricultural waste and the development of industrial-scale anaerobic digestion facilities.
North America's market is supported by low-carbon fuel credit mechanisms and renewable natural gas programs, while Asia-Pacific is projected to witness strong growth, driven by renewable gas initiatives and India's expanding CBG ecosystem. The Indian market remains moderately fragmented, with several established energy companies and technology providers competing across the value chain. Key players include Reliance Bio Energy, IndianOil, BPCL, Adani TotalEnergies Biomass, HPCL, GAIL, and Praj Industries.
Market Dynamics
Market Drivers
CBDGs are set to benefit from a rapidly expanding addressable market as demand for low-carbon fuels in commercial transport fleets and industry grows, due to blending requirements and low-carbon fuel incentives.
The integration of CBG into city gas distribution networks and the increase in the refueling infrastructure are creating greater certainty of offtake for producers.
Feedstock availability is growing due to increased amounts of agricultural and municipal organic waste as well as policies designed to reduce crop-residue burning and landfill methane.
Innovative technology for upgrading and compressing biogas is reducing the costs and enhancing the quality of the gas.
Market Restraints & Opportunities
The speed of scale-up is constrained by high capital cost of plants and upgrading equipment, largely due to the logistics and price volatility of feedstock, offtake and pricing uncertainty, and reliance on policy support for project economics.
However, opportunities for plant developers, technology suppliers and fuel distributors are growing rapidly thanks to decentralized production, gas quality standardization, carbon-credit revenues and the rising demand from fleets and industry.
Key Developments
August 2026: BP has awarded global automation leader Emerson, a multi-million-dollar contract to deliver automation technologies for the Shah Deniz Compression project off the coast of Azerbaijan.
July 2026: Burckhardt Compression confirms the completion of the acquisition of Fornovo Gas S.p.A.
Compressed Biogas Market Segmentation
The market is segmented by feedstock, application, end user, and geography.
By Feedstock
Agricultural Residues, Manure and Municipal Solid Waste
The main feedstocks are agricultural residues, animal manure and municipal solid waste, the mix depending on regional availability and policy; in addition, residue-based projects can help alleviate the problem of crop burning.
Verbio SE is a European biomethane producer of agricultural residues, working both in Europe and India.
Praj Industries Ltd. offers bioenergy technology solutions and CBG plant solutions.
By Application
Vehicle Fuel
The biggest application is in vehicle fuel, with CBG use existing in compressed natural gas (CNG) vehicles and stations, with commercial fleets and public transport.
Indian Oil Corporation Ltd. is building CBG supply and retail stores in India's national initiative.
Gasum Oy is the producer and distributor of biogas for transport in the Nordic region.
Regional Analysis
North America
North America had the highest regional penetration in 2025, partly driven by renewable NG programs, low carbon fuel credits and a solid number of landfill, dairy and wastewater projects.
Europe
The biomethane industry in Europe is well developed, with grid injection and transport use with renewable gas targets and incentives in Germany, France, Italy, Nordics and the Netherlands.
Asia-Pacific
Asia-Pacific is forecast to grow fastest, led by India's national CBG program and by large-scale organic waste and rural biogas initiatives in China and Southeast Asia.
Middle East and Africa
The Middle East and Africa are an early-stage market, with interest focused on municipal waste-to-energy and fleet fuel pilots.
South America
South America offers growing potential from sugarcane, livestock and landfill resources, with Brazil advancing biomethane policy and projects.
List of Companies
Air Liquide S.A.
Veolia Environnement S.A.
Gasum Oy
Verbio SE
Reliance Bio Energy
Indian Oil Corporation Ltd.
GAIL (India) Ltd.
Adani TotalEnergies Biomass Ltd.
Praj Industries Ltd.
EverEnviro Resource Management
Competitive Landscape
Air Liquide S.A.
Air Liquide supplies biogas purification and liquefaction technology and distributes biomethane for mobility and industrial use as part of its renewable gas activities.
Verbio SE
Verbio produces biomethane and biofuels from agricultural residues, with operations in Europe and expansion into India.
Indian Oil Corporation Ltd.
IndianOil is a leading Indian energy company developing CBG supply, offtake and retail outlets under the government's national program, alongside peers such as GAIL, BPCL and HPCL.
Analyst View
The Compressed Biogas market is growing quickly because it turns waste into a drop-in fuel that works with existing gas vehicles and networks, and because governments are backing it with targets, blending rules and incentives. Estimates vary widely by scope and by country, so users should read headline numbers against definition. India is the most dynamic national market, while North America and Europe continue to scale renewable natural gas. Success depends on securing feedstock, controlling plant costs and locking in offtake with fleets and city gas distributors. Companies that integrate feedstock aggregation, upgrading technology and fuel distribution are best positioned.
Compressed Biogas Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 7.48 billion |
| Total Market Size in 2031 | USD 12.05 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 10.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Feedstock, Application, End User , Geography |
| Companies |
|
Market Segmentation
By Feedstock
Agricultural Residues
Animal Manure
Municipal Solid Waste
Sewage & Others
By Application
Vehicle Fuel
City Gas Distribution
Industrial Use
Cooking & Others
By End User
Transportation
Residential & Commercial
Industrial
Utilities
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Others
Europe
Germany
France
United Kingdom
Others
Middle East and Africa
UAE
Saudi Arabia
Others
Asia Pacific
China
India
Japan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations (National CBG Programs, Blending Obligations, Low-Carbon Fuel Standards)
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Biogas Upgrading & Purification
4.2. Compression & Cascade Storage
4.3. Grid Injection & Distribution
4.4. Feedstock Aggregation & Logistics
5. COMPRESSED BIOGAS MARKET BY FEEDSTOCK
5.1. Introduction
5.2. Agricultural Residues
5.3. Animal Manure
5.4. Municipal Solid Waste
5.5. Sewage & Others
6. COMPRESSED BIOGAS MARKET BY APPLICATION
6.1. Introduction
6.2. Vehicle Fuel
6.3. City Gas Distribution
6.4. Industrial Use
6.5. Cooking & Others
7. COMPRESSED BIOGAS MARKET BY END USER
7.1. Introduction
7.2. Transportation
7.3. Residential & Commercial
7.4. Industrial
7.5. Utilities
8. COMPRESSED BIOGAS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Others
8.5. Middle East and Africa
8.5.1. UAE
8.5.2. Saudi Arabia
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Air Liquide S.A.
10.2. Veolia Environnement S.A.
10.3. Gasum Oy
10.4. Verbio SE
10.5. Reliance Bio Energy
10.6. Indian Oil Corporation Ltd.
10.7. GAIL (India) Ltd.
10.8. Adani TotalEnergies Biomass Ltd.
10.9. Praj Industries Ltd.
10.10. EverEnviro Resource Management
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for the Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











