
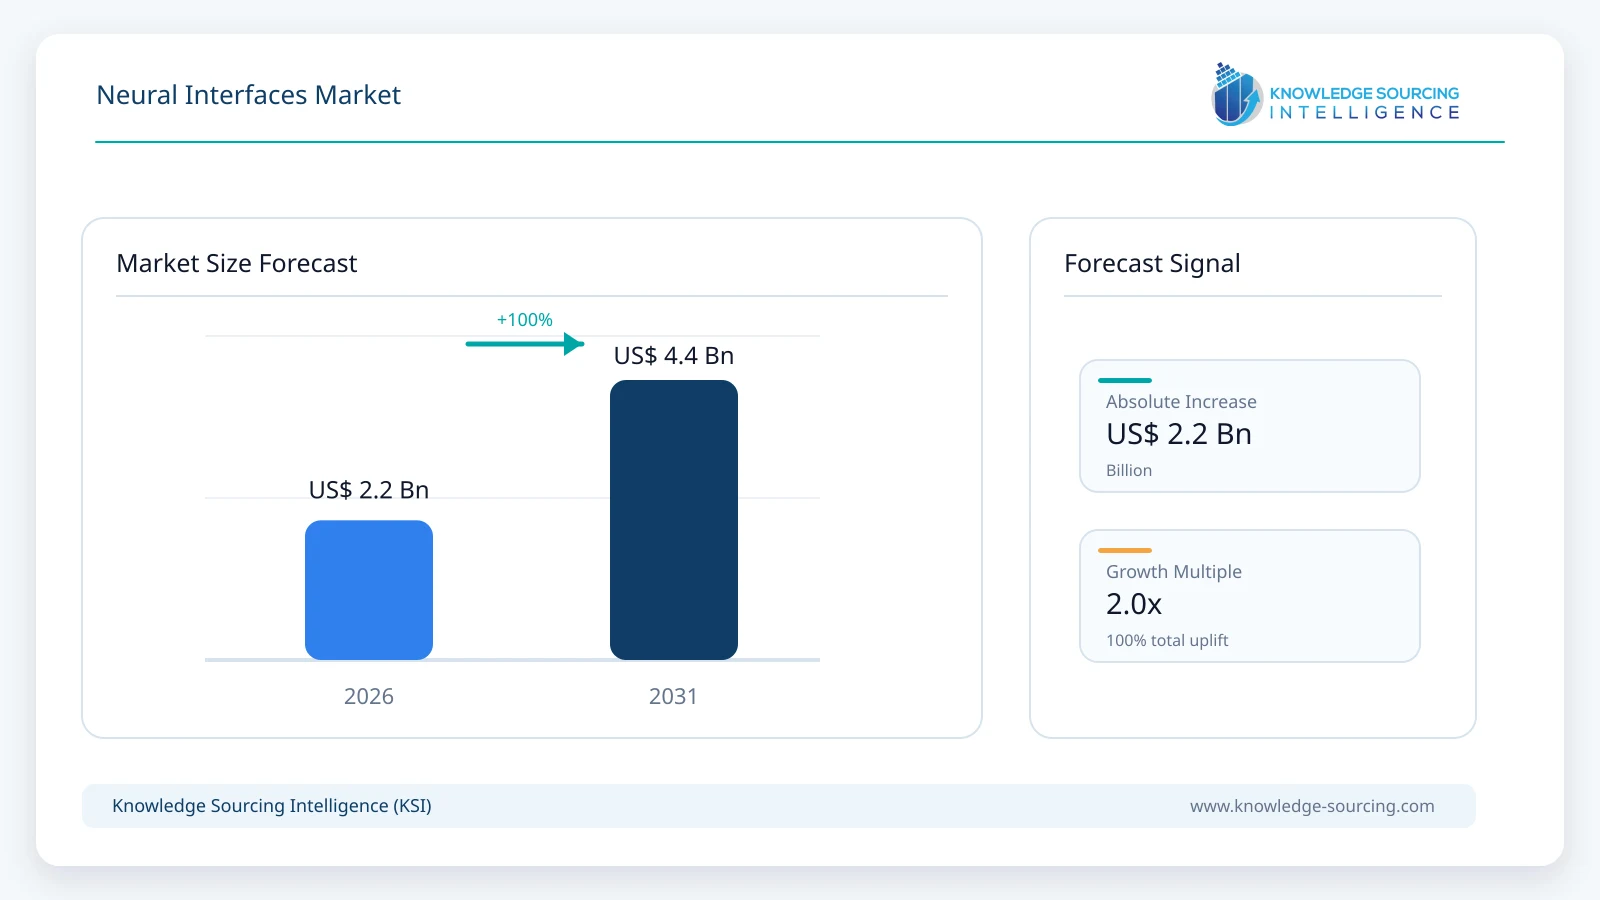
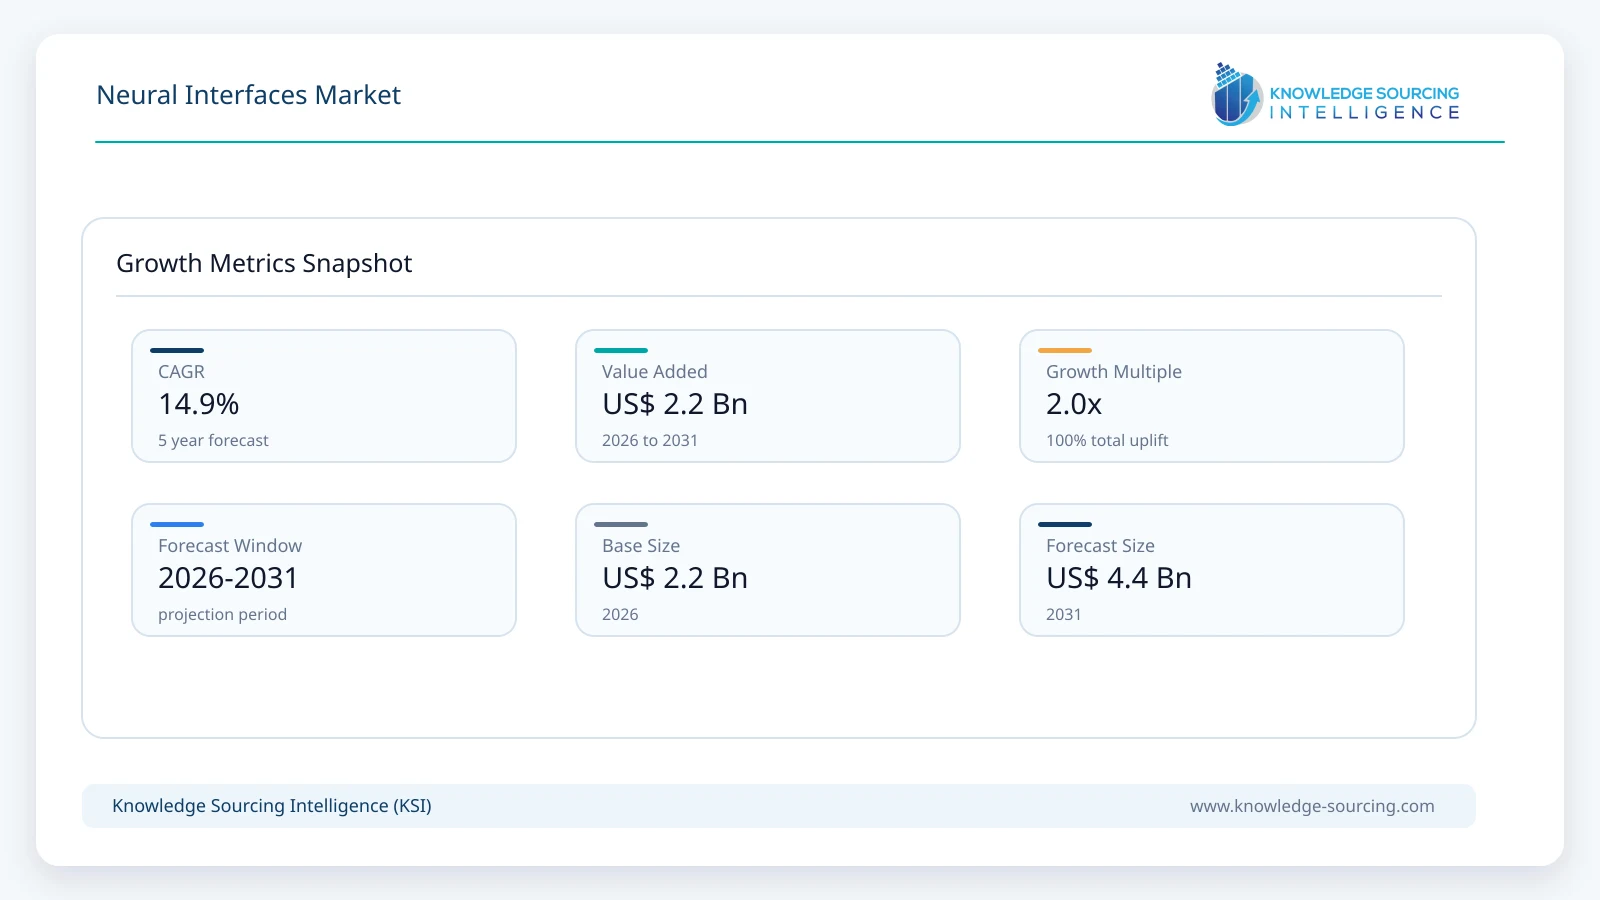
The global neural interfaces market is estimated at USD 2.18 billion in 2026 and is projected to reach USD 4.37 billion by 2031, growing at a CAGR of 14.9% during the forecast period.
Highlights:
- 1Hardware accounts for approximately 71% of global neural-interface revenue in 2026.
- 2Non-invasive BCIs represent about 56% of 2026 product-type revenue worldwide.
- 3Partially invasive interfaces are expected to post the fastest growth through 2031.
- 4Healthcare represents approximately 63% of global neural-interface spending in 2026.
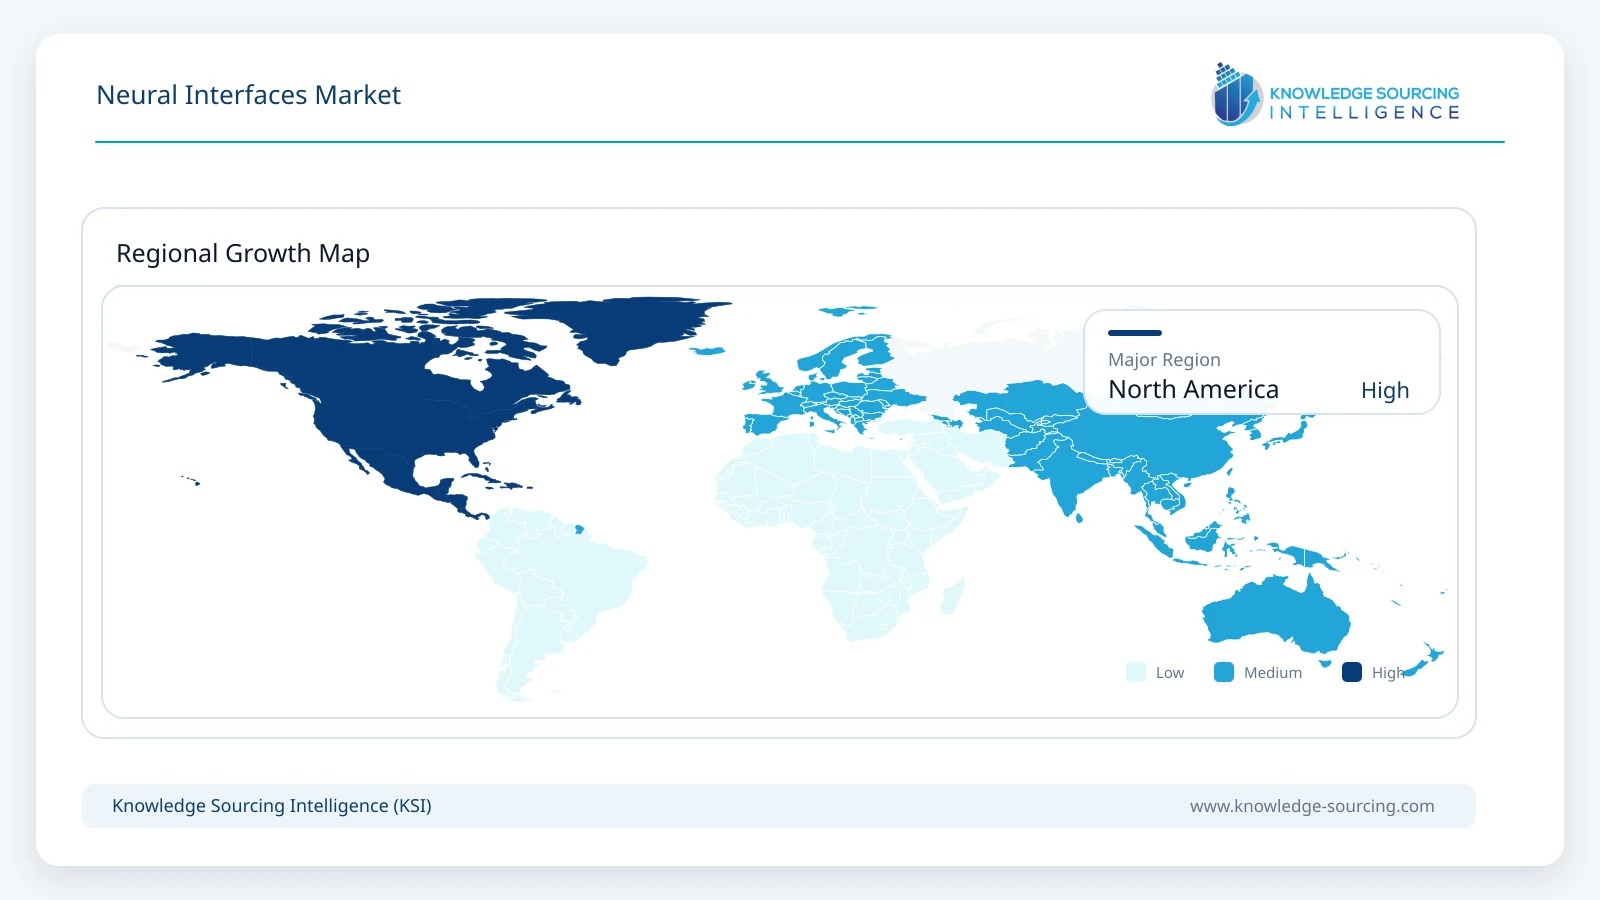
- 5North America accounts for about 44% of global neural-interface revenue in 2026.
Market Overview
The estimate reflects commercial sales of BCI-oriented acquisition systems, electrodes and headsets, neural signal processors, software and decoding platforms, rehabilitation systems, consumer neural-sensing products, and the emerging revenue base associated with implantable and minimally invasive neural-interface systems. The forecast does not assume that all investigational implants become commercial products; growth accelerates as selected platforms move from feasibility studies toward regulated deployment while the much larger non-invasive installed base continues to expand.
Commercial activity remains split between established research and non-invasive BCI suppliers and a rapidly developing implantable-interface segment. Companies such as g.tec, Brain Products, ANT Neuro, EMOTIV, Ripple Neuro, and Blackrock Neurotech already sell neural acquisition, processing, or BCI systems. At the same time, Neuralink, Synchron, Precision Neuroscience, Paradromics, INBRAIN Neuroelectronics, CorTec, ONWARD Medical, and Neuracle Medical Technology are moving invasive or minimally invasive interfaces through clinical, regulatory, and early commercial pathways. This mix produces a market in which research hardware remains an important revenue base while clinical-grade interfaces create the strongest medium-term growth potential.
The addressable need is substantial. The World Health Organization reported in October 2025 that neurological conditions affect more than 40% of the global population, or more than 3 billion people. Neural interfaces will address only a small subset of this population, but paralysis, spinal cord injury, stroke, amyotrophic lateral sclerosis, and other motor or communication impairments provide clear clinical use cases for direct neural control and neurorehabilitation. FDA guidance for implanted BCI devices also provides a defined framework for non-clinical testing and feasibility and pivotal study design, supporting a more structured route toward market access in the United States.
Market Drivers and Trends
Clinical translation is moving beyond single-patient demonstrations
Implantable and minimally invasive BCI programs are moving into larger and more structured clinical studies. Neuralink reported in January 2026 that its clinical program had expanded from three participants in 2024 to multiple participants per month during 2025, while it continued development of higher-electrode-count implants. Paradromics completed the first implantation in its FDA-approved Connect-One early feasibility study in June 2026 and later reported real-time speech and text communication from the first participant in September 2026. These programs expand the evidence base for communication, computer control, robotic control, and assistive autonomy.
Lower-invasiveness architectures broaden the competitive field
The market is no longer defined only by scalp EEG at one end and penetrating intracortical arrays at the other. Synchron uses an endovascular Stentrode placed through blood vessels; Precision Neuroscience uses a thin cortical-surface array; Neuracle Medical Technology commercialized an epidural BCI in China; and CorTec is evaluating a fully implantable cortical-surface system. These approaches target improved signal quality while reducing surgical burden or avoiding direct penetration of brain tissue, supporting the faster-growth outlook for partially invasive systems.
AI improves decoding, calibration, and adaptive control
Machine learning is increasingly embedded in neural-signal processing. Modern BCI systems use adaptive classifiers, neural decoding models, language models, and multimodal inputs to translate neural activity into cursor movement, speech, device control, or therapy. AI is particularly important for noisy non-invasive signals and for high-channel-count implantable systems, where large data streams must be converted into low-latency commands. The commercial implication is a gradual increase in software and recurring analytics value even though hardware remains the larger revenue pool in 2026.
Consumer neurotechnology creates a second commercialization path
Non-invasive neural interfaces are expanding beyond clinical research. Neurable integrates BCI sensing into everyday headphone form factors, while EMOTIV sells headset and software platforms for research, control, performance monitoring, and human-computer interaction. Consumer adoption remains smaller than healthcare and research spending, but it widens the market beyond severe neurological impairment and creates use cases in productivity, fatigue monitoring, entertainment, training, and adaptive computing.
Market Restraints
Long-term safety and signal stability remain critical
Implantable interfaces must maintain stable neural recording while limiting infection, tissue response, mechanical failure, electrode migration, and explantation risk. High-density systems also require reliable wireless communication, packaging, power management, and long-duration biocompatibility. These factors lengthen development timelines and raise evidence requirements compared with ordinary consumer electronics.
Clinical benefit must justify surgical and reimbursement burden
For medical BCIs, technical performance alone does not create adoption. Systems must demonstrate meaningful functional improvement, usability outside research environments, manageable surgical workflows, reliability, and a path to reimbursement. The economic case is strongest where a BCI restores communication or control that cannot be achieved effectively with conventional assistive technologies.
Non-invasive systems face signal-quality and calibration limitations
EEG-based interfaces are safer and easier to deploy but provide lower spatial resolution and are more sensitive to motion artifacts, electrode placement, individual variability, and session-to-session drift. These constraints can increase training and calibration requirements and can limit performance in high-precision control applications.
Segment Analysis
By Component - Hardware
Hardware generated an estimated USD 1.55 billion in 2026. This includes EEG and neural-acquisition systems, electrode arrays, amplifiers, headsets, signal processors, implantable interfaces, surgical components, and dedicated BCI peripherals. Hardware remains the major revenue pool because high-channel-count research systems and clinical-grade neural interfaces carry substantially higher unit values than software alone. Software is expected to gain share through decoding, adaptive control, data processing, device integration, and recurring platform functionality.
By Product Type - Non-Invasive and Partially Invasive BCIs
Non-invasive BCIs generated approximately USD 1.22 billion in 2026, supported by the broad installed base of EEG-based research, rehabilitation, education, consumer, and human-computer-interaction systems. Partially invasive BCIs are expected to be the fastest-growing product type, with an estimated 2026-2031 CAGR of about 19.2%. Endovascular, epidural, and cortical-surface systems are attracting clinical and regulatory activity because they seek a middle ground between signal fidelity and surgical burden.
By Application - Medical and Therapeutic Uses
Medical and therapeutic applications generated approximately USD 1.26 billion in 2026. The category includes communication restoration, motor control, neurorehabilitation, assistive robotics, assessment, therapeutic closed-loop interfaces, and selected neural-function restoration applications. Commercial demand is supported by hospitals, specialist centers, rehabilitation programs, clinical studies, and research institutions. Productivity, affective computing, gaming, and other consumer applications remain smaller but are expanding as non-invasive devices become easier to integrate into familiar form factors.
By End User - Healthcare
Healthcare generated approximately USD 1.37 billion in 2026. Hospitals, specialist neurological centers, rehabilitation providers, clinical research sites, and medically oriented neurotechnology programs account for the largest spending base because clinical-grade systems require high-performance acquisition, regulated components, specialist support, and integration with assistive or therapeutic workflows. Consumer electronics is expected to grow faster than the total market from a smaller base as brain-sensing capabilities move into headphones and other wearable devices.
Geographic Analysis
North America
North America generated approximately USD 959.0 million in 2026. The region combines a dense neurotechnology start-up ecosystem, established neuroscience-equipment suppliers, leading clinical research centers, FDA pathways for implanted BCIs, and significant venture and institutional funding. Neuralink, Synchron, Precision Neuroscience, Paradromics, Blackrock Neurotech, Ripple Neuro, EMOTIV, and Neurable all contribute to the regional ecosystem.
Europe
Europe has a strong base in BCI research equipment, implantable neurotechnology, and translational neuroscience. g.tec, Brain Products, ANT Neuro, INBRAIN Neuroelectronics, CorTec, and ONWARD Medical are important participants. European activity spans non-invasive research platforms, rehabilitation, graphene interfaces, cortical implants, and spinal-cord/BCI integration.
Asia Pacific
Asia Pacific is expected to be the fastest-growing region through 2031, supported by neuroscience research, expanding medical-device capabilities, rehabilitation demand, and commercialization in China. In March 2026, China approved Neuracle Medical Technology's NEO implantable BCI for hand-motor-function compensation, marking an important shift from investigational use toward regulated commercial deployment in the region.
Competitive Environment
Competition is segmented by interface architecture and route to market. Established non-invasive suppliers compete on channel count, signal quality, electrode design, mobility, software integration, and research workflow. Implantable-interface developers compete on surgical approach, electrode density, long-term stability, wireless architecture, decoding performance, clinical indication, regulatory progress, and manufacturability. The market therefore does not have a single dominant platform architecture.
The market includes only companies with current, direct participation in neural-interface or BCI systems. General neurostimulation, diagnostic EEG, prosthetics, AI, or neuroscience companies are excluded unless they sell or clinically develop a dedicated interface that reads, decodes, or bidirectionally interacts with neural signals.
Recent Developments
• September 14, 2026: Paradromics reported real-time speech and text communication by the first participant implanted with the Connexus BCI in the Connect-One study.
• August 31, 2026: CorTec received a second FDA Breakthrough Device Designation for Brain Interchange, adding a communication indication to its earlier 2026 stroke motor-rehabilitation designation.
• June 17, 2026: Paradromics and University of Michigan completed the first Connexus BCI implantation in the FDA-approved Connect-One early feasibility study.
• March 2026: China's National Medical Products Administration approved Neuracle Medical Technology's NEO implantable BCI hand motor function compensation system. Fudan University reported that the registration followed multicenter validation involving 32 cases.
• January 28, 2026: Neuralink reported two years of Telepathy clinical progress and said its development plan included increasing implant electrode count from about 1,000 to 3,000 while refining implantation and signal retention.
Market Outlook
Neural interfaces are moving from a research-led market toward a mixed commercial structure combining mature non-invasive platforms, consumer neural sensing, neurorehabilitation systems, and emerging regulated implantable interfaces. Through 2031, the largest revenue pool should remain hardware, but software and decoding layers will become more valuable as systems require adaptive algorithms, user-specific models, and device integration. The strongest growth is expected in partially invasive architectures and clinical applications where direct neural control can provide meaningful gains in communication or independence.
Implanted BCIs are not expected to become an immediate mass-adoption opportunity. Clinical evidence, safety, manufacturing, regulatory approval, reimbursement, and specialist deployment remain significant constraints. The forecast assumes gradual commercialization of selected platforms rather than broad replacement of established assistive technologies. Non-invasive research and rehabilitation systems remain the stabilizing base, while implantable and minimally invasive technologies provide the incremental growth engine.
Neural Interfaces Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.18 billion |
| Total Market Size in 2031 | USD 4.37 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 14.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Product Type, Application, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
Hardware
Software
By Product Type
Invasive BCIs
Partially Invasive BCIs
Non-Invasive BCIs
By Application
Medical and Therapeutic Uses
Substitute for CNS / Functional Restoration
Assessment and Diagnosis
Therapy and Neurorehabilitation
Affective Computing
Gaming and Entertainment
Productivity and Workplace Applications
Transport and Other Human-Machine Interaction
By End User
Healthcare
Consumer Electronics
Military and Defense Research
Research, Academic and Other Users
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1 Market Definition and Scope
1.2 Neural-Interface Revenue Boundary
1.3 Regulatory and Clinical Considerations
2. RESEARCH METHODOLOGY
2.1 Bottom-Up Vendor and Product Reconciliation
2.2 Clinical and Commercial Adoption Framework
2.3 Forecast Assumptions
3. EXECUTIVE SUMMARY
3.1 Market Size and Growth
3.2 Key Findings
4. MARKET DYNAMICS
4.1 Drivers
4.2 Restraints
4.3 Technology Trends
4.4 Regulatory and Commercialization Trends
5. NEURAL INTERFACES MARKET BY COMPONENT
5.1 Hardware
5.2 Software
6. NEURAL INTERFACES MARKET BY PRODUCT TYPE
6.1 Invasive BCIs
6.2 Partially Invasive BCIs
6.3 Non-Invasive BCIs
7. NEURAL INTERFACES MARKET BY APPLICATION
7.1 Medical and Therapeutic Uses
7.1.1 Substitute for CNS / Functional Restoration
7.1.2 Assessment and Diagnosis
7.1.3 Therapy and Neurorehabilitation
7.2 Affective Computing
7.3 Gaming and Entertainment
7.4 Productivity and Workplace Applications
7.5 Transport and Other Human-Machine Interaction
8. NEURAL INTERFACES MARKET BY END USER
8.1 Healthcare
8.2 Consumer Electronics
8.3 Military and Defense Research
8.4 Research, Academic and Other Users
9. NEURAL INTERFACES MARKET BY GEOGRAPHY
9.1 North America
9.1.1 United States
9.1.2 Canada
9.1.3 Mexico
9.2 South America
9.2.1 Brazil
9.2.2 Argentina
9.2.3 Others
9.3 Europe
9.3.1 United Kingdom
9.3.2 Germany
9.3.3 France
9.3.4 Italy
9.3.5 Spain
9.3.6 Others
9.4 Middle East and Africa
9.4.1 Saudi Arabia
9.4.2 UAE
9.4.3 Others
9.5 Asia Pacific
9.5.1 China
9.5.2 India
9.5.3 Japan
9.5.4 South Korea
9.5.5 Australia
9.5.6 Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1 Interface Architecture and Product Positioning
10.2 Clinical and Regulatory Progress
10.3 Partnerships, Funding and Commercialization
10.4 Competitive Dashboard
11. COMPANY PROFILES
11.1 Neuralink Corp.
11.2 Synchron, Inc.
11.3 Precision Neuroscience Corporation
11.4 Paradromics, Inc.
11.5 Blackrock Neurotech
11.6 Neuracle Medical Technology (Shanghai) Co., Ltd.
11.7 INBRAIN Neuroelectronics S.L.
11.8 CorTec GmbH
11.9 ONWARD Medical N.V.
11.10 g.tec medical engineering GmbH
11.11 EMOTIV Inc.
11.12 Brain Products GmbH
11.13 ANT Neuro
11.14 Ripple Neuro
11.15 Neurable, Inc.
12. APPENDIX





Frequently asked questions
What is the projected market size for neural interfaces by 2031?
The Neural Interfaces Market is projected to reach USD 4.37 billion by 2031.
What is the compound annual growth rate (CAGR) for 2026-2031?
The Neural Interfaces Market is projected to grow at a 14.9% CAGR.
Which component accounts for the largest neural interface revenue share?
Hardware accounts for approximately 71% of global revenue in 2026.
Which product type leads revenue for neural interfaces in 2026?
Non-invasive BCIs represent about 56% of 2026 product-type revenue.
Which geographical region dominates neural interface revenue in 2026?
North America accounts for about 44% of global revenue in 2026.
What is a primary market driver for neural interface growth?
Clinical translation beyond single-patient demonstrations is a key driver.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Neural Interfaces Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/neural-interfaces-market