
The AI in the assistive technology market is expected to grow steadily over the forecasted timeframe.
Highlights:
- 1Rising prevalence of age-related sensory and mobility impairments continues to strengthen demand for AI-enabled assistive solutions across healthcare and home-care settings.
- 2Hearing aids remain among the most commercially mature product categories due to continuous AI integration for sound optimization and speech enhancement.
- 3North America maintains a strong market position through advanced healthcare infrastructure, reimbursement support, and investment in accessibility technologies.
- 4Machine learning is becoming the primary enabling technology for adaptive personalization, predictive user behavior, and continuous device optimization.
- 5Accessibility legislation, disability inclusion policies, and medical device regulations encourage adoption while establishing quality and safety requirements.
- 6Competition increasingly depends on software intelligence, clinical validation, ecosystem partnerships, and integration with digital healthcare platforms.
The AI in Assistive Technology market represents the intersection of artificial intelligence and medical, rehabilitation, and accessibility technologies designed to improve independence and functional capabilities for individuals with physical, sensory, cognitive, and communication impairments. AI enables assistive devices to adapt to user behavior, recognize environmental conditions, process speech and visual information, and provide personalized support in real time. These capabilities are expanding the role of assistive technologies beyond conventional mechanical assistance toward intelligent systems that continuously improve user experience and clinical outcomes.
Demand is primarily supported by demographic and healthcare trends. Population ageing across developed and several emerging economies has increased the prevalence of hearing loss, visual impairment, mobility limitations, and neurodegenerative disorders. Simultaneously, higher survival rates following stroke, traumatic brain injury, spinal cord injury, and congenital disabilities have created sustained demand for long-term rehabilitation solutions. Healthcare providers, rehabilitation specialists, and caregivers are seeking technologies that reduce dependence on continuous human assistance while improving patient engagement and functional recovery.
Commercial adoption is also influenced by broader accessibility initiatives across education, workplaces, and public services. Governments have strengthened disability inclusion policies, encouraging the procurement of intelligent communication devices, AI-assisted reading systems, speech recognition platforms, and adaptive mobility equipment. Educational institutions and employers are investing in accessible technologies to comply with disability regulations while supporting participation in learning and employment.
Buyer priorities have shifted from hardware performance alone toward intelligent functionality, interoperability, ease of customization, and long-term software support. Hospitals increasingly evaluate whether AI-enabled devices can integrate with electronic health records and rehabilitation workflows. Home-care providers seek systems capable of remote monitoring and adaptive assistance that reduce caregiver burden. Procurement decisions are also influenced by reimbursement eligibility, clinical evidence, cybersecurity standards, and product reliability.
The industry consists of established hearing technology manufacturers, prosthetics developers, AI software specialists, and digital accessibility companies. Competition extends beyond hardware innovation to include cloud-based analytics, machine learning algorithms, multilingual speech recognition, computer vision capabilities, and software updates that enhance device performance throughout the product lifecycle. Partnerships with healthcare providers, research institutions, and disability organizations have become an important route for product validation and market expansion.
Market Drivers
Growing ageing population and disability prevalence
The expanding elderly population is increasing the incidence of hearing impairment, vision loss, reduced mobility, and cognitive decline. Healthcare systems require assistive technologies that support independent living while reducing long-term institutional care costs. Buyers increasingly prioritize AI-enabled products capable of learning user preferences and adapting assistance according to changing functional abilities. Manufacturers continue investing in adaptive algorithms and multimodal sensing technologies that improve long-term usability and patient outcomes.
Expansion of home-based healthcare and rehabilitation
Healthcare providers are shifting portions of rehabilitation from hospitals to home environments to improve patient convenience and optimize healthcare resources. AI-enabled assistive technologies support this transition by enabling continuous monitoring, remote adjustments, and personalized therapy recommendations. Home-care organizations and insurers recognize that intelligent devices can improve adherence to rehabilitation programs while reducing avoidable clinical visits, strengthening commercial demand across multiple product categories.
Advances in speech, vision, and language processing
Progress in natural language processing, computer vision, and machine learning has substantially improved the performance of communication aids, reading assistance, object recognition, and environmental navigation. These improvements expand the addressable user population by supporting individuals with multiple disabilities simultaneously. Buyers increasingly value products that combine several AI functions within a single device rather than relying on separate assistive solutions.
Greater emphasis on accessibility and workforce participation
Governments, employers, and educational institutions are investing in accessible technologies to improve participation among individuals with disabilities. AI-enabled communication platforms, captioning systems, visual interpretation tools, and cognitive support applications facilitate education and employment while helping organizations comply with accessibility requirements. This broadens commercial opportunities beyond healthcare into enterprise, education, and public sector procurement.
Market Restraints and Challenges
High acquisition and lifecycle costs
Advanced AI-enabled assistive technologies often involve premium hardware, specialized sensors, software licensing, and ongoing updates. Many healthcare providers and individuals face budget limitations, particularly in countries with limited reimbursement coverage. Manufacturers are responding through modular product designs, subscription-based software services, and financing programs, although affordability remains a purchasing constraint.
Uneven reimbursement and insurance coverage
Reimbursement policies differ considerably across countries and product categories. Some AI functions may not yet qualify for medical reimbursement despite providing measurable functional benefits. This uncertainty affects purchasing decisions by hospitals, rehabilitation centres, and individual users while extending procurement cycles and slowing commercial adoption.
Data privacy and cybersecurity requirements
AI-enabled assistive technologies frequently process voice recordings, biometric information, movement data, and health-related information. Compliance with healthcare privacy regulations requires substantial investment in cybersecurity, encryption, and secure cloud infrastructure. Smaller technology developers may experience higher compliance costs, influencing pricing and market competitiveness.
Clinical validation and user acceptance
Healthcare providers increasingly require evidence demonstrating measurable improvements in rehabilitation outcomes, communication effectiveness, and quality of life. AI systems must also perform reliably across different languages, accents, environmental conditions, and disability profiles. Extensive clinical evaluation and usability testing lengthen development timelines but remain essential for sustained commercial adoption.
Major Segment Analysis
Hearing Aids represent one of the most commercially important product categories within the AI in Assistive Technology market because they combine established reimbursement pathways with continuous advances in artificial intelligence. Modern AI-enabled hearing devices automatically classify listening environments, suppress background noise, prioritize speech, and personalize acoustic settings according to user behavior. These functions improve speech comprehension while reducing manual adjustments, increasing long-term user satisfaction.
Demand is supported by the growing prevalence of age-related hearing loss and greater awareness of early hearing intervention. Audiologists, hospitals, and hearing care providers increasingly recommend intelligent hearing systems that deliver measurable improvements in communication performance. Buyers also evaluate smartphone connectivity, remote programming capabilities, battery efficiency, and software update support when selecting products.
Competition within this segment increasingly depends on proprietary AI algorithms rather than hardware specifications alone. Companies differentiate through personalized sound processing, multilingual speech enhancement, cloud-enabled fitting platforms, and integration with broader digital health ecosystems. Continued investment in software intelligence is expected to strengthen recurring revenue opportunities through post-sale upgrades and connected healthcare services.
Regional Analysis
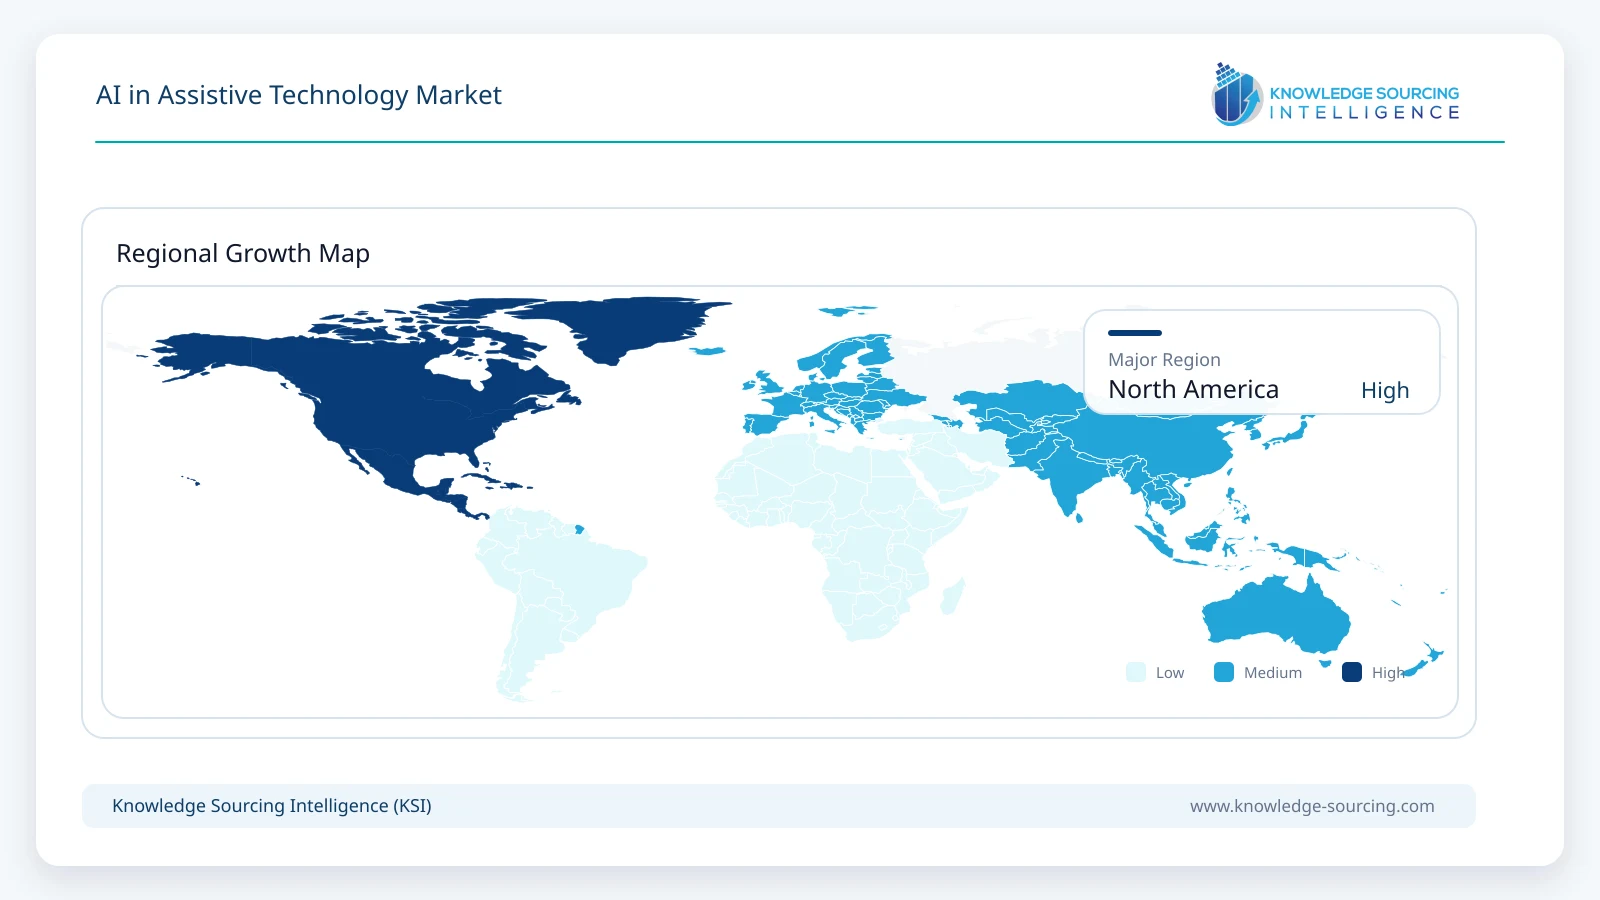
North America represents a mature commercial market supported by advanced healthcare infrastructure, disability legislation, and substantial investment in rehabilitation technologies. Healthcare providers demonstrate strong adoption of AI-assisted hearing, communication, and mobility devices, while reimbursement mechanisms encourage clinical deployment. Technology developers also benefit from active research partnerships and venture capital investment.
Europe benefits from comprehensive healthcare systems, ageing demographics, and established medical device regulations. Public procurement programs and accessibility legislation encourage adoption across healthcare, education, and employment sectors. Manufacturers also benefit from collaborative research initiatives focused on rehabilitation engineering and digital health innovation.
Asia Pacific offers considerable long-term commercial potential due to population size, expanding healthcare expenditure, and increasing awareness of disability services. Japan and South Korea demonstrate high adoption of advanced rehabilitation technologies, while China and India continue expanding healthcare infrastructure and digital accessibility initiatives. Cost sensitivity and uneven reimbursement remain important considerations across several regional markets.
Middle East & Africa is experiencing gradual adoption supported by healthcare modernization strategies and investment in specialist rehabilitation centres. Gulf countries continue expanding advanced healthcare services, while broader regional adoption depends on workforce training, procurement funding, and improved accessibility infrastructure.
South America presents opportunities through healthcare modernization and expanding rehabilitation services, particularly in Brazil and Argentina. Economic volatility, reimbursement limitations, and unequal healthcare access influence purchasing decisions, encouraging suppliers to develop cost-effective product portfolios suited to regional healthcare budgets.
Competitive Landscape
The AI in Assistive Technology market combines established medical device manufacturers with specialized AI technology developers. Competition extends across hardware engineering, software intelligence, clinical evidence generation, regulatory compliance, and ecosystem integration. Companies differentiate their offerings through adaptive machine learning, multilingual speech recognition, computer vision capabilities, personalized rehabilitation support, and seamless connectivity with smartphones and healthcare information systems.
Strategic collaborations with hospitals, universities, rehabilitation centres, and disability advocacy organizations support product validation and accelerate commercialization. Geographic expansion increasingly involves partnerships with regional distributors and healthcare providers to improve market access while addressing local reimbursement and regulatory requirements. Continuous software improvements, rather than hardware replacement alone, are becoming an important source of competitive differentiation and customer retention.
Recent Developments
July 2026: Torchit Electronics Pvt. Ltd. inaugurated the EnableMart Experience and Resource Center and introduced the EnableMart Assistive Technology Resource Book, providing AI-enabled accessibility solutions and practical resources supporting independent living for persons with visual disabilities.
May 2026: Apple unveiled Apple Vision Pro accessibility enhancements, enabling eye-tracking control for compatible powered wheelchairs, alongside AI-driven accessibility improvements designed to expand independence for users with mobility disabilities.
January 2026: Ottobock SE & Co. KGaA expanded digital rehabilitation capabilities by integrating AI-supported gait analysis into selected mobility and prosthetic solutions. The enhancement improved clinician decision-making and personalized rehabilitation planning.
Regulatory and Policy Environment
The regulatory framework for AI-enabled assistive technologies combines medical device oversight with accessibility, cybersecurity, and data protection requirements. Regulatory authorities increasingly evaluate AI functionality as part of software-enabled medical device assessments, requiring manufacturers to demonstrate safety, performance, clinical effectiveness, and risk management throughout the product lifecycle.
Accessibility legislation across several jurisdictions encourages adoption of communication technologies, adaptive learning systems, and workplace accommodations for individuals with disabilities. Government disability support programs and reimbursement policies also influence procurement decisions by hospitals, rehabilitation providers, and individual consumers.
Manufacturers must comply with evolving cybersecurity standards because connected assistive devices process sensitive health and personal information. International quality management standards, post-market surveillance obligations, and software update requirements have become increasingly important as AI capabilities continue expanding.
Outlook and Strategic Implications
Commercial investment over the next five years is expected to concentrate on adaptive intelligence, multimodal sensing, cloud connectivity, and personalized rehabilitation platforms. Procurement strategies are gradually shifting toward integrated ecosystems capable of supporting long-term patient management rather than standalone assistive devices. Healthcare providers are placing greater emphasis on clinical evidence demonstrating improved functional outcomes, user adherence, and cost efficiency.
Technology suppliers are expected to compete through software innovation, regulatory expertise, and partnerships with healthcare institutions that generate real-world clinical evidence. Expansion into home-based care and community rehabilitation will create additional opportunities for intelligent monitoring and remote device optimization.
Challenges related to affordability, reimbursement consistency, cybersecurity compliance, and equitable access will continue influencing purchasing decisions. Companies capable of combining clinical validation, scalable AI platforms, regulatory compliance, and region-specific commercialization strategies will be better positioned to address evolving healthcare and accessibility requirements while expanding their presence across global assistive technology markets.
AI in Assistive Technology Market Scope
| Report Metric | Details |
|---|---|
| Forecast Unit | Billion |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Technology, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product Type
By Technology
By End-user
By Geography
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Overview
4.2. Advances in Machine Learning for Assistive Technologies
4.3. Natural Language Processing and Speech Recognition
4.4. Computer Vision and Image Recognition
4.5. Emerging AI Innovations in Assistive Technology
5. AI IN ASSISTIVE TECHNOLOGY MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Mobility Aids
5.3. Hearing Aids
5.4. Vision and Reading Aids
5.5. Communication Aids
5.6. Cognitive and Sensory Aids
5.7. Prosthetics and Orthotics
6. AI IN ASSISTIVE TECHNOLOGY MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Machine Learning
6.3. Natural Language Processing
6.4. Computer Vision
6.5. Others
7. AI IN ASSISTIVE TECHNOLOGY MARKET BY END-USER
7.1. Introduction
7.2. Hospitals and Clinics
7.3. Home Care Settings
7.4. Rehabilitation Centres
7.5. Others
8. AI IN ASSISTIVE TECHNOLOGY MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Thailand
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Cognixion
10.2. Voiceitt
10.3. Parrots Inc.
10.4. OrCam Technologies Ltd.
10.5. Ava
10.6. Sonova AG
10.7. GN Store Nord A/S
10.8. Demant A/S
10.9. Ottobock SE & Co. KGaA
10.10. MED-EL Medical Electronics
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth trajectory for the AI in Assistive Technology Market during 2026-2031?
The AI in assistive technology market is anticipated to experience steady growth throughout the 2026-2031 forecast period. This expansion is driven by the increasing integration of AI into next-generation assistive tools, rising global awareness, and evolving accessibility regulations.
Which product type segment is expected to hold a dominant share in the AI in Assistive Technology market?
Mobility aids are projected to command a significant share within the AI in assistive technology market. This prominence is attributed to the growing global aging population and the increasing prevalence of mobility impairments, with smart wheelchairs and robotic exoskeletons being key examples enhancing user independence and safety.
What specific technology segment is a major contributor to the AI in Assistive Technology market?
Machine learning holds a considerable share in the AI in assistive technology market. Its importance stems from its ability to enable systems to adapt to individual user needs through pattern recognition, predictive analytics, and personalized responses, thereby enhancing the efficacy of assistive technologies.
Which geographical region is demonstrating strong growth in the AI in Assistive Technology Market?
The Asia-Pacific region is experiencing robust growth in the AI in assistive technology market. This surge is propelled by increasing awareness of disability inclusion, rapid technological advancements, and supportive government initiatives in countries like China and India, alongside expanding mobile and internet penetration.
What are the primary trends influencing the future direction of the AI in Assistive Technology Market?
Top trends shaping this market include the integration of AI with wearable and IoT devices, such as smart glasses for the visually impaired and AI-powered exoskeletons, to enhance user navigation and interaction. Furthermore, advancements in natural language processing are identified as a significant driver.
Which end-user setting represents a significant market share in the AI in Assistive Technology market?
Home Care Settings constitute a significant share of the AI in assistive technology market as primary end-users. AI-powered solutions in this segment are crucial for improving the independence, communication, and overall quality of life for individuals with disabilities in their daily lives.
Cite this report
Knowledge Sourcing Intelligence. (Jul 2026). AI in Assistive Technology Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ai-in-assistive-technology-market