Brazil Cosmetic Surgery Market - Strategic Insights and Forecasts (2026-2031)
Brazil Cosmetic Surgery Market Size, Share, Forecasts and Trends Analysis By Type (Surgical Procedures, Non-Surgical Procedures), By Application (Face and Head, Breast, Body and Extremities, Others), By End User (Private Aesthetic Clinics, Hospitals and Surgical Centers, Ambulatory Surgical Centers, Medical Tourism Providers), and Region
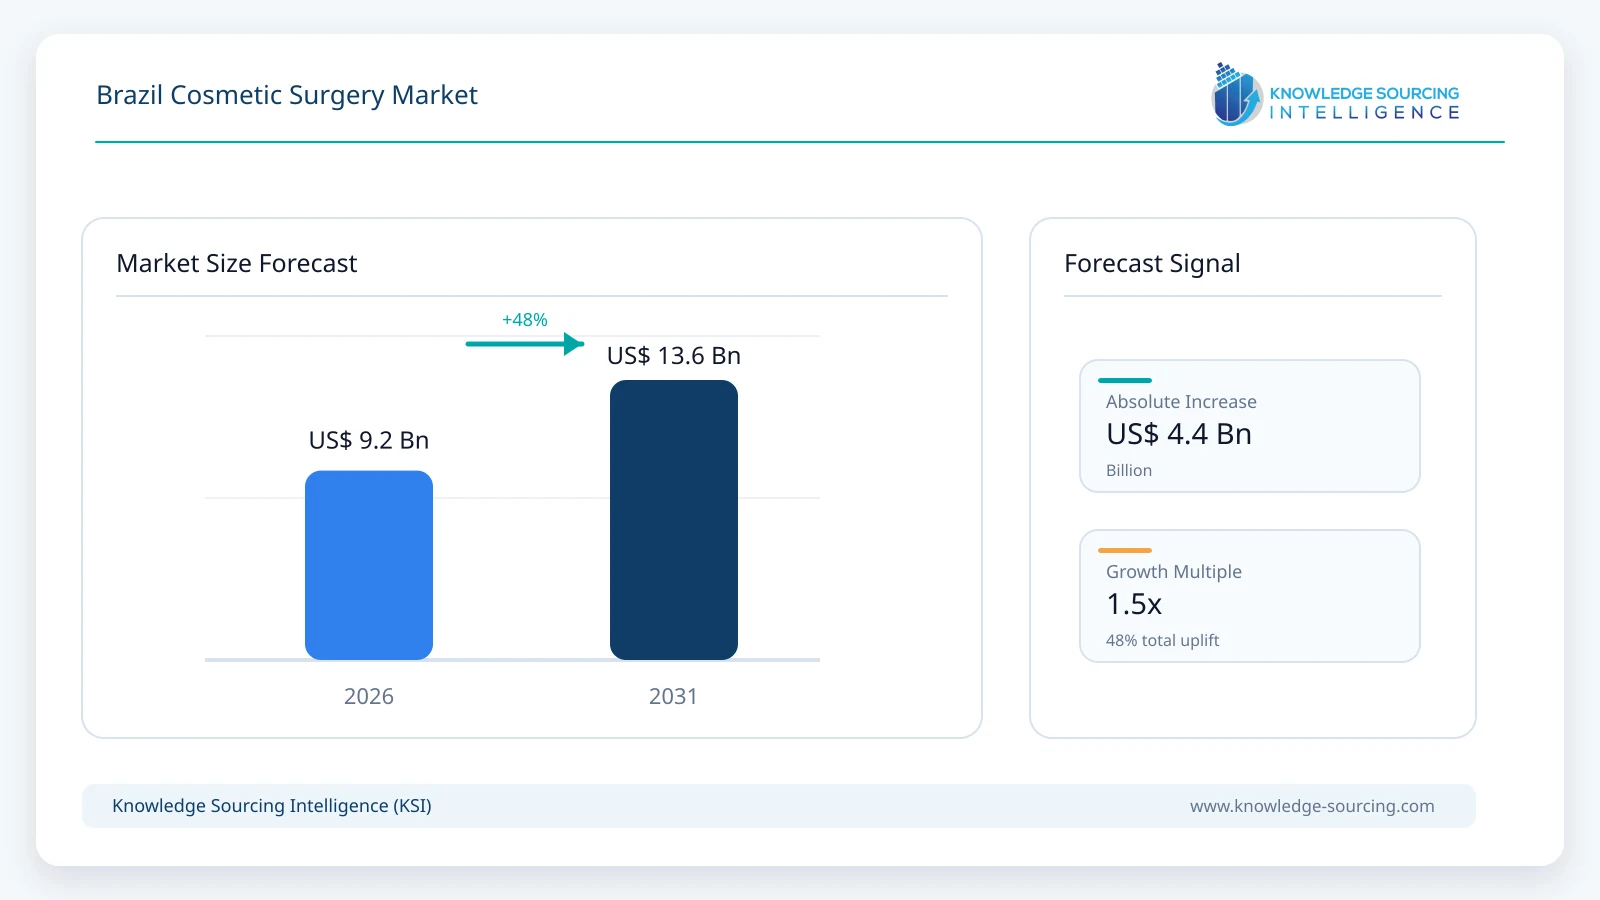
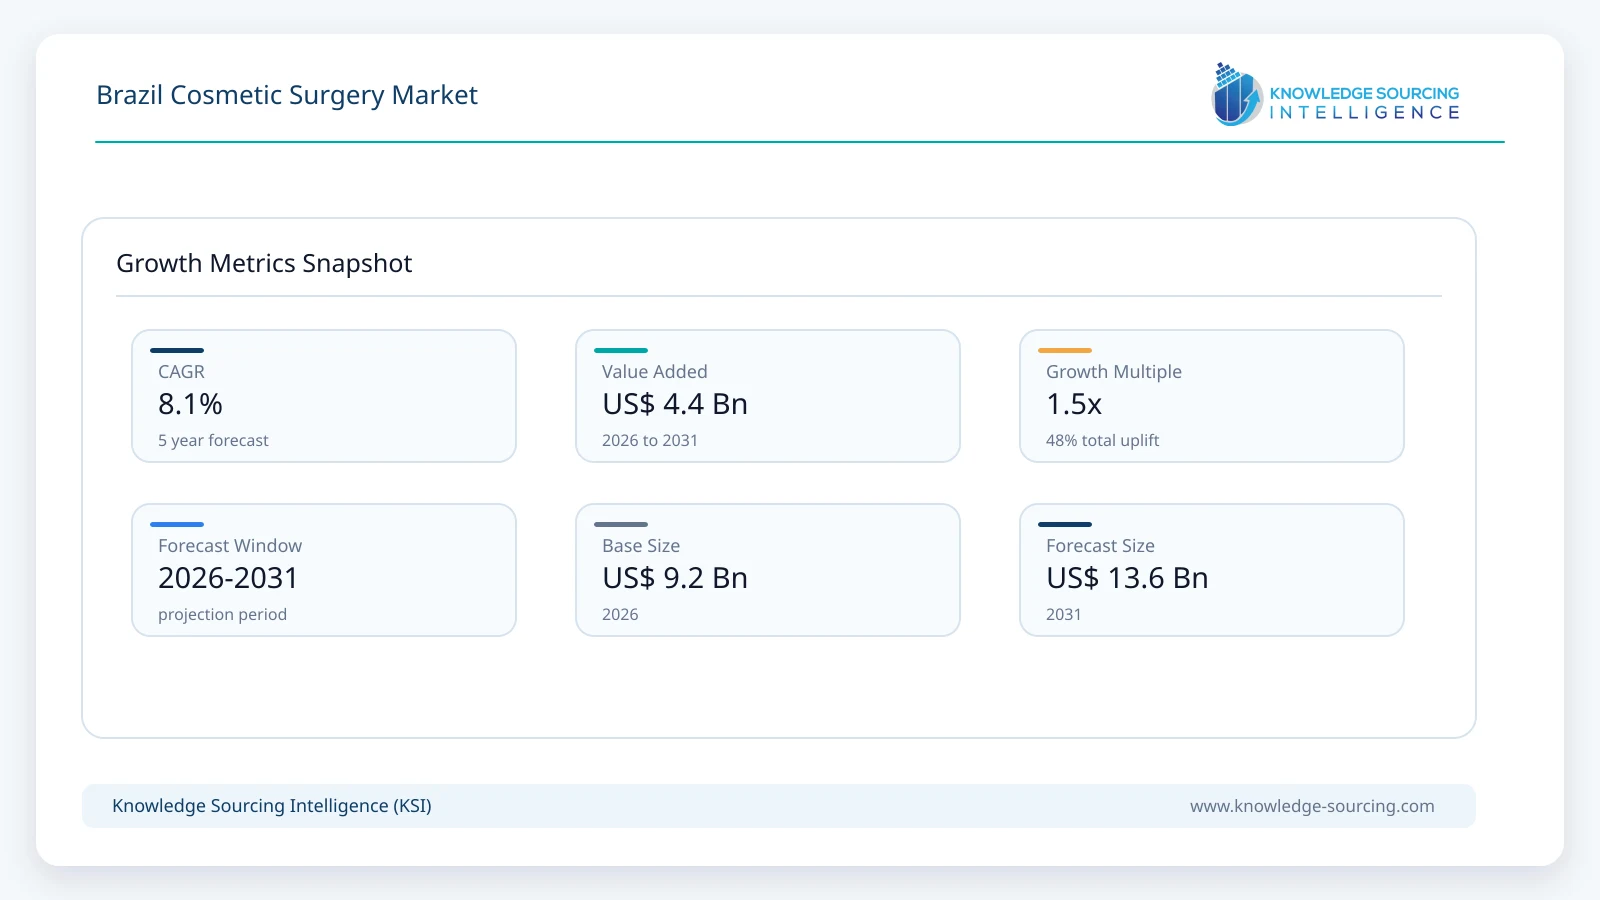
The Brazil Cosmetic Surgery market is forecast to grow at a CAGR of 8.12%, reaching USD 13.60 billion in 2031 from USD 9.20 billion in 2026.
Highlights:
1
Surgical procedures account for approximately 78% of Brazil cosmetic surgery market value in 2026.
2
Non-surgical procedures are projected to grow at approximately 10.5% annually between 2026 and 2031.
3
Body and extremity procedures generate approximately USD 3.3 billion of market value in 2026.
4
Southeast Brazil accounts for approximately 47% of national cosmetic surgery market value in 2026.
5
Brazil recorded approximately 3.12 million aesthetic procedures in 2024, including 2.35 million surgical procedures.
6
Patient safety, physician credentials and Anvisa-authorized products remain important market-quality factors.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Overview
Cosmetic surgery in this report includes elective aesthetic surgical procedures such as liposuction, abdominoplasty, breast augmentation, mastopexy, rhinoplasty, blepharoplasty, facelifts, buttock augmentation and related body-contouring procedures, together with medically delivered non-surgical aesthetics such as botulinum toxin, dermal fillers, collagen biostimulators and selected energy-based treatments. The market is measured as procedure revenue rather than the value of implants, injectables or aesthetic equipment sold separately. This avoids double counting with the cosmetic surgery products, injectable aesthetics and energy-based device markets.
Brazil's procedural intensity is unusually high. ISAPS estimated 2.35 million aesthetic surgical procedures in 2024 and identified Brazil as the world leader in surgical procedure volume. The country also has a large specialist base: the Sociedade Brasileira de Cirurgia Plastica states that it represents around 6,700 plastic surgeons across its national and regional structure. This combination creates both high capacity and strong competition, especially in Sao Paulo, Rio de Janeiro, Belo Horizonte, Brasilia and southern metropolitan centers. Large hospital groups provide operating-room infrastructure and complex perioperative support, while specialist clinics compete on surgeon reputation, patient experience, financing and procedure specialization.
Market Trends
Non-Surgical Aesthetics Are Increasing Procedure Frequency
Brazil's aesthetic-procedure mix is broadening beyond surgery. ISAPS recorded 769,245 non-surgical procedures performed by plastic surgeons in Brazil in 2024, including more than 351,000 botulinum toxin procedures and 176,000 hyaluronic-acid filler procedures. Product innovation supports this expansion. Galderma reported the Brazilian launch of Restylane SHAYPE in 2024, adding another injectable option for facial contouring. Non-surgical procedures generally have lower prices per treatment than surgery but shorter treatment intervals, supporting recurring procedure volumes across injectables, skin treatments and minimally invasive contouring.
Safety, Credentialing and Product Traceability Are Becoming More Visible to Patients
Patient-safety requirements are becoming more visible across the market. Anvisa's aesthetic-procedure guidance emphasizes authorized facilities, approved products and qualified professionals, while the Sociedade Brasileira de Cirurgia Plastica maintains a public surgeon-verification platform. Product scrutiny is also active: in July 2025 Anvisa suspended certain breast and gluteal implants after manufacturing inspections identified major and critical deficiencies. Surgeon credentials, hospital operating privileges and traceable regulated products therefore remain important elements of procedure selection and market quality.
Market Drivers
High Procedure Penetration and a Large Specialist Base Sustain Structural Demand
Brazil's market is supported by both demand familiarity and service capacity. ISAPS reported that Brazil performed about 2.35 million aesthetic surgical procedures in 2024. Liposuction alone accounted for roughly 290,000 procedures, while breast augmentation exceeded 232,000, eyelid surgery 231,000 and abdominoplasty 192,000. These volumes create established referral networks, operating protocols, anesthetic capacity and post-operative care ecosystems that are difficult for emerging markets to replicate quickly. The SBCP's specialist base also supports regional availability outside the largest metropolitan areas, although premium surgery remains concentrated in urban private-care centers.
Improving Household Income and Private-Pay Financing Support Elective Spending
Cosmetic procedures are primarily discretionary and often self-funded, making disposable income and financing access important demand variables. Brazil's Ministry of Development reported that average real monthly income from all sources reached a record BRL 3,367 in 2025, 5.4% above 2024. The improvement does not make high-cost surgery universally affordable, but it broadens the addressable middle-income cohort for installment-based procedures, injectables and staged treatments. Clinics increasingly compete through packaged pricing, financing partners and combinations of surgical and non-surgical procedures that distribute expenditure across time.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Restraint
Safety Risk, Regulatory Scrutiny and Uneven Provider Quality Can Limit Demand
Cosmetic surgery is elective but remains invasive medical care, and adverse outcomes can quickly affect demand. Brazil combines internationally recognized surgical expertise with a fragmented provider base that ranges from major hospitals to small practices. The SBCP recommends specialist-trained surgeons and accredited facilities, while Anvisa regulates medical devices, implants and products used in invasive aesthetic procedures. Enforcement actions, product recalls or highly publicized complications can reduce patient confidence and increase compliance costs. Higher-quality providers absorb these costs through credentialing, hospital infrastructure, product traceability and follow-up care, but low-cost operators may face greater pressure as consumers become more attentive to safety and qualifications.
Surgical procedures remain the largest revenue segment because of their higher average ticket value and Brazil's exceptionally high procedure volume. Liposuction, breast procedures, abdominoplasty, eyelid surgery and rhinoplasty form the core of the category, with operating-room, anesthesia and follow-up requirements raising expenditure per procedure. The segment is projected to remain dominant through 2031, while non-surgical procedures expand more rapidly because injectables and energy-based treatments support repeat visits and shorter recovery periods.
By Application - Body and Extremities
Body and extremity procedures represent the largest application group. ISAPS estimated 862,152 such procedures in Brazil in 2024. Liposuction was the leading individual procedure with 289,766 cases, followed by abdominoplasty and buttock augmentation. The category is supported by Brazil's established body-contouring practice base and demand for combined procedures such as lipoabdominoplasty and post-weight-loss contouring. Face and head procedures remain another major category through blepharoplasty, facelifts and rhinoplasty, while breast procedures continue to support implant and mastopexy demand.
By End User - Private Aesthetic Clinics and Specialist Surgical Centers
Private aesthetic clinics and specialist surgical centers account for the largest portion of elective procedure revenue. Their role reflects the concentration of specialist surgeons, dedicated consultation capacity and the ability to provide surgery alongside injectables, laser treatments and post-operative care. Master Health states that more than 185,000 surgeries have been performed over more than 30 years, while Clinica Leger operates across Sao Paulo, Rio de Janeiro and Porto Alegre with surgical and technology-based aesthetic services. Large hospitals remain important for higher-complexity procedures because they provide operating rooms, intensive-care support and multidisciplinary care.
By Geography - Southeast Brazil
Southeast Brazil is the largest regional market, led by Sao Paulo and Rio de Janeiro. The region combines the country's highest concentration of specialist physicians, major private hospitals, higher-income consumers and established aesthetic clinics. Sao Paulo hosts large private healthcare systems, specialist surgery centers and national referral practices, while Rio de Janeiro has a long-standing aesthetic-surgery base. Southern Brazil is another important market, particularly Porto Alegre and Curitiba, while Brasilia and other state capitals support regional demand. Growth outside the Southeast is supported by rising specialist availability and private healthcare capacity.
Competitive Environment
The market is highly fragmented and reputation-led. No single provider controls a large national share because patients frequently select an individual surgeon rather than a corporate brand. Competition therefore occurs across three overlapping provider models: large hospital networks that supply surgical infrastructure and multidisciplinary care; dedicated plastic-surgery clinics with standardized consultation and financing; and surgeon-led premium practices that compete on individual reputation, technique and international patient service. Rede D'Or, Hospital Sirio-Libanes and Hospital Israelita Albert Einstein represent the hospital-based end of the spectrum, while Master Health and Clinica Leger demonstrate dedicated clinic models. Smaller surgeon-led practices remain numerous and collectively represent a substantial share of procedures.
Competition increasingly reflects documented credentials, patient safety, digital consultation, treatment planning and continuity of care. Larger clinics have more capacity to standardize scheduling, financing and follow-up, while specialist practices compete through procedure expertise and hospital affiliations. Supplier relationships also matter because injectables, implants and energy-based devices require regulated procurement and practitioner training. Growth in non-surgical aesthetics is also broadening the treatment mix offered alongside surgical procedures.
Recent Developments
2026: Anvisa updated public guidance for safe aesthetic procedures, emphasizing authorized facilities, approved products and qualified professionals.
August 2025: Anvisa highlighted a scientific study on the post-market safety and performance of breast implants using technovigilance data, reinforcing the continuous surveillance of implant-based reconstructive and aesthetic procedures.
July 2025: Anvisa suspended commercialization and use of specified breast and gluteal implants after an inspection identified 47 major or critical manufacturing irregularities.
2025: Brazil's Demografia Medica 2025 study highlighted the concentration of medical specialists in private healthcare, relevant to elective aesthetic service capacity.
2024-2025: Galderma expanded its injectable aesthetics portfolio in Brazil, including the launch of Restylane SHAYPE, supporting growth in facial contouring and repeat non-surgical treatments.