
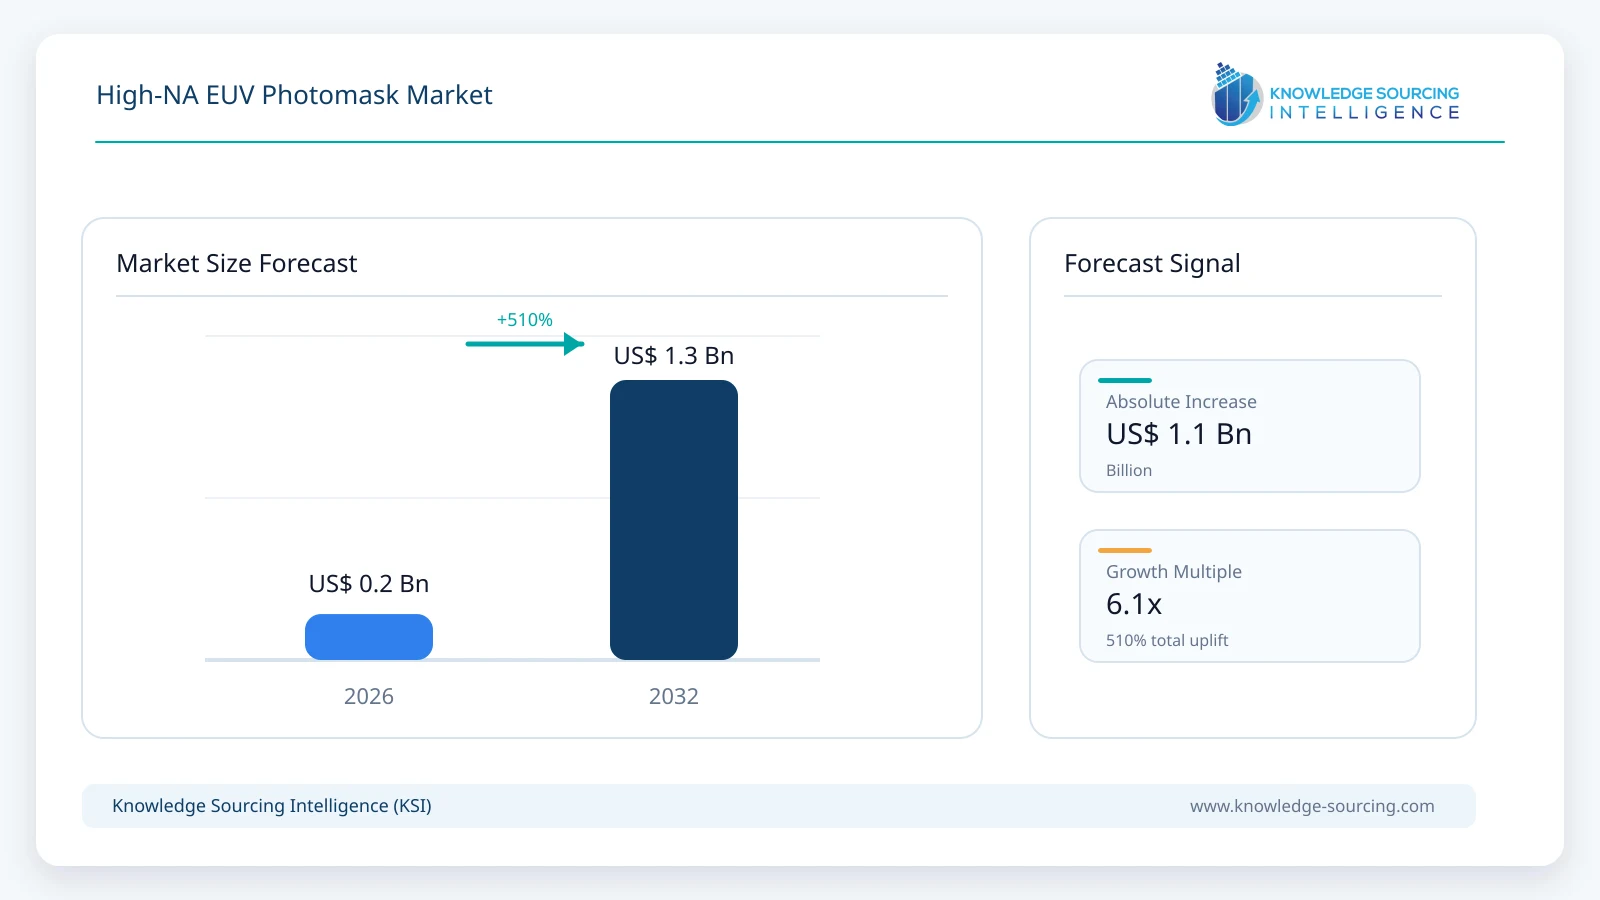
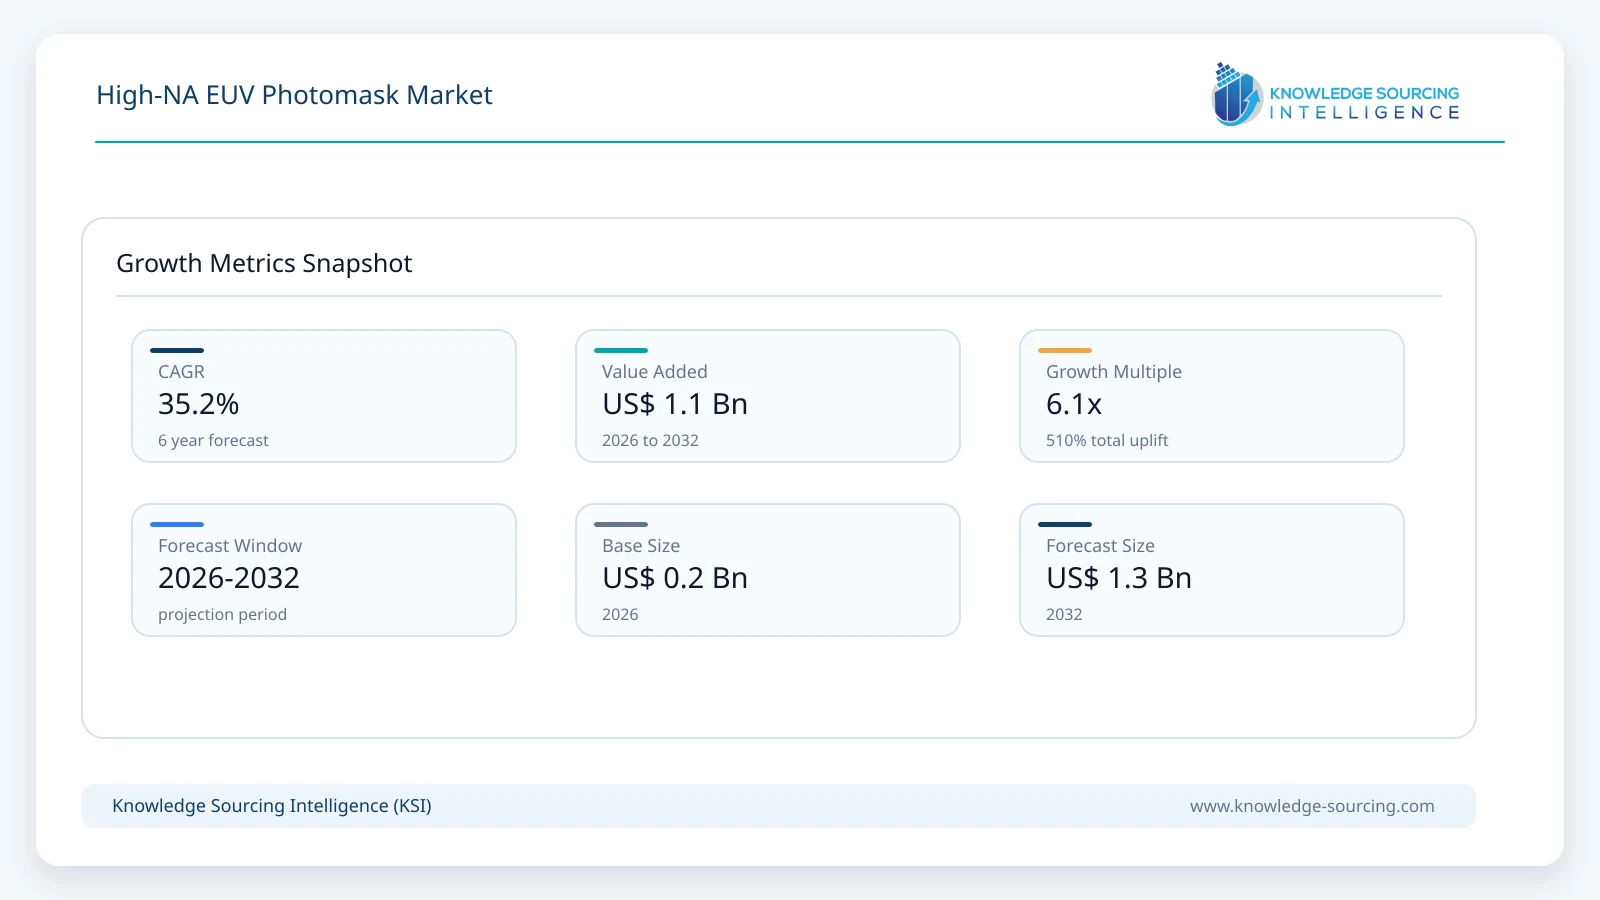
The High-NA EUV Photomask Market is estimated at USD 0.21 billion in 2026 and is projected to reach USD 1.28 billion by 2032, representing a CAGR of 35.2% over 2026-2032.
Highlights:
- 1Current 6-inch EUV masks remain the commercial starting point for High-NA production and qualification.
- 2Anamorphic imaging increases sensitivity to mask three-dimensional effects, pattern placement and absorber design.
- 3Low-refractive-index absorber architectures are gaining importance as fabs pursue wider High-NA process windows.
- 4Curvilinear masks and computational mask correction increase writing, inspection and data-preparation complexity.
- 5The planned transition toward larger-format masks could materially expand mask value and infrastructure requirements after 2030.
A High-NA EUV photomask performs the same basic function as a conventional EUV reticle: reflective multilayer regions return 13.5 nanometer EUV radiation while patterned absorber regions control where light reaches the wafer. The challenge is that High-NA optics collect a wider angular spectrum and operate with a more constrained depth-of-focus budget. The result is stronger interaction between the scanner, mask stack, absorber material and layout geometry. Small deviations in absorber sidewall profile, multilayer phase, critical dimension or pattern placement can therefore create larger wafer-level effects than in earlier lithography generations.
High-NA systems use anamorphic optics to avoid the extreme shadowing penalties that would result from a simple increase in conventional mask magnification. The first production route retains today's 6-inch reticle ecosystem, but the exposure field is effectively reduced in one direction. Large dies can be addressed through field stitching or layout floor-planning. This allows fabs to use existing mask-handling infrastructure while High-NA is introduced, but it also increases the value of precise mask placement, stitching-aware correction and reticle qualification. ASML and Intel have demonstrated that this approach is production-capable, while the industry simultaneously develops larger mask formats for a later productivity step.
Mask materials are also evolving. Conventional EUV masks use a molybdenum/silicon reflective multilayer and a tantalum-based absorber. At 0.55NA, mask three-dimensional effects become harder to correct using illumination and optical proximity correction alone. Research therefore increasingly focuses on low-refractive-index and alternative absorber stacks that can reduce shadowing, improve image contrast and widen depth of focus. Imec reported 2026 High-NA experiments comparing low-n masks with standard tantalum-based designs, while its broader imaging roadmap identifies mask tonality, alternative absorbers, sub-resolution structures and mask-scanner co-optimization as practical enablers for future single-exposure logic patterning.
Market Drivers
High-NA production creates a new recurring mask-generation cycle
Each new leading-edge logic or memory node requires a new set of critical-layer masks, and High-NA introduces an additional qualification cycle for layers that migrate from 0.33NA EUV or multi-patterning. Intel's production use provides the first commercial proof point, while Samsung's 2028 DRAM plan and TSMC's 2030 manufacturing plan expand the customer base over the forecast period. As High-NA moves from a small number of development layers into more production layers, mask demand grows not only through greater unit count but also through higher value per reticle because data preparation, mask writing, inspection and qualification become more demanding.
Single-exposure patterning can replace several lower-NA masks on selected layers
High-NA EUV is economically attractive when its higher resolution simplifies a process flow that would otherwise require multiple exposures, masks and etch steps. Imec has shown examples where future logic or DRAM structures that need several 0.33NA EUV masks can be patterned with a single High-NA exposure. This does not automatically increase total mask count for every device, but it raises the importance and value of the High-NA mask that replaces a more complex multi-patterning sequence. Photomask suppliers therefore compete on defectivity, imaging fidelity and turnaround time rather than simply on reticle volume.
Curvilinear mask layouts raise photomask data and manufacturing intensity
Inverse lithography and curvilinear optical proximity correction allow mask shapes to compensate more effectively for advanced imaging constraints, but the resulting geometries are harder to fracture, write, measure and inspect. High-NA accelerates this transition because process windows are narrower and mask-induced imaging effects are stronger. Multi-beam electron-beam writers, contour-based metrology and computational mask models become more valuable as pattern complexity increases. The commercial consequence is a shift toward premium photomask services that combine physical fabrication with sophisticated data preparation and qualification.
Large-format mask development opens a second infrastructure transition
The 6-inch mask format will support the first wave of High-NA production, but the industry is already preparing for larger formats. In September 2026, TSMC and ASML announced an initiative targeting a 12-inch photomask pilot line by 2031, while Samsung joined the program and Intel continued to support a 6-by-12-inch evolution. Larger masks can reduce stitching constraints and improve scanner productivity, but they require new blanks, writing, inspection, handling, cleaning and logistics infrastructure. This creates a second growth phase for the photomask ecosystem beyond the first 6-inch High-NA qualification cycle.
Restraints and Adoption Challenges
The market remains constrained by the small number of fabs that can justify High-NA lithography, the high cost of mask infrastructure and the long qualification cycle for any change in absorber or multilayer architecture. A High-NA mask must meet stringent defectivity, critical-dimension, placement and phase requirements while remaining compatible with pellicles, cleaning processes, inspection systems and scanner handling. Alternative absorber materials can improve imaging but require new etch, repair and metrology process windows. The 6-inch format also imposes half-field limitations that may require stitching for large designs. Finally, leading semiconductor manufacturers retain substantial captive mask capability, limiting the portion of demand available to merchant suppliers even as total High-NA mask value expands.
High-NA EUV Photomask Market Technology and Product Analysis
Standard 6-inch High-NA EUV photomasks are the principal commercial platform through the first half of the forecast because they allow fabs to introduce 0.55NA lithography without replacing the entire reticle infrastructure at once. The next technology step is not simply a larger mask. Suppliers are also improving absorber stacks, curvilinear pattern fidelity, mask process correction and inspection readiness. Low-n and attenuated phase-shift approaches are especially important because they can reduce mask three-dimensional effects and improve image contrast at the wafer. Large-format photomasks are expected to remain in pilot and infrastructure-development phases through most of the forecast, with their strongest commercial effect beginning around 2031-2032.
Photomask Platform | Commercial Position | Technical Direction | Primary High-NA Role |
6-inch standard High-NA EUV masks | Production / qualification | Anamorphic imaging with existing reticle ecosystem | Initial High-NA logic and memory insertion |
Low-n / alternative-absorber masks | Advanced qualification | Reduced mask 3D effects and improved imaging contrast | Future logic metal and critical DRAM layers |
Curvilinear High-NA masks | Early production enablement | Contour-based OPC and inverse lithography | Process-window and stochastic optimization |
Large-format High-NA masks | Pre-commercial / ecosystem build | Reduced stitching and improved productivity | Post-2030 High-NA scaling |
Market and Technology Indicators
Indicator | Latest Development | Market Implication |
Production High-NA use | Intel and ASML reported more than one million wafers processed across High-NA certification, R&D and selected production activity. | Moves High-NA masks from research-only demand into recurring production qualification. |
DRAM adoption | Samsung plans High-NA EUV introduction for future DRAM high-volume manufacturing in 2028. | Adds a major memory demand pool beyond logic and foundry applications. |
Foundry roadmap | TSMC expects High-NA EUV high-volume manufacturing from 2030. | Creates a second large commercial adoption wave late in the forecast. |
Large-format initiative | ASML and TSMC target a 12-inch mask pilot line by 2031. | Expands long-term photomask value and forces new blank, writing, inspection and handling infrastructure. |
Merchant-mask commercialization | DNP has completed High-NA criteria evaluation and is advancing EUV mask mass-production capability. | Supports a broader external supply base beyond captive mask shops. |
Regional Opportunity
Asia Pacific
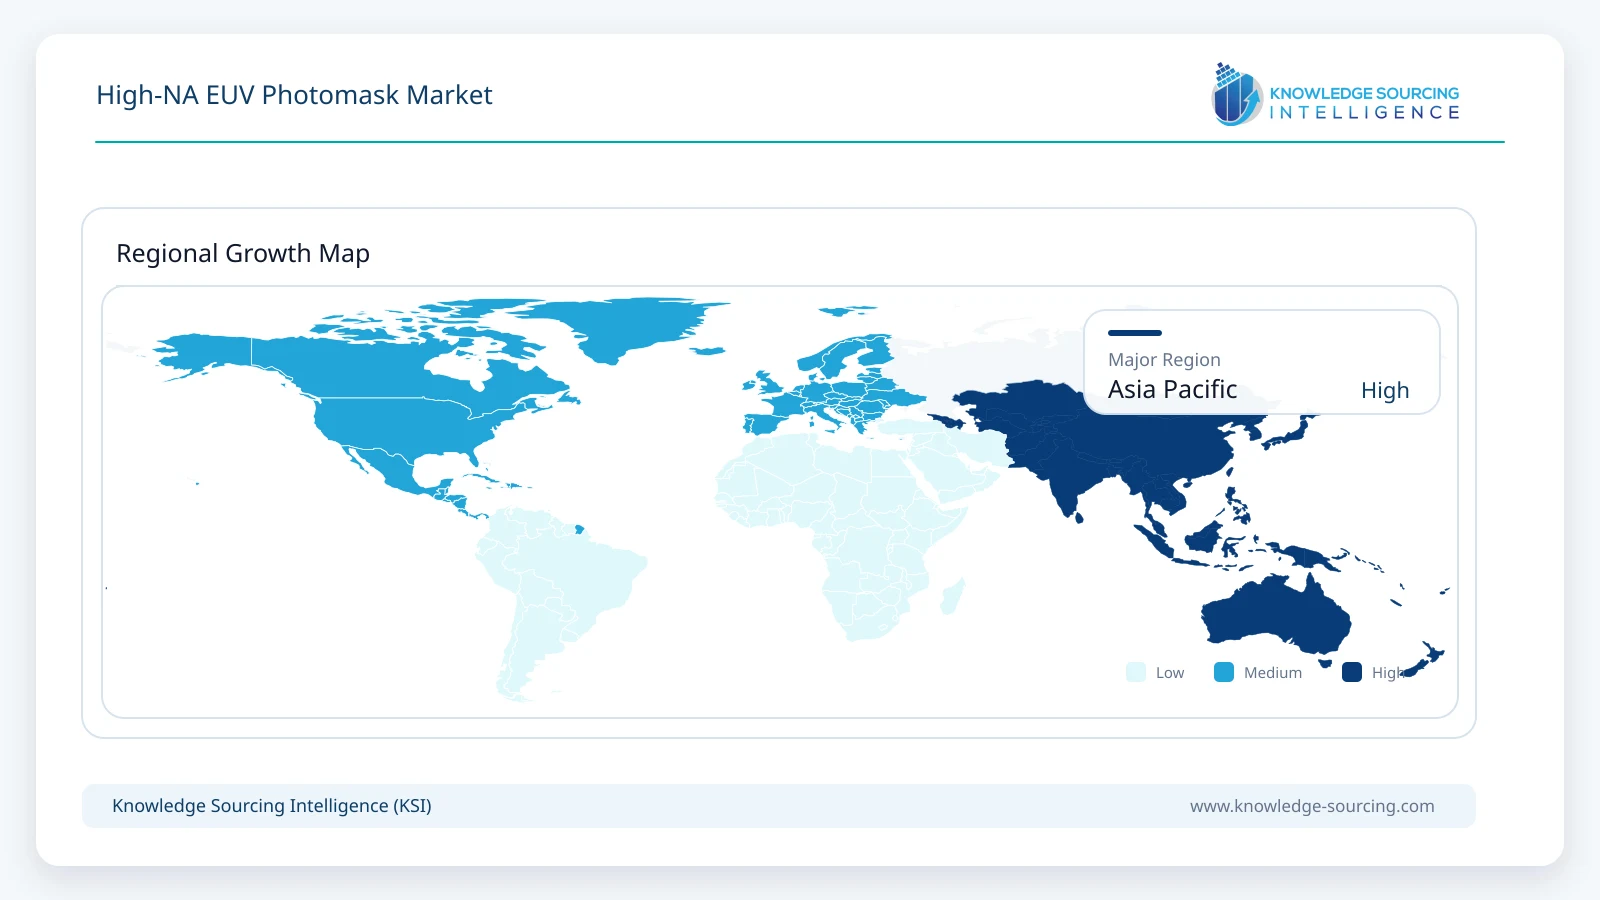
Asia Pacific is the largest long-term commercial opportunity for High-NA EUV photomasks because the region concentrates advanced foundry, memory, mask-material and merchant-photomask capabilities. Taiwan becomes increasingly important as TSMC prepares High-NA EUV for high-volume manufacturing from 2030 and participates directly in the large-format mask initiative with ASML. South Korea adds a major memory adoption path through Samsung's planned 2028 High-NA DRAM introduction and its participation in the 12-inch mask ecosystem. Japan contributes disproportionately through photomask manufacturing, mask blanks, electron-beam writing and materials infrastructure, led by companies such as DNP, Toppan Photomask, AGC, HOYA and NuFlare.
Japan is particularly important because High-NA adoption raises the value of each upstream mask component and process step. DNP has completed basic High-NA photomask evaluation, supplies evaluation masks to ecosystem partners and is preparing EUV photomask mass production for 2nm-class devices. AGC has been developing mask blanks for 0.55NA generations, while Japanese equipment suppliers participate in the mask-writing and inspection chain. These capabilities create a dense regional ecosystem that can support both merchant and captive mask production as advanced-node demand expands.
North America remains strategically important because Intel is the earliest production user of High-NA EUV and has developed stitching-aware design and manufacturing methods for the current 6-inch format. The United States also contains major semiconductor design companies that influence foundry mask requirements. Europe has an outsized role through ASML and imec: ASML defines scanner-mask interfaces, while imec provides a shared development environment for absorber, imaging, metrology and process-co-optimization. The commercial photomask revenue pool, however, is expected to become increasingly Asia-centered as TSMC and Samsung move High-NA into larger production volumes.
Competitive Landscape
The High-NA EUV photomask market combines merchant mask manufacturers, captive mask shops, mask-blank suppliers and specialized lithography ecosystem companies. DNP is one of the clearest merchant suppliers moving directly toward High-NA commercialization, having completed criteria evaluation for High-NA photomasks and begun sample supply to development organizations, equipment manufacturers and material suppliers. Toppan Photomask and Photronics also participate in advanced photomask manufacturing and are positioned to compete as external demand broadens. Captive operations at TSMC, Samsung and Intel remain important because leading-edge EUV mask sets are frequently manufactured or tightly controlled in-house.
Upstream mask-blank suppliers such as AGC and HOYA influence competitive performance through substrate flatness, multilayer uniformity, defect control and compatibility with next-generation absorber stacks. NuFlare contributes multi-beam mask-writing capability, while KLA and Lasertec support inspection, metrology and defect review. These companies are not all direct photomask-revenue competitors, but they determine how quickly new mask architectures can be qualified. Competitive advantage for the finished-mask supplier therefore depends on ecosystem integration as much as on writing resolution alone.
High-NA competition will increasingly center on defect-free multilayer control, pattern-placement accuracy, curvilinear writing throughput, low-n absorber process maturity, repairability and cycle time. Suppliers able to support the current 6-inch format while preparing for large-format masks are best positioned to bridge near-term production with the industry's post-2030 productivity roadmap.
Major companies and ecosystem participants covered: Dai Nippon Printing (DNP), Toppan Photomask, Photronics, TSMC, Samsung Electronics, Intel Foundry, AGC, HOYA, NuFlare Technology, Lasertec, KLA, ASML, imec, Applied Materials and Lam Research.
Recent Developments
September 2026: TSMC and ASML launched an industry initiative targeting a 12-inch High-NA photomask pilot line by 2031 and production-system readiness by 2033.
September 2026: Samsung joined the large-format photomask initiative and announced planned High-NA EUV introduction for future DRAM high-volume manufacturing in 2028.
September 2026: Intel Foundry and ASML reported High-NA production progress using current 6-inch masks, including stitching capability for larger layouts.
March 2026: imec received an ASML EXE:5200 High-NA EUV system in Leuven to accelerate joint mask, materials, metrology and process development.
February 2026: DNP invested in Rapidus and reiterated plans to accelerate EUV photomask development and mass-production capability for 2nm and subsequent generations.
High-NA EUV Photomask Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | 0.21 billion |
| Total Market Size in 2032 | 1.28 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 35.2% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Photomask Architecture, Mask Technology, Semiconductor Application, Mask Manufacturing Function, Geography |
| Companies |
|
Market Segmentation
By Photomask Architecture
Standard 6-inch High-NA EUV Masks
Low-n and Alternative-Absorber Masks
Curvilinear High-NA Masks
Large-Format High-NA Masks
By Mask Technology
Conventional Ta-Based Absorber
Low-n Absorber Materials
Attenuated Phase-Shift and Alternative Architectures
Multilayer and Capping-Layer Optimization
Pellicle-Compatible High-NA Masks
By Semiconductor Application
Leading-Edge Logic
Foundry Manufacturing
DRAM and Advanced Memory
High-Performance Computing and AI Process Nodes
R&D and Process Qualification
By Mask Manufacturing Function
Data Preparation and Mask Process Correction
Multi-Beam Mask Writing
Inspection and Metrology
Defect Repair and Cleaning
Final Qualification and Pellicle Integration
By Geography
Asia Pacific
Taiwan
South Korea
Japan
China
North America
Europe
Rest of World
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market Opportunity and Key Findings
1.2. High-NA EUV Adoption Outlook
1.3. Photomask Commercialization Path
2. MARKET OVERVIEW
2.1. High-NA EUV Mask Architecture
2.2. Anamorphic Imaging and Half-Field Exposure
2.3. Mask 3D Effects and Imaging Control
2.4. Curvilinear Masks and Computational Correction
2.5. Photomask Qualification and Defectivity
3. MARKET SIZE AND FORECAST, 2026-2032
3.1. Global Market Revenue
3.2. Annual Growth Analysis
3.3. High-NA Mask Demand by Production Ramp
4. MARKET BY PHOTOMASK ARCHITECTURE
4.1. Standard 6-inch High-NA EUV Masks
4.2. Low-n and Alternative-Absorber Masks
4.3. Curvilinear High-NA Masks
4.4. Large-Format High-NA Masks
5. MARKET BY MASK TECHNOLOGY
5.1. Conventional Ta-Based Absorber
5.2. Low-n Absorber Materials
5.3. Attenuated Phase-Shift and Alternative Architectures
5.4. Multilayer and Capping-Layer Optimization
5.5. Pellicle-Compatible High-NA Masks
6. MARKET BY SEMICONDUCTOR APPLICATION
6.1. Leading-Edge Logic
6.2. Foundry Manufacturing
6.3. DRAM and Advanced Memory
6.4. High-Performance Computing and AI Process Nodes
6.5. R&D and Process Qualification
7. MARKET BY MASK MANUFACTURING FUNCTION
7.1. Data Preparation and Mask Process Correction
7.2. Multi-Beam Mask Writing
7.3. Inspection and Metrology
7.4. Defect Repair and Cleaning
7.5. Final Qualification and Pellicle Integration
8. REGIONAL MARKET
8.1. Asia Pacific
8.1.1. Taiwan
8.1.2. South Korea
8.1.3. Japan
8.1.4. China
8.2. North America
8.3. Europe
8.4. Rest of World
9. MARKET DYNAMICS
9.1. Drivers
9.1.1. High-NA Production Adoption
9.1.2. Single-Exposure Patterning Economics
9.1.3. Curvilinear and Computational Mask Complexity
9.1.4. Large-Format Photomask Transition
9.2. Restraints
9.2.1. High Qualification Cost
9.2.2. Captive Mask Manufacturing
9.2.3. Mask 3D Effects and Alternative-Absorber Process Risk
9.2.4. Stitching and Field-Size Constraints
10. COMPETITIVE LANDSCAPE
10.1. Merchant and Captive Mask Structure
10.2. High-NA Mask Supplier Positioning
10.3. Mask Blank and Absorber Ecosystem
10.4. Writing, Inspection and Repair Infrastructure
10.5. Large-Format Mask Partnerships
11. COMPANY PROFILES
12. RECENT DEVELOPMENTS
13. APPENDIX
Navigate
Trusted by the world's leading organizations











