
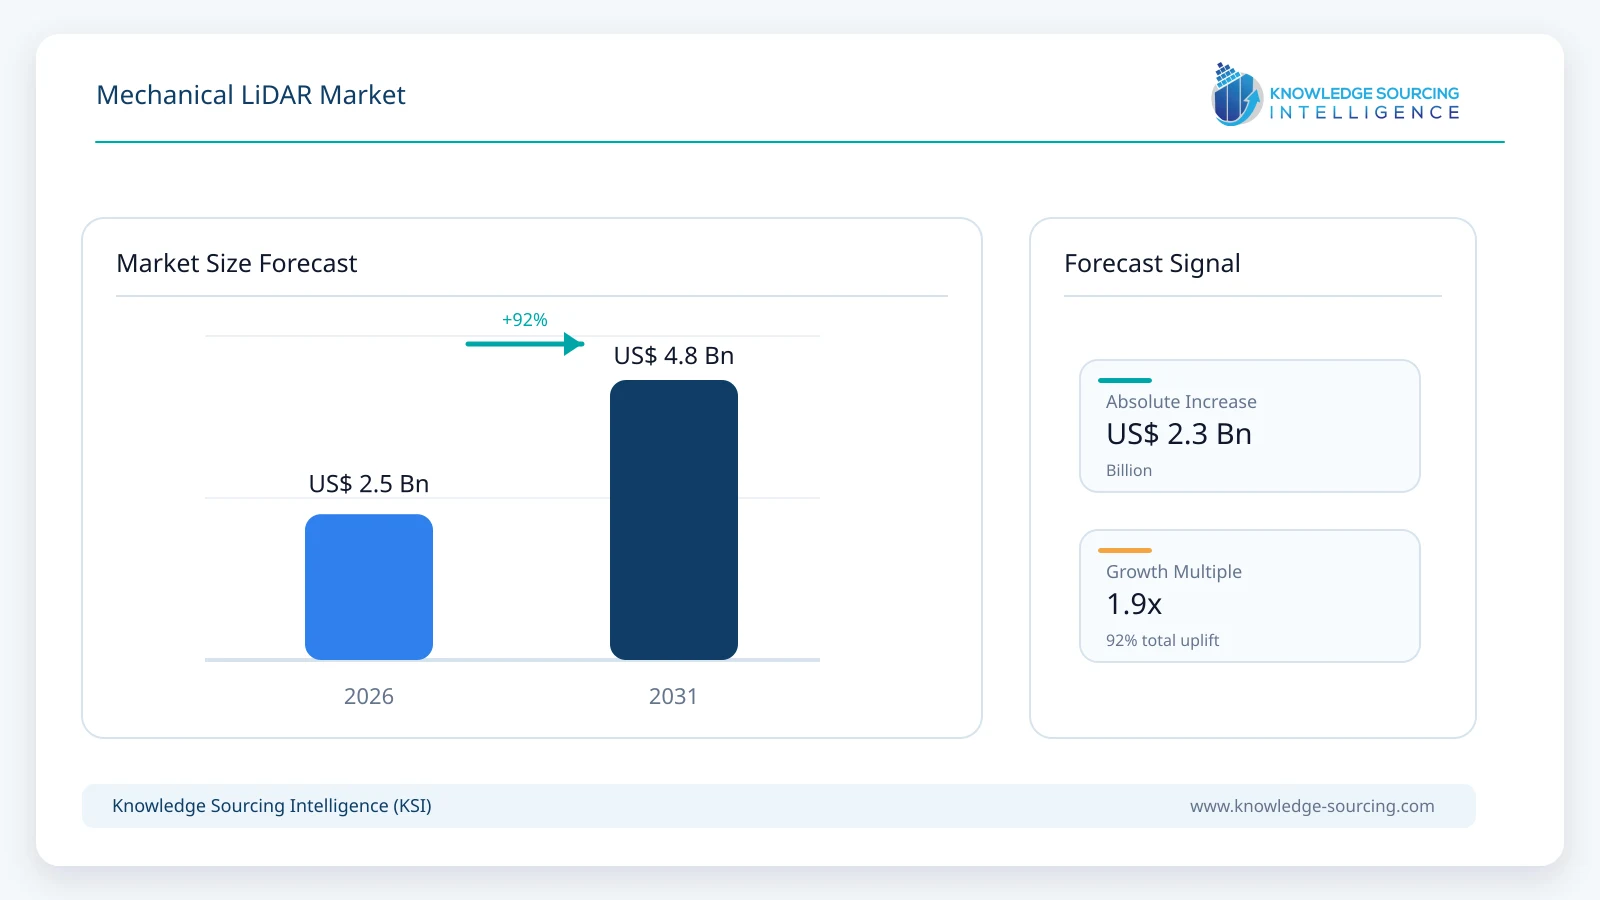
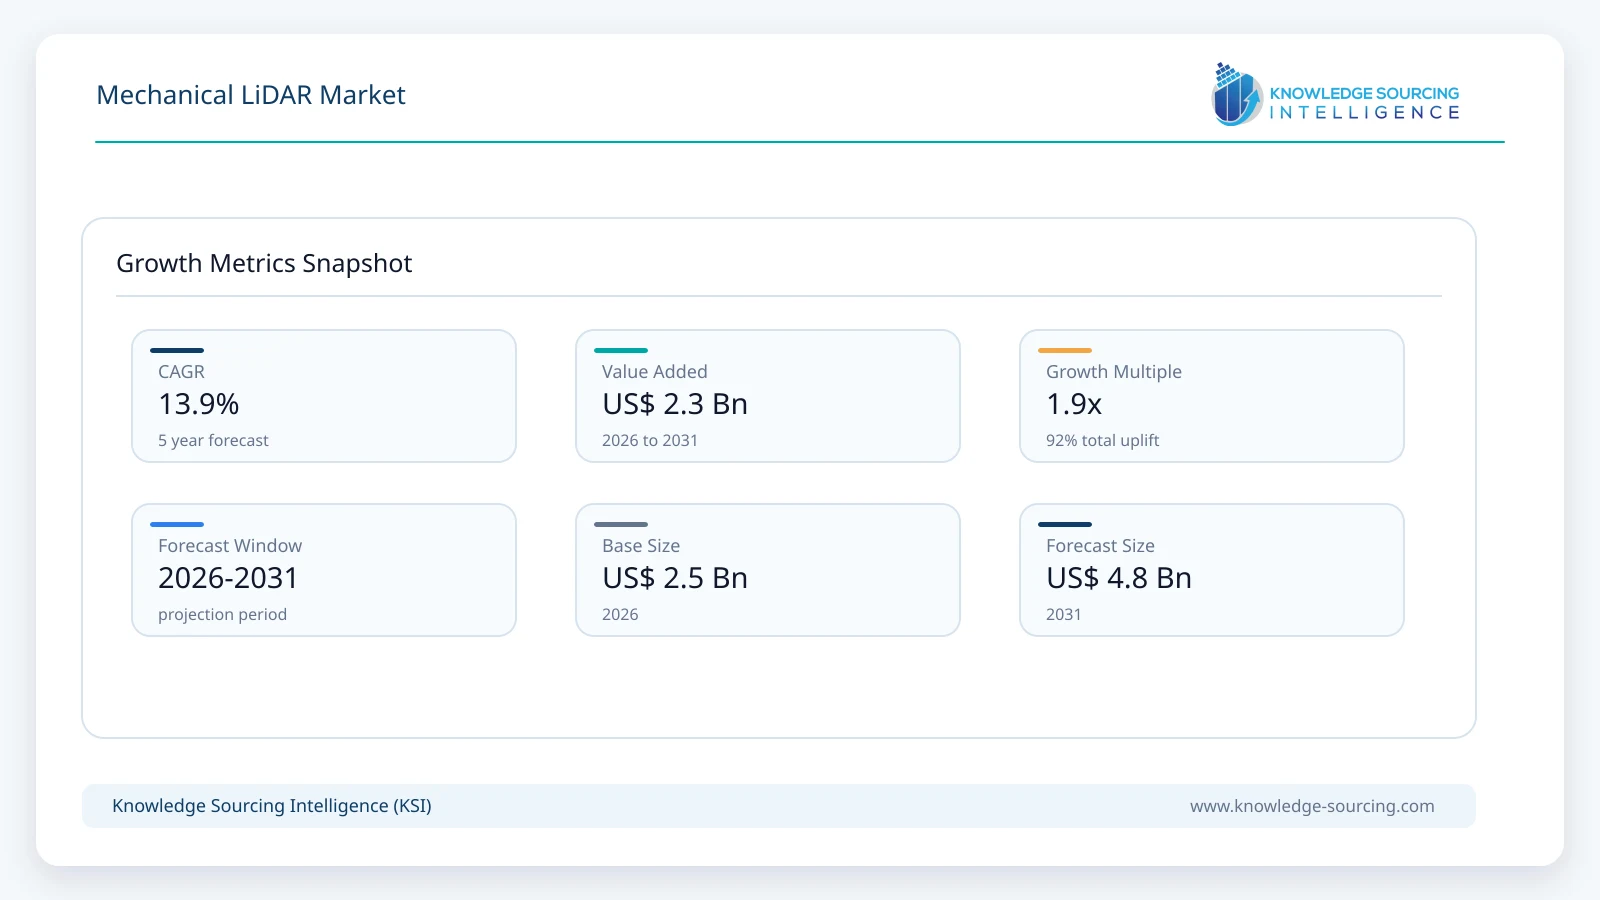
The Mechanical Lidar Market is forecast to grow at a CAGR of 13.9%, reaching USD 4.80 billion in 2031 from USD 2.50 billion in 2026.
Highlights:
- 1Mechanical LiDAR remains commercially relevant where long-range detection, dense point clouds, and wide field-of-view outweigh size constraints.
- 2Automotive ADAS, geospatial surveying, robotics, and defense continue to generate the broadest commercial demand.
- 3Manufacturing scale, automotive-grade qualification, and component cost reduction increasingly determine supplier competitiveness.
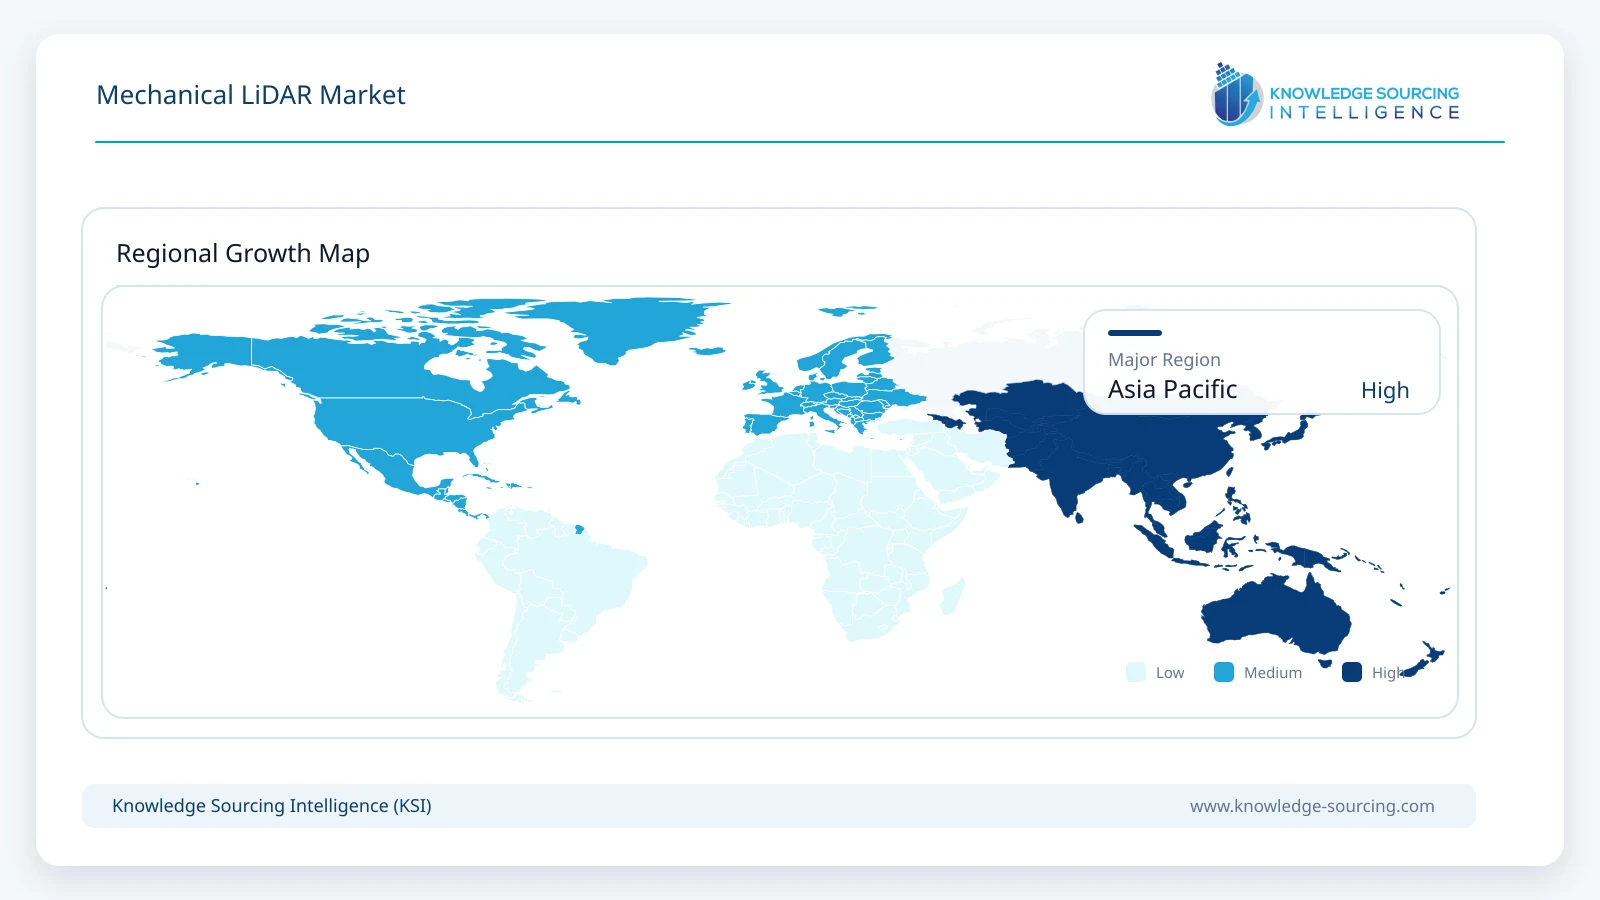
- 4Asia Pacific continues to attract production investment, while North America and Europe emphasize high-value applications and regulatory compliance.
- 5Mechanical scanning architectures retain advantages in mapping accuracy and mature deployment despite growing competition from solid-state alternatives.
Market Overview
Although solid-state architectures receive considerable investment, rotating mechanical systems remain widely deployed across geospatial mapping, autonomous vehicle development, industrial automation, mining, and security applications where scanning performance, measurement accuracy, and mature software ecosystems remain primary purchasing considerations.
Buyer priorities have shifted beyond basic detection capability. Automotive manufacturers increasingly evaluate functional safety, production scalability, cybersecurity compliance, qualification testing, and long-term supply assurance before selecting LiDAR suppliers. Industrial and infrastructure operators place greater emphasis on durability, service support, calibration stability, and compatibility with existing perception software, while surveying organizations prioritize measurement precision, repeatability, and lifecycle operating costs.
Commercial value is distributed across both hardware and software capabilities. Laser transmitters, photodetectors, rotating assemblies, controllers, and optical components collectively determine sensor performance, while perception software, calibration tools, and system integration increasingly influence purchasing decisions. Suppliers capable of delivering complete sensing platforms rather than standalone hardware are improving their competitive position across automotive and industrial procurement programs.
Mechanical LiDAR demand remains closely linked to automation investment, digital mapping initiatives, intelligent transportation infrastructure, warehouse robotics, and advanced driver assistance systems. At the same time, purchasing decisions increasingly reflect manufacturing resilience, component availability, certification capability, and supplier financial stability, particularly for customers planning multi-year deployment programs. Company disclosures also indicate continued investment in manufacturing capacity, automotive qualification, and proprietary semiconductor development to reduce production costs and improve product reliability.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Hesai annual LiDAR shipments | 1.6 million+ units (2025) | Demonstrates increasing production scale across automotive and robotics applications. |
Planned annual production capacity | 4 million units (2026) | Larger manufacturing capacity supports higher-volume automotive contracts. |
Automotive reliability testing | 60+ OEM-grade validation tests | Qualification remains a major purchasing requirement for vehicle manufacturers. |
Functional safety certifications | ISO 26262, IATF 16949, ISO/SAE 21434 | Certification capability increasingly influences supplier selection in regulated industries. |
Automotive-grade manufacturing | Automotive verification and cybersecurity processes | Compliance reduces qualification risk for long-term production programs. |
Market Drivers
Expansion of advanced driver assistance system (ADAS) deployment. Vehicle manufacturers continue to integrate LiDAR into higher-level driver assistance functions that require improved object recognition under challenging operating conditions. Purchasing decisions increasingly depend on automotive-grade validation, functional safety, cybersecurity certification, and long-term production capability rather than sensor performance alone. Suppliers are responding through dedicated semiconductor development, manufacturing automation, and expanded production capacity to support multi-year OEM contracts. Automotive qualification requirements therefore continue to strengthen demand for mature mechanical LiDAR platforms in selected vehicle programs.
Higher investment in geospatial mapping and infrastructure surveying. National mapping agencies, engineering companies, mining operators, and utility asset managers continue to require high-density three-dimensional data for digital terrain models, corridor mapping, and infrastructure inspection. Mechanical LiDAR remains commercially attractive because rotating architectures generate dense point clouds over wide scanning angles while maintaining measurement consistency across large survey areas. Buyers increasingly evaluate accuracy, calibration stability, compatibility with geographic information systems, and lifecycle maintenance costs rather than acquisition price alone, supporting demand for established surveying platforms.
Industrial automation and autonomous robotics requiring reliable environmental perception. Warehouses, ports, mining operations, logistics facilities, and industrial automation projects increasingly require dependable three-dimensional sensing for navigation, obstacle detection, localization, and operational safety. Mechanical LiDAR offers mature perception performance across demanding operating environments where lighting conditions, dust, or variable weather reduce camera effectiveness. Manufacturers are expanding software integration, perception algorithms, and industrial product portfolios to address customer demand for complete sensing solutions instead of standalone hardware. Company investment priorities increasingly reflect this broader robotics opportunity.
Manufacturing scale reducing unit production costs. Production economics have become a stronger competitive differentiator as automotive customers seek lower-cost sensors suitable for larger vehicle volumes. Companies are investing in proprietary chips, automated manufacturing, and vertically integrated production to improve yields while lowering component costs. Greater production capacity also strengthens supplier credibility during long-term procurement negotiations because automotive manufacturers increasingly evaluate supply continuity alongside technical specifications. Recent company disclosures indicate continuing investment in production expansion and dedicated LiDAR system-on-chip development.
Market Restraints and Challenges
Competition from solid-state LiDAR architectures. Mechanical LiDAR suppliers face increasing pricing pressure as solid-state alternatives improve in performance while reducing size, weight, and manufacturing complexity. Automotive customers evaluating future vehicle platforms frequently compare mechanical and solid-state technologies according to packaging efficiency, reliability, and total system cost rather than sensing performance alone. Mechanical systems therefore remain strongest in applications requiring wide field-of-view, established reliability, or very high point-cloud density, while suppliers continue investing in cost reduction and product differentiation to preserve commercial relevance.
Automotive qualification cycles extend commercialization timelines. Vehicle manufacturers typically require extensive validation before approving LiDAR sensors for production programs. Functional safety verification, electromagnetic compatibility testing, environmental durability assessment, cybersecurity compliance, and software validation can extend development schedules by several years. Company disclosures from automotive LiDAR suppliers indicate that long design cycles delay revenue recognition and increase engineering costs before production volumes are secured. Smaller manufacturers with limited financial resources may find it difficult to sustain these extended qualification periods, creating a structural barrier to market entry and reducing the number of suppliers capable of serving global automotive OEMs.
Dependence on specialized optical and semiconductor components. Mechanical LiDAR systems rely on precision lasers, photodetectors, optical assemblies, mirrors, scanning mechanisms, and application-specific integrated circuits that require stringent manufacturing tolerances. Supply disruptions affecting any of these components can delay production schedules and increase procurement costs. Several LiDAR manufacturers have identified component sourcing, supplier concentration, and inventory management as recurring operational risks in their public disclosures. In response, companies are expanding qualified supplier networks, increasing vertical integration, and investing in proprietary semiconductor development to improve supply security and reduce dependence on third-party component manufacturers.
Price pressure from large-scale procurement programs. Automotive and industrial buyers increasingly negotiate long-term supply agreements that emphasize lower unit pricing while maintaining demanding performance specifications. This creates margin pressure for suppliers that must continue investing in research, manufacturing automation, software development, and regulatory compliance. Competitive bidding has intensified as both established manufacturers and newer entrants compete for high-volume contracts. Companies capable of combining manufacturing efficiency, software integration, and reliable after-sales support are generally better positioned to maintain profitability despite declining average selling prices.
Major Segment Analysis
Automotive Application
The automotive application represents the most commercially important segment because it combines demanding technical requirements with long-term production opportunities and recurring procurement programs. Mechanical LiDAR continues to serve advanced driver assistance systems, autonomous shuttle projects, robotaxis, commercial vehicles, and selected passenger vehicle platforms where long-range detection accuracy and mature perception performance remain purchasing priorities. Vehicle manufacturers increasingly assess complete system capability, including functional safety certification, cybersecurity compliance, manufacturing scalability, and long-term supplier support before awarding production contracts.
Qualification requirements differentiate this segment from most industrial applications. Procurement decisions typically involve extensive validation, software integration, and multi-year testing before volume production begins. These longer development cycles raise entry barriers but also strengthen supplier relationships once production programs are secured. Companies including Hesai Technology, RoboSense, Ouster, and LeiShen continue to expand automotive product portfolios while investing in dedicated semiconductor platforms, automated manufacturing, and software capabilities to improve cost competitiveness and meet evolving OEM requirements. As vehicle automation expands across commercial and passenger transport, performance within this segment will remain an important indicator of broader Mechanical LiDAR market direction.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Autonomous mobility, industrial automation, defense procurement | Long automotive qualification cycles |
Europe | Automotive safety regulations, precision manufacturing, geospatial surveying | Cost pressure and regulatory compliance |
Asia Pacific | Automotive production, robotics manufacturing, electronics ecosystem | Intense pricing competition |
Middle East and Africa | Smart infrastructure, surveying, defense modernization | Limited domestic manufacturing capability |
North America
Autonomous vehicle development, warehouse automation, mining operations, and defense modernization continue to support Mechanical LiDAR demand across North America. The United States remains the region's largest commercial market because automotive manufacturers, robotics developers, technology companies, and defense contractors continue investing in perception technologies. Government-supported infrastructure modernization and digital mapping programs also sustain demand for surveying-grade LiDAR equipment. Buyers generally prioritize product reliability, software compatibility, cybersecurity, and long-term technical support over initial purchase price, creating opportunities for suppliers capable of meeting demanding qualification standards.
Europe
European demand is shaped by stringent vehicle safety requirements, advanced manufacturing capabilities, and established geospatial surveying activities. Germany, France, and the United Kingdom remain important markets because of their automotive engineering base and industrial automation investments. Surveying firms and infrastructure operators continue adopting LiDAR for transportation planning, utility inspection, and environmental monitoring. Suppliers competing in Europe must satisfy strict regulatory requirements while demonstrating high measurement accuracy, lifecycle reliability, and compliance with functional safety and cybersecurity standards. These purchasing criteria generally favor manufacturers with established engineering capabilities and proven certification experience.
Asia Pacific
Asia Pacific continues to represent the largest concentration of Mechanical LiDAR manufacturing activity owing to its extensive electronics supply chain, automotive production capacity, and expanding robotics industry. China, Japan, and South Korea host many LiDAR manufacturers as well as major automotive and industrial automation customers. Government support for intelligent transportation, manufacturing modernization, and smart city development also contributes to sustained deployment opportunities. Companies are expanding manufacturing capacity within the region to improve production efficiency and reduce delivery times. Intense competition, however, continues to place downward pressure on pricing, encouraging greater investment in proprietary chips, manufacturing automation, and vertically integrated production.
Middle East and Africa
Demand across the Middle East and Africa remains concentrated in surveying, energy infrastructure, mining, transportation planning, and defense applications. Countries including the United Arab Emirates and Saudi Arabia continue investing in smart city development, large-scale infrastructure projects, and digital mapping initiatives that require accurate three-dimensional data acquisition. Many buyers continue relying on imported LiDAR systems because regional manufacturing remains limited. Suppliers with established service capabilities, local distribution partnerships, and technical training programs are generally better positioned to compete for infrastructure and government procurement projects.
Competitive Landscape
The Mechanical LiDAR market remains technology-driven but increasingly influenced by manufacturing scale, automotive qualification capability, and software integration. Competition extends beyond sensor performance to include production capacity, cost efficiency, certification readiness, supply-chain resilience, and lifecycle support.
Hesai Technology, RoboSense, Ouster, Inc., and LeiShen Intelligent System Co., Ltd. continue strengthening their automotive and robotics portfolios through manufacturing expansion, proprietary semiconductor development, and broader software ecosystems. SICK AG and Hokuyo Automatic Co., Ltd. maintain strong positions in industrial automation by emphasizing reliability, machine safety, and long operating life. Within geospatial applications, Hexagon AB (Leica Geosystems) and Teledyne Optech continue competing through high-precision surveying solutions, established customer relationships, and integrated mapping workflows. Beijing SureStar Technology Co., Ltd. and Zvision Technologies are expanding their presence across industrial and infrastructure applications by broadening product offerings and regional distribution networks.
Barriers to entry remain relatively high because suppliers must combine optical engineering expertise, automotive-grade manufacturing capability, regulatory compliance, software integration, and dependable after-sales support. These requirements continue to favor companies capable of sustaining long product development cycles while supporting customers through multi-year deployment programs.
Recent Developments
April 2026 – Hesai launches ETX color LiDAR: Hesai introduced the ETX LiDAR, combining mechanical scanning with native color perception through its Picasso chip. The sensor improves object classification and traffic-signal recognition, with mass production scheduled during 2026.
February 2026 – Ouster acquires Stereolabs: Ouster completed the acquisition of Stereolabs, integrating AI vision, stereo cameras, perception software, and digital LiDAR into a unified sensing platform for robotics, autonomous machines, and industrial automation applications.
September 2025 – Hesai expands robotaxi collaboration: Hesai announced an expanded partnership with a leading U.S. robotaxi company, deepening supply of its mechanically scanning automotive LiDAR sensors for autonomous vehicle deployments and supporting higher-volume commercial production.
June 2025 – Ouster OS1 approved for Blue UAS: Ouster's OS1 digital mechanical LiDAR received Defense Innovation Unit Blue UAS approval, becoming the first NDAA-compliant 3D LiDAR qualified for U.S. Department of Defense unmanned aircraft programs.
Regulatory and Policy Environment
Mechanical LiDAR deployment is increasingly influenced by safety regulations, functional certification requirements, cybersecurity standards, and regional trade policies rather than by sensor performance alone. Automotive suppliers must comply with internationally recognized standards such as ISO 26262 for functional safety, IATF 16949 for automotive quality management systems, and ISO/SAE 21434 governing vehicle cybersecurity. These requirements extend development timelines but improve confidence among vehicle manufacturers selecting suppliers for long-term production contracts.
Industrial automation applications are shaped by machine safety standards developed by organizations such as the International Electrotechnical Commission (IEC) and the International Organization for Standardization (ISO). Surveying equipment used in infrastructure, mining, and environmental monitoring must also satisfy national measurement and calibration requirements to ensure data accuracy across engineering and public-sector projects.
Trade policy continues to influence manufacturing decisions. Export controls affecting advanced semiconductor technologies, regional localization initiatives, and evolving customs requirements encourage several manufacturers to diversify production footprints and strengthen regional supply chains. Companies increasingly establish local manufacturing, engineering, and service capabilities to reduce procurement risk, improve delivery performance, and satisfy customer preferences for supply continuity.
Government investment in intelligent transportation systems, digital infrastructure, smart cities, and national mapping programs also supports long-term demand for high-precision LiDAR systems. Although procurement priorities differ by region, public investment continues to provide stable opportunities for suppliers with proven technical capabilities and established compliance credentials.
Outlook and Strategic Implications
Mechanical LiDAR is expected to retain an important commercial position throughout the 2026–2031 forecast period despite accelerating investment in solid-state sensing technologies. Applications requiring long-range detection, dense point-cloud generation, wide scanning coverage, and proven operational reliability continue to favor mature mechanical architectures. Automotive qualification programs, digital infrastructure investment, industrial automation, and high-accuracy geospatial surveying are expected to remain the principal demand sources over the medium term.
Competitive priorities are gradually shifting from sensor performance toward manufacturing economics, lifecycle support, software capability, and production scalability. Buyers increasingly evaluate suppliers on their ability to provide complete perception solutions that include calibration software, system integration, cybersecurity compliance, and dependable after-sales support. As average selling prices continue to face pressure, companies capable of improving manufacturing efficiency while maintaining product reliability are likely to strengthen their competitive position.
Several strategic themes are expected to influence investment decisions during the forecast period:
Automotive manufacturers will prioritize suppliers capable of delivering automotive-grade production volumes, functional safety compliance, and long-term supply assurance.
Industrial and robotics customers will continue seeking integrated sensing platforms that reduce installation complexity and improve operational reliability.
Surveying and infrastructure organizations will maintain demand for high-accuracy systems supported by established calibration procedures and software compatibility.
Manufacturers are expected to increase investment in proprietary semiconductor technologies, automated production, and regional manufacturing capacity to reduce costs and improve supply resilience.
Technology providers and system integrators will increasingly compete through software ecosystems, perception algorithms, and lifecycle services rather than hardware specifications alone.
While solid-state LiDAR will continue expanding across several emerging vehicle platforms, mechanical LiDAR is expected to preserve its commercial relevance in applications where measurement precision, mature deployment experience, and operational reliability remain more important than sensor size or packaging efficiency. Companies that successfully balance manufacturing scale, regulatory compliance, software integration, and cost discipline are likely to capture the strongest commercial opportunities during the forecast period.
Mechanical LiDAR Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.50 billion |
| Total Market Size in 2031 | USD 4.80 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 13.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Application, Geography |
| Companies |
|
Market Segmentation
By Component
Laser Transmitter
Receiver / Photodetector
Scanner and Rotating Assembly
Processing Electronics / Controller
Others (Optics, Mirrors, Housing)
By Application
Automotive
Mapping and Surveying (Geospatial)
Robotics and Automation
Industrial
Security and Surveillance
Smart Infrastructure
Aerospace and Defense
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
Japan
China
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to the Stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. MECHANICAL LIDAR MARKET, BY COMPONENT
5.1. Introduction
5.2. Laser Transmitter
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.2.3. Geographic Lucrativeness
5.3. Receiver/ Photodetector
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.3.3. Geographic Lucrativeness
5.4. Scanner and Rotating Assembly
5.4.1. Market Trends and Opportunities
5.4.2. Growth Prospects
5.4.3. Geographic Lucrativeness
5.5. Processing Electronics / Controller
5.5.1. Market Trends and Opportunities
5.5.2. Growth Prospects
5.5.3. Geographic Lucrativeness
5.6. Others (Optics, Mirrors, Housing)
5.6.1. Market Trends and Opportunities
5.6.2. Growth Prospects
5.6.3. Geographic Lucrativeness
6. MECHANICAL LIDAR MARKET, BY APPLICATION
6.1. Introduction
6.2. Automotive
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.2.3. Geographic Lucrativeness
6.3. Mapping and Surveying (Geospatial)
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
6.3.3. Geographic Lucrativeness
6.4. Robotics and Automation
6.4.1. Market Trends and Opportunities
6.4.2. Growth Prospects
6.4.3. Geographic Lucrativeness
6.5. Industrial
6.5.1. Market Trends and Opportunities
6.5.2. Growth Prospects
6.5.3. Geographic Lucrativeness
6.6. Security and Surveillance
6.6.1. Market Trends and Opportunities
6.6.2. Growth Prospects
6.6.3. Geographic Lucrativeness
6.7. Smart Infrastructure
6.7.1. Market Trends and Opportunities
6.7.2. Growth Prospects
6.7.3. Geographic Lucrativeness
6.8. Aerospace and Defense
6.8.1. Market Trends and Opportunities
6.8.2. Growth Prospects
6.8.3. Geographic Lucrativeness
6.9. Others
6.9.1. Market Trends and Opportunities
6.9.2. Growth Prospects
6.9.3. Geographic Lucrativeness
7. MECHANICAL LIDAR MARKET, BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Component
7.2.2. By Application
7.2.3. By Country
7.2.3.1. United States
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Component
7.3.2. By Application
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1.1. Market Trends and Opportunities
7.3.3.1.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1.1. Market Trends and Opportunities
7.3.3.2.1.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1.1. Market Trends and Opportunities
7.3.3.3.1.2. Growth Prospects
7.4. Europe
7.4.1. By Component
7.4.2. By Application
7.4.3. By Country
7.4.3.1. United Kingdom
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. Germany
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. France
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Italy
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Spain
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.4.3.6. Others
7.4.3.6.1. Market Trends and Opportunities
7.4.3.6.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Component
7.5.2. By Application
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. UAE
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Others
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Component
7.6.2. By Application
7.6.3. By Country
7.6.3.1. Japan
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. China
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.2 India
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. South Korea
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. Taiwan
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Thailand
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Indonesia
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
7.6.3.4. Others
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Hesai Technology
9.2. Ouster, Inc.
9.3. LeiShen Intelligent System Co., Ltd.
9.4. SICK AG
9.5. Hokuyo Automatic Co., Ltd.
9.6. Hexagon AB (Leica Geosystems)
9.7. Teledyne Optech
9.8. Beijing SureStar Technology Co., Ltd.
9.9. Zvision Technologies
9.10. RoboSense
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











