
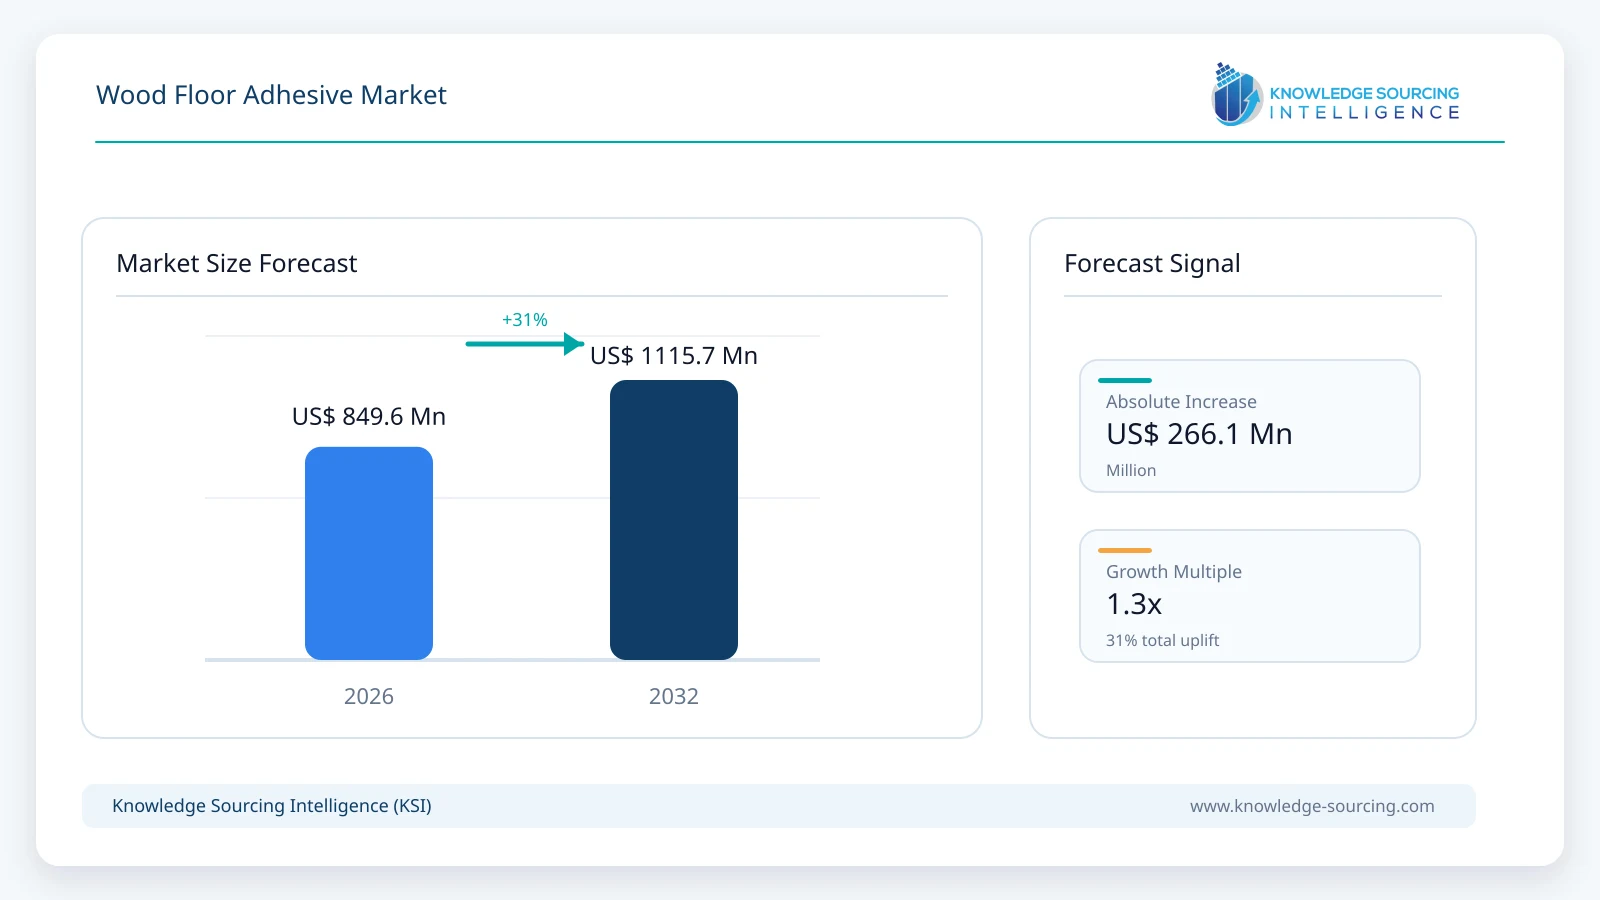
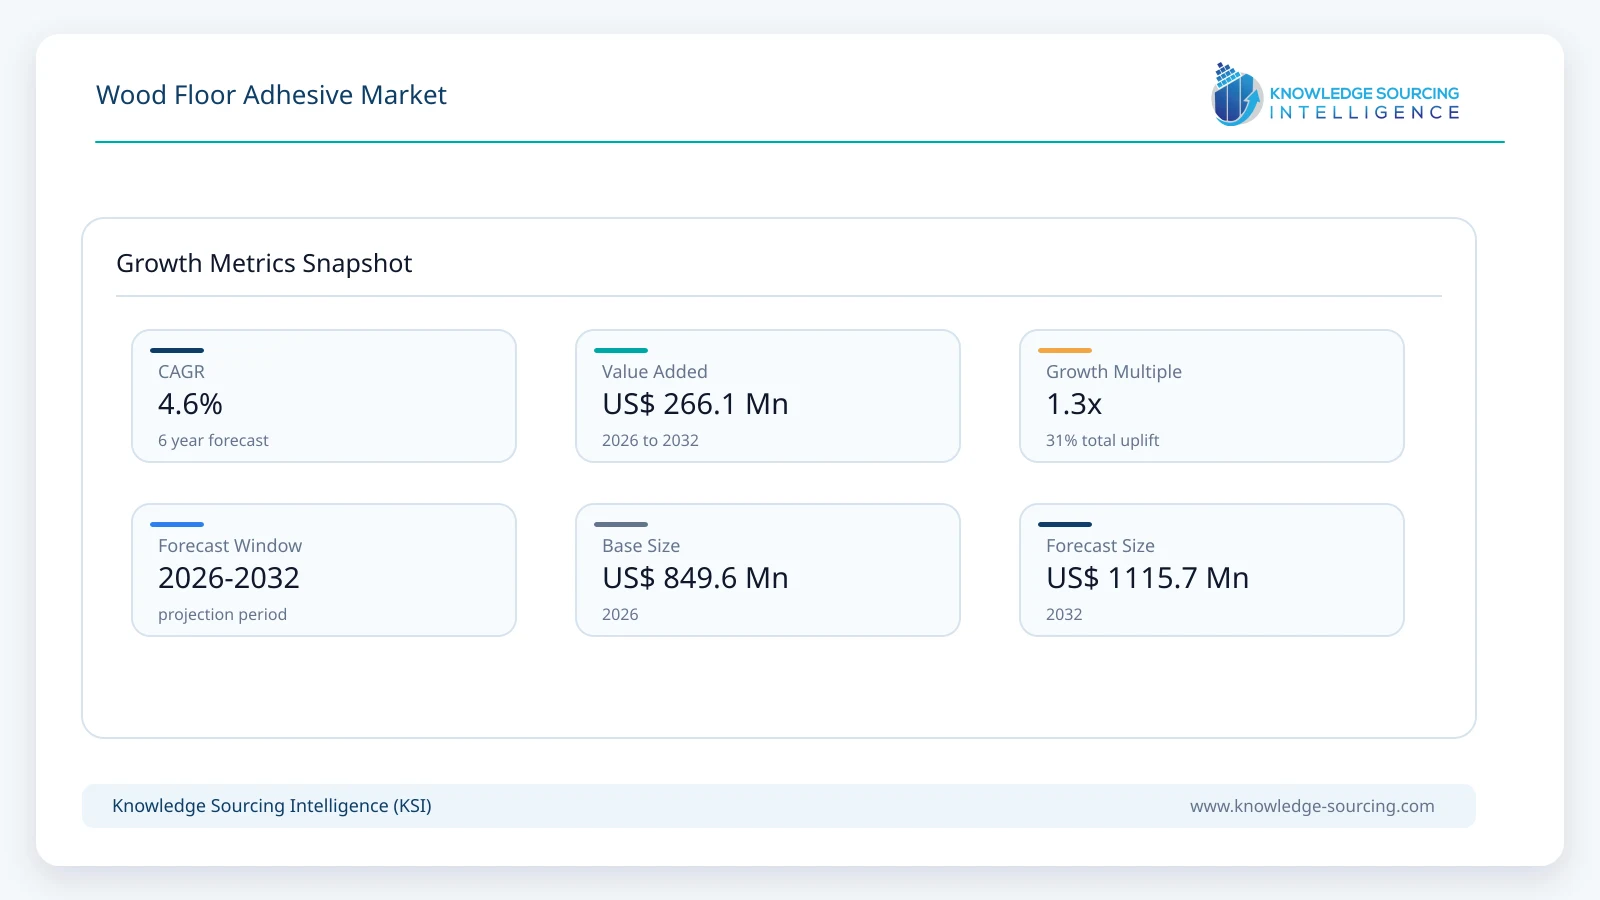
The wood floor adhesive market is estimated at USD 849.6 million in 2026 and is projected to reach USD 1,115.7 million in 2032, expanding at a 4.6% CAGR during the forecast period.
Highlights:
- 1Silane-modified polymer adhesives account for an estimated 51.1% of 2026 revenue, supported by flexible bonding, low-emission specifications and compatibility with a wide range of subfloors.
- 2European parquet demand remains restrained; the European Parquet Federation reported approximately 60.2 million m² of member-market consumption in 2025, broadly unchanged from 2024, making renovation and chemistry upgrades more important than rapid volume expansion.
- 3The market's economic exposure is concentrated in installation method. Floating and mechanically fastened floors require little or no full-spread adhesive, even when they use the same engineered-wood product sold into glue-down applications.
- 4Manufacturers increasingly compete on system-level installation performance, including bond flexibility, moisture tolerance, floor-heating suitability, working time and emissions certification, rather than adhesive price per kilogram alone.
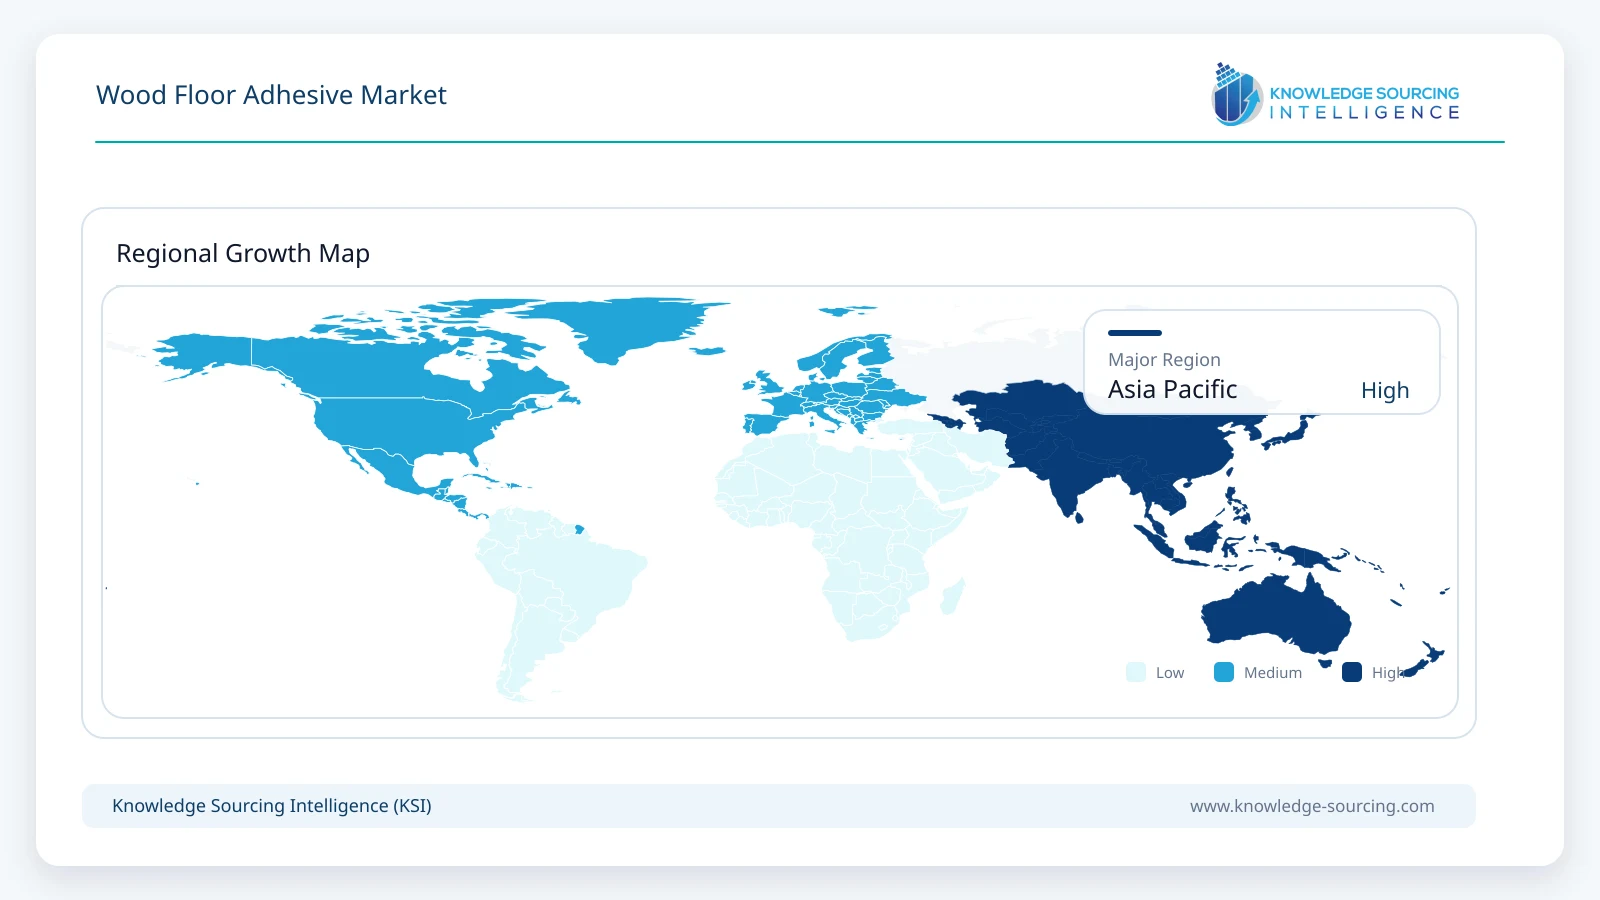
- 5Asia Pacific provides the largest modeled revenue contribution, while North American and European installations provide substantial demand for premium reactive and silane-based systems.
The market includes formulated adhesives purchased to bond engineered wood flooring, solid hardwood and parquet to subfloors in residential, commercial and institutional buildings. It excludes the resin used inside engineered flooring boards, adhesives for unrelated vinyl or carpet coverings, the value of finished flooring, and separately charged surface preparation or moisture-barrier products.
Wood-floor adhesive demand depends on three linked purchasing decisions: whether a customer chooses real wood flooring, whether the installer selects glue-down rather than a floating or mechanical installation, and which bond chemistry meets the floor's movement, moisture and indoor-emission requirements. As a result, revenue growth is not directly proportional to new housing completions or wood-floor shipments. A shift toward higher-value silane-based formulations can increase adhesive spend even when installed parquet area is flat, while wider floating-floor adoption can reduce consumption despite growth in engineered-wood shipments.
Wood Floor Adhesive Market Trends
Installation method matters more than the headline flooring shipment number
The primary constraint on adhesive demand is the proportion of wood flooring that is actually bonded to the subfloor. Factory sales of engineered boards are not a suitable proxy for adhesive consumption, because many click-system products are laid as floating floors. Equally, a glued engineered floor does not consume the same quantity as a nailed solid floor that receives only limited supplementary adhesive. Counting every square meter of wood flooring as an adhesive-consuming installation would therefore overstate the addressable market.
Regional flooring statistics reinforce this distinction. The European Parquet Federation reported consumption of approximately 60.2 million m² in 2025 across member markets. Chinese industry data show 2024 sales of about 110 million m² of solid-wood composite flooring and 27 million m² of solid wood flooring; the separate 132 million m² of laminate flooring should not be automatically counted as bonded hardwood. In the United States, industry estimates place 2025 hardwood flooring shipments near 630 million square feet, down 6.8% from the prior year. Those figures establish the physical flooring baseline, but they do not report glue-down penetration. Installation share is consequently a distinct forecast variable.
For manufacturers, improving contractor specification rates can be as important as growth in residential construction. Flooring suppliers that offer products suitable for glued, floating and mechanically fixed installation may generate different adhesive demand depending on installer preference, local subfloor conditions and project schedules. Wood-floor adhesive suppliers therefore need stronger access to flooring installers, specialized distributors and specification consultants, rather than relying exclusively on the growth of finished-floor sales.
Premium products must demonstrate an installation-cost benefit
Adhesive performance has a measurable impact on labor and rework costs. Sika publishes consumption ranges from approximately 0.6 to 1.0 kg/m² for one wood-floor adhesive and 0.95 to 1.25 kg/m² for another, depending on subfloor profile and trowel selection. A higher application rate can offset a low purchase price, particularly on large commercial projects. Uneven slabs also increase material usage and can necessitate grinding, moisture testing or primer application before bonding.
Higher-priced products increasingly combine elastic bond performance with claims related to moisture-vapor management, acoustic performance or rapid return to service. Those capabilities are not interchangeable: a basic silane adhesive should not be assumed to provide the same moisture-control rating as a specifically tested system, and a moisture barrier sold separately should not be counted as adhesive revenue. For contractors, the commercial comparison concerns total installed cost and defect risk per square meter, not the nominal price of a pail.
Indoor-air quality is becoming a product qualification issue
Wood-floor adhesives are installed across large interior surfaces and may contribute to indoor emissions during application and curing. Germany's DIBt distinguishes parquet adhesives as a construction-product category requiring verification of indoor-health performance under applicable national rules. The agency's product listings include silane polymers, polyurethanes and dispersions, showing that low-emission competition crosses multiple chemistries rather than simply replacing all polyurethane with water-based products.
This shifts competition toward documented installation suitability and emissions performance. Soudal, for example, markets separate hybrid, polyurethane and dispersion parquet adhesives for different wood constructions and substrate types. Product selection depends on sensitivity to moisture, board dimensions, subfloor porosity and desired bond stiffness. The result is a segmented specialty market in which a single formulation is unlikely to meet every installer requirement.
Wood Floor Adhesive Market Growth Drivers
Engineered wood and higher-quality renovation support specialty adhesive demand
Engineered flooring is a significant source of demand because wide planks, concrete slabs and refurbishment work create requirements that a basic wood glue may not address. For bonded installations, the adhesive must tolerate wood movement without excessive deformation or premature bond failure. Substrate moisture and curing time further influence whether a contractor uses a moisture-reactive polymer, polyurethane system or dispersion adhesive.
These considerations increase the value of product support. Manufacturers can differentiate through compatible primer systems, detailed substrate instructions, warranty documentation and contractor training. The commercial consequence is a premium opportunity for suppliers capable of qualifying entire installation systems, especially in high-value residential renovation and commercial refurbishment. However, the opportunity applies only to glued floor area; increasing market share of floating engineered flooring remains an offsetting restraint.
Moisture management and installation reliability influence purchasing
Concrete moisture is among the most consequential site variables in wood-floor installation. A flooring contractor must assess substrate condition before adhesive application, because moisture-related problems can cause cupping, debonding, damaged finish layers or expensive replacement work. Sika's product data specify different substrate preparation and moisture limits, making clear that a product's suitability depends on more than its chemical family.
Some high-performance products provide qualified moisture protection within the adhesive layer, while other applications still require a dedicated primer or moisture barrier. When compatible systems reduce installation steps or warranty risk, installers may accept a higher material price. The adhesive producer can capture part of the benefit through premium pricing, but project economics also depend on application coverage and whether the substrate requires remediation beyond normal preparation.
Wood Floor Adhesive Market Restraints
Floating floors and resilient coverings constrain volume growth
The principal structural restraint is the substitution of installation methods and floor finishes. Click-system engineered floors and many laminate products can be installed without full-spread adhesive. Luxury vinyl plank, SPC and other resilient coverings compete against hardwood for the same renovation budget, but their adhesive consumption belongs to separate categories or may be negligible for click products. These effects reduce the correlation between construction spending and wood-floor adhesive revenue.
The US market illustrates the pressure. Industry reporting indicates hardwood shipments declined to about 630 million square feet in 2025, while wood-look alternatives continued to take share. In Europe, parquet consumption remained nearly flat at a historically subdued level. A recovery in housing transactions could support adhesive demand, but it should not be projected as a uniform return to strong volume growth across regions.
Price realization is exposed to construction cycles and distribution margins
Adhesives are sold through industrial suppliers, professional flooring distributors and retail channels with different pricing structures. Posted US prices for recognized wood-floor adhesive pails span roughly US$115 to US$250 for common 3- to 4-gallon packs, depending on formulation. Those prices include distributor and retail economics and cannot be treated as average manufacturer selling prices worldwide.
Contractors also compare the cost per applied square meter. A higher-value adhesive may achieve better contribution margins per kilogram, yet face resistance if installation coverage falls or labor savings are not established. Raw-material cost fluctuations in silanes, polyurethane precursors, fillers and packaging create additional pressure, particularly when construction activity is weak and distributors resist price increases.
Wood Floor Adhesive Market Segmentation Analysis
By Chemistry: Silane-Modified Polymer Adhesives
Silane-modified polymer adhesives are estimated to generate US$565.51 million in 2032, making them the largest chemistry category within the defined market. The category includes products described as SMP, STP, MS polymer and related silane-terminated systems where silane modification is the defining binder technology. It does not automatically include every manufacturer-marketed “hybrid” product, which must be classified by its primary chemistry to avoid overlap with polyurethane.
The commercial advantage of these formulations rests on how they address hardwood movement and installer handling requirements. Wood expands and contracts with changes in humidity, while wide engineered planks can transmit shear forces through the adhesive bed. Systems engineered to remain elastically bonded can reduce stress concentration compared with overly rigid or brittle bonding methods. Manufacturers therefore market polymer structure, application tack, cure behavior and shear resistance as differentiated features. Bona's R851 is a silane-based wood-floor adhesive offered for professional installation, while UZIN's MK 250 and PALLMANN's P5 demonstrate competing approaches to hard-elastic STP bonding.
The economic value extends beyond the adhesive layer. Contractors increasingly evaluate whether the product suits concrete, screed, plywood, sound-reduction assemblies or underfloor heating, and how quickly a floor can be loaded or finished. A formulation that adheres reliably across several substrates may simplify inventory and training. Yet broader advertised compatibility does not eliminate the need to confirm substrate moisture and preparation requirements. A failed bond can require removal of high-cost finished wood, which is why specifications and warranties often matter more than small differences in material spend.
Application consumption remains a material purchasing variable. Manufacturer specifications commonly indicate roughly 0.6–1.25 kg/m² for full-spread bonding, depending on trowel, board type and slab condition. Even a difference of 0.2 kg/m² creates 200 kg of additional product usage across a 1,000 m² project. At a hypothetical US$5/kg realized purchase cost, that represents US$1,000 of incremental material spending before labor or wastage. Procurement teams therefore compare applied coverage and performance requirements rather than ranking products solely by unit price.
The competitive field includes SikaBond, Bona QUANTUM, UZIN MK, PALLMANN, WAKOL and other specialist brands. Supplier differentiation rests on documented emissions qualifications, moisture and sound performance, accessibility through professional distributors, technical support and installation-system warranties. In mature markets, manufacturers may gain share by converting an existing contractor from traditional formulations rather than relying on an increase in total floor area. This favors products with a clear specification advantage and reliable contractor acceptance.
Nevertheless, premium systems face two limits. First, cost-sensitive projects may choose lower-priced polyurethane or dispersion products when they meet the specified requirements. Second, demand disappears when an engineered floor is installed floating rather than bonded. Silane suppliers can expand the value captured per glued square meter, but they cannot assume that all engineered-flooring growth translates into adhesive purchases. This distinction is central to the segment's longer-term revenue outlook.
By Chemistry: Polyurethane and Water-Based Systems
Polyurethane adhesives are estimated to represent US$268.74 million of 2026 demand. Both one-component moisture-curing and two-component systems remain commercially relevant, particularly where installers require high shear strength, specific curing properties or qualified bonding of difficult wood constructions. Forbo Eurocol's two-component polyurethane parquet range and Soudal's product guidance show that the chemistry remains part of professional installation rather than an obsolete technology.
Water-based dispersion adhesives are projected to grow from US$110.61 million in 2026 to US$147.88 million in 2032. They retain a role in suitable parquet constructions and absorbent subfloors. Product selection must account for potential moisture sensitivity in the wood, board dimensions and drying conditions. Their lower price positioning can support use in less demanding installations, but they should not be treated as universal substitutes for reactive full-spread adhesives.
By Flooring Type and End User
Engineered wood and parquet installations account for approximately 78.6% of modeled 2026 adhesive revenue. The segment benefits from the wide range of available bonded flooring systems and their use in residential upgrading and commercial fit-outs. Solid hardwood remains a separate application, because installation practice varies more widely between full-spread bonding and mechanical fastening. Wood adhesives used only as minor supplementary beads should not be valued at the same intensity as a fully troweled installation.
Residential applications account for an estimated US$644.24 million in 2026. Demand is linked to higher-value housing, renovation decisions and contractor preferences. Commercial and institutional applications face more structured specification processes, including subfloor testing, acoustic requirements and installation scheduling. Neither end-user segment should be modeled simply as a fixed proportion of total construction expenditure.
Wood Floor Adhesive Market Geographical Outlook
Asia Pacific
Asia Pacific is estimated at US$309.77 million in 2026, representing the largest regional revenue pool under the installation-only definition. China provides the largest physical flooring reference within the region. Chinese association statistics indicate roughly 110 million m² of solid-wood composite and 27 million m² of solid wood flooring sold in 2024 by covered producers. However, much of the engineered-flooring market can use floating or mechanical installation, which means the entire sales area does not translate into adhesive consumption.
Adhesive demand also depends on the split between premium and economy products. Professional gluing of larger wood boards creates opportunities for elastic polymer and reactive polyurethane systems, while less demanding installations can favor lower-cost products. India and Southeast Asia offer longer-term growth through housing renovation and professional installation, although published country-level glue-down rates remain limited. Regional forecasts therefore depend as much on installation practice and pricing as on construction-volume growth.
Europe
Europe is estimated to generate US$268.27 million in 2026, supported by a relatively high share of professionally bonded parquet installations and premium construction-chemical specifications. FEP reported a 2025 parquet market of around 60.2 million m² across member countries, indicating stabilization rather than rapid expansion. The European Commission's July 2025 anti-dumping measures on Chinese multilayer wood flooring also demonstrate how trade policy can affect flooring sourcing and product mix. They do not directly establish adhesive-market growth, but they can influence the type and source of flooring supplied to installers.
Competition focuses on low-emission formulations, installation compatibility and the availability of qualified products. Germany's DIBt lists many approved parquet adhesives across silane, polyurethane and dispersion categories. This regulatory and technical environment favors suppliers that can document product suitability and maintain consistent distributor coverage.
North America and Other Regions
North America is estimated at US$180.81 million in 2026. Hardwood demand is concentrated in selected residential and commercial projects, with installation method and substrate condition strongly influencing adhesive consumption. The decline in US hardwood shipment volumes during 2025 constrains the volume baseline, even as professional adhesives command comparatively high per-kilogram prices. In South America and the Middle East and Africa, premium installation projects support selective opportunities, but there is not enough public evidence to treat all country markets as having the same glue-down share or price structure.
Competitive Environment and Analysis
The competitive landscape combines multinational construction-chemicals suppliers with specialist wood-floor installation brands. Sika markets SikaBond and SCHÖNOX flooring systems; Arkema participates through Bostik; Mapei provides Ultrabond parquet adhesives; Bona, WAKOL, STAUF, Berger-Seidle and Uzin Utz focus heavily on professional installation and finishing channels. Forbo Eurocol, Soudal, Murexin and Kiesel also offer documented parquet adhesive products.
Competitive positioning depends on technical approval, site support, installer loyalty, distribution breadth and achievable coverage per pail. A broad construction-adhesive portfolio does not by itself establish a meaningful position in wood-floor adhesives. Similarly, overlapping corporate brands must not be counted as independent company-level market shares. The strongest comparisons assess product availability in the relevant geography, exact approved applications, pricing channel and compatibility with the flooring manufacturer's installation instructions.
Recent Developments
August 2026: Germany's DIBt listed a new technical approval for Berger-Seidle's BergerBond M1X parquet adhesive, effective August 10, 2026.
June 2026: Germany's DIBt listed a new technical approval for Sika's SCHÖNOX iLINE 260 parquet adhesive, effective June 26, 2026.
June 2026: The European Parquet Federation reported 2025 member-country parquet consumption of approximately 60.2 million m² at its June 12 general assembly.
June 2026: Germany's DIBt listed technical approvals for Bostik WOOD P918 2K and WOOD A55 BASIC products, effective June 11, 2026.
Wood Floor Adhesive Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 849.6 million |
| Total Market Size in 2032 | USD 1,115.7 million |
| Forecast Unit | Million |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Chemistry, Flooring Type, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Chemistry
Silane-Modified Polymer (MS/SMP/STP)
Polyurethane (PUR)
Water-Based Dispersion
Solvent-Based, Epoxy and Others
By Flooring Type
Engineered Wood and Parquet
Solid Hardwood
By End User
Residential
Commercial and Institutional
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market Overview and Principal Findings
1.2. Wood Floor Adhesive Market Size, 2026–2032
1.3. Main Industry Constraints and Opportunities
1.4. Key End-Use and Regional Findings
2. MARKET SCOPE AND RESEARCH METHODOLOGY
2.1. Market Definition and Revenue Boundary
2.2. Included and Excluded Products
2.3. Primary and Secondary Evidence Sources
2.4. Installation-Area and Product Consumption Model
2.5. Forecast Assumptions and Data Validation
3. INDUSTRY AND TECHNOLOGY OVERVIEW
3.1. Engineered Wood, Solid Hardwood and Parquet Installation Systems
3.2. Glue-Down, Floating and Mechanically Fastened Methods
3.3. Substrate Preparation, Moisture and Floor Heating
3.4. Adhesive Performance and Applicable Technical Standards
3.5. Low-Emission and Health-Related Product Requirements
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Industry Opportunities
4.4. Raw Material and Realized Adhesive Pricing
4.5. Installation Economics and Value Chain
4.6. Regulations and Emissions Compliance
4.7. Porter’s Five Forces Analysis
5. WOOD FLOOR ADHESIVE MARKET BY CHEMISTRY
5.1. Silane-Modified Polymer (MS/SMP/STP)
5.2. Polyurethane (PUR)
5.3. Water-Based Dispersion
5.4. Solvent-Based, Epoxy and Others
6. WOOD FLOOR ADHESIVE MARKET BY FLOORING TYPE
6.1. Engineered Wood and Parquet
6.2. Solid Hardwood
7. WOOD FLOOR ADHESIVE MARKET BY END USER
7.1. Residential
7.2. Commercial and Institutional
8. WOOD FLOOR ADHESIVE MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. France
8.3.3. United Kingdom
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. South Korea
8.5.5. Australia
8.5.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategic Positioning
9.2. Product Portfolio and Chemistry Benchmarking
9.3. Distribution and Installer Specification Strategies
9.4. Mergers, Acquisitions and Recent Developments
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Sika AG
10.2. Arkema S.A. (Bostik)
10.3. Mapei S.p.A.
10.4. Bona AB
10.5. Uzin Utz SE (UZIN and PALLMANN)
10.6. WAKOL GmbH
10.7. STAUF Klebstoffwerk GmbH
10.8. Berger-Seidle GmbH
10.9. Forbo Holding AG (Forbo Eurocol)
10.10. Soudal NV
10.11. Murexin GmbH
10.12. Kiesel Bauchemie GmbH & Co. KG
11. APPENDIX
11.1. Currency and Units
11.2. Assumptions
11.3. Historical and Forecast Years
11.4. Abbreviations
11.5. Sources and Evidence Hierarchy
11.6. Research Methodology





Frequently asked questions
What is the projected Wood Floor Adhesive Market size and growth rate?
The Wood Floor Adhesive Market is projected to reach USD 1,115.7 million by 2032, at a 4.6% CAGR.
Which adhesive chemistry dominates the Wood Floor Adhesive Market?
Silane-modified polymer adhesives account for 51.1% of 2026 revenue.
Which region provides the largest revenue contribution for wood floor adhesives?
Asia Pacific provides the largest modeled revenue contribution.
What primary factor influences wood floor adhesive demand?
Installation method (glue-down vs. floating) significantly impacts adhesive demand.
What are manufacturers competing on beyond adhesive price?
They compete on system-level performance, bond flexibility, and emissions certification.
What is the forecast period covered by this report?
The report covers strategic insights and forecasts from 2026 to 2032.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Wood Floor Adhesive Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/wood-floor-adhesive-market