
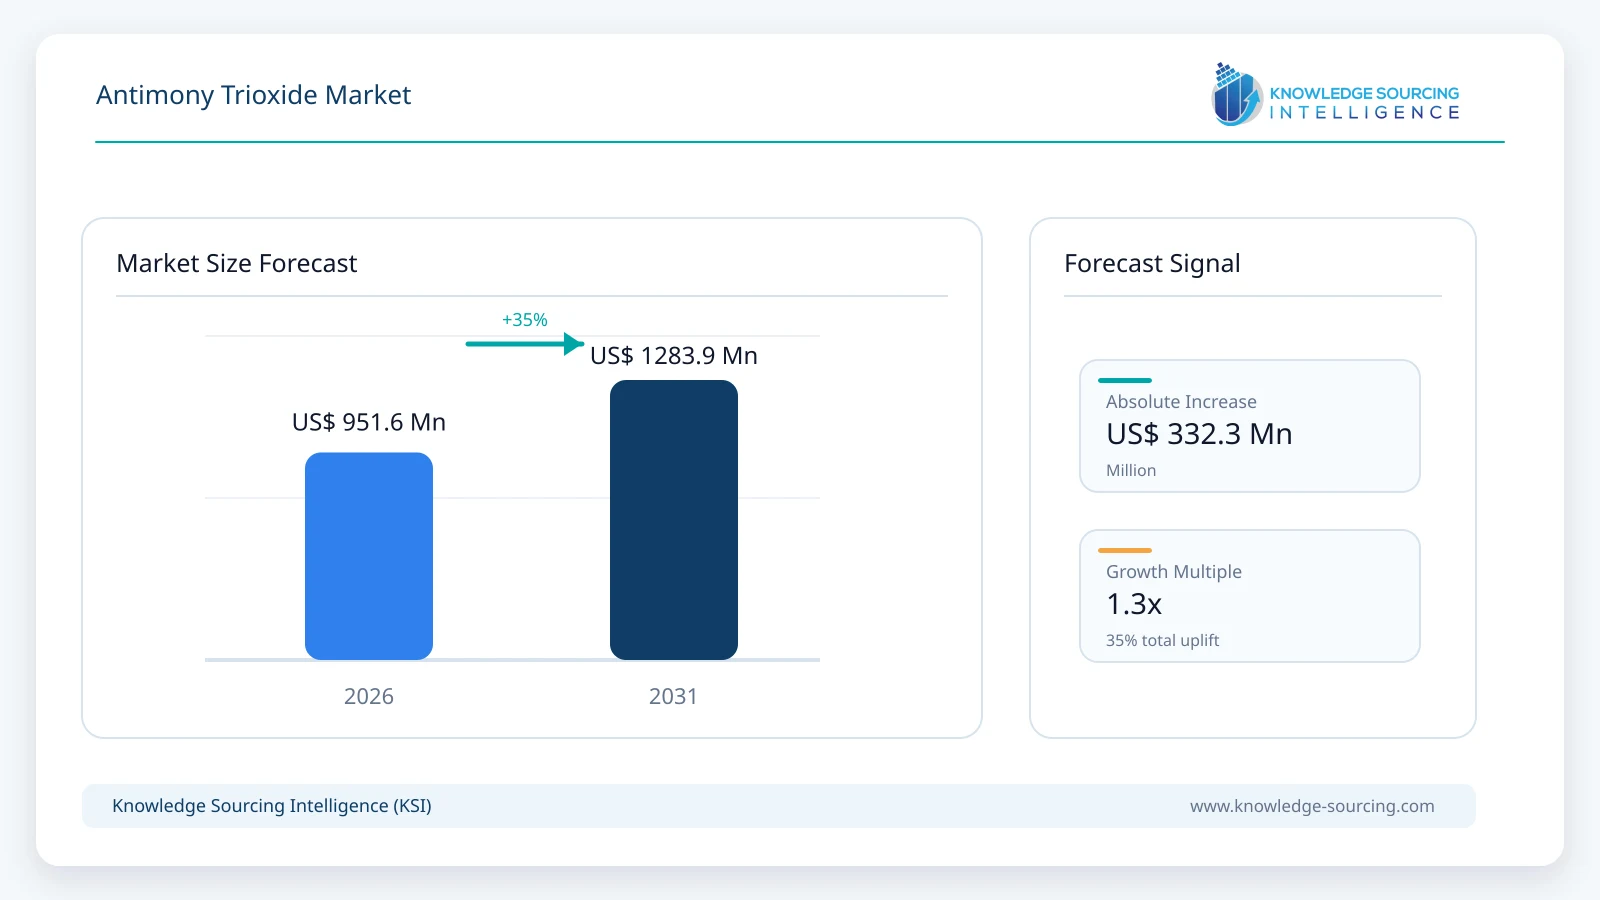
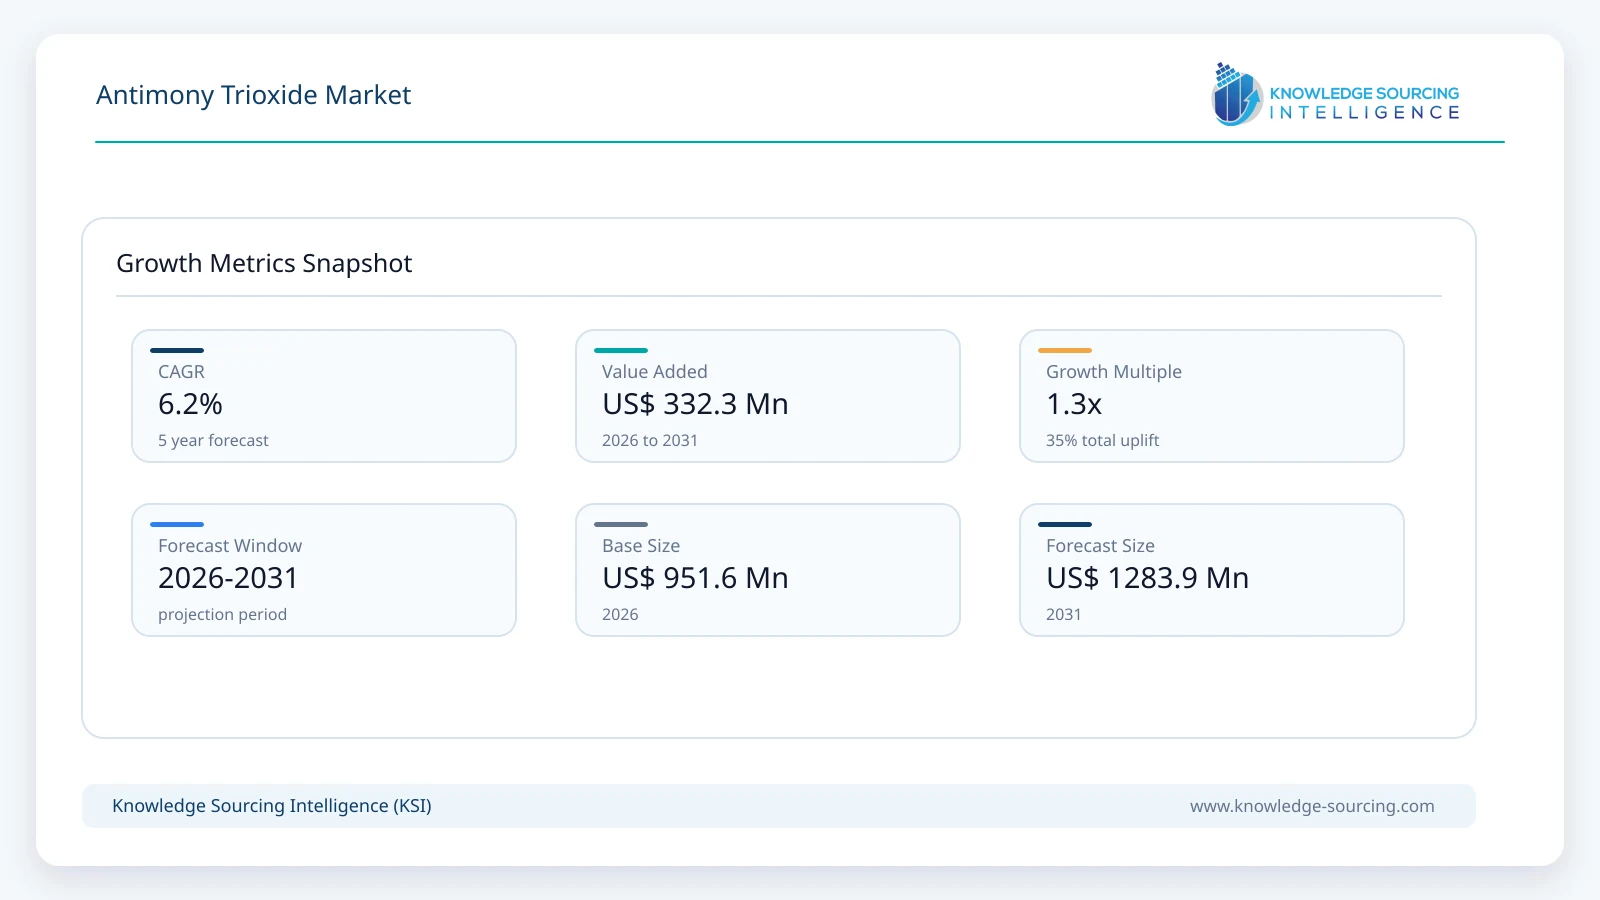
The Global Antimony Trioxide market is forecast to grow at a CAGR of 6.2%, reaching USD 1,283.9 million in 2031 from USD 951.6 million in 2026.
Highlights:
- 1Flame-retardant formulations remain the principal demand engine, particularly across plastics, rubber, textiles, cables, electrical components, and construction-related polymer products.
- 2Supply security is becoming a purchasing priority, as export controls and concentrated antimony feedstock availability have increased exposure to price and delivery volatility.
- 3Asia Pacific remains strategically important because China has a large antimony-processing base, while Japan, South Korea, Taiwan, and India provide major downstream electronics, plastics, textiles, and manufacturing demand.
- 4Masterbatch and pre-dispersed formats are gaining commercial relevance where processors want controlled dosing, lower dust exposure, improved dispersion, and simpler incorporation into polymer formulations.
- 5Regulatory compliance is influencing grade selection and production practices, particularly in Europe and North America where chemical classification, worker exposure, product documentation, and environmental requirements affect procurement.
- 6Recycling and regional supply-chain investment are becoming competitive differentiators, as manufacturers seek alternatives to dependence on concentrated primary antimony supply.
Antimony trioxide (Sb2O3) is an inorganic antimony compound primarily used as a flame-retardant synergist, but its commercial role extends into plastics, rubber, textiles, paints and coatings, pigments, glass and ceramics, and polyester manufacturing. Its value comes less from high-volume consumption than from its functional contribution to formulations where fire performance, process stability, optical characteristics, or catalytic performance must be achieved within tightly controlled material specifications. The market therefore operates at the intersection of specialty chemicals, inorganic materials, plastic additives, flame-retardant systems, and antimony supply chains.
The commercial market covers the manufacture, processing, formulation, distribution, and application of antimony trioxide in powder, masterbatch, and other application-specific forms. Buyers generally do not procure the material solely on headline price. Purity, particle-size distribution, dispersion characteristics, moisture content, packaging, consistency between batches, regulatory documentation, and the ability to maintain supply are important purchasing criteria. These factors are particularly relevant for plastics compounders, flame-retardant formulators, PET producers, coating manufacturers, and industrial processors that incorporate antimony trioxide into established recipes.
The demand structure is strongly linked to downstream products rather than direct consumer demand. Flame-retardant systems represent a central demand channel because antimony trioxide works synergistically with halogen-containing flame retardants. Campine identifies applications in vehicle components, building materials, electrical and electronic cables, plastic housings, connectors, sockets, textiles, and other polymer products. The company also supplies antimony trioxide as a PET catalyst and as a raw material for pigments, demonstrating the breadth of industrial applications beyond conventional flame retardancy.
Purchasing decisions differ by application. Flame-retardant compounders place greater emphasis on particle size, dispersion, compatibility with the polymer system, concentration, and formulation performance. PET producers require high-purity material with predictable solubility and catalytic behavior. Pigment manufacturers place greater weight on purity and particle-size distribution because these characteristics affect color performance and process efficiency. This application-specific purchasing behavior supports a differentiated market in which suppliers compete through grade consistency and formulation support rather than commodity pricing alone.
Supply economics are strongly influenced by the availability of antimony feedstock. China remains a central part of the global antimony processing and export system, while supply diversification has become a commercial priority following China's August 2024 decision to impose export controls on specified antimony-related items. The Chinese government stated that covered antimony products require export licensing and included certain antimony oxides meeting specified purity thresholds within the controlled items.
The consequences of this supply concentration were visible during 2025. Campine reported that antimony metal prices reached approximately US$60,000 per tonne by mid-2025, around three times early-2024 levels, following the withdrawal of Chinese suppliers from the market. The resulting price escalation caused some customers to reduce antimony usage or temporarily move toward alternative flame-retardant systems. Additional smelting capacity in Southeast Asia later improved physical availability and contributed to price declines toward the end of 2025.
This price cycle illustrates an important characteristic of the antimony trioxide market. Demand can remain structurally necessary while short-term consumption becomes price-sensitive. Buyers with qualified alternative formulations may adjust loading levels, reformulate products, or temporarily substitute other flame-retardant chemistries when antimony costs become excessive. However, substitution is constrained where product certifications, fire-performance requirements, processing conditions, or established customer specifications limit formulation changes.
The industry structure also rewards suppliers capable of securing feedstock and integrating processing activities. Recycling provides one route to reduce exposure to primary mineral supply. Campine, for example, recovers antimony from industrial waste streams and reuses recovered material in its specialty chemicals operations, including antimony trioxide production.
The market's commercial trajectory through 2031 will therefore depend on more than downstream volume growth. Supply diversification, recycling economics, regulatory compliance, formulation efficiency, flame-retardant requirements, electronics and vehicle production, construction-material demand, and the availability of qualified alternatives will determine how much antimony trioxide is purchased and at what price.
Market Drivers
Expansion of Flame-Retardant Applications Across Polymer-Intensive Industries
The most direct demand mechanism is the continued use of antimony trioxide as a synergist in flame-retardant systems. Its commercial importance arises because it can improve the performance of halogen-containing flame-retardant formulations without requiring the entire formulation to be redesigned around a different active chemistry. This makes antimony trioxide particularly relevant to polymer compounders producing materials for electrical components, automotive interiors, cables, construction products, textiles, and industrial goods.
Buyers typically evaluate antimony trioxide as part of a complete flame-retardant formulation rather than as an isolated ingredient. Consequently, suppliers that can provide predictable dispersion, suitable particle size, appropriate loading characteristics, and technical assistance can defend customer relationships even when lower-cost material is available.
Campine's product portfolio illustrates this model, with antimony trioxide offered as powder, plastic pellets, dispersions, and customized flame-retardant formulations. Its masterbatch products are designed for polymers including PE, EVA, PP, PVC, PBT, PA, SAN, and HIPS.
Growth in Electrical, Electronic, Automotive, and Building Applications
The expansion of polymer-containing electrical and electronic components supports demand for flame-retardant additives. Cable insulation, connectors, housings, sockets, and other polymeric components often need defined fire-performance characteristics. Automotive applications similarly use flame-retardant polymer materials in dashboards, seals, cables, and structural components. Construction materials can require fire performance across insulation, roofing, flooring, cladding, and related polymer-containing products.
For compounders serving these sectors, procurement decisions are influenced by qualification cycles. Once a formulation has been tested and approved for a specific application, replacing a functional additive can require additional testing and customer validation. This creates a degree of supplier stickiness and supports demand for consistent grades.
Demand for High-Purity Antimony Trioxide in PET Catalysis
Antimony trioxide is also used as a catalyst in polyester production. The requirement differs from flame-retardant applications because PET producers require high-purity and consistent material to support stable catalytic reactions. Campine states that it produces extra-pure antimony trioxide for PET applications and emphasizes solubility in monoethylene glycol and reproducible catalytic performance.
This application provides a separate source of demand and creates opportunities for suppliers capable of meeting tighter purity and consistency requirements. It also shifts competition away from simple cost-per-tonne comparisons toward technical qualification, batch reliability, and process performance.
Development of Masterbatch and Pre-Dispersed Formats
Masterbatch represents an important product-development pathway because it addresses practical challenges associated with handling fine powders. Pre-dispersed material can improve dosing accuracy, reduce dust generation, and simplify incorporation into polymer-processing systems.
Suppliers can differentiate through polymer carrier selection, concentration, particle-size distribution, plasticizer compatibility, and formulation design. Campine, for example, offers monobatches and combined masterbatches containing antimony trioxide and other flame-retardant components, including low-halogen and halogen-free formulations.
The commercial implication is that some buyers may increasingly purchase a formulated intermediate rather than raw antimony trioxide. This can increase supplier value per unit while strengthening technical relationships with compounders.
Supply-Chain Diversification and Recycling Investment
Supply disruption has increased the economic value of non-China sourcing, recycling, and regional processing. Antimony trioxide manufacturers that can secure feedstock from multiple sources or recover antimony from industrial waste can reduce exposure to primary mineral availability.
Campine's integrated model demonstrates the potential of this approach. The company recovers antimony from industrial waste and feeds recovered material into its specialty chemical operations, where it is further refined into reusable raw materials including antimony trioxide.
For buyers, this can translate into more predictable supply and improved traceability. For producers, it can improve feedstock flexibility and support a differentiated value proposition based on circular material sourcing.
Market Restraints and Challenges
Concentrated Antimony Feedstock Supply
The largest structural challenge is the concentration of antimony mining, processing, and refining capacity. Export restrictions can affect availability even when downstream demand remains intact. China's 2024 export-control regime covers specified antimony-related materials and requires authorization for exports falling within the controlled scope.
The impact extends beyond Chinese suppliers. Importers, compounders, distributors, and manufacturers must account for licensing, lead times, inventory requirements, and price uncertainty. Mitigation increasingly involves multi-source procurement, higher safety stocks, recycling partnerships, and regional processing capacity.
Price Volatility and Reformulation Risk
Antimony prices can move sharply when supply availability changes. Campine reported that unusually high prices during 2025 caused customers to reduce usage or temporarily switch to alternative flame retardants.
This creates a direct margin challenge for formulators that cannot immediately pass higher raw-material costs to customers. It also increases the incentive to optimize antimony loading or qualify alternative synergists. Suppliers therefore face pressure to provide products that deliver required fire performance at efficient loading levels.
Regulatory and Occupational Exposure Requirements
Antimony trioxide is subject to hazardous-substance classification and workplace controls in major markets. The European Chemicals Agency identifies antimony trioxide under EU CLP with a Carc. 2 classification. In the United States, OSHA lists an exposure limit of 0.5 mg/m³ for antimony and compounds, expressed as antimony, on an eight-hour time-weighted-average basis.
These requirements affect manufacturing, packaging, warehouse handling, workplace ventilation, personal protective equipment, safety documentation, and customer qualification. Producers that invest in containment, dust control, quality systems, and compliant documentation can reduce operational risk, but these measures also raise production and handling costs.
Substitution by Alternative Flame-Retardant Chemistries
High antimony prices and regulatory scrutiny can encourage formulators to evaluate alternative synergists and halogen-free systems. Substitution is not universal because fire-performance requirements, formulation compatibility, certification, processing behavior, and cost can prevent immediate replacement.
The commercial risk is therefore application-specific. Commodity-oriented applications with flexible formulations are more exposed to substitution than highly qualified applications where changing the additive would require extensive testing.
Quality Variability Across Suppliers
Antimony trioxide is not a uniform commodity from the buyer's perspective. Differences in purity, particle size, particle distribution, moisture, dispersion, and packaging can affect downstream performance. For PET catalysts and pigment applications, these characteristics can directly affect process stability and product quality.
Buyers therefore tend to qualify suppliers against technical specifications rather than selecting solely on quoted price. This creates barriers for suppliers entering established customer accounts and places greater emphasis on laboratory testing, certification, batch traceability, and technical support.
Major Segment Analysis:
Flame Retardants
Flame retardants represent the most commercially important application segment because antimony trioxide's strongest established function is as a synergist in flame-retardant systems. The material is particularly relevant where polymers must meet defined fire-performance requirements without materially compromising processing characteristics.
Demand comes primarily from compounders and formulators rather than from final product manufacturers purchasing the chemical directly. These intermediate buyers supply automotive, electrical and electronics, construction, textile, cable, and industrial-product manufacturers. Procurement teams therefore assess both chemical performance and supply reliability because a disruption can affect the customer's ability to manufacture certified products.
The purchasing specification typically includes antimony concentration, purity, particle size, particle distribution, moisture, packaging, dispersion behavior, and compatibility with the flame-retardant formulation. Buyers also increasingly consider workplace exposure and dust-management requirements. This supports demand for masterbatch, dispersion, and other pre-formulated formats alongside conventional powder.
The segment is also highly sensitive to raw-material pricing. During the 2025 supply disruption, Campine reported strong demand in the first half of the year but later observed reduced consumption and temporary substitution as antimony prices reached exceptional levels. This indicates that flame-retardant demand has both structural and price-responsive components.
Competitive differentiation is consequently shifting toward formulation efficiency. A supplier able to provide the required fire performance with controlled particle characteristics and efficient loading can reduce the customer's total formulation cost even if its antimony trioxide unit price is not the lowest.
Masterbatch provides another commercial avenue within this segment. Pre-dispersed antimony trioxide can simplify dosing, improve material distribution, and reduce powder-handling concerns. Campine's portfolio includes polymer-specific masterbatch solutions and customized formulations, showing how suppliers can move from selling a chemical ingredient toward selling a processing solution.
Through 2031, the flame-retardant segment should therefore be assessed through both volume demand and formulation economics. Growth in polymer-intensive end uses can support consumption, while high prices, regulatory scrutiny, and alternative chemistries can moderate the amount of antimony trioxide used per finished product.
Regional Analysis
North America
North American demand is supported by electrical and electronics manufacturing, automotive applications, construction materials, textiles, and industrial plastics. Buyers place high importance on regulatory documentation, supply continuity, quality assurance, and domestic or regionally secure sourcing.
Supply-chain security has become particularly important. The United States is investing in domestic antimony capacity and processing, reflecting the strategic importance of antimony to industrial and defense supply chains. In 2026, United States Antimony Corporation reported a US Department of War grant of US$27 million under Defense Production Act Title III to expand and modernize domestic antimony processing and support Alaskan mining operations.
North American buyers are therefore likely to maintain diversified procurement strategies, combining established imported material with emerging domestic supply. The principal constraint remains the time and capital required to establish qualifying mining, refining, and processing capacity.
Europe
Europe has a mature downstream manufacturing base across automotive, electrical equipment, construction materials, plastics, coatings, and specialty chemicals. Buyers generally place strong emphasis on chemical compliance, documentation, workplace safety, and consistent product specifications.
Antimony trioxide is subject to EU CLP classification, with ECHA identifying the substance under the harmonized classification framework as Carc. 2. This increases the importance of correct classification, labeling, safety documentation, worker protection, and supply-chain communication.
European suppliers also have a strong incentive to develop recycling-based sourcing. Campine's integration of recovered antimony into new antimony trioxide production provides an example of how circular feedstock can reduce exposure to primary supply constraints.
Asia Pacific
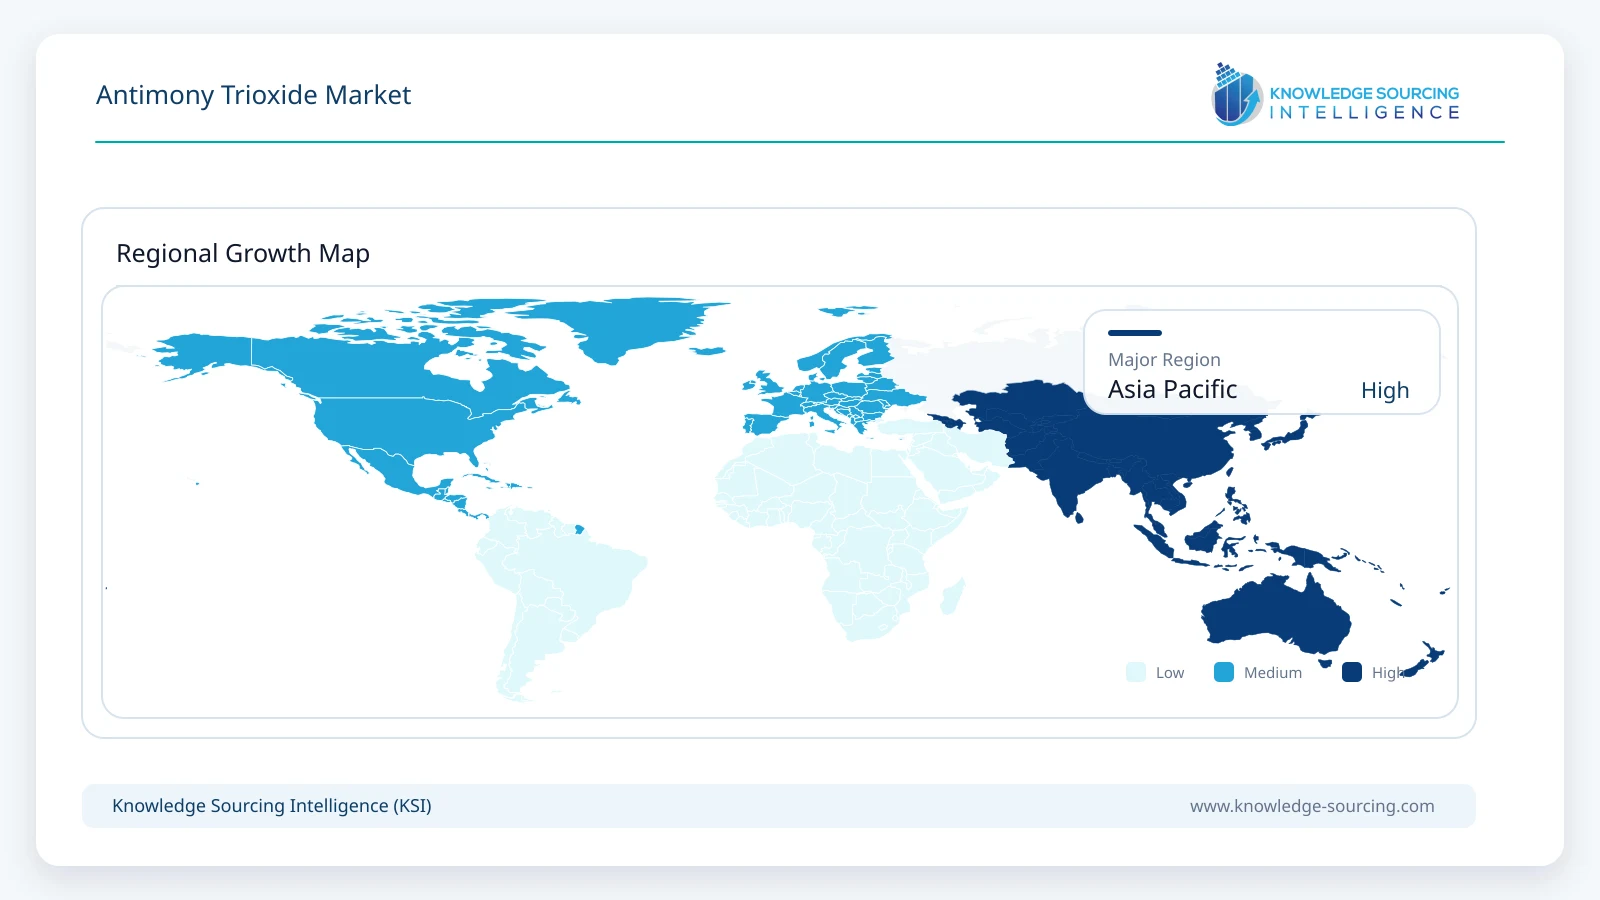
Asia Pacific is the most strategically important regional market because it combines antimony processing capacity with large downstream manufacturing industries. China has an extensive antimony industry, while Japan, South Korea, Taiwan, and India provide substantial demand from electronics, plastics, textiles, chemicals, automotive, and industrial manufacturing.
China's export-control framework has changed procurement behavior outside the country. The government stated that specified antimony-related products, including certain high-purity antimony oxides, are subject to export controls. This has encouraged importers to review inventories, establish alternative sources, and evaluate recycled or regionally produced material.
India presents an opportunity for suppliers serving plastics, textiles, paints, coatings, and industrial chemicals. Local suppliers such as Chemico Chemicals offer multiple antimony trioxide grades, including high-tint and catalytic grades, illustrating the presence of application-specific supply within the country.
Middle East & Africa
Demand in the Middle East and Africa is smaller than in Asia Pacific, Europe, or North America but is supported by construction materials, coatings, plastics conversion, cables, and industrial manufacturing. The region's importance also extends to trade and raw-material sourcing.
Buyers are generally sensitive to delivered cost because imports represent a substantial part of supply. Inventory management, shipping reliability, distributor relationships, and availability of compliant grades are therefore important purchasing considerations. New mining and processing investment in Africa could create additional feedstock sources over the medium term, although project development timelines and infrastructure constraints remain important risks.
South America
South American demand is linked to plastics processing, construction, automotive manufacturing, textiles, paints, coatings, and electrical products. Brazil represents the largest manufacturing base in the region and therefore provides the broadest downstream application opportunity.
The principal challenge is supply-chain dependence on imported material and exposure to freight, currency, and international antimony prices. Buyers can mitigate these risks through longer-term contracts, distributor inventory, and multi-origin sourcing. Growth in polymer processing and infrastructure spending can support demand, but regional consumption remains more sensitive to economic cycles than in larger industrial markets.
Competitive Landscape
The competitive structure includes primary antimony processors, specialty chemical manufacturers, masterbatch suppliers, regional distributors, and vertically integrated recyclers. Competition is not determined solely by installed capacity. Feedstock access, purity control, particle-size management, regulatory compliance, delivery reliability, and technical formulation support are important sources of differentiation.
The competitive scope of this market includes Hunan Gold Group, Campine NV, Yiyang Huachang Antimony Industry Co., Ltd., Nihon Seiko Co., Ltd., Chemico Chemicals Pvt. Ltd., Beijing Institute of Chemical Reagents, Ambani Organics Limited, and Jiulong Chemical Co., Ltd.
Hunan Gold Group and Campine NV represent different approaches to the antimony value chain, with upstream resource exposure and integrated specialty-chemical production being important strategic considerations. Campine combines antimony trioxide production with metal recovery and flame-retardant masterbatch capabilities.
Yiyang Huachang Antimony Industry Co., Ltd. has a long operating history in antimony products and reports production capacity exceeding 20,000 tonnes, with antimony trioxide and antimony trioxide masterbatch among its products. Its stated applications include plastics, rubber, textiles, adhesives, fiberglass, paper, glass, porcelain, and paint.
Chemico Chemicals Pvt. Ltd. demonstrates the role of regional specialty suppliers. Its portfolio includes high-tint, catalytic, and other antimony trioxide grades, allowing customers to purchase according to application requirements.
Across the competitive field, product differentiation is likely to center on purity, particle-size control, masterbatch formulation, customization, packaging, supply reliability, and regulatory support. Suppliers with integrated recycling or secure feedstock relationships can also reduce exposure to raw-material shortages.
Partnerships and geographic expansion are becoming more commercially relevant as buyers seek alternatives to concentrated sources. The market is therefore moving toward a combination of long-term supply relationships, application-specific grades, regional inventories, recycled feedstock, and selective vertical integration.
Recent Developments
July 2026: Teck, Canada Growth Fund, and Natural Resources Canada signed an agreement supporting expanded germanium, gallium, and antimony production at Teck's Trail Operations. The framework includes up to C$400 million of Canada Growth Fund investment and potential antimony capacity expansion, strengthening North American supply security.
July 2026: Nova Minerals announced completion of engineering and design for its Estelle antimony pilot plant in Alaska, including a modular processing configuration that could later support antimony trioxide and metal production. The project advances U.S. domestic antimony processing capability.
March 2026: United States Antimony Corporation reported a US$27 million Defense Production Act Title III grant to expand and modernize domestic antimony processing and support Alaskan mining operations. The investment strengthens regional feedstock and processing security for antimony products.
Regulatory and Policy Environment
Regulation affects the market through chemical classification, workplace exposure, export controls, environmental management, product documentation, and downstream product requirements.
In the European Union, antimony trioxide is identified under the CLP framework with a Carc. 2 classification. Suppliers and downstream users must therefore manage classification and labeling obligations and communicate hazards through appropriate safety documentation. ECHA's CLP framework requires suppliers, manufacturers, importers, downstream users, and distributors to classify and label hazardous substances and mixtures appropriately.
Worker exposure is another important consideration. OSHA lists an eight-hour permissible exposure limit of 0.5 mg/m³ for antimony and compounds measured as antimony. This makes dust control, ventilation, containment, sampling, and personal protection relevant to facilities handling antimony trioxide powder.
Export controls are becoming equally important for international procurement. China's 2024 export-control announcement covers specified antimony ores, metals, products, and certain antimony oxides. The policy took effect on September 15, 2024, and exports falling within the controlled scope require authorization.
These controls have direct commercial implications. Buyers need to evaluate supplier-country exposure, licensing procedures, lead times, inventory buffers, contractual clauses, and alternative feedstock sources. Suppliers outside China can gain strategic relevance when they provide reliable material that satisfies technical and regulatory specifications.
Environmental and occupational requirements also influence production economics. Manufacturers may need investment in dust collection, closed handling, wastewater treatment, emissions controls, worker monitoring, and waste-management systems. Companies with established compliance infrastructure can therefore have an advantage when supplying regulated markets.
Outlook and Strategic Implications
The antimony trioxide market through 2031 will be shaped by a tension between structurally necessary applications and increasingly active supply-chain management. Flame-retardant demand is expected to remain central because antimony trioxide continues to serve established formulations across polymer-intensive industries. However, consumption will not be determined solely by growth in end-use production. Antimony pricing, substitution economics, regulatory requirements, and formulation efficiency will influence the quantity used per application.
Procurement strategies are likely to become more diversified. Large buyers will have greater incentive to combine established Asian suppliers with regional sources, recycled material, and longer-term supply agreements. Contract structures that include pricing adjustments, volume commitments, quality specifications, and supply-continuity provisions can become more common where buyers need protection from extreme price swings.
Investment will increasingly target feedstock security and processing capacity rather than only finished-product manufacturing. The North American investments reported during 2026 demonstrate the strategic shift toward domestic mining, beneficiation, refining, and downstream processing.
Recycling will also become more commercially important. Antimony recovered from industrial waste can supplement primary sources and reduce dependence on newly mined material. Integrated recycling and chemical production can provide greater control over feedstock quality while improving resource efficiency. Campine's operating model illustrates this approach.
Technology development will favor application-specific material formats. Powder will remain important, particularly for established industrial applications, but masterbatch, dispersions, and customized grades can capture additional value by solving handling and formulation challenges. Suppliers that understand polymer processing and downstream certification requirements will be better positioned to defend customer relationships.
The main strategic risk is a prolonged period of elevated antimony prices that accelerates substitution. Buyers will continue testing alternative flame-retardant systems where economics justify reformulation. Suppliers can mitigate this risk by improving the efficiency of antimony trioxide formulations, supporting lower loading levels, developing pre-dispersed products, and providing technical data that demonstrates total formulation economics.
Another risk is uneven regional supply development. New projects can improve diversification, but mining and processing facilities require permitting, financing, technical validation, infrastructure, and customer qualification. The market may therefore experience continued supply volatility even as investment increases.
For suppliers, the strongest strategic opportunities lie in secure feedstock, recycled antimony, high-purity grades, masterbatch formulations, application engineering, and regional inventory. For buyers, the priority will be to build resilient sourcing strategies without sacrificing product qualification or cost competitiveness.
Overall, the market's commercial direction will be determined by the interaction of downstream fire-safety requirements, polymer and electronics manufacturing, antimony availability, regulatory compliance, and supply-chain localization. Companies that combine reliable material quality with secure sourcing and application-specific technical support will have the strongest basis for maintaining long-term customer relationships through 2031.
Antimony Trioxide Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 951.6 million |
| Total Market Size in 2031 | USD 1,283.9 million |
| Forecast Unit | Million |
| Growth Rate | 6.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, End-User Industry, Geography |
| Companies |
|
Market Segmentation
By Type
By Application
By End-user Industry
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ANTIMONY TRIOXIDE MARKET BY TYPE
5.1. Introduction
5.2. Antimony Trioxide Powder
5.3. Antimony Trioxide Masterbatch
5.4. Others
6. ANTIMONY TRIOXIDE MARKET BY APPLICATION
6.1. Introduction
6.2. Flame Retardants
6.3. Plastics and Polymers
6.4. Glass and Ceramics
6.5. Paints and Coatings
6.6. Others
7. ANTIMONY TRIOXIDE MARKET BY END-USER INDUSTRY
7.1. Introduction
7.2. Electronics
7.3. Automotive
7.4. Construction
7.5. Textiles
7.6. Others
8. ANTIMONY TRIOXIDE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. Others
8.6. Asia Pacific
8.6.1. Japan
8.6.2. China
8.6.3. India
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Hunan Gold Group
10.2. Campine NV
10.3. Yiyang Huachang Antimony Industry Co., Ltd.
10.4. Nihon Seiko Co., Ltd.
10.5. Chemico Chemicals Pvt. Ltd.
10.6. Beijing Institute of Chemical Reagents
10.7. Ambani Organics Limited
10.8. Jiulong Chemical Co., Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for the Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











